
 Global Precision Livestock Farming Market | 2026-2036
Global Precision Livestock Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Livestock Farming Market Outlook
Sensor-grade accuracy in wearable collar tags is unwinding cost barriers that once limited precision livestock farming to elite dairy operations. DeLaval leverages its vertical integration across milking robots and herd management software to sustain premium positioning in automated dairy systems. Nedap N.V. anchors its competitive stance through specialized cow monitoring hardware that dominates European pasture-based operations.
Precision livestock farming deploys networked sensors, automated feeding mechanisms, and algorithmic analytics to track individual animal physiology, optimize feed conversion ratios, and preempt disease outbreaks across confined and grazing systems. Sensor Systems command the largest installed base due to universal deployment across species, while Machine Learning represents the fastest-expanding technology layer as predictive models improve calving detection and mastitis forecasting accuracy. Monitoring Software captures concentrated margin pools through recurring subscription structures tied to cloud data architectures.
The EU F-Gas Regulation, FDA veterinary feed directive, and ISO 22000 food safety management standards collectively tighten equipment efficiency mandates and traceability requirements for livestock technology vendors. These frameworks shape demand by conditioning subsidy eligibility and export market access on compliance with emissions and data integrity protocols. Stakeholders must monitor how carbon accounting rules and animal welfare certification schemes reshape procurement criteria for precision farming capital equipment.
Market Dynamics
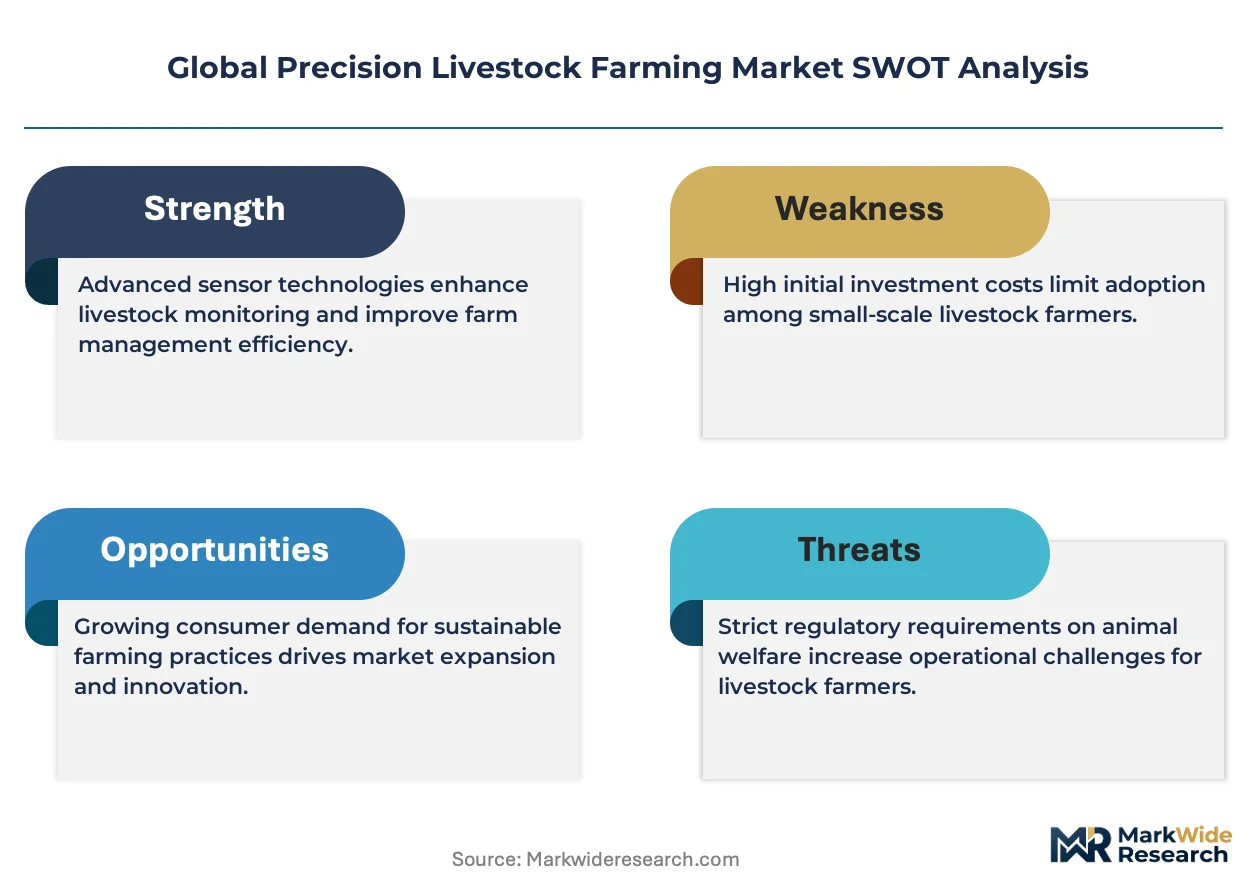
EU F-Gas Regulation mandates are compressing hydrofluorocarbon deployment timelines for livestock cooling infrastructure, forcing equipment vendors to accelerate heat pump and natural refrigerant transitions ahead of phasedown deadlines.
Growth Catalysts
- EU Green Deal carbon accounting:Member state subsidy frameworks now tie direct payments to precision livestock data verification, pulling IoT adoption into smaller herd operations previously priced out.
- Machine learning calving detection:Predictive algorithms trained on accelerometer and rumination sensor streams are cutting veterinary intervention response times by half in Dutch pasture-based dairies.
- Lower Saxony precision farming clusters:Germany's concentrated veterinary research infrastructure and equipment financing cooperatives are creating localized demonstration effects that accelerate neighboring farm adoption.
Market Restraints
- Sensor hardware cost volatility:MEMS accelerometer and LoRa module supply chains concentrate in East Asian contract manufacturers, exposing European integrators to semiconductor tariff and logistics cost swings.
- CE marking complexity for AI-enabled devices:The EU AI Act's risk classification framework for veterinary diagnostic algorithms is extending product registration timelines by 8-14 months for novel predictive health platforms.
- Manual labor substitution limits:Extensive grazing systems in Ireland and New Zealand face terrain and herd dispersion patterns that resist full automation, capping addressable market share for robotic milking and feeding systems.
Strategic Opportunities
- India FSSAI traceability mandates:Upcoming dairy supply chain digitization requirements for export certification are opening precision livestock hardware deployment in a market with minimal existing sensor penetration.
- Subscription-based monitoring software:Cloud-native herd management platforms with recurring revenue structures are capturing margin pools that hardware-only vendors cannot access, particularly in Danish cooperative procurement frameworks.
- 5G and edge AI convergence:Low-latency connectivity combined with on-collar inference chips is enabling real-time estrus detection without cloud dependency, unlocking remote pasture operations previously beyond cellular coverage.
Industry Challenges
- Veterinary data science talent scarcity:Livestock technology vendors compete with human health and fintech sectors for machine learning engineers capable of translating physiological sensor streams into clinically validated alerts.
- ISO 22000 certification timelines:Food safety management system audits for precision farming data integrity are creating 6-9 month delays in equipment procurement cycles for EU export-oriented processors.
- Legacy herd management software integration:Decades-old on-premise dairy record systems in family-owned operations resist API connectivity, forcing costly middleware development for sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Livestock Farming Market |
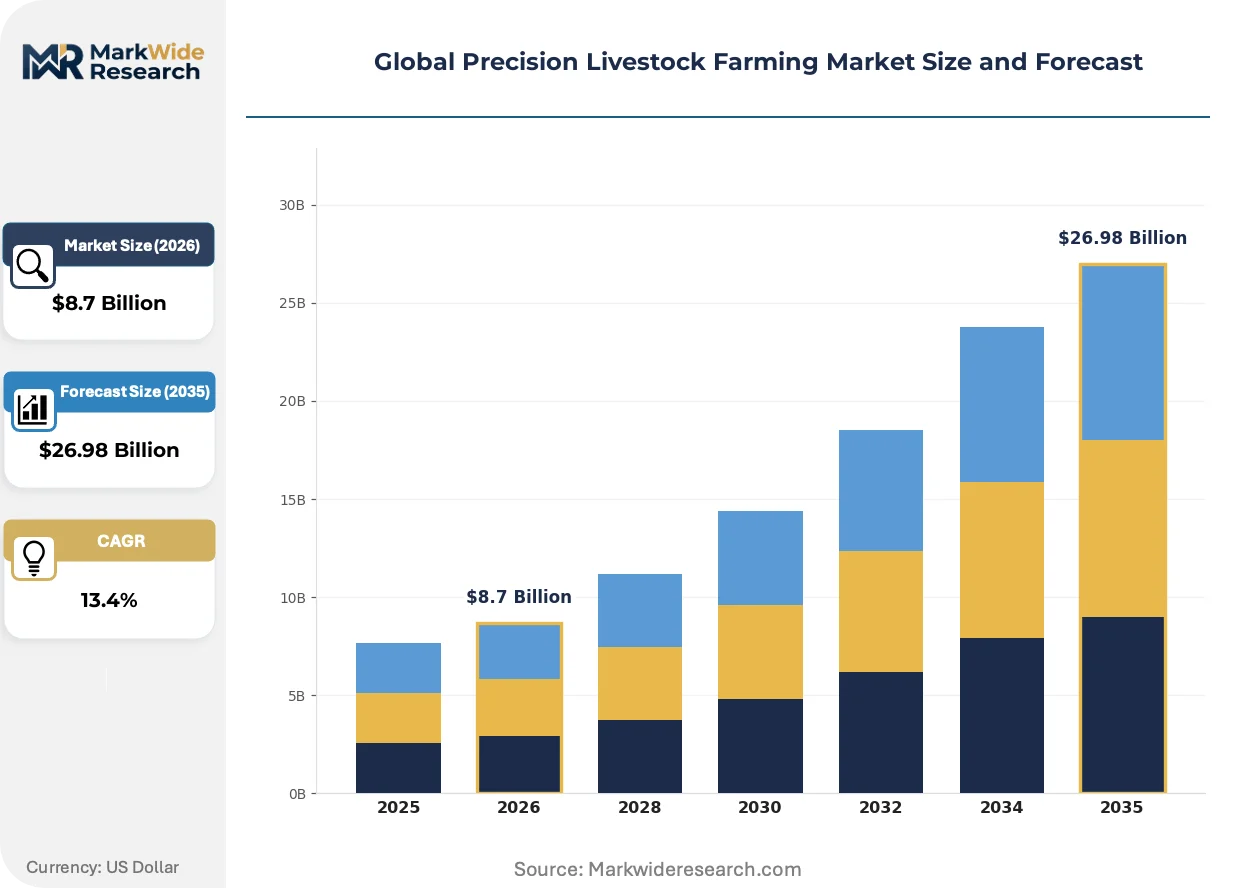
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Sensor Systems, Feeding Systems, Monitoring Software End User: Farmers, Livestock Producers, Agribusinesses, Research Institutions Application: Health Monitoring, Production Management, Environmental Control, Behavior Tracking Technology: IoT Solutions, Data Analytics, Machine Learning, Cloud Computing |
| Companies Covered | Lely International, BouMatic LLC, DeLaval, Dairymaster Holdings Ltd., SCR Dairy Ltd., GEA Group, Nedap N.V., Merck & Co., Inc, Afimilk Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Livestock Farming Market Strategic Shifts
Algorithmic inference at the network edge is restructuring how livestock data flows from pasture to processor, collapsing latency constraints that previously centralized analytics in distant cloud facilities.
On-collar edge AI processors are displacing cellular-dependent transmission architectures for estrus and calving alerts. Large-scale grazing cooperatives in New Zealand and Uruguay are deploying these devices across dispersed herds where satellite or mesh connectivity remains unreliable. This displacement is compressing infrastructure requirements for precision livestock deployment in remote rangeland systems previously deemed uneconomical for sensor networks.
The EU F-Gas Regulation's hydrofluorocarbon phasedown is forcing refrigeration equipment retrofits across Spanish and Italian intensive livestock facilities. Manufacturers are pivoting production lines toward CO2 and ammonia-based heat pump systems that comply with 2030 reduction targets. Dairy processors in Denmark and the Netherlands are responding by bundling cooling upgrades with sensor infrastructure in integrated capital packages.
Cooperative procurement consolidation is reshaping equipment acquisition patterns across Northern European dairy sectors. Buying groups representing thousands of member farms are unbundling after-sales service from hardware contracts, forcing DeLaval and Nedap to compete on platform subscription pricing rather than bundled maintenance margins. This shift is most visible in the Netherlands, where Rabobank-financed purchasing consortia now dominate capital allocation decisions for automated milking investments.
Global Precision Livestock Farming Market Segmentation
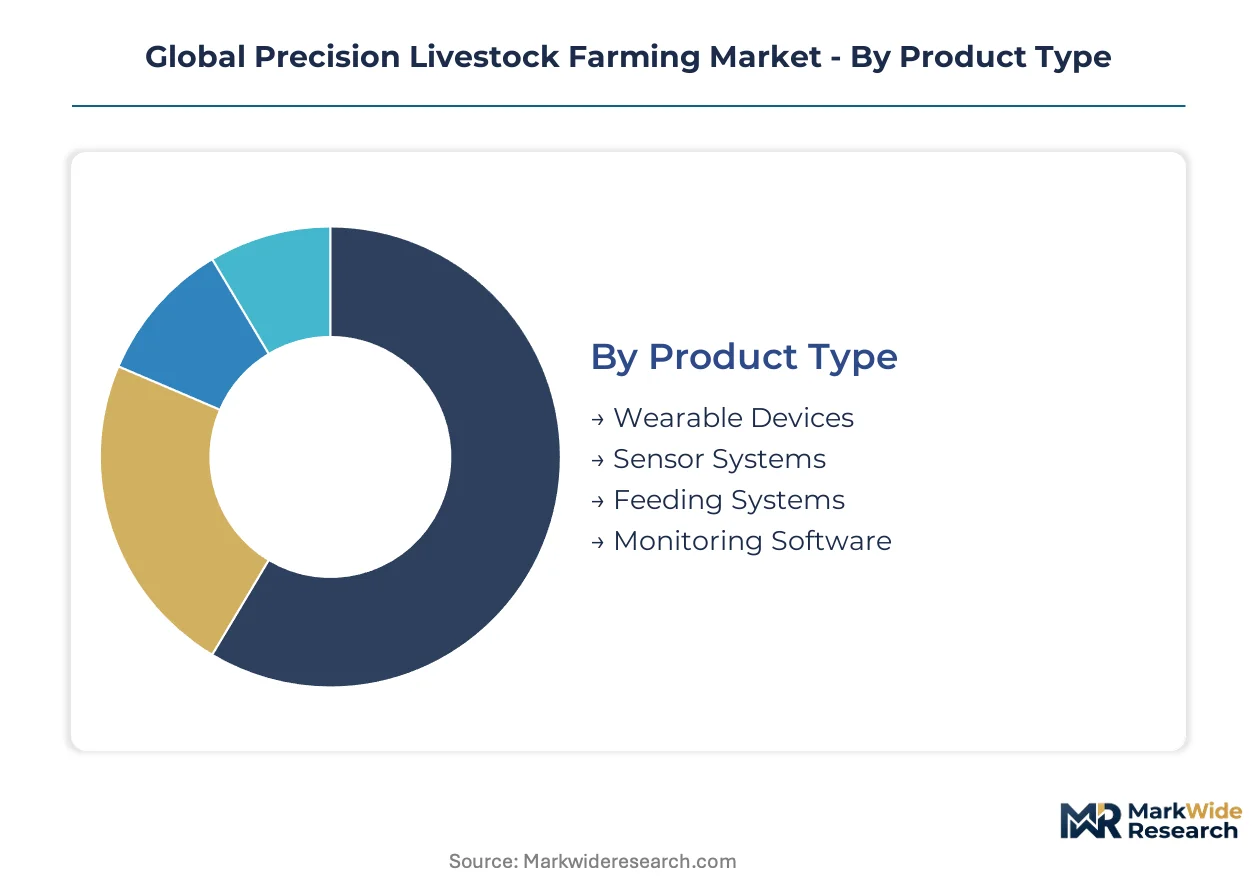
Segmentation in precision livestock farming exposes how hardware commoditization pressures collide with software margin capture. Equipment vendors and platform providers occupy fundamentally different competitive terrain across product, user, and technology dimensions.
Product Type:
Wearable Devices face acute substitution pressure from smartphone-based visual monitoring apps in smallholder segments, while integrated Sensor Systems defend their installed base through multi-parameter fusion.
- Wearable Devices:Collar-mounted accelerometers and rumination monitors transmit physiological data via LoRa or Bluetooth Low Energy protocols. Dutch pasture-based dairies in Friesland and Gelderland drive replacement cycles as battery life improvements justify hardware refresh.
- Sensor Systems:Fixed environmental and biometric arrays integrate temperature, humidity, and gas detection with animal-mounted transponders. German Lower Saxony clusters anchor European demand for barn-based installations tied to F-Gas Regulation compliance.
- Feeding Systems:Automated dispensers with RFID individual recognition optimize ration delivery.
- Monitoring Software:Cloud-native platforms with recurring subscription structures capture concentrated margin pools unavailable to hardware-only vendors.
Sensor Systems retain volume leadership; Monitoring Software holds the steepest expansion curve.
End User:
Procurement authority concentrates differently across user types, with cooperatives and agribusinesses wielding scale leverage that individual farmers cannot match.
- Farmers:Individual owner-operators under 200 head dominate volume in fragmented Southern European and South Asian markets where financing constraints limit capital intensity.
- Livestock Producers:Mid-scale operations with 500-2000 head deploy partial automation, mixing robotic milking with manual health checks in Polish and Romanian dairy sectors.
- Agribusinesses:Vertically integrated processors and feed companies mandate data interoperability across supplier networks.
- Research Institutions:Veterinary universities and breeding stations pilot algorithm validation before commercial deployment.
Agribusinesses command platform pricing power; Research Institutions anchor technology diffusion pipelines.
Application:
Functional priorities shift with production intensity, as confinement operations emphasize environmental control while grazing systems prioritize location and behavior tracking.
- Health Monitoring:Predictive algorithms processing rumination, activity, and temperature streams enable mastitis and ketosis early warning. Danish cooperative procurement frameworks prioritize clinically validated alert accuracy over sensor cost.
- Production Management:Milk yield optimization, feed conversion tracking, and reproductive scheduling integrate across herd management platforms. Spanish intensive dairy regions deploy these systems to meet processor traceability mandates.
- Environmental Control:Ventilation, cooling, and ammonia management systems respond to EU F-Gas Regulation and national emissions ceilings.
- Behavior Tracking:Estrus detection, calving alerts, and welfare indicators leverage accelerometer and GPS fusion.
Health Monitoring captures the highest software attach rates; Behavior Tracking is climbing the fastest as edge AI reduces connectivity dependency.
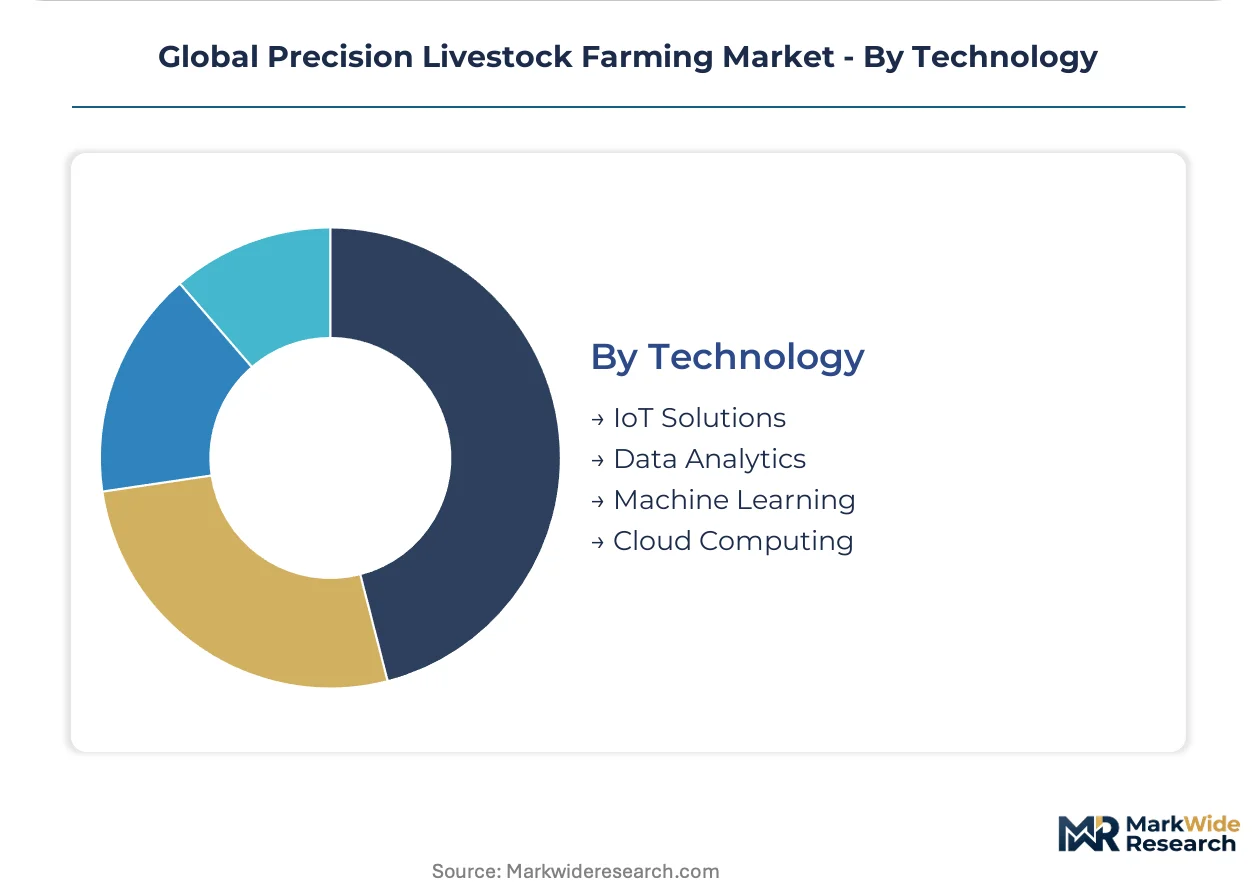
Technology:
Technology layers stack unevenly, with infrastructure-dependent solutions facing deployment barriers that embedded intelligence circumvents.
- IoT Solutions:Networked sensor arrays and gateway architectures form the connectivity backbone. New Zealand grazing cooperatives deploy satellite-linked collars where cellular coverage fails.
- Data Analytics:Descriptive dashboards and historical benchmarking tools dominate legacy software architectures. Italian family-owned operations resist API connectivity, forcing middleware development.
- Machine Learning:Predictive models for calving detection and disease forecasting train on multi-year physiological datasets. Netherlands-based veterinary research infrastructure accelerates algorithm validation.
- Cloud Computing:Centralized data lakes and subscription platforms enable cross-herd benchmarking and processor-facing traceability.
IoT Solutions retain installed base dominance; Machine Learning is gaining share fastest as veterinary data science talent concentrates in EU research clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in the Netherlands and Germany, where dairy automation heritage and veterinary research infrastructure create dense supplier ecosystems. Demand diffusion follows distinct national patterns shaped by subsidy frameworks, emissions regulations, and cooperative procurement structures.
Netherlands
Dutch dairy cooperatives drive automated milking system deployment through Rabobank-financed purchasing consortia. EU Green Deal carbon accounting ties direct payments to precision livestock data verification, accelerating IoT adoption across Friesland and Gelderland pasture operations. Wageningen University anchors algorithm validation pipelines that feed commercial health monitoring platforms.
Germany
Lower Saxony precision farming clusters integrate IoT-enabled herd management platforms with concentrated veterinary research infrastructure. F-Gas Regulation compliance deadlines force refrigeration equipment retrofits in intensive dairy facilities, bundling cooling upgrades with sensor infrastructure. Equipment financing cooperatives create localized demonstration effects that accelerate neighboring farm adoption.
United States
Large-scale confinement dairies in Wisconsin and California deploy machine learning calving detection systems to cut veterinary intervention response times. FDA veterinary feed directive mandates shape traceability requirements for automated feeding equipment. Dairy processors in the Upper Midwest mandate data interoperability across supplier networks.
India
FSSAI traceability mandates for dairy export certification open precision livestock hardware deployment in a market with minimal existing sensor penetration. Smallholder operations under 200 head dominate volume, constraining capital intensity for automated systems. Gujarat and Maharashtra processing cooperatives pilot sensor networks for supply chain digitization.
New Zealand
Extensive grazing cooperatives deploy satellite-linked collar systems where cellular coverage fails across dispersed hill-country herds. Terrain and herd dispersion patterns resist full automation, capping addressable market share for robotic milking. Edge AI processors enable real-time estrus detection without cloud dependency in remote pasture operations.
Global Precision Livestock Farming Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with premium-tier vendors commanding integrated platform margins while Asian contract manufacturers supply MEMS components under price pressure. The vendor base organizes around three strategic archetypes: full-stack dairy automation specialists, sensor hardware pure-plays, and cloud-native software platforms. Consolidation pressure intensifies as cooperative procurement unbundles after-sales service from hardware contracts. Dominant competitive moves include backward integration into captive sensor production and subscription-based revenue model transitions.
Among Dutch full-stack specialists, Lely International and DeLaval occupy positions exemplifying integrated platform strategies that span milking robots through herd management software. Nedap N.V. sits within the sensor hardware tier, representing specialized cow monitoring archetypes that dominate European pasture-based operations. GEA Group anchors the German engineering-centric tier, reflecting industrial automation heritage applied to livestock facilities. These three archetypes illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability bundles.
| Leading Market Players |
|---|
| Lely International |
| BouMatic LLC |
| DeLaval |
| Dairymaster Holdings Ltd. |
| SCR Dairy Ltd. |
| GEA Group |
| Nedap N.V. |
| Merck & Co., Inc |
| Afimilk Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance certification gates both equipment vendor qualification and price differentiation across cooling-integrated livestock systems, forcing unbundled service pricing to absorb compliance cost premiums while MEMS component sourcing concentrates pricing power in East Asian contract manufacturers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across precision livestock farming equipment, separating CE-marked premium systems with natural refrigerant heat pumps from standard-tier retrofit packages and economy-tier sensor-only deployments. Price differentiation hinges on ISO 22000 certification grade and after-sales service bundling, with Danish cooperatives showing lowest sensitivity due to Rabobank-financed procurement leverage. Cost compression in sensor hardware is intensifying because MEMS accelerometer supply chains face semiconductor tariff exposure, while margins are tightening for European integrators caught between component volatility and cooperative unbundling demands.
Supply Chain Analysis
Strategic stockpiling of LoRa modules and edge AI processors dominates inventory strategy as lead time volatility from East Asian foundries disrupts just-in-time preferences among Dutch system integrators. Component manufacturing concentrates in China, Taiwan, and South Korea, with European vendors drawing from these hubs for MEMS sensors, RF modules, and inference chips. Supply chain risk centers on single-source vulnerability for specialized veterinary-grade accelerometers. Distribution runs through Rabobank-financed purchasing consortia in the Netherlands and equipment financing cooperatives in Germany's Lower Saxony clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Precision Livestock Farming Market dynamics reflect a cyclical recovery anchored to EU Green Deal subsidy disbursement cycles, with carbon accounting verification requirements pulling IoT adoption into capital-constrained herd operations previously deferred during rate-tightening periods.
For Market Incumbents: Fortify platform subscription pricing structures against cooperative procurement unbundling by embedding ISO 22000 data integrity certification as a non-separable service layer. Backward integration into captive MEMS sensor production hedges East Asian supply volatility, while deepening Wageningen University research partnerships accelerates algorithm validation pipelines that defend margin pools against cloud-native software entrants.
For New Entrants and Emerging Players: FSSAI traceability fast-track certification for Indian dairy export corridors opens white-space deployment in Gujarat and Maharashtra processing cooperatives where sensor penetration remains minimal. Target smallholder operations under 200 head through smartphone-integrated visual monitoring apps that circumvent hardware cost barriers, leveraging veterinary data science talent scarcity in EU clusters to source algorithm development remotely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native monitoring software sub-segments as recurring revenue structures displace hardware-heavy business models. Five-to-ten year viability favors acquisition targets with validated machine learning pipelines for mastitis forecasting and established API connectivity to legacy herd management systems. Watch for inflection when edge AI processor costs cross thresholds enabling profitable deployment in New Zealand hill-country grazing cooperatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Production | Captive MEMS supply from Taiwanese foundries insulates Dutch integrators from tariff exposure. |
| CE Marking Fast-Track for AI-Enabled Devices | EU AI Act risk classification compliance accelerates veterinary diagnostic platform registration timelines. |
| Subscription Revenue Model Transition | Cloud-native herd management platforms capture margin pools unavailable to hardware-only vendors. |
| Cooperative Procurement Partnership | Rabobank-financed consortia in the Netherlands dominate capital allocation for automated milking investments. |
| Edge AI Processor Deployment | On-collar inference chips enable real-time estrus detection in New Zealand satellite-linked pasture systems. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, veterinary research publication databases, and cooperative procurement disclosure records. Dairy technology executives, livestock veterinary researchers, agricultural equipment financing officers, and sensor hardware procurement leads provided structured input across the Netherlands, Germany, and New Zealand. Secondary validation drew from EMA veterinary device registrations, F-Gas Regulation implementation reports, FSSAI traceability mandate drafts, and SEC filings of listed agricultural technology suppliers. Bottom-up equipment shipment tracking triangulates against top-down subsidy disbursement analysis.
Segmentation dimensions modeled span product type, end user category, application function, and technology layer across the projection horizon. CAGRs derive from equipment replacement cycle analysis, cooperative procurement volume aggregation, and algorithm adoption curve modeling within dairy operations. Forecast inputs incorporate EU Green Deal payment verification timelines, FDA veterinary feed directive enforcement patterns, and edge AI chip cost trajectories from semiconductor supply chain monitoring.
Decision-makers should treat outputs as directional under assumptions of sustained EU subsidy frameworks and stable East Asian semiconductor logistics; material deviation would warrant model refresh. Revision becomes warranted when F-Gas Regulation phasedown deadlines accelerate or India FSSAI traceability mandates expand beyond export-oriented processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Soil Moisture Meter Market