
 North America Oil Filled Transformer Market | 2026-2036
North America Oil Filled Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil Filled Transformer Market Analysis
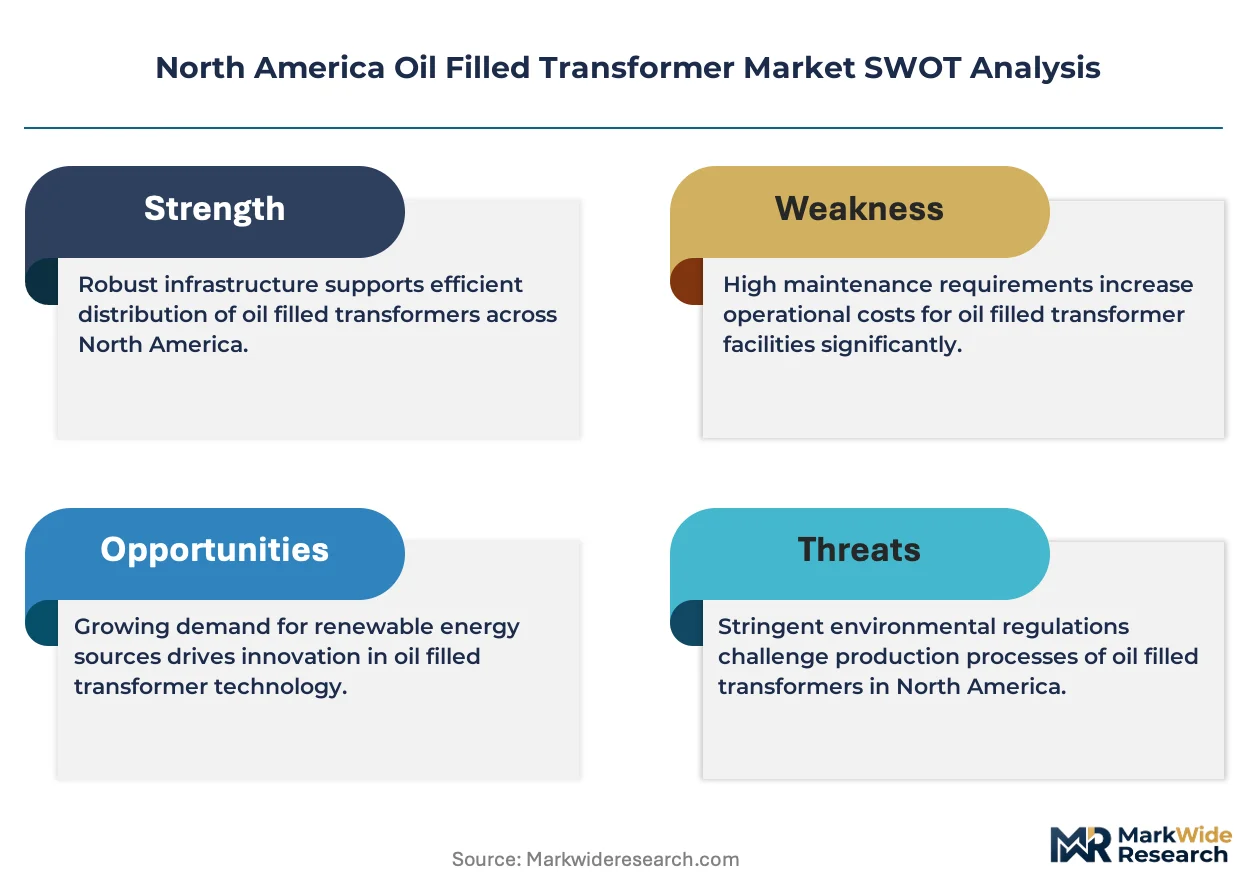
Multi-sourcing strategies among North American utilities is expanding as grid operators seek to derisk procurement from sole-supplier dependencies. GE Vernova leverages its domestic manufacturing footprint to anchor large utility contracts across the United States. Siemens Energy competes through advanced core-steel formulations that reduce no-load losses. Hitachi Energy specializes in extra-high-voltage designs for renewable interconnection projects.
An oil filled transformer is an electrical apparatus that uses insulating mineral oil or ester-based fluid to cool windings and suppress arcing, typically operating at voltages from 2.4 kV through 765 kV depending on grid application. The oil serves dual functions: dielectric insulation and convective heat transfer from copper or aluminum windings to external radiators. Three-phase configurations dominate utility procurement due to superior power density and lower per-MVA infrastructure cost. Among end user segments, renewable energy installations represent the fastest-expanding demand pool as wind and solar farms require step-up transformers for transmission-level voltage. Outdoor installations retain the largest share by installation type, reflecting the predominance of substation-based deployment.
The EPA enforces minimum efficiency standards under the Energy Policy Act that govern transformer losses at standardized load profiles. NEMA and IEEE publish construction and testing standards that shape product certification requirements across the United States and Canada. The Department of Energy periodically tightens these efficiency rules, forcing manufacturers to redesign core geometries and winding configurations. Stakeholders must monitor regulatory dockets for pending efficiency tier upgrades that could obsolete current product lines.
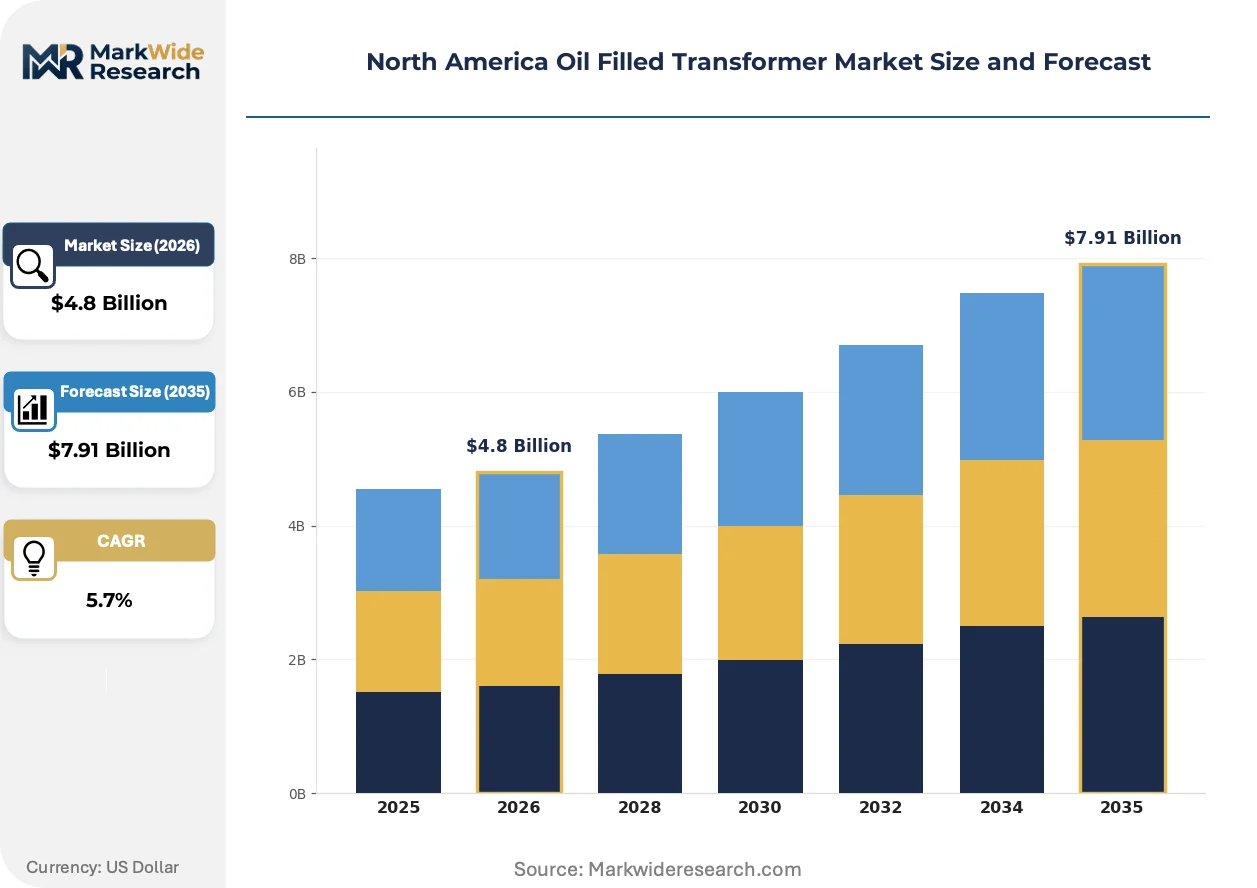
Market Dynamics
Grid operators across the United States and Canada face a structural supply-demand mismatch as aging transformer fleets approach end-of-life while renewable interconnection queues stretch to unprecedented lengths. Utilities must simultaneously replace obsolete units and expand capacity for wind and solar farm tie-ins.
Growth Catalysts
- Energy Policy Act efficiency mandates:The EPA's tightened loss standards under DOE rulemaking force fleet replacements, creating pull for next-generation core designs across investor-owned utilities.
- Texas ERCOT interconnection surge:Renewable developers in the Texas Panhandle and West Texas require step-up transformers for multi-gigawatt solar and wind projects entering commercial operation.
- Amorphous metal core adoption:Advanced core-steel formulations reduce no-load losses by 70 percent compared to conventional grain-oriented silicon steel, satisfying utility lifecycle cost requirements.
Market Restraints
- Grain-oriented electrical steel concentration:Domestic supply of specialized transformer-grade steel concentrates among a handful of North American mills, exposing procurement to capacity constraints and price volatility.
- Mineral oil substitution pressure:Natural and synthetic ester fluids displace conventional mineral oil in environmentally sensitive installations, requiring manufacturers to maintain dual fluid certification and inventory.
- Extra-high-voltage design complexity:345 kV and 765 kV class transformers demand specialized winding expertise and testing infrastructure that limits qualified supplier pools.
Strategic Opportunities
- Canadian hydroelectric expansion:Quebec and British Columbia transmission utilities require bulk power transformers for remote hydroelectric site interconnection, creating demand for transportable modular designs.
- Infrared thermography integration:Convergence of thermal imaging sensors with transformer monitoring systems enables predictive maintenance contracts as a recurring revenue stream for OEM service divisions.
- Inflation Reduction Act manufacturing credits:Domestic content bonuses accelerate reshoring of core lamination and winding operations to capture federal tax incentives.
Industry Challenges
- Transformer design engineer scarcity:Electromagnetic field modeling and insulation coordination expertise concentrates among retiring utility specialists, constraining OEM product development timelines.
- IEEE C57 certification backlog:Third-party testing laboratory capacity limits delay new product introductions, compressing commercialization windows for redesigned efficiency-tier units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil Filled Transformer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Hermetically Sealed, Non-Hermetically Sealed End User: Utilities, Industrial Facilities, Commercial Buildings, Renewable Energy Installation Type: Indoor, Outdoor, Stationary, Mobile Capacity: Up to 500 kVA, 500 kVA - 2000 kVA, 2000 kVA - 5000 kVA, Above 5000 kVA |
| Companies Covered | GE Vernova, Siemens Energy, Schneider Electric, Hitachi Energy, Eaton, Niagara Power Transformer, Virginia Transformer, MGM Transformer Company, Northern Transformer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil Filled Transformer Market Emerging Trajectories
Transformer technology trajectories center on thermal performance optimization and digital integration. Manufacturers compete through materials science advances and embedded sensor architectures that redefine asset management economics.
Amorphous metal ribbon cores are electrifying utility procurement preferences for distribution-class units. These metallic glass alloys virtually eliminate hysteresis losses. Pacific Gas & Electric and Consolidated Edison have specified amorphous core designs for new urban substations. The technology is electrifying competitive positioning among mid-tier manufacturers seeking efficiency-tier compliance without premium silicon steel supply.
The EPA's updated Energy Policy Act efficiency standards trigger fundamental core geometry redesigns across the supply base. Minimum efficiency thresholds for medium-voltage distribution transformers tighten progressively through 2027. Low-loss core-steel formulations and optimized winding configurations dominate engineering priorities. Texas and California utilities face the steepest compliance curves due to renewable-driven load growth.
Multi-year framework agreements displace transactional spot purchasing among North American utilities. Procurement teams negotiate consolidated supply contracts spanning 36 to 60 months with price-adjustment mechanisms. Original equipment manufacturers respond with dedicated production line allocations and priority scheduling guarantees. The shift concentrates most visibly among Southwest investor-owned utilities managing aggressive interconnection timelines.
North America Oil Filled Transformer Market Segmentation
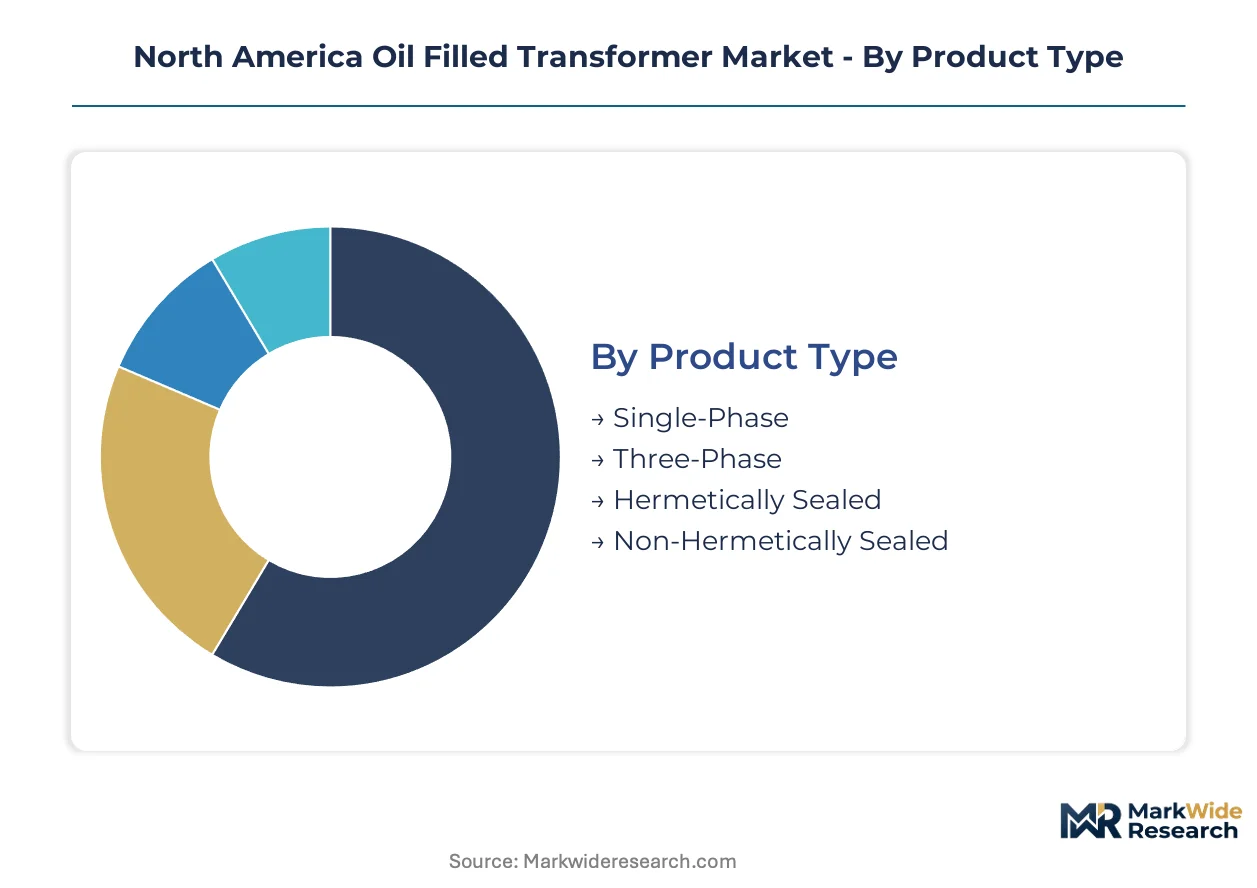
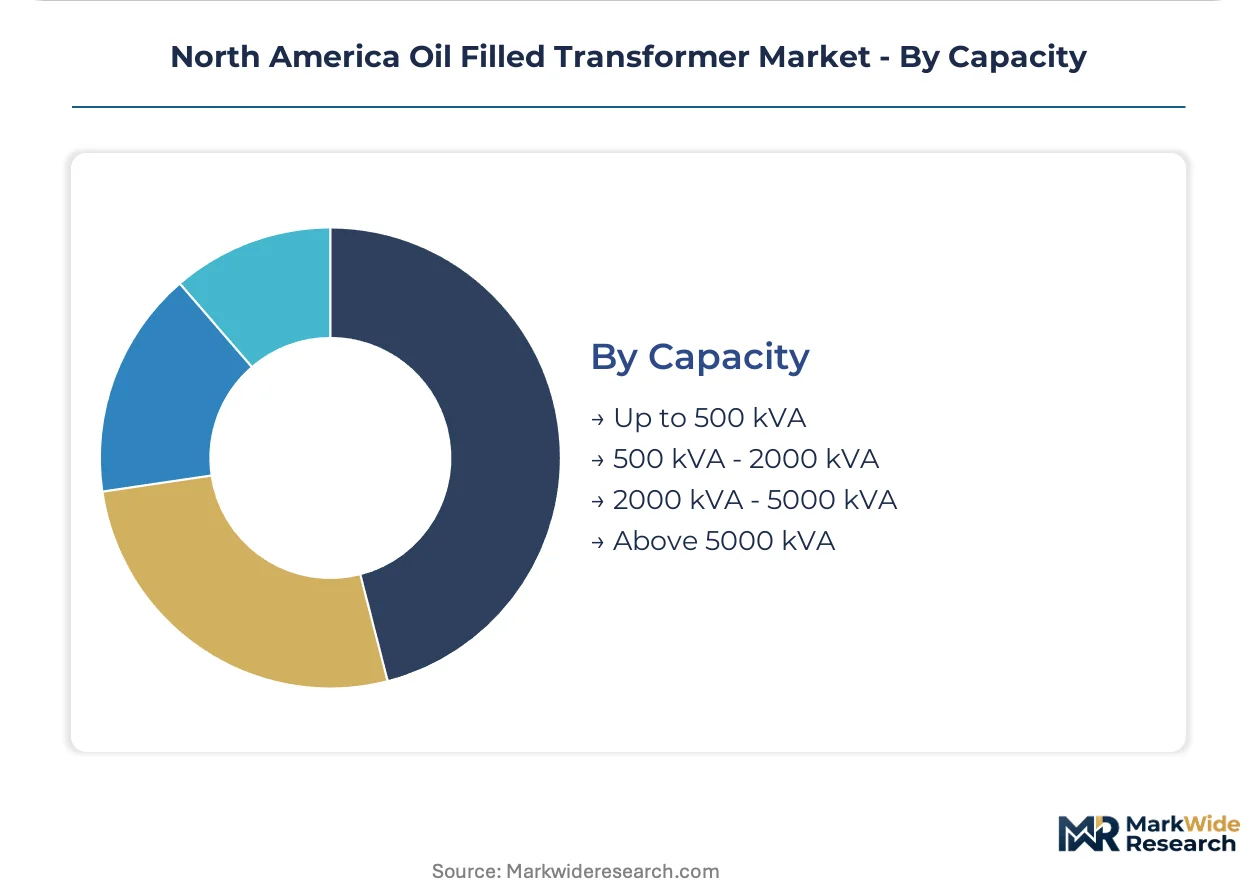
Oil filled transformer procurement patterns diverge sharply across voltage classes and deployment environments. Understanding these segment boundaries clarifies where efficiency mandates, interconnection timelines, and fluid substitution pressures concentrate competitive investment.
Product Type:
Volume concentration favors standard three-phase designs, while premium positioning attaches to specialized sealing technologies for harsh environments.
- Single-Phase:Compact pole-mounted units serve rural distribution feeders and residential tap lines. Demand clusters in Midwest agricultural regions and Rocky Mountain utilities where low-density load patterns predominate.
- Three-Phase:These configurations dominate utility procurement through superior power density and lower per-MVA infrastructure cost. ERCOT and CAISO interconnection queues are pulling record orders for step-up variants.
- Hermetically Sealed:Welded-tank designs eliminate oil expansion chambers, suiting contaminated or altitude-challenged sites. Mining operations in Nevada and Alberta oil sands specify these for reduced maintenance exposure.
- Non-Hermetically Sealed:Conventional conservator-tank construction remains the default for accessible substation installations. EPA efficiency rulemakings are accelerating core redesigns across this largest-volume category.
Mature deployment sits with Non-Hermetically Sealed units. Newer deployment is concentrated in Hermetically Sealed designs for extreme-environment reliability.
End User:
Application economics separate regulated utilities from private developers, with divergent procurement timelines and lifecycle cost calculations.
- Utilities:Investor-owned and municipal operators drive baseline demand through fleet replacement and grid expansion. FERC interconnection backlogs are compressing procurement cycles for transmission-grade units.
- Industrial Facilities:Petrochemical complexes, steel mills, and data centers require dedicated substations with high fault-current tolerance. Gulf Coast chemical corridor demand is climbing with reshoring announcements.
- Commercial Buildings:High-rise developments and hospital campuses specify compact pad-mounted designs. Urban density constraints in Toronto and Manhattan favor low-noise, reduced-footprint configurations.
- Renewable Energy:Wind and solar farms require step-up transformers for transmission-level voltage integration. West Texas solar and Great Plains wind projects are expanding most quickly within this segment.
Established procurement patterns sit with Utilities. Accelerating deployment is concentrated in Renewable Energy developers racing interconnection deadlines.
Installation Type:
Physical deployment constraints split between permanent infrastructure and contingency mobility requirements.
- Indoor:Vault and building-integrated installations serve urban substations and critical facility backup power. Fire-code restrictions in Chicago and Boston are pushing ester fluid specifications.
- Outdoor:Open-air substation deployment retains the largest share, reflecting transmission and distribution infrastructure predominance. Coastal corrosion protection is becoming standard for Gulf and Atlantic installations.
- Stationary:Fixed foundation-mounted units constitute the overwhelming majority of utility asset bases. Seismic anchoring requirements tightened post-2011 for Pacific Coast installations.
- Mobile:Trailer-mounted emergency replacement units address storm recovery and planned outage bridging. Hurricane-prone Southeast utilities maintain regional mobile transformer fleets.
Conventional infrastructure sits with Stationary Outdoor installations. Contingency investment is climbing fastest in Mobile configurations for resilience planning.
Capacity:
Scale thresholds align with voltage step requirements and thermal loading profiles across the grid hierarchy.
- Up to 500 kVA:Distribution-class units serve residential feeders and small commercial loads. Amorphous metal core adoption is penetrating this segment fastest for loss reduction.
- 500 kVA - 2000 kVA:Medium distribution blocks handle commercial districts and light industrial parks. Urban underground network transformers in this range face space-constrained replacement cycles.
- 2000 kVA - 5000 kVA:Substation entry units aggregate multiple distribution feeders. Renewable collector substations in California and Texas are specifying this range for solar farm aggregation.
- Above 5000 kVA:Bulk power and generator step-up transformers interface with transmission networks. Manufacturing lead times for these units now stretch beyond 24 months due to core steel and winding capacity constraints.
Replacement cycles sit with 500 kVA - 2000 kVA units. Capacity expansion is concentrating in Above 5000 kVA designs for transmission-level renewable interconnection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel production concentrates in the Ohio River Valley and Great Lakes industrial corridor, anchoring transformer manufacturing capacity across the continent. This feedstock locality shapes procurement radii and logistics economics for utility-scale equipment deployment.
United States
Texas ERCOT interconnection queues and California renewable mandates drive step-up transformer procurement at unprecedented scale. The EPA enforces Energy Policy Act efficiency tiers that force core redesigns through 2027. West Texas solar farms and Panhandle wind projects concentrate demand for 345 kV class units.
Canada
Quebec and British Columbia hydroelectric expansion requires bulk power transformers for remote site interconnection. Health Canada coordinates with provincial utilities on environmental compliance for mineral oil and ester fluid installations. Ontario manufacturing clusters in Hamilton and Toronto supply distribution-class units to cross-border utility customers.
Mexico
Northern border states absorb manufacturing reshoring demand as US utilities diversify procurement geography. The country's national energy regulator oversees grid code harmonization with NEMA and IEEE standards. Monterrey industrial parks host winding and assembly operations serving Southwest US renewable developers.
North America Oil Filled Transformer Market Vendor Landscape
Global majors compete with regional champions across manufacturing footprint and domestic content qualification. The vendor base splits between consolidated integrated electrical equipment conglomerates and specialized transformer fabricators with narrow product focus. Three archetypes dominate: vertically integrated energy technology platforms, regional winding specialists with utility relationships, and mid-tier efficiency-focused challengers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as lead times stretch beyond 24 months for transmission-grade units.
Among integrated technology platforms, GE Vernova and Siemens Energy exemplify the scale-driven archetype with broad utility contracting reach. Hitachi Energy occupies a position within the high-voltage specialization tier, anchoring extra-high-voltage design capability for renewable interconnection projects. Virginia Transformer represents the regional specialist archetype, sitting within the domestic fabricator tier with concentrated utility relationships in the Eastern and Midwestern United States.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Schneider Electric |
| Hitachi Energy |
| Eaton |
| Niagara Power Transformer |
| Virginia Transformer |
| MGM Transformer Company |
| Northern Transformer |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators with multi-decade utility relationships anchor pricing discipline through long-term service contracts that bundle installation, commissioning, and predictive maintenance. Their ownership structure enables patient capital allocation toward core-steel inventory buffers that insulate customers from commodity volatility. This concentration of specialized manufacturing capacity shapes how procurement teams negotiate total cost of ownership across efficiency tiers.
Pricing Analysis
Extended warranty and field-service bundling separates premium-tier suppliers from unbundled transactional competitors in utility procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in core-steel grade, IEEE certification tier, and geographic delivery radius. Cost compression in economy-tier distribution units is intensifying because amorphous metal core adoption narrows the efficiency gap at lower price points. Municipal utilities exhibit the highest price sensitivity due to rate-case scrutiny, while investor-owned operators prioritize lifecycle loss reduction over upfront capital outlay.
Supply Chain Analysis
Domestic-content bonuses under the Inflation Reduction Act are reshaping sourcing patterns toward captive North American core lamination capacity. Grain-oriented electrical steel production concentrates in the United States, Canada, and Mexico, with Ohio River Valley mills feeding winding operations across the continent. Transformer-grade steel, copper winding wire, and insulating mineral oil draw from metallurgical and petrochemical supply chains vulnerable to capacity constraints at specialized mills. Single-source vulnerability in electrical steel exposes procurement to mill outage risk. Distribution runs through direct utility contracting with dedicated production line allocation rather than distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where extended manufacturing lead times and specialized engineering expertise are forcing sub-scale fabricators toward strategic exit or acquisition.
For Market Incumbents: Cement utility relationships through multi-year framework agreements with price-adjustment mechanisms that lock in dedicated production capacity. Expand backward integration into core-steel slitting and lamination to capture Inflation Reduction Act domestic content bonuses while insulating against mill concentration risk. Prioritize amorphous metal core certification investments to defend against emerging efficiency-tier challengers. For New Entrants and Emerging Players: EPC contractors serving West Texas solar and Panhandle wind developers represent the most accessible channel for wedge positioning without incumbent utility relationships. Target mobile transformer leasing and emergency replacement services where hurricane-prone Southeast utilities maintain contingency fleets. Pursue infrared thermography integration partnerships to establish predictive maintenance recurring revenue before competing on unit manufacturing. For Investors and Strategic Acquirers: IEEE C57 certification backlog clearance is the leading indicator that engineering-constrained fabricators are unlocking commercialization capacity for redesigned efficiency-tier units. The five-to-ten-year viability window favors acquisition of regional winding specialists with established utility relationships and dormant manufacturing footprint suitable for core-steel integration. Monitor FERC interconnection queue processing velocity as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core-Steel Lamination | Captures Inflation Reduction Act credits while securing supply from Ohio River Valley mills. |
| Amorphous Metal Core Certification Investment | Positions suppliers for EPA Energy Policy Act efficiency tier compliance without premium silicon steel dependency. |
| Multi-Year Utility Framework Agreements | Locks in dedicated production allocation as ERCOT interconnection queues stretch procurement cycles. |
| Infrared Thermography Service Integration | Transforms OEM service divisions into recurring revenue platforms through predictive maintenance contracts. |
| Mobile Transformer Fleet Expansion | Addresses hurricane resilience planning among Southeast utilities with contingency deployment capabilities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with utility procurement officers, transformer design engineers, EPC project developers, and aftermarket service directors. EPA rulemaking dockets, DOE efficiency standard notices, FERC interconnection queue reports, and IEEE standards documentation provided regulatory and technical validation. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure disclosures.
Reconciliation of manufacturer order backlogs, utility interconnection timelines, and core-steel mill capacity data shaped the analytical framework across the projection horizon. Segmentation modeling incorporated voltage class, end-user archetype, installation environment, and capacity tier dimensions. CAGRs derived from unit volume trajectories and average selling price evolution through efficiency-tier transitions. Forecast inputs included renewable energy interconnection queue velocity, grain-oriented electrical steel production capacity, and EPA rulemaking implementation schedules.
Caveats apply where tariff policy shifts, mill capacity expansion delays, or accelerated efficiency standard tightening could materially shift the outlook. Forecasts reflect assumptions about domestic content qualification thresholds and utility rate-case approval timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
China Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
Amorphous Core Transformers Market
Transformers
Cast Resin Transformers Market
Transformers
Global Large Power Transformers Market
Transformers
Air Cooled Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
United Arab Emirates Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Saudi Arabia Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Rectifier Transformers Market
Transformers
India Distribution Transformer Market
Transformers
Distribution Transformer Market
Transformers
Transformer Core Market
Transformers
Middle-East Smart Transformer Market