
 Global Transformer Market | 2026-2036
Global Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transformer Market Outlook
After-sales maintenance contracts and software-defined monitoring layers are recalibrating how transformer vendors capture lifetime value from utility customers. Hitachi Energy leverages its digital transformer portfolio to extend service revenue beyond hardware shipment. Siemens Energy anchors its competitive stance through integrated asset management platforms that reduce unplanned downtime for grid operators. ABB competes by embedding predictive analytics into oil-immersed units sold to European and North American utilities.
A transformer is a static electromagnetic device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 or 60 hertz with voltage ratings spanning from distribution-level 11 kV to ultra-high-voltage 1,100 kV. Its core function is to step up or step down alternating-current voltages to enable efficient long-distance transmission and safe end-use distribution across power networks. Power transformers occupy the dominant share of value given their critical role in bulk energy transfer and long asset life cycles, while dry-type technology segments are gaining traction in urban commercial installations where fire safety and reduced maintenance drive specification decisions. The renewable energy end-user category represents the fastest-growing demand pool as wind and solar farms require specialized step-up transformers to connect variable output to transmission grids.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that directly dictate core loss limits and conductor material choices for distribution transformers sold domestically. China's National Energy Administration and the State Grid Corporation impose GB standards that mandate localized testing and certification, creating structural barriers for non-domestic manufacturers seeking utility contracts. India's Central Electricity Authority notification on transformer efficiency and the Bureau of Indian Standards specifications for insulation and short-circuit withstand capacity shape procurement criteria for state distribution companies. Stakeholders must monitor how divergent efficiency timelines across these jurisdictions affect inventory planning and platform standardization strategies.
Market Dynamics
Grid operators in China, Germany, and the United States are simultaneously retiring transmission assets installed during the 1960s-1980s buildout while integrating inverter-based renewable generation, creating a bifurcated procurement environment where legacy replacement and new-connectivity specifications diverge.
Growth Catalysts
- EU Ecodesign Directive efficiency mandates:Tiered loss limits for distribution transformers are accelerating amorphous metal core adoption across European utilities seeking compliance ahead of enforcement deadlines.
- Offshore wind farm buildouts:Floating and fixed-bottom installations in the North Sea and East Asian waters require specialized step-up transformers rated for marine environments and variable loading profiles.
- India's Green Energy Corridors:Central Electricity Authority transmission strengthening programs are channeling state capital toward high-capacity interconnections linking renewable-rich states to demand centers.
Market Restraints
- Grain-oriented electrical steel concentration:Japanese and European steelmakers control premium core material supply, exposing transformer OEMs to alloying element price volatility and allocation rationing during demand surges.
- Copper conductor cost exposure:Winding material represents 25-35% of unit manufacturing cost, with London Metal Exchange price swings compressing margin visibility for long-lead utility contracts.
- GB standards localization barriers:China's mandatory in-country testing and certification requirements structurally limit non-domestic manufacturers from competing for State Grid Corporation bulk procurement tenders.
Strategic Opportunities
- Brazil's transmission auction pipeline:ANEEL regulatory frameworks are opening concession opportunities for foreign equipment suppliers meeting local content thresholds through joint manufacturing arrangements.
- Solid-state transformer convergence:Silicon carbide power electronics married to conventional magnetic cores enable bidirectional power flow and reactive compensation for microgrid applications.
- Digital twin service layers:Software-defined monitoring and predictive maintenance subscriptions extend vendor revenue streams beyond hardware shipment across European and North American installed bases.
Industry Challenges
- Specialized winding technician scarcity:Vacuum pressure impregnation and epoxy resin casting expertise is concentrating among aging workforces in Germany and Japan, constraining production scaling for dry-type units.
- IEC 60076-7 thermal model certification timelines:Extended validation protocols for load guide compliance are elongating product launch cycles and freezing design iterations mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transformer Market |
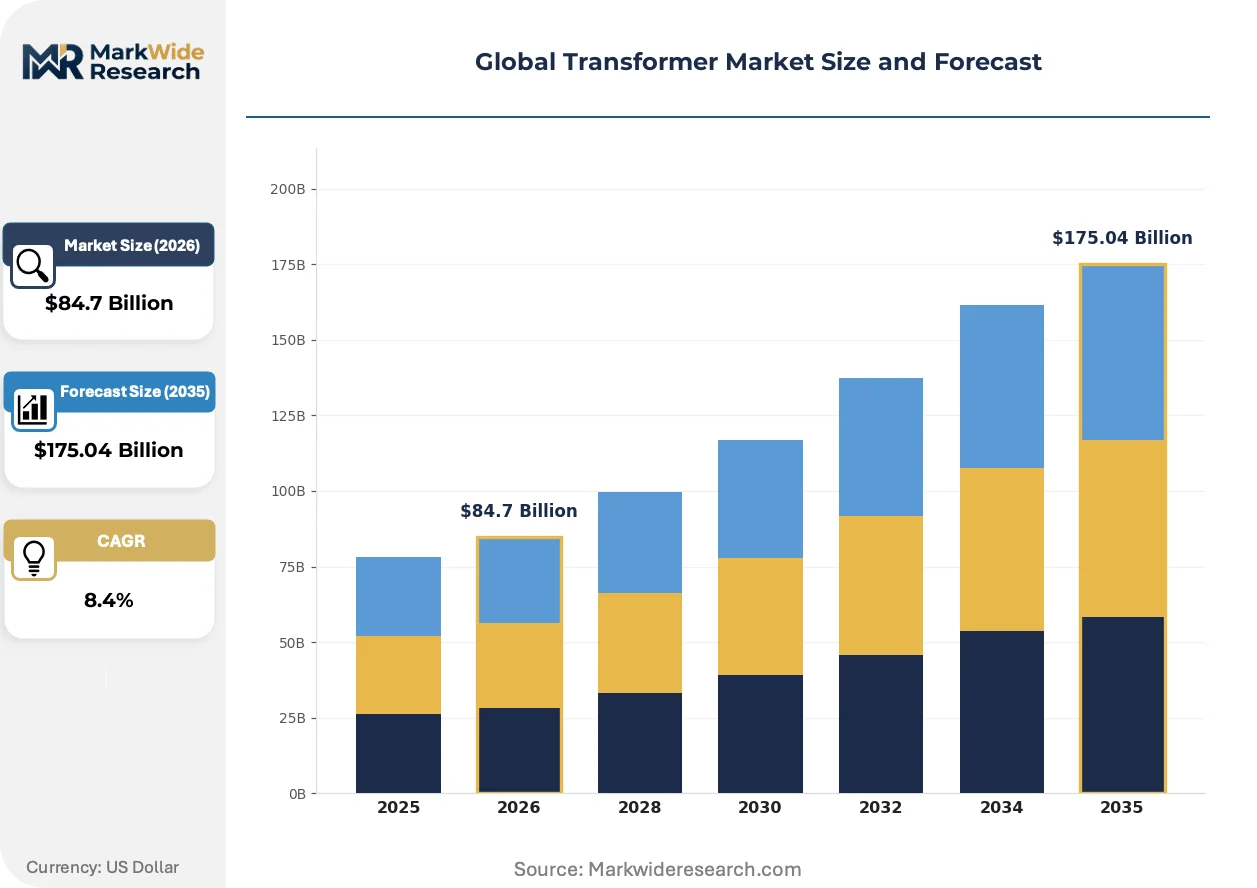
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $175.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Power Transformer, Distribution Transformer, Instrument Transformer, Rectifier Transformer Technology: Air Cooled, Oil Immersed, Gas Insulated, Dry Type End User: Utility, Industrial, Commercial, Renewable Energy Installation: Stationary, Mobile, Modular, Compact |
| Companies Covered | Hitachi Energy, Siemens Energy, GE Vernova, ABB, Mitsubishi Electric, General Electric, Toshiba Energy Systems & Solutions, Eaton Corporation, Hyundai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transformer Market Strategic Shifts
Transformer architecture is bifurcating between maximized efficiency for grid-connected bulk power and modularity for distributed energy resource integration, with material science and embedded intelligence driving divergence from standardized product platforms.
Amorphous metal core technology is integrating into distribution transformer designs to slash no-load losses below conventional grain-oriented silicon steel thresholds. European utilities facing EU Ecodesign Directive tiered mandates are specifying amorphous units for urban substations where load profiles favor static efficiency over peak capacity. This material transition is compressing the total cost of ownership calculus for municipal distribution companies evaluating 30-year asset life cycles.
REACH regulation amendments restricting mineral oil formulations are accelerating bio-based and synthetic ester adoption for liquid-immersed units in European installations. Industrial consequences include reformulated insulation systems requiring compatibility testing with existing gasket materials and expansion tank designs. German TSOs and Scandinavian utilities are responding fastest, embedding ester specifications into technical procurement documents ahead of formal mandate deadlines.
Utility procurement departments are unbundling hardware purchase from lifecycle service obligations, separating transformer delivery from condition monitoring and predictive maintenance contracts. Equipment vendors face margin compression on unit sales while competing for recurring software and field service revenue. This behavioral shift is most visible among North American investor-owned utilities restructuring vendor relationships under integrated asset management frameworks.
Global Transformer Market Segmentation
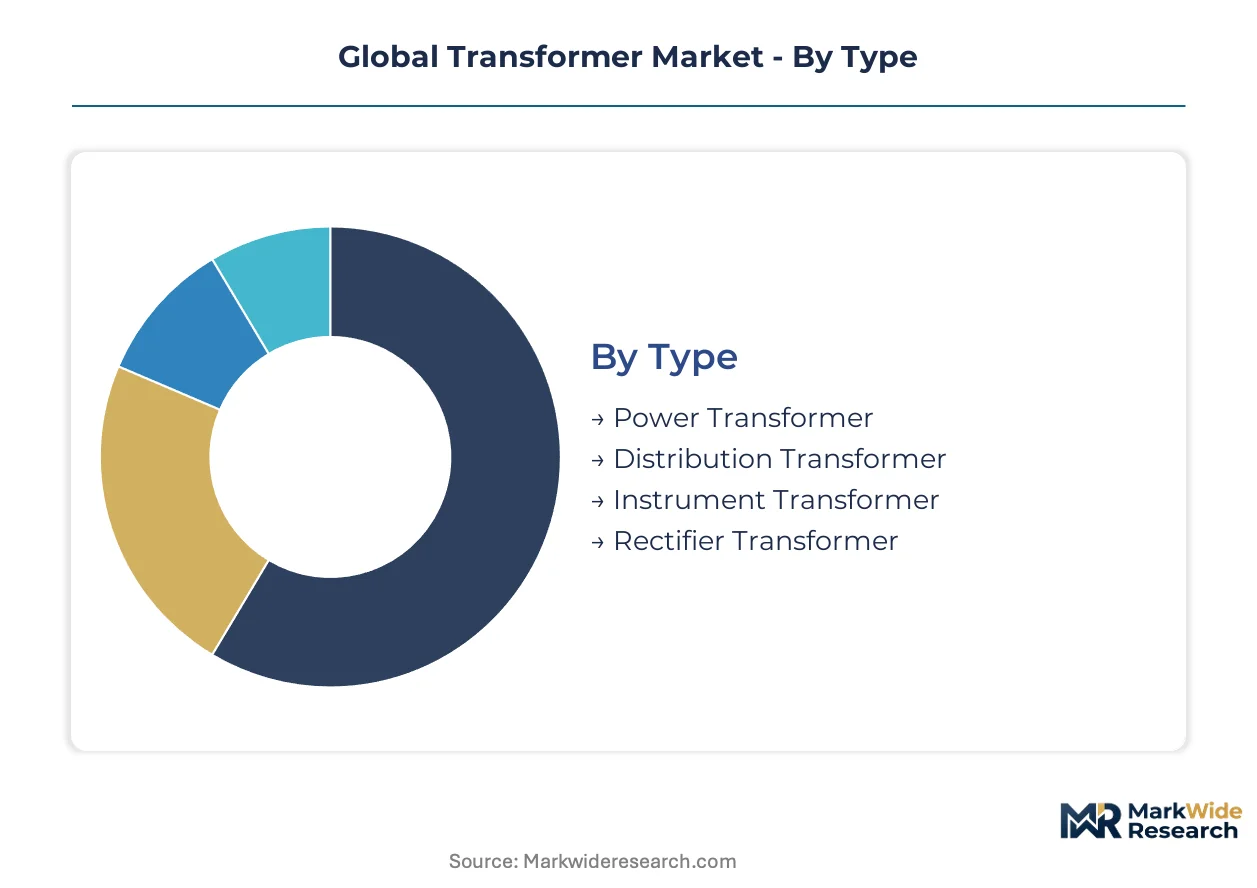
Transformer procurement patterns diverge sharply across application contexts, with voltage ratings and cooling architectures dictating capital deployment cycles. Segment-specific specifications determine raw material intensity, manufacturing lead times, and aftermarket service attach rates for equipment vendors.
Type:
Capital intensity peaks in bulk power infrastructure, where unit costs scale exponentially with voltage class and megavolt-ampere ratings.
- Power Transformer:These units handle transmission-level voltages from 66 kV to 1,100 kV with ratings exceeding 100 MVA, requiring specialized transport logistics and on-site assembly. State Grid Corporation in China and German TSOs dominate procurement for interconnection corridors and offshore wind integration projects, with lead times stretching 18-24 months due to core steel allocation constraints.
- Distribution Transformer:Step-down units operating at 11-33 kV serve last-mile connectivity, with EU Ecodesign Directive loss mandates accelerating amorphous metal core adoption. European municipal utilities prioritize no-load efficiency for urban substations where load profiles favor static performance over peak capacity.
- Instrument Transformer:Voltage and current sensing devices provide metering and protection inputs for grid automation systems. These units require precision winding tolerances and IEC 61850 communication compatibility for digital substation deployments.
- Rectifier Transformer:Specialized designs feed high-current DC industrial processes including aluminum smelting and chlorine electrolysis. Chinese and Middle Eastern industrial complexes drive specification demand for 12-pulse and 24-pulse configurations.
Most installed capacity flows through Distribution Transformer. Expansion is steepest in Power Transformer.
Technology:
Cooling architecture selection hinges on fire safety codes, maintenance access constraints, and thermal performance requirements across installation environments.
- Oil Immersed:Mineral oil or ester fluid provides superior heat dissipation for high-power density applications. German and Scandinavian utilities are transitioning to synthetic ester formulations ahead of REACH regulation amendments restricting traditional mineral oil chemistries.
- Dry Type:Cast resin or vacuum pressure impregnated windings eliminate fire and spill risks for indoor commercial and urban substation installations. Japanese and German manufacturers face production constraints due to specialized epoxy resin casting technician scarcity.
- Air Cooled:Natural or forced convection designs serve lower-power applications where maintenance simplicity outweighs thermal efficiency tradeoffs. These units find niche deployment in remote mining and telecommunications infrastructure.
- Gas Insulated:Sulfur hexafluoride or fluoronitrile mixtures enable compact footprints for space-constrained urban substations and offshore platforms. European F-Gas Regulation phase-down timelines are compressing adoption windows for SF6-dependent designs.
Oil Immersed retains the largest installed base. Dry Type is climbing the fastest due to urban fire code tightening.
End User:
Customer procurement behavior splits between regulated rate-base frameworks and merchant industrial contracting, with divergent risk allocation and service bundling expectations.
- Utility:Grid operators in China, Germany, and the United States account for the dominant procurement volume under integrated asset management frameworks. These customers are unbundling hardware purchase from predictive maintenance and digital twin service subscriptions.
- Renewable Energy:Wind and solar developers require specialized step-up transformers for variable output integration. Offshore wind farms in the North Sea and East Asian waters are specifying marine-rated units with enhanced corrosion protection.
- Industrial:Heavy manufacturing and process industries prioritize reliability-centered maintenance protocols. Steel, cement, and chemical facilities in India and Brazil are modernizing captive power infrastructure.
- Commercial:Data centers, hospitals, and retail complexes specify compact dry-type units for indoor electrical rooms. Fire safety and reduced insurance premiums drive specification decisions for cast resin designs.
Utility channels command the greatest absolute volume. Renewable Energy is gaining share fastest as generation buildouts accelerate.
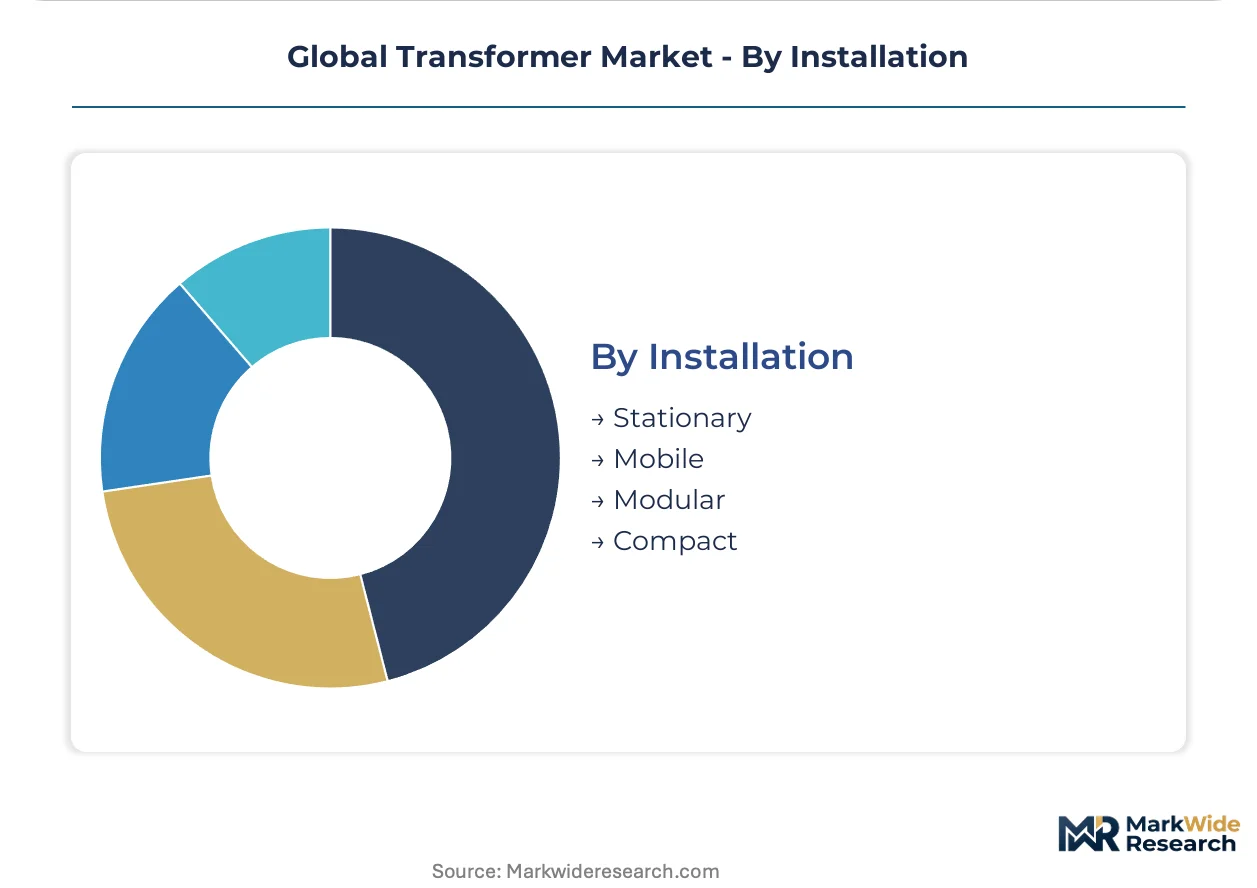
Installation:
Deployment flexibility requirements are segmenting procurement between permanent infrastructure and temporary or relocatable power solutions.
- Stationary:Fixed substation installations represent the conventional deployment mode for grid infrastructure. Chinese and Indian transmission strengthening programs are channeling capital toward permanent high-capacity interconnections.
- Modular:Factory-integrated substation packages reduce on-site construction timelines and labor requirements. These configurations are penetrating North American utility procurement for rapid deployment scenarios.
- Mobile:Trailer-mounted or skid-based units serve emergency restoration and construction power applications. Storm response and grid hardening initiatives in the United States are expanding rental fleet demand.
- Compact:Reduced-footprint designs address space constraints in dense urban environments and offshore platforms. Japanese metropolitan utilities and European offshore wind developers are specifying these variants.
Stationary configurations anchor the existing asset base. Modular approaches are expanding most quickly as utilities compress project delivery schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China approach transformer procurement through fundamentally different regulatory lenses, yet both are accelerating high-voltage interconnection investments to accommodate renewable integration timelines.
China
State Grid Corporation dominates procurement for 1,100 kV ultra-high-voltage corridors linking western generation basins to eastern demand centers. GB standards mandate in-country testing and certification, structurally limiting non-domestic OEM participation in bulk tenders. The Yangtze River Delta cluster concentrates manufacturing capacity for amorphous metal core distribution units serving municipal utilities.
United States
Investor-owned utilities are unbundling hardware purchase from digital service subscriptions under integrated asset management frameworks. The US Department of Energy enforces 10 CFR 431 efficiency standards that dictate core loss limits and conductor specifications. Gulf Coast and Midwest transmission operators are expanding mobile transformer fleets for storm hardening and emergency restoration.
Germany
TenneT and 50Hertz are procuring specialized units for North Sea offshore wind integration, with synthetic ester insulation specifications accelerating ahead of REACH amendment deadlines. The EU Ecodesign Directive tiered loss mandates are reshaping distribution transformer procurement for urban substations. Bavarian and Baden-Württemberg industrial zones anchor manufacturing expertise for vacuum pressure impregnated dry-type designs.
India
The Central Electricity Authority's Green Energy Corridor program is channeling state capital toward high-capacity interconnections linking Rajasthan and Gujarat solar zones to Maharashtra and Tamil Nadu demand centers. Bureau of Indian Standards specifications for short-circuit withstand capacity and insulation integrity shape DISCOM procurement criteria. Gujarat and Karnataka clusters are emerging as domestic manufacturing hubs for 33 kV distribution units.
Brazil
ANEEL transmission auctions are opening concession opportunities for foreign equipment suppliers meeting local content thresholds through joint manufacturing arrangements. State-owned utility Eletrobras is modernizing aging 1960s-1980s transmission assets while integrating Amazon basin hydroelectric output. São Paulo and Minas Gerais industrial corridors concentrate demand for rectifier transformers serving aluminum and steel processing facilities.
Global Transformer Market Competitive Environment
Top-tier vendors anchor high-voltage power transformer supply, while mid-tier specialists concentrate on distribution-class units and digital service layers. Market structure reflects consolidation around integrated energy majors with captive grid automation portfolios, alongside fragmentation among regional fabricators serving utility procurement localization requirements. Strategic archetypes include full-lifecycle service integrators, amorphous metal core technology specialists, and modular substation package providers. Competitive moves center on predictive maintenance platform deployment and joint venture manufacturing arrangements to satisfy local content mandates.
Within the integrated energy major tier, Hitachi Energy and Siemens Energy exemplify full-lifecycle positioning through digital transformer portfolios and asset management platforms. ABB occupies a position bridging hardware supply and predictive analytics embedding for European and North American utilities. These three entities represent the dominant competitive anchors against which regional specialists and technology-focused entrants define differentiated positioning.
| Leading Market Players |
|---|
| Hitachi Energy |
| Siemens Energy |
| GE Vernova |
| ABB |
| Mitsubishi Electric |
| General Electric |
| Toshiba Energy Systems & Solutions |
| Eaton Corporation |
| Hyundai Electric |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange copper price volatility cascades through transformer manufacturing into three-tier pricing structure across premium, standard, and economy levels, with Japanese and European grain-oriented electrical steel allocations compressing margin visibility for long-lead utility contracts. Procurement departments in China and Germany are unbundling hardware from service subscriptions, forcing OEMs to defend position through backward integration into core material supply or captive maintenance revenue streams.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for distribution-class units while premium power transformer tiers anchored in German and Japanese manufacturing expertise maintain pricing power through amorphous metal core certification and synthetic ester insulation specifications. Cost compression in standard-tier units intensifies because copper conductor exposure represents 25-35% of unit manufacturing cost. Municipal utilities in India exhibit highest price sensitivity due to DISCOM budget constraints, while offshore wind developers in the North Sea demonstrate lowest sensitivity given marine-rated specification premiums.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China anchor hub-and-spoke patterns for transformer core steel and winding materials, with specialized logistics for 1,100 kV ultra-high-voltage units requiring on-site assembly coordination. Raw material dependencies center on grain-oriented electrical steel from Nippon Steel and ThyssenKrupp, copper cathode from Chilean and Indonesian smelters, and epoxy resin formulations for dry-type casting. Single-source vulnerability concentrates in premium core steel alloying elements. Distribution runs through utility-direct procurement channels for bulk power units and electrical distributor networks for distribution-class replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on amorphous metal core adoption accelerating ahead of EU Ecodesign Directive enforcement, allowing certified OEMs to capture premium pricing while conventional silicon steel competitors face cost-down pressure.
For Market Incumbents: Anchor defensive positioning through backward integration into grain-oriented electrical steel supply arrangements with Japanese or European mills, insulating against allocation rationing during demand surges. Deepen predictive maintenance platform deployment to capture recurring software revenue as North American utilities unbundle hardware from service contracts. Prioritize IEC 60076-7 thermal model certification investment to compress product launch cycles against emerging competitors. For New Entrants and Emerging Players: Begin with modular substation packages for Brazil's ANEEL transmission auction pipeline, exploiting local content thresholds through joint manufacturing arrangements with domestic fabricators. Target India's Green Energy Corridor program for 33 kV distribution unit penetration, where Bureau of Indian Standards compliance creates addressable entry barriers. Lead with solid-state transformer convergence demonstrations for microgrid applications, bypassing conventional magnetic core manufacturing scale requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with digital twin service layer specialists possessing installed-base monitoring contracts across European and North American utilities. Five-to-ten year viability favors asset-light software vendors with recurring revenue attachment to legacy transformer fleets rather than capital-intensive manufacturing scale plays. Watch for State Grid Corporation procurement tender participation rates by non-domestic OEMs as inflection indicator for GB standards localization barrier erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Manufacturing Scale-Up | EU Ecodesign Directive compliance positions European utilities for 30-year total cost of ownership advantages. |
| Synthetic Ester Insulation Transition | REACH amendment deadlines accelerate German TSO procurement ahead of mineral oil restriction enforcement. |
| Predictive Maintenance Platform Deployment | Hitachi Energy and Siemens Energy extend service revenue beyond hardware shipment through digital twin subscriptions. |
| Joint Venture Manufacturing Arrangement | Brazil's ANEEL local content thresholds open concession access for foreign suppliers through domestic partnership structures. |
| Solid-State Transformer R&D Investment | Silicon carbide power electronics enable bidirectional power flow for microgrid and distributed energy resource integration. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, transformer OEM procurement directors, EPC contractors, and grid operators with secondary validation against EIA electricity transmission data, IEA renewable integration reports, FERC interconnection filings, and State Grid Corporation tender documentation. Bottom-up unit shipment modeling across voltage classes and cooling architectures triangulated against top-down infrastructure investment forecasts from national regulators.
Segment-weighting approaches distributed value across power, distribution, instrument, and rectifier transformer categories, with technology splits between oil-immersed, dry-type, air-cooled, and gas-insulated designs, and end-user allocation across utility, renewable energy, industrial, and commercial channels. CAGRs were derived from infrastructure replacement cycles and renewable generation buildout trajectories. Forecast inputs incorporated GB standards localization barriers, EU Ecodesign Directive enforcement timelines, and copper price volatility assumptions.
Caveats apply where Chinese regulatory shifts on foreign OEM participation, REACH amendment acceleration on ester insulation mandates, or grain-oriented electrical steel supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Power Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Liquid Filled Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Transformer Steel Market
Transformers
India Distribution Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Transformer Oil Market
Transformers
High Frequency Transformer Market
Transformers
Transformer Core Market
Transformers
Amorphous Core Transformers Market