
 Liquid-Immersed Transformers Market | 2026-2036
Liquid-Immersed Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid-Immersed Transformers Market Outlook
Project finance tied to long-term power purchase agreements is narrowing the field of transformer suppliers capable of bidding on utility-scale deployments. ABB leverages its integrated manufacturing footprint across Europe and Asia to compete on delivery timelines for extra-high-voltage orders. Siemens anchors its position through R&D intensity in digital monitoring systems embedded within liquid-immersed units. CG Power and Industrial Solutions specializes in cost-optimized distribution transformers tailored to emerging market specifications.
Liquid-immersed transformers are electromagnetic devices that use dielectric fluid—mineral oil, natural ester, or synthetic ester—to insulate windings and dissipate thermal energy, typically operating at power ratings from 10 kVA to over 1,000 MVA depending on application. These units serve as critical voltage conversion and isolation nodes across generation, transmission, and distribution networks. Power transformers occupy the highest margin pool due to engineering complexity and extended qualification cycles for grid interconnection projects. Distribution transformers represent the largest volume segment, driven by rural electrification and urban densification programs across multiple continents. Natural ester insulation is gaining structural share as fire-safety and biodegradability requirements tighten in environmentally sensitive installations.
IEC 60076 standards govern thermal performance and short-circuit withstand for liquid-immersed transformers in international trade, while the EU F-Gas Regulation and REACH framework restrict certain synthetic fluids and mandate material traceability. IEEE C57 standards dominate North American procurement specifications, shaping product design for utilities operating under FERC interconnection rules. Stakeholders must monitor evolving cooling efficiency mandates and carbon accounting requirements that will determine supplier qualification criteria in forthcoming grid modernization tenders.
Market Dynamics
The EU F-Gas Regulation is forcing insulation substitution toward natural ester fluids, compressing mineral oil's historical dominance while reshaping supplier qualification requirements across European grid modernization tenders.
Growth Catalysts
- Rural Electrification Mandates:India's state distribution companies are accelerating procurement of distribution-class units under central government rural network modernization programs, creating sustained volume demand.
- Fire-Safety Regulation:The EU F-Gas Regulation and REACH framework are mandating biodegradable dielectric fluids in environmentally sensitive installations, structurally elevating natural ester adoption rates.
- Grid Hardening Investment:Utilities across emerging Asia are procuring forced-cooled extra-high-voltage transformers to address climate resilience requirements and interconnection bottlenecks.
Market Restraints
- Copper and Grain-Oriented Steel Volatility:Core winding and core material costs fluctuate with commodity cycles, compressing margin visibility for long-delivery transformer contracts.
- Qualification Cycle Duration:Extended type-testing and grid-interconnection certification timelines for power-class units delay revenue recognition and tie up working capital.
- Synthetic Ester Regulatory Friction:REACH substance restrictions and material traceability mandates are complicating supply chains for certain synthetic dielectric fluid formulations.
Strategic Opportunities
- Digital Monitoring Convergence:Embedded sensor arrays and edge analytics are virtualizing transformer health monitoring, enabling predictive maintenance service models for utility fleets.
- Natural Ester Production Scale-Up:Underdeveloped domestic ester refining capacity in India presents backward integration opportunities for suppliers seeking cost parity with mineral oil.
- Distribution Channel Digitization:E-procurement platforms and tender aggregation portals are disintermediating traditional distributor networks in emerging market segments.
Industry Challenges
- Specialized Winding Technician Scarcity:Precision coil winding and vacuum pressure impregnation skills are concentrating among aging workforces in Europe and North America.
- IEC-IEEE Standard Divergence:Harmonization gaps between international and North American thermal performance testing protocols complicate multi-region product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid-Immersed Transformers Market |
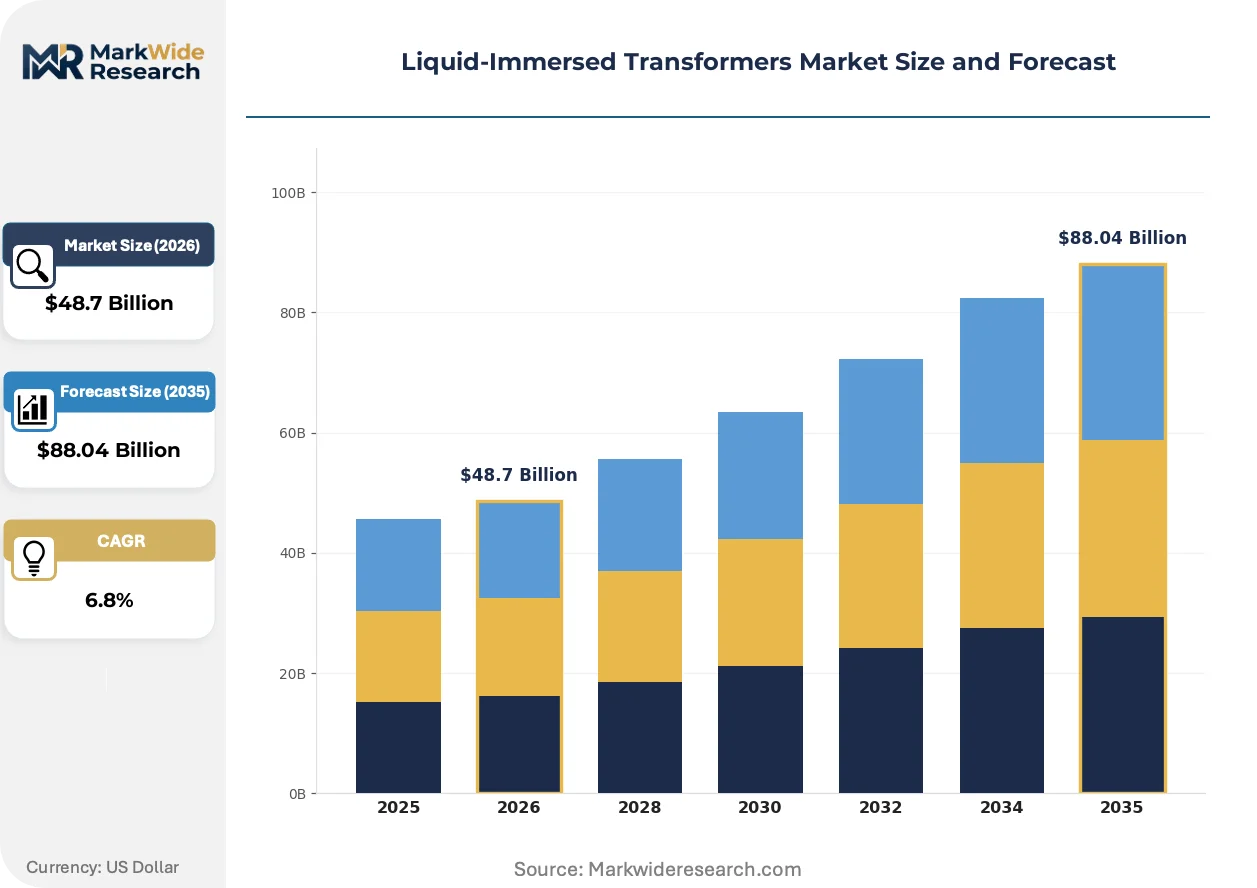
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distribution Transformers, Power Transformers, Instrument Transformers, Auto Transformers Insulation Type: Natural Ester, Synthetic Ester, Mineral Oil, Others Cooling Method: Self-Cooled, Forced-Cooled, Air-Cooled, Water-Cooled End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Schneider Electric, CG Power and Industrial Solutions, ABB, JSHP Transformer, Hyosung Heavy Industries, Siemens, China XD Group, TBEA, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid-Immersed Transformers Market Strategic Shifts
Digital instrumentation is penetrating liquid-immersed transformer architectures, converting passive assets into grid-edge data nodes that enable condition-based operational decisions.
Natural ester dielectric fluids derived from vegetable oil feedstocks are virtualizing fire-safety and environmental performance benchmarks for indoor and urban substation deployments. European utilities are specifying ester-insulated units for underground and densely populated installations where mineral oil leakage risks are prohibitive. This fluid transition is compressing the addressable market for conventional mineral oil formulations while elevating thermal performance requirements for winding insulation systems.
REACH substance restrictions and the EU F-Gas Regulation are eliminating certain synthetic fluid chemistries from approved procurement lists. Manufacturers are reformulating dielectric fluid portfolios to exclude restricted substances while maintaining oxidation stability and pour-point specifications. Power transformer tenders in Germany, France, and the Netherlands now mandate biodegradable fluid content thresholds that exclude legacy synthetic esters.
Utility procurement offices are consolidating transformer purchasing through multi-year framework agreements that bundle installation, commissioning, and digital monitoring services. This bundling is displacing transactional spot purchasing for distribution-class units in India and Southeast Asia. State-owned distribution companies in Maharashtra, Tamil Nadu, and Karnataka are piloting outcome-based service contracts where suppliers retain asset performance risk across extended operational periods.
Liquid-Immersed Transformers Market Segmentation
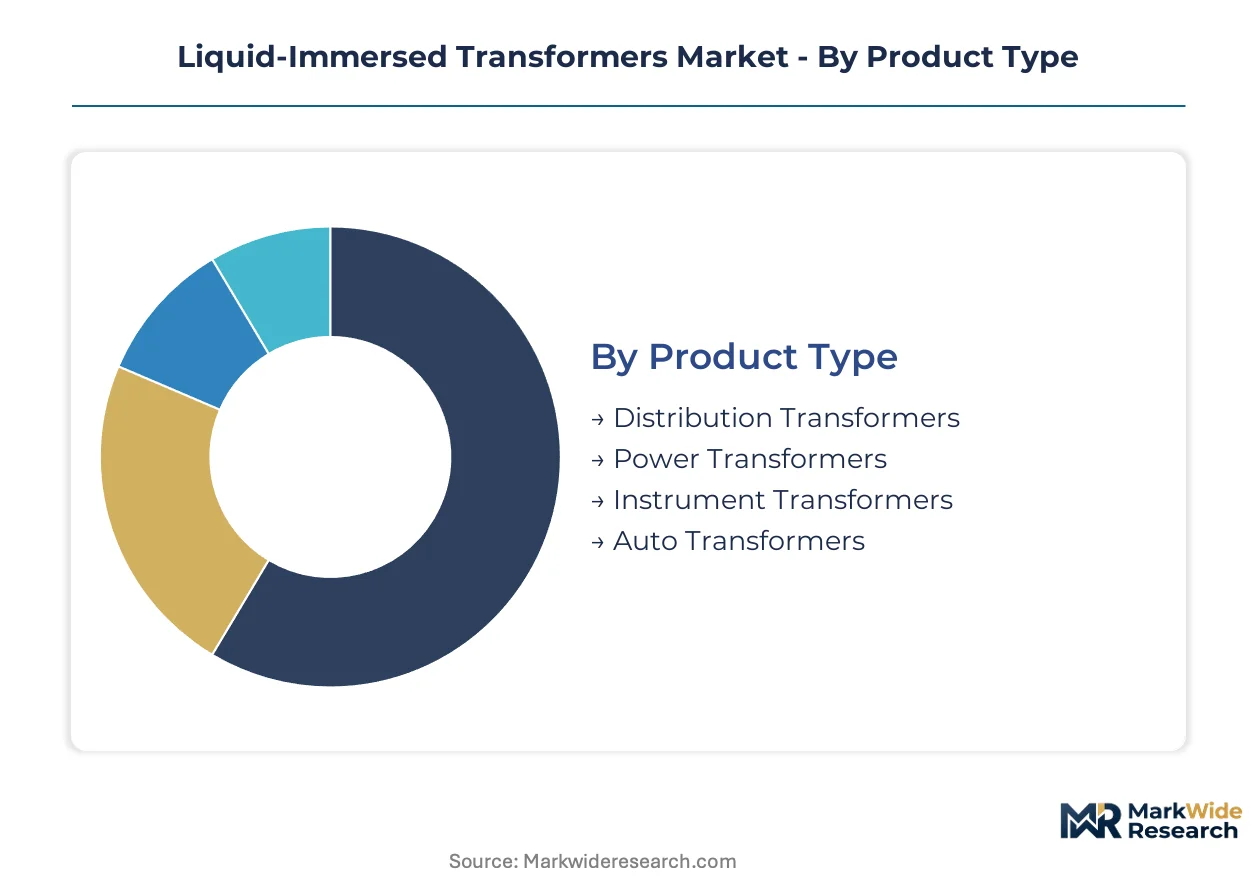
Liquid-immersed transformer configurations diverge sharply in service intensity, warranty exposure, and lifecycle revenue potential. Procurement patterns across product tiers reveal distinct margin architectures that reshape supplier positioning strategies.
Product Type:
After-sales-service intensity escalates dramatically from distribution through power classes, with field engineering requirements and spare parts logistics determining long-term contract profitability.
- Power Transformers:These high-voltage units operate above 100 MVA for transmission grid interconnection and generation step-up applications. Demand concentrates in Germany, India, and Brazil where transmission system operators are hardening corridors against climate stress. Extended qualification cycles and embedded digital monitoring systems generate multi-decade service revenue streams.
- Distribution Transformers:Units rated below 10 MVA serve last-mile voltage conversion for rural electrification and urban densification. Maharashtra, Tamil Nadu, and Karnataka state distribution companies in India are modernizing procurement through framework agreements that bundle installation and commissioning services.
- Instrument Transformers:These precision measurement devices isolate metering and protection circuits from high-voltage primary systems. IEC 60076 compliance requirements dominate international procurement specifications.
- Auto Transformers:Single-winding designs provide cost-efficient voltage transformation for closely-rated systems. Railway electrification and industrial substation retrofits in China and Japan drive specification volumes.
Distribution transformers hold the largest share; momentum sits with power transformers as grid interconnection bottlenecks intensify.
Insulation Type:
Cost tier differentiation separates premium biodegradable fluids from commodity mineral oil formulations, with regulatory mandates in European markets compressing the addressable market for conventional dielectrics.
- Natural Ester:Vegetable-oil-derived fluids deliver fire-safety and biodegradability performance for indoor and urban substation deployments. The EU F-Gas Regulation and REACH framework are structurally elevating adoption rates across German, French, and Dutch utility procurement lists.
- Mineral Oil:Petroleum-based dielectrics retain cost advantages in price-sensitive emerging markets. India's rural electrification programs and Southeast Asian distribution network expansions sustain volume demand despite environmental liability exposure.
- Synthetic Ester:Engineered fluid formulations offer oxidation stability and extended temperature performance. REACH substance restrictions are eliminating certain chemistries from approved procurement lists.
- Others:Silicone-based and hydrocarbon alternatives serve niche high-temperature or fire-resistance applications. Specialized industrial installations in Japan and South Korea specify these formulations for critical process continuity.
Mineral oil dominates volume; natural ester is climbing the fastest as regulatory thresholds tighten.
Cooling Method:
Application severity determines thermal management architecture, with forced-cooled designs commanding premium positioning for high-load-density installations.
- Forced-Cooled:Pump and fan systems enable compact packaging for extra-high-voltage transformers in space-constrained urban substations. Emerging Asian utilities are procuring these units for climate resilience and interconnection capacity expansion.
- Self-Cooled:Natural convection and radiation dissipate thermal loads without auxiliary power. Rural distribution networks across India and Africa favor these designs for operational simplicity and maintenance access constraints.
- Air-Cooled:Finned radiators augment heat rejection for moderate load profiles. Industrial captive power plants in China specify these configurations for cost-optimized medium-voltage applications.
- Water-Cooled:Heat exchanger integration enables extreme power density for generator step-up and HVDC converter stations. Coastal installations in Japan and South Korea leverage seawater cooling for thermal efficiency.
Self-cooled designs retain the largest installed base; forced-cooled configurations are gaining share fastest in high-voltage procurement.
End User:
Customer type segmentation reveals diverging procurement sophistication, with utility framework agreements consolidating supplier relationships against fragmented industrial spot purchasing.
- Utilities:State-owned and investor-owned grid operators dominate power and distribution transformer procurement through multi-year tenders. India's central government mandates are accelerating rural network modernization programs.
- Industrial:Manufacturing, mining, and petrochemical facilities specify specialized units for process power quality and reliability. captive power integration requirements in China and Brazil shape thermal performance specifications.
- Commercial:Data centers, hospitals, and large commercial complexes demand fire-safe ester-insulated designs for indoor installation. Urban densification in European and Japanese metropolitan areas elevates specification stringency.
- Residential:Single-phase pole-mounted units serve low-density rural electrification. India's Saubhagya scheme and similar programs across sub-Saharan Africa drive unit volume.
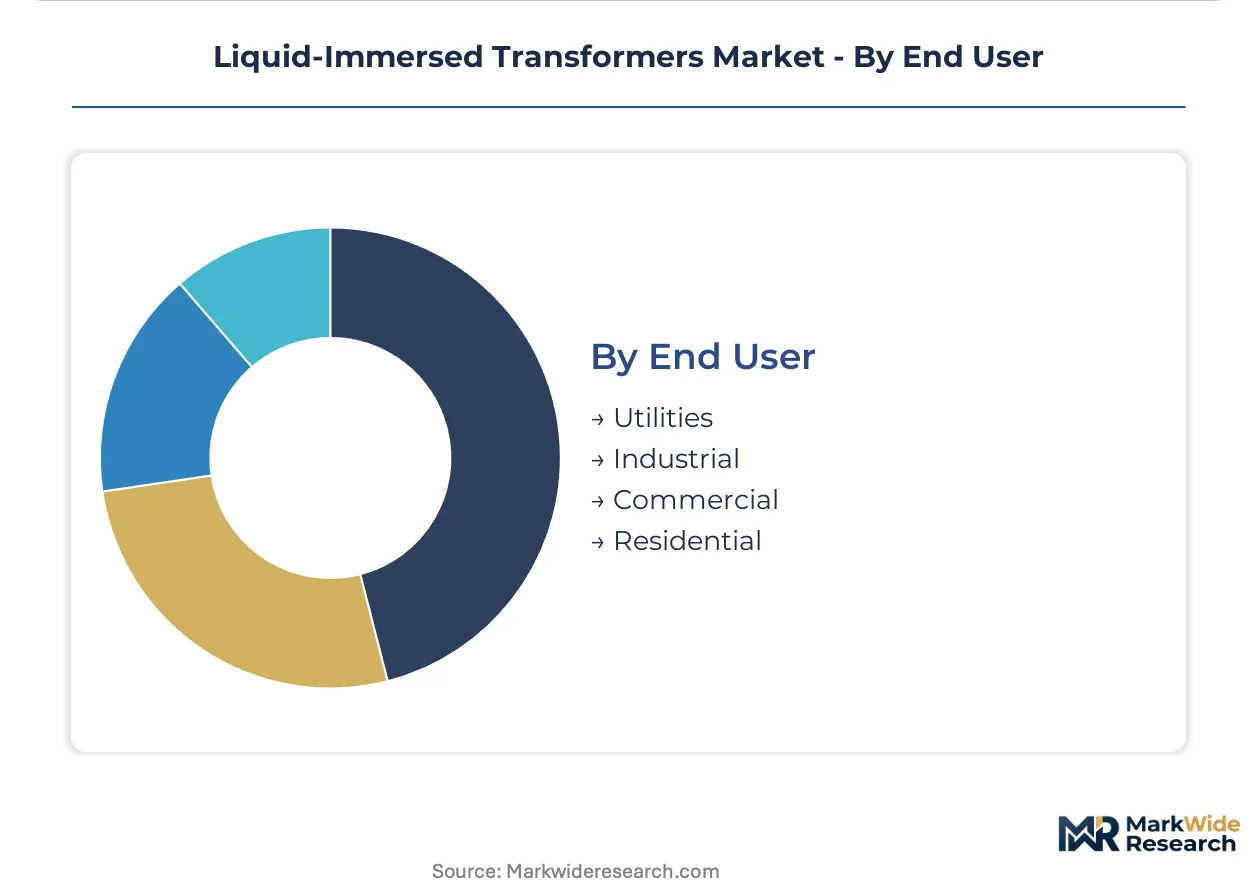
Utilities command the largest revenue share; industrial procurement is expanding most quickly as captive power and process reliability investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement offices in India, Germany, China, Brazil, and the United States concentrate transformer demand through multi-year framework agreements that reshape supplier qualification requirements across voltage classes.
India
Maharashtra, Tamil Nadu, and Karnataka state distribution companies are modernizing rural networks under central government mandates for universal electrification. The CEA enforces technical standards for distribution transformer efficiency and fire-safety performance. Domestic manufacturing clusters in Gujarat and Maharashtra are scaling natural ester refining capacity to reduce import dependence for biodegradable dielectric fluids.
Germany
Transmission system operators are hardening extra-high-voltage corridors against climate stress while integrating offshore wind interconnection capacity. The EU F-Gas Regulation and REACH framework mandate biodegradable fluid thresholds that exclude legacy synthetic esters from approved procurement lists. Industrial transformer fabricators in North Rhine-Westphalia are reformulating dielectric portfolios to maintain oxidation stability under stricter substance restrictions.
China
State Grid Corporation is procuring forced-cooled units for urban substation densification and ultra-high-voltage transmission expansion. GB standards and MIIT technical regulations govern thermal performance testing and short-circuit withstand certification. Manufacturing concentration in the Yangtze River Delta and Shandong Peninsula is driving cost optimization for distribution-class exports to Southeast Asian markets.
Brazil
Transmission concessionaires are investing in power transformer capacity to address interconnection bottlenecks between generation centers in the North and load centers in the Southeast. ANEEL regulatory frameworks shape procurement specifications for grid interconnection projects. Industrial transformer assembly in São Paulo and Minas Gerais states is expanding to serve captive power integration at mining and petrochemical facilities.
United States
Investor-owned utilities are replacing aging distribution infrastructure while integrating renewable generation zones requiring voltage conversion assets. FERC interconnection rules and IEEE C57 standards dominate procurement specifications for power-class units. Transformer manufacturing concentration in the Midwest and Texas is responding to lead-time pressures from utility hardening programs and data center electrification demand.
Liquid-Immersed Transformers Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement access through differentiated service bundling and qualification depth. The supplier base organizes into three tiers: integrated electrical conglomerates with multi-voltage portfolios, regional specialists focused on distribution-class cost optimization, and state-affiliated manufacturers serving captive domestic markets. Consolidation pressure intensifies as framework agreements bundle installation, commissioning, and digital monitoring services that favor scale. Competitive moves concentrate on backward integration into core materials and geographic expansion through local manufacturing joint ventures.
Within the integrated conglomerate tier, Schneider Electric, ABB, and Siemens exemplify archetypes combining manufacturing breadth with digital service platforms. Schneider Electric anchors European utility relationships through fire-safety-compliant ester-insulated portfolios. ABB occupies a position linking European and Asian manufacturing footprints for extra-high-voltage delivery timeline competitiveness. Siemens sits within the premium service tier through embedded monitoring system integration. These three represent positioning patterns visible across the competitive set rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Schneider Electric |
| CG Power and Industrial Solutions |
| ABB |
| JSHP Transformer |
| Hyosung Heavy Industries |
| Siemens |
| China XD Group |
| TBEA |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility amplifies price dispersion between Asian manufacturing clusters and European utility buyers, compressing margin buffers for mineral oil-based distribution units while elevating premium positioning for natural ester-insulated power transformers sourced through long-term framework agreements.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper and grain-oriented electrical steel benchmarks dominate procurement for utility-scale power transformers, with price differentiation hinging on IEC 60076 certification tier and bundled digital monitoring service depth. Distribution-class units face acute price compression in India's state tender markets where Maharashtra and Tamil Nadu discoms prioritize lowest-compliant-bid awards. Margin erosion intensifies for synthetic ester formulations as REACH substance restrictions eliminate certain fluid chemistries from approved supplier lists.
Supply Chain Analysis
Export control regimes restricting high-grade grain-oriented steel and precision winding equipment flows from Germany and Japan constrain capacity expansion for extra-high-voltage transformer manufacturing. Core material supply concentrates in China, South Korea, and Japan, with copper winding wire drawing from Chilean and Indonesian smelter output. Single-source vulnerability in specialized vacuum pressure impregnation resin feeds from European chemical producers elevates qualification risk for new manufacturing entrants. Distribution runs through utility framework agreements and EPC contractor specifications rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid-immersed transformer market functions as a regulatory-moat business where IEC 60076 and IEEE C57 certification entrenchment creates decade-long switching costs for utility procurement offices, insulating qualified suppliers from price-only competition.
For Market Incumbents: Insulate market position by deepening backward integration into natural ester refining capacity in Gujarat and Maharashtra to capture margin migrating from mineral oil substitution. Accelerate embedded sensor array deployment to convert hardware margins into predictive maintenance subscription revenue, defending against Chinese state-affiliated manufacturers competing on delivery timelines for distribution-class tenders.
For New Entrants and Emerging Players: Rural electrification procurement in Karnataka and sub-Saharan African markets presents the most penetrable white space, as established European and Japanese suppliers disengage from price-competitive distribution tenders below 10 MVA. Target outcome-based service contracts where asset performance risk retention differentiates against transactional spot vendors, leveraging digital monitoring partnerships with regional EPC contractors as primary go-to-market channel.
For Investors and Strategic Acquirers: The EU F-Gas Regulation's full implementation reshapes the acquisition landscape toward natural ester formulation capabilities and REACH-compliant fluid portfolios. Five-to-ten year viability favors mid-cap specialists with captive dielectric fluid production and established utility framework relationships. Monitor German and Dutch transmission operator tender specifications for biodegradable fluid mandate acceleration as the decisive inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Ester Refining Capacity Expansion | Backward integration into vegetable oil feedstock processing captures margin from EU F-Gas Regulation-driven substitution. |
| Embedded Digital Monitoring Platform Launch | Edge analytics integration converts ABB and Siemens hardware positions into recurring predictive maintenance revenue streams. |
| Multi-Year Framework Agreement Consolidation | Bundled installation and commissioning services displace spot purchasing in Maharashtra and Tamil Nadu state discom tenders. |
| REACH-Compliant Fluid Portfolio Reformulation | Elimination of restricted synthetic ester chemistries maintains German and Dutch utility procurement qualification. |
| Forced-Cooled Extra-High-Voltage Capacity Buildout | Climate resilience specifications in India and Brazil transmission corridors command premium positioning against self-cooled alternatives. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, transformer procurement leads at state distribution companies, EPC contractor project managers, and aftermarket service heads; and secondary validation through IEC 60076 certification databases, CEA technical standard filings, EU F-Gas Regulation implementation reports, and customs trade data for grain-oriented steel and copper winding imports. Bottom-up unit volume estimates across voltage classes and insulation types were triangulated against top-down utility capital expenditure disclosures.
Forecast inputs incorporated power transformer and distribution transformer segmentation by cooling method, insulation fluid type, and end-user procurement sophistication, modeled across the projection horizon. CAGRs were derived from utility framework agreement volume commitments, rural electrification mandate trajectories, and regulatory substitution timelines for natural ester adoption. Industry-specific inputs included transmission system operator climate hardening budgets and state discom modernization program disbursement schedules.
Practitioners should monitor EU F-Gas Regulation enforcement intensity and Indian PLI scheme disbursement timing for early signals of forecast deviation. Material shifts in copper and grain-oriented steel commodity cycles, or abrupt REACH substance restriction expansion, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Transformer Market
Transformers
Transformer Bobbin Market
Transformers
United States Distribution Transformer Market
Transformers
Green Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
Gas Insulated Transformer Market
Transformers
Transformer Oil Market
Transformers
Transformer Core Market
Transformers
Cast Resin Transformers Market
Transformers
North America Smart Transformers Market
Transformers
Current Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Neon Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Smart Transformer Market