
 Phase-Shifting Transformer Market | 2026-2036
Phase-Shifting Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Phase-Shifting Transformer Market Analytics
Specialized transformer winding engineers is reorganizing competitive dynamics in the phase-shifting transformer sector, as fewer technicians possess expertise in asymmetric tap changer design and quadrature booster construction. Siemens Energy leverages its European manufacturing heritage to sustain leadership in ultra-high-voltage phase-shifting units for cross-border interconnections. Hitachi Energy Ltd. anchors its position through integrated digital monitoring systems that extend asset life cycles for utility operators. Toshiba Energy Systems & Solutions Corporation differentiates via precision control systems that dominate niche applications in congested urban grids.
A phase-shifting transformer is a specialized power transformer equipped with on-load tap changers that inject a regulated voltage phase angle shift to control active power flow between parallel transmission paths, typically rated from 100 MVA to 1,200 MVA with voltage classes up to 765 kV. The device enables grid operators to redirect power away from overloaded lines and balance loading across network corridors without building new transmission infrastructure. Static phase-shifting transformers occupy the largest revenue share due to proven reliability in decades of utility deployment, while dynamic variants represent the fastest-expanding category as real-time power electronics enable sub-cycle response to grid disturbances. Modular multilevel converter technology leads R&D investment intensity, though magnetic phase-shifting transformers retain margin strength in retrofit installations where operators prioritize mechanical simplicity over semiconductor-based control.
The US Federal Energy Regulatory Commission and the North American Electric Reliability Corporation enforce mandatory reliability standards that compel utilities to deploy power flow control devices including phase-shifting transformers for grid stability compliance. China's National Energy Administration and State Grid Corporation implement technical procurement specifications that prioritize domestic manufacturing content for critical transmission equipment. Grid operators must monitor evolving converter interoperability standards and assess whether hybrid voltage-current source architectures warrant migration from conventional electromagnetic designs.
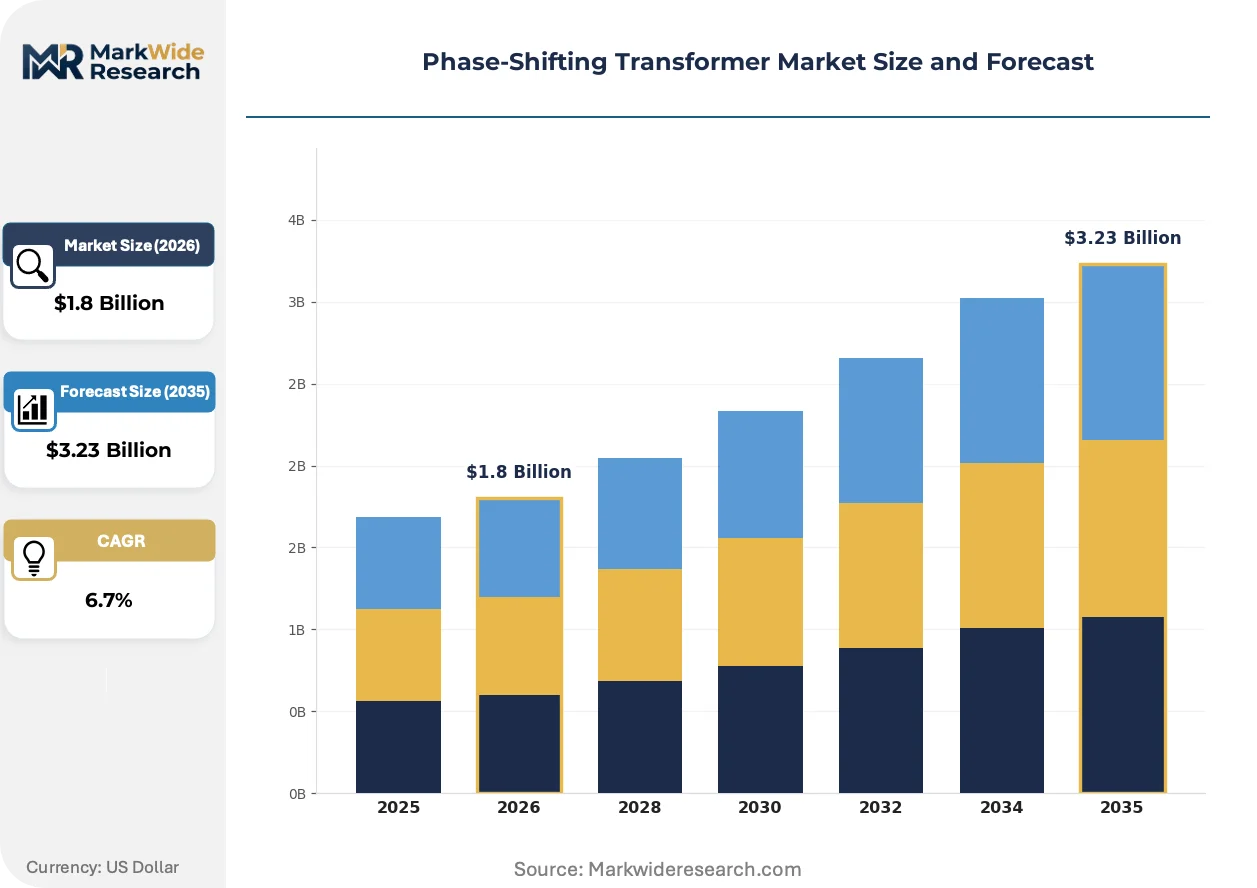
Market Dynamics
Grid operators face mounting pressure from renewable intermittency that forces real-time power flow redirection, driving phase-shifting transformer deployment as an alternative to billion-dollar transmission line construction. State Grid Corporation in China, FERC-mandated US utilities, and European TSOs now treat these assets as essential congestion management tools rather than optional grid enhancements.
Growth Catalysts
- Interconnection mandates:FERC Order 1000 compels US regional transmission organizations to prioritize cost-effective congestion relief, elevating phase-shifting transformers above new line builds in interconnection queues.
- Renewable integration protocols:China's dual carbon goals require State Grid to manage bidirectional power flows from distributed solar and wind, creating procurement pull for dynamic phase-shifting units with sub-cycle response.
- Modular multilevel converters:Semiconductor-based designs enable real-time phase angle adjustment that magnetic transformers cannot match, attracting grid operators in Germany and Japan seeking precision control.
Market Restraints
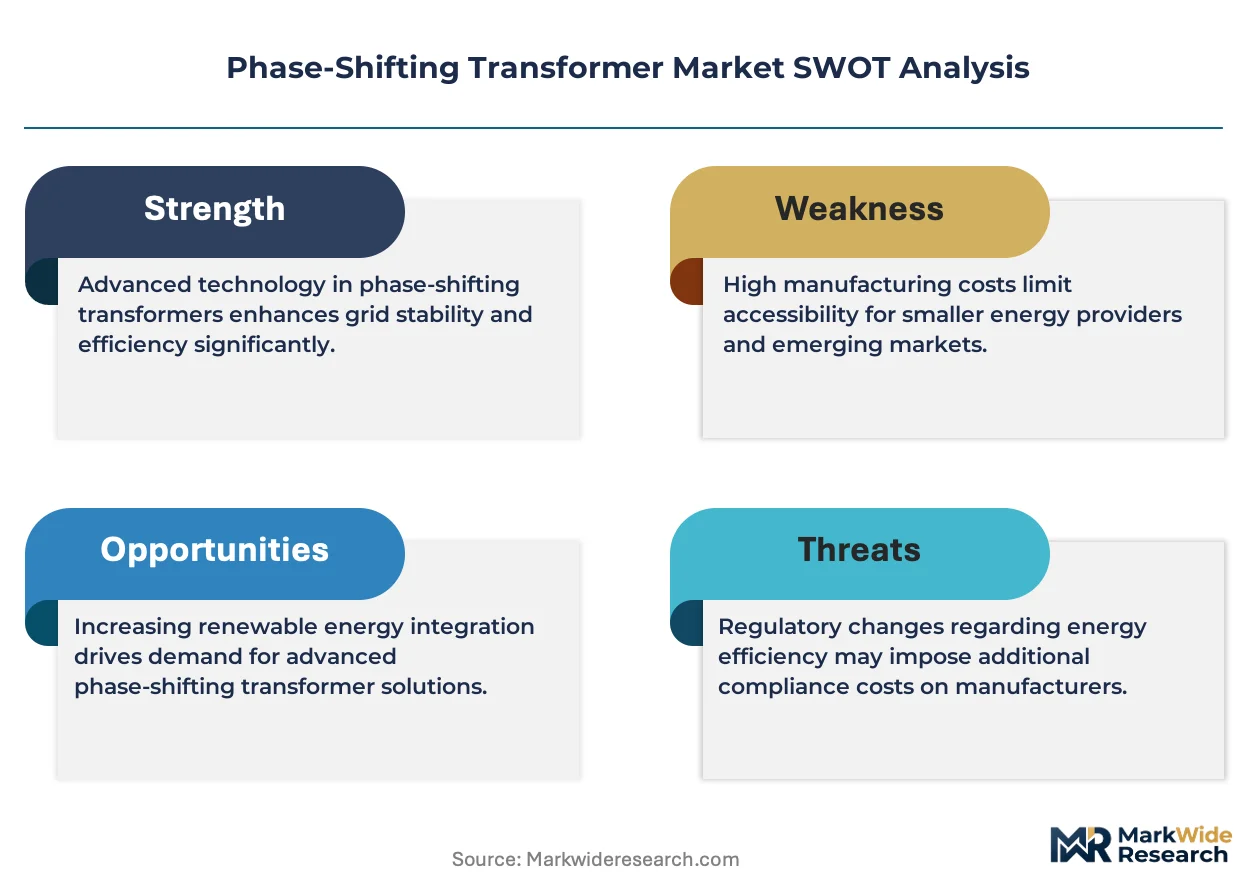
- Copper and grain-oriented electrical steel volatility:Core winding materials face supply concentration from Chinese and Japanese mills, compressing manufacturer margins during price spikes.
- Specialized engineering scarcity:Asymmetric tap changer design expertise concentrates among retiring European technicians, constraining production scaling for ultra-high-voltage units.
- Static VAR compensators:Power electronics-based alternatives threaten phase-shifting transformer relevance in urban substations where footprint and speed outweigh mechanical reliability preferences.
Strategic Opportunities
- India's transmission expansion:Central Electricity Authority targets 765 kV network buildout that lacks indigenous phase-shifting transformer manufacturing, opening import substitution partnerships.
- Hybrid voltage-current architectures:Convergence of magnetic cores with modular converter controls creates next-generation units bridging reliability and responsiveness gaps.
- EU Green Deal grid modernization:Trans-European energy infrastructure funding prioritizes cross-border flow control assets, directing capital toward phase-shifting installations at German-Polish and French-Spanish interties.
Industry Challenges
- Quadrature booster construction expertise:Fewer than two dozen engineers globally possess demonstrated capability in 400 kV+ quadrature winding design, creating project execution bottlenecks.
- IEC 60076-20 compliance timelines:Extended type-testing protocols for dynamic phase-shifting transformers delay commercialization by 18-24 months versus static variants.
- SCADA integration complexity:Legacy EMS platforms at US municipal utilities require costly middleware development to interface with digital tap changer controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phase-Shifting Transformer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Phase-Shifting Transformers, Magnetic Phase-Shifting Transformers, Static Phase-Shifting Transformers, Dynamic Phase-Shifting Transformers Technology: Voltage Source Converter, Current Source Converter, Hybrid Converter, Modular Multilevel Converter End User: Utilities, Industrial Sector, Commercial Sector, Renewable Energy Providers Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Toshiba Energy Systems & Solutions Corporation, China XD Group, Hitachi Energy Ltd., CHINT Electric Co., Ltd., Taikai Group, Siemens Energy, TBEA Co., Ltd., Huapeng Transformer Co., Ltd., GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phase-Shifting Transformer Market Evolving Landscape
Power electronics integration is fragmenting the phase-shifting transformer category into distinct performance tiers, with magnetic-only designs defending retrofit markets while hybrid architectures capture greenfield high-performance applications.
Modular multilevel converter technology is bifurcating the competitive landscape between electromagnetic purists and semiconductor-integrated suppliers. European TSOs including TenneT and Elia favor hybrid designs for North Sea offshore wind integration. This technology is bifurcating procurement patterns, with utilities segmenting projects into reliability-critical retrofits versus flexibility-driven new builds.
EU F-Gas Regulation phase-down mandates are accelerating transformer insulation fluid transitions from SF6 toward natural ester and synthetic alternatives. Manufacturers face reformulation investments to maintain dielectric performance in phase-shifting tap changer compartments. German utilities including 50Hertz now specify fluoronitrile-based insulation for 420 kV quadrature boosters, pressuring suppliers to requalify designs.
Asset performance contracting is displacing conventional equipment-only sales among US investor-owned utilities. Duke Energy and Southern Company now procure 15-year availability guarantees bundled with hardware, transferring operational risk to OEM service organizations. This model concentrates in the PJM interconnection region where FERC-mandated reliability incentives reward uptime over capital efficiency.
Phase-Shifting Transformer Market Segmentation
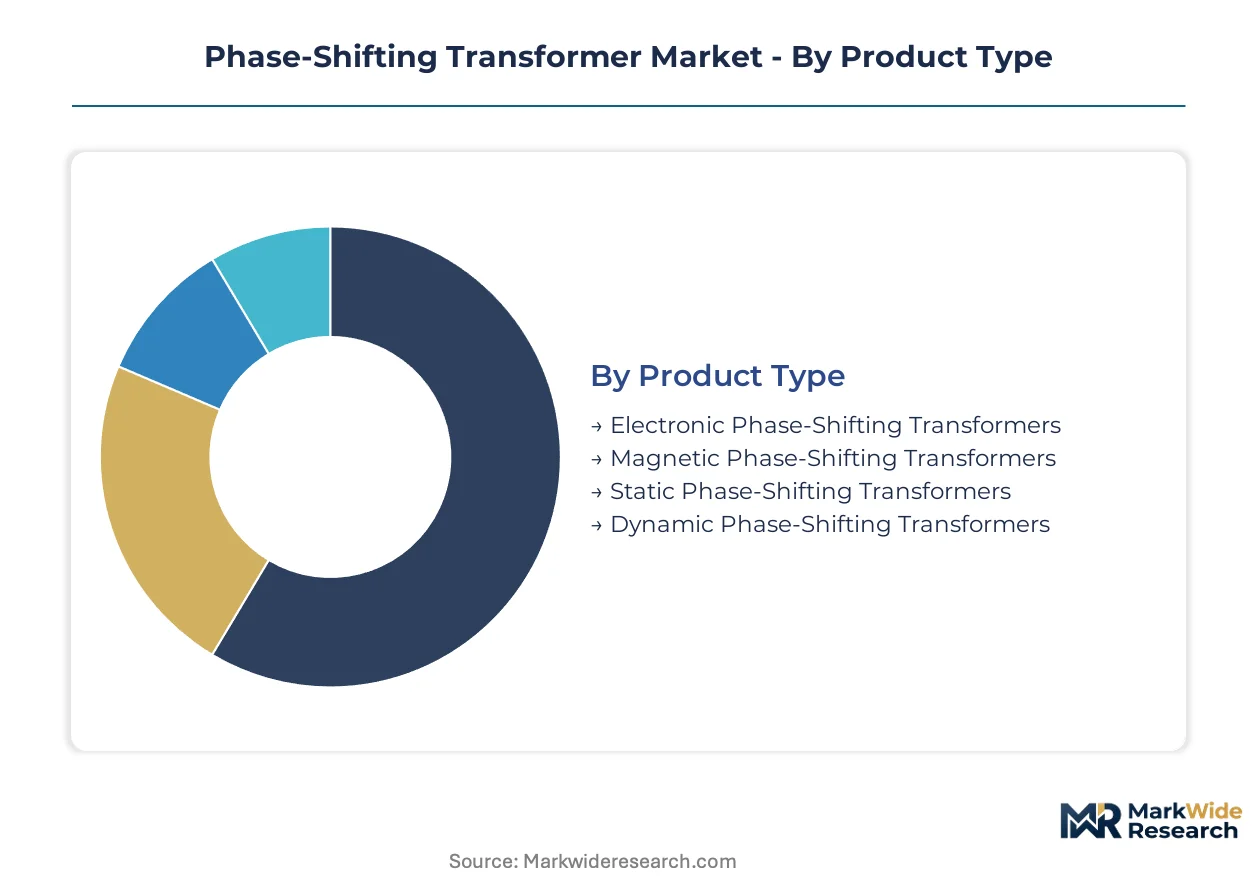
Segmentation in the phase-shifting transformer market reveals distinct vulnerability profiles against substitute technologies. Each dimension exposes where power electronics threaten traditional electromagnetic designs and where incumbent architectures retain defensive moats.
Product Type:
Electronic and magnetic variants face divergent substitution pressures from static VAR compensators and modular converter stations, reshaping procurement priorities across grid operators.
- Electronic Phase-Shifting Transformers:Semiconductor-based phase angle control enables sub-cycle response times unattainable by magnetic cores. German TSOs including TenneT specify these units for North Sea offshore wind integration where rapid power flow reversal is mandatory.
- Magnetic Phase-Shifting Transformers:Conventional electromagnetic designs rely on mechanical tap changers and quadrature windings. State Grid Corporation in China procures these for 765 kV inter-regional corridors where decades of operational data support reliability-centered maintenance regimes.
- Static Phase-Shifting Transformers:Fixed-phase configurations dominate installed base across US RTOs under FERC reliability mandates.
- Dynamic Phase-Shifting Transformers:Real-time adjustable units attract Japanese utilities managing earthquake-induced grid reconfiguration.
Static variants retain volume leadership; dynamic configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium converter architectures from commodity electromagnetic solutions, concentrating R&D investment in semiconductor-integrated designs.
- Voltage Source Converter:Self-commutated topology enables black-start capability and reactive power support independent of grid voltage. European TSOs at French-Spanish interties favor this technology for asynchronous interconnection of power systems with different frequencies.
- Current Source Converter:Line-commutated designs using thyristors persist in legacy installations across India's state transmission utilities where capital constraints outweigh efficiency penalties.
- Hybrid Converter:Combined voltage-current architectures bridge reliability and responsiveness gaps for utilities in Poland upgrading Soviet-era infrastructure.
- Modular Multilevel Converter:Stacked submodule topology reduces harmonic distortion and enables scalability to 1,200 MVA ratings. Siemens Energy and Hitachi Energy dominate this segment through proprietary control algorithms.
Voltage source converters command premium pricing tiers; modular multilevel designs are climbing the fastest.
End User:
Application-driven demand concentration centers on transmission utilities with mandatory reliability obligations, while industrial and commercial segments remain price-sensitive and sporadic.
- Utilities:Grid operators under FERC Order 1000 and NERC reliability standards deploy phase-shifting transformers as congestion management infrastructure. PJM interconnection members treat these assets as essential for inter-regional power transfer optimization.
- Industrial Sector:Steel mills and aluminum smelters in Germany use quadrature boosters for load balancing across multiple utility feeds. ThyssenKrupp and ArcelorMittal specify 420 kV units for Ruhr Valley manufacturing complexes.
- Commercial Sector:Data center operators in Northern Virginia procure smaller 100-200 MVA units for substation-level power quality management.
- Renewable Energy Providers:Offshore wind developers in the North Sea require dynamic phase-shifting capability for variable output stabilization.
Utilities anchor procurement volume; renewable energy providers are expanding most quickly.
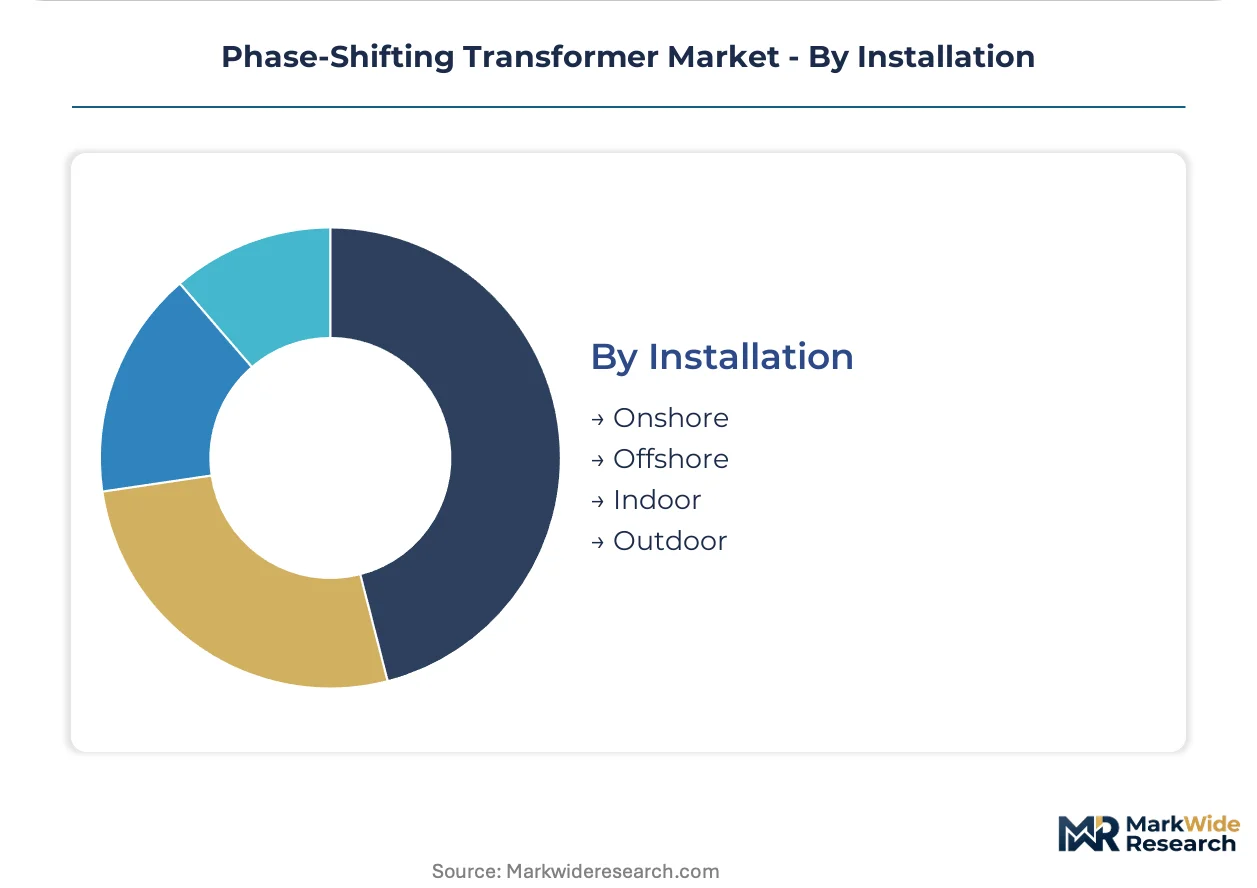
Installation:
Geography and physical environment dictate cooling system design, fire protection requirements, and maintenance access protocols, fragmenting supplier specialization.
- Onshore:Conventional outdoor installations at 345 kV and 765 kV substations constitute the majority of deployed base. State Grid Corporation's Gansu-Qinghai intertie project exemplifies desert-environment specifications with sand-filtered cooling systems.
- Offshore:Platform-mounted units for North Sea wind farms require salt-corrosion resistance and compact footprints. 50Hertz and TenneT specify fluoronitrile insulation for subsea cable landing points.
- Indoor:Urban substations in Tokyo and Seoul favor enclosed designs with synthetic ester fluids meeting EU F-Gas Regulation phase-down requirements.
- Outdoor:Exposed installations in Nordic countries incorporate ice-resistant tap changer mechanisms for winter operation.
Onshore configurations retain volume leadership; offshore installations hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State Grid Corporation procurement specifications under China's National Energy Administration anchor regional demand concentration for phase-shifting transformers. Grid modernization mandates across multiple jurisdictions are redistributing manufacturing investment toward high-voltage corridor markets.
China
State Grid Corporation deploys 765 kV quadrature boosters across Gansu-Qinghai and Xinjiang interties for renewable absorption. The National Energy Administration mandates domestic content thresholds for critical transmission equipment procurement. Manufacturing clusters in Shenyang and Xi'an concentrate winding expertise for ultra-high-voltage asymmetric tap changer construction.
United States
FERC Order 1000 compels RTOs including PJM and MISO to prioritize cost-effective congestion relief over new transmission builds. NERC reliability standards enforce mandatory power flow control device deployment for grid stability compliance. Texas ERCOT operators and California ISO procurement teams specify dynamic phase-shifting capability for wildfire-induced line reconfiguration scenarios.
Germany
TenneT and 50Hertz specify hybrid converter designs for North Sea offshore wind landing points at BorWin and SylWin clusters. EU F-Gas Regulation phase-down mandates fluoronitrile insulation requalification for 420 kV quadrature boosters. Industrial demand from ThyssenKrupp and ArcelorMittal Ruhr Valley complexes sustains niche procurement for load balancing across multiple utility feeds.
India
Central Electricity Authority targets 765 kV network buildout through Green Energy Corridors linking Rajasthan solar zones to load centers. CEA technical standards lack indigenous phase-shifting transformer manufacturing capacity, creating import dependency. Maharashtra State Electricity Transmission Company and Gujarat Energy Transmission Corporation tender specifications favor European and Japanese OEM partnerships for technology transfer.
Japan
Tokyo Electric Power and Chubu Electric deploy dynamic phase-shifting units for earthquake-induced grid reconfiguration protocols. METI grid resilience directives prioritize sub-cycle response capability for islanding events. Osaka and Nagoya industrial zones concentrate demand from steel and chemical processors requiring precision power flow management across dual utility connections.
Phase-Shifting Transformer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European and Japanese firms commanding premium positioning in converter-integrated designs while Chinese manufacturers scale magnetic-core production. The vendor base stratifies across three tiers: integrated energy conglomerates with full transmission portfolios, specialized transformer OEMs with winding expertise concentration, and state-backed national champions serving protected procurement markets. Siemens Energy and Hitachi Energy exemplify the technology-integrated archetype, while China XD Group and TBEA represent scale-driven manufacturing concentration. Competitive moves center on hybrid architecture R&D partnerships and 15-year asset performance contracting to transfer operational risk from utilities to OEM service organizations.
Among Japanese and European integrated energy suppliers, Toshiba Energy Systems & Solutions Corporation and Siemens Energy occupy positions emphasizing precision control systems and ultra-high-voltage manufacturing heritage respectively. Chinese state-affiliated fabricators including China XD Group and Taikai Group exemplify the scale-driven archetype serving domestic grid buildout mandates. Hitachi Energy Ltd. anchors the digital-integrated tier through bundled monitoring and lifecycle service offerings.
| Leading Market Players |
|---|
| Toshiba Energy Systems & Solutions Corporation |
| China XD Group |
| Hitachi Energy Ltd. |
| CHINT Electric Co., Ltd. |
| Taikai Group |
| Siemens Energy |
| TBEA Co., Ltd. |
| Huapeng Transformer Co., Ltd. |
| GE Vernova |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Shenyang and Xi'an manufacturing clusters anchors cost structures across the phase-shifting transformer sector, concentrating supply-side pricing power among Chinese state-affiliated fabricators while European and Japanese OEMs defend premium positioning through converter-integrated designs. This scale asymmetry forces procurement teams to navigate a bifurcated market where magnetic-core units face commoditization pressure and hybrid architectures command sustained margin premiums.
Pricing Analysis
Geographic price spreads between Chinese domestic tenders and European export contracts exceed three-to-one ratios for equivalent 400 kV magnetic ratings. Three-tier pricing structure across premium converter-integrated, standard electromagnetic, and economy-grade static configurations segments buyer archetypes, with utilities under FERC reliability mandates least sensitive and Indian state transmission utilities most price-constrained. Cost compression in economy magnetic tiers is intensifying because indigenous manufacturing capacity in India remains undeveloped, forcing import dependency on Chinese and European suppliers.
Supply Chain Analysis
Inventory lead times for grain-oriented electrical steel extend eighteen to twenty-four months from Nippon Steel and Baowu Group mills, constraining production scheduling for ultra-high-voltage winding construction. Supply concentrates in China, Japan, and Germany for core electromagnetic components, while semiconductor modules for converter-integrated designs source from South Korean and Taiwanese foundries. Single-source vulnerability around asymmetric tap changer mechanisms from ABB and Siemens Energy legacy inventories threatens project execution timelines. Distribution runs through utility-direct procurement channels with EPC contractor intermediation for complex offshore installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset performance contracting layers now expand faster than hardware-only sales, with fifteen-year availability guarantees transferring operational risk from PJM interconnection utilities to OEM service organizations and creating recurring revenue streams that outpace equipment margin trajectories.
For Market Incumbents: Fortify quadrature booster engineering capabilities through apprenticeship programs targeting retiring European technicians, while securing captive supply of grain-oriented electrical steel via offtake agreements with Baowu Group. Static VAR compensators threaten phase-shifting transformer relevance in urban substations where footprint constraints dominate procurement criteria. For New Entrants and Emerging Players: Differentiate on modular multilevel converter control algorithms for North Sea offshore wind integration, where TenneT and 50Hertz specifications favor semiconductor-integrated responsiveness over mechanical reliability. India's 765 kV Green Energy Corridor buildout presents the most penetrable geography given absent indigenous manufacturing capacity and CEA-mandated technology transfer partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid architecture specialists bridging magnetic-core reliability with converter responsiveness, as grid operators migrate from static retrofits toward dynamic greenfield deployments. Acquisition targets should demonstrate demonstrated 400 kV+ quadrature winding design capability with fewer than two dozen engineers globally possessing this expertise. Watch FERC Order 1000 implementation velocity across MISO and SPP regions as inflection indicator for congestion-relief procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Baowu Group offtake agreements secure grain-oriented electrical steel allocation against price volatility. |
| Hybrid Converter R&D Partnership | Siemens Energy and Hitachi Energy collaborations bridge voltage-current source architectures for Polish grid modernization. |
| Asset Performance Contracting Expansion | Duke Energy and Southern Company fifteen-year availability guarantees transfer operational risk to OEM service organizations. |
| Quadrature Booster Engineering Apprenticeship | European technician retirement waves threaten 400 kV+ construction capability concentration. |
| India Technology Transfer Partnership | Maharashtra State Electricity Transmission Company tenders favor European and Japanese OEM joint ventures for domestic manufacturing. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, transformer procurement managers at State Grid Corporation and PJM interconnection members, EPC contractors specializing in offshore wind grid connection, and aftermarket service directors at major OEMs, and refined through secondary validation against FERC Order 1000 implementation filings, IEC 60076-20 type-testing protocols, CEA Green Energy Corridor tender specifications, and IEA grid modernization investment trackers. Bottom-up unit economics from individual project databases were triangulated against top-down transmission infrastructure spending forecasts.
Variance decomposition across product type, converter technology, end-user segment, voltage class tier, and geographic regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles and greenfield interconnection queue data, with renewable integration mandates and FERC reliability standards serving as demand-side forecast inputs alongside copper and electrical steel price indices on the supply side.
Decision-makers should treat outputs as directional under assumptions of sustained grid modernization investment and stable raw material supply; material deviation in Chinese domestic content enforcement or F-Gas Regulation phase-down timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Transformer Steel Market
Transformers
Power Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
Box Transformer Substation Market
Transformers
North America Dry Type Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Gas Insulated Transformer Market
Transformers
Green Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
United States Power Transformer Market
Transformers
North America Transformer Market
Transformers
India Transformer Market
Transformers
Liquid-Immersed Transformers Market