
 Wind Turbine Scrap Market | 2026-2036
Wind Turbine Scrap Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Scrap Market Analytics
Cement production is pivoting toward wind turbine blade-derived raw feed. Veolia Environnement S.A. leverages integrated waste-to-resource infrastructure across European decommissioning clusters. Carbon Rivers anchors advanced pyrolysis capacity for fiberglass recovery from thermoset composites. Siemens Gamesa Renewable Energy SA competes through blade design-for-recycling protocols that ease downstream material liberation.
Wind turbine scrap encompasses decommissioned blades, towers, nacelles, and gearboxes containing fiberglass-reinforced polymers, structural steel, rare earth magnets, and aluminum alloys. Blade segments typically span 40-80 meters in length with thermoset epoxy or polyester matrices that resist conventional mechanical shredding, necessitating specialized pyrolysis or solvolysis for fiber reclamation. Mechanical recycling of steel towers and aluminum housings dominates current volume owing to established metallurgical infrastructure and strong scrap pricing. Chemical recycling of fiberglass blades captures emerging margin pools as pyrolysis yields recoverable glass fiber and syngas fractions.
The EPA oversees hazardous waste classification for resin-containing blade fragments in the United States. The EU Waste Framework Directive and REACH constrain landfill disposal of thermoset composites while mandating extended producer responsibility. China's MEE enforces solid waste import bans that redirect domestic blade scrap toward local recycling capacity buildout. Stakeholders must monitor regulatory divergence between jurisdictions that either accelerate or obstruct cross-border movement of composite waste streams.
Market Dynamics
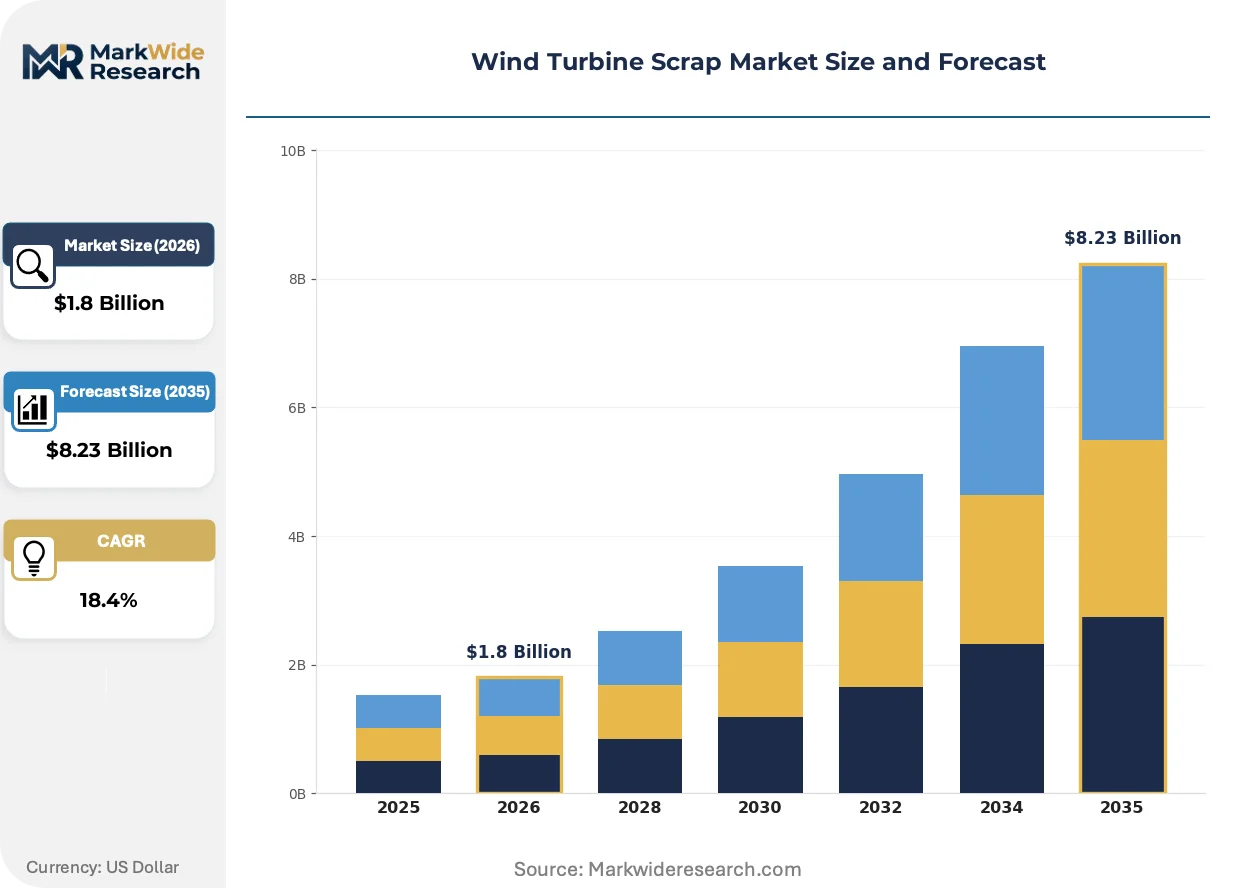
The Wind Turbine Scrap Market is being fundamentally restructured by the collision of early turbine decommissioning waves with immature composite recycling infrastructure. Blade mass volumes now exceed available pyrolysis kiln capacity across European clusters.
Growth Catalysts
- EU Waste Framework Directive:Extended producer responsibility mandates force original equipment manufacturers to internalize end-of-life costs. This creates guaranteed feedstock pipelines for specialized recyclers.
- Cement kiln co-processing:Cement manufacturers in Germany and Spain absorb crushed blade fragments as alternative raw feed. Thermoset composite ash content substitutes for traditional clinker minerals.
- Rare earth magnet recovery:Direct-drive turbine dismantling yields neodymium-iron-boron magnets. Urban mining economics now compete with virgin rare earth extraction from Chinese deposits.
Market Restraints
- Pyrolysis energy intensity:Thermal decomposition of thermoset epoxy matrices requires sustained temperatures exceeding 500°C. Natural gas price volatility directly compresses recycler operating margins.
- Logistics cost concentration:Blade segments measuring 60+ meters face transport restrictions on European road networks. Specialized flatbed capacity concentrates with regional haulers in northern Germany.
- Landfill diversion friction:REACH compliance documentation for composite waste streams creates administrative burdens. Small decommissioning contractors lack regulatory affairs capabilities.
Strategic Opportunities
- Spain's lagging installed base:Iberian wind farms installed during the 2005-2010 boom approach end-of-life. Domestic blade recycling capacity remains underdeveloped relative to incoming scrap volumes.
- Solvolysis technology convergence:Supercritical fluid processing combined with catalyst innovation enables fiber reclamation at lower temperatures than conventional pyrolysis.
- Carbon fiber blade segments:Next-generation offshore turbines incorporate carbon fiber reinforcements. Recovered carbon fiber commands premium pricing in automotive and aerospace secondary markets.
Industry Challenges
- Composite chemist talent scarcity:Thermoset matrix characterization requires specialized polymer science expertise. Academic programs produce insufficient graduates familiar with epoxy degradation pathways.
- Pyrolysis kiln certification timelines:EPA hazardous waste combustion permits for blade processing facilities extend 18-24 months. Capital deployed remains non-revenue-generating during regulatory review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Scrap Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Blades, Towers, Nacelles, Gearboxes Material: Fiberglass, Steel, Rare Earth Metals, Aluminum Recycling Method: Mechanical Recycling, Chemical Recycling, Repurposing, Disposal End User: Manufacturers, Scrap Yards, Renewable Energy Companies, Environmental Agencies |
| Companies Covered | Vestas Wind Systems A/S, Carbon Rivers, Veolia Environnement S.A., Stena Recycling AB, HJHansen Recycling Group, LM Wind Power, Arkema S.A., Eurecum, Siemens Gamesa Renewable Energy SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Scrap Market Evolving Landscape
Active innovation across the Wind Turbine Scrap Market centers on liberating valuable fiber fractions from thermoset prisons. Three distinct vectors are compressing processing economics and reshaping competitive positioning.
Pyrolysis reactor design is unifying thermal decomposition with syngas capture systems. Industrial gas suppliers in the Netherlands deploy integrated kiln-infrastructure packages that simultaneously yield clean glass fiber and energy-neutral process heat. Cement producers purchasing these systems achieve captive disposal capacity while offsetting fossil fuel consumption.
REACH Annex XVII restrictions on microplastic release are tightening disposal pathways for mechanically shredded blade fragments. German environmental regulators now classify fine thermoset dust as persistent organic pollutant precursors. Decommissioning contractors respond by shifting volume toward chemical recycling partnerships rather than traditional size-reduction services.
Blade resale markets for intact second-life applications are fragmenting established scrap flows. Polish and Romanian wind farm operators purchase refurbished 40-meter segments from decommissioned German onshore sites. This arbitrage displaces material from recycling queues while extending composite landfill timelines by 10-15 years.
Wind Turbine Scrap Market Segmentation
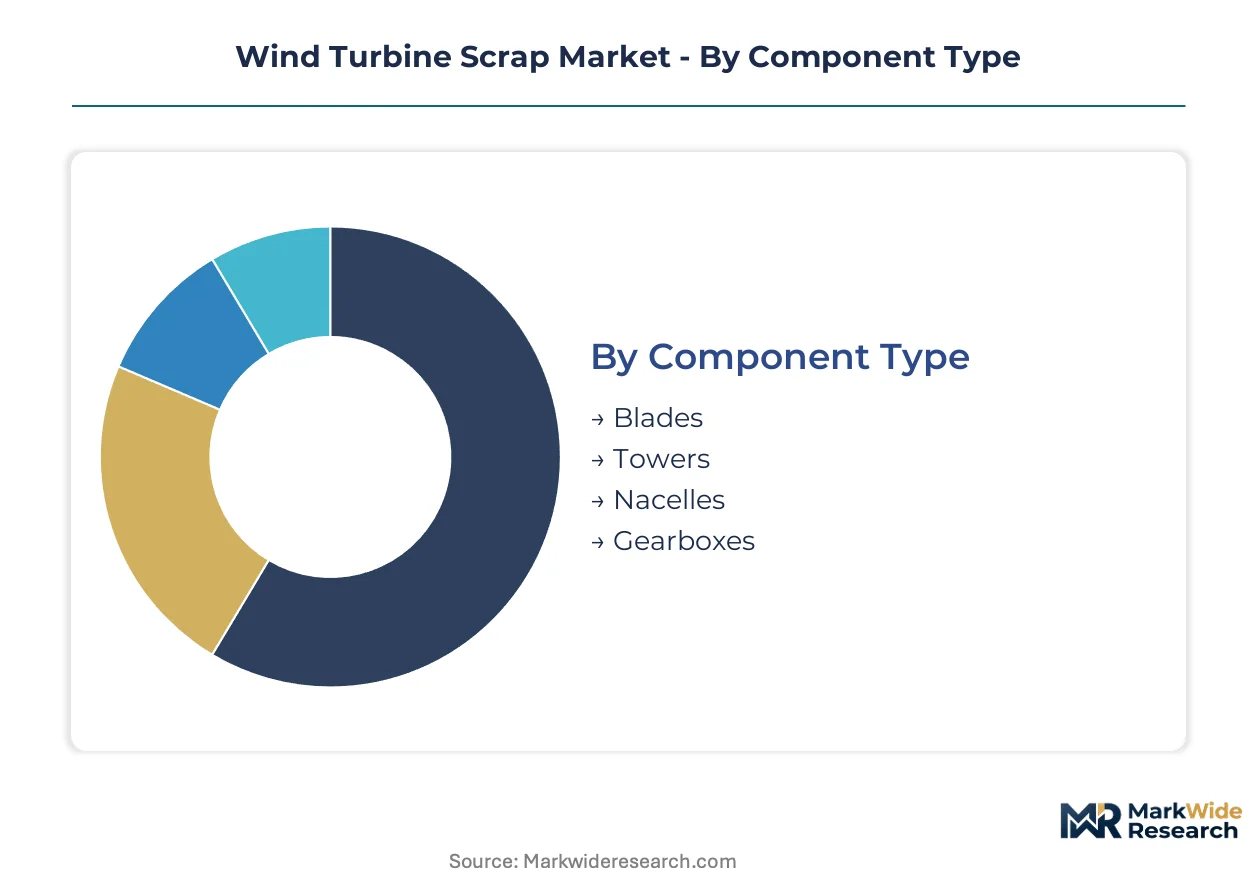
Wind turbine scrap segmentation reveals divergent value capture across material liberation pathways. Component geometry and matrix chemistry dictate whether fragments flow toward metallurgical recovery, cement kiln substitution, or hazardous waste streams.
Component Type:
Blades command disproportionate processing complexity relative to their mass share, while steel towers anchor current recycler revenue through established commodity markets.
- Blades:Thermoset epoxy and polyester matrices encasing glass or carbon fiber reinforcements resist conventional shredding. Pyrolysis facilities in northern Germany and the Netherlands concentrate processing capacity for these 40-80 meter segments, though kiln throughput lags incoming decommissioning volumes from early Danish and German wind farms.
- Towers:Structural steel sections yield immediate scrap value through existing metallurgical infrastructure. Spanish and German steel recyclers absorb these flows directly, bypassing the certification delays that constrain composite processing.
- Nacelles:Aluminum housings and copper windings from generator assemblies extract cleanly through mechanical dismantling. Rare earth magnet contents in direct-drive units create urban mining opportunities.
- Gearboxes:High-grade steel alloys and lubricant residues require specialized handling. Gear oil contamination triggers hazardous waste protocols in EPA jurisdictions.
Today's leader: Towers. Tomorrow's challenger: Blades.
Material:
Scrap value stratifies sharply between established commodity metals and thermoset composites requiring chemical liberation.
- Fiberglass:Glass fiber reclamation from thermoset matrices demands pyrolysis or solvolysis. Recovered fiber quality varies by kiln temperature control, with German and Dutch operators achieving specification grades suitable for automotive panel reinforcement.
- Steel:Tower sections and gearbox housings flow directly into electric arc furnace feedstock. German scrap pricing volatility compresses decommissioning contractor margins during natural gas price spikes.
- Rare Earth Metals:Neodymium-iron-boron magnets from direct-drive generators attract specialized urban mining operators. Separation and re-magnetization capabilities concentrate in Germany and Japan.
- Aluminum:Nacelle housings and electrical components yield clean secondary ingot. Spanish aluminum smelters increasingly specify turbine-derived scrap for carbon footprint reduction claims.
Steel dominates tonnage. Fiberglass claims the steepest expansion trajectory as pyrolysis capacity scales.
Recycling Method:
Method selection hinges on material-matrix bonds, with mechanical routes dominating metals and chemical routes capturing composite premiums.
- Mechanical Recycling:Size reduction and sorting of metallic components proceeds without thermal intervention. German scrap yards process tower sections through conventional shearing and baling equipment.
- Chemical Recycling:Pyrolysis and solvolysis liberate fibers from epoxy prisons. Supercritical fluid processing in pilot Dutch facilities achieves lower energy intensity than conventional thermal decomposition.
- Repurposing:Intact blade segments find second-life applications in Polish and Romanian wind farm refurbishment. This arbitrage delays material entry into recycling queues by 10-15 years.
- Disposal:Landfill diversion faces REACH Annex XVII constraints on microplastic release. German regulators now classify fine thermoset dust as persistent organic pollutant precursors.
Mechanical recycling holds volume. Chemical recycling is climbing fastest as fiber reclamation economics improve.
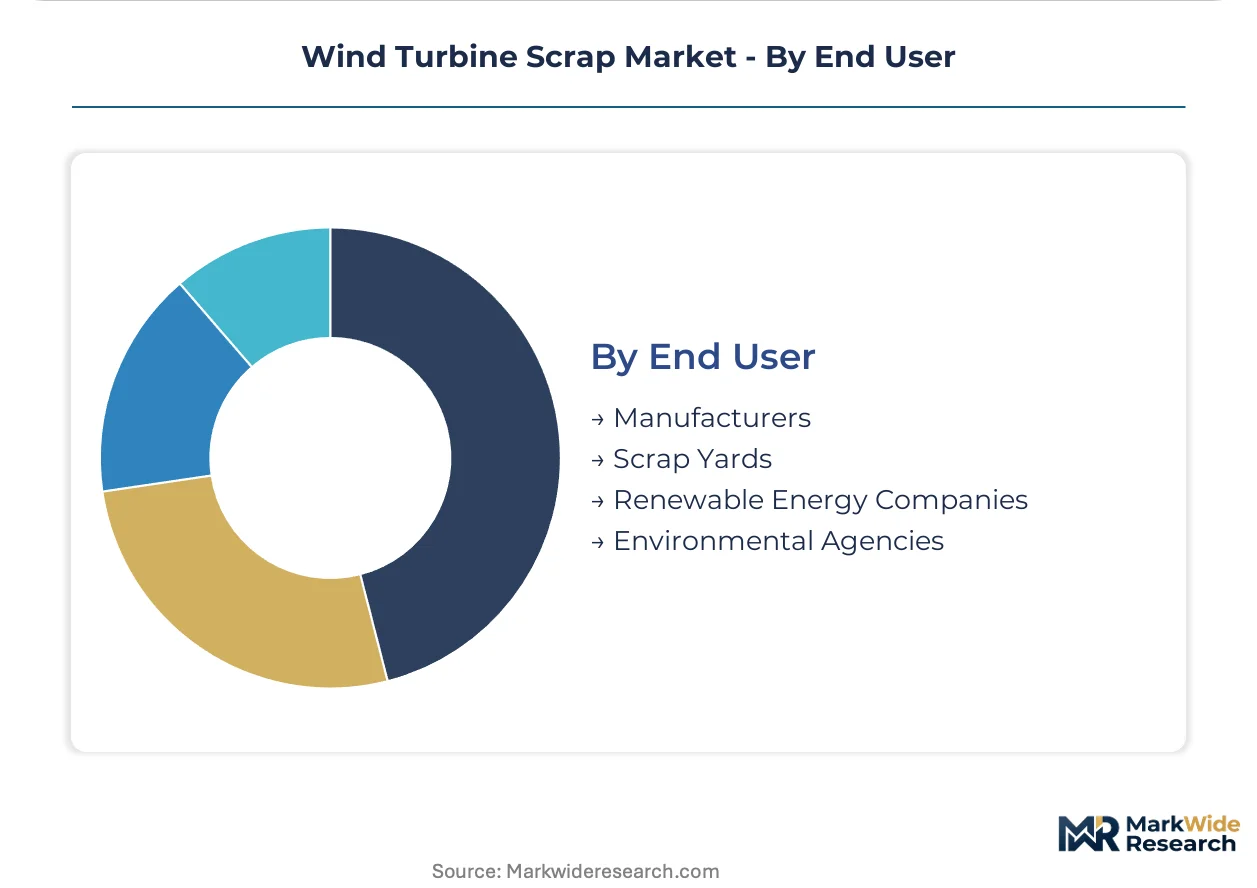
End User:
End-user procurement patterns fragment across captive cement kiln absorption, merchant scrap trading, and regulatory compliance mandates.
- Manufacturers:Cement producers in Germany and Spain absorb crushed blade fragments as clinker substitutes. Thermoset composite ash content substitutes for traditional raw feed minerals.
- Scrap Yards:Merchant processors handle steel tower flows through established commodity channels. Composite blade acceptance remains limited by pyrolysis kiln availability.
- Renewable Energy Companies:OEMs face EU Waste Framework Directive extended producer responsibility mandates. Siemens Gamesa and Vestas internalize end-of-life costs through recycling partnerships.
- Environmental Agencies:EPA and German state regulators oversee hazardous waste classification for resin-containing fragments. Permit timelines extend 18-24 months for pyrolysis facilities.
Manufacturers drive volume absorption. Environmental agencies shape permissible pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where blade decommissioning capacity concentrates, as compliance cost differentials between jurisdictions redirect investment flows toward markets with streamlined permitting and integrated waste-to-resource infrastructure.
Germany
Early Danish and German wind farms installed during the 1990s-2000s now reach end-of-life, generating concentrated blade scrap volumes in northern Länder. The EU Waste Framework Directive and REACH Annex XVII constrain landfill diversion, forcing OEMs to internalize recycling costs. Pyrolysis kiln clusters in Lower Saxony and Schleswig-Holstein process thermoset composites, though throughput lags incoming decommissioning volumes.
Spain
Iberian wind capacity installed during the 2005-2010 boom approaches decommissioning age, yet domestic blade recycling infrastructure remains underdeveloped relative to incoming scrap flows. Spanish cement producers in Catalonia and Andalusia absorb crushed blade fragments as clinker substitutes under EU circular economy mandates. Barcelona-based environmental engineering firms are retrofitting cement kilns for composite co-processing.
United States
Texas and Iowa host the largest cumulative wind installations reaching retirement age, with blade segments piling at decommissioning sites pending EPA hazardous waste classification rulings. The EPA oversees resin-containing fragment permitting, with state-level variations in composite waste handling creating compliance fragmentation. Specialized haulers in the Great Plains face transport restrictions moving 60+ meter segments on interstate highways.
Netherlands
Rotterdam-Europoort industrial complex anchors integrated pyrolysis-syngas capture systems deployed by industrial gas suppliers. REACH compliance documentation requirements concentrate regulatory expertise in Dutch environmental consultancies serving cross-border decommissioning contractors. Eindhoven-based materials science programs supply composite chemist talent scarce across broader European recycling operations.
China
Domestic blade scrap volumes surge as early wind farms in Inner Mongolia and Gansu provinces reach design life, redirected toward local recycling capacity buildout under MEE solid waste import bans. Yangtze River Delta metallurgical processors adapt steel tower shredding lines for nacelle aluminum recovery. Shandong cement producers trial blade fragment co-processing under evolving national circular economy standards.
Wind Turbine Scrap Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated waste management conglomerates controlling volume flows while technology-focused ventures capture margin premiums in fiber reclamation. Market structure concentrates around three strategic archetypes: environmental services giants with captive logistics networks, advanced materials ventures commercializing pyrolysis innovations, and OEM-affiliated recyclers securing feedstock pipelines through extended producer responsibility mandates. Dominant competitive moves include pyrolysis kiln capacity expansion in European decommissioning clusters and strategic partnerships between cement producers and blade fragment processors.
Among European environmental services conglomerates, Veolia Environnement S.A. and Stena Recycling AB exemplify the integrated infrastructure archetype, leveraging established waste-to-resource networks across northern European wind farm clusters. Within the advanced materials tier, Carbon Rivers occupies a position representing pyrolysis technology commercialization for fiberglass recovery from thermoset composites. These three entities anchor competitive positioning across distinct value capture vectors—logistics scale, technological differentiation, and regulatory compliance integration.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Carbon Rivers |
| Veolia Environnement S.A. |
| Stena Recycling AB |
| HJHansen Recycling Group |
| LM Wind Power |
| Arkema S.A. |
| Eurecum |
| Siemens Gamesa Renewable Energy SA |
| Others |
Value Network & Pricing Analysis
Captive pyrolysis integration by cement producers anchors supply positioning while compressing merchant recycler margins. German kiln operators leverage EU Waste Framework Directive compliance premiums to defend fiber reclamation pricing against natural gas cost volatility.
Pricing Analysis
Distributor margins on crushed blade fragments for cement kiln feed run 15-25% above pyrolysis-derived fiber premiums. Three-tier pricing structure across premium-specification recovered fiber, standard-grade clinker substitute, and economy-tier landfill diversion captures divergent buyer willingness-to-pay. Cost compression in standard-grade material is intensifying because Spanish cement producers are retrofitting kilns for captive processing. Decommissioning contractors exhibit highest price sensitivity due to thin project margins, while OEMs under extended producer responsibility mandates absorb premium-tier pricing without volume reduction.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale blade decommissioning contracts from Siemens Gamesa and Vestas, bypassing merchant scrap yard intermediaries. Supply concentrates in Germany, the Netherlands, and Spain, with German Lower Saxony clusters drawing from Danish and domestic wind farm retirements. Raw material flows rest on thermoset composite feedstock, natural gas for kiln operations, and specialized flatbed transport capacity. Single-source vulnerability concentrates in pyrolysis kiln engineering expertise, where Dutch and German equipment suppliers command 18-24 month order backlogs. Distribution runs through environmental services conglomerates with captive logistics networks across northern European wind clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wind Turbine Scrap Market compounds steadily as decommissioning waves from 1990s-2000s installations create guaranteed feedstock pipelines regardless of macroeconomic cycles.
For Market Incumbents: To counter solvolysis technology disruption from Dutch pilot facilities, Veolia and Stena Recycling should anchor pyrolysis capacity additions in Spain's underdeveloped Iberian corridor while pursuing REACH compliance certification lock-in with German OEMs. Backward integration into specialized flatbed transport fleets mitigates logistics chokepoint exposure on 60+ meter blade segments. For New Entrants and Emerging Players: Digital auction platforms for intact blade resale arbitrage offer immediate revenue without capital-intensive kiln investment. Poland and Romanian wind farm refurbishment markets remain the most penetrable geography, with 10-15 year second-life extensions displacing material from saturated German recycling queues. A go-to-market angle targeting decommissioning contractors lacking regulatory affairs capabilities with compliance-as-a-service bundling captures administrative burden relief budgets. For Investors and Strategic Acquirers: Roll-up economics work for regional pyrolysis specialists because EU extended producer responsibility mandates guarantee offtake visibility and permit scarcity creates local moats. Target mid-cap recyclers with EPA or German state environmental permits already in hand rather than greenfield development exposure. The signal to watch is cement producer captive kiln announcements, which would displace merchant processor volumes and compress acquisition multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Kiln Capacity Expansion | Spanish cement producers retrofitting kilns for blade co-processing under EU circular economy mandates capture captive disposal economics. |
| Backward Integration into Transport | German haulers acquiring specialized flatbed fleets for 60+ meter segments bypass road network restrictions and capture logistics premiums. |
| REACH Compliance Certification Investment | Dutch environmental consultancies concentrating regulatory expertise serve cross-border decommissioning contractors facing Annex XVII constraints. |
| Solvolysis Technology Licensing | Supercritical fluid processing pilots in the Netherlands achieve lower energy intensity than thermal decomposition, threatening incumbent kiln economics. |
| Second-Life Blade Resale Platform | Polish and Romanian operators purchasing refurbished 40-meter German segments fragment established scrap flows and extend composite landfill timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with decommissioning project managers, cement plant procurement officers, pyrolysis facility operators, and German state environmental regulators combined with secondary validation against EPA hazardous waste classifications, EU Waste Framework Directive implementation reports, ECHA REACH guidance documents, and customs trade data on composite waste movements. Bottom-up decommissioning volume estimates triangulated against top-down cement kiln absorption capacity models.
Comparable-period anchoring tied projection assumptions to historical decommissioning waves from Danish and German 1990s-2000s installations. Segmentation modeling spanned component type, material matrix chemistry, recycling method, and end-user procurement pattern across the projection horizon. CAGRs derived from facility capacity buildout timelines and regulatory mandate compliance deadlines. Forecast inputs incorporated natural gas price volatility scenarios and pyrolysis kiln certification backlog durations.
The model assumes a particular technology adoption path; alternative pathways for solvolysis commercialization would alter the outlook. Forecasts reflect assumptions about EU extended producer responsibility enforcement intensity and cement producer willingness to substitute blade fragments for traditional clinker minerals. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
New Zealand Wind Energy Market