
 United States Transformer Market | 2026-2036
United States Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Transformer Market Analytics
A shift from single-source utility procurement to multi-source contracting is repositioning how transformer vendors compete for large-scale orders. General Electric leverages its domestic manufacturing footprint to secure utility tenders across the Southeast. Siemens Energy anchors its position through high-voltage direct current expertise for offshore wind interconnection projects. Virginia Transformer Corp. specializes in medium-power units for data center campuses, differentiating through rapid delivery timelines.
A transformer is an electromagnetic device that transfers electrical energy between circuits through magnetic induction, typically operating at frequencies of 50-60 Hz with voltage ratings spanning 120V to 765kV depending on application. Its core function is to step voltage up for efficient long-distance transmission or step it down for safe end-use distribution across industrial, commercial, and residential loads. Distribution transformers occupy the largest volume share due to pervasive grid-edge deployment, while power transformers command the deepest margin pools given engineering complexity and longer replacement cycles. Smart technology integration is the fastest-expanding segment as utilities deploy digital monitoring for predictive maintenance and load optimization.
FERC, NEMA, and IEEE shape the United States transformer landscape through interconnection standards, efficiency mandates, and testing protocols that dictate product certification and market access. EPA regulations on oil-filled unit containment and PCB phase-out requirements influence material selection and retrofit demand. State public utility commissions in California, New York, and Texas layer additional efficiency and resiliency requirements that filter procurement specifications. Stakeholders must monitor evolving grid-interconnection queue reforms and domestic content incentives as these policy levers determine project economics and supplier qualification.
Market Dynamics
Grid interconnection queue reforms under FERC Order 2023 are compressing procurement timelines and forcing utilities to pre-position transformer inventory years ahead of renewable project completion, fundamentally altering capital deployment rhythms across the sector.
Growth Catalysts
- Offshore wind mandates:State-level renewable portfolio standards in New York, New Jersey, and Massachusetts mandate gigawatt-scale offshore capacity requiring specialized high-voltage transformers for submarine cable landing stations.
- Data center power density:Hyperscale facilities in Northern Virginia and Phoenix now draw 500+ megawatts per campus, requiring stepped-up procurement of medium-power units with rapid installation timelines.
- Domestic content incentives:The Inflation Reduction Act's manufacturing tax credits are reshoring transformer core and coil production to qualify projects for federal renewable energy subsidies.
Market Restraints
- Grain-oriented electrical steel concentration:Domestic supply of transformer-grade core steel depends on a single operational facility in Pennsylvania, creating vulnerability to price volatility and import tariff exposure.
- Copper winding cost exposure:Raw material inputs represent 35-45% of unit manufacturing cost, with London Metal Exchange price swings directly compressing margin predictability for OEMs.
- Extended lead time for EHV units:Extra-high-voltage transformers above 345kV require 18-24 month manufacturing cycles, creating mismatch with accelerated renewable interconnection schedules.
Strategic Opportunities
- Grid edge digitalization:Distribution utilities in California and Hawaii are deploying sensor-integrated smart transformers enabling real-time load balancing and predictive maintenance revenue streams.
- Texas ERCOT expansion:The state's isolated grid requires 12+ gigawatts of new substation capacity to accommodate Permian Basin solar and battery storage projects through 2030.
- SF6 alternative insulation:Dry-type and fluoronitrile-based designs are capturing market share in urban substations where EPA greenhouse gas regulations restrict sulfur hexafluoride deployment.
Industry Challenges
- Specialized winding technician shortage:Precision coil assembly requires 5-7 year apprenticeship pipelines that vocational programs have failed to replenish, constraining domestic production ramp rates.
- IEEE C57 certification backlog:Third-party testing laboratory capacity for full-load thermal and impulse testing creates 4-6 month delays between manufacturing completion and grid interconnection approval.
- Legacy oil containment retrofit burden:Thousands of PCB-contaminated units installed before 1979 require EPA-mandated replacement or remediation, diverting utility capital from capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Transformer Market |
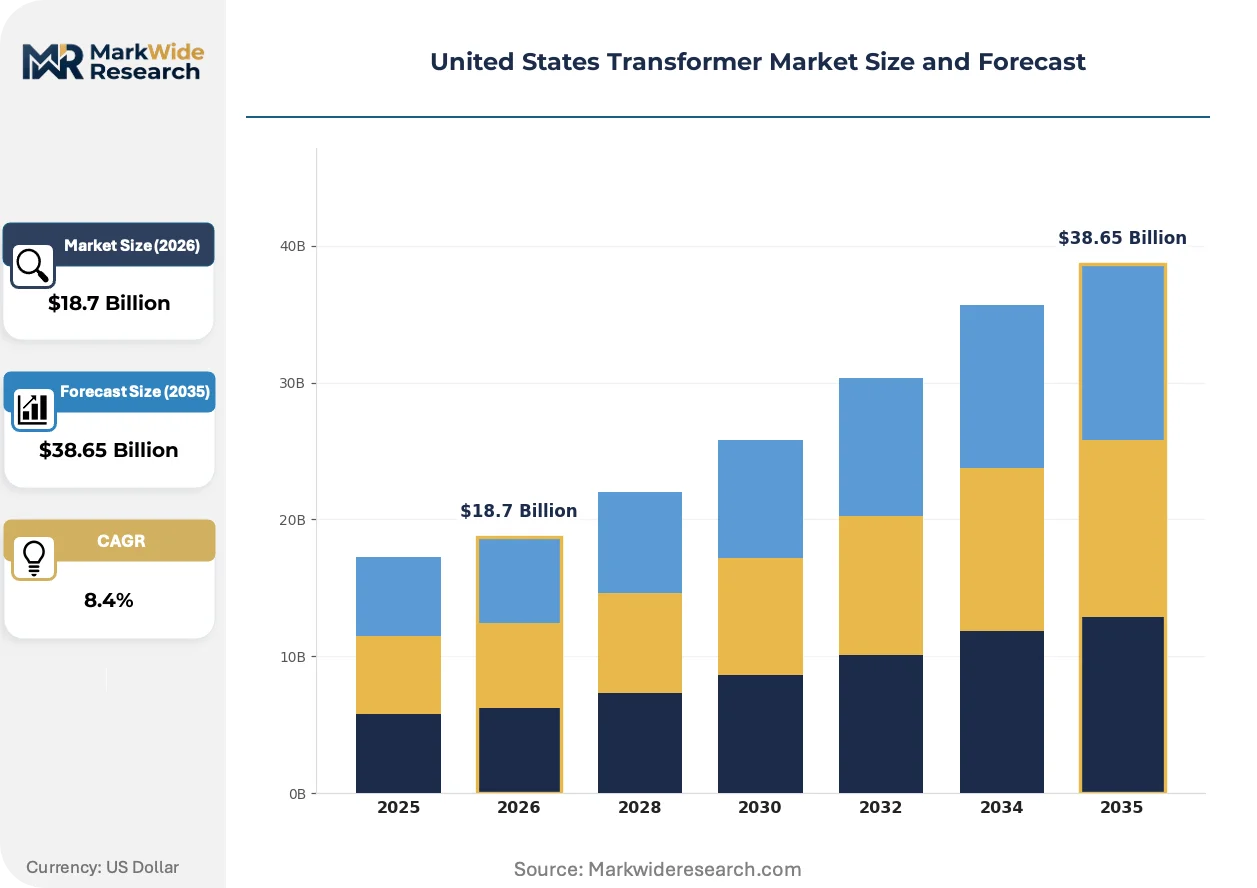
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformers, Distribution Transformers, Autotransformers, Instrument Transformers End User: Utilities, Industrial, Commercial, Residential Installation Type: Indoor, Outdoor, Substation, Pole-Mounted Technology: Electromechanical, Digital, Smart, Conventional |
| Companies Covered | General Electric, Siemens Energy, Eaton Corporation, Hitachi Energy, Virginia Transformer Corp., ABB, Schneider Electric, Howard Industries, ERMCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Transformer Market Evolving Landscape
Solid-state power electronics and advanced monitoring systems are converging to redefine transformer architecture, shifting competitive advantage from pure manufacturing scale toward integrated hardware-software capability.
Modular solid-state transformers are unifying voltage conversion, power quality management, and bidirectional power flow within a single silicon-carbide-based architecture. Data center operators in Arizona and Nevada are piloting 1-10 MVA units for direct current microgrid integration. This technology is unifying previously separate power conditioning and transformation functions, compressing substation footprints by 60% and enabling faster deployment cycles for hyperscale facilities.
FERC Order 2023 mandates standardized interconnection study processes and cost allocation reforms for transmission-level renewable projects. The rule compresses queue processing timelines from 5+ years to 3 years for projects meeting readiness criteria. Offshore wind developers in the PJM Interconnection corridor are restructuring procurement schedules to align transformer delivery with these accelerated approval windows.
Utilities are consolidating supplier relationships from fragmented regional purchasing toward national framework agreements with performance guarantees. Duke Energy and Southern California Edison now require 20-year lifecycle service commitments including predictive analytics and emergency replacement inventory. This concentration is most visible in the Southeast, where integrated utilities leverage scale to extract priority manufacturing slots from domestic OEMs.
United States Transformer Market Segmentation
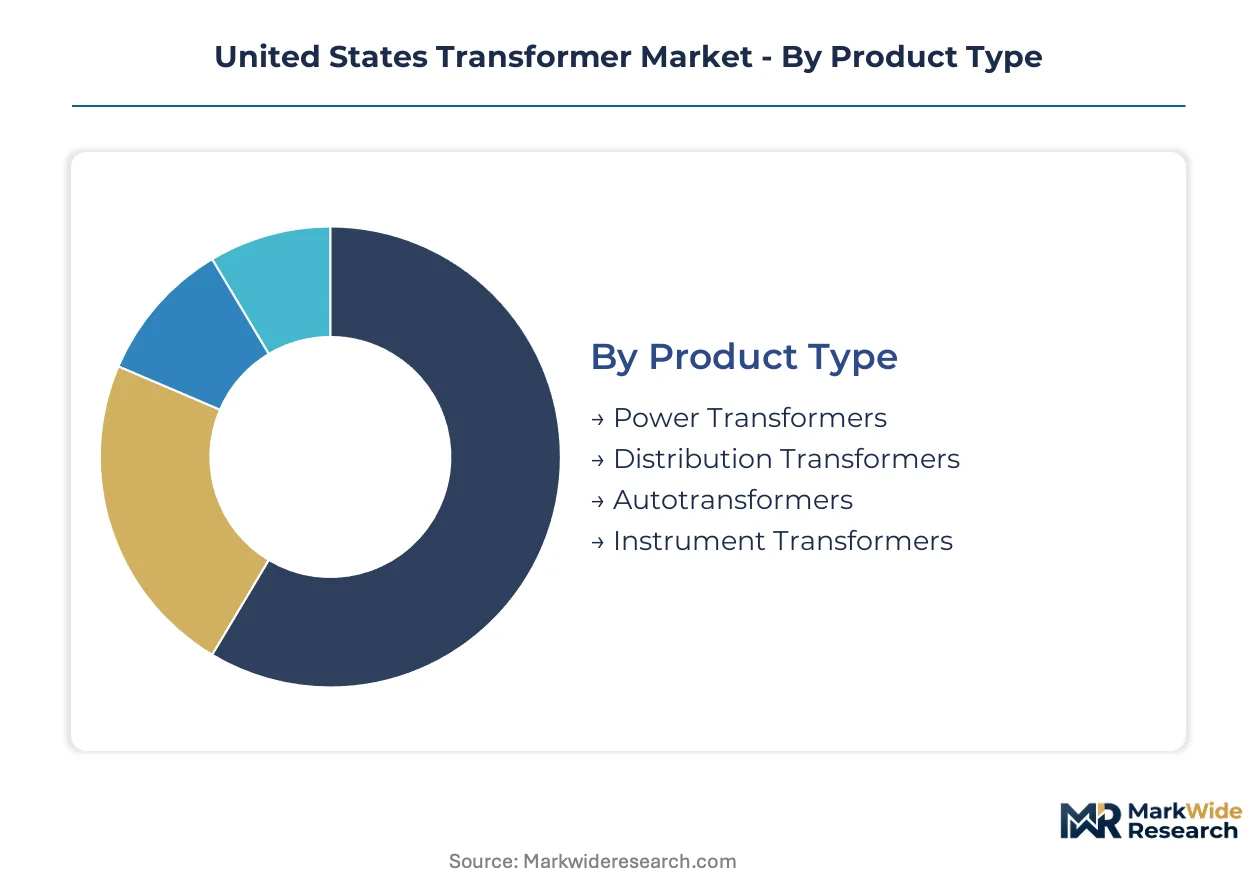
Transformer procurement patterns diverge sharply across voltage classes and deployment contexts, with utility-scale renewable interconnection driving high-voltage unit demand while data center expansion reshapes medium-power procurement timelines. Understanding these segment boundaries clarifies where capital concentrates and which technical specifications command pricing premiums.
Product Type:
Buyers select transformer class based on voltage transformation magnitude and grid position, with thermal capacity and insulation medium driving total cost of ownership calculations.
- Power Transformers:These units handle voltages above 69kV for transmission-level interconnection, utilizing oil-immersed cooling systems and laminated grain-oriented steel cores. Demand concentrates in Texas and the PJM Interconnection corridor where utility-scale solar and offshore wind projects require new substation infrastructure. Extended 18-24 month lead times create procurement bottlenecks that developers must navigate through advance reservation contracts.
- Distribution Transformers:Stepping voltage down to 4-34.5kV for local distribution networks, these units dominate unit volume through pervasive grid-edge deployment across residential and commercial feeders. California IOUs and Texas cooperatives are accelerating replacement cycles under state efficiency mandates and storm resiliency programs, compressing traditional 30-40 year asset lifecycles.
- Autotransformers:Single-winding designs offering cost and efficiency advantages for voltage ratios below 3:1, commonly deployed in transmission network voltage matching.
- Instrument Transformers:Precision measurement devices scaling high voltages and currents for metering and protection relay applications.
Distribution transformers lead on scale; smart technology integration is gaining share fastest through digital monitoring retrofits.
End User:
Procurement scale and technical specification authority vary dramatically by customer type, with integrated utilities wielding national framework agreements against fragmented commercial buyers.
- Utilities:Vertically integrated and transmission-only entities procure the largest individual units under FERC-jurisdictional interconnection standards, with Duke Energy and Southern California Edison requiring 20-year lifecycle service commitments including predictive analytics and emergency replacement inventory.
- Industrial:Heavy manufacturing and petrochemical facilities specify ruggedized units for harsh environments, with Gulf Coast refineries driving demand for explosion-proof enclosures and enhanced oil containment systems.
- Commercial:Data center operators in Northern Virginia and Phoenix now draw 500+ megawatts per campus, requiring stepped-up procurement of medium-power units with rapid installation timelines.
- Residential:Single-family and multi-family developments rely on standard pad-mounted and pole-mounted distribution units specified by host utilities.
Utilities anchor procurement volume; data center operators are expanding fastest through hyperscale facility commitments.
Installation Type:
Site constraints and environmental exposure dictate enclosure specifications, with urban density and coastal corrosion resistance driving material selection.
- Outdoor:Pad-mounted and substation-deployed units constitute the majority of new capacity additions, with Arizona and Nevada solar projects requiring NEMA 3R enclosures for extreme temperature cycling.
- Indoor:Dry-type units with cast resin insulation serve high-rise commercial buildings and underground substations where fire safety codes restrict oil-filled designs.
- Substation:Integrated switchgear-transformer assemblies reduce footprint and installation labor for greenfield renewable interconnection projects.
- Pole-Mounted:Single-phase units serve rural distribution spurs and residential tap lines across the Southeast and Mountain West.
Outdoor installations dominate capacity additions; indoor configurations are climbing fastest through urban infill electrification.
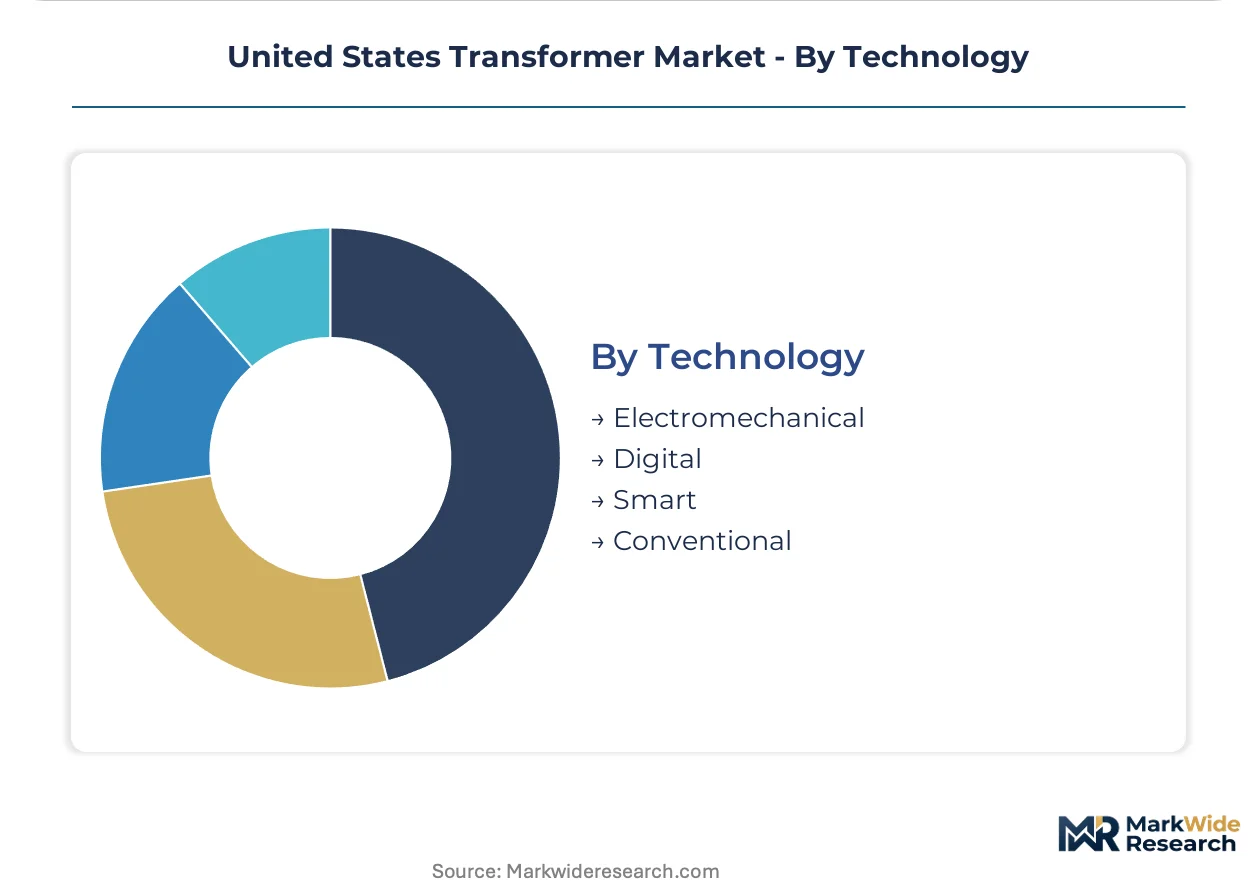
Technology:
Digital capability is repositioning competitive advantage from pure manufacturing scale toward integrated hardware-software offerings with recurring revenue potential.
- Smart:Sensor-integrated designs enabling real-time thermal monitoring, load balancing, and predictive maintenance are capturing premium pricing in California and Hawaii where grid edge digitalization programs subsidize deployment.
- Digital:Solid-state power electronics using silicon-carbide semiconductors are unifying voltage conversion and power quality management, with Arizona data centers piloting 1-10 MVA units for DC microgrid integration.
- Electromechanical:Conventional copper-and-steel designs retain cost advantage for standard utility specifications without monitoring requirements.
- Conventional:Legacy oil-immersed units without digital instrumentation serve replacement markets and budget-constrained rural cooperatives.
Electromechanical units retain volume leadership; solid-state architectures are expanding most quickly through data center pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic content incentives under the Inflation Reduction Act are shifting production location decisions toward states with qualified manufacturing zones, compressing the cost-of-compliance gap between coastal import hubs and inland fabrication centers.
Texas
ERCOT's isolated grid requires substantial substation expansion to absorb Permian Basin solar and battery storage additions. State regulators exempt certain transmission investments from rate-base scrutiny, accelerating utility procurement cycles. Houston and Dallas-Fort Worth host the densest cluster of transformer service facilities and coil winding operations.
California
IOUs face accelerated distribution transformer replacement mandates under CPUC resiliency and efficiency rules. CARB regulations on SF6 emissions are driving dry-type unit adoption in urban substations. The Central Valley solar belt and Bay Area data center corridors concentrate demand for medium-power and high-voltage units.
PJM Interconnection Corridor
Offshore wind interconnection queues in New Jersey, Maryland, and Virginia are compressing procurement timelines for submarine cable landing stations. FERC Order 2023 standardized study processes align transformer delivery schedules with accelerated approval windows. Northern Virginia data center campuses now draw 500+ megawatts each, requiring rapid-deployment medium-power units.
Southeast
Integrated utilities in Georgia, North Carolina, and South Carolina leverage national framework agreements to secure priority manufacturing slots from domestic OEMs. State public utility commissions mandate storm hardening programs that shorten replacement cycles for distribution assets. Charleston and Savannah port infrastructure supports heavy-lift logistics for extra-high-voltage unit delivery.
Pacific Northwest
Hydropower-rich utilities in Washington and Oregon are integrating utility-scale solar and wind, requiring new transmission step-up capacity. State renewable portfolio standards mandate gigawatt-scale additions that strain existing substation infrastructure. Seattle and Portland serve as logistics hubs for transformer delivery to remote renewable project sites.
United States Transformer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and solid-state architectures. The vendor base organizes around three archetypes: integrated conglomerates with domestic manufacturing footprints, specialized medium-power fabricators serving data center demand, and technology licensors advancing silicon-carbide power electronics. Capacity reservation contracts and 20-year lifecycle service commitments represent the dominant competitive moves, with utilities consolidating supplier relationships to secure priority delivery slots.
Among integrated conglomerates, General Electric and Siemens Energy exemplify archetypes anchored in high-voltage transmission expertise and offshore wind interconnection capability. Virginia Transformer Corp. occupies a position within the specialized tier, differentiated by rapid delivery timelines for medium-power units serving hyperscale facility procurement. These three entities represent distinct strategic postures: manufacturing scale, technical specialization, and velocity-focused service models.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Eaton Corporation |
| Hitachi Energy |
| Virginia Transformer Corp. |
| ABB |
| Schneider Electric |
| Howard Industries |
| ERMCO |
| Others |
Value Network & Pricing Analysis
Solid-state transformer architectures using silicon-carbide semiconductors are compressing manufacturing cost curves while fragmenting procurement channels between electromechanical incumbents and power-electronics specialists. This technology transition simultaneously erodes traditional copper-and-steel cost advantages and concentrates advanced component sourcing among semiconductor fabricators.
Pricing Analysis
Distributor margins on standard distribution transformers compress under utility framework agreements that extract volume discounts for 20-year service commitments. Three-tier pricing structure across premium smart units, standard electromechanical designs, and economy-grade replacements reflects certification grade and digital monitoring integration. Cost compression in medium-power segments intensifies as data center operators bundle rapid-delivery premiums into total cost of ownership calculations. Rural cooperatives exhibit highest price sensitivity; offshore wind developers accept premium positioning for specialized high-voltage units with accelerated delivery guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for medium-power units, while utility procurement flows through national framework agreements with integrated conglomerates. Grain-oriented electrical steel draws from a single domestic Pennsylvania facility, with supplementary sourcing from Japan and Germany. Copper winding supply rests on Chilean mining output and domestic scrap recovery. Single-source vulnerability in core steel creates exposure to tariff volatility and import disruption. Distribution runs through regional service hubs in Houston, Dallas-Fort Worth, and Chicago with heavy-lift logistics for extra-high-voltage unit delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic content incentives under the Inflation Reduction Act create arbitrage between qualified manufacturing zones in Pennsylvania and Texas versus coastal import-dependent procurement, rewarding capital deployment to states with transformer-grade steel production.
For Market Incumbents: Cement priority manufacturing slots through 20-year lifecycle service commitments that bundle predictive analytics and emergency replacement inventory. Defend against silicon-carbide power-electronics entrants by backward integration into grain-oriented electrical steel sourcing to secure core material access. Expand coil-winding capacity in Texas ERCOT corridor to capture Permian Basin solar substation demand.
For New Entrants and Emerging Players: Solid-state transformer pilot programs at Arizona and Nevada data centers offer technology-first wedge into medium-power procurement. Target urban indoor substation retrofits where EPA SF6 restrictions drive dry-type and fluoronitrile-based insulation demand. Pursue licensing arrangements with silicon-carbide semiconductor suppliers to bypass capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized medium-power fabricators without high-voltage transmission credentials. Long-term viability favors suppliers with domestic core steel access and digital monitoring software stacks. Watch FERC interconnection queue processing velocity as inflection indicator for transformer delivery backlog clearing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Core Steel Capacity Expansion | Secures supply chain resilience against Pennsylvania facility disruption and qualifies projects for IRA manufacturing credits. |
| Smart Transformer Digital Platform Launch | Enables recurring predictive maintenance revenue from California IOU grid-edge digitalization programs. |
| Offshore Wind Interconnection Partnership | Aligns high-voltage unit delivery schedules with FERC Order 2023 accelerated approval windows in PJM corridor. |
| Solid-State Transformer Pilot Scale-Up | Captures data center direct-current microgrid integration demand from Arizona and Nevada hyperscale campuses. |
| Winding Technician Apprenticeship Program | Addresses specialized coil assembly labor constraints constraining domestic production ramp rates. |
Research Methodology
Direct dialogue with utility planning officers, transformer OEM procurement directors, EPC contractors, and grid interconnection specialists anchored qualitative insights. Secondary validation drew from FERC filings, EIA electricity infrastructure databases, IEEE standards documentation, and state public utility commission dockets. Bottom-up unit demand modeling triangulated against top-down transmission investment forecasts.
Bottom-up segmentation analysis modeled voltage class, installation type, cooling medium, and digital technology integration across the projection horizon. CAGRs derived from utility capital expenditure trajectories, renewable interconnection queue velocities, and data center power density trends. Forecast inputs incorporated grain-oriented electrical steel production capacity, copper price volatility bands, and FERC Order 2023 implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interconnection queue reform implementation, domestic steel production expansion, and solid-state transformer technology maturation. Forecasts reflect documented assumptions on policy continuity and material supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Locomotive Traction Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
United States Power Transformer Market
Transformers
Transformer Bobbin Market
Transformers
India Power Transformer Market
Transformers
North America Oil Filled Transformer Market
Transformers
Transformer Steel Market
Transformers
Single Phase Power Transformer Market
Transformers
China Transformer Market
Transformers
North America Transformer Market
Transformers
Europe Distribution Transformer Market
Transformers
Europe Smart Transformers Market
Transformers
Step Up/Down Transformers Market
Transformers
Canada Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Latin America Transformer Market