
 Step Up/Down Transformers Market | 2026-2036
Step Up/Down Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
Step Up/Down Transformers Market Analytics
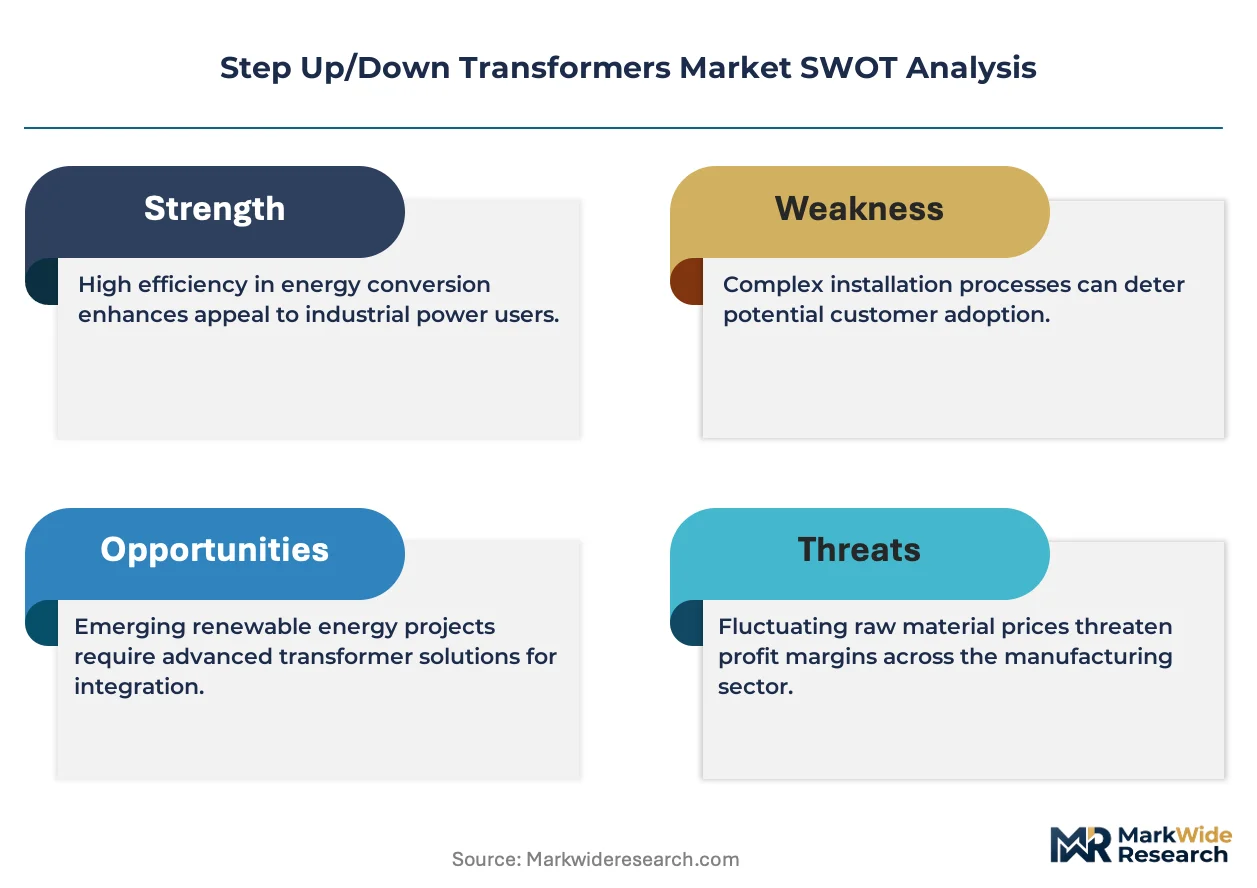
Amorphous metal core material is pivoting transformer economics by slashing no-load losses versus conventional grain-oriented electrical steel. ABB Ltd. leverages extensive vertical integration from core material sourcing through final assembly to protect margin structures. Siemens Energy AG anchors its position through high-voltage direct current tie-ins that demand specialized step-up configurations. Hitachi Energy Ltd. differentiates via digital transformer monitoring platforms that extend service revenue beyond hardware sales.
Step up/down transformers are electromagnetic devices that transfer electrical energy between circuits through mutual induction, typically operating at frequencies of 50–60 Hz with core laminations stacked to minimize eddy current losses and hysteresis, serving to raise or lower voltage levels for efficient power transmission and safe end-use distribution. Three-phase units dominate utility and heavy industrial procurement due to superior power density and balanced load handling, while single-phase designs sustain steady demand across residential distribution networks and rural electrification programs. The renewable energy application segment is expanding fastest as solar farms and offshore wind clusters require step-up transformers to interface with medium-voltage collection systems and high-voltage transmission backbones.
IEC 60076 and IEEE C57 standards govern insulation classes, temperature rise limits, and short-circuit withstand capabilities, while the EU Ecodesign Directive and U.S. DOE efficiency rules mandate minimum performance thresholds that filter out lower-tier suppliers. China's GB standards and India's CEA technical regulations impose localized testing protocols that shape market access for foreign manufacturers. Stakeholders must monitor evolving efficiency tiers and carbon-border adjustment mechanisms to calibrate product portfolios and regional manufacturing footprints.
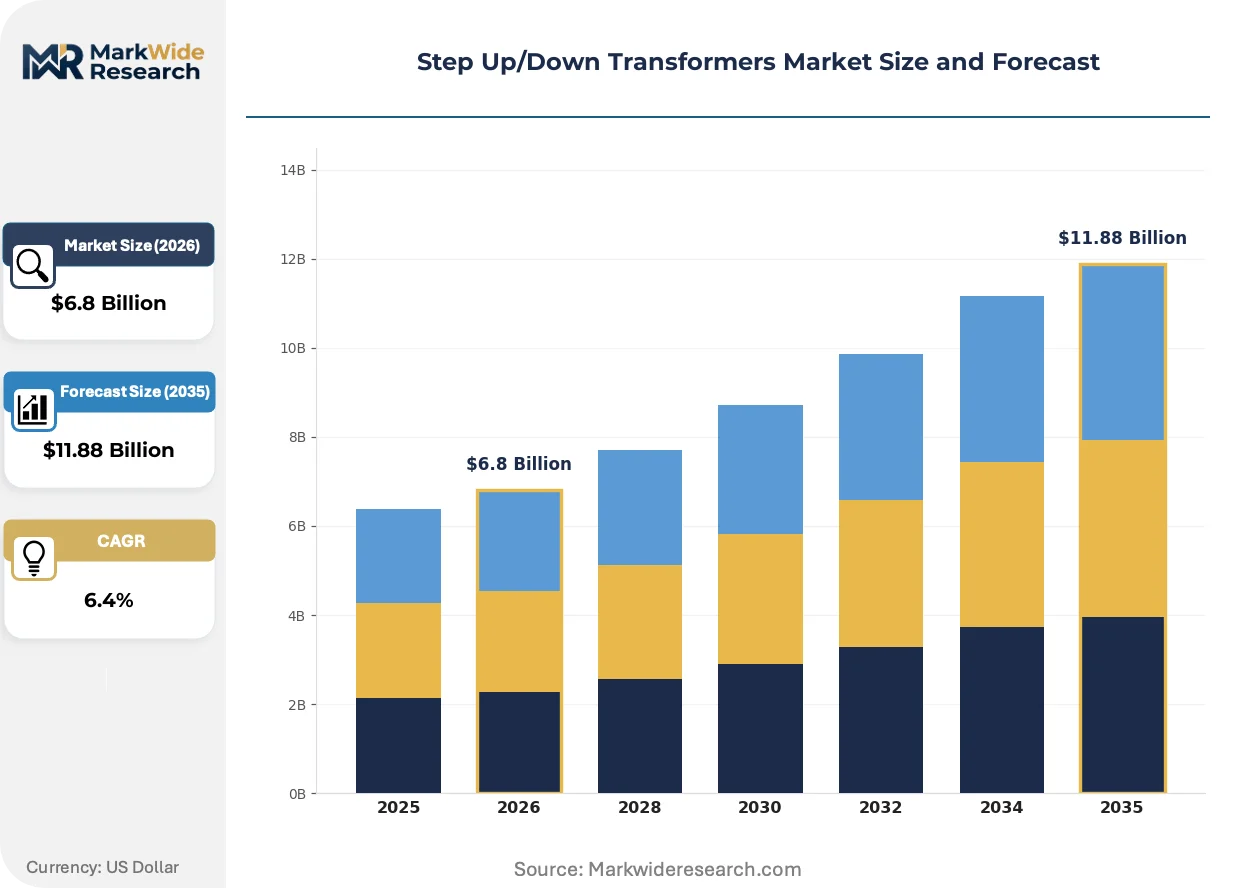
Market Dynamics
The transformer market is reconfiguring around efficiency mandates that compel asset owners to retire silicon-steel core units before end-of-life, creating a replacement cycle independent of traditional failure-driven procurement.
Growth Catalysts
- EU Ecodesign Directive Tier 2 requirements:Minimum efficiency standards for liquid-immersed distribution transformers are accelerating replacement demand across European distribution networks.
- Utility-scale solar deployment:Photovoltaic clusters in India, China, and the United States require step-up transformers to interface with medium-voltage collection systems and transmission backbones.
- Amorphous metal core adoption:No-load loss reductions of up to 80% versus conventional grain-oriented electrical steel are reshaping total-cost-of-ownership calculations for grid operators.
Market Restraints
- Grain-oriented electrical steel supply concentration:Production of specialized transformer-grade steel concentrates among a limited set of integrated steelmakers, exposing transformer manufacturers to input price volatility and allocation constraints.
- IEC 60076-11 dry-type thermal limitations:Cast-resin insulation classes cap unit ratings at lower voltages than liquid-immersed alternatives, restricting dry-type penetration in high-voltage transmission applications.
- Copper and aluminum price correlation:Winding material costs constitute 25-35% of total manufacturing cost, making margin protection dependent on commodity hedging sophistication.
Strategic Opportunities
- Rural electrification in sub-Saharan Africa:Mini-grid and off-grid solar installations require compact step-up/step-down units for voltage matching between generation assets and distribution networks.
- Digital twin integration:Real-time thermal monitoring and dissolved gas analysis are converging with transformer hardware to create recurring service revenue streams beyond equipment sales.
- U.S. Inflation Reduction Act domestic content bonuses:Tax credit adders for projects sourcing qualifying domestic transformers are incentivizing reshoring of manufacturing capacity.
Industry Challenges
- Transformer design engineer scarcity:Electromagnetic modeling expertise and insulation coordination knowledge are concentrating among retiring specialists, constraining product development velocity.
- Multi-standard certification timelines:Simultaneous pursuit of IEEE C57, IEC 60076, and GB 1094 approvals extends time-to-market for platforms targeting multiple geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Step Up/Down Transformers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Buck-Boost, Autotransformer Application: Industrial, Residential, Commercial, Renewable Energy Installation: Indoor, Outdoor, Wall-Mounted, Pole-Mounted End User: Utilities, Manufacturing, Construction, Electrical Contractors |
| Companies Covered | ABB Ltd., Siemens Energy AG, Hitachi Energy Ltd., GE Vernova, Schneider Electric SE, Mitsubishi Electric Corporation, Eaton Corporation PLC, TBEA Co., Ltd., Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Step Up/Down Transformers Market Evolving Landscape
Transformer technology is bifurcating between ultra-high-efficiency premium units for regulated utilities and cost-optimized designs for merchant renewable developers, with digital monitoring layers becoming standard across both tiers.
Amorphous metal ribbon is absorbing the efficiency premium previously captured by advanced grain-oriented silicon steel in distribution-class units. European distribution system operators are adopting amorphous-core designs for new urban substations to meet loss-reduction targets. The technology is absorbing margin pressure from raw material suppliers by enabling transformer OEMs to command pricing premiums through guaranteed loss performance rather than commodity-grade specifications.
China's GB 20052-2020 efficiency standards for three-phase distribution transformers are tightening no-load and load-loss limits in three-year intervals. Domestic manufacturers are accelerating R&D into ultra-low-loss core configurations to maintain market access. The regulation is forcing foreign suppliers to establish local testing partnerships or joint ventures to navigate conformity assessment procedures.
Asset owners are unbundling transformer procurement from installation and commissioning services, treating hardware as a commodity while negotiating separate performance guarantees for field assembly. This fragmentation is compressing OEM service margins and elevating the importance of distributor and EPC relationships. The shift is most pronounced in North American utility procurement, where integrated turnkey contracts are giving way to multi-vendor project structures.
Step Up/Down Transformers Market Segmentation
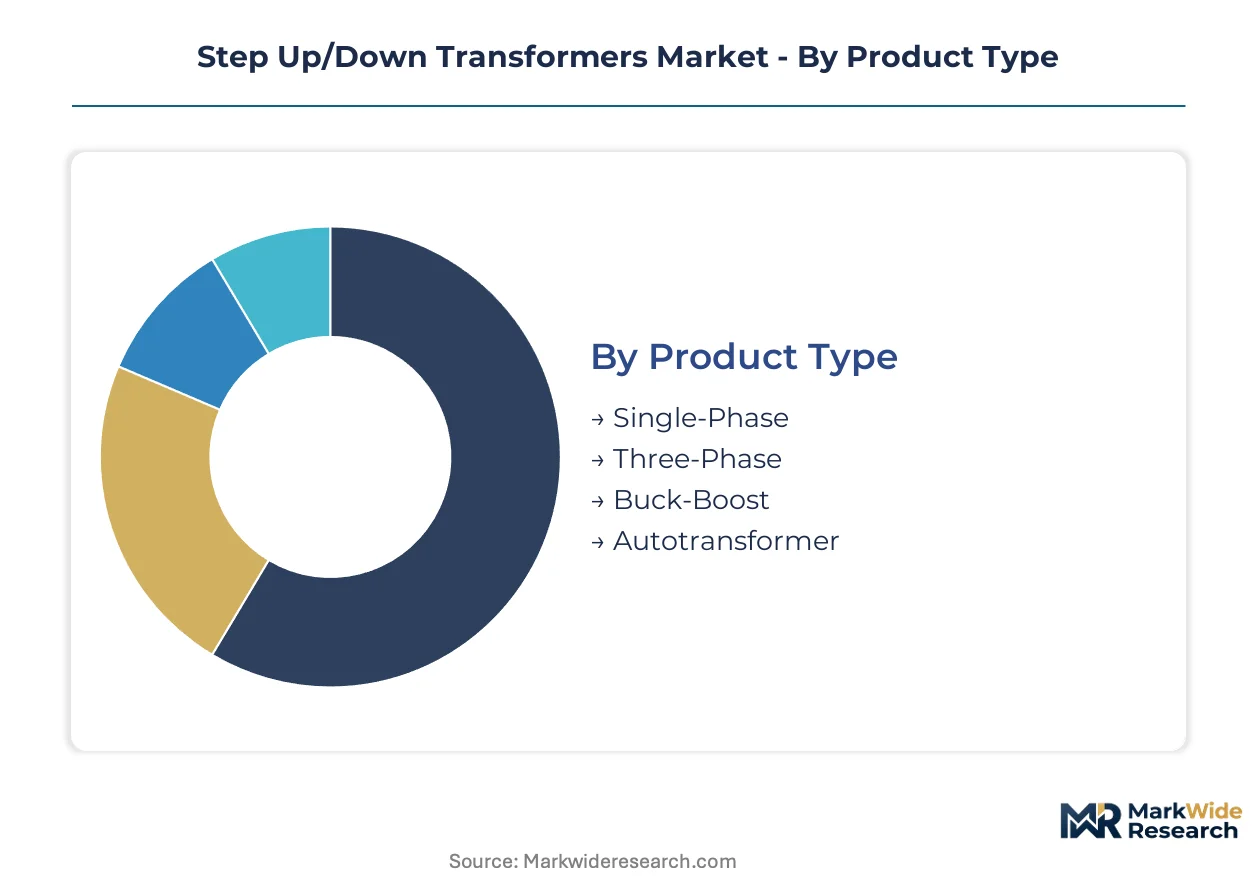
Transformer procurement patterns diverge sharply across voltage classes and deployment contexts, with efficiency mandates and renewable interconnection standards rewriting specification priorities for each segment cluster.
Product Type:
Upgrade cycles are decoupling from asset failure timelines as efficiency regulations force premature retirement of older core designs across all product categories.
- Single-Phase:These units employ a single primary and secondary winding pair for low-voltage distribution, typically rated below 50 kVA. Rural electrification programs in India and residential distribution networks in the United States concentrate procurement, with compact pole-mounted designs dominating last-mile infrastructure.
- Three-Phase:Three distinct windings arranged in delta or wye configurations deliver balanced power for heavy industrial loads and utility substations. Manufacturing facilities in China and Germany drive volume, with amorphous metal core adoption accelerating to meet loss-reduction targets under national efficiency codes.
- Buck-Boost:Autotransformer variants with tapped windings provide fractional voltage adjustment for equipment protection. Data centers and precision manufacturing lines specify these units to buffer grid voltage fluctuations.
- Autotransformer:Single-winding designs with shared magnetic circuits offer size and cost advantages for modest voltage ratios. Urban distribution upgrades in Brazil and commercial building retrofits in Japan favor these compact configurations.
Three-Phase sits at the top of the volume ranking, with Renewable Energy climbing the fastest.
Application:
Cost-tier stratification separates premium-specification utility procurements from price-optimized merchant renewable developer orders.
- Industrial:Heavy manufacturing, mining operations, and chemical processing plants demand ruggedized units with high short-circuit withstand capability. Steel mills in South Korea and petrochemical complexes in Saudi Arabia specify liquid-immersed designs for thermal performance under continuous loading.
- Residential:Distribution utilities serving dense urban populations prioritize compact, low-noise units for pad-mounted and underground vault installations. Apartment district electrification in Vietnam and suburban expansion in Australia sustain steady replacement demand.
- Commercial:Office complexes, retail centers, and hospitality facilities require dry-type or cast-resin units for indoor safety compliance. Shopping mall construction in Indonesia and hospital expansions in Turkey specify these fire-resistant alternatives.
- Renewable Energy:Solar farms and offshore wind clusters need step-up transformers to bridge generation voltage to collection system levels. Photovoltaic installations in Spain and onshore wind projects in Sweden are expanding procurement fastest as interconnection queues clear.
Industrial commands the largest installed base, though Renewable Energy is gaining share fastest as capacity additions accelerate.
Installation:
Physical mounting constraints dictate insulation class selection and thermal management architecture across deployment environments.
- Indoor:Cast-resin or dry-type units with IP-rated enclosures occupy electrical rooms and basement vaults in commercial and high-rise residential buildings. Fire codes in Singapore and seismic requirements in Chile shape enclosure specifications.
- Outdoor:Liquid-immersed designs in weather-resistant tanks withstand temperature extremes and precipitation exposure. Substation yards in Texas and desert solar sites in Morocco deploy these robust configurations.
- Wall-Mounted:Compact single-phase units attach directly to building facades or utility poles for space-constrained urban environments. Narrow streetscapes in Italy and dense favela electrification in Brazil favor this mounting approach.
- Pole-Mounted:Cylindrical or rectangular tanks suspended from utility poles serve rural distribution spurs and temporary construction power. Grid extension programs in Nigeria and agricultural electrification in Argentina rely heavily on these accessible designs.
Outdoor configurations dominate utility-scale deployment, with Wall-Mounted expanding most quickly in urban densification corridors.
End User:
Procurement authority fragmentation is unbundling hardware purchasing from installation and commissioning services across customer categories.
- Utilities:Vertically integrated grid operators and independent transmission companies specify loss-guaranteed units with 30-40 year service life expectations. State-owned distributors in France and investor-owned utilities in California drive standardization through master supply agreements.
- Manufacturing:Industrial facility owners prioritize total-cost-of-ownership metrics including no-load loss and maintenance intervals. Automotive plants in Mexico and semiconductor fabs in Taiwan demand high reliability with minimal downtime exposure.
- Construction:Temporary power specialists and permanent infrastructure developers source portable or skid-mounted units for phased project energization. High-rise construction in Dubai and tunneling projects in Switzerland create cyclical demand spikes.
- Electrical Contractors:Installation firms serving commercial and residential markets procure through distributor channels with rapid delivery requirements. Service upgrade backlogs in the United Kingdom and electrification contractors in South Africa sustain this fragmented procurement tier.
Utilities anchor volume procurement, with Electrical Contractors showing the steepest expansion trajectory as distributed generation interconnection multiplies project sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing belt concentrates the world's largest transformer production capacity, feeding both domestic grid expansion and export demand across Asia and Africa.
United States
Texas and California utility-scale solar installations drive step-up transformer procurement as interconnection queues clear for renewable projects. The Inflation Reduction Act domestic content bonuses incentivize reshoring of manufacturing capacity to capture tax credit adders. Transformer assembly facilities in Wisconsin and South Carolina are expanding to serve regional utility procurement.
China
Provincial grid operators in Jiangsu and Guangdong provinces are retiring silicon-steel core units ahead of failure timelines under GB 20052-2020 efficiency standards. The MIIT mandates three-year tightening intervals for no-load and load-loss limits. TBEA Co., Ltd. and domestic competitors anchor production clusters in Xinjiang and Shenyang serving Belt and Road infrastructure exports.
India
Rural electrification programs under the Saubhagya scheme sustain pole-mounted single-phase transformer demand across Bihar and Uttar Pradesh. The CEA technical regulations impose localized testing protocols that shape market access for foreign manufacturers. Gujarat and Tamil Nadu industrial corridors are procuring three-phase units for manufacturing facility expansion.
Germany
Distribution system operators in North Rhine-Westphalia and Bavaria are adopting amorphous-core designs for urban substations to meet EU Ecodesign Directive Tier 2 loss-reduction targets. The REACH regulation governs insulation fluid chemistry for liquid-immersed units. Siemens Energy AG anchors high-voltage direct current tie-in manufacturing in Nuremberg and Berlin.
Brazil
Amazon basin mini-grid solar installations require compact step-up/step-down units for voltage matching between generation assets and distribution networks. ANEEL regulatory frameworks govern grid code compliance for renewable interconnection. São Paulo and Minas Gerais industrial zones sustain demand for heavy-duty three-phase transformers in mining and petrochemical applications.
Step Up/Down Transformers Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers add amorphous metal core winding lines to capture efficiency-premium pricing. The vendor base stratifies into three tiers: integrated electrical conglomerates with captive steel sourcing, national champions serving protected domestic markets, and regional fabricators competing on delivery speed. Two strategic archetypes predominate: vertically integrated specialists controlling core material through final assembly, and technology licensors leveraging digital monitoring platforms for recurring service revenue. Geographic expansion into sub-Saharan Africa and strategic partnerships with EPC contractors represent the dominant competitive vectors.
Within the integrated conglomerate tier, ABB Ltd. and Siemens Energy AG exemplify archetypes of upstream control over core material supply chains. Hitachi Energy Ltd. occupies a position representing the digital service extension model. Among Asia-Pacific-based fabricators, TBEA Co., Ltd. and Mitsubishi Electric Corporation sit within the national champion category serving protected procurement channels. GE Vernova and Schneider Electric SE anchor the diversified industrial technology group archetype, leveraging cross-divisional project bundling for grid infrastructure contracts. Eaton Corporation PLC and Toshiba Corporation represent mid-scale specialists competing on application-specific configurations rather than volume scale.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens Energy AG |
| Hitachi Energy Ltd. |
| GE Vernova |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Eaton Corporation PLC |
| TBEA Co., Ltd. |
| Toshiba Corporation |
| Others |
Value Network & Pricing Analysis
Grain-oriented electrical steel spot indices cascade through transformer manufacturing cost structures, compressing margins for silicon-steel core designs while amplifying pricing power for amorphous metal alternatives that command efficiency premiums under EU Ecodesign Tier 2 mandates.
Pricing Analysis
Input-cost pass-through dominates transformer pricing, with copper and aluminum winding material fluctuations constituting 25-35% of manufacturing cost bases. Three-tier pricing structure across premium, standard, and economy levels separates amorphous-core loss-guaranteed units from conventional silicon-steel designs and commodity-grade imports. Pricing pressure stems from grain-oriented electrical steel supply concentration among integrated steelmakers, forcing margin compression on non-integrated fabricators. Merchant renewable developers exhibit highest price sensitivity, while regulated utilities prioritize total-cost-of-ownership metrics including no-load loss guarantees over upfront capital expenditure.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale procurement for regulated grid operators, while distributor networks serve electrical contractors and commercial installers requiring rapid delivery turnaround. Manufacturing concentrates in China, India, and Germany, with the Yangtze River Delta anchoring global amorphous metal ribbon winding capacity. Supply chains draw from grain-oriented electrical steel mills in Japan and South Korea, copper cathode from Chilean smelters, and insulation materials from German chemical producers. Single-source vulnerability concentrates in transformer-grade steel production, exposing OEMs to allocation constraints during capacity tightness. Distribution runs through master supply agreements with national utilities, EPC contractor partnerships for renewable projects, and electrical wholesale channels for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where efficiency mandates under EU Ecodesign Directive Tier 2 and China's GB 20052-2020 standards force premature replacement cycles independent of asset failure timelines.
For Market Incumbents: Extend digital monitoring platform penetration to capture recurring service revenue beyond hardware commoditization. Defend margin structures through backward integration into amorphous metal core material sourcing, mirroring ABB's vertical control from ribbon production through final assembly. Add winding capacity in Wisconsin and South Carolina to qualify for U.S. Inflation Reduction Act domestic content bonuses. Counter emerging Chinese national champions by deepening IEC 60076-11 dry-type certification portfolios for indoor commercial applications where fire codes restrict liquid-immersed alternatives. For New Entrants and Emerging Players: Enter via rural electrification mini-grid deployments in sub-Saharan Africa where established OEMs maintain limited presence. Target solar-plus-storage hybrid installations requiring compact step-up/step-down units for voltage matching between DC generation assets and AC distribution networks. Partner with regional EPC contractors in Nigeria and Kenya to bypass utility procurement bureaucracy. Leverage modular, skid-mounted designs for construction temporary power applications where delivery speed outweighs brand preference. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists controlling amorphous metal core winding technology and digital twin integration capabilities. Long-term viability favors platforms with demonstrated conformity assessment navigation across IEEE C57, IEC 60076, and GB 1094 multi-standard certification regimes. Target acquisition candidates include regional fabricators in India and Southeast Asia with established CEA testing partnerships. Monitor EU carbon-border adjustment mechanism implementation timelines as inflection indicators for margin structure shifts favoring European manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Capacity Expansion | Captures efficiency-premium pricing under EU Ecodesign Tier 2 loss-reduction mandates. |
| Digital Twin Platform Integration | Extends service revenue streams beyond hardware sales through real-time thermal monitoring. |
| Domestic Content Qualification | Positions manufacturers to capture U.S. Inflation Reduction Act tax credit adders for utility-scale solar. |
| Multi-Standard Certification Investment | Accelerates time-to-market for platforms targeting simultaneous IEEE C57 and IEC 60076 approvals. |
| Rural Electrification Partnership | Opens procurement channels in sub-Saharan Africa mini-grid and off-grid solar installations. |
Research Methodology
Multiple input streams — utility procurement database tracking, EPC contractor project pipelines, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews with transformer design engineers, utility planning officers, and electrical distributor procurement heads informed specification priority shifts and replacement cycle timing. Secondary validation drew from IEC 60076 standard revision documentation, EU Ecodesign Directive implementing measures, FERC interconnection queue data, and customs trade records for transformer-grade steel and copper winding material flows.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmentation modeling across voltage class, core material type, installation environment, and end-user procurement authority. CAGRs were derived from replacement demand curves under efficiency mandate compliance deadlines, renewable capacity addition forecasts, and industrial electrification load growth assumptions. Industry-specific forecast inputs included dissolved gas analysis adoption rates for predictive maintenance revenue modeling and amorphous metal ribbon production capacity expansion timelines.
Inputs from utility master supply agreement disclosures and national regulatory efficiency standard publications were available through the study window; gaps in merchant renewable developer procurement transparency introduce uncertainty bands around non-regulated demand segments. Forecasts reflect assumptions regarding interconnection queue clearance rates, commodity price stabilization, and carbon-border adjustment mechanism implementation scope. Periodic stress-testing of base assumptions against actual efficiency mandate enforcement intensity and raw material supply allocation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Transformer Steel Market
Transformers
India Power Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Green Transformer Market
Transformers
Rectifier Transformers Market
Transformers
Global Large Power Transformers Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Neon Transformer Market
Transformers
Locomotive Traction Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Current Transformer Market
Transformers
United States Power Transformer Market
Transformers
China Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market