
 Poultry Feed Market | 2026-2036
Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Feed Market Intelligence
Contract-based financing for feed mill infrastructure is rewriting competitive entry barriers across developing poultry belts. ForFarmers leverages its European network density to sustain margin capture in layer feed formulations. Charoen Pokphand Foods anchors Southeast Asian supply through integrated broiler operations that span hatchery to processing. Cargill competes on global grain origination strength, positioning its nutrition division to navigate volatile commodity cycles.
Poultry feed denotes formulated rations combining grains, protein meals, vitamins, minerals, and functional additives to optimize growth rates, feed conversion ratios, and flock health across distinct production stages. Manufacturing employs thermal processing, pelleting, and extrusion to achieve standardized nutrient density and reduce pathogen loads. Broiler feed dominates volume as integrators prioritize rapid weight gain economics, while enzyme-supplemented formulations represent the fastest-growing ingredient composition segment due to phosphorus reduction mandates and digestibility improvements. Layer feed occupies mature margin pools where calcium specification and shell quality parameters differentiate supplier relationships.
The EU Green Deal and REACH frameworks restrict antibiotic growth promoter residues and mandate feed chain traceability, compelling reformulation investments across European suppliers. Brazil's ANVISA and the US FDA enforce divergent mycotoxin thresholds and veterinary drug withdrawal protocols that shape export-oriented milling standards. Stakeholders must monitor regulatory divergence between destination markets when allocating R&D budgets and certifying production lines for cross-border shipment eligibility.
Market Dynamics
Integrators are consolidating feed procurement under captive milling operations, compressing third-party supplier margins and rewriting asset-light entry strategies across Brazil, Thailand, and Poland.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in feed storage infrastructure accelerates investment in climate-controlled silo networks across member states.
- Enzyme-supplemented formulations:Phytase and xylanase additives reduce phosphorus discharge liabilities while improving digestibility coefficients in broiler rations.
- Vertically integrated processors:Charoen Pokphand Foods and JBS expand backward into feed milling to secure margin capture across hatchery-to-processing value chains.
Market Restraints
- Soybean meal price volatility:Argentine export taxes and Brazilian logistics bottlenecks transmit input cost spikes directly into formulation economics.
- REACH chemical registration:Novel feed additive approval timelines stretch 18-36 months, freezing innovation pipelines for European suppliers.
- Alternative protein competition:Cultivated meat and precision fermentation platforms threaten long-term demand elasticity for conventional poultry protein.
Strategic Opportunities
- India's layer sector consolidation:Contract farming expansion in Andhra Pradesh and Tamil Nadu creates demand for standardized phase-feeding protocols.
- Insect meal integration:Black soldier larva protein qualifies under EU aquafeed authorization pathways, with poultry applications pending EFSA safety clearance.
- Digital feed formulation platforms:Real-time nutrient optimization software enables millers to substitute ingredients dynamically against commodity price swings.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in amino acid balancing and mycotoxin binder selection concentrates among aging technical workforces in Europe and North America.
- Multi-jurisdiction certification stacking:Simultaneous compliance with US FDA veterinary feed directives, EU feed hygiene regulations, and destination-country residue limits strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Feed Market |
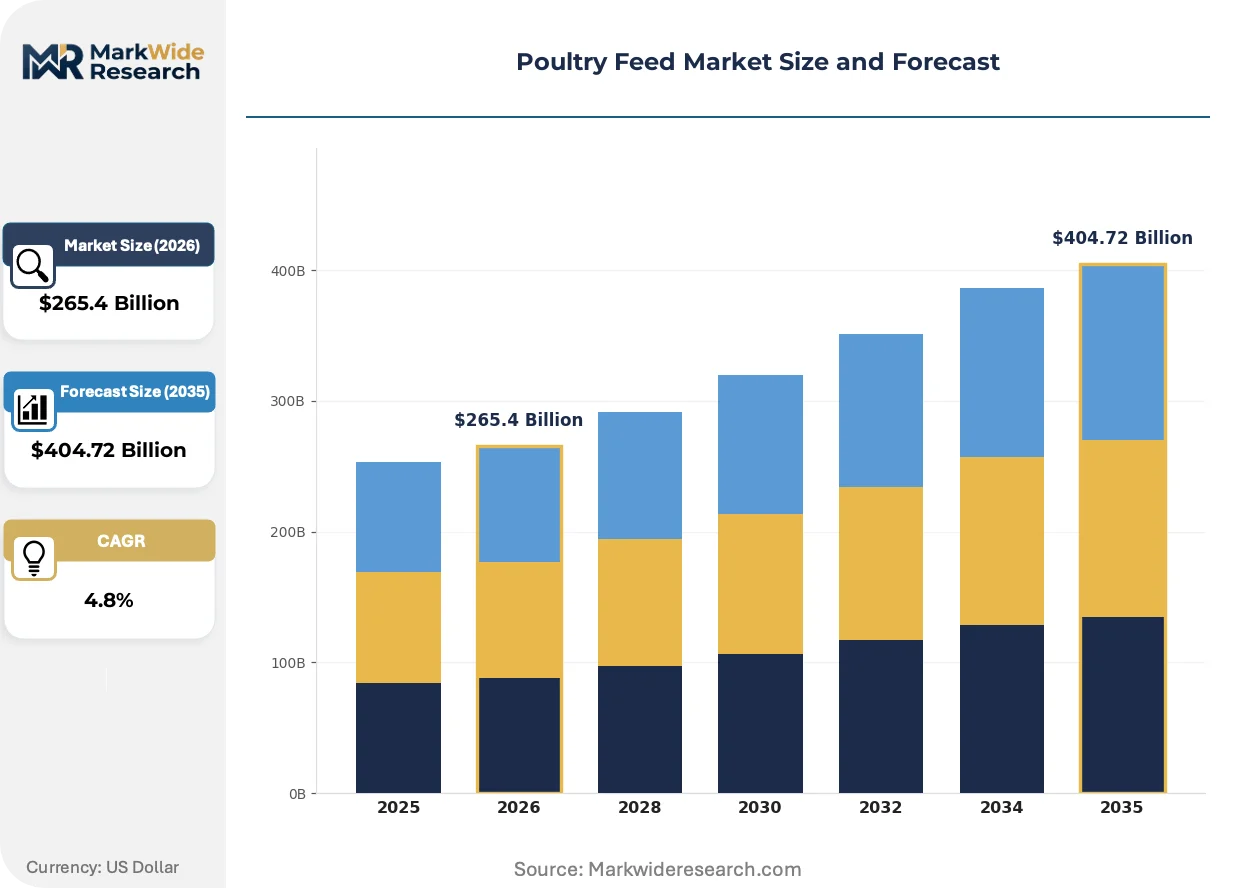
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $404.72 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starter Feed, Grower Feed, Layer Feed, Broiler Feed, Finisher Feed Ingredient Composition: Grains, Protein Meals, Vitamins & Minerals, Enzymes, Probiotics Application: Broiler Farming, Layer Farming, Hatcheries, Backyard Poultry, Contract Farming End User: Poultry Integrators, Independent Farmers, Feed Millers, Agribusiness Firms |
| Companies Covered | ForFarmers, Charoen Pokphand Foods, Cargill, Alltech, Trouw Nutrition, Archer Daniels Midland, Land O'Lakes, Kent Nutrition Group, De Heus Animal Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Feed Market Strategic Shifts & Innovations
Precision nutrition platforms and alternative protein streams are fragmenting the traditional commodity feed model, rewarding suppliers who can customize rations to flock genetics and real-time performance data.
Near-infrared spectroscopy coupled with cloud-based formulation engines enables real-time adjustment of nutrient density during pelleting operations. Large integrators in the Netherlands and Denmark deploy these systems to compress feed conversion ratio variance across contract grower networks. Manual sampling and laboratory analysis is rendering obsolete as millers shift to continuous in-line monitoring.
REACH authorization requirements for novel feed additives now mandate full toxicological dossiers including reproductive and carcinogenicity endpoints. European suppliers face 2-3 year registration timelines that advantage incumbents with established substance portfolios. Layer feed manufacturers absorb the heaviest compliance burden as calcium speciation and shell quality claims require extensive safety documentation.
Buyer consolidation among protein processors shifts procurement toward long-term supply agreements with indexed pricing clauses. Third-party feed millers in Poland and Spain lose volume to integrator-owned facilities that internalize margin capture. This channel compression is most visible in broiler operations where JBS and Cargill Protein dominate processing capacity and backward-integrate into nutrition supply.
Poultry Feed Market Segmentation
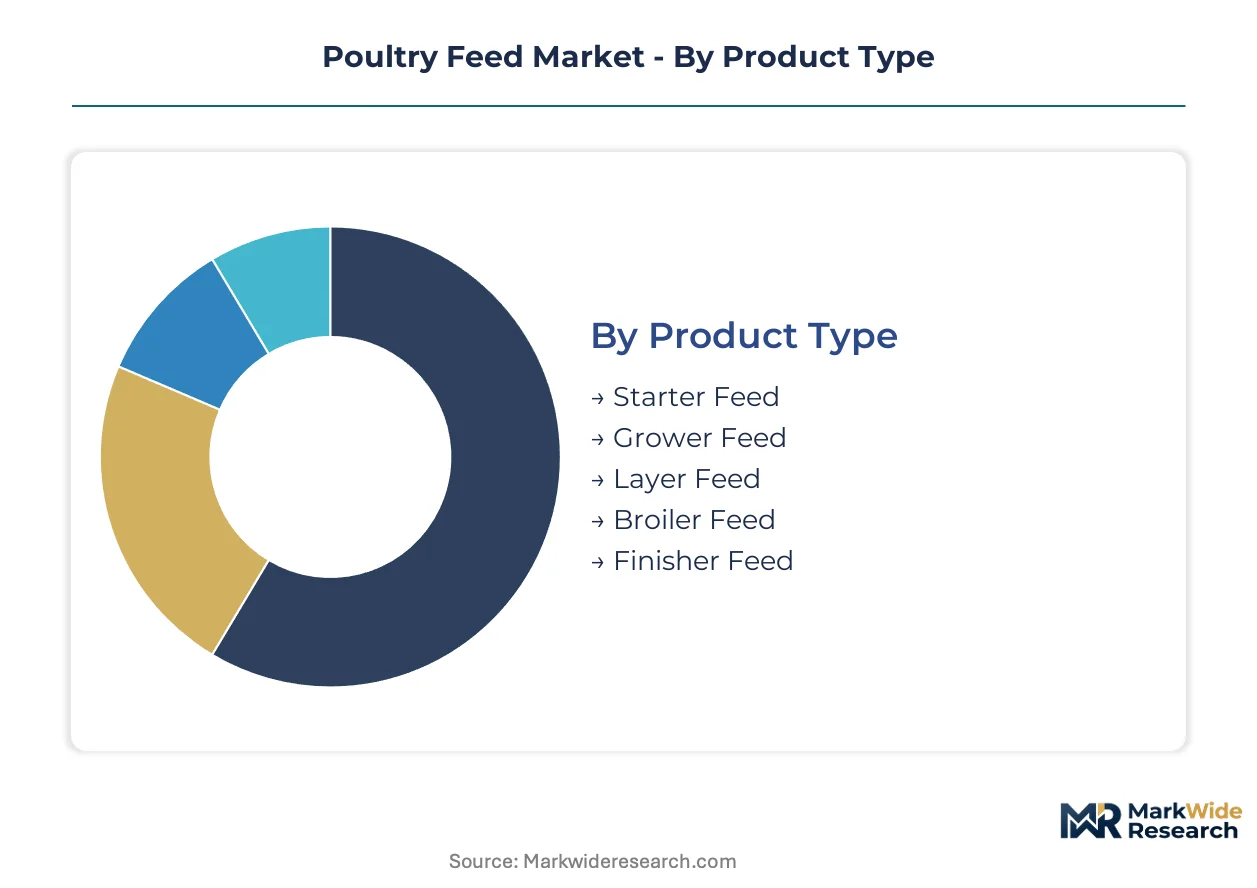
Poultry feed segmentation tracks distinct nutritional specifications across production stages, with cycle times varying from rapid-turn broiler rations to multi-year layer formulations. Understanding these velocity differences enables suppliers to align inventory, R&D, and margin capture strategies with biological production timelines rather than commodity cycles alone.
Product Type:
Broiler rations turn over in 35-42 day cycles, while layer feeds sustain 60-80 week production runs, creating fundamentally different replenishment economics and formulation stability requirements across the portfolio.
- Starter Feed:High-protein formulations (20-24% crude protein) with precise amino acid profiles support early skeletal development and immune system priming. Demand concentrates among hatchery-to-processing integrators in Brazil and Thailand who standardize day-old chick nutrition protocols to compress mortality variance.
- Broiler Feed:Energy-dense rations optimized for feed conversion ratio performance dominate procurement volumes across vertically integrated operations. JBS and Charoen Pokphand Foods specify customized pellet durability and nutrient density parameters to align with genetic strain performance curves.
- Grower Feed:Transitional formulations bridge starter and finisher phases with moderated protein levels.
- Layer Feed:Calcium-specified rations (3.5-4.5% Ca) with phase-adjusted nutrient profiles support extended production cycles.
- Finisher Feed:Withdrawal-period formulations with restricted medication residues prepare birds for processing compliance.
Broiler Feed anchors the volume base while Starter Feed gains share at the steepest rate as early-phase nutrition science advances.
Ingredient Composition:
Cost tiering separates commodity bulk ingredients from functional additives, with margin capture concentrating in specialized categories that command technical specification premiums.
- Enzymes:Phytase and xylanase additives reduce phosphorus discharge liabilities while improving digestibility coefficients. EU REACH registration requirements stretch 18-36 months, freezing innovation pipelines for European suppliers while incumbents with established portfolios sustain margin capture.
- Protein Meals:Soybean meal and alternative oilseed meals constitute the dominant cost input, with Argentine export taxes and Brazilian logistics bottlenecks transmitting price volatility directly into formulation economics.
- Grains:Corn and wheat provide basal energy density across all ration types.
- Vitamins & Minerals:Premix specifications vary by production stage and regulatory jurisdiction.
- Probiotics:Direct-fed microbials face divergent approval pathways between FDA veterinary feed directives and EU feed hygiene regulations.
Protein Meals constitute the cost foundation while Enzymes climb the fastest as phosphorus reduction mandates tighten across member states.
Application:
Customer concentration varies dramatically, with contract farming operations demanding standardized protocols while backyard poultry sustains fragmented, price-sensitive demand.
- Broiler Farming:Integrator-controlled operations specify feed conversion ratio targets and pathogen reduction parameters. Near-infrared spectroscopy coupled with cloud-based formulation engines enables real-time nutrient adjustment across Dutch and Danish contract grower networks.
- Contract Farming:Processor-backed production expansion in Andhra Pradesh and Tamil Nadu creates demand for standardized phase-feeding protocols and technical support services.
- Layer Farming:Mature margin pools where calcium specification and shell quality parameters differentiate supplier relationships.
- Hatcheries:Pre-starter nutrition and day-old chick quality protocols require specialized formulation expertise.
- Backyard Poultry:Small-scale operations sustain residual demand for generic compound feeds.
Broiler Farming commands procurement volume leadership while Contract Farming expands most quickly as processor consolidation penetrates developing production belts.
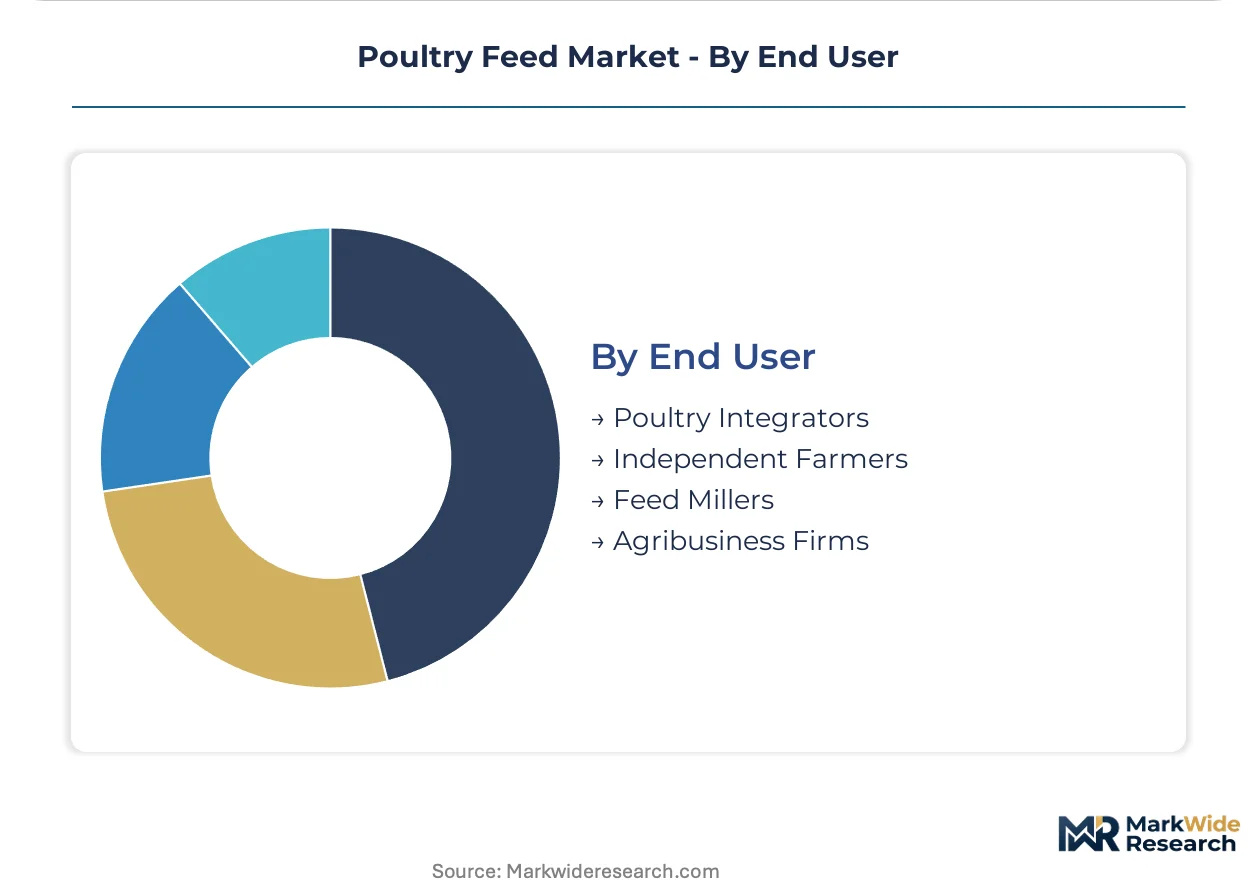
End User:
Backward integration trends are compressing third-party supplier access, with asset-heavy mill construction favoring incumbents with balance sheet capacity.
- Poultry Integrators:Captive milling operations internalize margin capture across hatchery-to-processing value chains. JBS and Cargill Protein dominate processing capacity and backward-integrate into nutrition supply, rewriting competitive entry barriers.
- Feed Millers:Third-party operators in Poland and Spain lose volume to integrator-owned facilities. Contract-based financing for infrastructure is rewriting competitive positioning across developing poultry belts.
- Independent Farmers:Price-taker procurement with limited formulation customization access.
- Agribusiness Firms:Diversified operations with cross-species feed manufacturing capabilities.
Poultry Integrators anchor the volume base while Feed Millers face the steepest share compression as captive milling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented milling standards diverge sharply across destination markets, with regulatory compliance costs reshaping cross-border shipment eligibility for major producing nations. Trade flows concentrate in corridors linking feed grain surplus regions to poultry processing clusters.
Brazil
Vertically integrated processors expand captive milling capacity across São Paulo and Paraná states. ANVISA enforces mycotoxin thresholds that exceed US FDA baselines, compelling reformulation investments for export-oriented suppliers. The Sorocaba cluster anchors South American supply as JBS backward-integrates into nutrition manufacturing.
United States
Corn belt proximity sustains formulation cost advantages for domestic broiler operations. FDA veterinary feed directive protocols mandate veterinary oversight for medicated rations, extending compliance timelines for novel additive introductions. Georgia and Arkansas processing corridors concentrate demand for standardized grower and finisher protocols.
Netherlands
Dense layer farming operations in Gelderland and Overijssel provinces sustain premium formulation demand. EU REACH chemical registration stretches 18-36 months for novel feed additives, freezing innovation pipelines while incumbents with established portfolios sustain margin capture. Near-infrared spectroscopy adoption accelerates across Dutch contract grower networks.
India
Contract farming expansion in Andhra Pradesh and Tamil Nadu creates demand for standardized phase-feeding protocols. FSSAI feed safety regulations diverge from export destination requirements, straining multi-jurisdiction certification capacity for suppliers serving both domestic and Gulf markets. Hyderabad and Chennai clusters concentrate technical service deployment.
Thailand
Integrator-controlled broiler operations span hatchery-to-processing value chains across the Central Plains. Charoen Pokphand Foods anchors Southeast Asian supply through backward integration into captive milling. Thai FDA alignment with EU residue protocols shapes export eligibility for European supermarket supply chains.
Poultry Feed Market Key Industry Players
On the supply side, the industry is consolidating around integrator-owned milling capacity and specialized nutrition formulators. Third-party feed millers face volume compression as captive operations internalize margin capture. Two strategic archetypes dominate: grain-trading conglomerates with nutrition divisions and regionally focused compound feed specialists. M&A activity concentrates on regional feed mill acquisitions, while R&D investment flows toward enzyme-supplemented formulations and precision nutrition platforms.
Among European compound feed specialists, ForFarmers leverages network density to sustain layer feed margin capture. Charoen Pokphand Foods exemplifies integrator-driven supply chain control across Southeast Asian operations. Cargill occupies a position anchored in global grain origination strength, positioning its nutrition division to navigate volatile commodity cycles.
| Leading Market Players |
|---|
| ForFarmers |
| Charoen Pokphand Foods |
| Cargill |
| Alltech |
| Trouw Nutrition |
| Archer Daniels Midland |
| Land O'Lakes |
| Kent Nutrition Group |
| De Heus Animal Nutrition |
| Others |
Cost & Logistics Intelligence
Soybean meal price volatility transmits directly into formulation economics, compressing margin spreads between premium enzyme-supplemented rations and commodity bulk blends while forcing millers toward geographic sourcing diversification and captive grain origination investments.
Pricing Analysis
Poultry integrators anchor contract-based procurement with indexed pricing clauses tied to Chicago Board of Trade grain futures. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-supplemented formulations with REACH registration from generic compound feeds and residual spot-market volumes. Cost compression in standard-tier broiler rations is intensifying because Argentine export taxes and Brazilian logistics bottlenecks transmit input spikes directly into formulation economics. Independent farmers in Poland and Spain exhibit highest price sensitivity, while JBS and Charoen Pokphand Foods capture cost advantages through backward integration into captive milling.
Supply Chain Analysis
Upstream feedstock sourcing draws from corn surplus regions in the United States, Brazil, and Ukraine, with soybean meal dependencies centering on Argentine crushing capacity and Brazilian port logistics. Wheat, corn, and oilseed meals constitute the dominant raw material inputs, with phytase and xylanase enzymes sourced from specialized fermentation facilities in Denmark and the Netherlands. Tariff exposure on trans-Atlantic grain flows strains cross-border formulation economics for European compound feed specialists. Distribution runs through integrator-owned silo networks and third-party mill direct-delivery contracts, with channel compression favoring asset-heavy players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in amino acid balancing and mycotoxin binder selection concentrates among aging technical workforces in Europe and North America, creating a capability gap that rewards targeted recruitment and automated formulation platform investments.
For Market Incumbents: Pre-empt enzyme-supplemented formulation share erosion by accelerating EFSA safety dossier preparation for novel additives before REACH registration timelines freeze competitor pipelines. Anchor layer feed margin capture through calcium speciation technical services that deepen customer switching costs against regional compound feed specialists. For New Entrants and Emerging Players: Pursue contract farming penetration in Andhra Pradesh and Tamil Nadu where standardized phase-feeding protocols create demand for technical support bundles beyond commodity feed supply. Target digital feed formulation platform deployment as a service-based entry wedge, enabling real-time nutrient optimization without asset-heavy mill construction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrator-owned milling capacity over third-party compound feed specialists. Long-term viability hinges on backward integration depth and REACH-registered additive portfolios. Monitor EFSA safety clearance timelines for insect meal poultry applications as the inflection signal for alternative protein platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | JBS and Cargill internalize margin capture across Sorocaba and Arkansas processing corridors. |
| Enzyme-Supplemented Formulation Registration | REACH dossier preparation stretches 18-36 months, freezing innovation pipelines for European suppliers. |
| Digital Feed Formulation Platform Deployment | Near-infrared spectroscopy adoption accelerates across Dutch and Danish contract grower networks. |
| Contract Farming Technical Service Expansion | Andhra Pradesh and Tamil Nadu processor consolidation creates demand for phase-feeding protocols. |
| Insect Meal Regulatory Pathway Navigation | Black soldier larva protein awaits EFSA safety clearance for poultry applications beyond aquafeed. |
Research Approach
Operator-level perspectives from feed mill plant managers, poultry integrator procurement leads, veterinary nutritionists, and distribution channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from EU feed hygiene regulation filings, ANVISA mycotoxin threshold documentation, USDA grain supply reports, and customs trade flow data. Bottom-up volume modeling across ingredient composition segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around commodity price volatility and regulatory divergence shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient composition tier, application stage, and end-user integration level. CAGRs derived from historical trajectory analysis adjusted for captive milling expansion rates and enzyme adoption curves. Feed conversion ratio performance benchmarks and layer cycle length assumptions informed biological production timeline alignment.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by protein processors would shift outcomes beyond modeled parameters. Cross-checking against Chicago Board of Trade grain futures curves and EFSA novel food approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Europe Swine Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Bird Feeder Market
Livestock Management
Wild Birds Products Market
Livestock Management
Swine Feed Market
Livestock Management
North America Swine Feed Market
Livestock Management
Feed Management Software Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Cattle Management Software Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
South America Ruminant Feed Premix Market