
 North America Swine Feed Market | 2026-2036
North America Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Swine Feed Market Analytics
AAFCO feed ingredient approval cycles is reorganizing competitive access across the North America swine feed landscape, elevating formulation costs for challengers while cementing incumbent advantages. Cargill, Incorporated leverages its vertically integrated grain origination network to captive-supply major Midwestern integrators with customized premix programs. ADM Animal Nutrition anchors its position through fermentative amino acid production that displaces soybean meal inclusion rates in grower-finisher diets. Alltech, Inc. differentiates via yeast cell wall technologies that sustain gut integrity under antibiotic-free production protocols demanded by pork packers.
North America swine feed encompasses complete diets, supplements, and premixes formulated to meet the nutritional requirements of pigs across gestation, nursery, grower, and finisher phases, typically specified by crude protein minimums, standardized ileal digestible lysine ratios, and metabolizable energy densities ranging from 3,200 to 3,400 kcal per kilogram. Its primary commercial purpose centers on optimizing feed conversion efficiency and carcass lean yield while controlling mortality and veterinary intervention costs in confinement production systems. Pellet form commands preference among large commercial farms for reduced feed wastage and improved nutrient density uniformity, while probiotic feed additives represent the fastest-expanding margin pool as antibiotic growth promoter restrictions harden across U.S. packer specifications and Canadian Pork Excellence program requirements. Mash formulations retain cost-driven adoption among private farms and smaller cooperative associations where on-farm grinding infrastructure defrays processing premiums.
The FDA's Veterinary Feed Directive governs medically important antimicrobial usage in swine feed, compelling veterinarians to authorize prescriptions and reshaping how nutritionists formulate for growth promotion versus disease prevention. EPA nutrient management regulations under the Clean Water Act, alongside CFIA feed safety oversight in Canada, constrain formulation flexibility around phosphorus and nitrogen excretion rates. Stakeholders must monitor evolving state-level ballot initiatives on animal housing density, as these threaten to fragment production geography and redirect feed demand toward jurisdictions with less restrictive confinement standards.
Market Dynamics
Integrator contract consolidation across the Midwest is compressing feed procurement autonomy, forcing independent nutritionists to cede formulation control to packer-mandated specifications that prioritize lean yield metrics over cost minimization.
Growth Catalysts
- EPA Clean Water Act enforcement:Nutrient management pressure is accelerating precision feeding adoption, creating pull for low-excretion amino acid formulations across Iowa and Minnesota commercial operations.
- Antibiotic-free packer mandates:Major pork processors are hardening specifications, expanding addressable demand for gut health additives and fermented protein alternatives in grower-finisher diets.
- Midwest sow herd expansion:Dense packing plant proximity in Iowa and Illinois is concentrating feed volume requirements, rewarding suppliers with captive grain origination capabilities.
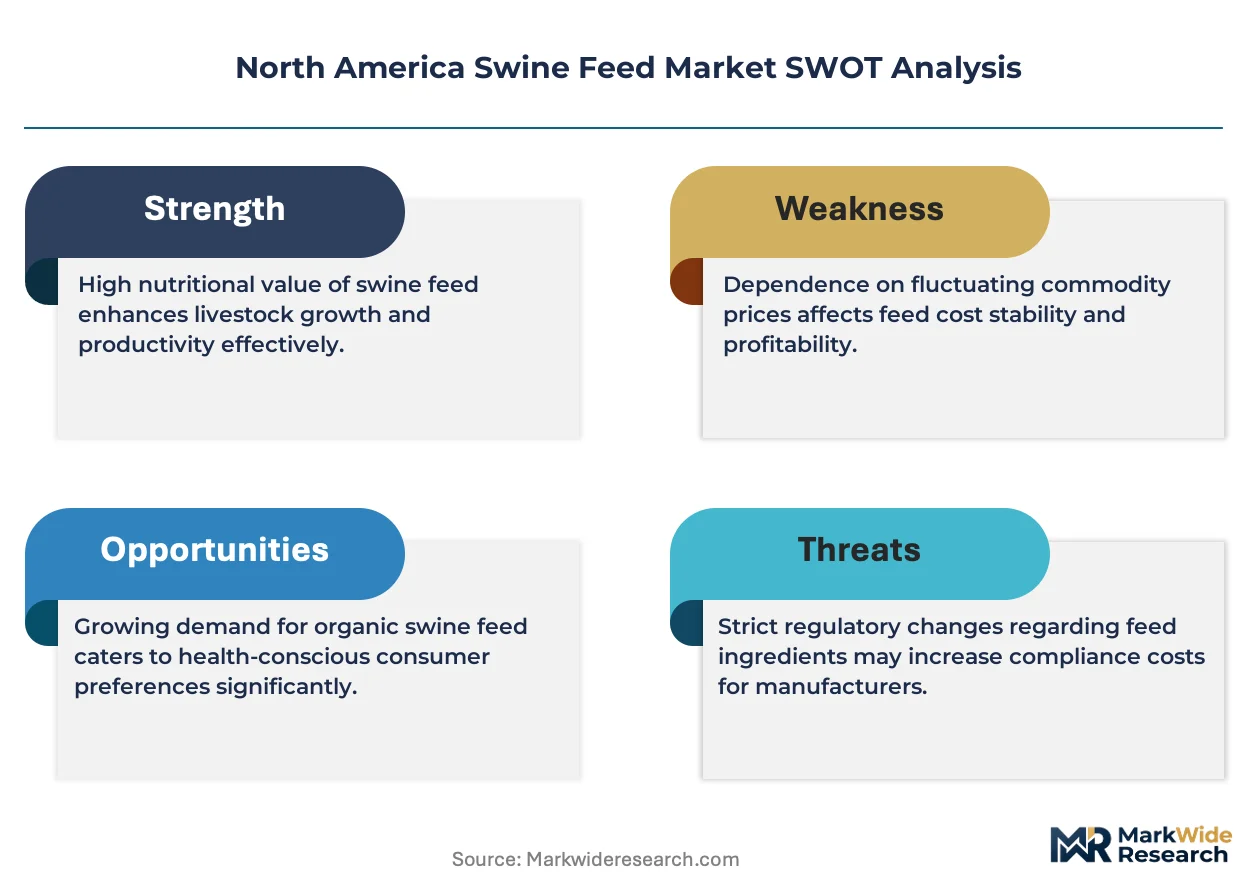
Market Restraints
- AAFCO approval cycles:Novel feed ingredient commercialization faces 18-24 month regulatory lag, elevating formulation costs for challengers without incumbent premix infrastructure.
- Phosphate input volatility:Dicalcium phosphate and phytase enzyme costs fluctuate with global mineral concentrate markets, compressing margin predictability for standard diet producers.
- Integrator purchasing concentration:Three major packers control 70% of U.S. slaughter capacity, consolidating feed procurement leverage and squeezing regional cooperative suppliers.
Strategic Opportunities
- Canadian antibiotic-free expansion:Pork Excellence program requirements are creating unmet demand for yeast cell wall technologies and organic acid blends in Ontario and Quebec finishing barns.
- Precision fermentation amino acids:Microbial lysine and methionine production is converging with enzymatic soybean processing, enabling complete meal displacement in high-performance diets.
- Direct-to-farm digital channels:E-commerce platforms are bypassing traditional distributor markups, opening margin capture for specialty additive suppliers serving mid-sized independent farms.
Industry Challenges
- Swine nutritionist talent scarcity:Veterinary Feed Directive complexity and precision formulation requirements have outpaced university training pipeline output, inflating compensation for credentialed professionals.
- On-farm mixing infrastructure:Mash diet producers face capital intensity for pelleting equipment upgrades needed to meet integrator feed physical quality specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Swine Feed Market |
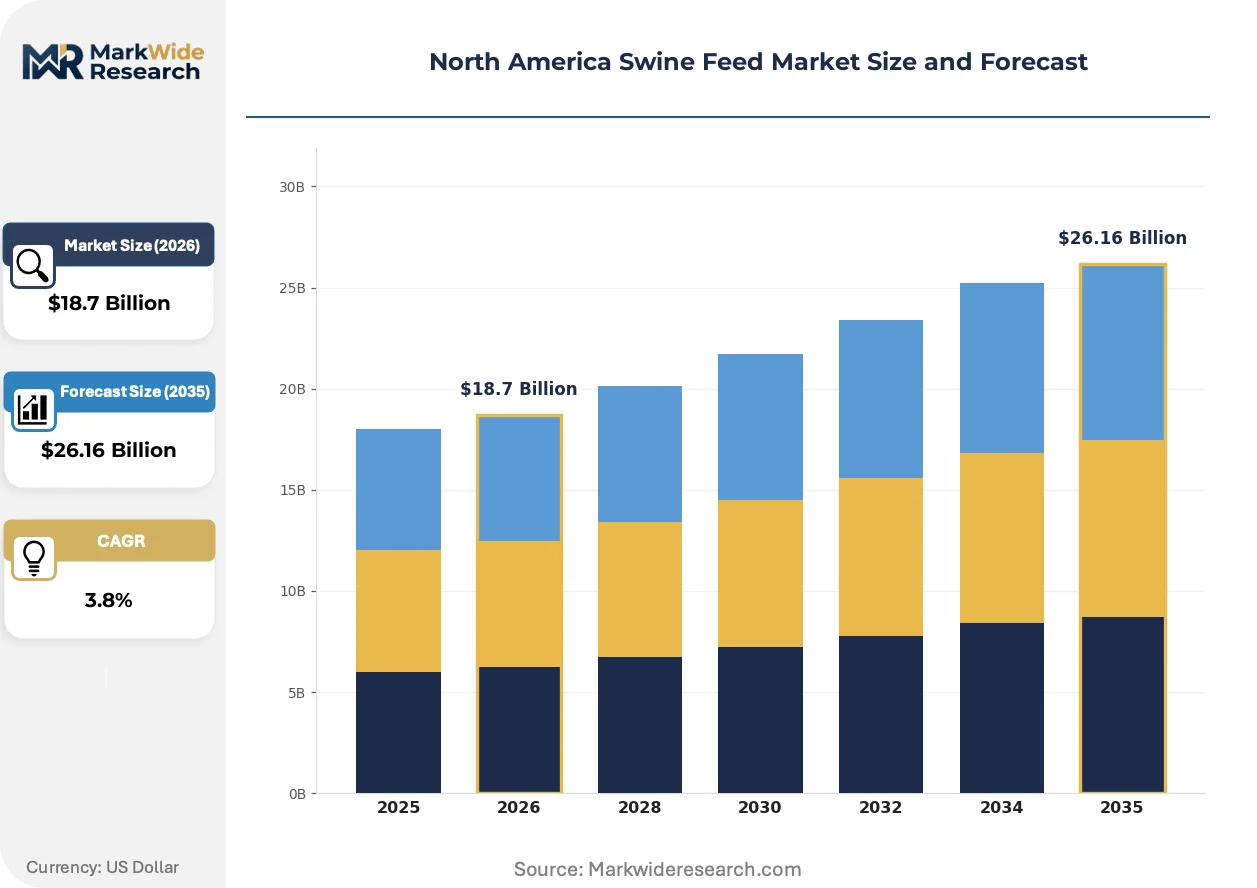
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Mash, Crumbles, Liquid Feed Additive: Vitamins, Minerals, Antioxidants, Probiotics End User: Commercial Farms, Cooperative Associations, Private Farms, Research Institutions Distribution Channel: Online Retail, Direct Sales, Feed Stores, Agriculture Cooperatives |
| Companies Covered | Cargill, Incorporated, Land O’Lakes, Inc., ADM Animal Nutrition, Lallemand Inc., Kent Nutrition Group, Alltech, Inc., Novus International, Inc., BASF SE, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Swine Feed Market Evolving Landscape
Digital feeding systems and microbiome-targeted additives are displacing conventional growth promotion approaches, reconfiguring how nutritionists balance performance, compliance, and cost in confinement production.
Precision liquid feeding technology is fragmenting traditional dry feed delivery models. Large commercial farms in Iowa and Minnesota are retrofitting nurseries with computer-controlled dispensing systems that blend water, acidifiers, and micro-ingredients at the pen level. This shift is fragmenting premix supplier relationships, as farms bypass bulk dry inclusion in favor of tank-farm additive partnerships with specialized liquid nutrition firms.
The FDA's Veterinary Feed Directive has eliminated over-the-counter antimicrobial growth promotion, compelling veterinarians to document medical necessity for feed-grade antibiotics. This regulatory compression has forced nutritionists to reformulate grower diets around non-antibiotic alternatives, with the heaviest burden falling on mid-sized independent farms lacking in-house veterinary staff to manage prescription workflows.
Packer-driven certification requirements are reshaping procurement priorities. Major processors now mandate third-party verification for antibiotic-free claims, redirecting feed purchasing toward suppliers with transparent ingredient traceability systems. This behavioral shift is most visible in the Corn Belt, where integrator-aligned farms are consolidating purchasing through approved vendor lists that exclude non-certified regional blenders.
North America Swine Feed Market Segmentation
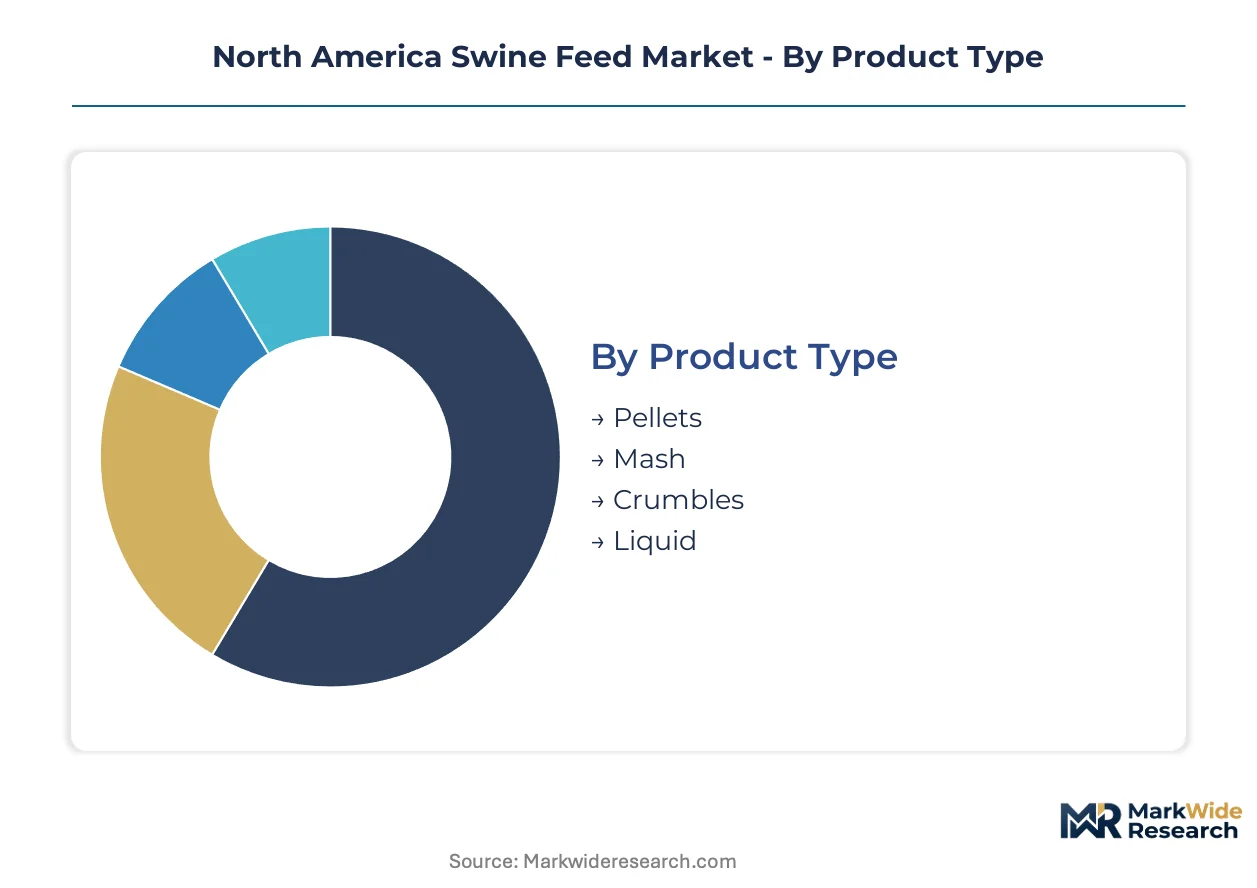
Feed form and delivery specifications vary sharply across the North American swine sector, with integrator contracts dictating physical quality standards that independent operations cannot ignore. Additive portfolios and channel access further stratify procurement power between large commercial systems and smaller cooperative members.
Product Type:
Pellet and liquid formulations dominate export-oriented operations and dense Midwestern production clusters, while mash retains strongholds in cost-driven domestic private farm networks across the Corn Belt.
- Pellets:Compressed feed forms reduce wastage and improve nutrient density uniformity. Demand concentrates most heavily in Iowa and Illinois commercial operations where integrator contracts mandate physical feed quality specifications for automated delivery systems.
- Mash:Ground grain mixes allow on-farm flexibility and lower processing premiums. Private farms and smaller cooperative associations across Minnesota and Indiana leverage existing grinding infrastructure to defray capital costs.
- Crumbles:Intermediate particle size suits nursery phase transitions. Ontario and Quebec finishing barns under Canadian Pork Excellence protocols show rising specification rates.
- Liquid:Precision-blended slurries enable acidifier and enzyme integration at the pen level. Large Minnesota and Iowa nurseries retrofitting with computer-controlled dispensing systems drive adoption.
Pellets command the established base. The steepest expansion runs through liquid feeding systems.
Feed Additive:
Cost tier stratification separates commodity micronutrient inclusion from premium functional additives that command veterinary oversight and packer certification requirements.
- Vitamins:Standardized premixes of fat-soluble and water-soluble compounds meet baseline nutritional requirements. Volume demand anchors in Midwestern commercial farms with integrator-aligned specification sheets.
- Minerals:Trace element and macro-mineral supplementation addresses regional soil deficiency profiles. Phosphate input volatility from global concentrate markets compresses margin predictability for standard diet producers.
- Antioxidants:Synthetic and natural compounds preserve lipid stability in high-fat grower-finisher diets. Export-focused operations near West Coast ports prioritize extended shelf-life formulations.
- Probiotics:Live microbial cultures and fermentation products sustain gut integrity under antibiotic-free protocols. The heaviest pull originates from packer-mandated certification programs across the Corn Belt and Ontario finishing systems.
Vitamins and minerals anchor volume throughput. Probiotics gain share fastest under regulatory compression.
End User:
Customer scale directly determines formulation autonomy, with procurement concentration shifting from independent nutritionist control toward packer-mandated specification compliance.
- Commercial Farms:Large confinement operations with standardized genetics and veterinary staff. Iowa and Illinois integrator-aligned systems drive premix volume and precision amino acid formulation demand.
- Cooperative Associations:Member-owned purchasing pools aggregate smaller farm volumes. Regional blenders in Minnesota and Indiana serve these networks with customized mash programs.
- Private Farms:Independently owned operations retaining nutritionist relationships. The Veterinary Feed Directive burden falls heaviest here due to prescription workflow complexity without in-house veterinary staff.
- Research Institutions:University and industry trial facilities testing novel ingredient efficacy. AAFCO approval cycle data generation supports regulatory submission pathways.
Commercial farms concentrate purchasing leverage. Cooperative associations show the steepest technology adoption curve as digitization penetrates member services.
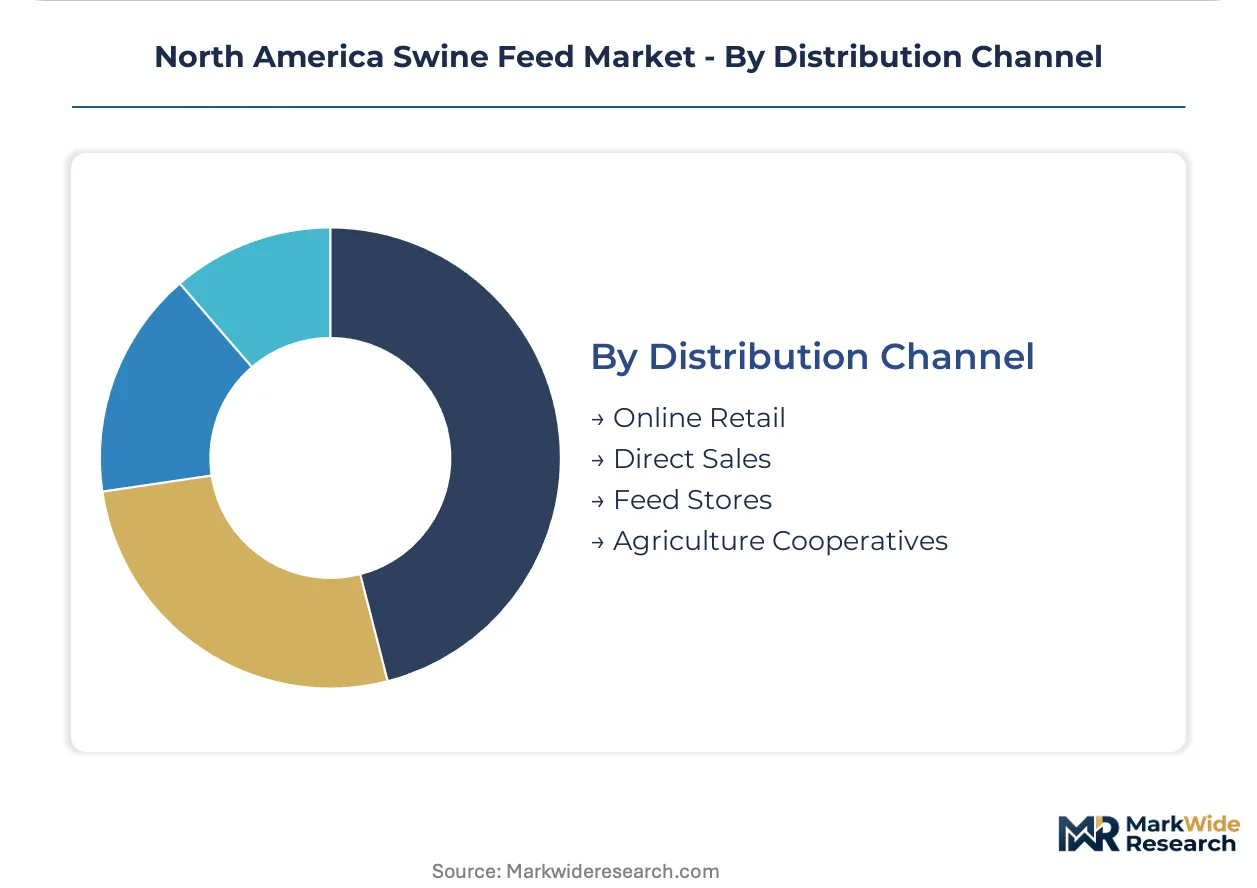
Distribution Channel:
Channel selection reflects farm scale and specification complexity, with direct relationships displacing traditional distributor markups in mid-tier independent operations.
- Online Retail:E-commerce platforms bypassing traditional markups for specialty additives. Mid-sized independent farms in secondary production counties access direct manufacturer pricing.
- Direct Sales:Manufacturer-to-farm relationships for customized premix programs. Major Midwestern integrators lock in captive supply through multi-year amino acid and grain origination contracts.
- Feed Stores:Local retail points serving private farms with bagged supplements and small-batch orders. Rural counties across Missouri and Ohio maintain this infrastructure.
- Agriculture Cooperatives:Member-owned distribution handling bulk delivery and credit terms. Regional systems in Wisconsin and Michigan blend local grain with purchased concentrates.
Direct sales anchor high-volume commercial supply. Online retail climbs fastest as digital procurement penetrates mid-scale independent operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrator contract structures and packer-mandated specifications are reconfiguring procurement geography across North America. The EPA's Clean Water Act enforcement and the FDA's Veterinary Feed Directive are concentrating feed demand in jurisdictions with compliant infrastructure and veterinary capacity.
United States
Iowa and Illinois anchor commercial feed volume through dense packing plant proximity and sow herd expansion. The EPA's nutrient management regulations under the Clean Water Act pressure producers toward precision amino acid formulations that reduce phosphorus excretion. Minnesota's nursery retrofitting with liquid feeding systems is fragmenting traditional premix supplier relationships toward tank-farm additive partnerships.
Canada
Ontario and Quebec finishing barns are expanding antibiotic-free production under Canadian Pork Excellence program requirements. CFIA feed safety oversight constrains formulation flexibility around microbial standards and traceability documentation. The Prairie Provinces maintain cooperative grain handling infrastructure that supports regional mash blending for domestic private farm networks.
Mexico
Jalisco and the Bajío Region concentrate commercial swine operations serving domestic protein demand and U.S. export channels. Mexico's national agricultural health authority enforces feed safety protocols aligned with international trade access requirements. Nuevo León's industrial corridor is attracting integrator-aligned feed milling investment from cross-border suppliers seeking tariff-advantaged origination.
North America Swine Feed Market Competitive Landscape
Player mix skews toward integrated grain-trading conglomerates with captive origination networks and specialized additive technology firms. Market structure concentrates around three major packers controlling slaughter capacity, compressing procurement autonomy for independent nutritionists. Dominant archetypes include vertically integrated grain processors, fermentation-based amino acid producers, and gut health biotechnology specialists. Competitive moves center on multi-year integrator contracts locking in grain supply and amino acid volumes, alongside digital platform development for direct-to-farm additive distribution.
Among U.S.-based integrated processors, Cargill, Incorporated and Land O'Lakes, Inc. occupy positions anchored by Midwestern grain origination infrastructure and cooperative member networks. ADM Animal Nutrition represents the fermentative production archetype, with capabilities in microbial amino acid manufacturing that displace conventional protein sources in grower-finisher formulations. These three entities exemplify how scale-driven grain control and biotechnology integration are consolidating formulation influence under packer-mandated specification regimes.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Land O'Lakes, Inc. |
| ADM Animal Nutrition |
| Lallemand Inc. |
| Kent Nutrition Group |
| Alltech, Inc. |
| Novus International, Inc. |
| BASF SE |
| Chr. Hansen Holding A/S |
| Others |
Value Network & Pricing Analysis
Multi-year integrator offtake contracts lock in grain origination access and amino acid volumes while compressing price visibility for independent nutritionists outside packer-aligned procurement networks. These arrangements tether feed pricing to indexed corn and soybean meal benchmarks, leaving regional blenders exposed to phosphate and phytase enzyme volatility without captive mineral sourcing.
Pricing Analysis
Certification level under Canadian Pork Excellence and U.S. packer verification programs creates the primary spread between premium additive suppliers and commodity premix blenders. Three-tier pricing structure across certified antibiotic-free, standard compliance, and unverified economy tiers reflects veterinary oversight costs and traceability system investments. Cost compression in standard diet tiers is intensifying because integrator purchasing concentration transfers margin pressure downstream. Private farms lacking in-house veterinary staff show highest price sensitivity due to Veterinary Feed Directive compliance burdens, while commercial integrator-aligned operations absorb premiums for guaranteed supply security.
Supply Chain Analysis
The United States and Canada anchor North American grain origination and amino acid fermentation capacity, with Mexico's Bajío Region emerging as cross-border milling investment destination. Supply draws from Midwestern corn belts, Prairie Province wheat handling infrastructure, and imported mineral concentrates for phosphate supplementation. Single-source vulnerability concentrates in microbial lysine and methionine production where fermentative capacity clusters among three major suppliers. Distribution runs through agriculture cooperatives and direct manufacturer relationships, with e-commerce platforms fragmenting traditional distributor markups for specialty additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swine nutritionist credential scarcity has outpaced university training pipeline output, creating acute formulation capability gaps that inflate compensation and cede control to packer-mandated specification regimes. This talent compression rewards players who can embed veterinary oversight directly into feed service models.
For Market Incumbents: Fortify captive grain origination networks through multi-year sow herd expansion contracts in Iowa and Illinois, locking out challengers without elevator infrastructure. Deepen backward integration into fermentative amino acid production to displace soybean meal inclusion and capture margin from precision nutrition demand. Defend against digital platform disintermediation by embedding liquid feeding system partnerships directly into nursery retrofit specifications. For New Entrants and Emerging Players: Mid-sized independent farm service gaps in prescription workflow management and Veterinary Feed Directive compliance create entry points outside integrator-dominated procurement channels. Target Ontario and Quebec antibiotic-free finishing barns where Canadian Pork Excellence requirements outpace local yeast cell wall technology supply. Pursue direct-to-farm digital channels with acidifier and enzyme micro-dosing subscriptions that bypass agriculture cooperative markups. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-based amino acid specialists with microbial production platforms and existing AAFCO approval pathways. Long-term viability hinges on consolidation of gut health biotechnology assets as antibiotic-free mandates harden across North American packer specifications. Watch liquid feeding system retrofit rates in Minnesota and Iowa nurseries as inflection indicator for tank-farm additive partnership demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial lysine production displaces soybean meal in grower-finisher diets across Midwestern integrator contracts. |
| Antibiotic-Free Certification Investment | Third-party verification systems unlock approved vendor list access under packer-mandated procurement regimes. |
| Liquid Feeding System Partnerships | Computer-controlled nursery retrofits fragment traditional premix relationships toward tank-farm additive supply. |
| Direct-to-Farm Digital Platform | E-commerce channels bypass agriculture cooperative markups for specialty probiotic and organic acid sales. |
| Grain Origination Backward Integration | Captive elevator networks lock in corn and wheat supply security for multi-year integrator offtake commitments. |
Research Methodology
The analysis maps complete diets, premixes, and feed additives across gestation through finisher phases, each validated through nutritionists at commercial integrators, veterinary feed directive compliance officers, cooperative procurement managers, and packer specification directors. Primary interview insights triangulate against secondary sources including FDA Veterinary Feed Directive guidance documents, EPA Clean Water Act nutrient management enforcement records, CFIA feed safety oversight filings, and USDA sow inventory reports. Bottom-up volume estimates from state-level production data reconcile with top-down market sizing through amino acid and grain consumption benchmarks.
Consistency checks validate projections against external benchmarks including integrator contract disclosure patterns, grain handling capacity utilization, and fermentation industry capacity announcements. The analytical framework segments by feed form, additive category, end-user scale, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of sow herd expansion rates, antibiotic-free certification adoption curves, and precision feeding technology penetration. Key inputs include EPA enforcement intensity indices and packer specification timeline accelerations.
Forecasts assume regulatory continuity in FDA Veterinary Feed Directive and EPA Clean Water Act regimes; material policy shifts would require re-modeling. Specific risks include state-level ballot initiatives on animal housing density that could fragment production geography and redirect feed demand. Recalibration cycles align with material shifts in packer certification requirements, AAFCO approval timelines, and integrator contract restructuring events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Layer Feed Market
Livestock Management
Swine Feed Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Herd Management Software Market
Livestock Management
Poultry Health Market
Livestock Management
Cattle Feeder Market
Livestock Management
Bird Feeder Market
Livestock Management
Roughage Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Cattle Management Software Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Smart Feeding Systems Market