
 North America Swine Feed Premix Market | 2026-2036
North America Swine Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
North America Swine Feed Premix Market Analytics
Modular premix bundling is repositioning how commercial farms and integrated operations configure their nutritional programs across North America. Cargill Inc leverages its captive grain origination network to anchor ingredient cost advantages in the Corn Belt. ADM Animal Nutrition sustains formulation leadership through extensive amino acid research infrastructure in the Midwest. Nutreco competes by specializing in precision nutrition protocols tailored to high-health sow herds.
Swine feed premix denotes a concentrated blend of vitamins, minerals, amino acids, and functional additives typically dosed at one to five percent of total ration weight, manufactured through multi-stage mixing and micro-ingredient dispersion systems to ensure homogeneous nutrient distribution. Its primary commercial purpose is to standardize dietary precision across large sow and grower-finisher populations while reducing on-farm mixing error and labor. Complete feed premixes dominate volume flows to commercial farms where operational scale justifies outsourced nutritional engineering, while delayed release formats command premium positioning among integrated operations managing extended production cycles. Synthetic additives represent the most technically contested ingredient source segment as antibiotic growth promoter phase-outs redirect R&D toward enzyme and acidifier alternatives.
The FDA Veterinary Feed Directive and CFIA's feed regulatory framework jointly constrain medicated premix availability while elevating documentation burdens for cross-border ingredient shipments between the United States and Canada. USDA organic certification standards and state-level nutrient management regulations in Iowa and North Carolina further differentiate permissible formulation paths by production system type. Stakeholders must monitor evolving amino acid price volatility and regulatory divergence between American and Canadian jurisdictions to sustain margin performance without premature capacity commitments.
Market Dynamics
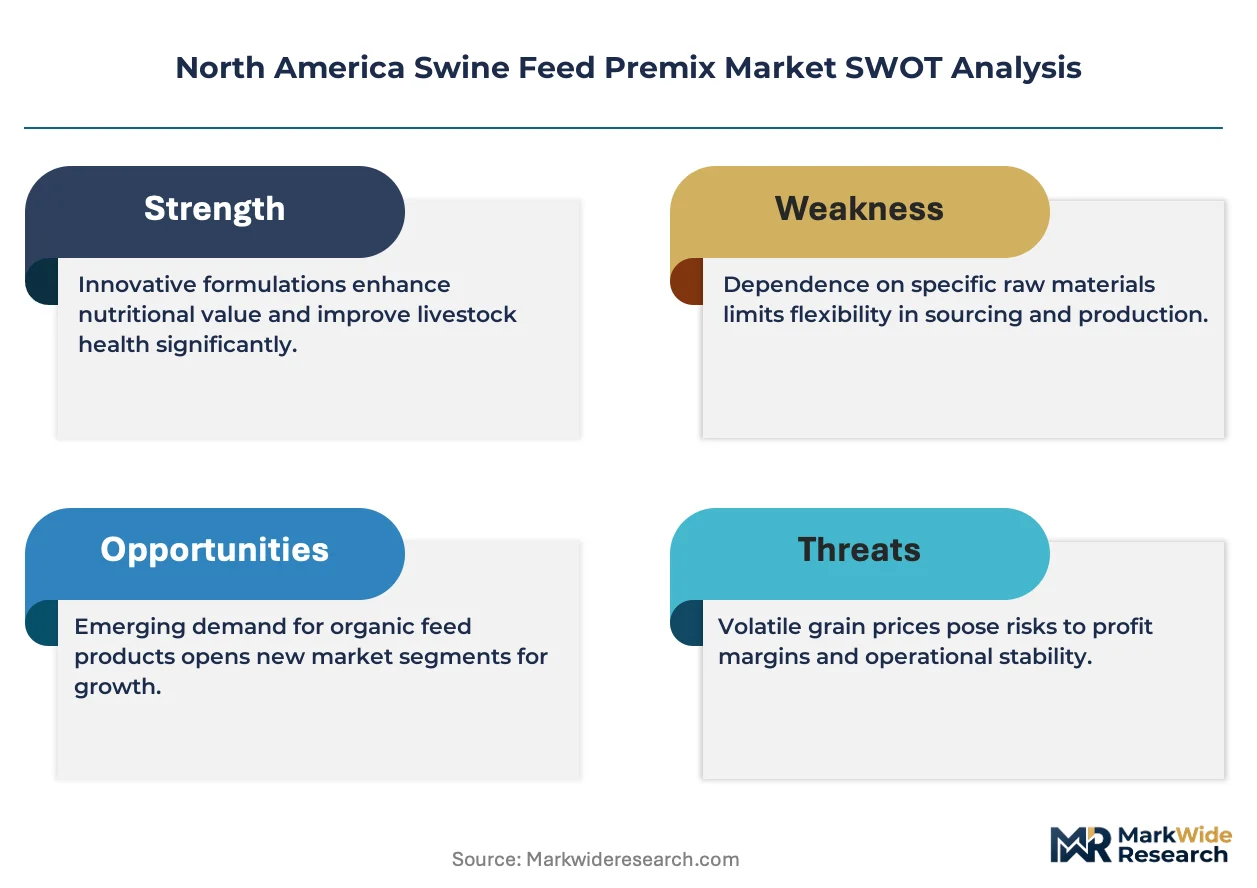
The FDA's Veterinary Feed Directive has permanently altered antibiotic premix availability, forcing reformulation investments while compressing margins for operations still transitioning to enzyme-based growth promotion alternatives across the United States and Canada.
Growth Catalysts
- Precision nutrition protocols:High-health sow herds in Iowa and North Carolina are adopting customized micronutrient matrices that optimize reproductive performance. Commercial farms contract nutrition engineers to design phase-specific premix bundles.
- FDA regulatory pressure:The Veterinary Feed Directive's documentation requirements for medicated feeds have accelerated investment in antibiotic-free alternatives. This creates pull-through demand for acidifier and probiotic premix categories.
- Corn Belt concentration:Iowa, Minnesota, and Illinois host the densest integrated pork production facilities in North America. Proximity to grain origination infrastructure reduces premix ingredient logistics costs.
Market Restraints
- Amino acid price volatility:Lysine and methionine input costs swing with fermentation capacity utilization in China and Southeast Asia. North American premix manufacturers lack upstream control over these critical inputs.
- Cross-border regulatory friction:CFIA and FDA maintain divergent approval timelines for novel feed additives. Shipment delays between United States and Canada operations complicate just-in-time premix delivery.
- Enzyme substitution ceiling:Exogenous phytase and carbohydrase performance plateaus in certain diet matrices limit complete antibiotic growth promoter replacement in grower-finisher phases.
Strategic Opportunities
- Canadian prairie expansion:Manitoba and Saskatchewan sow operations remain underpenetrated by precision nutrition services. Premix providers can establish formulation partnerships before facility consolidation accelerates.
- USDA organic certification pathway:The organic livestock feed standard creates premium positioning for mineral and vitamin premixes meeting restricted substance lists. Integrated operations in the Midwest are certifying sow herds to capture price premiums.
- Direct-to-farm digital channels:Large commercial farms in North Carolina are bypassing traditional distributor networks to order custom premix blends through manufacturer portals. This disintermediation captures margin previously allocated to feed dealers.
Industry Challenges
- Micro-ingredient dispersion expertise:Premix manufacturing requires specialized engineering talent for multi-stage mixing systems. The North American feed industry faces acute shortages of process engineers with homogeneity validation experience.
- Legacy facility retrofit costs:Older Midwest feed mills require capital-intensive upgrades to handle enzyme and probiotic premix lines with temperature and moisture controls. Financing these conversions strains mid-sized regional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Swine Feed Premix Market |
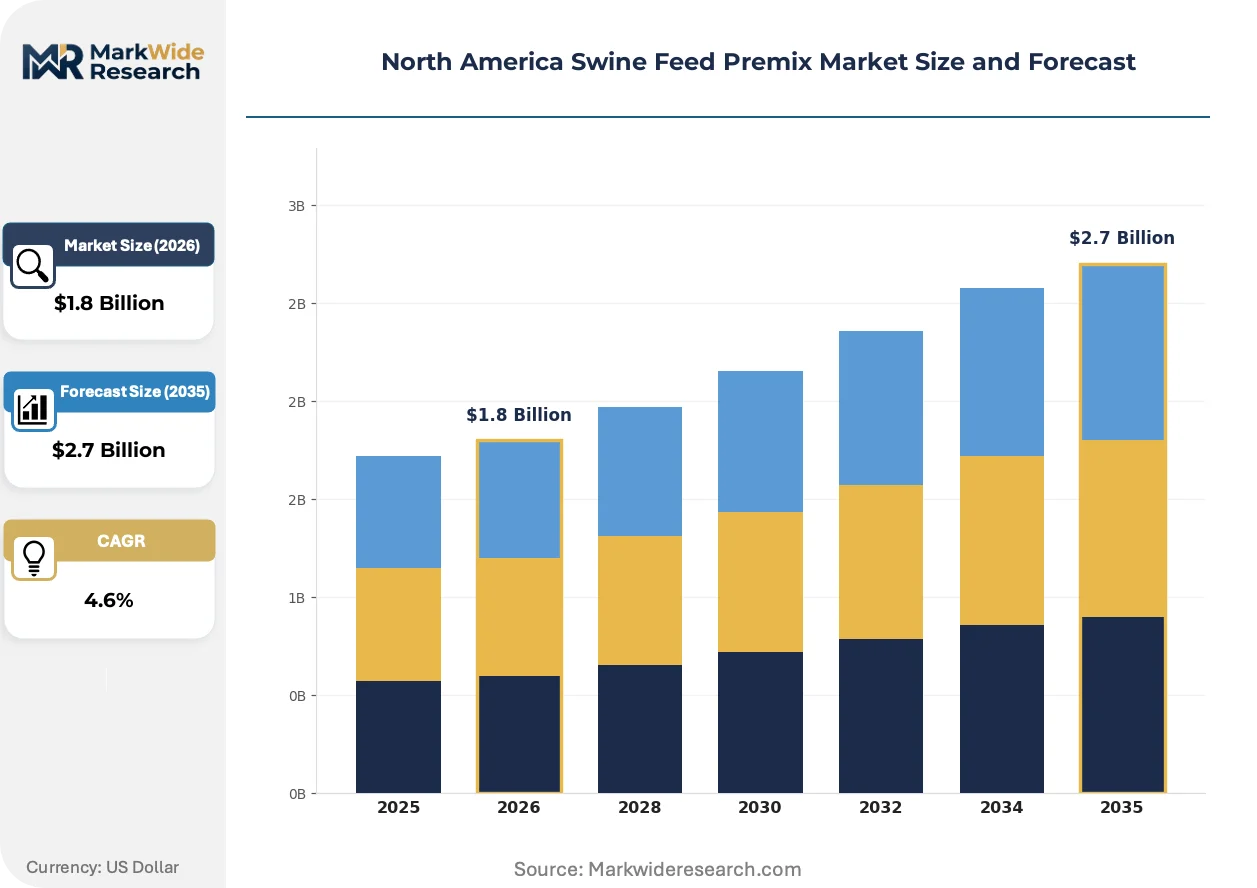
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplement, Base Mix, Delayed Release Ingredient Source: Animal By-Product, Plant-Based, Synthetic Additives, Organic End User: Commercial Farms, Backyard Producers, Research Institutions, Integrated Operations Distribution Channel: Direct Sales, Distributors, Retail Stores, Online Platforms |
| Companies Covered | Lallemand Animal Nutrition, ADM Animal Nutrition, Kent Nutrition Group, BASF SE, Nutreco, Elanco, Alltech Inc, Land O'Lakes, Cargill Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Swine Feed Premix Market Evolving Landscape
Real-time formulation software and on-farm mixing automation are compressing the traditional premix supply chain, enabling farms to adjust micronutrient dosing within production cycles rather than accepting static quarterly blends.
Near-infrared spectroscopy coupled with cloud-based ration optimization is decentralizing nutritional decision-making from centralized feed mill laboratories to individual sow barn managers. Large integrated operations in Iowa are deploying handheld NIR devices that analyze ingredient composition in receiving bays, enabling same-day premix adjustments. This capability is compressing the value capture of traditional formulation services into hardware and software subscriptions.
The FDA's phased enforcement of Veterinary Feed Directive record-keeping requirements is mandating electronic feed documentation systems for all medicated premix purchases. Commercial farms across the United States are implementing batch-tracking software that integrates with veterinary prescription platforms. Sow operations in North Carolina report compliance costs consuming operational resources previously allocated to nutrition staff.
Buyer concentration among the largest integrated pork producers is consolidating premix procurement into multi-year supply agreements with volume-tiered pricing. Independent commercial farms in the Midwest are responding by forming purchasing cooperatives to access equivalent scale economics. This cooperative model is most visible in Minnesota and Illinois, where mid-sized operations pool orders to qualify for customized premix formulation services previously reserved for top-tier accounts.
North America Swine Feed Premix Market Segmentation
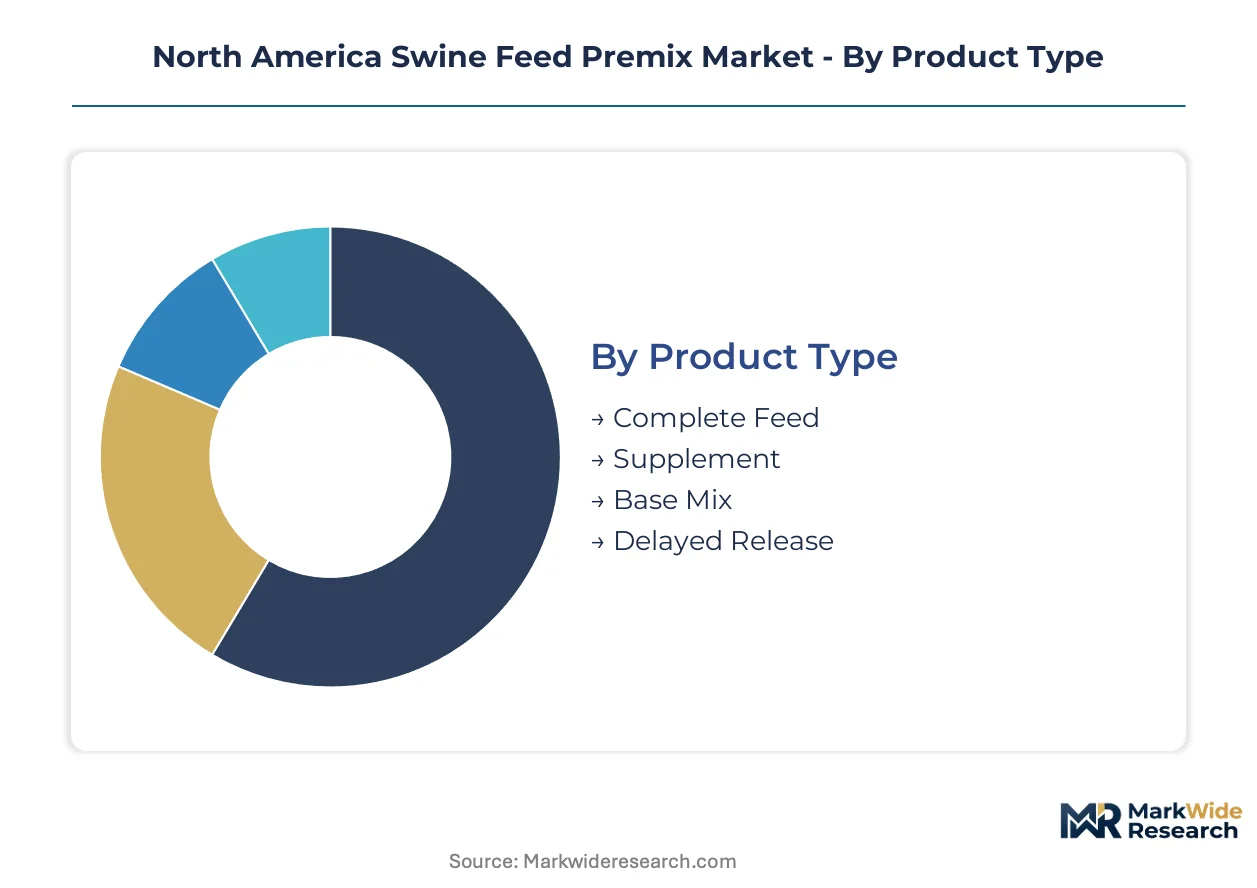
Swine feed premix segmentation in North America reflects divergent operational scales, regulatory pressures, and sourcing philosophies across the pork production value chain. Buyers select product formats and ingredient sources based on facility automation levels, veterinary oversight intensity, and margin sensitivity to input cost swings.
Product Type:
Commercial farms prioritize mixing efficiency and labor reduction when selecting among premix formats, with facility scale determining whether complete outsourcing or on-farm blending delivers superior economics.
- Complete Feed:Fully formulated rations requiring no on-farm supplementation dominate procurement at large integrated operations in Iowa and North Carolina. Sow barn managers value guaranteed nutrient homogeneity and reduced mixing labor. Volume sits with Complete Feed; growth tilts toward Delayed Release.
- Supplement:Concentrated micronutrient packs designed for blending with base grains appeal to mid-sized commercial farms seeking formulation flexibility without full premix engineering investment. Minnesota purchasing cooperatives favor supplements for their ability to adjust amino acid matrices seasonally.
- Base Mix:Mineral-vitamin carriers requiring protein and energy ingredient addition serve smaller commercial farms with limited nutrition staff. These buyers trade formulation precision for per-ton cost reduction.
- Delayed Release:Encapsulated nutrient technologies protect heat-sensitive additives through pelleting and extended storage. High-health sow herds in the Southeast adopt these formats to stabilize reproductive performance across variable climatic conditions.
Format selection tracks facility capital intensity; automated mills favor complete feeds while manual operations retain base mix flexibility.
Ingredient Source:
Regulatory constraints and certification requirements reshape sourcing decisions, with antibiotic-free mandates and organic premiums redirecting procurement away from conventional animal-derived inputs.
- Animal By-Product:Rendered proteins and fats face declining inclusion rates as FDA Veterinary Feed Directive documentation burdens increase. Some Midwest operations retain porcine plasma for nursery phase palatability despite traceability costs.
- Plant-Based:Soybean meal, canola, and corn gluten dominate amino acid provisioning across the Corn Belt. Iowa and Illinois facilities leverage captive grain origination to compress plant-based input costs below synthetic alternatives.
- Synthetic Additives:Laboratory-derived lysine, methionine, and vitamins enable precise dietary manipulation. North Carolina integrated producers specify synthetic matrices to hit restrictive environmental nutrient discharge limits.
- Organic:USDA-certified mineral and vitamin premixes command substantial premiums from operations pursuing organic livestock certification. Midwest sow herds transitioning to organic production drive the steepest expansion trajectory in this category.
Plant-based inputs anchor volume flows; organic certification requirements accelerate premium segment development.
End User:
Customer scale and veterinary infrastructure availability determine service intensity requirements, with the largest buyers demanding customized formulation partnerships unavailable to smaller accounts.
- Commercial Farms:Independent operations with 500 to 5,000 sows constitute the core volume base. These buyers balance premix cost against nutritionist consulting fees.
- Backyard Producers:Subsistence and hobby operations with fewer than 50 animals purchase retail-packaged premixes through farm supply stores. Price sensitivity limits premium product penetration.
- Research Institutions:University swine units and pharmaceutical testing facilities require specialized premixes with documented batch homogeneity for trial reproducibility.
- Integrated Operations:Vertically coordinated pork producers with company-owned feed mills internalize premix procurement into captive supply chains. These accounts negotiate multi-year supply agreements with volume-tiered pricing.
Integrated operations concentrate procurement leverage; commercial farms respond through cooperative purchasing structures.
Distribution Channel:
Channel selection reflects buyer digital maturity and the value placed on technical service proximity versus transaction efficiency.
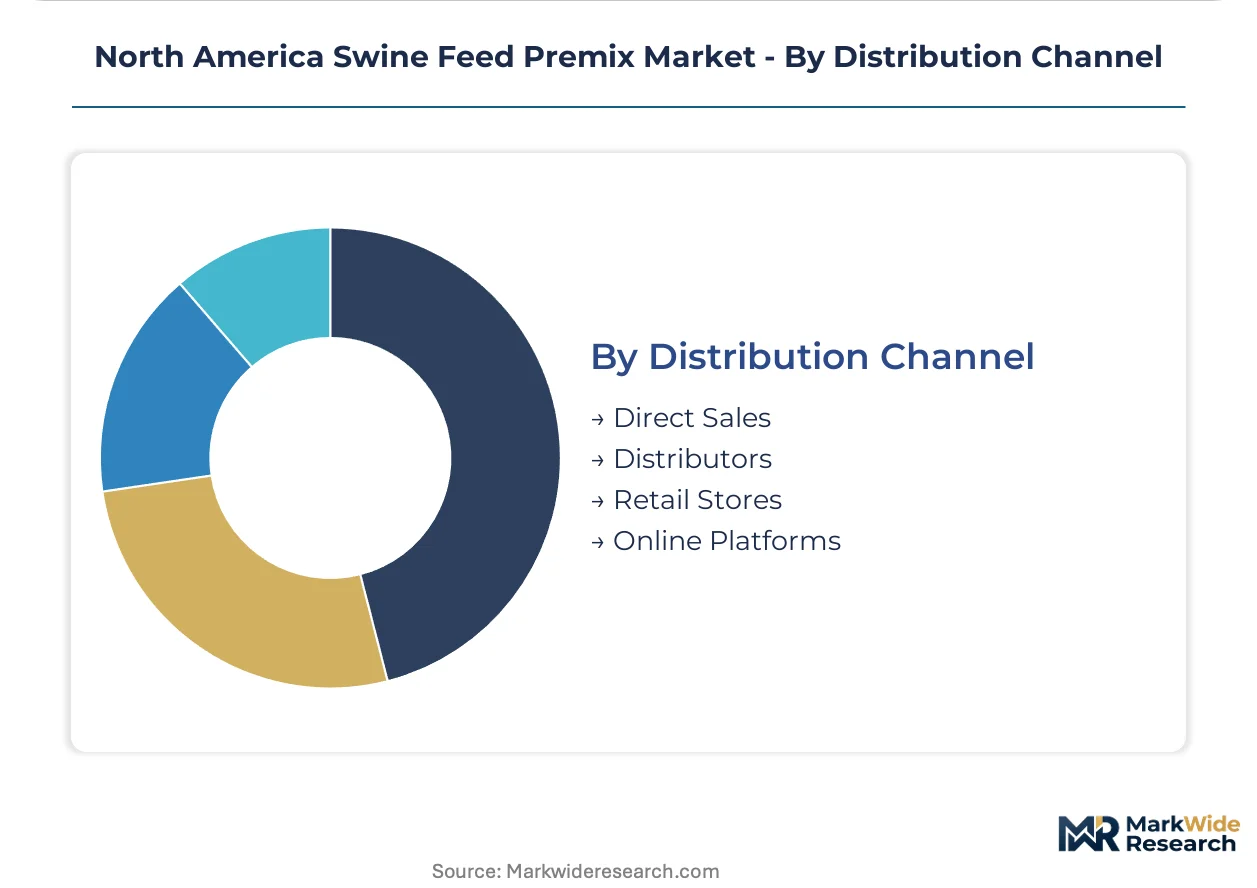
- Direct Sales:Manufacturer field nutritionists engage integrated operations and large commercial farms with customized formulation services. These relationships emphasize production outcome guarantees over commodity pricing.
- Distributors:Regional feed dealers aggregate demand from mid-sized commercial farms, providing inventory financing and local delivery logistics. Minnesota and Wisconsin retain dense distributor networks serving dispersed sow operations.
- Retail Stores:Farm supply cooperatives and independent retailers serve backyard producers with bagged premix SKUs. Shelf space constraints limit product assortment breadth.
- Online Platforms:Manufacturer portals and agricultural e-commerce sites enable direct-to-farm ordering. North Carolina commercial farms increasingly bypass distributors through digital channels to capture margin compression.
Distributor relationships retain volume dominance; digital direct channels gain share fastest among technologically sophisticated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the dominant share of North American swine feed premix consumption, while Canada supplies specialized formulation expertise and Mexico expands finishing capacity for export-oriented pork production.
United States
Iowa and North Carolina host the densest concentrations of integrated sow operations, driving demand for phase-specific premix bundles. The FDA's Veterinary Feed Directive mandates electronic documentation for all medicated feed purchases, accelerating antibiotic-free formulation transitions. Midwest commercial farms in Minnesota and Illinois are forming purchasing cooperatives to access volume-tiered pricing previously reserved for top-tier accounts.
Canada
Manitoba and Saskatchewan sow operations remain underpenetrated by precision nutrition services, creating expansion opportunities for premix providers. Health Canada's CFIA maintains divergent approval timelines from the FDA for novel feed additives, complicating cross-border shipment logistics. Ontario-based feed mills are retrofitting legacy facilities to handle enzyme and probiotic premix lines with enhanced temperature controls.
Mexico
Sonora and Jalisco are expanding finishing facilities to supply pork exports to Asian markets, driving demand for growth-optimized premix formulations. Mexico's national feed regulatory framework aligns partially with FDA standards but maintains independent veterinary prescription requirements for medicated feeds. Large integrated operations in the Bajío Region are adopting complete feed premixes to standardize nutrient delivery across company-owned barns.
North America Swine Feed Premix Market Competitive Landscape
The competitive structure tilts toward diversified agribusiness conglomerates with captive grain origination networks. Market concentration is moderate, with the top five players controlling formulation leadership but regional specialists retaining share in service-intensive segments. Two archetypes dominate: integrated nutrition platforms combining ingredient sourcing with formulation engineering, and precision health specialists focusing on high-health sow herd protocols. Competitive intensity centers on backward integration into amino acid supply and direct-to-farm digital channel development.
Within the integrated nutrition tier, Cargill Inc and ADM Animal Nutrition exemplify scale-driven competitors leveraging Midwest grain infrastructure to compress input costs. Nutreco occupies a position among precision health specialists, targeting reproductive performance optimization through customized micronutrient matrices. These three companies collectively represent the strategic spectrum from commodity-scale efficiency to veterinary-nutrition service integration.
| Leading Market Players |
|---|
| Lallemand Animal Nutrition |
| ADM Animal Nutrition |
| Kent Nutrition Group |
| BASF SE |
| Nutreco |
| Elanco |
| Alltech Inc |
| Land O'Lakes |
| Cargill Inc |
| Others |
Value Network & Pricing Analysis
Process engineers with homogeneity validation expertise in the Midwest command wage premiums that compress margin spreads between premium enzyme-premium formulations and standard vitamin-mineral blends. Labor scarcity in Iowa and Minnesota feed mill corridors forces manufacturers to absorb higher fixed costs or automate, widening the pricing gap between technology-intensive delayed-release formats and commodity base mixes.
Pricing Analysis
Cost-down pressure on standard premix tiers accelerates because commercial farms in Minnesota and Illinois purchasing cooperatives negotiate volume-tiered contracts that strip distributor markups. Three-tier pricing structure across premium delayed-release, standard complete feed, and economy base mix levels reflects certification grade and customization intensity. USDA organic certification commands the widest spread, while synthetic additive matrices face narrowing premiums as amino acid spot markets soften. Independent commercial farms exhibit acute price sensitivity; integrated operations prioritize outcome guarantees over per-ton economics.
Supply Chain Analysis
Dual-sourcing requirements for critical synthetic amino acids force premix manufacturers to qualify suppliers in China, Southeast Asia, and domestic fermentation facilities simultaneously. Lysine and methionine supply rests on fermentation capacity utilization in Asian manufacturing hubs, creating exposure to ocean freight volatility and customs documentation delays. Single-source vulnerability concentrates in novel enzyme and probiotic strains where patent-protected production limits alternative qualification. Distribution runs through regional feed dealers in Wisconsin and Minnesota, though North Carolina integrated operations increasingly bypass intermediaries via manufacturer direct portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around operations with captive grain origination and formulation engineering depth; FDA Veterinary Feed Directive compliance costs and legacy facility retrofit burdens force subscale regional mills toward acquisition or exit.
For Market Incumbents: Hedge amino acid price exposure through long-term offtake agreements with fermentation suppliers in China and Southeast Asia. Defend margin position by retrofitting Midwest facilities for temperature-controlled enzyme and probiotic lines before facility consolidation accelerates. Channel control through direct-to-farm digital portals in North Carolina captures margin previously allocated to distributors. For New Entrants and Emerging Players: Launch via precision nutrition service partnerships targeting underpenetrated sow operations in Manitoba and Saskatchewan. White-space concentration sits with organic-certified premix formulations for Midwest herds transitioning to USDA livestock standards. Go-to-market leverage rests on veterinary-nutritionist bundled consulting rather than commodity tonnage pricing. For Investors and Strategic Acquirers: The window for entry favors mid-sized regional premix manufacturers with established CFIA-FDA cross-border shipment capabilities and existing sow herd relationships. Long-term viability hinges on backward integration into amino acid sourcing or forward integration into on-farm formulation software. Monitor enzyme substitution performance plateaus in grower-finisher phases as the inflection signal for antibiotic-free formulation R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Supply | Captive lysine sourcing from Corn Belt fermentation facilities insulates margin from Asian spot market volatility. |
| Direct-to-Farm Digital Channel Launch | Manufacturer portals bypass distributor networks in North Carolina to capture margin compression from buyer concentration. |
| Organic Certification Pathway Investment | USDA-compliant mineral and vitamin matrices unlock premium positioning for transitioning Midwest sow herds. |
| Precision Nutrition Service Partnership | Customized micronutrient protocols for high-health herds in Iowa differentiate commodity premix providers. |
| Legacy Facility Retrofit for Enzyme Lines | Temperature-controlled mixing systems enable probiotic and acidifier premix production amid FDA regulatory pressure. |
Research Methodology
Document review covered FDA Veterinary Feed Directive enforcement records, CFIA feed regulatory filings, and USDA organic certification databases, complemented by interviews with feed mill operations managers, swine nutritionists at integrated pork producers, veterinary prescription platform developers, and amino acid procurement specialists. Secondary validation drew from customs trade data, SEC filings of diversified agribusiness conglomerates, and regional feed industry association reports. Bottom-up volume estimates from facility-level production data were cross-referenced against top-down consumption projections from sow herd inventory statistics.
Historical capacity utilization trends were cross-referenced against panel input from nutrition formulation software providers and grain origination traders. The forecast framework models segmentation across product type, ingredient source, end user scale, and distribution channel complexity throughout the projection horizon. CAGRs were derived from regression analysis of premix tonnage against sow herd expansion patterns and regulatory phase-in timelines. Industry-specific inputs include amino acid price index volatility and electronic feed documentation system adoption curves.
The model assumes a particular technology adoption path for near-infrared spectroscopy and cloud-based ration optimization; alternative pathways for on-farm mixing automation would alter the outlook for traditional premix formulation service demand. Forecasts reflect assumptions regarding FDA enforcement continuity and CFIA-FDA regulatory convergence. Deviation in amino acid fermentation capacity expansion in China or enzyme performance breakthroughs in grower-finisher applications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
Animal Derivatives Market