
 Cattle Management Software Market | 2026-2036
Cattle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Management Software Market Analytics
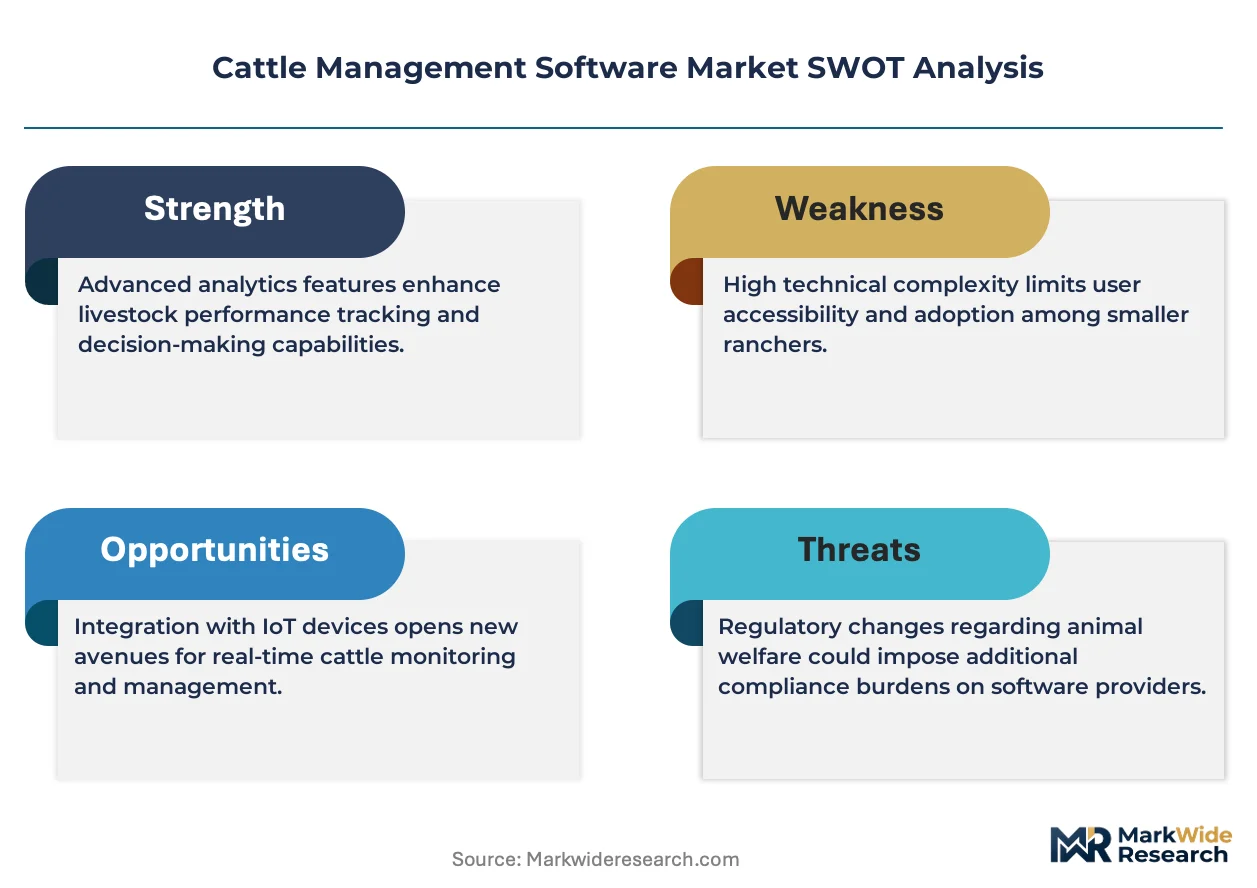
Veterinary data science talent is reorganizing how software vendors build predictive health modules for livestock operations. DeLaval leverages its embedded hardware footprint to bundle sensors with subscription analytics. GEA Group AG sustains R&D intensity across automated milking-to-management workflows. Zoetis differentiates through pharmaceutical-linked digital health records that integrate with diagnostic protocols.
Cattle management software comprises digital platforms that capture, process, and visualize livestock data across breeding, nutrition, health, and movement parameters, typically integrating RFID tags, IoT sensors, and cloud databases to enable real-time decision-making. The primary purpose is to replace paper-based herd records with traceable, analytics-driven workflows that reduce mortality, optimize feed conversion, and ensure regulatory compliance. Herd management functions dominate current revenue as the foundational module ranchers adopt first, while grazing management represents the fastest-expanding segment where satellite pasture mapping and rotational scheduling tools command premium pricing. Cloud-based deployment is displacing on-premise installations among mid-sized operators seeking lower upfront capital burdens and remote access across dispersed properties.
The USDA enforces animal disease traceability rules that mandate electronic identification and movement documentation, directly elevating software demand among US feedlots and auction yards. Australia's Biosecurity Act and the EU Green Deal's methane-reduction targets for agriculture are tightening environmental reporting obligations that ranch software must address. Stakeholders should monitor how national livestock databases evolve from voluntary to compulsory participation, as this transition determines which vendors can embed their platforms into mandatory government infrastructure.
Market Dynamics
Cloud-based grazing management platforms are compressing deployment timelines for pastoral operations while national livestock traceability mandates force software vendors to embed compliance modules directly into core product architecture.
Growth Catalysts
- EU Green Deal methane targets:Ranchers across Germany, France, and the Netherlands must document emissions reductions, creating mandatory software procurement for environmental reporting workflows.
- RFID-to-cloud integration:Low-cost sensor hardware combined with cellular connectivity enables real-time weight and location tracking for feedlot operators previously dependent on manual record-keeping.
- Australia's Biosecurity Act enforcement:Electronic identification requirements for cattle movement documentation drive subscription upgrades among Queensland and Northern Territory pastoral companies.
Market Restraints
- Connectivity infrastructure gaps:Remote rangelands in Western Australia and the Brazilian Pantanal lack reliable cellular coverage, degrading real-time data transmission for cloud-dependent platforms.
- Specialized veterinary data science talent scarcity:Predictive health algorithm development requires livestock domain expertise combined with machine learning proficiency, a skill intersection concentrated in university clusters near Wageningen and Davis.
- Legacy paper record persistence:Generational ranch operators in Argentina's Pampas and the US Great Plains resist digital migration despite regulatory pressure, elongating sales cycles.
Strategic Opportunities
- Carbon credit verification integration:Methane quantification tools that generate auditable offset documentation open revenue streams for software vendors serving sustainability-focused beef supply chains.
- Artificial insemination timing optimization:Heat detection algorithms paired with estrus cycle databases create premium subscription tiers for seedstock producers targeting genetic improvement.
- Mobile-first deployment in East Africa:Pastoralist cooperatives in Kenya and Ethiopia represent greenfield demand for lightweight herd tracking applications operating on basic smartphone hardware.
Industry Challenges
- Interoperability with government livestock databases:Vendors must rebuild data export architectures each time a national authority modifies API specifications for mandatory disease traceability submissions.
- Hardware sensor calibration drift:Weight and temperature monitoring devices deployed in dusty feedlot environments require frequent recalibration, eroding margin on bundled sensor-plus-software contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Management Software Market |
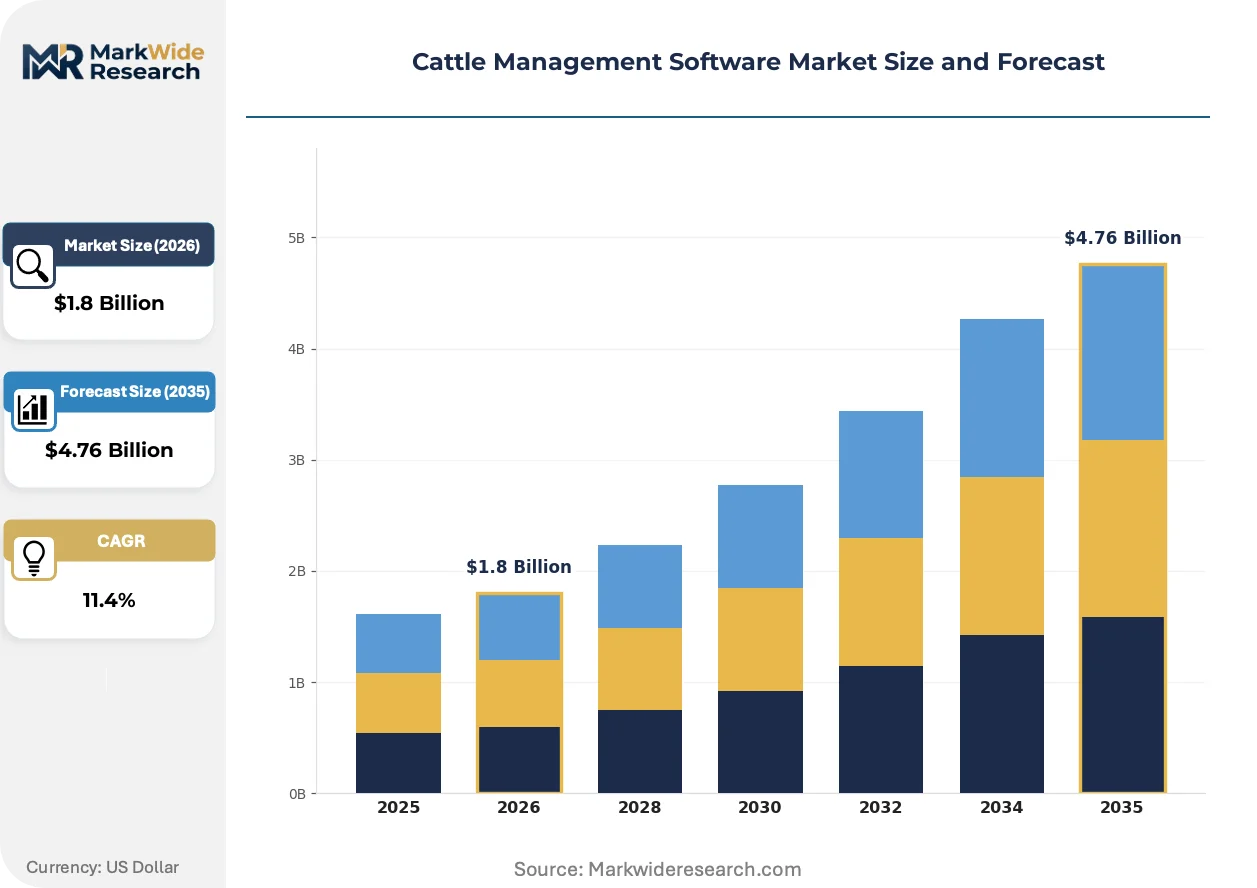
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herd Management, Grazing Management, Feed Management, Health Management Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Dairies, Ranch Operators, Feedlots, Agribusiness Integration Level: API Integration, Standalone, Third-Party Software, IoT Integration |
| Companies Covered | DeLaval, Afimilk Ltd., GEA Group AG, Merck & Co. Inc., BouMatic, Zoetis, Lely, Cattlesoft Inc., AgriWebb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Management Software Market Evolving Landscape
Satellite pasture biomass monitoring is rewriting how rotational grazing decisions are made, compressing the gap between imagery capture and paddock allocation while forcing software vendors to integrate geospatial analytics into core herd management platforms.
Machine learning-driven predictive health algorithms are supplanting scheduled veterinary inspection routines for large-scale feedlot operations. Feedlot managers in Texas and Alberta now receive mortality risk scores 48-72 hours before clinical symptoms appear. This capability is compressing antibiotic use rates and reshaping procurement criteria for enterprise software contracts.
The USDA's advancing animal disease traceability rules mandate electronic identification and movement documentation for cattle crossing state lines. US feedlots and auction yards must upgrade software infrastructure to submit real-time data to federal databases. Vendors are responding by pre-certifying platforms against USDA technical standards to accelerate procurement approvals.
Subscription pricing is displacing perpetual license models among mid-sized ranch operators seeking to avoid upfront capital deployment. Australian pastoral companies with dispersed properties across multiple states favor monthly cloud access fees that scale with headcount. This shift compresses vendor cash conversion cycles while expanding addressable market penetration among capital-constrained operators.
Cattle Management Software Market Segmentation
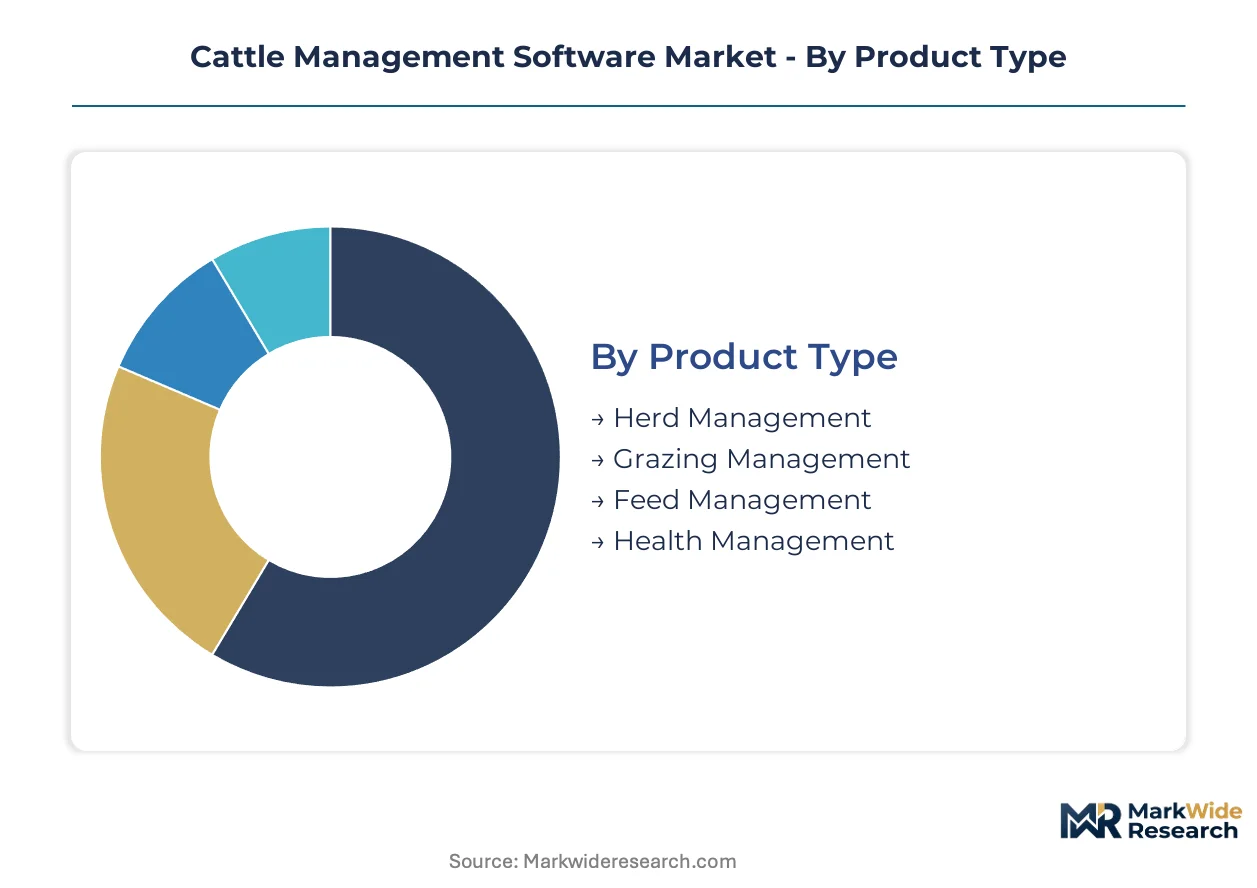
Segmentation in cattle management software reveals how procurement priorities diverge across operational scales and regulatory exposure. Ranchers select modules based on herd size, connectivity infrastructure, and mandatory traceability obligations rather than feature breadth alone.
Product Type:
Margin pools concentrate in grazing management modules where satellite pasture analytics command premium subscription tiers from large-scale pastoral operations.
- Herd Management:Foundational digital platforms tracking breeding records, calving intervals, and lineage documentation through centralized databases. Queensland pastoral companies deploy these systems across dispersed properties to satisfy Australia's Biosecurity Act electronic identification mandates.
- Grazing Management:Satellite-enabled platforms combining biomass monitoring with rotational scheduling algorithms. German and Dutch ranchers purchase these modules to document methane reduction efforts under EU Green Deal reporting requirements.
- Feed Management:Ration formulation tools integrating nutritional databases with cost optimization engines.
- Health Management:Predictive analytics modules processing veterinary records and sensor data for early disease detection.
The dominant share belongs to herd management, while grazing management is expanding most quickly as environmental compliance tightens.
Deployment:
Volume concentrates in cloud-based delivery where monthly subscription models reduce capital barriers for mid-sized operators.
- Cloud-Based:Browser-accessible platforms with automatic updates and remote property synchronization. Australian operators spanning multiple states favor this model for dispersed workforce access without on-site server maintenance.
- Mobile:Smartphone-native applications processing RFID scans and pasture observations offline with periodic synchronization. Kenyan and Ethiopian pastoralist cooperatives adopt lightweight versions operating on basic Android hardware.
- On-Premise:Locally installed software requiring dedicated server infrastructure and IT support.
- Hybrid:Architectures combining local data storage with cloud backup and selective synchronization.
Cloud-based deployment holds the largest installed base, with mobile gaining share fastest among emerging market cooperatives.
End User:
Application intensity varies by operational complexity and regulatory scrutiny exposure.
- Feedlots:Enterprise-scale platforms integrating weight monitoring, feed conversion tracking, and antibiotic administration records. Texas and Alberta operators deploy predictive health algorithms to compress mortality rates ahead of scheduled veterinary inspections.
- Dairies:Automated milking-to-management workflows capturing individual cow production, somatic cell counts, and reproductive status. These systems synchronize with pharmaceutical protocols from integrated animal health providers.
- Ranch Operators:Mixed-use platforms balancing breeding management with grazing optimization across extensive rangeland holdings.
- Agribusiness:Consolidated enterprise systems managing multiple species and geographic locations with centralized reporting.
Feedlots generate the highest per-seat revenue, though dairies are climbing the fastest as automation penetrates milking operations.
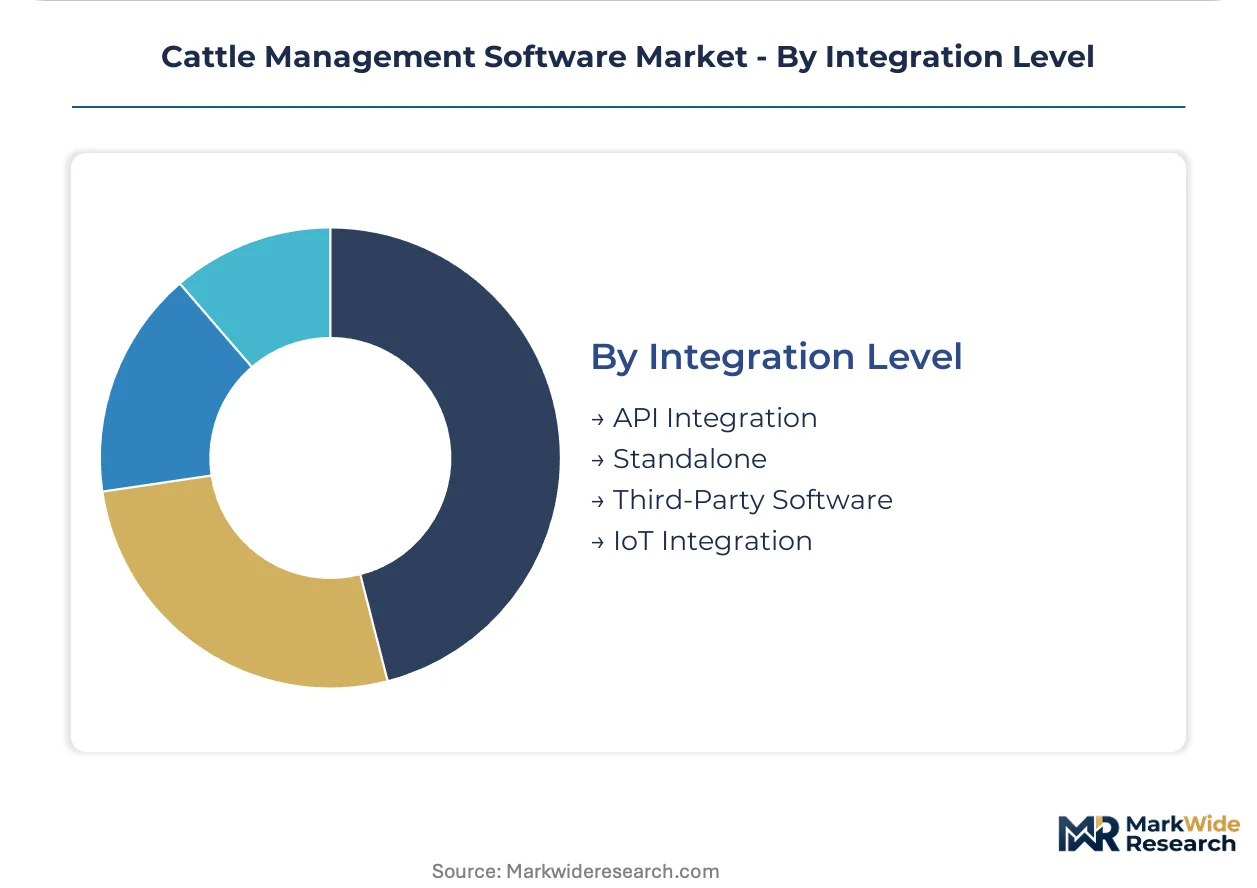
Integration Level:
Supply concentration sits with vendors building pre-certified government database connections.
- IoT Integration:Direct sensor connectivity enabling real-time weight, temperature, and location transmission from RFID-enabled hardware. Feedlot operators in the US purchase bundled sensor-plus-software contracts to satisfy USDA animal disease traceability rules.
- API Integration:Programmatic data exchange with third-party accounting, genetics, and supply chain platforms.
- Standalone:Self-contained software requiring manual data entry without external system connectivity.
- Third-Party Software:Modules designed for interoperability with existing farm management or ERP systems.
IoT integration captures the steepest expansion trajectory as hardware costs decline, while standalone systems retain share among generational operators resisting digital migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors demand concentration through advancing animal disease traceability rules that mandate electronic identification and movement documentation. Ranch software procurement clusters where national regulators enforce compulsory livestock databases.
United States
Texas feedlot operators deploy predictive health algorithms to compress mortality rates ahead of veterinary inspections. The USDA mandates real-time data submission to federal databases for cattle crossing state lines. Kansas and Nebraska processors upgrade software infrastructure to satisfy pre-certification requirements against USDA technical standards.
Australia
Queensland and Northern Territory pastoral companies drive subscription upgrades for electronic identification compliance. The Biosecurity Act enforces movement documentation requirements across extensive rangeland holdings. New South Wales agribusinesses favor cloud-based platforms for dispersed property synchronization without on-site server maintenance.
Germany
Dutch and German ranchers purchase satellite-enabled grazing modules to document methane reduction efforts. The EU Green Deal imposes binding emissions targets that elevate environmental reporting obligations. Bavarian dairy cooperatives integrate automated milking-to-management workflows with pharmaceutical protocols.
Brazil
Mato Grosso feedlot operators seek weight monitoring integration despite connectivity gaps in the Pantanal. The national agricultural regulator enforces traceability documentation for export certification to EU and Chinese markets. São Paulo-based agribusinesses consolidate enterprise systems across multiple species and geographic locations.
Kenya
Pastoralist cooperatives in the Rift Valley represent greenfield demand for lightweight herd tracking applications. The country's livestock ministry pilots electronic identification programs with development agency support. Nairobi-based technology distributors partner with basic smartphone hardware providers to reach smallholder operators.
Cattle Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in cattle management software. Tier-one players bundle hardware sensors with subscription analytics to capture recurring revenue streams. Mid-tier specialists concentrate on single-function modules such as grazing optimization or artificial insemination timing. Competitive moves center on pre-certification against government database standards and carbon credit verification integration.
Within the integrated systems tier, DeLaval and GEA Group AG exemplify hardware-anchored platform strategies. Lely occupies a position among automation-focused specialists targeting dairy workflow integration. Afimilk Ltd. and Cattlesoft Inc. represent the specialist tier with modular approaches to herd data management.
| Leading Market Players |
|---|
| DeLaval |
| Afimilk Ltd. |
| GEA Group AG |
| Merck & Co. Inc. |
| BouMatic |
| Zoetis |
| Lely |
| Cattlesoft Inc. |
| AgriWebb |
| Others |
Value Network & Pricing Analysis
Ninety-day sensor procurement lead times from Asia-Pacific contract manufacturers compress margin buffers for vendors bundling hardware with SaaS subscriptions, concentrating pricing power with integrated platform providers while forcing specialist software firms toward pure-play cloud models.
Pricing Analysis
Australian pastoral operators pay premiums exceeding North American benchmarks for satellite-enabled grazing modules, reflecting sparse connectivity infrastructure and mandatory Biosecurity Act compliance requirements. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with IoT-bundled tiers commanding sustained premiums. Cost compression in the mid-market intensifies because Kenyan and Ethiopian cooperatives adopt lightweight mobile deployments at sub-scale price points. Smallholder cooperatives exhibit acute price sensitivity, while Queensland agribusinesses prioritize compliance-grade reliability over unit economics.
Supply Chain Analysis
China and Taiwan anchor RFID sensor fabrication, with South Korean memory chip suppliers feeding cloud data center expansion. Hardware draws from Shenzhen contract manufacturers, Texas Instruments analog components, and Nordic Semiconductor low-power connectivity modules. Single-source vulnerability concentrates in satellite imagery providers serving pasture biomass analytics. Distribution runs through Australian agricultural technology distributors, US farm management service cooperatives, and Kenyan mobile network operator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent software vendors face substitution pressure from vertically integrated equipment manufacturers bundling sensors with captive analytics platforms, eroding standalone SaaS pricing power.
For Market Incumbents: Secure pre-certification against USDA and EU livestock database API standards to embed platforms into mandatory government infrastructure. Defend against DeLaval and GEA Group AG hardware-software bundling by deepening veterinary data science capabilities in university clusters near Wageningen and Davis.
For New Entrants and Emerging Players: USDA technical standard pre-certification fast-tracks procurement approval for feedlot operators facing state-line movement documentation mandates. Target Kenyan and Ethiopian pastoralist cooperatives with offline-capable mobile applications operating on basic Android hardware. Pursue carbon credit verification integration as a premium tier differentiator for European sustainability-focused beef supply chains.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because livestock traceability mandates are transitioning from voluntary to compulsory participation across multiple jurisdictions. Acquire specialist firms with pre-certified government database connections and embedded veterinary data science talent. Watch national livestock database API specification changes as the primary inflection signal for vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-certified USDA and EU database connections accelerate procurement cycles for feedlot operators. |
| Acquisition of Specialist Firm | Veterinary data science teams near Wageningen and Davis compress predictive health algorithm development timelines. |
| Geographic Expansion | Kenyan and Ethiopian mobile-first deployments access greenfield pastoralist cooperative demand. |
| Product Launch | Carbon credit verification modules capture EU Green Deal methane reporting premium tiers. |
| Strategic Partnership | Satellite imagery provider alliances embed biomass analytics into core grazing management workflows. |
Research Methodology
A spread of perspectives from ranch operators, veterinary data scientists, agricultural technology distributors, and government livestock database administrators converged on the working assumptions driving this analysis. Primary interviews with Queensland pastoral companies, Texas feedlot managers, and Kenyan cooperative leaders combined with secondary validation against USDA regulatory filings, EU Green Deal implementation documents, and Australian Biosecurity Act enforcement records. Bottom-up property-level adoption modeling and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled span deployment architecture, integration complexity, end-user operational scale, and regional regulatory framework intensity across the analysis window. CAGRs derive from property-level software procurement velocity, sensor hardware cost decline curves, and mandatory traceability mandate implementation schedules. Forecast inputs incorporate satellite connectivity coverage expansion and veterinary data science graduate pipeline capacity.
Underlying assumptions cover sustained regulatory enforcement of electronic identification mandates, with deviation risk concentrated in connectivity infrastructure deployment delays and generational operator digital adoption resistance. Recalibration cycles align with material shifts in national livestock database API specifications and EU methane reduction target enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
South America Swine Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
North America Swine Feed Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Wagyu Beef Market
Livestock Management
Pig Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Hominy Feed Market
Livestock Management
Cattle Head Catch Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Africa Alfalfa Hay Market