
 Europe Swine Feed Market | 2026-2036
Europe Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Swine Feed Market Intelligence
The price-performance gap between premium compound feeds and commodity bulk rations is hardening across European procurement channels. Cargill Inc. leverages its transcontinental grain origination network to secure cost-advantaged positions in Iberian and Benelux markets. Nutreco N.V. anchors its premium tier through advanced pre-starter formulations targeting hyperprolific sow lines in Denmark and the Netherlands. Forfarmers B.V. competes on distribution density, operating over two hundred mill-to-farm delivery routes that compress lead times for independent finishers.
Europe swine feed denotes nutritionally complete rations formulated to meet the metabolizable energy, lysine, and phosphorus requirements of pigs across distinct physiological stages, typically manufactured through thermal conditioning and pelleting to achieve digestibility coefficients above eighty-five percent. These feeds serve the primary commercial purpose of optimizing feed conversion ratios and carcass uniformity in intensive pork production systems. Grower feeds occupy the largest volume share as European herds push slaughter weights upward, while pre-starter feeds command the steepest per-tonne premiums due to specialized milk replacer and plasma protein inclusions. Pellet form dominates logistics and intake efficiency, though liquid feeding systems retain structural presence in newly constructed Danish and Dutch facilities where automated dispensing reduces labor costs.
The European Food Safety Authority and EU Feed Hygiene Regulation establish baseline contaminant thresholds and manufacturing practice standards that all compounders must satisfy for market access. REACH and the F-Gas Regulation additionally constrain preservative chemistries and processing refrigerants, elevating compliance costs for smaller regional blenders. Stakeholders must track the EU Deforestation Regulation's due diligence timelines, as feed crop traceability requirements will soon force sourcing system overhauls for soy-dependent formulations.
Market Dynamics
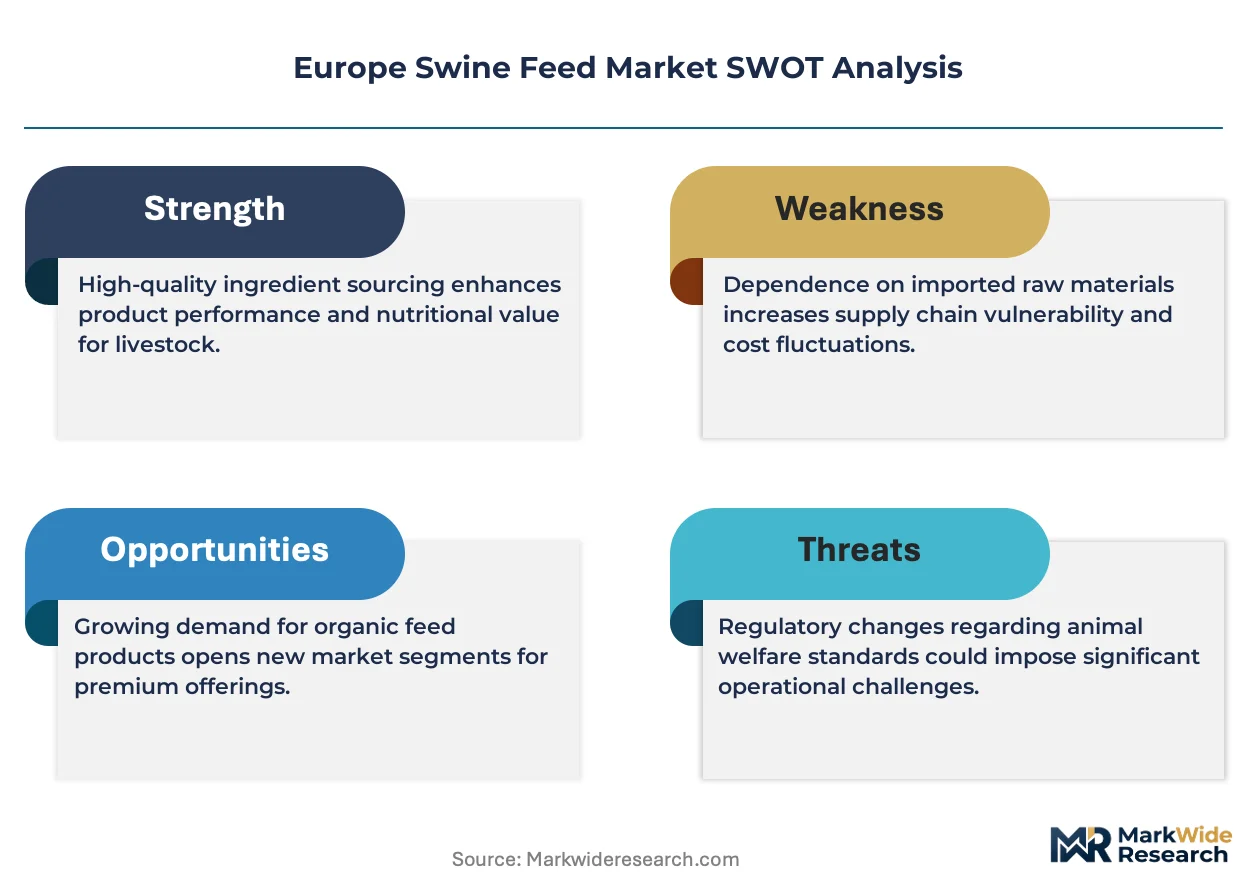
The EU Green Deal's Farm to Fork Strategy is compressing formulation windows for compounders, forcing rapid substitution of imported soy with regional protein crops while tightening additive restrictions across northwestern European supply chains.
Growth Catalysts
- Regulatory Protein Substitution Mandates:The EU Deforestation Regulation's traceability requirements are accelerating domestic rapeseed and faba bean cultivation, creating captive supply bases for Iberian and Benelux formulators.
- Denmark's Hyperprolific Sow Expansion:Danish breeding operations are extending pre-starter feed programs to capture genetic potential from high-litter genetics, pulling specialized milk replacer volumes upward.
- Pelleting Technology Upgrades:Thermal conditioning investments across German mill networks are achieving digestibility coefficients above ninety percent, unlocking feed conversion premiums for integrated finishers.
Market Restraints
- Soy Import Dependency Concentration:Brazilian and Argentinian soy meal supplies sixty to seventy percent of European crude protein, exposing compounders to currency volatility and port congestion at Rotterdam and Hamburg.
- REACH-Compliant Preservative Scarcity:The European Chemicals Agency's authorization restrictions on formaldehyde-based mold inhibitors are narrowing the approved additive list and elevating formulation costs for regional blenders.
- Liquid Feeding System Capex Barriers:Automated dispensing infrastructure for fermented wet feeds requires seven-figure installation investments, limiting adoption to newly constructed Dutch and Danish facilities with capital access.
Strategic Opportunities
- Polish Independent Finisher Penetration:Fragmented pork operations across Mazovia and Greater Poland lack dedicated nutrition services, creating whitespace for mobile mill-to-farm distribution models.
- CSRD-Driven Scope 3 Reporting:The Corporate Sustainability Reporting Directive is mandating feed carbon footprint disclosure, positioning certified low-emission compounders for premium procurement contracts with processor-aligned integrators.
- Insect Protein-Conventional Feed Convergence:Black soldier larva meal approvals under novel food regulations are opening dual-protein formulations that satisfy amino acid profiles while reducing land-use intensity.
Industry Challenges
- Precision Nutrition Skill Gaps:Formulation chemists with metabolizable energy modeling expertise are concentrated in Danish and Dutch research clusters, creating recruitment friction for expanding Spanish and German operations.
- EU Deforestation Regulation Compliance Timelines:The eighteen-month due diligence implementation window is forcing sourcing system overhauls before traceability mandates activate, compressing procurement reconfiguration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Swine Feed Market |
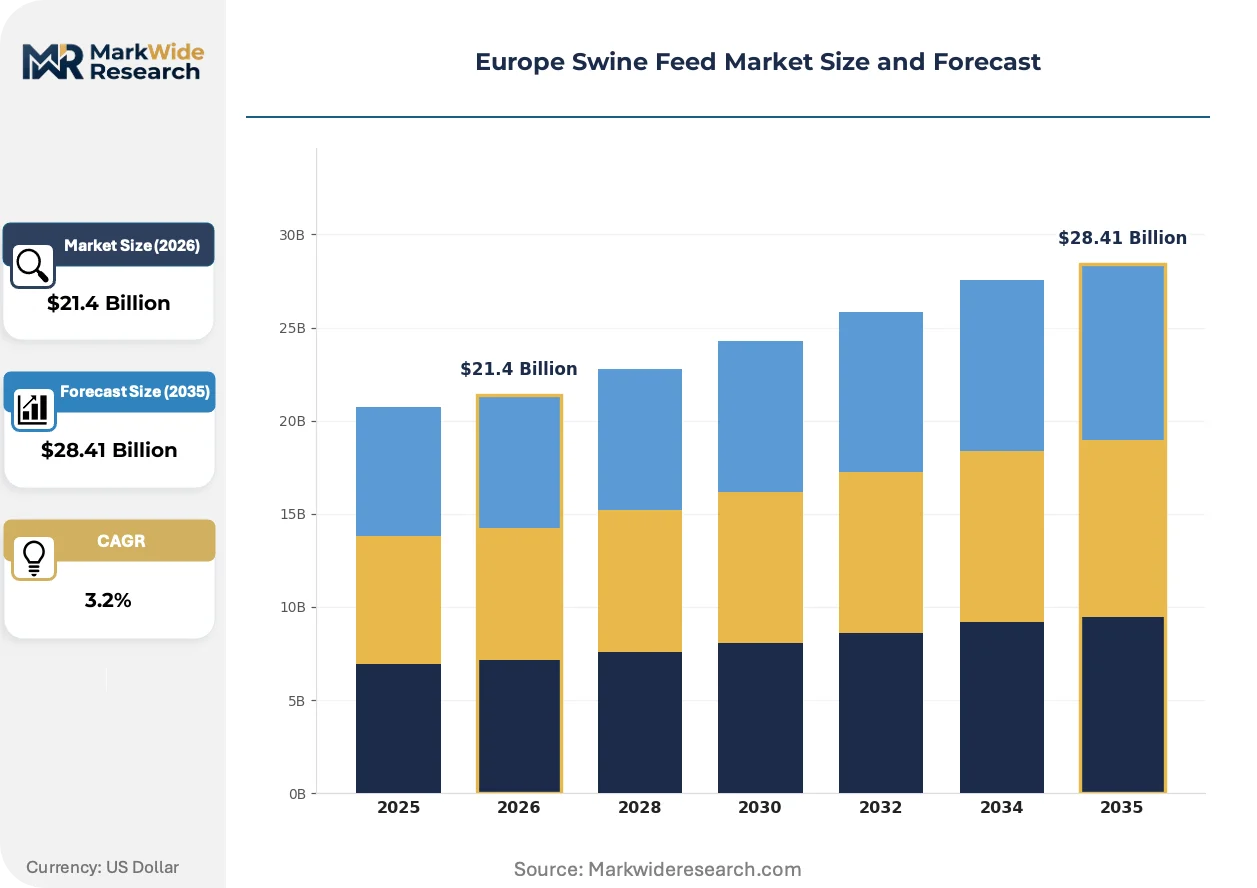
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $28.41 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Starter Feeds, Grower Feeds, Finisher Feeds, Sow Feeds Ingredient: Corn, Soybean Meal, Wheat, Barley Distribution Channel: Online Retail, Specialty Stores, Distributors, Direct Sales Form: Pellets, Meal, Crumbles, Liquid |
| Companies Covered | Cargill Inc., Nutreco N.V., Archer Daniels Midland Company, Forfarmers B.V., Land O'Lakes Inc., BASF SE, Alltech Inc., Novus International, De Heus B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Swine Feed Market Strategic Shifts & Innovations
Formulation science is pivoting from crude protein metrics to standardized ileal digestible amino acid ratios, compressing safety margins and demanding real-time near-infrared spectroscopy at mill intake points.
Near-infrared reflectance spectroscopy is absorbing quality control functions across compound feed manufacturing. German and Dutch mill operators are deploying inline NIR sensors at hammer mill discharge points to adjust thermal conditioning parameters batch-by-batch. This technology is absorbing the role of offline laboratory testing, compressing release-to-delivery cycles from forty-eight hours to under six hours for integrated finishers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in pelleting cooling towers, elevating capital costs for mill retrofits. Compounders in Denmark and the Netherlands are migrating to ammonia-based cooling systems ahead of quota restrictions. Pre-starter feed manufacturers with temperature-sensitive plasma protein inclusions face the steepest compliance timelines.
Buyer concentration among processor-aligned integrators is consolidating procurement decisions into centralized nutrition teams. Independent finishers in Spain and Poland are losing direct mill relationships as volume flows through cooperative purchasing groups. This shift is most visible in Castile and León, where slaughterhouse-owned feed mills now supply sixty percent of regional finishing capacity.
Europe Swine Feed Market Segmentation
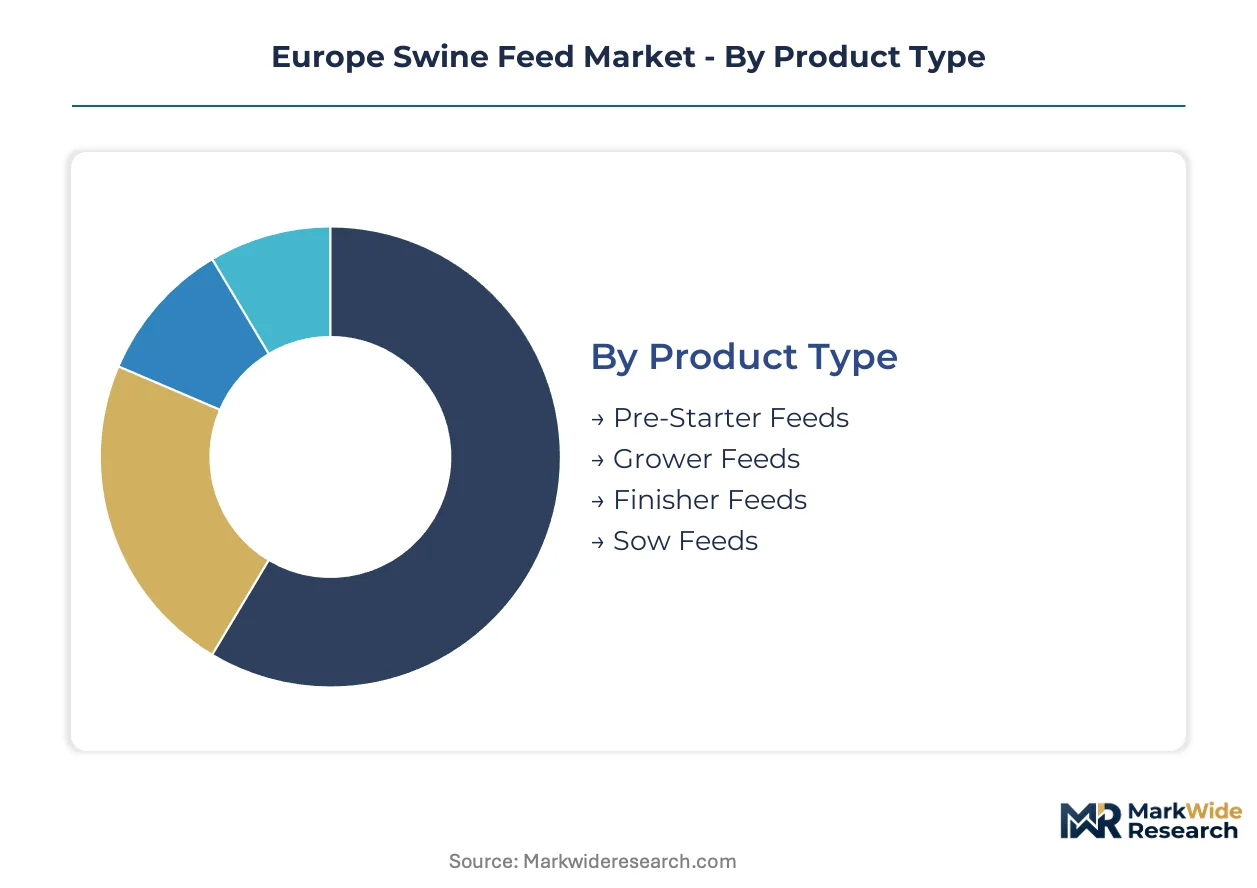
European swine feed segmentation reveals how procurement power concentrates around specific product tiers and distribution configurations. Formulators align manufacturing investments with the physiological stages commanding premium pricing and volume throughput.
Product Type:
Supply concentration in compound feed manufacturing tilts toward the segments integrating most tightly with processor-aligned integrators.
- Grower Feeds:These rations balance metabolizable energy density with lysine-to-calorie ratios for pigs between twenty and sixty kilograms live weight. Demand clusters in northwestern Germany and Denmark where integrated finishers push slaughter weights upward to capture processor premiums for uniform carcasses.
- Pre-Starter Feeds:Specialized formulations incorporate spray-dried plasma protein and processed milk products to support gut development in piglets from birth to seven kilograms. Danish hyperprolific sow operations extend these programs to maximize genetic potential from high-litter genetics, pulling specialized ingredient volumes upward.
- Finisher Feeds:Energy-dense rations designed for the final fattening phase prior to slaughter, emphasizing feed conversion efficiency over crude protein content.
- Sow Feeds:Gestation and lactation formulations adjusted for body condition scoring and milk yield requirements across parity cycles.
Today's leader: Grower Feeds. Tomorrow's challenger: Pre-Starter Feeds.
Ingredient:
Cost tier differentiation separates commodity grains from imported protein meals across European formulation strategies.
- Soybean Meal:The dominant crude protein source supplying sixty to seventy percent of amino acid requirements in northwestern European formulations. EFSA mycotoxin thresholds and impending EU Deforestation Regulation traceability mandates are forcing sourcing system overhauls before compliance deadlines activate.
- Wheat:Preferred energy base in Benelux and northern French mills where local harvests reduce transport costs and improve supply security versus imported alternatives.
- Corn:Higher metabolizable energy content drives inclusion in southern European formulations, though price volatility links to Black Sea export disruptions.
- Barley:Regional cultivation in Scotland and northern England supports local finishing operations with beta-glucan management protocols for digestibility optimization.
Volume leadership sits with Soybean Meal. Regional substitution momentum favors Wheat.
Distribution Channel:
Customer type fragmentation determines route-to-market economics across independent versus integrated production systems.
- Direct Sales:Mill-to-farm delivery contracts dominate volume flows to Dutch and Danish integrators with captive slaughterhouse alignment. These arrangements compress lead times below six hours through dedicated logistics fleets and real-time order management systems.
- Distributors:Regional blenders and cooperatives serve fragmented independent finishers across Poland and Spain where volume aggregation justifies procurement intermediation.
- Specialty Stores:Agricultural supply retailers capture hobby farm and smallholder demand with bagged product configurations.
- Online Retail:Digital procurement channels remain nascent, constrained by bulk logistics requirements and just-in-time delivery expectations.
Direct Sales commands margin concentration. Distributors face compression from cooperative purchasing consolidation.
Form:
Technology maturity separates established pelleting infrastructure from emerging liquid system investments.
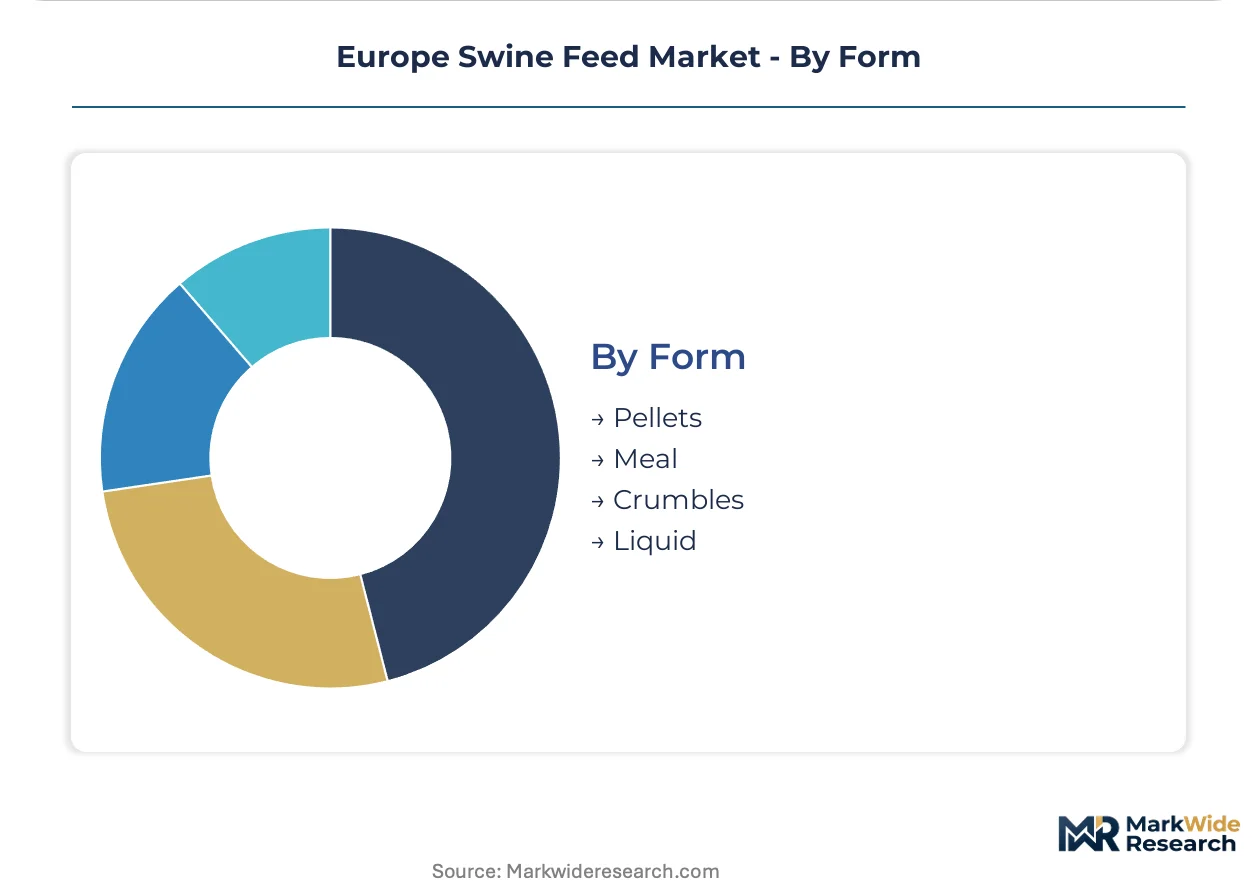
- Pellets:Thermal-conditioned cylindrical feeds achieving digestibility coefficients above eighty-five percent through steam conditioning and die compression. German mill networks are upgrading to exceed ninety percent coefficients, unlocking feed conversion premiums.
- Liquid:Fermented wet feeds dispensed through automated pipeline systems in newly constructed Dutch and Danish facilities. ECHA F-Gas Regulation refrigerant constraints and seven-figure capital requirements limit adoption to greenfield installations with capital access.
- Meal:Unprocessed mash feeds retaining lower manufacturing costs but sacrificing intake efficiency and dust control versus pelleted alternatives.
- Crumbles:Intermediate particle size targeting pre-starter applications where pellet hardness risks feed refusal in young piglets.
Pellets anchor logistics efficiency. Liquid forms are climbing the fastest in premium new-build facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Danish and Dutch research hubs, creating recruitment friction for expanding operations elsewhere in Europe. This talent concentration shapes regional competitive dynamics across the continent.
Germany
Integrated finishers in northwestern Germany push slaughter weights upward to capture processor premiums for uniform carcasses. The EFSA and EU Feed Hygiene Regulation establish baseline contaminant thresholds that all compounders must satisfy for market access. Mill networks across Lower Saxony and North Rhine-Westphalia are upgrading thermal conditioning investments to exceed ninety percent digestibility coefficients.
Denmark
Hyperprolific sow operations extend pre-starter feed programs to maximize genetic potential from high-litter genetics. REACH and the F-Gas Regulation constrain preservative chemistries and processing refrigerants, elevating compliance costs. Research clusters in Copenhagen and Aarhus anchor precision nutrition expertise that expanding Spanish and German operations struggle to replicate.
Netherlands
Mill-to-farm delivery contracts dominate volume flows to Dutch integrators with captive slaughterhouse alignment. The EU Green Deal's Farm to Fork Strategy tightens feed additive regulations and pushes substitution of imported soy with regional protein crops. Automated liquid feeding systems in newly constructed facilities around Eindhoven and the Randstad reduce labor costs through fermented wet feed dispensing.
Spain
Slaughterhouse-owned feed mills now supply sixty percent of regional finishing capacity in Castile and León. The EU Deforestation Regulation's due diligence timelines force sourcing system overhauls for soy-dependent formulations before traceability mandates activate. Iberian formulators accelerate domestic rapeseed and faba bean cultivation to create captive supply bases.
Poland
Fragmented pork operations across Mazovia and Greater Poland lack dedicated nutrition services. The Corporate Sustainability Reporting Directive mandates feed carbon footprint disclosure, positioning certified low-emission compounders for premium procurement contracts. Mobile mill-to-farm distribution models target whitespace among independent finishers lacking cooperative purchasing group access.
Europe Swine Feed Market Key Industry Players
Top-tier vendors anchor transcontinental grain origination and advanced formulation science, while regional blenders compete on distribution density and mill-to-farm logistics. The market structure consolidates around three strategic archetypes: global agribusiness conglomerates with origination networks, European specialists in premium pre-starter formulations, and regional cooperatives with dense delivery route coverage. Dominant competitive moves include backward integration into regional protein crop cultivation and technology licensing for automated liquid feeding systems.
Within the global agribusiness tier, Cargill Inc. and Archer Daniels Midland Company exemplify players leveraging transcontinental supply chain scale. Among European specialists, Nutreco N.V. and Forfarmers B.V. occupy positions defined by formulation expertise and distribution infrastructure respectively. De Heus B.V. represents the regional cooperative archetype with mill-to-farm delivery route density across fragmented independent finisher markets.
| Leading Market Players |
|---|
| Cargill Inc. |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| Forfarmers B.V. |
| Land O'Lakes Inc. |
| BASF SE |
| Alltech Inc. |
| Novus International |
| De Heus B.V. |
| Others |
Cost & Logistics Intelligence
Precision nutrition chemists concentrated in Danish and Dutch research clusters command compensation premiums that compounders pass through as tiered spreads between commodity bulk rations and specialized pre-starter formulations. Labor-cost differentials between these talent-dense regions and expanding Spanish or German operations widen pricing gaps as formulators compete for scarce metabolizable energy modeling expertise.
Pricing Analysis
Bundled mill-to-farm delivery contracts with embedded technical advisory services command premium positioning against unbundled commodity spot purchases by independent finishers. Three-tier pricing structure across premium, standard, and economy levels separates CSRD-certified low-carbon compounders from regional blenders and cooperative-sourced bulk rations. Cost compression in standard-tier formulations is intensifying because REACH-compliant preservative scarcity elevates input expenses for mid-size blenders. Independent finishers in Poland and Spain exhibit highest price sensitivity, while Dutch and Danish integrators with processor alignment prioritize feed conversion performance over per-tonne cost.
Supply Chain Analysis
Workforce availability constraints in German and Spanish manufacturing geographies limit expansion of thermal conditioning capacity despite digestibility upgrade demand. Supply concentration rests on Germany, Denmark, and the Netherlands for compound feed manufacturing, with Iberian and Polish markets drawing from these northern production hubs. Raw material dependencies center on Brazilian and Argentinian soybean meal, regional wheat harvests across Benelux and northern France, and domestic rapeseed substitution crops. Single-source vulnerability in South American protein meal exposes compounders to port congestion at Rotterdam and Hamburg. Distribution runs through dedicated logistics fleets for integrated finishers and cooperative purchasing groups for fragmented independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe swine feed market functions as a stable compounder anchored by protein substitution mandates under the EU Green Deal that perpetuate reformulation demand across northwestern European supply chains.
For Market Incumbents: Lock in captive supply bases through backward integration into regional rapeseed and faba bean cultivation ahead of EU Deforestation Regulation activation. Deepen technical advisory bundling with mill-to-farm delivery contracts to defend margin position against cooperative purchasing consolidation threatening direct customer relationships. Prioritize ammonia-based cooling system retrofits to outrun F-Gas Regulation quota restrictions that will strand competitors with legacy refrigerant infrastructure. For New Entrants and Emerging Players: Independent finishers across Mazovia and Greater Poland represent the most penetrable buyer archetype currently underserved by dedicated nutrition services. Mobile mill-to-farm distribution models bypass cooperative purchasing intermediation to capture whitespace among fragmented pork operations lacking slaughterhouse alignment. Target certified low-emission positioning to exploit CSRD-driven Scope 3 reporting requirements that processor-aligned integrators now mandate from feed suppliers. For Investors and Strategic Acquirers: Processor-aligned agribusiness conglomerates are the most active acquirer in this space, consolidating backward integration into regional protein crop cultivation. Long-term viability centers on formulation science capabilities and captive distribution infrastructure rather than commodity trading positions. Monitor EU Deforestation Regulation enforcement rigor as the inflection indicator that will separate compliant compounders with traceable sourcing systems from stranded operators dependent on untraceable South American soy.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Protein Crops | Captive rapeseed and faba bean supply secures EU Deforestation Regulation compliance ahead of traceability mandates. |
| Ammonia-Based Cooling System Migration | Pre-starter feed manufacturers with temperature-sensitive plasma protein inclusions face steepest F-Gas Regulation compliance timelines. |
| Mobile Mill-to-Farm Distribution Deployment | Compressed lead times below six hours match integrated finisher service levels for independent Polish operations. |
| CSRD-Certified Low-Emission Positioning | Carbon footprint disclosure compliance unlocks premium procurement contracts with processor-aligned Dutch and Danish integrators. |
| Precision Nutrition Talent Acquisition | Danish and Dutch metabolizable energy modeling expertise concentration creates recruitment friction for expanding German and Spanish operations. |
Research Approach
Bottom-up finisher and sow operation modeling reconciled against top-down compound feed manufacturing capacity tracking forms the analytical core. Primary interviews with nutrition directors at integrated pork operations, procurement leads at cooperative purchasing groups, mill operations managers, and regulatory affairs specialists at formulators combined with secondary validation from EFSA contaminant threshold documentation, EU Feed Hygiene Regulation compliance records, customs trade data on soybean meal imports, and SEC filings of publicly listed agribusiness conglomerates. Triangulation between demand-side consumption patterns and supply-side production volumes resolves measurement discrepancies.
Historical trendline analysis of feed conversion ratio improvements and protein substitution rates established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type tier, ingredient composition, distribution channel configuration, and regional regulatory cluster. CAGRs derived from weighted average of historical momentum and policy-driven step changes in formulation requirements. Industry-specific forecast inputs incorporated pelleting technology upgrade cycles and hyperprolific sow genetic adoption curves.
Underlying measurement precision varies by segment; grower feeds and direct sales channels carry tighter precision than specialty pre-starter formulations and fragmented distributor-served independents. Forecasts reflect assumptions on EU Green Deal implementation pace and ECHA preservative authorization timelines. Material deviation in protein substitution rates or EU Deforestation Regulation enforcement rigor warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Squeeze Market
Livestock Management
Layer Breeding System Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Morocco Poultry Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Hog Production and Pork Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Bird Feeder Market
Livestock Management
Swine Feed Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Layer Feed Market