
 Africa Alfalfa Hay Market | 2026-2036
Africa Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Alfalfa Hay Market Outlook
Premium-grade alfalfa hay with protein content exceeding 18% is redrawing competitive boundaries across African livestock feed markets. Al Dahra ACX Global Inc. leverages integrated desert farming operations near the Nile Delta to sustain year-round supply consistency for Egyptian dairy cooperatives. Anderson Hay & Grain Inc. anchors its Africa presence through controlled-atmosphere shipping protocols that preserve leaf retention during extended transit to Mombasa and Dar es Salaam. Border Valley competes on small-bale packaging formats suited to emerging Kenyan horse breeding estates.
Alfalfa hay denotes dried perennial legume forage harvested at early bloom stage, typically containing 15-22% crude protein and 25-30% fiber on a dry-matter basis, produced through sun-curing or mechanical dehydration for protein-dense animal nutrition. Dairy farm end users occupy the dominant demand position given lactation-stage nutrient requirements that soybean meal alternatives struggle to match at comparable cost structures. Pelleted hay formats are gaining structural traction among commercial livestock feeders seeking reduced storage losses and standardized ration mixing, while dehydrated hay retains margin concentration in premium export channels serving Middle Eastern buyers.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces mycotoxin thresholds under agricultural product standards that directly determine which hay lots enter formal dairy supply chains. Kenya's Kenya Bureau of Standards operates parallel grading protocols for imported forage that classify shipments into utility grades affecting tariff treatment and retail positioning. Egypt's agricultural quarantine service under the Ministry of Agriculture mandates phytosanitary certification for cross-border hay movements that shapes regional trade corridor viability. Stakeholders must monitor evolving grade enforcement stringency and irrigation water access constraints as climate variability intensifies across East African production zones.
Market Dynamics
East African dairy cooperatives are consolidating feed procurement through centralized buying pools, compressing spot-market volumes and favoring suppliers with certified cold-chain logistics capable of delivering leaf-grade hay across the Rift Valley corridor.
Growth Catalysts
- Kenya Bureau of Standards grading protocols:Formal classification of imported forage into utility tiers creates transparent price discovery, accelerating commercial dairy farm participation in certified supply chains.
- Desert irrigation technology:Egyptian Nile Delta operators deploy drip-fed pivot systems that sustain triple-cut annual harvest cycles, securing protein consistency unavailable in rain-fed zones.
- Commercial feedlot expansion:Ethiopia's highland dairy corridor attracts integrated livestock investors requiring year-round protein-dense rations that open-field grazing cannot match.
Market Restraints
- Fertilizer input cost volatility:Egyptian alfalfa cultivation depends on imported urea and phosphate, exposing margin structures to currency fluctuation against the US dollar.
- Single-corridor supply concentration:Premium dehydrated hay flows predominantly through Alexandria port infrastructure, creating bottleneck vulnerability during seasonal phytosanitary inspection backlogs.
- Substitution by cottonseed cake:Oilseed processing byproducts from Sudan's Gezira Scheme offer comparable protein at lower unit cost for non-lactating stock.
Strategic Opportunities
- Tanzania's Southern Highlands:Underdeveloped dairy infrastructure in Mbeya and Iringa regions presents first-mover advantage for hay suppliers establishing depot networks ahead of cooperative formation.
- Pellet format penetration:Compact storage and mechanized ration mixing appeal to emerging commercial pig and poultry operations in Rwanda's Eastern Province.
- South African mycotoxin standards harmonization:Regional alignment of maximum allowable aflatoxin thresholds would unlock cross-border trade between Pretoria and Maputo dairy processors.
Industry Challenges
- Forage agronomy expertise scarcity:Optimal cutting-window determination and moisture management at harvest require specialized knowledge absent in extension services across Uganda's cattle corridor.
- Phytosanitary certification timeline compression:Egypt's agricultural quarantine service mandates 72-hour pre-shipment inspection windows that conflict with vessel scheduling at Damietta port.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Alfalfa Hay Market |
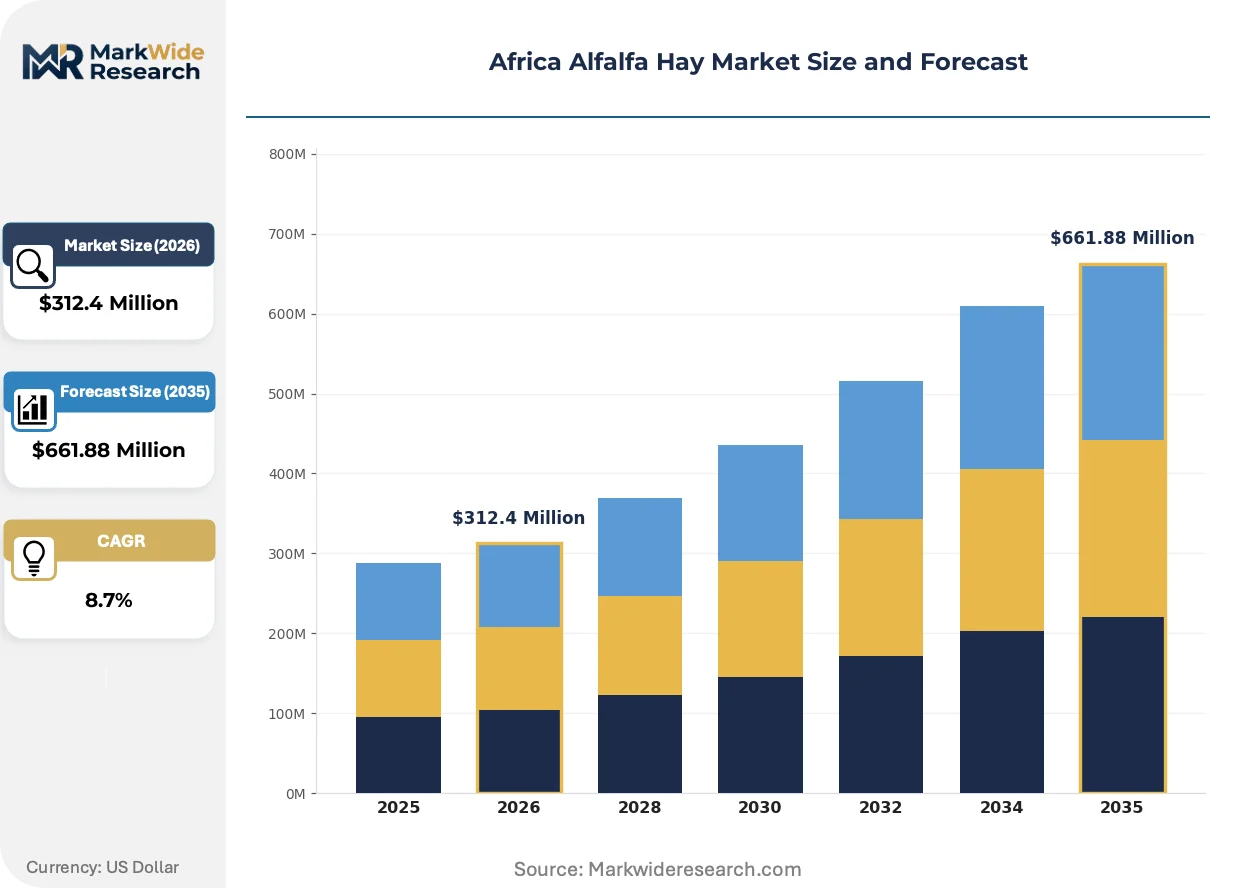
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Hay, Cubed Hay, Pelleted Hay, Chopped Hay End User: Dairy Farms, Livestock Feeders, Horse Breeders, Exporters Grade: Premium, Standard, Low Grade, Organic Distribution Channel: Direct Sales, Retail Stores, Online Sales, Wholesalers |
| Companies Covered | Al Dahra ACX Global Inc., Alfalfa Monegros SL, Border Valley, Bailey Farms, Anderson Hay & Grain Inc., Hill Top Farmers, J and Sharp Holdings Pty Ltd., Alpha Alfa, Halmac Trading, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Alfalfa Hay Market Strategic Shifts
Mechanical dehydration and controlled-atmosphere logistics are redrawing quality benchmarks across African hay supply chains, while regulatory grade enforcement and buyer consolidation reshape competitive access.
Mechanical dehydration systems utilizing rotary drum dryers are decomposing the historical dominance of sun-cured hay in premium export channels. Egyptian operators near Beni Suef deploy continuous-flow units that reduce moisture to 12% within four hours, preserving leaf retention rates above 90%. Dairy processors in the Gulf Cooperation Council now specify dehydrated origin in tender documents, compressing price premiums for traditional field-cured alternatives.
South Africa's Department of Agriculture enforces mycotoxin thresholds under agricultural product standards that determine formal market entry. Dairy supply chains in the Western Cape now reject hay lots exceeding 10 micrograms per kilogram total aflatoxin, forcing upstream suppliers to invest in pre-export testing infrastructure. Kenyan import inspectors are adopting comparable rapid-test protocols at Mombasa, accelerating regulatory convergence across the East African Community.
Centralized procurement through cooperative buying pools is displacing fragmented spot purchasing among medium-scale dairy farms. The Kenya Dairy Board's aggregation platforms now handle 40% of certified hay volumes in Nakuru and Kiambu counties, consolidating price-setting power. This concentration favors suppliers with integrated logistics capable of direct-to-silo delivery, marginalizing traditional broker intermediaries.
Africa Alfalfa Hay Market Segmentation
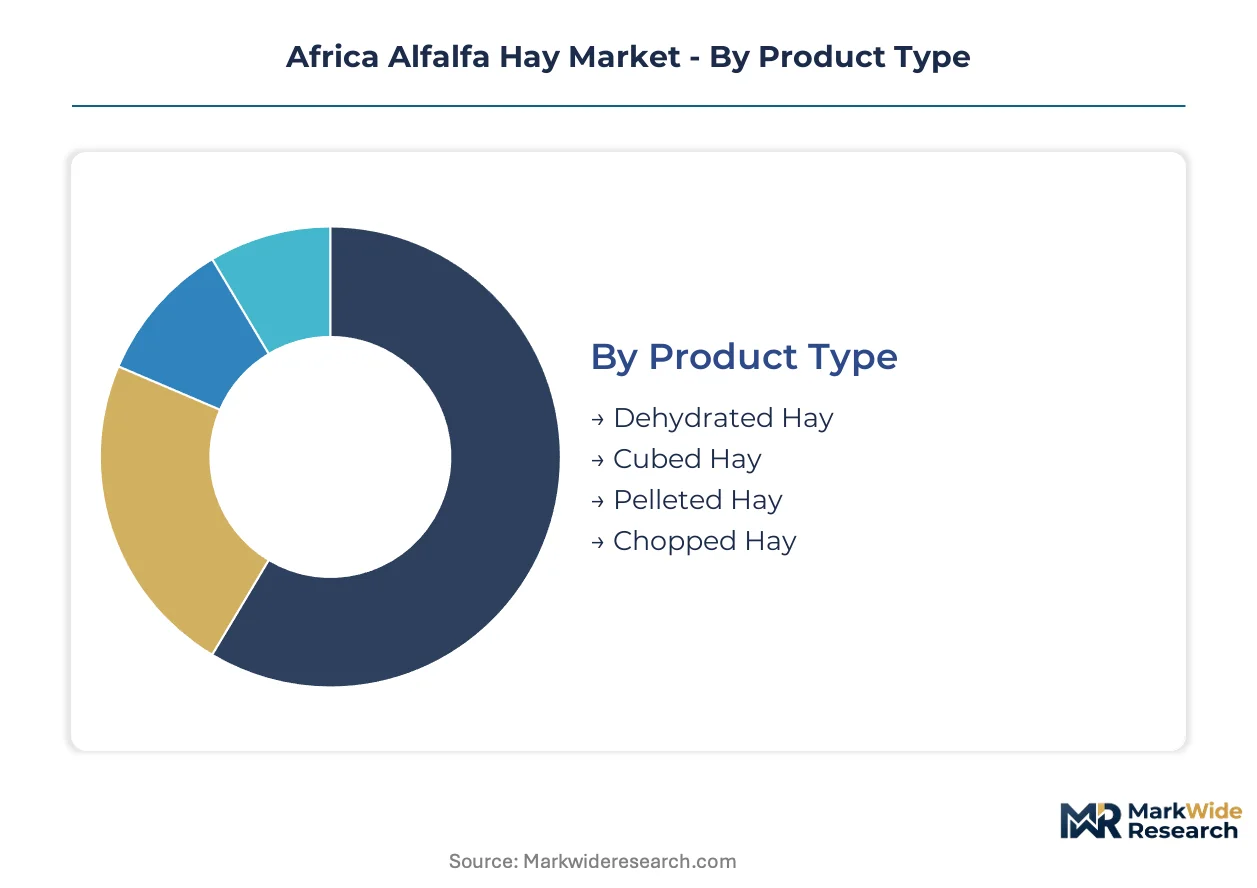
Segmentation across product formats, end-user requirements, and quality grades determines pricing power and logistics configuration for suppliers serving African livestock markets. Understanding how margin pools distribute across these dimensions clarifies where capital deployment yields sustainable returns versus commodity exposure.
Product Type:
Highest margins concentrate in mechanically processed formats where leaf retention and moisture control create export-grade specifications unavailable from field-cured alternatives.
- Dehydrated Hay:Rotary drum-dried product achieving 12% moisture within four hours, preserving 90% leaf retention. Egyptian Nile Delta operators supply Gulf Cooperation Council dairy processors who specify dehydrated origin in procurement tenders, commanding price premiums that sun-cured lots cannot match.
- Pelleted Hay:Ground and compressed cylinders reducing storage volume by 60% and enabling mechanized ration mixing. Commercial pig and poultry operations in Rwanda's Eastern Province are adopting pellet formats for standardized feed preparation, displacing loose hay in facilities with automated distribution systems.
- Cubed Hay:Compressed blocks suited to manual handling in smallholder dairy cooperatives lacking mechanized feed lines.
- Chopped Hay:Field-processed product serving price-sensitive beef feedlots in Ethiopia's highland corridor where labor costs offset mechanization advantages.
The dominant share belongs to Dehydrated Hay, while Pelleted Hay is expanding most quickly as commercial livestock operations mechanize.
End User:
Application-specific nutrient requirements and procurement scale create distinct service models across buyer categories.
- Dairy Farms:Lactation-stage operations require 18%+ crude protein to sustain milk yield targets that oilseed alternatives cannot match at comparable cost. Kenya's Rift Valley feedlot zones and Ethiopia's highland dairy corridor concentrate demand for certified leaf-grade hay with guaranteed mycotoxin compliance.
- Livestock Feeders:Commercial beef and small ruminant operations prioritize fiber content and bulk pricing over protein density. Feedlot operators in Tanzania's Southern Highlands source utility-grade hay through cooperative buying pools that consolidate spot-market volumes.
- Horse Breeders:Nairobi-area estates and South African thoroughbred operations demand dust-free small-bale packaging with consistent leaf-to-stem ratios.
- Exporters:Middle Eastern buyers specify phytosanitary certification and controlled-atmosphere shipping protocols that only integrated suppliers can fulfill.
Dairy Farms retain the largest procurement volumes, though Livestock Feeders are gaining share fastest as commercial feedlot investment accelerates.
Grade:
Regulatory enforcement of quality thresholds is compressing volumes available at lower tiers while concentrating margin capture at certified premium levels.
- Premium:Protein content exceeding 18% with total aflatoxin below 10 micrograms per kilogram, qualifying for formal dairy supply chains in South Africa's Western Cape and Kenya's Nakuru County. South Africa's Department of Agriculture, Land Reform and Rural Development enforces mycotoxin thresholds that reject non-compliant lots.
- Standard:Mid-tier product meeting basic nutritional specifications for non-lactating stock and backgrounding operations. Sudan's Gezira Scheme cottonseed cake competes aggressively in this tier through lower unit pricing.
- Low Grade:Field-cured hay with variable protein content serving subsistence producers outside formal certification systems.
- Organic:Cultivation without synthetic fertilizer or pesticide inputs, appealing to specialty dairy brands in Kenya's urban retail channels.
Premium grade commands the strongest pricing power, while Organic certification is climbing the fastest as consumer-facing dairy brands differentiate.
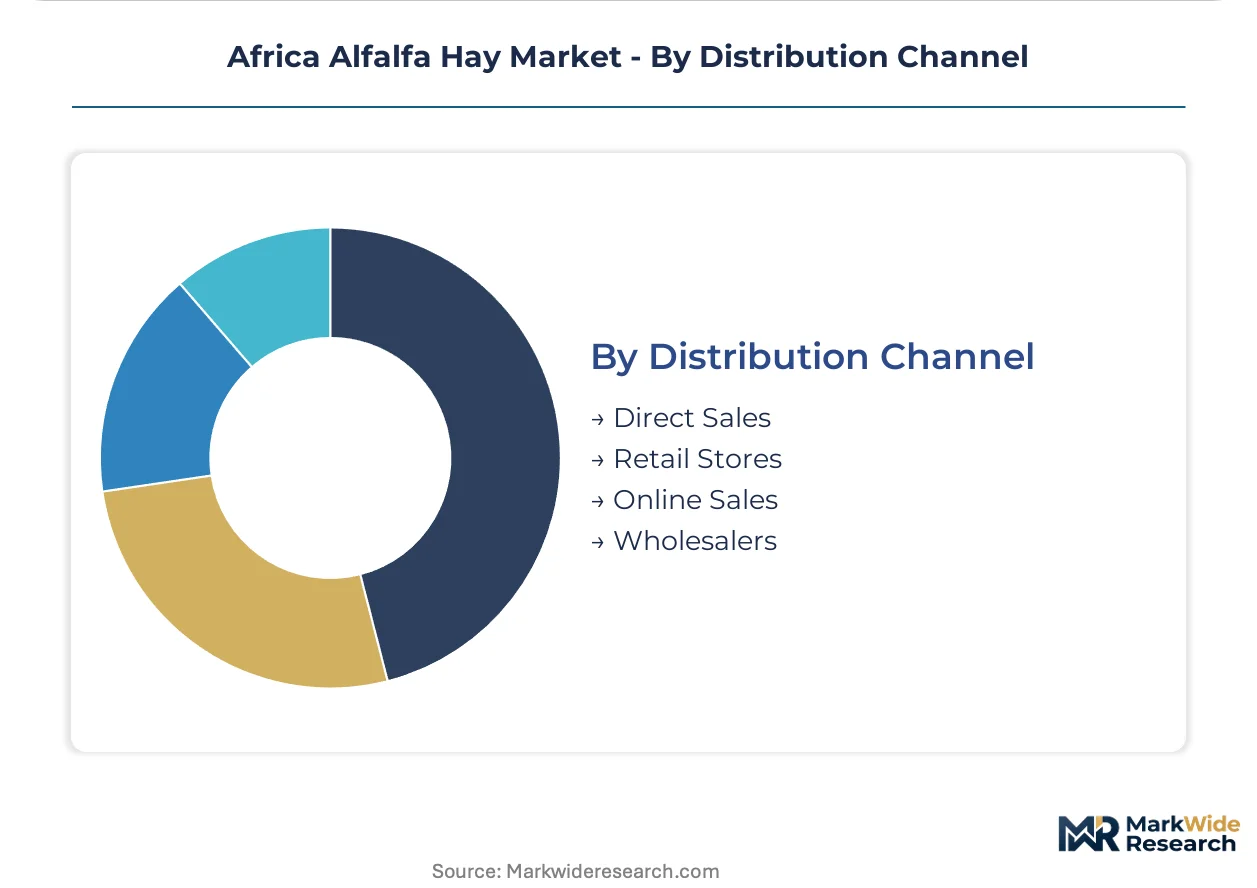
Distribution Channel:
Channel selection determines working capital intensity and customer intimacy trade-offs across supplier business models.
- Direct Sales:Supplier-to-farm relationships enabling customized delivery scheduling and silo-direct logistics. Kenya Dairy Board aggregation platforms now handle substantial certified hay volumes, consolidating procurement for medium-scale operations in Kiambu and Nakuru counties.
- Wholesalers:Regional depot networks bridging supply concentration in Egypt and South Africa with dispersed demand across East African Community markets.
- Retail Stores:Small-bale formats for hobby farmers and horse owners in South Africa's Gauteng province and Kenya's peri-urban zones.
- Online Sales:Emerging platform-based procurement for commercial feeders seeking price transparency, constrained by hay's bulk-to-value ratio and last-mile logistics costs.
Direct Sales captures the highest volume flows, with Wholesalers expanding fastest as regional trade corridor infrastructure improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa hay supply concentrates in Nile Delta irrigation zones and South African commercial farming belts, with demand radiating through East African dairy corridors. Regional trade flows follow phytosanitary certification corridors through Alexandria and Mombasa ports.
Egypt
Triple-cut annual harvest cycles from Beni Suef operators sustain protein consistency for Gulf Cooperation Council export contracts. The Ministry of Agriculture's agricultural quarantine service mandates 72-hour pre-shipment inspection windows that shape vessel scheduling at Damietta port. Desert farming operations near the Nile Delta deploy drip-fed pivot systems unavailable in rain-fed zones.
South Africa
Western Cape dairy processors enforce aflatoxin thresholds below 10 micrograms per kilogram, rejecting non-compliant hay lots from formal supply chains. The Department of Agriculture, Land Reform and Rural Development operates mycotoxin standards that determine market entry for upstream suppliers. Gauteng province hobby farmers and thoroughbred operations generate small-bale demand for dust-free packaging formats.
Kenya
Rift Valley feedlot zones and Nakuru County dairy cooperatives consolidate procurement through Kenya Dairy Board aggregation platforms handling certified hay volumes. The Kenya Bureau of Standards classifies imported forage into utility grades affecting tariff treatment and retail positioning. Kiambu county medium-scale operations increasingly demand direct-to-silo delivery capabilities.
Ethiopia
Highland dairy corridor attracts integrated livestock investors requiring year-round protein-dense rations that open-field grazing cannot match. Commercial feedlot expansion drives structural demand for 18%+ crude protein hay grades. Addis Ababa-area processors face supply bottlenecks during seasonal phytosanitary inspection backlogs at single-corridor entry points.
Tanzania
Mbeya and Iringa regions present first-mover advantage for depot network establishment ahead of cooperative formation. Southern Highlands dairy infrastructure remains underdeveloped relative to Kenyan and Ethiopian corridors. Dar es Salaam port receives controlled-atmosphere shipments preserving leaf retention during extended transit from Egyptian suppliers.
Africa Alfalfa Hay Market Competitive Environment
Concentration sits with integrated desert farming operators and controlled-atmosphere logistics specialists serving premium export channels. The competitive structure fragments between Egyptian Nile Delta producers with year-round irrigation capacity and South African operators leveraging established mycotoxin testing infrastructure. Two strategic archetypes dominate: vertically integrated farming-to-export platforms and specialized cold-chain logistics providers. Competitive moves center on phytosanitary certification pre-positioning and cooperative buying pool penetration.
Within the integrated farming tier, Al Dahra ACX Global Inc. and Anderson Hay & Grain Inc. exemplify archetypes combining production control with export logistics. Al Dahra ACX Global Inc. anchors Egyptian supply consistency through captive Nile Delta operations. Anderson Hay & Grain Inc. occupies a position emphasizing shipping protocol sophistication for leaf-grade preservation. Border Valley represents the specialized packaging segment serving niche horse breeding estates with format differentiation.
| Leading Market Players |
|---|
| Al Dahra ACX Global Inc. |
| Alfalfa Monegros SL |
| Border Valley |
| Bailey Farms |
| Anderson Hay & Grain Inc. |
| Hill Top Farmers |
| J and Sharp Holdings Pty Ltd. |
| Alpha Alfa |
| Halmac Trading |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Egyptian Nile Delta operators and Gulf Cooperation Council dairy processors lock in both supply access and price visibility, insulating premium dehydrated hay from spot-market volatility while compressing margins for uncertified field-cured alternatives.
Pricing Analysis
South Africa's Department of Agriculture, Land Reform and Rural Development dictates the pricing tier structure through enforced mycotoxin thresholds that reject non-compliant lots from formal dairy supply chains. Three-tier pricing structure across premium, standard, and economy levels separates certified 18%+ protein hay from utility-grade alternatives and ungraded field-cured product. Pricing pressure stems from Sudan's Gezira Scheme cottonseed cake substitution at comparable protein levels for non-lactating stock. Commercial dairy cooperatives exhibit lowest price sensitivity given lactation-stage nutrient requirements, while smallholder beef backgrounding operations in Ethiopia's highland corridor drive hardest bargaining on bulk utility grades.
Supply Chain Analysis
Egypt and South Africa anchor alfalfa hay production, with the Nile Delta's triple-cut irrigation systems and the Western Cape's mycotoxin-testing infrastructure supplying distinct market tiers. Egyptian cultivation draws from imported urea and phosphate, while South African operations rest on established fertilizer distribution networks. Single-corridor vulnerability concentrates at Alexandria and Damietta ports where phytosanitary inspection backlogs create seasonal bottlenecks. Distribution runs through cooperative buying pools in Kenya's Rift Valley and direct-to-silo arrangements for large-scale Ethiopian feedlot operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Kenya Dairy Board aggregation platforms and Ethiopian cooperative formation, shifting price-setting leverage from fragmented spot-market intermediaries toward consolidated procurement entities.
For Market Incumbents: Fortify cold-chain logistics capabilities across the Rift Valley corridor to preserve leaf retention rates above 90% during extended transit, while deepening backward integration into captive Nile Delta irrigation infrastructure to offset fertilizer cost volatility threatening margin stability. For New Entrants and Emerging Players: Depot network gaps in Tanzania's Southern Highlands present first-mover opportunity for suppliers establishing pre-cooperative distribution nodes ahead of formal dairy infrastructure development, with pellet-format penetration offering mechanized feed line compatibility for Rwanda's emerging commercial pig and poultry operations. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated farming-to-export platforms combining desert irrigation control with phytosanitary certification pre-positioning, with long-term viability hinging on regulatory convergence signals across the East African Community.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Logistics Investment | Anderson Hay & Grain Inc. protocols preserve leaf retention during Mombasa-Dar es Salaam transit corridors. |
| Cooperative Buying Pool Penetration | Kenya Dairy Board aggregation platforms now handle substantial certified hay volumes in Nakuru and Kiambu counties. |
| Mechanical Dehydration Capacity Addition | Beni Suef rotary drum systems reduce moisture to 12% within four hours for Gulf export specifications. |
| Phytosanitary Certification Pre-Positioning | Egypt's agricultural quarantine service mandates 72-hour pre-shipment inspection windows shaping vessel scheduling. |
| Pellet Format Manufacturing Scale-Up | Rwanda's Eastern Province commercial operations adopt compressed formats for automated distribution systems. |
Study Parameters
Initial hypotheses were tested against primary input from dairy cooperative procurement managers, alfalfa hay export logistics specialists, agricultural quarantine inspectors, and commercial feedlot nutritionists and refined through secondary validation against Kenya Bureau of Standards grading protocols, South African Department of Agriculture mycotoxin enforcement records, Egyptian Ministry of Agriculture phytosanitary certification timelines, and regional customs trade data. Bottom-up volume estimates from individual producer operations were triangulated against top-down demand calculations from dairy processor intake requirements.
Variance in projected values decomposes across product format segments, end-user categories, quality grade tiers, and distribution channel structures throughout the forecast period. CAGRs were derived from segmented growth trajectory modeling incorporating irrigation water access constraints, cooperative formation timelines, and regulatory enforcement stringency patterns. Industry-specific inputs include Nile Delta triple-cut harvest cycle yields and Rift Valley cold-chain logistics penetration rates.
Forecasts assume regulatory continuity in South African mycotoxin standards, Kenyan import grading protocols, and Egyptian phytosanitary certification regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in East African Community regulatory harmonization and cooperative buying pool consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Smart Feeding Systems Market
Livestock Management
Dairy Herd Management Market
Livestock Management
North America Feed Binders Market
Livestock Management
Poultry Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Livestock Dewormers Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Hog Production and Pork Market
Livestock Management
China Swine Feed Market
Livestock Management
Hominy Feed Market
Livestock Management
Layer Breeding System Market
Livestock Management
North America Swine Feed Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Equine Artificial Insemination Market