
 Canada Backyard Poultry Feed Market | 2026-2036
Canada Backyard Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Backyard Poultry Feed Market Outlook
Hobby farming is restructuring demand patterns across Canada's backyard poultry feed landscape. Cargill Inc leverages its national distribution network to reach remote rural co-ops and farm supply stores. Jones Feed Mills Limited anchors its position through Ontario-centric manufacturing and direct farm delivery channels. Country Junction Feeds differentiates via specialized small-batch formulations tailored to heritage breed nutrition.
Canada backyard poultry feed comprises nutritionally complete rations formulated with precise protein, calcium, and amino acid profiles to support egg production and bird health in non-commercial flocks. Manufacturers grind and pelletize grain bases—typically corn, soybean meal, and wheat—then fortify with vitamins, minerals, and occasional coccidiostats to meet CFIA-approved specifications. Layer feed dominates volume as hobby farmers prioritize consistent egg output over meat production cycles. Starter feed commands premium positioning due to higher protein formulations and smaller particle sizing requirements for chick development. Bulk packaging captures cost-conscious small-scale producers while 25 kg bags sustain retail channel margins through urban garden center placement.
Health Canada and the Canadian Food Inspection Agency jointly enforce feed safety standards, with CFIA's Feed Program mandating licensing for medicated feed manufacturers and strict label claims for antibiotic-free positioning. Provincial agricultural ministries in Ontario and British Columbia supplement federal rules with flock registration requirements and avian influenza biosecurity protocols that indirectly shape feed purchasing patterns. Stakeholders must monitor evolving municipal backyard chicken bylaws and potential restrictions on synthetic additive use that could force rapid reformulation investments.
Market Dynamics
Municipal backyard chicken bylaws are proliferating across Canadian cities, with Ontario and British Columbia municipalities issuing thousands of residential flock permits annually. This regulatory permissiveness is compressing the traditional farm-supply-to-consumer distribution chain and forcing feed manufacturers to develop urban-accessible packaging and retail placement strategies.
Growth Catalysts
- Heritage Breed Preservation:Rare breed conservation programs in Quebec and Alberta are driving demand for specialized nutrition formulations that support non-commercial genetic lines.
- CFIA Feed Program Licensing:Clear federal pathways for medicated feed approval are reducing manufacturer uncertainty and enabling new product development cycles.
- Urban Self-Sufficiency Movements:Vancouver and Toronto residents are establishing residential flocks at accelerating rates, creating concentrated demand pockets within metropolitan boundaries.
Market Restraints
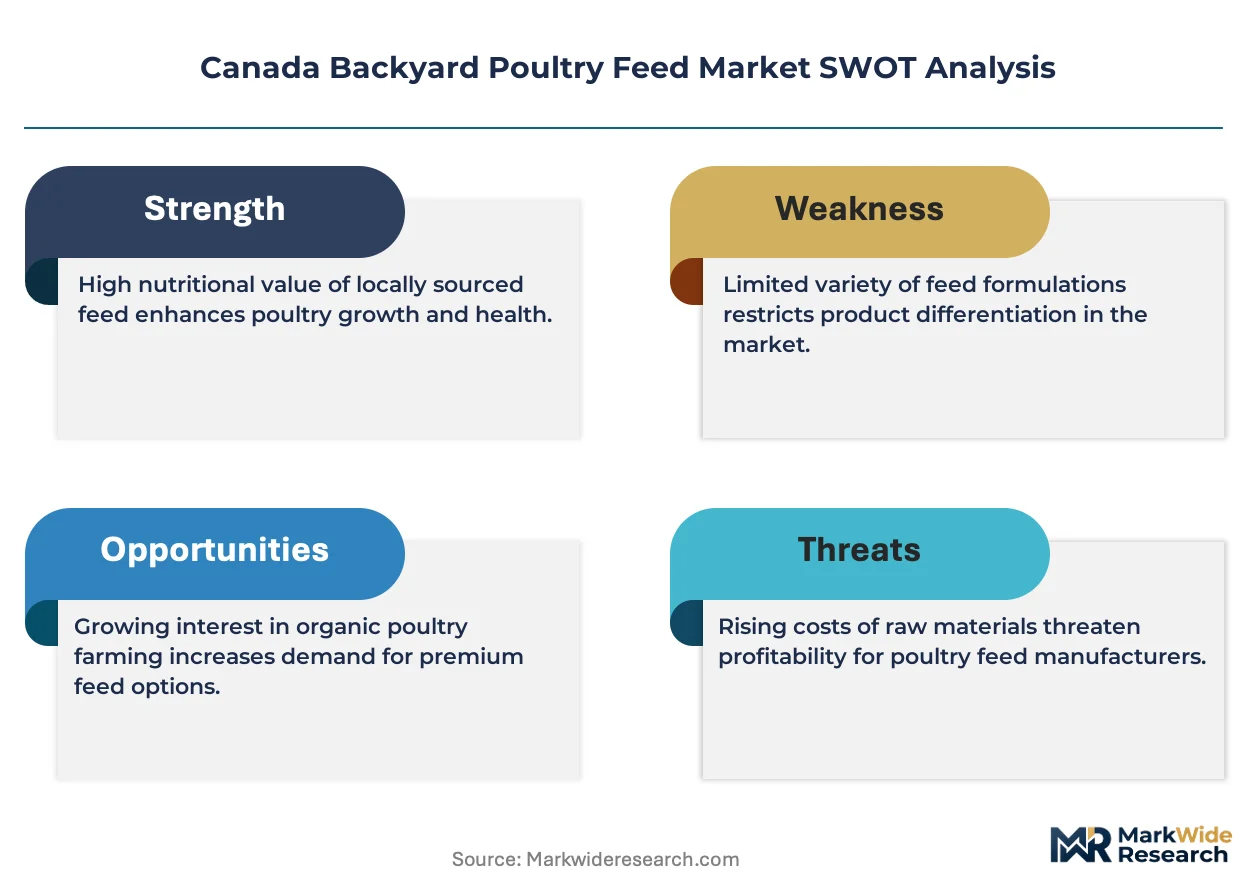
- Grain Input Volatility:Prairie drought cycles and international commodity price swings compress formulation margins for corn and wheat-based rations.
- Supply Concentration:Ontario's Golden Horseshoe hosts the majority of domestic feed milling capacity, exposing western provinces to freight cost premiums and delivery delays.
- Regulatory Friction:Health Canada's tightening disclosure requirements for synthetic additives force costly reformulation cycles before existing inventory depletes.
Strategic Opportunities
- Atlantic Canada Penetration:Nova Scotia and New Brunswick exhibit minimal commercial feed presence despite rising hobby farm registrations.
- Subscription Distribution Models:Direct-to-consumer delivery platforms are bypassing traditional farm supply store intermediaries in dense urban corridors.
- Organic Certification Tailwinds:Canada Organic Regime standards are creating price-premium positioning for additive-free layer formulations.
Industry Challenges
- Avian Influenza Biosecurity Compliance:Provincial flock registration mandates require traceability system investments that small-batch manufacturers struggle to fund.
- Formulation Talent Scarcity:Qualified poultry nutritionists concentrate in commercial broiler and layer operations, leaving backyard feed specialists competing for limited expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Backyard Poultry Feed Market |
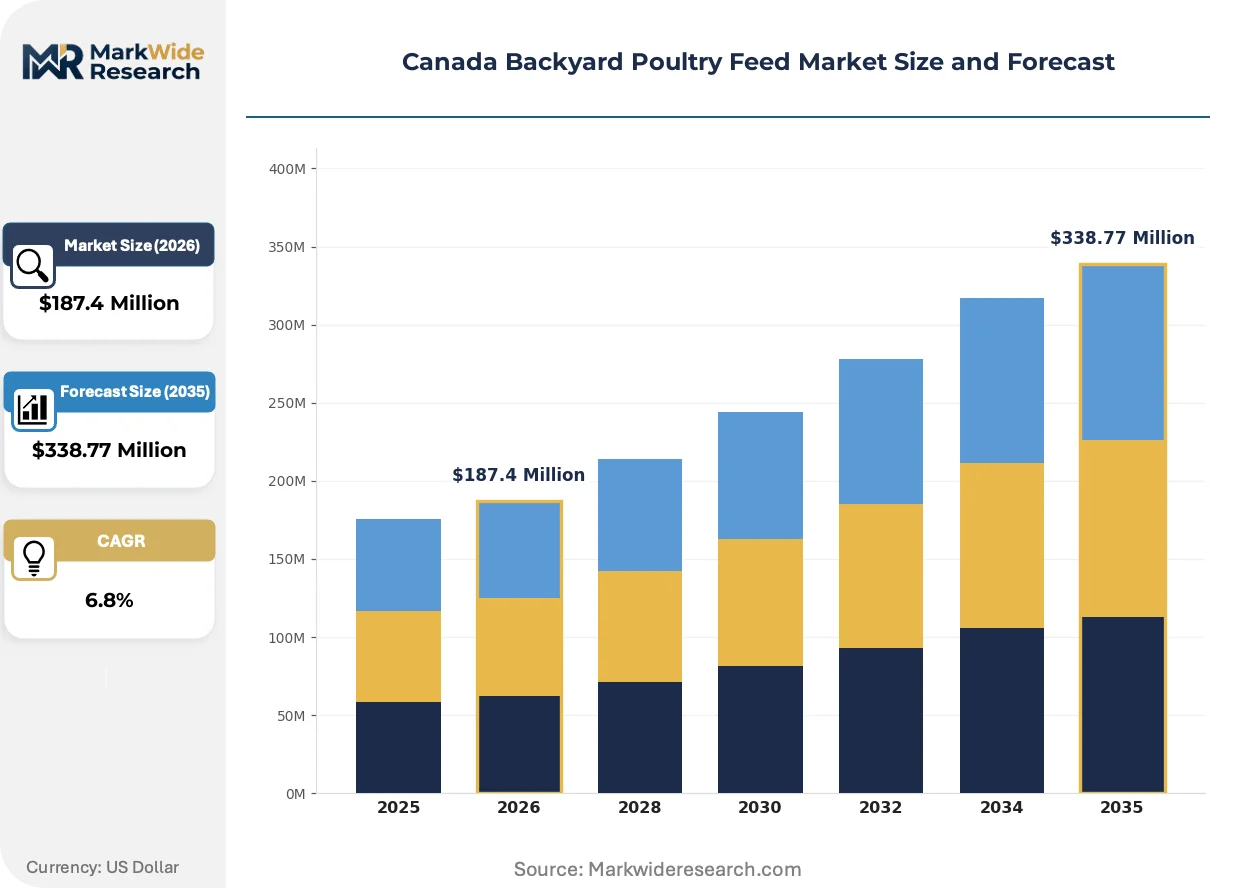
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer Feed, Broiler Feed, Starter Feed, Grower Feed Ingredient Type: Corn, Soybean Meal, Wheat, Rice Bran Packaging Type: 25 kg Bags, 50 kg Bags, Bulk, Pellets Customer Type: Hobby Farmers, Small Scale Producers, Commercial Growers, Retail Users |
| Companies Covered | Floradale Feed Mill Limited, Cargill Inc, ADM Animal Nutrition, Jones Feed Mills Limited, Country Junction Feeds, New Rosedale Feed Mill, Hi Pro Feeds, Nutreco Canada Inc., Shur-Gain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Backyard Poultry Feed Market Strategic Shifts
Precision nutrition and alternative protein sourcing are converging to reshape how Canadian manufacturers approach small-batch feed production. These developments are compressing the gap between commercial-grade formulations and backyard-specific products.
Black soldier fly larvae meal is expanding into heritage breed starter formulations as a sustainable protein alternative to soybean meal. Alberta-based hobby farmers are piloting these insect-based rations for chick development phases. The technology is expanding into Ontario's retail channel as garden centers seek differentiated premium offerings.
Health Canada's Feed Regulations are mandating granular ingredient disclosure that exceeds previous label standards. Manufacturers must now specify additive sources and inclusion rates with precision that challenges proprietary formulation practices. Layer feed producers in British Columbia are responding by simplifying recipes to reduce compliance documentation burdens.
Hobby farmers are consolidating purchases through cooperative buying groups that aggregate demand across municipal boundaries. These collectives negotiate direct manufacturer relationships that displace traditional farm supply store volume. The pattern concentrates in Fraser Valley municipalities where flock density supports viable group procurement thresholds.
Canada Backyard Poultry Feed Market Segmentation
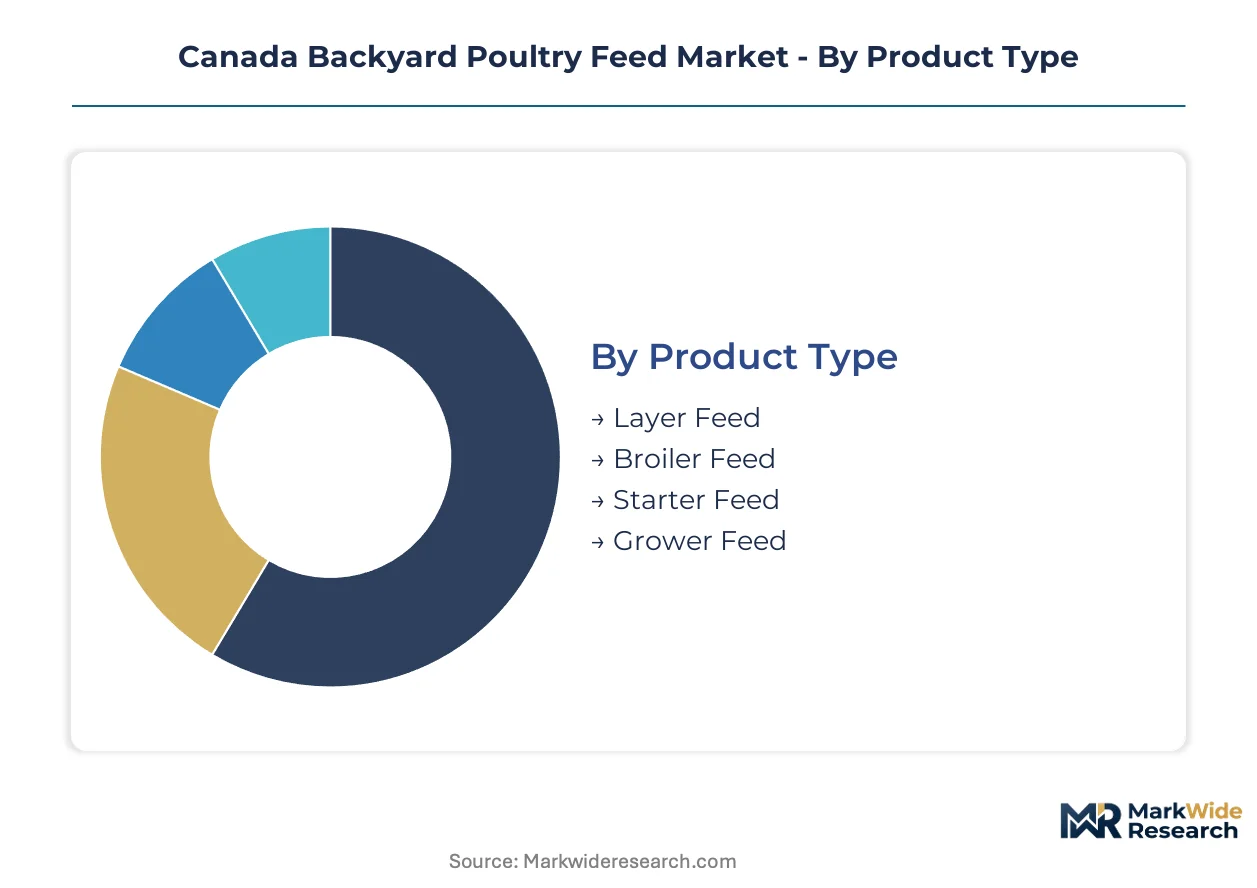
Backyard flock owners cycle through distinct nutritional formulations as birds mature from chicks to laying hens, creating predictable repurchase patterns that reward manufacturers with structured product portfolios. Segmentation clarity enables feed producers to align formulation investments with the upgrade triggers that drive hobby farmer purchasing decisions across Ontario and British Columbia.
Product Type:
Replacement cycles accelerate when hobby farmers transition birds between developmental stages, with each phase demanding precise nutrient recalibration.
- Layer Feed:Formulated with 16-18% protein and elevated calcium levels to sustain consistent egg production in mature hens. Demand clusters in Ontario's Golden Horseshoe where urban flock permits have proliferated, though British Columbia's Fraser Valley shows comparable consumption density among heritage breed enthusiasts.
- Starter Feed:Higher protein formulations at 20-24% support rapid chick development with finely ground particle sizing for immature digestive systems. Hobby farmers in Vancouver and Toronto metropolitan areas prioritize premium starter options, driving faster product turnover as new flock establishments surge.
- Broiler Feed:Energy-dense rations optimized for meat bird weight gain cycles rather than egg production.
- Grower Feed:Intermediate protein levels bridge starter and layer formulations during juvenile maturation phases.
Volume placements concentrate in Layer Feed; the faster expansion belongs to Starter Feed.
Ingredient Type:
Cost tier differentiation separates commodity grain formulations from premium heritage-focused alternatives, with input sourcing geography shaping regional availability.
- Corn:Primary energy source in Prairie-milled formulations, subject to drought cycle volatility that compresses manufacturer margins during poor harvest years. Ontario feed mills source corn through established supply agreements with southwestern provincial growers.
- Soybean Meal:Dominant protein input supplying essential amino acids for muscle and feather development. Demand from Quebec heritage breed conservation programs is climbing fastest as specialized nutrition requirements gain attention.
- Wheat:Alternative carbohydrate base preferred in some Prairie formulations for digestibility characteristics.
- Rice Bran:Niche fiber and fat supplement appearing in premium small-batch heritage formulations.
Cost-sensitive hobby farmers default to corn-soy formulations; the steepest expansion trajectory tracks soybean meal as protein quality awareness spreads.
Packaging Type:
Customer density and storage constraints determine packaging economics, with urban accessibility requirements fragmenting traditional bulk-dominant supply patterns.
- 25 kg Bags:Retail-optimized sizing for garden center placement and residential storage limitations. Vancouver and Toronto hobby farmers favor this format for its vehicle transportability and garage storage compatibility.
- Bulk:Ton-scale deliveries to multi-flock cooperatives and rural properties with dedicated feed storage infrastructure. Freight cost advantages sustain this channel in Ontario's Golden Horseshoe where flock density supports aggregation.
- 50 kg Bags:Mid-scale option for small-scale producers with modest flock counts.
- Pellets:Physical form specification rather than packaging, reducing waste and improving feed conversion efficiency.
Urban channel growth favors 25 kg Bags; rural cooperatives defend Bulk procurement for cost efficiency.
Customer Type:
Application maturity separates established commercial knowledge from novice hobbyist learning curves, with customer journey stage dictating formulation complexity tolerance.
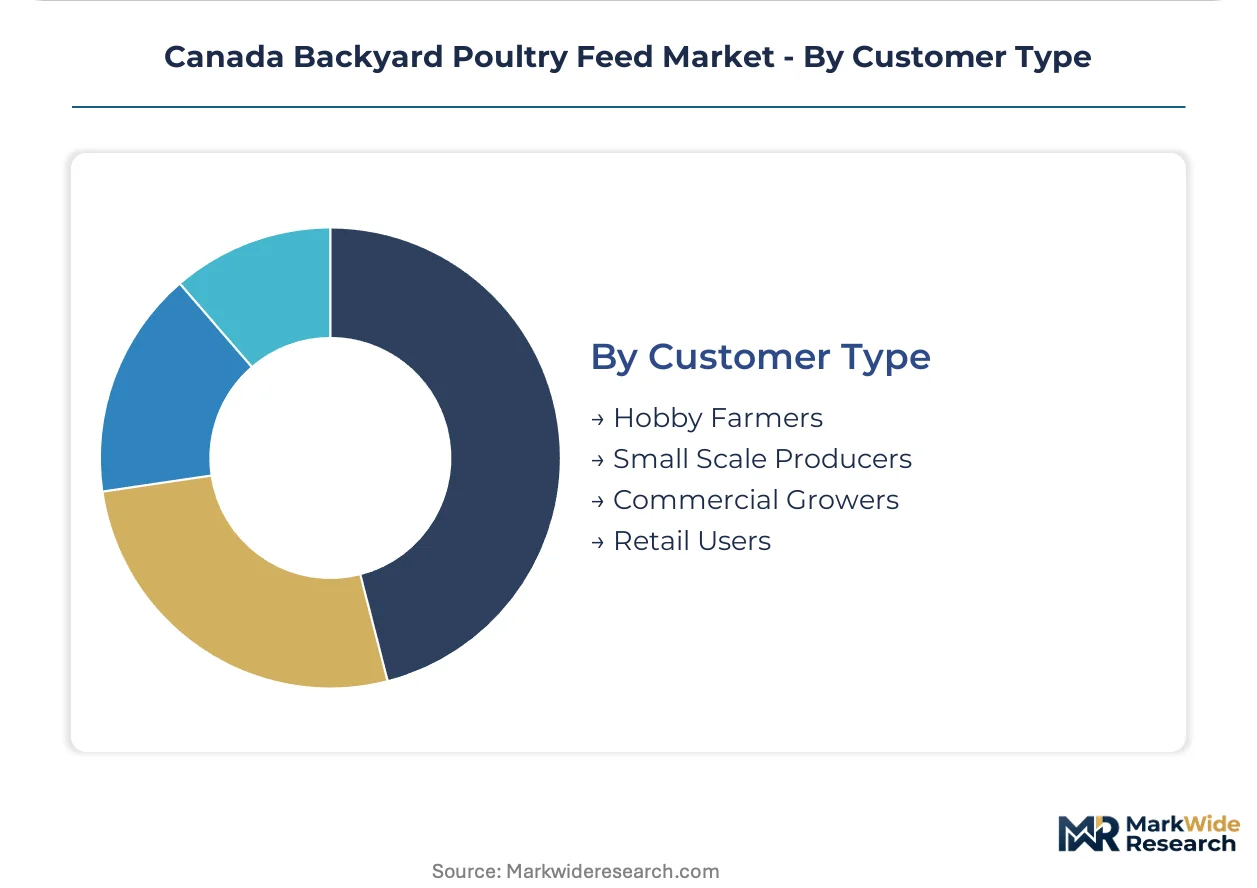
- Hobby Farmers:Urban and suburban flock owners prioritizing egg self-sufficiency and heritage breed engagement over production economics. Municipal permit proliferation across Ontario and British Columbia municipalities is expanding this segment most aggressively.
- Small Scale Producers:Rural property owners with 50-200 bird operations selling surplus eggs at farmers markets. Direct manufacturer relationships are displacing farm supply store intermediaries as this segment consolidates purchasing.
- Commercial Growers:Larger non-industrial operations with established veterinary relationships and biosecurity protocols.
- Retail Users:Occasional purchasers acquiring feed for single birds or temporary flock maintenance.
Established volume sits with Small Scale Producers; Hobby Farmers are gaining share fastest as urban self-sufficiency movements accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Golden Horseshoe special economic zone concentrates backyard poultry feed demand through municipal permit proliferation and urban self-sufficiency movements. Health Canada's Feed Regulations and CFIA oversight create compliance gravity that shapes manufacturer location decisions.
Ontario
Municipal flock permits across Toronto, Hamilton, and surrounding municipalities drive concentrated demand for 25 kg retail packaging. Health Canada's tightening ingredient disclosure requirements force reformulation investments from Ontario-based mills. The Golden Horseshoe corridor hosts the majority of domestic feed milling capacity, with direct farm delivery channels competing against urban garden center placement.
British Columbia
Vancouver metropolitan residents establish residential flocks at accelerating rates, creating dense demand pockets for premium starter formulations. CFIA's Feed Program licensing requirements apply uniformly, though provincial flock registration mandates add biosecurity compliance layers. Fraser Valley municipalities exhibit cooperative buying group formation that aggregates demand across municipal boundaries for bulk procurement leverage.
Quebec
Rare breed conservation programs drive specialized nutrition demand for heritage genetic lines requiring non-commercial formulations. The province's agricultural ministry supplements federal CFIA rules with additional traceability expectations. Montreal and Quebec City urban corridors show emerging flock permit activity, though density remains below Ontario and British Columbia levels.
Alberta
Prairie drought cycles introduce grain input volatility that compresses margins for corn-dependent formulations. Provincial hobby farm registrations climb, particularly around Calgary and Edmonton metropolitan zones. Black soldier fly larvae meal pilot programs among Alberta hobby farmers signal protein sourcing diversification.
Atlantic Canada
Nova Scotia and New Brunswick exhibit minimal commercial feed presence despite rising hobby farm registrations, creating penetration opportunities. CFIA regulations apply uniformly, though provincial agricultural extension services vary in flock support infrastructure. Halifax and Moncton urban areas show nascent municipal bylaw development for residential poultry keeping.
Canada Backyard Poultry Feed Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with national distributors commanding rural co-op channels while regional mills defend direct farm relationships. The vendor base concentrates around three strategic archetypes: integrated grain handlers with feed divisions, province-centric milling operations with delivery fleets, and small-batch heritage specialists. Capacity expansion and portfolio diversification dominate competitive moves as manufacturers respond to urban packaging requirements and organic certification tailwinds.
Within the national distribution tier, Cargill Inc leverages its grain origination infrastructure to supply remote rural markets through established co-op networks. Jones Feed Mills Limited anchors the Ontario-centric manufacturing archetype with direct delivery capabilities across the Golden Horseshoe. Country Junction Feeds exemplifies the heritage specialization vector through small-batch formulation expertise.
| Leading Market Players |
|---|
| Floradale Feed Mill Limited |
| Cargill Inc |
| ADM Animal Nutrition |
| Jones Feed Mills Limited |
| Country Junction Feeds |
| New Rosedale Feed Mill |
| Hi Pro Feeds |
| Nutreco Canada Inc. |
| Shur-Gain |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap mills across Ontario and Quebec anchor supply discipline through generational grain origination relationships, translating procurement stability into pricing power that resists commodity volatility. Their balance sheet conservatism limits distressed inventory sales, compressing spot-market discount availability and sustaining contract-premium structures for loyal farm accounts.
Pricing Analysis
Short-lead-time premiums dominate pricing architecture as Ontario hobby farmers pay markups for garden-center accessibility versus bulk-contract discounts available to multi-flock cooperatives. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels segments buyers by certification awareness and flock scale. Pricing pressure intensifies in the economy tier as Prairie drought cycles elevate corn and wheat input costs without commensurate retail price recovery. Small-scale producers exhibit highest price sensitivity, while heritage breed enthusiasts absorb organic premiums with minimal volume elasticity.
Supply Chain Analysis
Reverse-logistics flows remain minimal as feed freshness requirements preclude returns, though empty bulk tote reclamation programs operate across Fraser Valley cooperatives. Supply concentrates in Ontario's Golden Horseshoe, with secondary milling presence in Alberta and Quebec. Corn, soybean meal, and wheat constitute the foundational input triad, drawing from Prairie harvest cycles and international commodity markets. Single-source vulnerability concentrates in Ontario's transport-dependent western distribution, where freight cost premiums erode margin. Distribution runs through farm supply store intermediaries in rural corridors, with direct-to-cooperative channels gaining share in urban-adjacent municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision nutrition platforms are displacing legacy one-size-fits-all formulations as black soldier fly protein and customized amino acid profiling redefine feed value propositions.
For Market Incumbents: Anticipate displacement from insect-protein specialists by securing exclusive Alberta larvae supply contracts and accelerating CFIA-approved medicated feed licensing. Channel control through cooperative buying group penetration offers defensive leverage against direct-to-consumer entrants. Vertical integration into Prairie grain origination buffers margin compression from drought-driven input volatility. For New Entrants and Emerging Players: Begin with Atlantic Canada penetration where Nova Scotia and New Brunswick exhibit minimal commercial feed presence despite climbing hobby farm registrations. Subscription distribution models targeting Vancouver and Toronto metropolitan corridors offer the most penetrable white space, bypassing entrenched farm supply store relationships. Heritage breed specialization provides differentiation leverage against commodity-focused incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor Ontario-centric milling assets with established direct delivery fleets during Prairie drought compression phases. Long-term viability hinges on organic certification infrastructure and urban packaging adaptability. Monitor municipal bylaw proliferation rates as inflection indicators for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Insect Protein Integration | Black soldier fly larvae meal diversifies protein sourcing beyond soybean dependence. |
| Organic Certification Investment | Canada Organic Regime compliance unlocks premium positioning in Fraser Valley. |
| Subscription Distribution Launch | Direct-to-consumer platforms bypass farm supply store intermediaries in dense urban corridors. |
| Atlantic Canada Manufacturing Footprint | Nova Scotia and New Brunswick penetration captures underaddressed hobby farm demand. |
| Cooperative Buying Group Partnership | Fraser Valley aggregation models secure volume commitments and displace retail channels. |
Study Parameters
Multi-period observation of municipal flock permit issuance, grain futures pricing, and heritage breed registration trends anchored the trend analysis, supplemented by interviews with feed mill operations managers, provincial agricultural extension officers, garden center category buyers, and CFIA compliance specialists. Secondary validation drew from Health Canada Feed Regulations filings, Canadian Grain Commission harvest reports, Statistics Canada agricultural census data, and municipal bylaw databases. Bottom-up volume triangulation across product type, packaging format, and customer segment converged with top-down macroeconomic calibration.
Input-output matrices modeled feed consumption coefficients against flock population projections across the analysis window, with segmentation dimensions spanning product life-cycle stage, ingredient certification tier, packaging accessibility grade, and customer sophistication level. CAGRs were derived from regression-based trend extrapolation moderated by regulatory event probabilities and commodity cycle phase assumptions. Forecast inputs incorporated Prairie precipitation indices and municipal bylaw adoption elasticity parameters.
Underlying measurement precision varies by segment; layer feed volume estimates carry tighter precision than heritage breed specialty formulations due to standardized consumption coefficients. Forecasts embed assumptions regarding CFIA disclosure requirement implementation timing and drought frequency patterns. Practitioners should monitor municipal permit issuance velocity and black soldier fly protein cost parity thresholds for early demand shift signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Organic Hemp Market