
 South America Ruminant Feed Premix Market | 2026-2036
South America Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ruminant Feed Premix Market Analytics
Modular premix bundling is decoupling from traditional complete feed packages across South America, letting buyers customize mineral and vitamin ratios independently. Cargill Incorporated leverages its Brazilian manufacturing footprint to supply modular mineral premixes at scale. Nutreco NV anchors its regional position through R&D intensity in rumen-protected nutrient delivery. BASF SE differentiates via specialty additive premixes targeting mycotoxin mitigation in humid subtropical zones.
Ruminant feed premix denotes a concentrated blend of vitamins, minerals, amino acids, and functional additives mixed at inclusion rates between 0.5% and 3% of total ration weight, manufactured via sequential micro-dosing and thermal-stabilized coating to preserve bioactive potency during pelleting. Its primary purpose is to close nutritional gaps in basal forage or grain diets, thereby optimizing feed conversion efficiency and reproductive performance in cattle, sheep, and goat operations. Mineral premixes occupy the dominant value share given Brazil's widespread phosphorus and selenium deficient soils, while additive premixes represent the fastest-expanding margin pool as producers adopt yeast derivatives and organic trace minerals to reduce antibiotic dependency. Dairy cattle application leads volume demand, though beef cattle premix adoption is accelerating in Argentina's feedlot sector where finishing diets require precise micronutrient calibration.
ANVISA in Brazil and SENASA in Argentina enforce feed additive registration and maximum residue limits that shape product formulation portfolios and import approval timelines across the region. Brazil's MAPA traceability mandates and the Mercosur harmonized feed safety protocol are tightening compliance costs for premix suppliers while advantaging certified domestic manufacturers. Stakeholders must monitor evolving probiotic and enzyme classification debates under ANVISA's novel feed additive pathway, as reclassification could unlock or constrain entire additive premix segments.
Market Dynamics
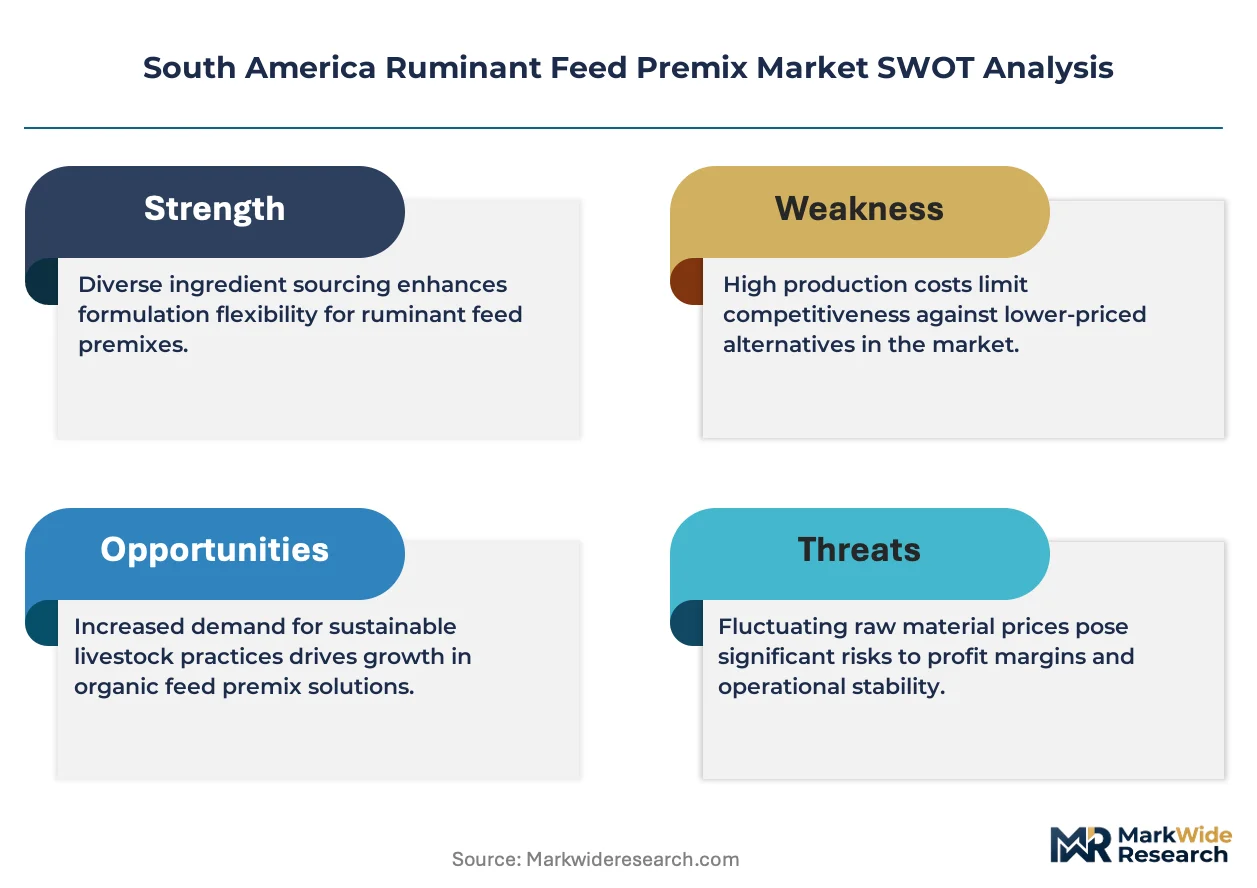
Brazil's MAPA traceability mandates and ANVISA's novel feed additive pathway are forcing premix suppliers to restructure formulation portfolios and compliance investments, compressing margins for uncertified operators while advantaging domestic manufacturers with established regulatory infrastructure.
Growth Catalysts
- Mineral deficiency correction:Brazil's phosphorus and selenium deficient soils drive mandatory mineral premix supplementation across dairy and beef operations, creating baseline demand that expands with herd size growth.
- ANVISA's probiotic reclassification pathway:Brazil's national health surveillance agency is evaluating yeast derivatives and direct-fed microbials under novel feed additive rules, potentially unlocking entire additive premix segments previously restricted.
- Argentina feedlot sector expansion:Precision finishing diets in the Pampas region require calibrated micronutrient premix protocols, accelerating beef cattle premix adoption beyond traditional dairy concentration.
Market Restraints
- Input cost volatility:Organic trace minerals and rumen-protected amino acids face price swings tied to global specialty chemical supply chains, squeezing premix formulation margins.
- Mercosur harmonization friction:Divergent implementation timelines between Brazil's MAPA and Argentina's SENASA on feed safety protocols create cross-border compliance complexity for regional suppliers.
- Antibiotic alternative performance gap:Yeast derivatives and organic acids substitute for growth promoters with variable efficacy across humid subtropical conditions, limiting producer willingness to pay premium additive premix prices.
Strategic Opportunities
- Paraguay and Uruguay underpenetration:Smaller Mercosur members lack domestic premix manufacturing infrastructure, creating import substitution openings for Brazilian certified suppliers with regional logistics networks.
- Modular premix unbundling:Large cooperatives in Brazil's southeastern dairy belt are decoupling mineral and vitamin procurement from complete feed packages, enabling independent ratio customization and direct supplier relationships.
- Mycotoxin mitigation specialization:Humid subtropical storage conditions across the region amplify aflatoxin and fumonisin risk, creating demand pull for specialty additive premixes with binding and biotransformation claims.
Industry Challenges
- Rumen nutrition specialist scarcity:Formulating effective rumen-protected nutrient delivery requires cross-disciplinary expertise in microbiology and animal physiology that outpaces regional university program output.
- Thermal-stabilized coating capex:Preserving bioactive potency during pelleting demands spray-drying and micro-encapsulation equipment investments that strain mid-scale premix manufacturer balance sheets.
- ANVISA registration timeline uncertainty:Novel enzyme and probiotic approvals face unpredictable review durations, complicating product launch planning and inventory positioning for additive premix portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ruminant Feed Premix Market |
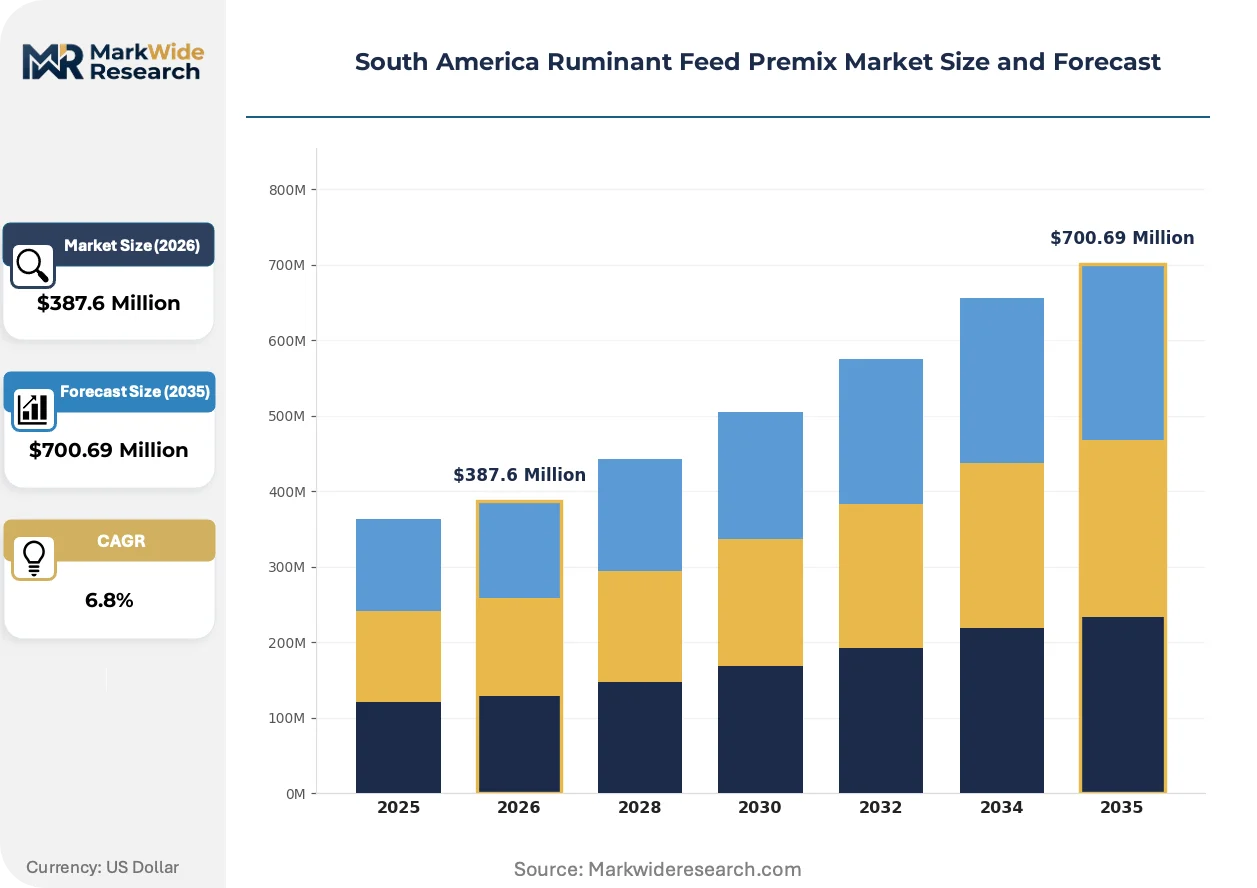
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premixes, Vitamin Premixes, Additive Premixes, Complete Feed Premixes Application: Dairy Cattle, Beef Cattle, Sheep, Goats Distribution Channel: Online Retail, Direct Sales, Distributors, Agrochemical Stores End User: Farmers, Feed Manufacturers, Livestock Producers, Veterinarians |
| Companies Covered | Nutreco NV, Lallemand Inc, Cargill Incorporated, Royal Agrifirm Group, Land O'Lakes Inc, BASF SE, ICC, Cladan Animal Nutrition, CCPA GROUP, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ruminant Feed Premix Market Evolving Landscape
Sequential micro-dosing and thermal-stabilized coating technologies are reshaping premix manufacturing economics, while regulatory classification debates and cooperative procurement consolidation are restructuring how micronutrients reach South American ruminant operations.
Precision micro-dosing systems are unifying vitamin, mineral, and additive inclusion into single-pass manufacturing workflows. Large-scale cooperatives in Brazil's southeastern dairy belt are adopting these systems at accelerating pace. This technology is unifying previously separate premix production lines, compressing capital requirements for multi-species formulation flexibility and enabling smaller batch sizes without efficiency loss.
ANVISA's evolving stance on direct-fed microbials and enzyme classifications is creating formulation portfolio uncertainty across Brazil. Suppliers must maintain dual-track R&D investments pending regulatory clarity on whether specific strains require pharmaceutical or feed additive registration. Dairy cattle premix portfolios face the highest exposure, with several major cooperatives delaying yeast derivative expansion until classification pathways stabilize.
Cooperative procurement consolidation is compressing supplier counts and extending contract durations across Brazil's dairy belt. Volume aggregation by large-scale operations is displacing fragmented distributor networks with direct manufacturer relationships. Argentina's feedlot sector shows parallel concentration, though with greater reliance on integrator-mediated supply chains rather than cooperative structures.
South America Ruminant Feed Premix Market Segmentation
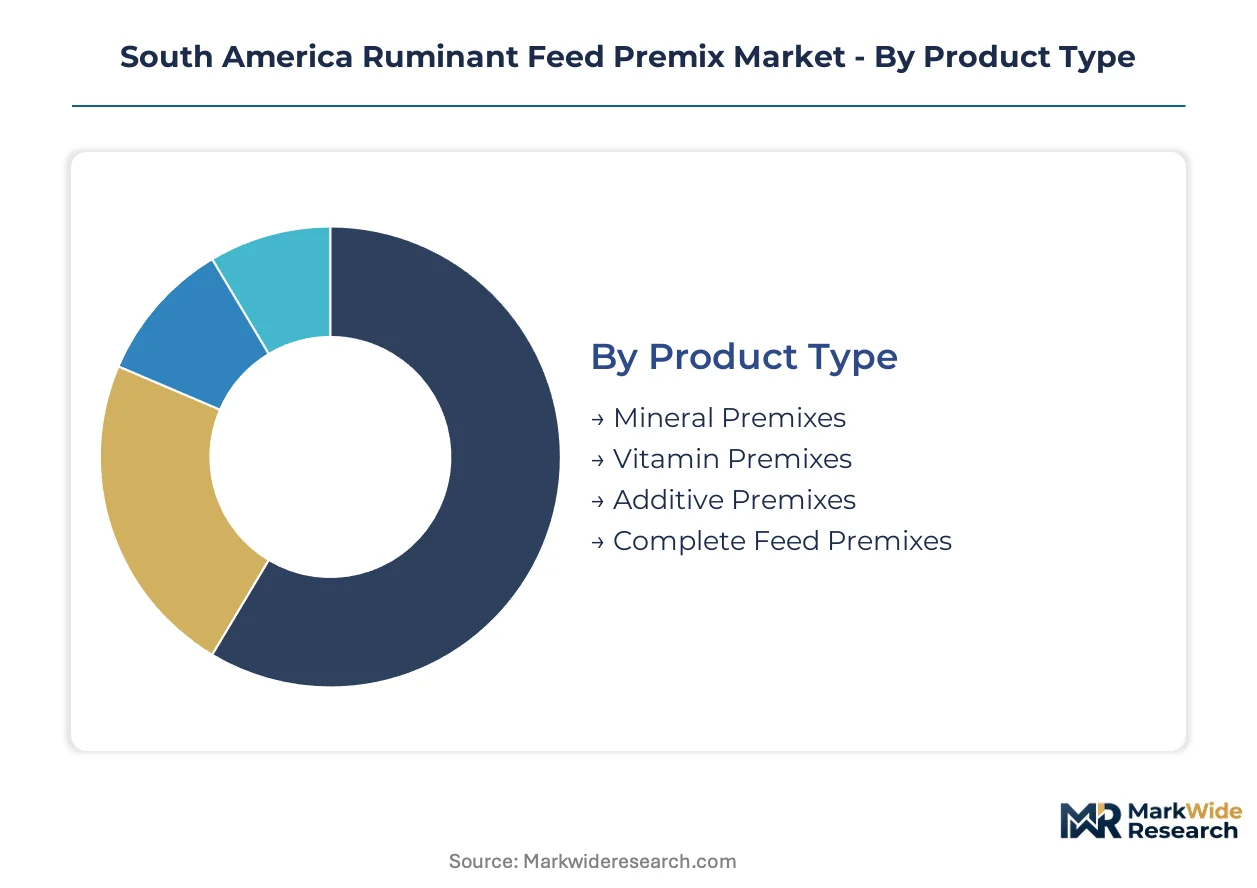
Segmentation in the South America ruminant feed premix market reveals distinct integration patterns across product formulations, species applications, and procurement channels. Understanding these divisions exposes where value concentrates and how regulatory pressure reshapes supplier relationships across Brazil, Argentina, and neighboring Mercosur markets.
Product Type:
Integration depth varies sharply across premix categories, with standalone mineral formulations dominating independent procurement while complete packages retain embedded channel relationships.
- Mineral Premixes:Concentrated blends of macro and trace minerals calibrated to correct phosphorus and selenium deficiencies endemic to Brazilian soils. Demand concentrates in São Paulo and Minas Gerais dairy cooperatives where large-scale operations bypass complete feed suppliers to customize ratios independently. MAPA certification requirements advantage domestic manufacturers with established testing infrastructure.
- Additive Premixes:Functional blends incorporating yeast derivatives, organic acids, and mycotoxin binders delivered via rumen-protected coating technologies. Argentina's expanding Pampas feedlot sector drives fastest adoption as finishing protocols reduce antibiotic dependency. ANVISA's pending probiotic reclassification creates formulation portfolio uncertainty.
- Vitamin Premixes:Thermal-stabilized fat- and water-soluble vitamin complexes dosed between 0.5% and 2% inclusion rates.
- Complete Feed Premixes:Fully formulated micronutrient packages bundled with protein and energy bases, still preferred by smaller Brazilian operations lacking in-house nutrition expertise.
Mineral premixes lead volumes today; additive premixes are gaining share fastest.
Application:
Species-specific nutrition requirements create divergent margin structures, with dairy operations commanding premium formulation services and beef feedlots driving volume throughput.
- Dairy Cattle:Precision micronutrient protocols targeting reproductive performance and milk component optimization in high-producing Holstein and crossbred herds. Brazil's southeastern dairy belt concentrates demand, where cooperative consolidation enables direct manufacturer relationships and extended contract terms.
- Beef Cattle:Finishing diet calibration for feedlot operations requiring precise trace mineral and vitamin ratios to maximize feed conversion. Argentina's Pampas region shows steepest adoption acceleration as export-oriented operations professionalize nutrition management.
- Sheep:Seasonal supplementation focused on breeding and lactation periods, with Patagonian operations in Argentina representing concentrated demand pockets.
- Goats:Niche premix formulations targeting smallholder dairy operations across Brazil's northeast and Paraguay's Chaco region.
Dairy cattle applications anchor current value; beef cattle premix adoption is climbing the fastest.
Distribution Channel:
Channel structure reflects farm scale stratification, with direct sales capturing cooperative volume and distributor networks retaining fragmented smallholder access.
- Direct Sales:Manufacturer-to-producer relationships eliminating intermediary margins, dominant among Brazil's large-scale dairy cooperatives with certified nutrition staff. Cargill and Nutreco anchor positions through dedicated technical service teams.
- Distributors:Regional warehousing networks serving mid-scale operations across Brazil's interior and Argentina's provincial feedlot sectors, consolidating fragmented demand into volume procurement.
- Agrochemical Stores:Rural retail points capturing smallholder premix purchases alongside crop inputs, prevalent in Paraguay and Uruguay where dedicated feed distribution infrastructure remains underdeveloped.
- Online Retail:Emerging channel for standardized mineral premixes in Brazil's southern states, constrained by ANVISA documentation requirements for additive-containing formulations.
Direct sales channels command the largest transaction values today; online retail is expanding most quickly in Brazil's southern tier.
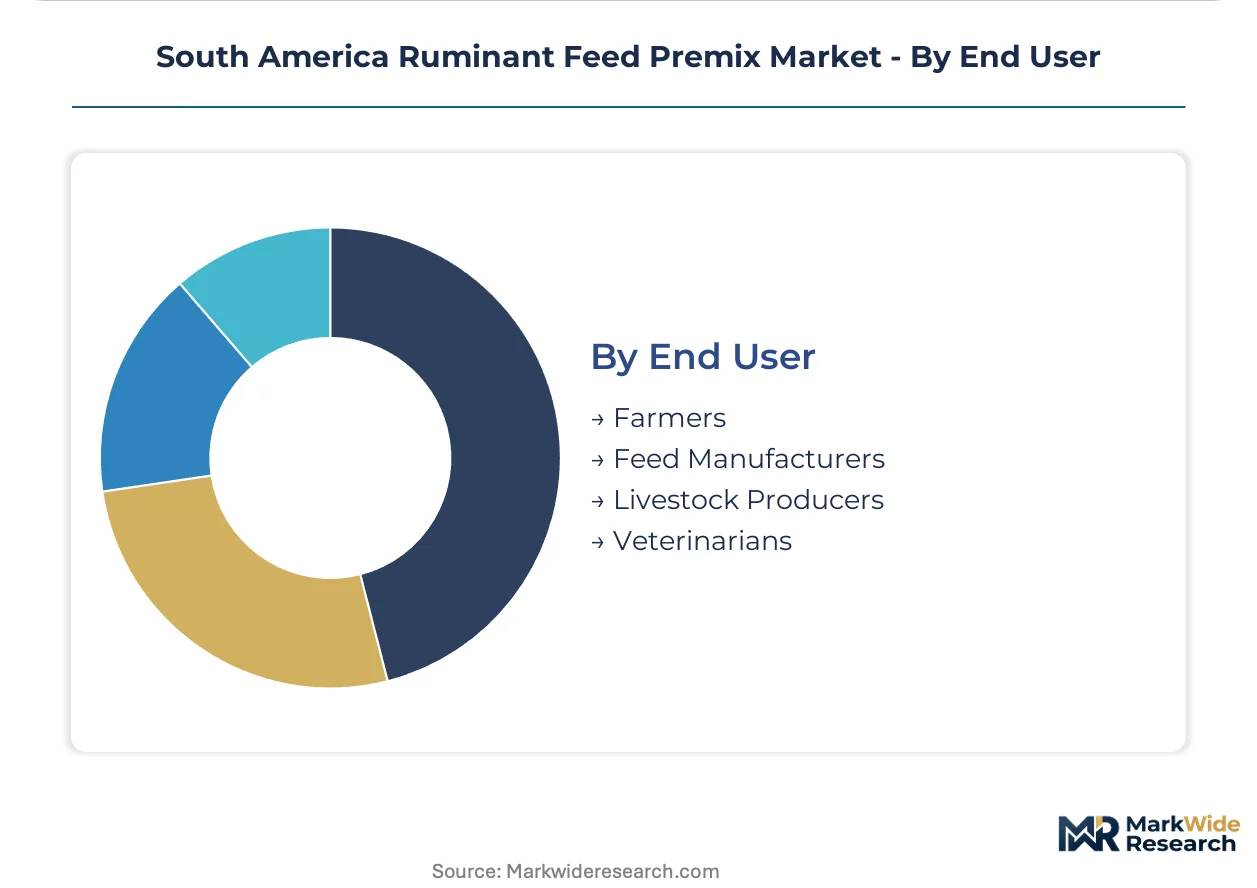
End User:
End-user sophistication determines formulation complexity, with feed manufacturers demanding bulk mineral inputs and livestock producers seeking turnkey additive solutions.
- Feed Manufacturers:Industrial-scale buyers of base mineral and vitamin premixes for integration into complete feed production, concentrated in Brazil's São Paulo state and Argentina's Santa Fe province.
- Livestock Producers:Direct premix purchasers among large-scale dairy and beef operations with in-house nutrition capabilities, driving modular unbundling trends across the Mercosur region.
- Farmers:Small-to-mid-scale operations relying on distributor-mediated supply chains and standardized premix recommendations.
- Veterinarians:Specialized channel for therapeutic additive premixes and mycotoxin mitigation products, particularly in humid subtropical zones with elevated aflatoxin risk.
Feed manufacturers represent the largest procurement volumes today; livestock producers are gaining share fastest through direct sourcing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered industrial-scale premix manufacturing in South America during the 1990s, establishing the regulatory and technical foundations that neighboring markets later adopted. Argentina's feedlot professionalization and Paraguay's import-dependent operations now represent distinct demand profiles across the Mercosur region.
Brazil
São Paulo and Minas Gerais dairy cooperatives drive mineral premix volumes as large-scale Holstein operations customize phosphorus and selenium ratios independently. MAPA's traceability mandates and ANVISA's novel feed additive pathway compel certified domestic manufacturers to restructure formulation portfolios. The southeastern dairy belt concentrates procurement power through cooperative consolidation, displacing fragmented distributor networks with direct manufacturer relationships.
Argentina
Pampas feedlot expansion accelerates beef cattle premix adoption as export-oriented operations professionalize finishing diet calibration. SENASA enforces feed additive registration and maximum residue limits that shape import approval timelines and local formulation requirements. Santa Fe province anchors industrial feed manufacturing, with provincial feedlots demanding precise micronutrient protocols for feed conversion optimization.
Paraguay
Chaco region goat and cattle operations create niche premix demand lacking domestic manufacturing infrastructure. The country's national agricultural regulator maintains import-dependent supply chains for certified mineral and vitamin formulations. Asunción-based distributors consolidate fragmented smallholder purchases into volume procurement from Brazilian certified suppliers.
Uruguay
Pastoral beef and dairy systems in the southern departments generate seasonal supplementation demand without dedicated premix production capacity. Mercosur harmonized feed safety protocol implementation lags behind Brazilian and Argentine timelines, extending import clearance durations. Montevideo serves as the logistics hub for distributor-mediated supply chains reaching mid-scale livestock operations.
Chile
Patagonian sheep operations and central valley dairy clusters drive concentrated demand pockets for breeding and lactation premix protocols. The country's national agricultural service enforces residue monitoring that shapes additive formulation acceptance. Santiago-based feed manufacturers integrate imported mineral and vitamin premixes into complete feed production for domestic livestock producers.
South America Ruminant Feed Premix Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and technical service capabilities, with ANVISA-registered domestic manufacturers capturing cooperative direct sales while uncertified operators retreat to distributor channels. The market exhibits tiered consolidation: multinational nutrition companies with Brazilian manufacturing footprints occupy the premium tier, regional Mercosur specialists serve mid-scale feedlot integrators, and local blenders compete on price for fragmented smallholder demand. Strategic moves concentrate on modular premix unbundling to bypass complete feed suppliers, and mycotoxin mitigation specialization targeting humid subtropical storage risk.
Within the multinational nutrition tier, Nutreco NV and Cargill Incorporated exemplify archetypes of R&D-intensive and scale-driven positioning respectively. BASF SE occupies a specialty additive position. These three companies represent distinct competitive vectors: Dutch-based Nutreco NV anchors rumen-protected nutrient delivery expertise, Minnesota-based Cargill Incorporated leverages Brazilian manufacturing scale for modular mineral supply, and German BASF SE differentiates via mycotoxin binder formulations.
| Leading Market Players |
|---|
| Nutreco NV |
| Lallemand Inc |
| Cargill Incorporated |
| Royal Agrifirm Group |
| Land O'Lakes Inc |
| BASF SE |
| ICC |
| Cladan Animal Nutrition |
| CCPA GROUP |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap premix blenders across Brazil's interior states anchor supply-side discipline, their conservative balance sheets limiting speculative inventory builds and transmitting organic trace mineral cost volatility directly into contract pricing. This ownership pattern concentrates pricing power among certified domestic manufacturers with MAPA-established testing infrastructure while squeezing margins for distributor-dependent operators lacking thermal-stabilized coating capabilities.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Brazil's southeastern dairy cooperatives and ANVISA-registered manufacturers, with price differentiation resting on MAPA certification tier and volume scale commitments. Cost compression in additive premix formulations is intensifying because yeast derivative and organic trace mineral inputs face global specialty chemical supply swings. Smallholder operations purchasing through agrochemical stores exhibit highest price sensitivity, while large-scale cooperatives with dedicated nutrition staff accept premium positioning for customized mineral ratio protocols.
Supply Chain Analysis
Specialized rumen nutrition expertise scarcity across São Paulo state and Minas Gerais limits expansion of thermal-stabilized coating capacity despite accelerating cooperative demand. Manufacturing concentrates in Brazil, Argentina, and imported formulations from North American multinationals. Raw material dependencies center on Chinese organic trace mineral supply, European yeast derivative production, and domestic phosphorus sourcing. Single-source vulnerability in rumen-protected amino acid inputs creates exposure. Distribution runs through direct manufacturer relationships for cooperative volume and regional distributor networks for fragmented provincial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America ruminant feed premix market represents a late-cycle quality story as Argentine feedlot professionalization and Brazilian dairy cooperative consolidation shift procurement toward certified, technically-supported formulations over commodity mineral blends.
For Market Incumbents: Acquire thermal-stabilized coating equipment and cross-disciplinary rumen nutrition specialist teams to defend against modular premix unbundling that threatens complete feed package margins. Deepen backward integration into organic trace mineral sourcing to buffer global supply chain volatility and compress formulation costs for price-competitive mineral premix positioning. For New Entrants and Emerging Players: ANVISA's pending probiotic reclassification pathway in Brazil opens a window for additive premix specialists to establish yeast derivative and direct-fed microbial formulations ahead of classification clarity. Target Paraguay and Uruguay's import-dependent markets through Brazilian-certified suppliers with established Mercosur logistics networks, leveraging distributor consolidation gaps in Asunción and Montevideo. For Investors and Strategic Acquirers: Valuations sit cheapest among uncertified local blenders lacking MAPA infrastructure but possessing established smallholder distributor relationships. Long-term viability favors acquisition of mid-scale Brazilian manufacturers with thermal-stabilized coating capex already deployed and ANVISA registration timelines advanced. Watch ANVISA's novel feed additive classification decisions as the critical inflection signal for additive premix segment expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Trace Mineral Sourcing | Captive supply of selenium and phosphorus inputs insulates margins from global specialty chemical price swings. |
| MAPA Certification Investment | Certified testing infrastructure unlocks direct sales to Brazil's southeastern dairy cooperatives bypassing distributors. |
| Thermal-Stabilized Coating Capacity Expansion | Spray-drying and micro-encapsulation equipment preserves bioactive potency for rumen-protected nutrient delivery. |
| Regional Logistics Network Buildout | Distribution infrastructure in Paraguay and Uruguay captures import substitution demand from underpenetrated Mercosur members. |
| Mycotoxin Mitigation Specialization | Specialty additive premixes with aflatoxin binding claims address humid subtropical storage risk across Brazil and Argentina. |
Research Methodology
Multiple input streams — structured interviews with premix formulation directors, cooperative procurement managers, and ANVISA regulatory affairs specialists; secondary validation through MAPA feed safety filings, SENASA registration databases, and Mercosur trade harmonization protocols; customs records of organic trace mineral imports — were reconciled through bottom-up volume modeling and top-down value triangulation across the analysis window.
Historical consumption patterns were cross-referenced against panel input from dairy nutrition consultants and feedlot integrators to construct projection frameworks across product type, species application, and distribution channel dimensions. CAGRs were derived from segmented growth trajectory analysis incorporating herd expansion rates, regulatory implementation timelines, and cooperative consolidation velocity as industry-specific forecast inputs.
Revisions become necessary when ANVISA classification decisions on direct-fed microbials materialize, when Mercosur harmonization timelines diverge significantly, or when organic trace mineral supply disruptions alter input cost assumptions. Material deviation in these named triggers warrants pause and re-evaluation of premix adoption trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
North America Ruminant Feed Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Cattle Management Software Market
Livestock Management
Poultry Feed Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
United States Swine Feed Market
Livestock Management
Bird Feeder Market
Livestock Management
Cattle Feeder Market
Livestock Management
Roughage Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Feed Management Software Market
Livestock Management
China Swine Feed Market
Livestock Management
Poultry Health Market