
 Europe Feed Binders Market | 2026-2036
Europe Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Binders Market Foresight
Precision fermentation and enzymatic modification of lignocellulosic biomass is reshaping how European feed binders achieve binding strength without synthetic additives. Borregaard AS leverages its Norwegian wood-chemistry heritage to dominate specialty lignin binder production for premium aquaculture and pet food applications. Cargill, Inc. sustains broad supply chain control across multiple European countries, integrating grain processing with in-house binder formulation. ADM anchors its position through backward integration into corn wet-milling streams that yield starches and modified carbohydrates for livestock feed pelleting.
Feed binders are adhesive compounds—typically comprising lignosulfonates, bentonite clays, molasses, or modified starches—that physically bond feed ingredients into durable pellets, crumbles, or coated products resisting breakage during handling and transport. Manufacturing involves thermal gelatinization, chemical cross-linking, or mechanical compression to achieve target pellet durability indices above 90 percent for commercial aquaculture and poultry operations. Natural binders derived from plant gums and lignin occupy the fastest-expanding margin pool as EU feed buyers reject synthetic alternatives under sustainability procurement protocols. Pelleting applications consume the largest volume share across European compound feed mills, while aquaculture feed demands specialized binders with controlled water-stability profiles for extended submersion without nutrient leaching.
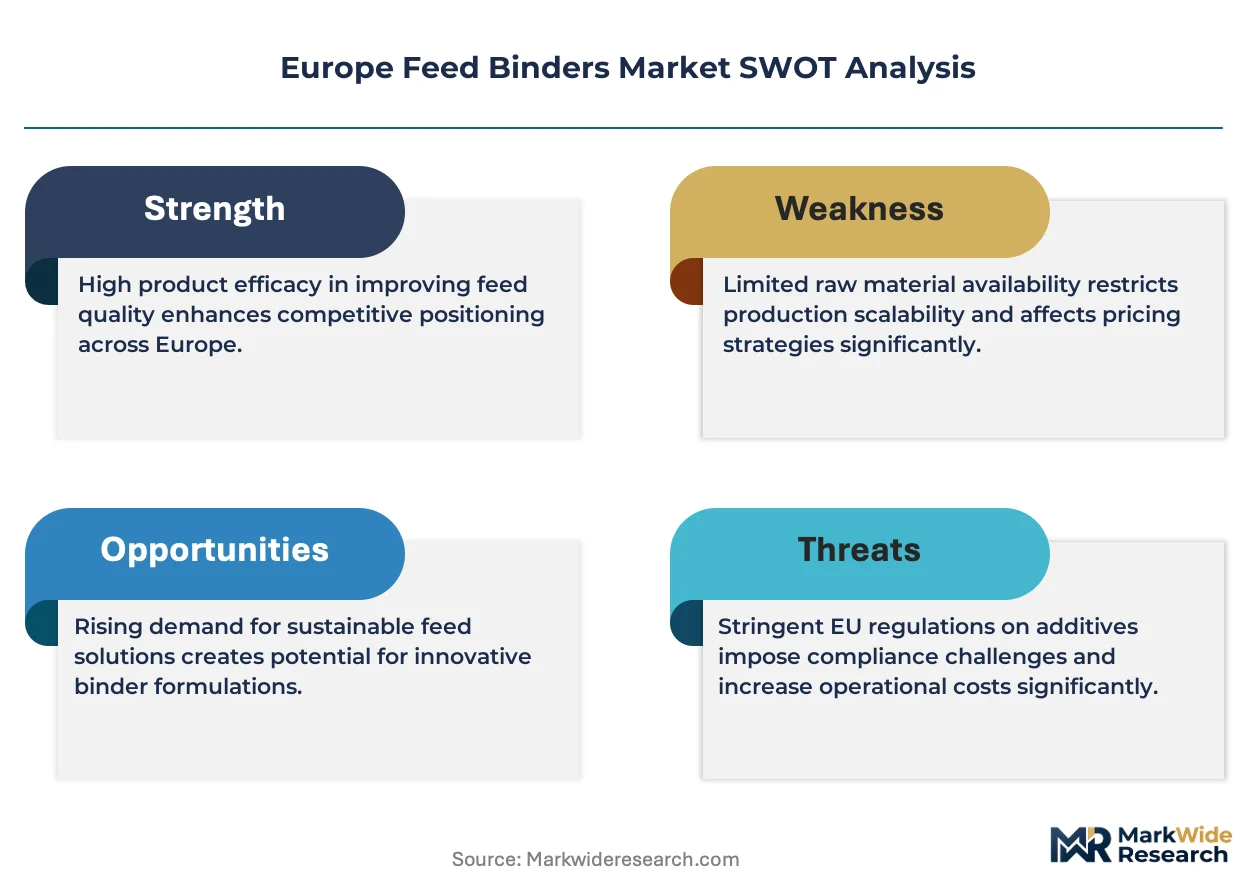
EMA feed additive registration requirements and EFSA safety evaluations govern market access for novel binder chemistries, creating multi-year approval timelines that favor incumbents with established regulatory dossiers. The EU Green Deal and REACH chemical restrictions are systematically displacing petroleum-derived synthetic binders from formulations sold into European livestock and pet food channels. Stakeholders must monitor evolving EFSA opinions on novel protein and carbohydrate binders to anticipate which feed segments will open to next-generation adhesive technologies.
Market Dynamics
EU Green Deal sustainability mandates are systematically displacing petroleum-derived synthetic binders from European livestock and pet food channels, forcing compound feed manufacturers across Germany, France, and the Netherlands to reformulate toward lignin and plant gum alternatives.
Growth Catalysts
- REACH chemical restrictions:European compound feed producers face binding phase-out schedules for synthetic additives, accelerating natural binder adoption in pelleted feed formulations.
- Dairy and swine operations in Germany:Intensive livestock sectors prioritize pellet durability indices above 90 percent to minimize feed waste during automated handling systems.
- Precision fermentation:Enzymatic modification of lignocellulosic biomass enables novel binding strength profiles without synthetic cross-linking agents.
Market Restraints
- Wheat starch price volatility:Modified carbohydrate binders face input cost pressure from grain market fluctuations tied to Black Sea supply disruptions.
- EMA multi-year approval timelines:Novel binder chemistries require extensive EFSA safety dossiers that favor incumbents with established regulatory histories.
- Water-stability limitations of plant gums:Aquaculture feed applications demand controlled submersion profiles that lignin derivatives struggle to match against synthetic alternatives.
Strategic Opportunities
- Poland and Romania livestock expansion:Underpenetrated Central European markets show rising compound feed capacity with limited local binder supply infrastructure.
- CSRD supply chain disclosure rules:Mandatory sustainability reporting drives procurement officers toward certified organic binder formulations with traceable lignin sourcing.
- Aquaculture feed specialization:Controlled water-stability binders for extended submersion represent a premium margin pool distinct from standard pelleting applications.
Industry Challenges
- EFSA novel food evaluations:Carbohydrate-based binders from precision fermentation face 18-36 month safety assessment timelines that delay commercial rollout.
- Pelleting equipment retrofit costs:Natural binder formulations require modified thermal gelatinization parameters in existing compound feed mill infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Binders Market |
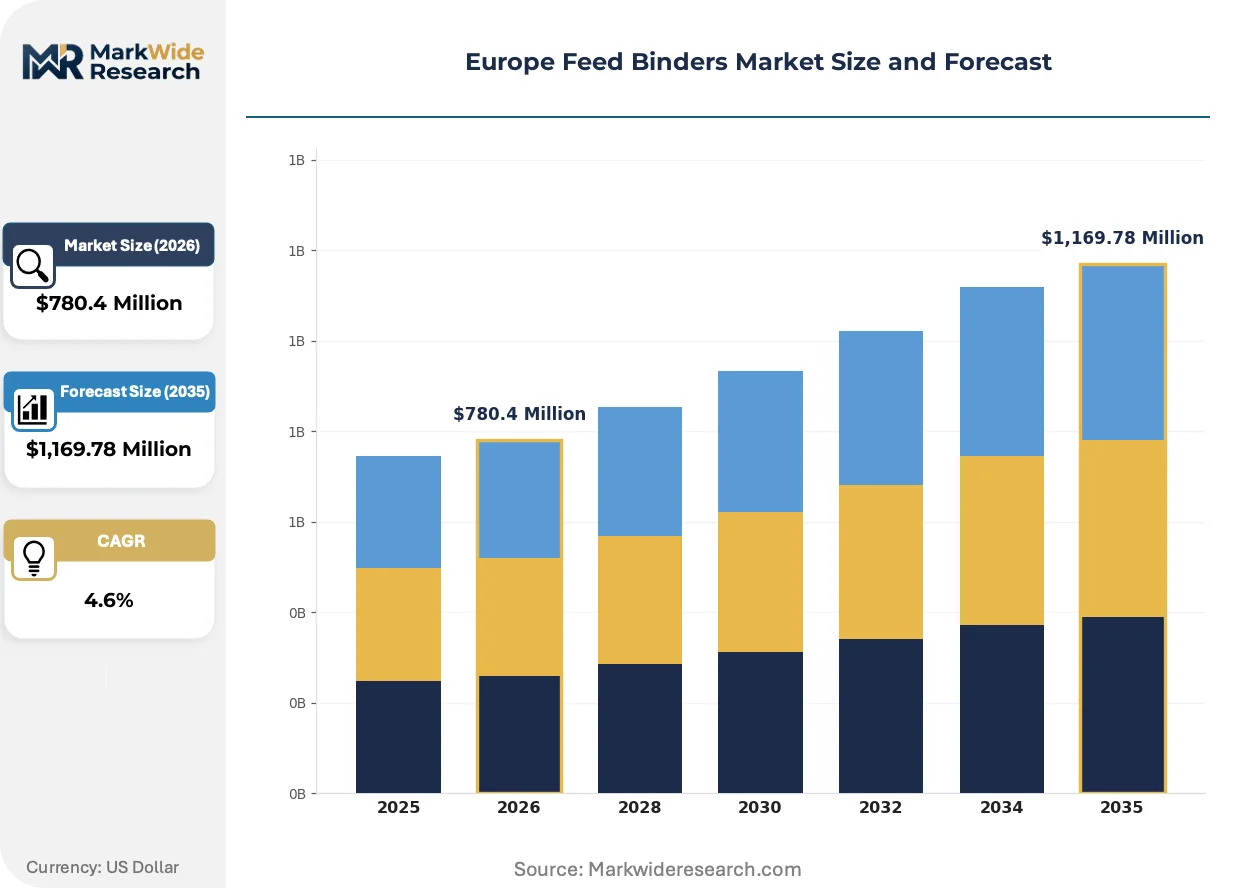
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,169.78 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
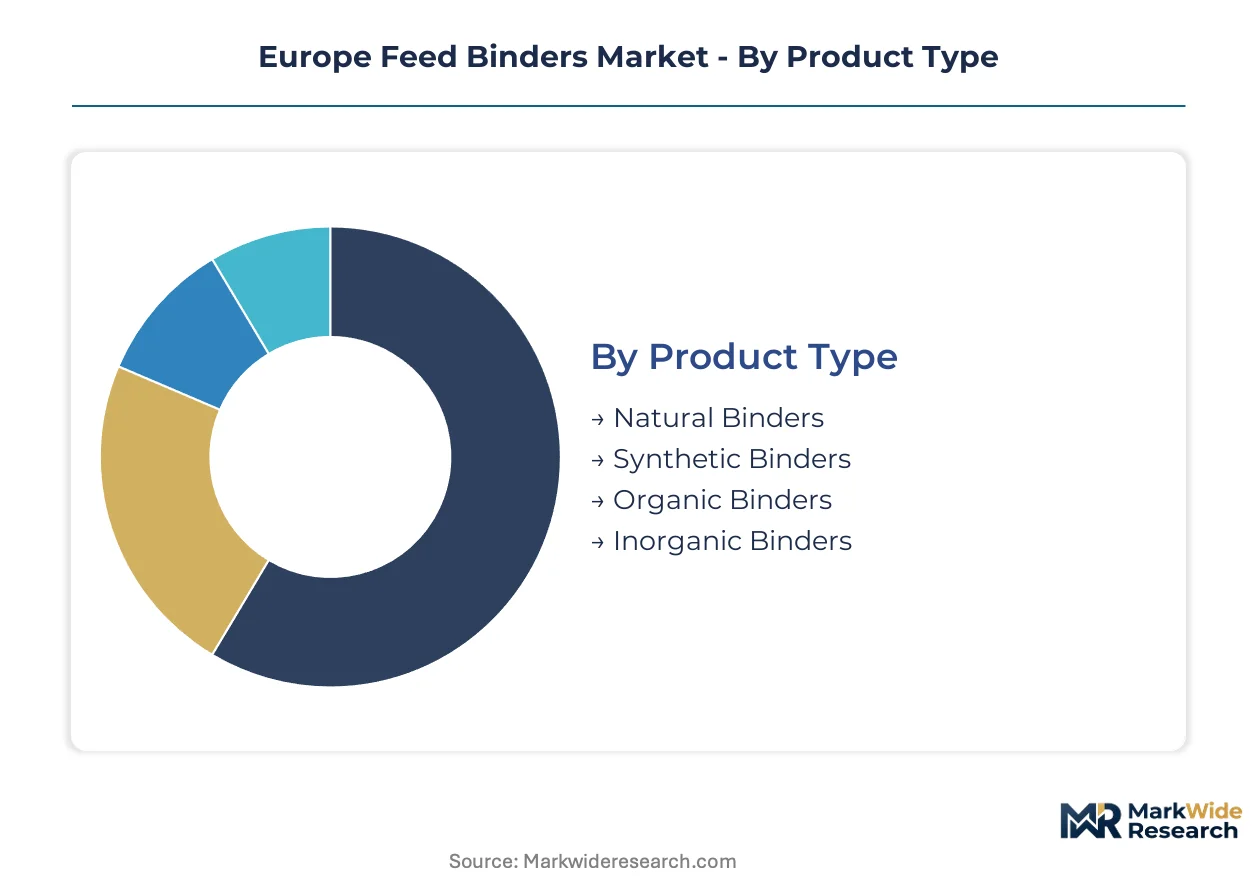
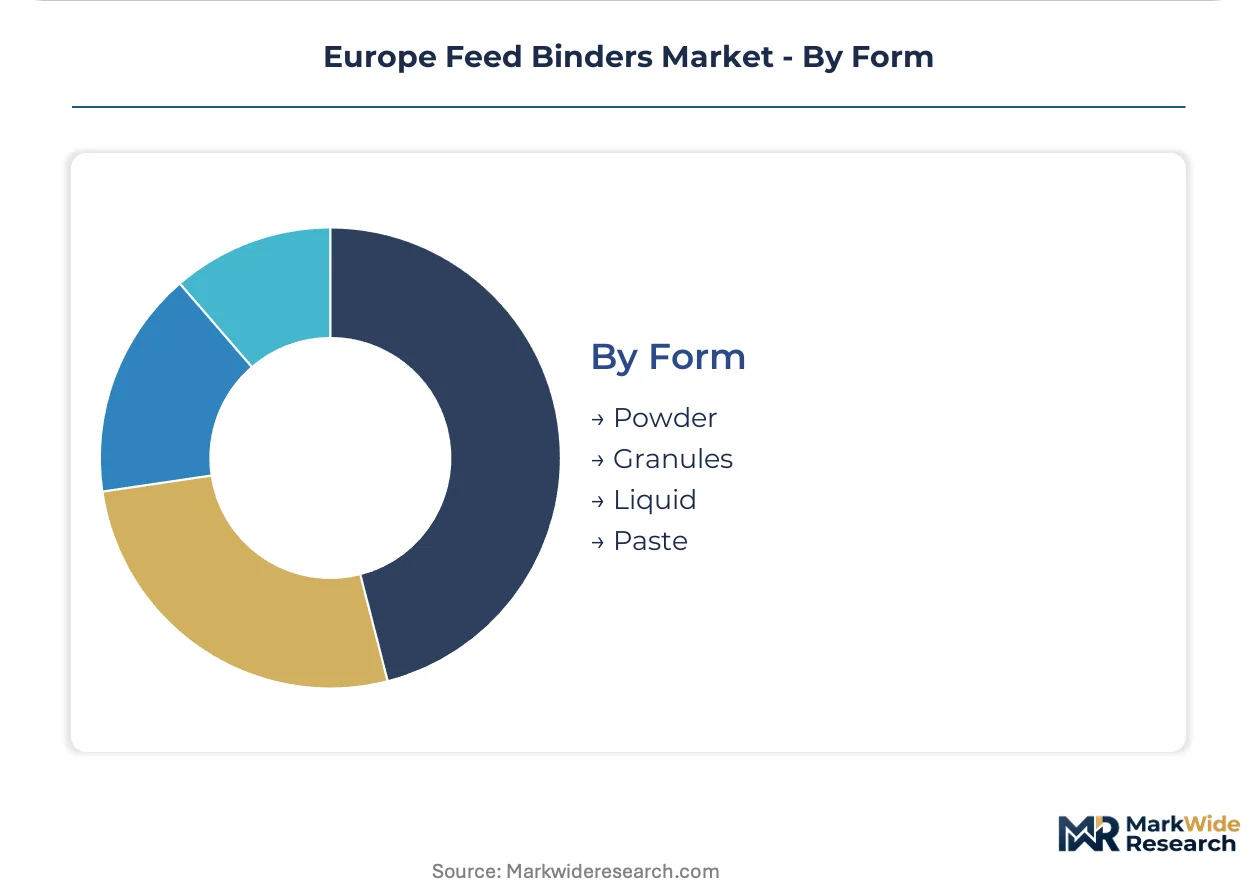
| Segmentation | Product Type: Natural Binders, Synthetic Binders, Organic Binders, Inorganic Binders End User: Livestock Feed, Aquaculture Feed, Pet Food, Poultry Feed Application: Pelleting, Crumbling, Coating, Grinding Form: Powder, Granules, Liquid, Paste |
| Companies Covered | ADM, Cargill, Inc., Adisseo, Alltech, Inc., Borregaard AS, Oil-Dri Corporation of America, Bentoli, Kemin Industries, FMC Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Binders Market Shifts & Advancements
Feed binder technology is migrating from commodity chemical additives toward bioengineered lignocellulosic solutions, with regulatory pressure and procurement specifications converging to reward innovation in natural adhesive platforms.
Enzymatically modified lignin derivatives are migrating from specialty aquaculture applications into mainstream poultry and swine pelleting operations. Dutch compound feed manufacturers lead adoption curves, integrating these binders to meet retailer sustainability audit requirements. The technology is migrating from premium positioning toward cost-competitive scale as Borregaard expands Norwegian wood-chemistry production capacity.
EU Green Deal Farm to Fork strategy mandates 50 percent reduction in chemical pesticide and fertilizer risk by 2030, with binding implications for feed additive portfolios. Compound feed formulators face downstream pressure from protein producers seeking Scope 3 emissions reductions. German dairy cooperatives now specify lignin-based binders in procurement tenders to satisfy retail chain climate commitments.
Buyer consolidation across European compound feed manufacturing is compressing supplier negotiation cycles and unbundling technical service from bulk chemical supply. Large mill groups in France and the Netherlands now conduct centralized binder procurement with standardized durability specifications. This pattern concentrates volume with multi-site suppliers capable of pan-European logistics coordination and regulatory documentation.
Europe Feed Binders Market Segmentation
Feed binder selection in Europe hinges on pelleting equipment compatibility, regulatory clearance status, and sustainability certification requirements that vary sharply across livestock, aquaculture, and pet food channels. Compound feed manufacturers prioritize segments offering documented EFSA safety dossiers and REACH-compliant chemistries to avoid reformulation costs.
Product Type:
After-sales technical support intensity runs highest for natural and organic binder categories, where mill operators require ongoing calibration assistance for modified thermal gelatinization parameters.
- Natural Binders:Derived from lignin, plant gums, and molasses, these formulations rely on enzymatic modification of lignocellulosic biomass to achieve binding strength. German dairy cooperatives specify lignin-based variants in procurement tenders to satisfy retail chain climate commitments under EU Green Deal mandates.
- Synthetic Binders:Petroleum-derived chemical additives face systematic displacement from European channels as REACH restrictions enforce binding phase-out schedules. Residual demand concentrates in aquaculture applications where water-stability specifications exceed current natural binder performance.
- Organic Binders:Certified formulations with traceable lignin sourcing command premium positioning under CSRD supply chain disclosure rules. Dutch compound feed manufacturers integrate these to meet retailer sustainability audit requirements.
- Inorganic Binders:Bentonite clays and mineral-based adhesives serve cost-sensitive pelleting operations with established equipment compatibility.
Natural binders hold the largest share; momentum sits with organic binders climbing the fastest on certification-driven procurement.
End User:
Application-specific durability requirements create distinct margin tiers across livestock species and pet food channels.
- Livestock Feed:Dairy and swine operations in Germany prioritize pellet durability indices above 90 percent to minimize waste during automated handling. Intensive livestock sectors drive volume concentration for standard pelleting binders.
- Aquaculture Feed:Controlled water-stability profiles for extended submersion without nutrient leaching represent the premium margin pool. Lignin derivatives struggle to match synthetic alternatives here, creating technology investment pressure.
- Pet Food:Palatability and texture specifications favor specialized coating binders with documented EFSA safety evaluations.
- Poultry Feed:High-throughput mill operations demand consistent pellet integrity across variable grain input qualities.
Livestock feed dominates volume; aquaculture feed shows the steepest expansion trajectory on premium specialization.
Application:
Equipment retrofit requirements and thermal parameter sensitivity differentiate processing method economics.
- Pelleting:Thermal gelatinization and mechanical compression bond ingredients into durable pellets. This application consumes the largest volume share across European compound feed mills, with natural formulations requiring modified processing parameters.
- Crumbling:Breaks pellets into smaller particles for young animal feed, demanding binders that maintain structural integrity through secondary processing.
- Coating:Surface application for palatability enhancement and nutrient protection in pet food and premium livestock formulations.
- Grinding:Pre-processing binder addition to improve flow characteristics and reduce dust generation during milling operations.
Pelleting commands installed capacity; coating gains share fastest on pet food premiumization.
Form:
Logistics economics and dosing precision requirements shape form selection across mill scale tiers.
- Powder:Dry flowable binders integrate directly into premix systems. Large mill groups in France and the Netherlands prefer powder forms for automated dosing accuracy in centralized procurement configurations.
- Granules:Reduced dust handling improves occupational safety profiles and metering consistency.
- Liquid:Molasses-based and modified starch solutions enable uniform distribution in high-moisture pelleting applications.
- Paste:Specialized aquaculture and pet food coating applications requiring precise viscosity control.
Powder holds the largest share; liquid forms expand most quickly on molasses binder adoption in Central European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized lignin-based feed binders to Dutch and Danish compound feed manufacturers, establishing a cross-border trade corridor that channels premium natural formulations into Northwest European livestock operations.
Germany
Dairy cooperatives in Lower Saxony and Bavaria specify lignin-based binders in procurement tenders to satisfy retail chain climate commitments. EU Green Deal Farm to Fork mandates drive reformulation timelines across German compound feed mills. The Münsterland region hosts dense clusters of swine and dairy operations where pellet durability specifications exceed 90 percent.
Netherlands
Dutch compound feed manufacturers lead European adoption curves for enzymatically modified lignin derivatives to meet retailer sustainability audit requirements. CSRD supply chain disclosure rules compel procurement officers toward certified organic binder formulations. The Port of Rotterdam serves as the primary import gateway for lignocellulosic raw materials sourced from Nordic suppliers.
France
Large mill groups in Brittany and the Pays de la Loire conduct centralized binder procurement with standardized durability specifications. REACH chemical restrictions enforce binding phase-out schedules for petroleum-derived synthetic additives. The Rennes agglomeration anchors a concentration of poultry feed specialists demanding consistent pellet integrity.
Poland
Rising compound feed capacity in Greater Poland and Silesia faces limited local binder supply infrastructure, creating import dependency on German and Dutch distributors. EFSA safety dossier requirements delay market entry for novel binder chemistries. The Łódź region shows emerging demand from expanding dairy operations seeking automated handling compatibility.
Spain
Aquaculture feed producers in Galicia demand controlled water-stability profiles that lignin derivatives struggle to match against synthetic alternatives. EMA feed additive registration requirements govern market access for novel chemistries. The Vigo cluster concentrates marine feed manufacturing where extended submersion specifications command premium positioning.
Europe Feed Binders Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates volume with multi-site suppliers capable of pan-European logistics coordination. Incumbents with established EFSA regulatory dossiers hold structural advantages over entrants facing multi-year approval timelines. Two dominant archetypes emerge: vertically integrated agricultural conglomerates with captive starch and lignin streams, and specialty chemical producers with concentrated wood-chemistry expertise. Competitive moves center on backward integration into raw material supply and capacity expansion in enzymatic modification facilities.
Among the integrated agricultural conglomerates, ADM and Cargill, Inc. exemplify archetypes combining grain processing infrastructure with in-house binder formulation capabilities. Borregaard AS occupies a distinct position as a specialty lignin producer leveraging Norwegian wood-chemistry heritage. These three anchors represent the competitive spectrum from commodity-scale supply chain control to premium natural binder specialization.
| Leading Market Players |
|---|
| ADM |
| Cargill, Inc. |
| Adisseo |
| Alltech, Inc. |
| Borregaard AS |
| Oil-Dri Corporation of America |
| Bentoli |
| Kemin Industries |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
The Münsterland region's dense concentration of swine and dairy operations generates substantial pull-through demand for premium lignin-based binders, concentrating procurement leverage among German compound feed cooperatives and compressing margin capture for suppliers lacking pan-European scale.
Pricing Analysis
Next-generation enzymatically modified lignin derivatives command 15-25 percent premiums over conventional lignosulfonate formulations, while unmodified plant gum alternatives occupy a cost-competitive tier attractive to price-sensitive Central European mills. Pricing stratifies across premium, standard, and economy tiers based on certification grade and EFSA dossier completeness. Cost compression in the synthetic binder tier is intensifying because REACH phase-out schedules strand petroleum-derived inventory. Large mill groups in France and the Netherlands exhibit lowest price sensitivity due to sustainability audit requirements, while Polish and Romanian operators remain most cost-conscious.
Supply Chain Analysis
Tariff exposure between Norway and continental EU markets dominates supply chain risk planning for specialty lignin derivatives, as Borregaard's Nordic production anchors premium natural binder supply. Raw material sourcing draws from Norwegian spruce lignin, Black Sea wheat starch, and Brazilian molasses streams. Single-source vulnerability concentrates in enzymatic modification capacity, where Dutch toll manufacturers currently process the majority of next-generation formulations. Distribution runs through Rotterdam bulk liquid terminals and Münsterland rail hubs serving compound feed mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation across Northwest European compound feed manufacturing has shifted negotiating power toward large mill groups, fragmenting supplier relationships and compressing technical service margins for binder producers without multi-site logistics capabilities.
For Market Incumbents: Insulate margin structures by securing backward integration into Nordic lignocellulosic raw material streams and expanding enzymatic modification capacity in the Netherlands to serve centralized procurement configurations. EFSA dossier maintenance represents a critical defensive moat against precision fermentation entrants facing 18-36 month approval timelines. Channel control through pan-European logistics coordination preserves volume relationships with buyer-consolidated mill groups. For New Entrants and Emerging Players: Build out white-space positions in Poland and Romania's underpenetrated compound feed markets, where local binder supply infrastructure lags rising livestock capacity. Aquaculture feed specialization offers the most penetrable premium tier, as controlled water-stability specifications currently exceed natural binder performance and reward technology investment. A go-to-market angle anchored to CSRD-compliant traceability documentation addresses procurement officer mandates in Dutch and German retail supply chains. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agricultural conglomerates seeking to divest non-core specialty chemical operations, particularly lignin derivative units with established EFSA regulatory histories. Long-term viability hinges on the durability of EU Green Deal sustainability mandates and the pace of precision fermentation cost curves. The signal to watch is EFSA opinion issuance on novel carbohydrate binders, which would indicate segment opening for next-generation adhesive platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignocellulosic Supply | Nordic wood-chemistry heritage secures premium natural binder raw material access against Black Sea grain volatility. |
| Enzymatic Modification Capacity Expansion | Dutch toll manufacturing clusters process next-generation formulations for retailer sustainability audit compliance. |
| EFSA Regulatory Dossier Investment | Established safety evaluations create multi-year barriers against precision fermentation entrants. |
| CSRD-Compliant Traceability Systems | Certified organic binder sourcing satisfies mandatory supply chain disclosure rules for procurement officers. |
| Aquaculture Water-Stability R&D | Controlled submersion profiles command premium positioning in Galicia's marine feed manufacturing cluster. |
Research Methodology
Initial hypotheses were tested against primary input from compound feed procurement directors, lignin derivative plant managers, EFSA regulatory affairs consultants, and aquaculture feed formulators, and refined through secondary validation against customs trade data, Cefic chemical industry reports, EU Green Deal policy documentation, and SEC filings from listed agricultural conglomerates. Bottom-up volume estimates from mill-level consumption patterns were triangulated with top-down market sizing derived from compound feed production statistics.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning binder chemistry type, livestock species application, pelleting equipment compatibility, and sustainability certification tier. CAGRs were derived from regression analysis of historical consumption trends and forward projection of EU regulatory phase-out schedules. Industry-specific forecast inputs included REACH restriction timelines and EFSA novel food evaluation pipelines.
Stress conditions across wheat starch price volatility, EMA approval delays, and Black Sea logistics disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and livestock sector consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Livestock Dewormers Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Bird Feeder Market
Livestock Management
Feed Management Software Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Layer Feed Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Cattle Feeder Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Roughage Feed Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Layer Breeding System Market