
 Saudi Arabia Poultry Market | 2026-2036
Saudi Arabia Poultry Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Poultry Market Outlook
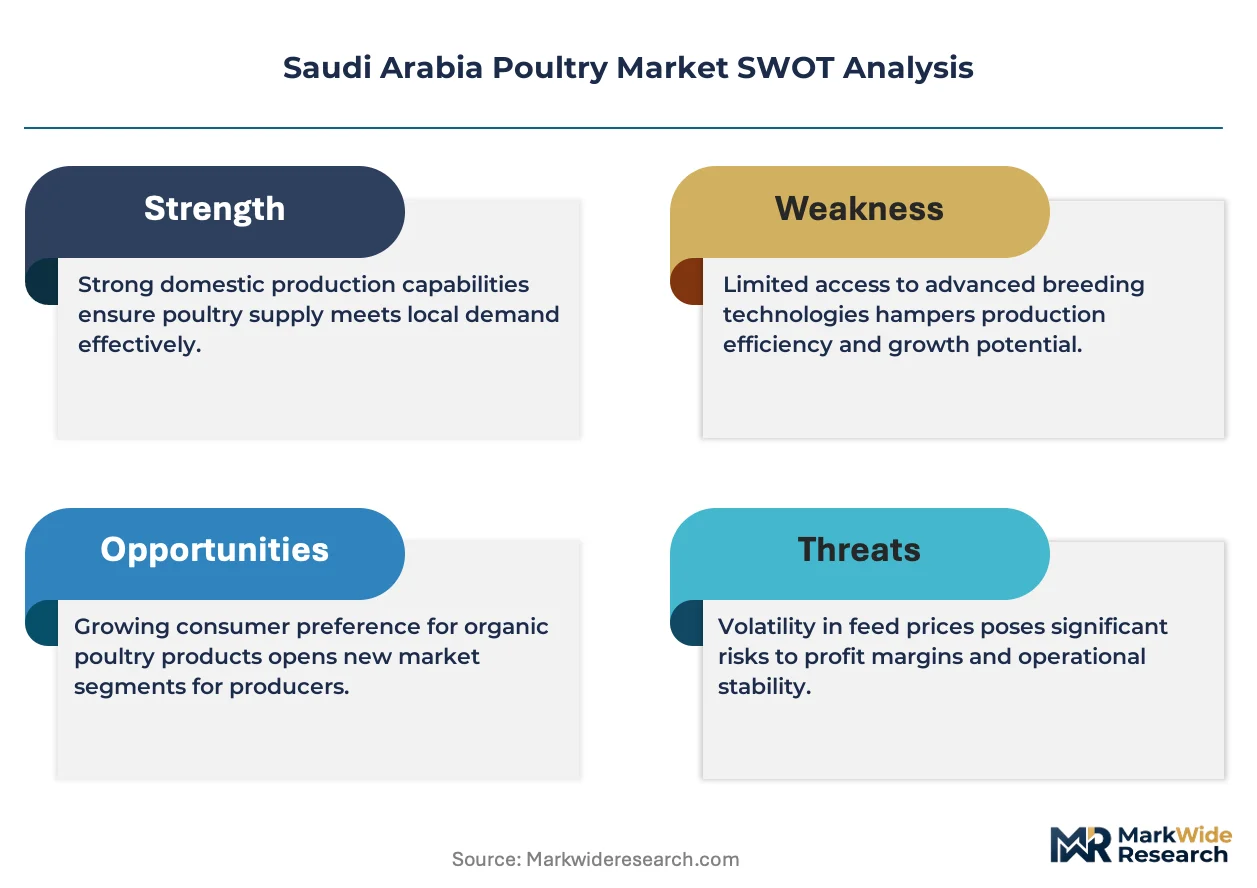
Expatriate veterinary and farm-management talent is bifurcating the competitive landscape between integrated operators and fragmented backyard producers. Al-Watania Poultry leverages its fully integrated feed-to-retail infrastructure across the Kingdom's central corridor. Almarai Company anchors its position through backward integration into grain milling and cold-chain logistics. Tanmiah Food Company differentiates via halal-certified export capacity targeting Gulf Cooperation Council neighbors.
Saudi Arabia poultry encompasses broiler chickens, layer hens, turkeys, and ducks raised for meat and egg production under controlled-environment housing with automated climate systems maintaining 18-24°C for optimal feed conversion ratios. The primary purpose is supplying protein to domestic foodservice, retail, and processing channels while reducing import dependency. Broilers dominate volume throughput given their short 35-42 day grow-out cycles and alignment with consumer price sensitivity. Food Service channels capture premium margin pools as hotel and restaurant chains demand consistent portion-controlled cuts. E-commerce distribution is gaining velocity among younger urban households seeking same-day chilled delivery.
SFDA enforces maximum residue limits for veterinary drugs and mandates HACCP compliance across slaughter and processing facilities, elevating capital requirements for market entry. The Saudi Standards, Metrology and Quality Organization specifies labeling and shelf-life protocols that directly shape packaging investment and inventory rotation strategies. MOHAP coordinates zoonotic disease surveillance with provincial agriculture departments, creating layered biosecurity obligations. Stakeholders must monitor feed grain import tariff adjustments and water pricing reforms as these input cost variables will determine which integrated operators can sustain margin compression without sacrificing biosecurity standards.
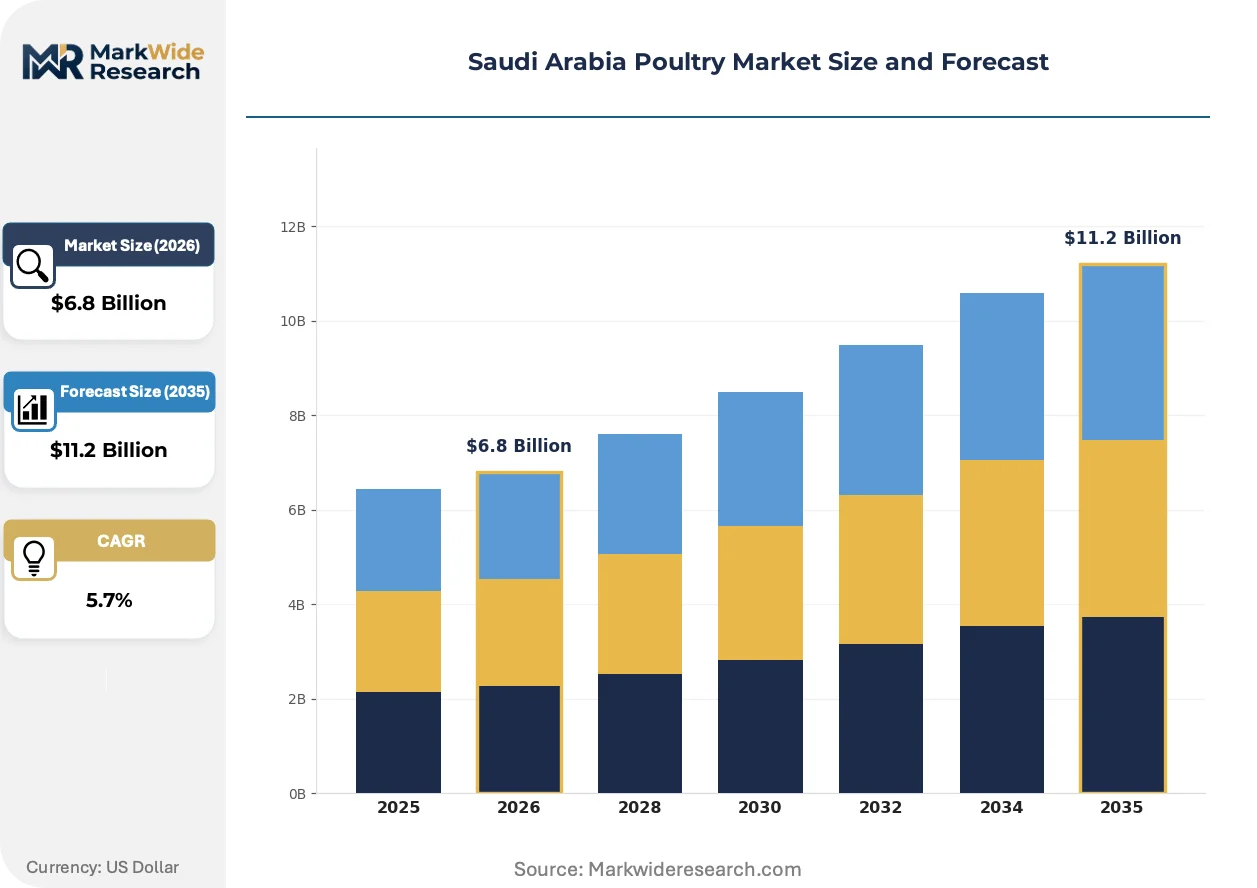
Market Dynamics
SFDA's tightened antibiotic residue standards are compressing margins for fragmented backyard producers while rewarding integrated operators with captive laboratory and veterinary infrastructure across Riyadh and Jeddah corridors.
Growth Catalysts
- Foodservice channel expansion:Quick-service restaurant chains are scaling poultry procurement as domestic consumption rises in urban corridors. Hotel and restaurant operators demand consistent portion-controlled cuts.
- SFDA regulatory elevation:Tightened maximum residue limits for veterinary drugs are forcing consolidation toward operators with in-house compliance infrastructure.
- Halal export certification:Gulf Cooperation Council neighbors are accepting Saudi halal-certified poultry, creating cross-border offtake for integrated processors.
Market Restraints
- Feed grain import dependency:Yellow corn and soybean meal price volatility tied to Black Sea supply disruptions compresses feed conversion economics.
- Water pricing reforms:The Kingdom's agricultural water tariff adjustments threaten cooling system operating costs for controlled-environment housing.
- Expatriate veterinary talent scarcity:Farm-management expertise concentration in integrated operators leaves fragmented producers exposed to disease outbreaks.
Strategic Opportunities
- Same-day chilled delivery channels:E-commerce platforms are capturing younger urban households seeking convenience without retail visitation.
- Backward integration into grain milling:Captive feed production insulates margin structures from import tariff volatility.
- MOHAP zoonotic surveillance coordination:Biosecurity infrastructure investments align with layered disease monitoring obligations.
Industry Challenges
- Automated climate system calibration:Maintaining 18-24°C grow-out environments requires skilled technicians scarce outside central corridor integrated operations.
- HACCP compliance capex:Slaughter and processing facility upgrades demand capital commitments that exclude sub-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Poultry Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Layers, Turkeys, Ducks Distribution Channel: Retail, Wholesale, E-commerce, Food Service Packaging Type: Plastic Trays, Vacuum Bags, Cartons, Cans End User: Households, Restaurants, Catering Services, Food Processing |
| Companies Covered | Fakieh Poultry Farms, Americana Group, Al-Watania Poultry, BRF, Sunbulah Group, Almarai Company, Entaj, Radwa Food Company, Tanmiah Food Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Poultry Market Strategic Shifts
Automation and regulatory digitization are compressing the competitive set toward capital-intensive operators while channel fragmentation creates parallel demand pathways for chilled and frozen product formats.
Climate-controlled housing with automated ventilation and precision feeding systems is bifurcating the producer base. Integrated operators across the central corridor are deploying these systems at scale. Backyard producers lacking capital access are exiting or contracting as grow-out consistency becomes a procurement prerequisite for foodservice buyers.
SFDA's electronic traceability mandates for veterinary drug administration are reshaping record-keeping infrastructure. Slaughter facilities must now integrate digital logging systems with laboratory testing workflows. Exporters targeting Gulf Cooperation Council markets are prioritizing blockchain-enabled halal certification documentation.
Younger urban households in Riyadh and Jeddah are substituting traditional retail visitation with mobile-ordered chilled delivery. Quick-commerce platforms are building dedicated cold-chain micro-fulfillment nodes. This channel shift is compressing wholesale market throughput while elevating margin capture for operators with direct-to-consumer packaging capabilities.
Saudi Arabia Poultry Market Segmentation
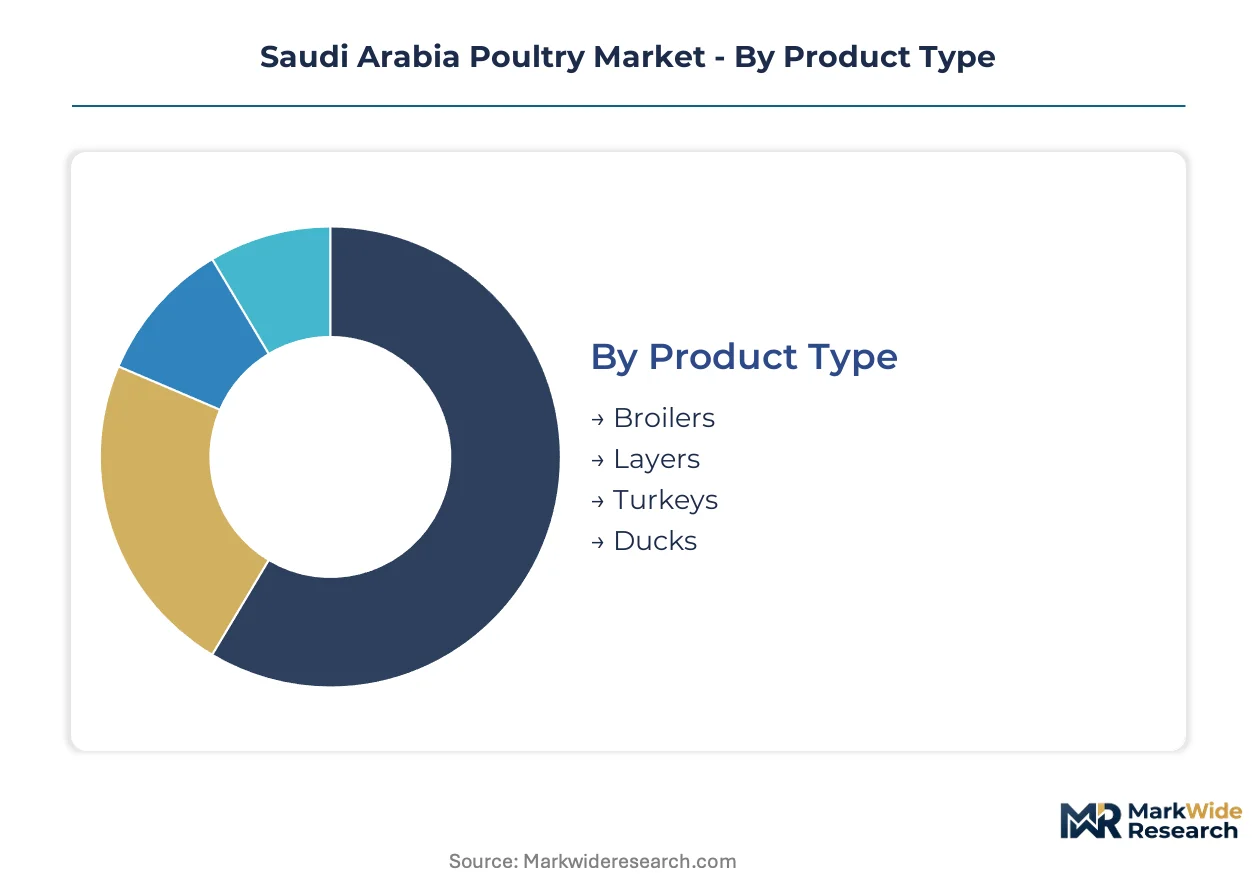
Saudi Arabia's poultry market segments reflect divergent compliance capabilities and channel-specific cold-chain requirements. SFDA residue standards and foodservice procurement protocols create asymmetric competitive access across each dimension.
Product Type:
SFDA maximum residue limits for veterinary drugs apply uniformly across all categories, yet grow-out cycle length determines laboratory testing frequency and compliance cost burden per bird.
- Broilers:Short 35-42 day grow-out cycles align with consumer price sensitivity and quick-service restaurant portion-controlled cut specifications. Demand concentrates in Riyadh and Jeddah foodservice corridors where procurement contracts mandate consistent bird weights and antibiotic-free certification.
- Layers:Extended production cycles require sustained veterinary oversight and feed conversion optimization across 60-80 week laying periods. Table egg demand clusters in urban retail and e-commerce channels where younger households prioritize same-day chilled delivery reliability.
- Turkeys:Niche protein source for hotel banquet and premium catering segments with seasonal demand spikes around religious and national celebrations.
- Ducks:Limited commercial scale serving ethnic restaurant segments and specialty food processing applications with concentrated demand in Eastern Province expatriate corridors.
Established volume favors broilers; emerging adoption favors layers as cage-free and enriched colony housing investments respond to retail certification differentiation.
Distribution Channel:
Channel selection determines margin capture potential and cold-chain infrastructure requirements, with direct-to-consumer formats demanding dedicated micro-fulfillment capabilities.
- Food Service:Hotel and restaurant chains source portion-controlled cuts through contracted slaughter facilities with HACCP-certified processing lines. Procurement contracts specify consistent bird weights and halal certification documentation for Gulf Cooperation Council re-export.
- E-commerce:Quick-commerce platforms capture younger urban households in Riyadh and Jeddah through same-day chilled delivery promises. Dedicated cold-chain micro-fulfillment nodes separate viable operators from traditional wholesale-dependent competitors.
- Retail:Hypermarket and supermarket chains dominate household purchasing through branded chilled and frozen product placement.
- Wholesale:Central produce markets and institutional buyers serve fragmented restaurant and catering segments with bulk pricing and limited traceability documentation.
Margin concentration favors food service; channel expansion velocity favors e-commerce as mobile ordering penetration climbs fastest among 25-40 year old demographics.
Packaging Type:
Saudi Standards, Metrology and Quality Organization labeling and shelf-life protocols directly shape material selection and inventory rotation strategies across each format.
- Vacuum Bags:Extended shelf-life preservation for frozen export shipments and institutional food processing procurement. Modified atmosphere specifications meet Gulf Cooperation Council import documentation requirements.
- Plastic Trays:Overwrapped foam or PET formats dominate retail chilled presentation with SFDA-mandated production date and halal slaughter certification visibility.
- Cartons:Bulk institutional formats for quick-service restaurant chain central kitchens with portion-controlled cut specifications.
- Cans:Shelf-stable processed products for remote area distribution and emergency food reserve programs.
Export compliance favors vacuum bags; retail velocity favors plastic trays as chilled case space allocation tightens in Jeddah and Riyadh hypermarket formats.
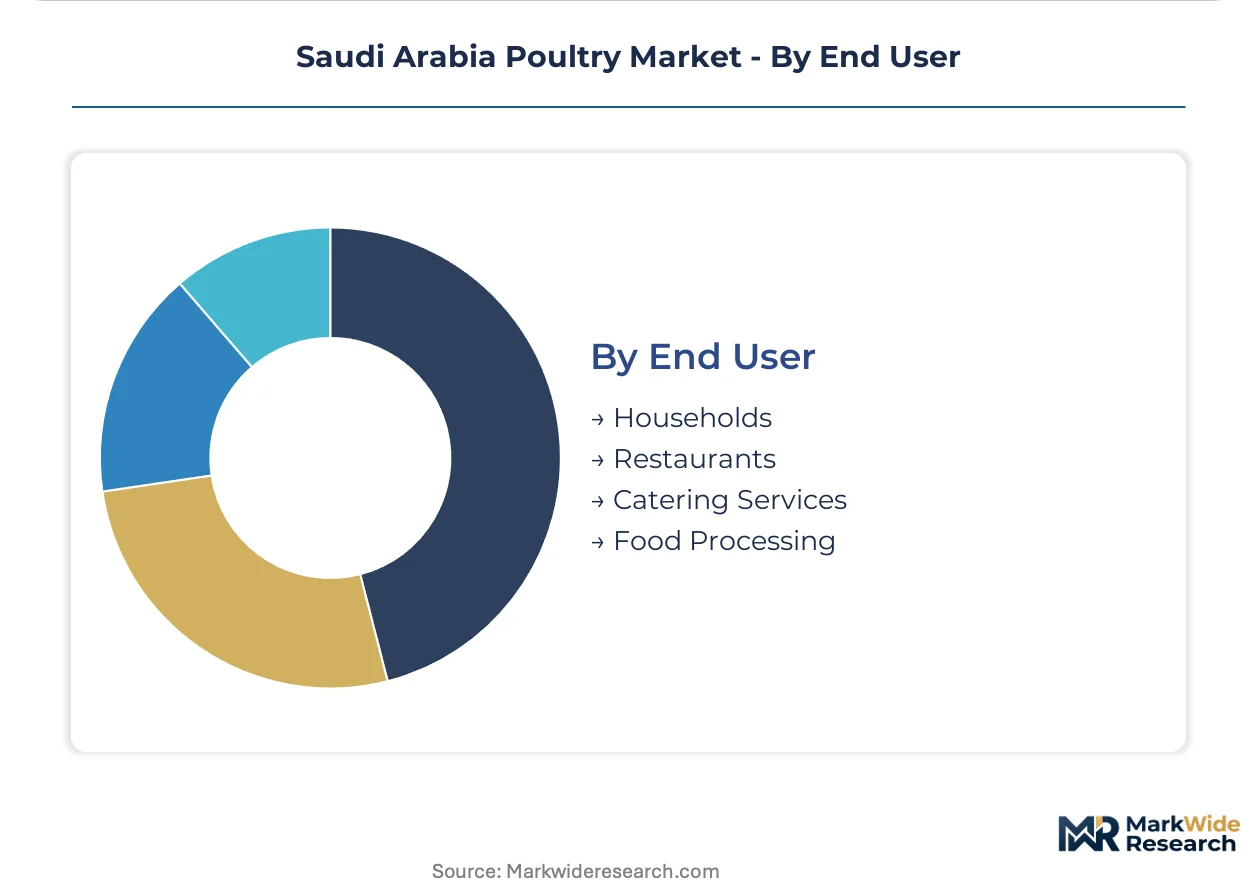
End User:
End-user procurement sophistication spans from household price sensitivity to food processing traceability mandates, with biosecurity documentation requirements scaling accordingly.
- Restaurants:Quick-service and full-service chains demand consistent portion-controlled cuts with batch-level veterinary drug administration records. SFDA electronic traceability mandates for slaughter facilities integrate with chain-level supplier audit protocols.
- Food Processing:Further-processing operators require deboned meat specifications and Salmonella-negative certification for ready-meal and nugget production lines.
- Households:Retail and e-commerce purchasing prioritizes price per kilogram and halal certification visibility over production method documentation.
- Catering Services:Event and institutional catering segments source bulk whole birds and cut portions with flexible delivery scheduling and volume pricing.
Traceability investment favors restaurants; volume throughput favors catering services as government and corporate event procurement scales seasonally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Saudi Arabia's sub-regions. Riyadh and Jeddah corridors prioritize foodservice portion-controlled cuts for quick-service restaurant chains, while Eastern Province demand clusters around institutional catering and expatriate household formats. NEOM's emerging population centers are testing chilled delivery infrastructure at greenfield scale.
Riyadh
Quick-service restaurant chains dominate procurement volumes through contracted slaughter facilities with HACCP-certified processing lines. SFDA's electronic traceability mandates for veterinary drug administration integrate with supplier audit protocols demanded by international hotel operators. The central corridor's automated climate-controlled housing clusters supply consistent bird weights to foodservice buyers.
Eastern Province
Expatriate household density drives retail and e-commerce channel velocity for whole birds and cut portions. MOHAP coordinates zoonotic disease surveillance with provincial agriculture departments, creating layered biosecurity obligations for producers serving Dammam and Al-Khobar metropolitan zones. Catering services capture seasonal volume spikes around corporate and government event procurement.
Western Region
Jeddah's port infrastructure anchors halal-certified export capacity targeting Gulf Cooperation Council neighbors. Saudi Standards, Metrology and Quality Organization labeling protocols shape packaging investment for re-export shipments. The Mecca corridor's religious tourism flow concentrates demand for premium catering segments during Hajj and Umrah seasons.
NEOM Northwest
Greenfield urban development is testing same-day chilled delivery infrastructure without legacy wholesale market dependencies. Water pricing reforms threaten cooling system operating costs for controlled-environment housing in this arid zone. Construction-phase labor camps generate institutional catering demand distinct from established urban consumption patterns.
Saudi Arabia Poultry Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's poultry market. Al-Watania Poultry and Almarai Company anchor the integrated segment with captive feed-to-retail infrastructure, while fragmented backyard producers contract under regulatory compression. Three archetypes dominate: vertically integrated feed-to-retail operators, halal-certified export specialists, and foodservice-dedicated processors. Competitive moves center on backward integration into grain milling and cold-chain micro-fulfillment node construction.
Within the integrated tier, Al-Watania Poultry and Almarai Company exemplify capital-intensive operators with laboratory and veterinary infrastructure spanning Riyadh and Jeddah corridors. Tanmiah Food Company occupies a position among halal-certified export specialists targeting Gulf Cooperation Council markets. These three entities represent the consolidation trajectory that SFDA's tightened antibiotic residue standards are accelerating.
| Leading Market Players |
|---|
| Fakieh Poultry Farms |
| Americana Group |
| Al-Watania Poultry |
| BRF |
| Sunbulah Group |
| Almarai Company |
| Entaj |
| Radwa Food Company |
| Tanmiah Food Company |
| Others |
Value Chain & Pricing Dynamics
SFDA halal certification and electronic traceability mandates gate both slaughter facility qualification and price tiering across chilled, frozen, and live-bird segments. Buyers with HACCP-compliant supplier audits command premium positioning while fragmented backyard producers face margin compression from compliance capex.
Pricing Analysis
Long-term offtake contracts dominate foodservice procurement, with quick-service restaurant chains locking consistent bird weights and antibiotic-free certification through annual volume agreements. Price differentiation separates HACCP-certified integrated operators from wholesale-dependent competitors, with the latter facing intensifying cost compression from feed grain import tariffs. Foodservice buyers show lowest price sensitivity given portion-control specifications, while household retail segments prioritize per-kilogram pricing over production method documentation.
Supply Chain Analysis
Inventory lead times for yellow corn and soybean meal stretch 45-60 days from Black Sea and South American origins, tethering feed conversion economics to maritime logistics volatility. Supply concentration centers on the Kingdom's central corridor integrated operators, with captive grain milling insulating margin structures from import tariff swings. Single-source vulnerability in veterinary drug imports threatens biosecurity compliance timelines. Distribution runs through contracted cold-chain networks serving Riyadh and Jeddah foodservice corridors, with e-commerce micro-fulfillment nodes emerging as parallel downstream infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as SFDA electronic traceability mandates create interoperability requirements between slaughter facilities, laboratory testing workflows, and buyer audit systems. This ecosystem shift rewards operators with integrated data infrastructure.
For Market Incumbents: Secure captive feed milling capacity to anchor margin structures against grain import tariff volatility. Deepen cold-chain micro-fulfillment node density in Riyadh and Jeddah corridors before e-commerce channel saturation. SFDA's tightened antibiotic residue standards threaten fragmented competitors lacking laboratory infrastructure.
For New Entrants and Emerging Players: Same-day chilled delivery reliability gaps in Eastern Province expatriate corridors offer white-space entry points. Target institutional catering segments in NEOM construction-phase labor camps with flexible volume scheduling. Partner with quick-commerce platforms for direct-to-consumer channel access rather than building wholesale market dependencies.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HACCP-compliant slaughter and processing facilities, favoring scaled operators with veterinary infrastructure. Long-term viability frames toward integrated feed-to-retail archetypes with Gulf Cooperation Council export certification. Monitor feed grain import tariff adjustments as the primary inflection signal for margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Milling | Captive yellow corn and soybean meal production insulates feed conversion economics from Black Sea supply disruptions. |
| Cold-Chain Micro-Fulfillment Expansion | Dedicated chilled delivery nodes in Riyadh and Jeddah capture e-commerce velocity among younger urban households. |
| Halal Export Certification Investment | Blockchain-enabled documentation unlocks Gulf Cooperation Council cross-border offtake for integrated processors. |
| Automated Climate System Deployment | Precision ventilation and feeding systems maintain 18-24°C grow-out environments required by foodservice procurement contracts. |
| SFDA Electronic Traceability Integration | Digital logging systems for veterinary drug administration align with slaughter facility compliance mandates and buyer audit protocols. |
Study Parameters
The analysis maps broiler, layer, turkey, and duck segments, each validated through primary interviews with feed mill operations directors, slaughter facility quality managers, quick-service restaurant procurement leads, and SFDA compliance officers. Secondary sources include customs records for yellow corn and soybean meal imports, SFDA veterinary drug residue testing disclosures, and Saudi Standards, Metrology and Quality Organization labeling protocols. Bottom-up volume estimates from grow-out cycle throughput triangulate against top-down consumption projections across foodservice, retail, and e-commerce channels.
Consistency checks validated volume and value outputs against feed grain import tonnage trends and cold-chain infrastructure expansion disclosures. Segmentation modeling spans product type, distribution channel, packaging format, and end-user procurement sophistication across the projection horizon. CAGRs derive from feed conversion ratio improvements, regulatory compliance cost trajectories, and channel shift velocity among urban demographics. Forecast inputs incorporate water pricing reform scenarios and expatriate veterinary talent availability constraints.
Underlying assumptions cover SFDA enforcement continuity and Gulf Cooperation Council halal certification mutual recognition, with deviation risk concentrated in Black Sea grain supply disruptions and MOHAP zoonotic disease outbreak response protocols. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Layer Feed Market
Livestock Management
Swine Feed Market
Livestock Management
Poultry Feed Market
Livestock Management
Herd Management Software Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
China Swine Feed Market
Livestock Management
South America Swine Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Layer Breeding System Market
Livestock Management
Hominy Feed Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Animal Feed Protease Market