
 Dairy Herd Management Market | 2026-2036
Dairy Herd Management Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Herd Management Market Intelligence
The capital-intensity divergence between automated rotary parlor specialists and basic stall-equipment suppliers is collapsing as sensor costs fall and software platforms commoditize hardware margins. DeLaval leverages its integrated milking-robot-to-cloud pipeline to sustain premium positioning across Nordic dairy cooperatives. GEA Group Aktiengesellschaft anchors its competitiveness through large-scale manufacturing of parallel milking parlors and refrigeration systems for industrial farms. Afimilk Ltd. differentiates via specialized fertility monitoring algorithms that dominate Israeli and Mediterranean precision breeding programs.
Dairy herd management encompasses integrated systems of hardware sensors, software platforms, and data analytics tools that monitor individual animal health, reproductive cycles, milk yield, and feed efficiency across commercial dairy operations. Core functional parameters include real-time somatic cell count detection, rumination activity measurement via accelerometer neck collars, and automated sort-gate routing based on veterinary alert protocols. Hardware devices and sensors represent mature margin pools where established suppliers compete on reliability and service density, while data analytics platforms capture the fastest-growing segment as cooperative societies and livestock consultants demand predictive disease models and herd-level benchmarking tools. Cloud-based and SaaS deployment modes are displacing on-premise installations among mid-sized dairy farmers seeking lower upfront capital requirements and remote veterinary access.
The EU F-Gas Regulation and MDR constrain refrigerant choices in milk cooling equipment and elevate clinical-validation standards for diagnostic sensors marketed to veterinary services. The USDA and FDA oversee Grade A milk safety protocols that mandate traceable temperature logging and sanitary milking system design, directly shaping equipment procurement specifications for US dairy farmers. Stakeholders must monitor evolving interoperability standards between competing hardware platforms and cloud architectures, as vendor lock-in risks intensify with the proliferation of subscription-based analytics services.
Market Dynamics
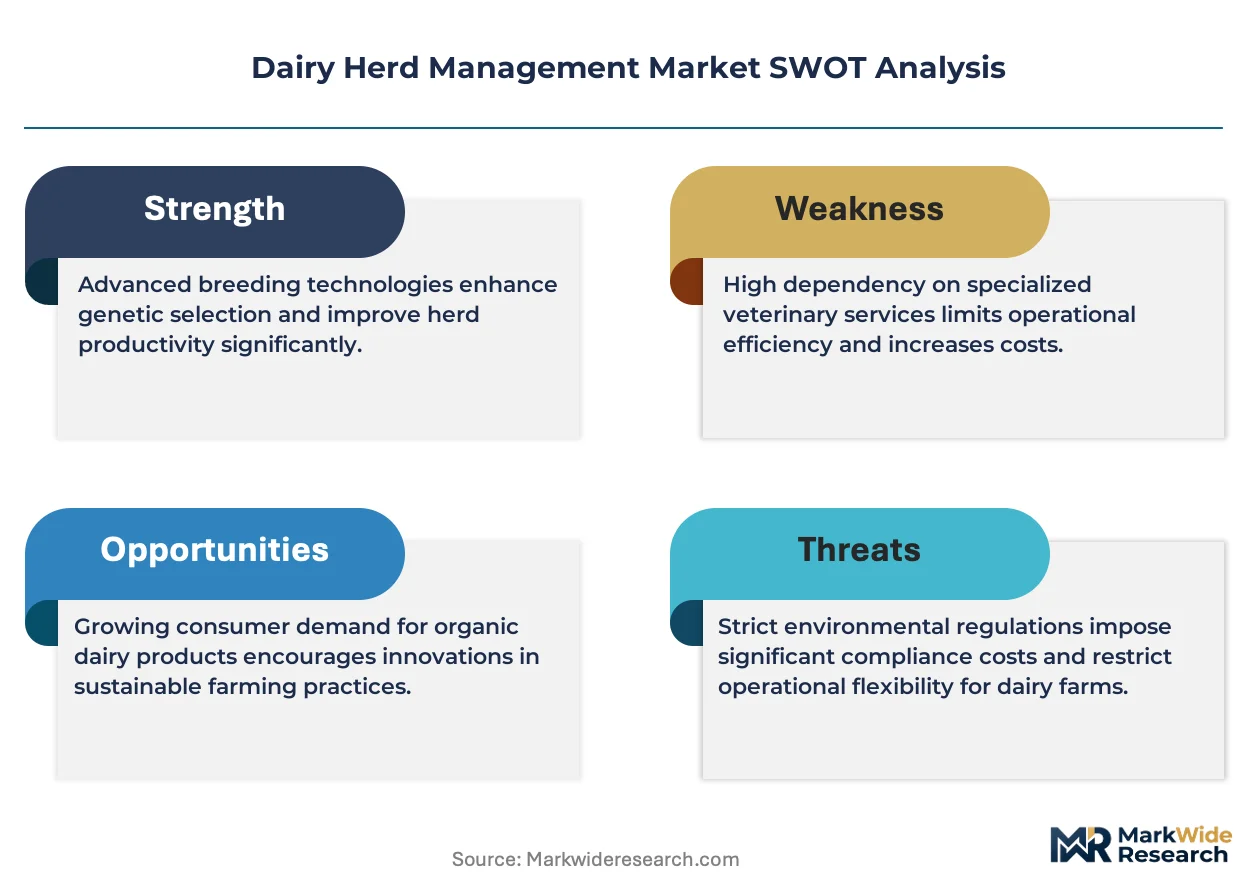
Sensor cost deflation and cloud-platform commoditization are collapsing the traditional margin hierarchy between premium automated milking systems and basic stall equipment, forcing incumbents to defend positioning through software lock-in and service density rather than hardware differentiation.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:Mandates for lower-GWP refrigerants in milk cooling equipment are accelerating replacement cycles for aging bulk tanks and driving demand for integrated heat-recovery systems.
- Large-scale commercial dairy farms:Operations exceeding 500 head are deploying automated rotary parlors with embedded somatic cell count sensors to reduce labor dependency and tighten milk-quality compliance.
- Predictive disease modeling:Machine-learning algorithms trained on rumination and activity data are cutting veterinary intervention response times from days to hours across cooperative-managed herds.
Market Restraints
- Copper and semiconductor input volatility:Price swings in sensor-grade components and milking-parlor electronics compress hardware margins and destabilize equipment financing arrangements.
- Vendor concentration in Nordic precision-equipment manufacturing:Three suppliers control critical rotary-parlor automation IP, creating procurement bottlenecks for North American dairy cooperatives.
- Interoperability gaps between competing cloud architectures:Proprietary data formats prevent seamless integration of fertility monitors from one vendor with milking robots from another, fragmenting herd-level analytics.
Strategic Opportunities
- Underpenetrated pasture-based systems in Ireland and New Zealand:Mobile milking units with GPS-linked cow identification and cloud-synced health records address labor scarcity in seasonal calving operations.
- USDA conservation cost-share programs:Funding streams for precision-agriculture adoption subsidize sensor deployment on mid-sized farms previously priced out of automated monitoring.
- Convergence of genomics and sensor data:Breeding programs integrating real-time phenotypic capture with genomic selection indices are shortening genetic improvement cycles from five years to eighteen months.
Industry Challenges
- Embedded software engineer scarcity:Dairy-equipment manufacturers compete with automotive and medical-device sectors for firmware developers capable of real-time sensor fusion at farm-gate computing scale.
- MDR clinical-validation timelines:Diagnostic sensor vendors face eighteen-to-twenty-four-month approval cycles for veterinary health-alert algorithms, delaying product launches and compressing revenue recognition windows.
- Legacy herd-management software integration:Decades-old on-premise record systems resist API connectivity, forcing costly middleware development for cooperative data-pooling initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Herd Management Market |
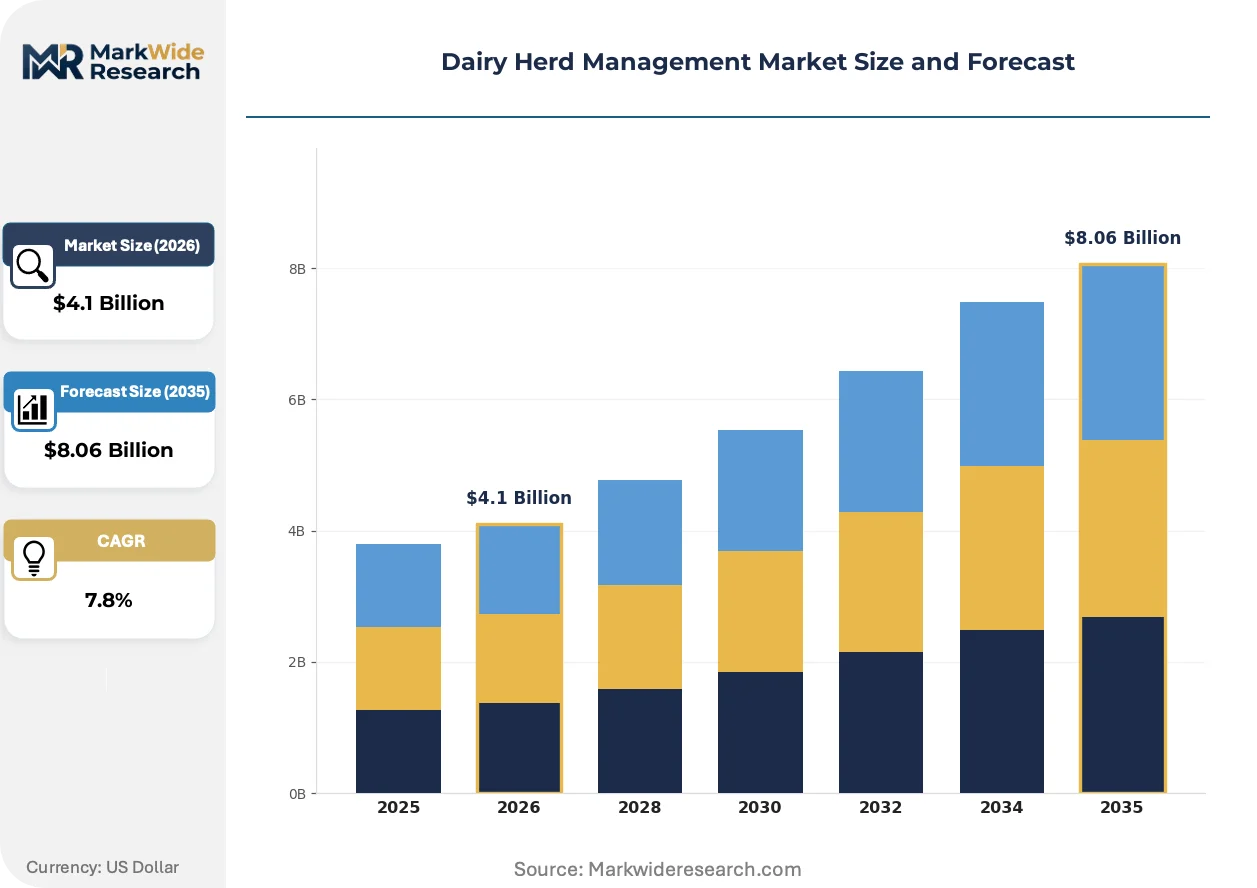
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Sensors, Data Analytics Platforms, Mobile Applications Application: Breeding Management, Health Monitoring, Feed Optimization, Milk Production Tracking, Disease Detection End User: Dairy Farmers, Cooperative Societies, Livestock Consultants, Veterinary Services, Research Institutions Deployment Mode: Cloud-based, On-premise, Hybrid Systems, Edge Computing, SaaS Platforms |
| Companies Covered | DeLaval, GEA Group Aktiengesellschaft, Afimilk Ltd., BouMatic, Lely, Dairymaster, Fullwood Packo, SCR Dairy, VAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Herd Management Market Strategic Shifts & Innovations
Edge computing architectures and low-power wide-area networks are relocating data processing from remote cloud servers to farm-gate installations, cutting latency for real-time health alerts while reducing connectivity dependency in rural dairy clusters.
Computer-vision-based lameness detection using gait-analysis cameras is fragmenting the traditional accelerometer-collar market for locomotion monitoring. Mid-sized Dutch and Danish farms are piloting camera systems at parity pricing with wearable sensors. The technology is fragmenting vendor lock-in by enabling multi-brand hardware mixing through standardized image-recognition APIs.
The EU MDR's software-as-a-medical-device classification for diagnostic algorithms is tightening clinical-evidence requirements for fertility-prediction tools. Vendors must now submit retrospective herd studies to notified bodies before marketing predictive health alerts. Israeli and Mediterranean precision-breeding programs face the steepest compliance ramps due to their reliance on algorithm-driven estrus detection.
Subscription-based analytics unbundling is displacing capital-intensive hardware bundles among 100-to-300-head operations. Farmers lease sensor hardware while paying monthly for predictive disease models and benchmarking dashboards. This shift is most visible in the Netherlands, where Rabobank-structured financing packages wrap SaaS fees into operating credit lines, converting capex barriers into manageable opex flows.
Dairy Herd Management Market Segmentation
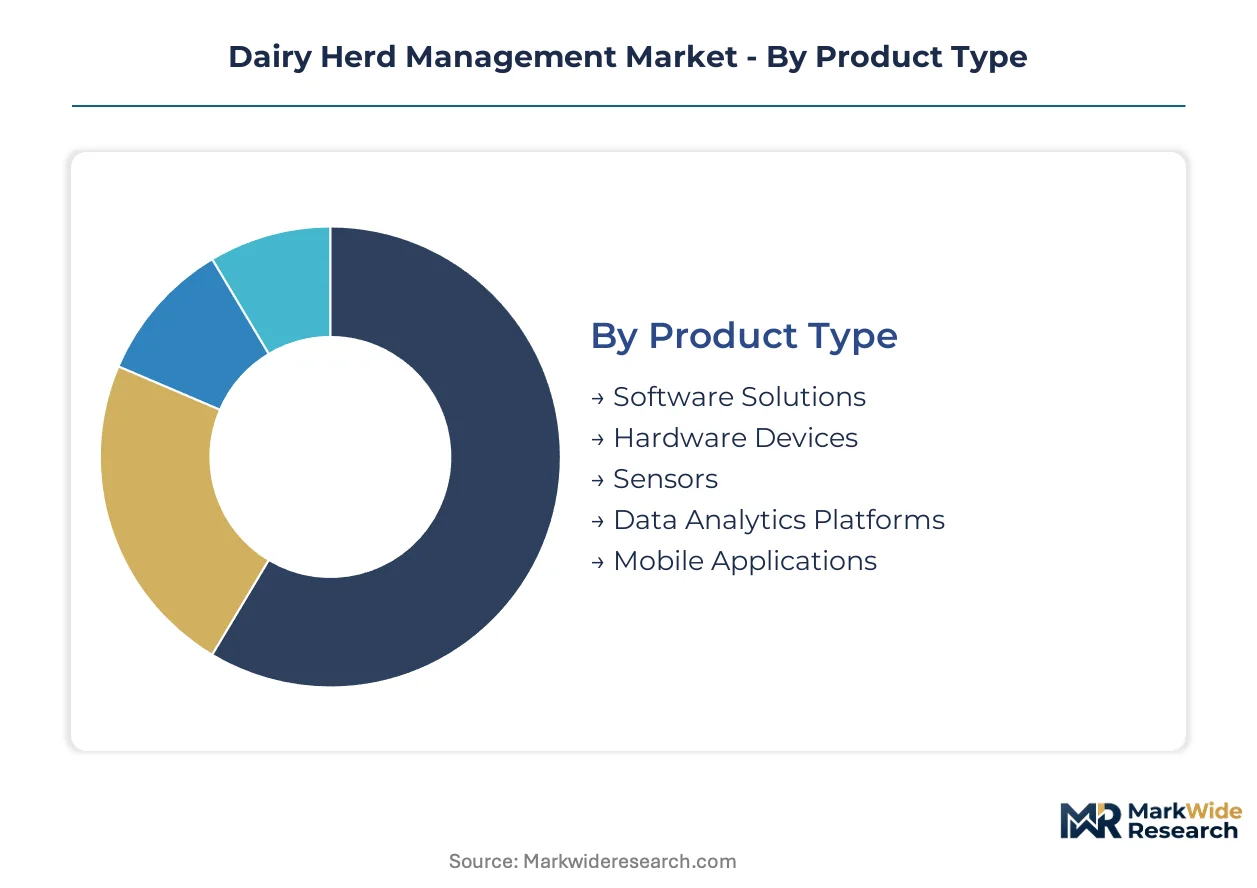
Segmentation in dairy herd management reveals how value migrates from capital-intensive hardware toward recurring software revenue. Farmers prioritize deployment flexibility over equipment ownership, while cooperative societies drive standardization across member farms.
Product Type:
Margin pools concentrate in data analytics platforms and SaaS subscriptions as hardware commoditizes.
- Software Solutions:Herd-management platforms integrate milking records, fertility calendars, and veterinary protocols into unified dashboards. Dutch dairy cooperatives mandate interoperable software standards across member farms to enable benchmarking analytics.
- Hardware Devices:Automated milking parlors, sort gates, and cooling systems anchor capital expenditure budgets. Large-scale operations in the Netherlands deploy rotary parlors with embedded somatic cell count sensors to reduce labor dependency.
- Sensors:Accelerometer neck collars and rumination monitors capture real-time behavioral data.
- Data Analytics Platforms:Cloud-based predictive models for disease detection and feed optimization command subscription premiums.
- Mobile Applications:Smartphone interfaces for remote herd monitoring extend platform reach to smaller operations.
Hardware Devices hold installed capacity. Data Analytics Platforms is rotating up the share rankings.
Application:
Application segmentation tracks where sensor-generated data delivers measurable economic returns.
- Health Monitoring:Continuous vital-sign tracking via wearable devices enables early intervention for metabolic disorders. Israeli precision-breeding programs leverage real-time alerts to cut veterinary response times from days to hours.
- Disease Detection:Machine-learning algorithms trained on rumination patterns identify mastitis and ketosis before clinical symptoms appear. Mediterranean farms face EU MDR validation timelines that delay algorithm deployment.
- Breeding Management:Estrus detection systems synchronize artificial insemination timing.
- Feed Optimization:Ration formulation software balances nutrient intake against milk yield targets.
- Milk Production Tracking:Automated milk meters and quality sensors enforce Grade A compliance protocols.
Health Monitoring commands the steepest expansion trajectory. Disease Detection is gaining share fastest among algorithm-dependent applications.
End User:
End-user segmentation reflects divergent procurement authority between individual farmers and collective entities.
- Cooperative Societies:Member-owned organizations aggregate purchasing power and mandate technology standards across hundreds of farms. Rabobank-structured financing in the Netherlands wraps SaaS fees into operating credit lines for cooperative members.
- Dairy Farmers:Individual operators prioritize payback periods under five years and resist vendor lock-in. Mid-sized farms in seasonal calving regions favor mobile milking units with GPS-linked cow identification.
- Livestock Consultants:Independent advisors drive platform adoption through recommendation influence.
- Veterinary Services:Clinical practices demand MDR-validated diagnostic sensors for liability protection.
- Research Institutions:Universities and breeding centers pilot genomics-sensor convergence projects.
Cooperative Societies concentrate procurement volume. Dairy Farmers is rotating up the share rankings as subscription models lower entry barriers.
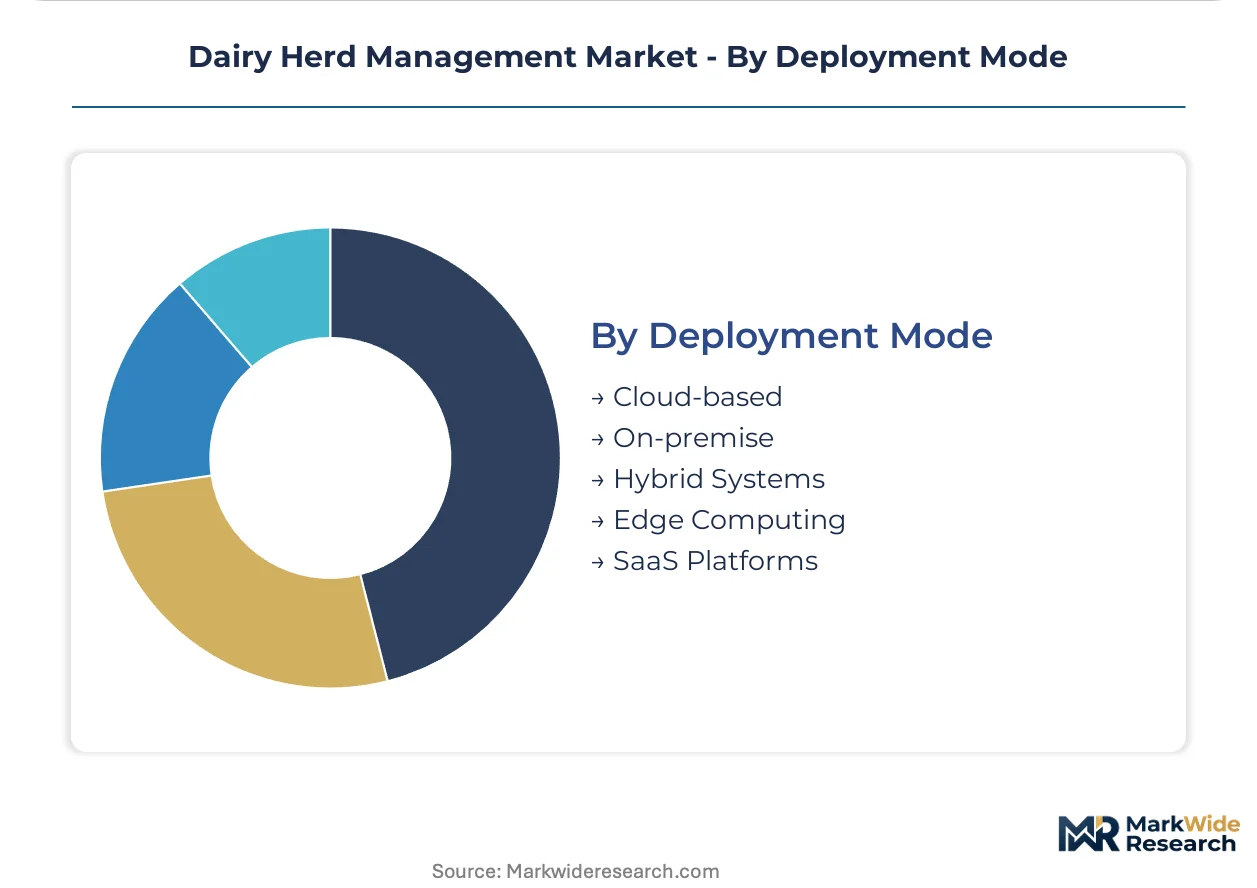
Deployment Mode:
Deployment segmentation captures the shift from capital expenditure toward operational expenditure financing.
- Cloud-based:Remote server hosting eliminates on-farm IT infrastructure and enables veterinary access from anywhere. Irish pasture-based systems rely on cloud-synced health records where connectivity permits.
- SaaS Platforms:Subscription pricing converts sensor hardware costs into predictable monthly fees. USDA conservation cost-share programs subsidize SaaS adoption on mid-sized farms previously priced out of automation.
- On-premise:Local server installations persist where data sovereignty concerns or connectivity gaps dominate.
- Hybrid Systems:Mixed architectures balance real-time processing at the farm gate with cloud-based analytics.
- Edge Computing:Farm-gate data processing reduces latency for critical health alerts in rural dairy clusters.
On-premise holds installed capacity. SaaS Platforms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Dutch and Danish buyers accept premium automation given cooperative financing structures, while Irish and New Zealand pasture-based operators demand mobile units with compressed payback periods. Emerging markets prioritize basic sensor packages over integrated robotics.
Netherlands
Dense dairy farming clusters around Friesland and Gelderland drive automated rotary parlor deployment. Rabobank structures operating credit lines that wrap SaaS fees into manageable opex flows. The EU F-Gas Regulation accelerates replacement cycles for aging bulk milk cooling tanks across cooperative member farms.
United States
USDA conservation cost-share programs subsidize precision-agriculture sensor deployment on mid-sized farms previously priced out of automation. Grade A milk safety protocols from the FDA and USDA mandate traceable temperature logging and sanitary milking system design. Large-scale operations exceeding 500 head concentrate in Wisconsin and California's Central Valley.
Germany
Baden-Württemberg and Lower Saxony anchor industrial dairy farm concentration. The EU MDR elevates clinical-validation standards for diagnostic sensors marketed to veterinary services. Manufacturers face eighteen-to-twenty-four-month approval cycles for health-alert algorithms.
Israel
Precision-breeding programs leverage real-time fertility monitoring to cut veterinary response times from days to hours. Mediterranean operations face steep EU MDR compliance ramps for algorithm-driven estrus detection tools. The country's dairy technology sector clusters around Rehovot's agricultural research corridor.
New Zealand
Seasonal calving operations in Waikato and Canterbury demand mobile milking units with GPS-linked cow identification. Pasture-based systems require cloud-synced health records where rural connectivity permits. Farmers resist capital-intensive fixed installations given volatile milk price cycles.
Dairy Herd Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in dairy herd management equipment. Three Nordic suppliers control critical rotary-parlor automation intellectual property, creating procurement bottlenecks for North American cooperatives. The specialist tier fragments across sensor manufacturers, software platforms, and regional dairy equipment fabricators. Dominant competitive moves include subscription-based analytics unbundling and strategic partnerships between equipment makers and agricultural finance institutions.
Within the integrated systems tier, DeLaval and GEA Group Aktiengesellschaft exemplify full-stack competitors spanning milking robotics through cloud platforms. Afimilk Ltd. occupies a specialized position in fertility monitoring algorithms. These three anchors demonstrate how market positioning now depends on software lock-in and service density rather than hardware differentiation alone.
| Leading Market Players |
|---|
| DeLaval |
| GEA Group Aktiengesellschaft |
| Afimilk Ltd. |
| BouMatic |
| Lely |
| Dairymaster |
| Fullwood Packo |
| SCR Dairy |
| VAS |
| Others |
Cost & Logistics Intelligence
Sensor-grade semiconductor substitution for legacy electromechanical components is redrawing procurement geography from Nordic precision-equipment hubs toward Asian electronics manufacturing clusters while compressing hardware margins and elevating software licensing premiums.
Pricing Analysis
After-sales service contracts and predictive analytics subscriptions now generate the majority of lifetime customer value, displacing upfront equipment margins. Three-tier pricing structure across premium integrated robotics, standard parallel parlors, and economy sensor packages reflects divergent service bundling levels. Cost compression in hardware tiers stems from cloud-platform commoditization and falling sensor input costs. Mid-sized dairy farmers exhibit the steepest price sensitivity, demanding sub-five-year payback periods, while cooperative societies accept extended amortization for benchmarked data access.
Supply Chain Analysis
Sweden and Denmark anchor rotary-parlor automation manufacturing and embedded software development. The Netherlands concentrates cooling equipment and precision sensor assembly. China feeds semiconductor-grade components and cloud infrastructure hardware. Raw material dependencies span copper for electrical systems, rare earth elements for sensor magnets, and refrigerant-grade steel for milk cooling tanks. Single-source vulnerability concentrates in Nordic IP for robotic milking arm kinematics. Distribution runs through agricultural equipment dealers and cooperative procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a defensive-moat story anchored in regulatory entrenchment. The EU MDR and F-Gas Regulation create eighteen-to-twenty-four-month validation barriers that cement incumbent positions and deter speculative entry.
For Market Incumbents: Secure algorithmic lock-in through API-controlled data architectures that resist interoperability mandates. Deepen backward integration into edge-computing chip design to escape semiconductor input volatility. The MDR clinical-validation bottleneck protects market share but requires sustained regulatory affairs investment.
For New Entrants and Emerging Players: Anchor in mobile milking units for Irish and New Zealand pasture-based systems where fixed automation penetration remains minimal. Target 100-to-300-head operations with subscription-unbundled sensor leasing wrapped into agricultural credit products. Partner with regional livestock consultants for endorsement leverage.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors software-specialist acquisitions over hardware capacity expansion. Long-term viability hinges on predictive disease model accuracy and cooperative data-pooling scale. Watch MDR enforcement consistency across notified bodies as the critical inflection signal for algorithm-dependent valuation tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Analytics Unbundling | Converts capital barriers into operating expenditure flows through Rabobank-structured financing. |
| Edge Computing Architecture Deployment | Reduces cloud dependency latency for real-time veterinary alerts in rural dairy clusters. |
| Genomics-Sensor Data Convergence | Shortens genetic improvement cycles by integrating real-time phenotypic capture with breeding indices. |
| MDR Clinical-Validation Investment | Secures algorithm marketing authorization for fertility-prediction tools across EU veterinary services. |
| Cooperative Data-Pooling Infrastructure | Enables benchmarking analytics across Friesland and Gelderland member farms through interoperable standards. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy cooperative technology officers, livestock consultants, veterinary service procurement leads, and precision-equipment R&D directors. Secondary validation drew from EU MDR notified body guidance documents, USDA conservation program disbursement records, FDA Grade A milk safety protocols, and Rabobank agricultural financing disclosures. Bottom-up equipment shipment data triangulated against top-down cooperative membership technology adoption surveys.
Across the analysis window, forecasts modeled product type segmentation spanning hardware devices, software platforms, and data analytics subscriptions alongside deployment mode differentiation between cloud-based SaaS and on-premise installations. CAGRs derived from equipment replacement cycle acceleration under F-Gas Regulation phase-down schedules and sensor cost deflation trajectories. Inputs incorporated cooperative procurement volume aggregation effects and MDR validation timeline compression for algorithm-dependent revenue recognition.
Material uncertainties — regulatory enforcement variance across EU member states, semiconductor input price volatility, and cooperative financing availability shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding MDR notification body capacity and cloud connectivity infrastructure rollout in pasture-based regions. Recalibration cycles align with material shifts in F-Gas refrigerant phase-down schedules and MDR software-as-a-medical-device classification precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Management Software Market
Livestock Management
Wagyu Beef Market
Livestock Management
Layer Feed Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Swine Feed Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Europe Swine Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
Livestock Dewormers Market
Livestock Management
Wild Birds Products Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Africa Alfalfa Hay Market