
 Feed Management Software Market | 2026-2036
Feed Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Management Software Market Analysis
Market Context with Strategic Players
Subscription-based analytics layers is pivoting how feed management vendors monetize their platforms, shifting from perpetual licenses to recurring revenue tied to herd-size tiers. Feedonomics leverages deep API integrations with major ERP systems to anchor its position among mid-sized agricultural cooperatives. ChannelAdvisor competes through multi-platform support that spans feed mills, nutrition consultants, and livestock tracking services. DataFeedWatch specializes in real-time ingredient price indexing, occupying a narrow but defensible niche in volatile commodity markets.
Technical Definition and Structural Segments
Feed management software encompasses digital platforms that formulate, monitor, and optimize animal nutrition programs through algorithmic analysis of ingredient composition, cost variables, and livestock performance metrics, typically processing crude protein, fiber, and energy density data against species-specific dietary requirements. Cloud-based solutions lead deployment preferences among agricultural producers seeking remote access across distributed farm networks, while on-premise systems retain traction with feed manufacturers guarding proprietary formulation databases. API integrations represent the fastest-growing integration level, as livestock owners demand seamless data flow between feed software, milking parlor sensors, and veterinary health records.
Regulatory Frame and Forward-Looking Close
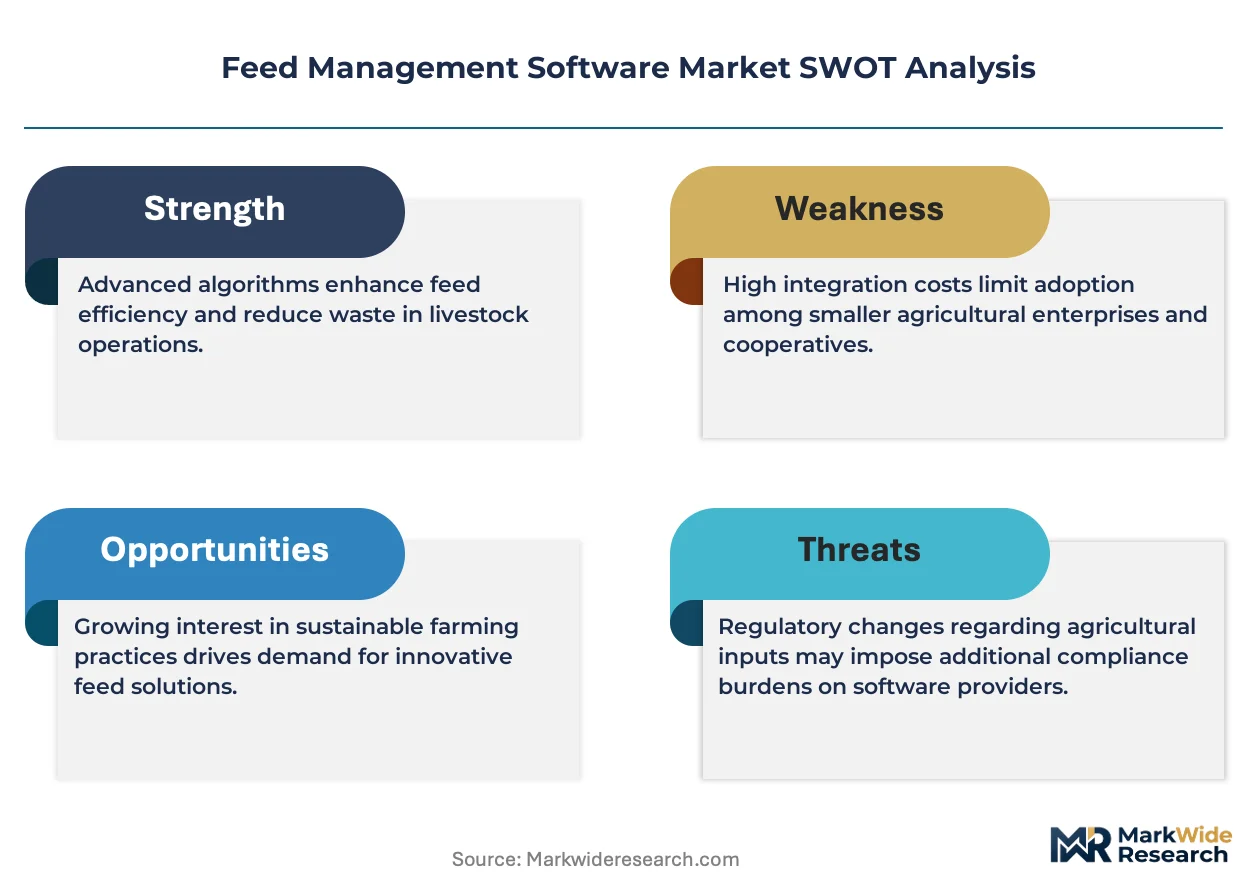
The EU Green Deal and Farm to Fork Strategy shape product standards by mandating greenhouse gas emissions tracking per kilogram of livestock output, forcing software vendors to embed carbon accounting modules. The USDA's National Organic Program and FDA's Veterinary Feed Directive influence formulation compliance workflows, particularly for antibiotic-free and organic certification pathways. Stakeholders must monitor whether emerging sustainability disclosure rules in major protein-exporting nations will require traceability features that current platform architectures can support without costly restructuring.
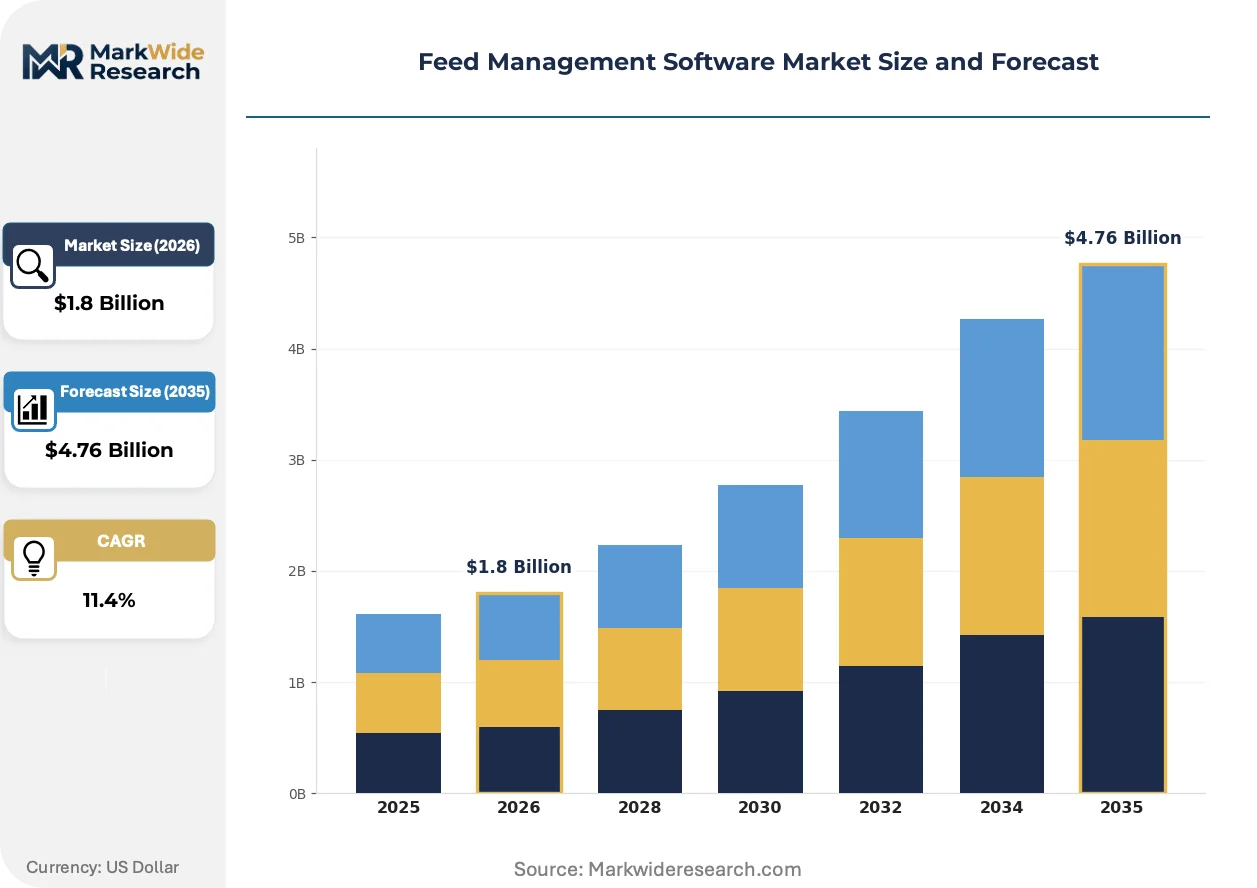
Market Dynamics
The transition from perpetual licenses to recurring revenue models tied to herd-size tiers is restructuring vendor economics and customer retention strategies across livestock operations.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory greenhouse gas emissions tracking per kilogram of livestock output forces feed software vendors to embed carbon accounting modules, creating compliance-driven upgrade cycles.
- Cloud-based platform adoption:Dairy farm cooperatives in the Netherlands are expanding deployment of remote-access feed optimization platforms across distributed farm networks.
- API integration demand:Livestock owners require seamless data flow between feed software, milking parlor sensors, and veterinary health records, accelerating interoperability investments.
Market Restraints
- Ingredient price volatility:Crude protein and energy commodity swings compress formulation margins and destabilize cost-optimization algorithms.
- On-premise system lock-in:Feed manufacturers guarding proprietary formulation databases resist cloud migration, fragmenting addressable market expansion.
- Data sovereignty requirements:Veterinary Feed Directive compliance workflows create jurisdictional friction for cross-border platform standardization.
Strategic Opportunities
- Carbon credit monetization:Precision feeding data streams enable verified emission reductions tradeable under emerging compliance markets.
- Smallholder penetration:India's fragmented dairy sector presents untapped demand for mobile-first feed advisory tools.
- Sensor convergence:Integration of rumen bolus monitors with feed management algorithms enables real-time diet adjustment automation.
Industry Challenges
- Veterinary nutritionist scarcity:Shortage of professionals capable of interpreting algorithmic recommendations limits on-farm implementation quality.
- Legacy system integration:Proprietary data formats in existing herd management software obstruct seamless platform consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Management Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, Hybrid Solutions End User: Agricultural Producers, Feed Manufacturers, Livestock Owners, Consultants Deployment: Subscription-Based, One-Time Purchase, Freemium, Pay-As-You-Go Integration Level: API Integrations, Standalone Systems, Multi-Platform Support, Custom Solutions |
| Companies Covered | Productsup, Intelligent Reach, Feedonomics, FeedOps, VersaFeed, ChannelEngine, ChannelAdvisor, Feedoptimise, DataFeedWatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Management Software Market Emerging Trajectories
Algorithmic formulation engines are compressing the gap between laboratory nutrition science and real-time farm execution, restructuring how dietary programs are designed, monitored, and adjusted.
Edge computing architectures are modularizing feed management deployment by enabling localized data processing at barn-level rather than centralized cloud dependence. Mid-sized agricultural cooperatives in Germany's Bavarian dairy belt are piloting these systems to reduce latency in automated feeding decisions. This distributed approach is modularizing vendor business models away from pure SaaS subscriptions toward hardware-software bundled offerings.
The EU Green Deal's tightening sustainability reporting requirements are mandating traceability features that current platform architectures must retrofit. Feed software vendors are embedding lifecycle assessment calculators to track cradle-to-farm-gate environmental impacts. German and Dutch livestock operations face the steepest compliance cost escalations, driving fastest adoption of integrated carbon-footprint modules.
Subscription pricing tied to animal-unit volumes is displacing flat-rate licensing across cooperative purchasing agreements. Channel consolidation among nutrition consultants is shifting procurement authority toward aggregator platforms that negotiate enterprise-wide software access. This concentration is most pronounced in the Netherlands, where dairy farm cooperatives centralize technology purchasing decisions at federation level.
Feed Management Software Market Segmentation
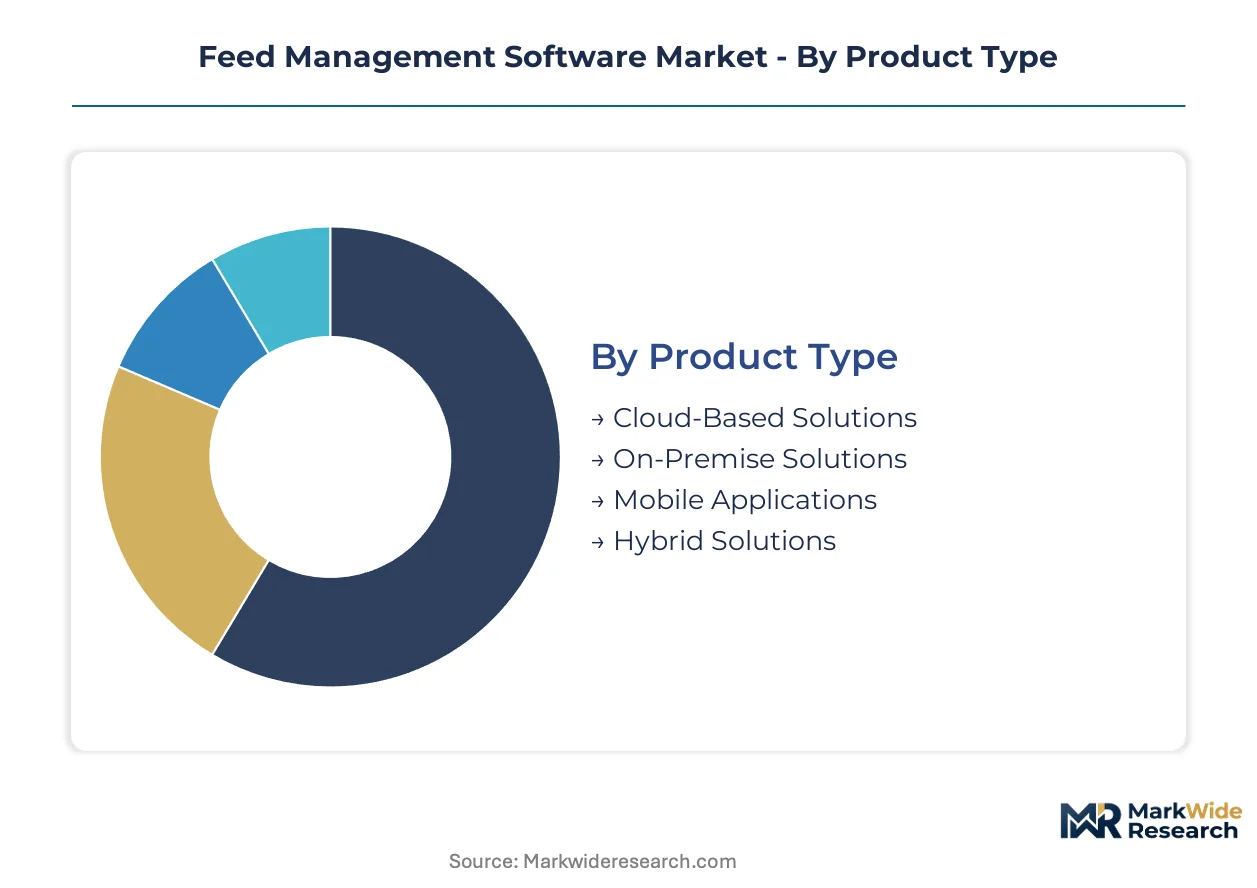
Feed management software segments diverge sharply on regulatory burden, with cloud and API-heavy configurations facing EU Green Deal carbon-accounting mandates while on-premise systems navigate FDA Veterinary Feed Directive data-sovereignty constraints. Understanding these certification fault lines determines which vendor architectures capture compliance-driven upgrade cycles.
Product Type:
EU Green Deal Farm to Fork Strategy carbon-accounting modules are mandatory for cloud-based deployments handling cross-border data flows, while FDA Veterinary Feed Directive compliance workflows constrain on-premise systems guarding proprietary formulation databases.
- Cloud-Based Solutions:Remote-access platforms process crude protein, fiber, and energy density data across distributed farm networks. Dutch dairy cooperatives are expanding deployment fastest, driven by federation-level technology purchasing centralization and EU sustainability reporting deadlines.
- On-Premise Solutions:Localized servers retain proprietary formulation databases behind institutional firewalls. Feed manufacturers in Germany's Bavarian dairy belt resist migration due to intellectual property protection requirements and latency sensitivity in automated feeding decisions.
- Mobile Applications:Smartphone-first advisory tools target India's fragmented dairy sector with offline-capable nutrient calculators.
- Hybrid Solutions:Edge computing architectures enable barn-level processing with periodic cloud synchronization, piloted by mid-sized German agricultural cooperatives.
Leading the category by volume: Cloud-Based Solutions. Growing fastest: Hybrid Solutions.
End User:
Cost tier stratification separates enterprise-grade deployments from advisory-tool penetration, with livestock owners bearing per-animal-unit subscription scaling while consultants aggregate purchasing across producer networks.
- Agricultural Producers:Farm operators managing mixed livestock portfolios require species-specific dietary requirement modules. Netherlands dairy cooperatives concentrate demand through centralized federation procurement, compressing vendor margins via volume aggregation.
- Feed Manufacturers:Industrial formulators demand batch-optimization algorithms tied to real-time ingredient price indexing. German manufacturers face steepest compliance cost escalations from embedded lifecycle assessment calculators tracking cradle-to-farm-gate impacts.
- Livestock Owners:Individual operators prioritize rumen bolus monitor integration for real-time diet adjustment automation.
- Consultants:Nutrition advisory firms negotiate enterprise-wide software access, shifting procurement authority toward aggregator platforms in concentrated European markets.
Capturing majority revenue: Agricultural Producers. Expanding most quickly: Consultants.
Deployment:
Recurring revenue displacement of perpetual licenses varies by customer scale, with herd-size tiering enabling cooperative penetration while one-time purchases persist among privacy-sensitive manufacturers.
- Subscription-Based:Recurring models tied to animal-unit volumes dominate cooperative purchasing agreements. Dutch dairy federations centralize these negotiations, forcing vendors toward hardware-software bundled offerings.
- One-Time Purchase:Perpetual licenses retain traction where data sovereignty requirements block external hosting. FDA Veterinary Feed Directive compliance workflows create jurisdictional friction favoring this model.
- Freemium:Basic formulation calculators with premium sensor integration upsells target smallholder acquisition in price-sensitive markets.
- Pay-As-You-Go:Transactional pricing for seasonal operations aligns costs with cash-flow cycles in commodity-volatile environments.
Highest revenue concentration: Subscription-Based. Steepest expansion trajectory: Freemium.
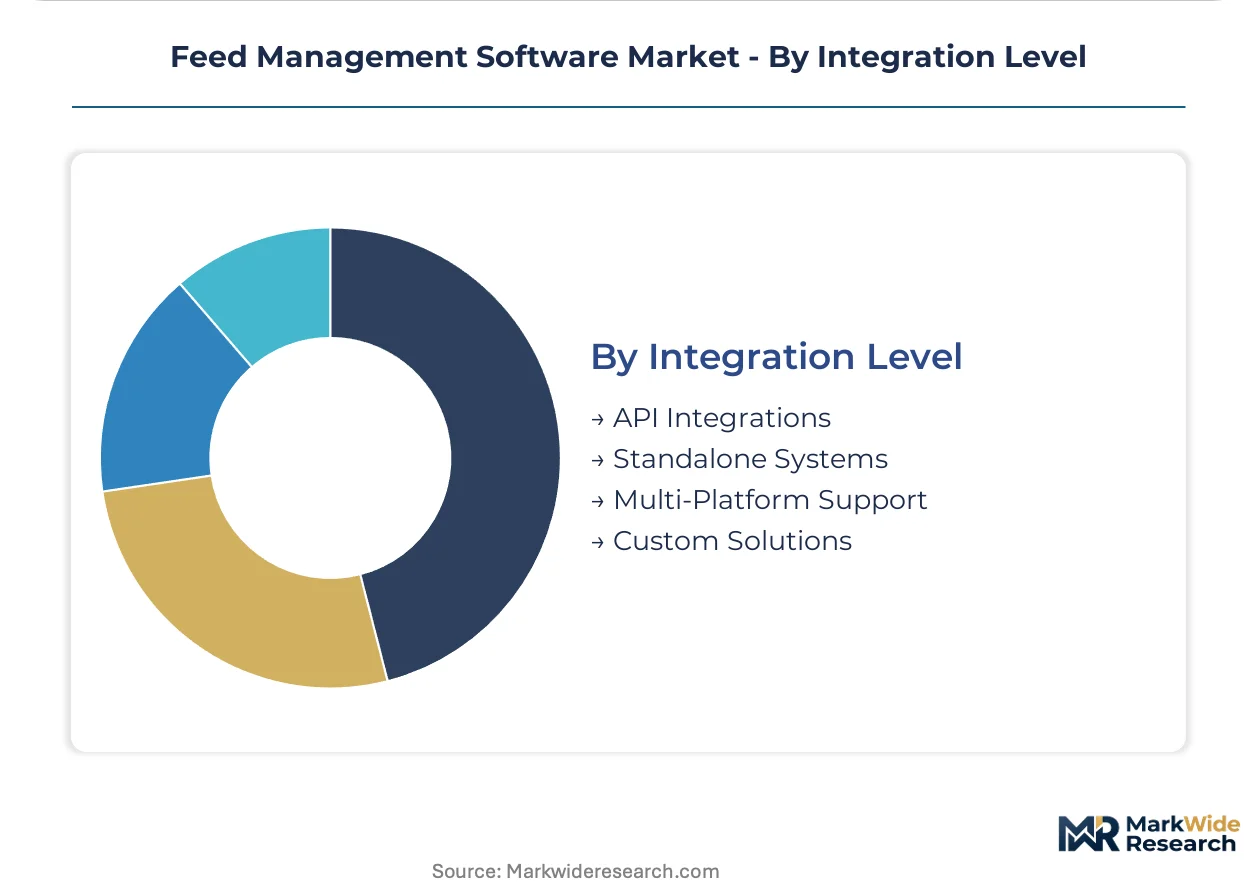
Integration Level:
Interoperability depth determines platform consolidation potential, with API architectures capturing sensor convergence investments while standalone systems defend legacy installed bases.
- API Integrations:Seamless data flow between feed software, milking parlor sensors, and veterinary health records accelerates livestock owner demand. German and Dutch operations lead adoption, driven by precision feeding compliance cost pressures.
- Standalone Systems:Closed architectures persist where proprietary data formats obstruct migration. Legacy herd management software fragmentation limits consolidation quality.
- Multi-Platform Support:Spanning feed mills, nutrition consultants, and livestock tracking services enables channel consolidation capture.
- Custom Solutions:Bespoke development for large cooperatives with unique workflow requirements commands premium pricing.
Gaining share fastest: API Integrations. Defending installed base: Standalone Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software consumption concentrates in European dairy belts where regulatory compliance costs accelerate platform adoption, while production capability clusters around North American and Asian technology hubs serving agricultural export markets.
Netherlands
Dairy farm cooperatives in Friesland and Gelderland drive federation-level procurement of cloud-based feed optimization platforms. The EU Green Deal's Farm to Fork Strategy mandates greenhouse gas emissions tracking per kilogram of milk output, forcing embedded carbon accounting modules. Eindhoven-based technology clusters supply API integration expertise for sensor convergence projects.
Germany
Bavarian dairy operations face steepest precision feeding compliance cost escalations in Europe, accelerating hybrid solution pilots. The country's national agricultural regulator enforces strict data sovereignty requirements for veterinary feed records. Munich and Stuttgart industrial corridors host feed manufacturers resisting cloud migration due to proprietary formulation protection needs.
United States
Midwest feedlot operators and California dairy cooperatives generate demand for antibiotic-free certification pathway software. The FDA's Veterinary Feed Directive shapes formulation compliance workflows, particularly for organic livestock operations. Chicago and Des Moines serve as procurement hubs where nutrition consultants aggregate enterprise-wide platform access.
India
Fragmented dairy sectors in Maharashtra and Gujarat present untapped demand for mobile-first feed advisory tools with offline-capable nutrient calculators. The country's food safety regulator pushes digitization of livestock record-keeping under national dairy development schemes. Anand and Pune clusters incubate low-cost sensor integration startups targeting smallholder penetration.
Brazil
Large-scale beef and poultry integrators in São Paulo and Mato Grosso deploy batch-optimization algorithms tied to volatile commodity price indexing. The country's national agricultural supply company influences technology adoption through subsidized precision agriculture programs. Campinas technology parks host emerging feed software vendors serving Latin American protein export markets.
Feed Management Software Market Vendor Landscape
Capital-heavy platform developers compete with asset-light integration specialists, creating a tiered structure where full-stack vendors absorb infrastructure costs while modular players capture niche interoperability contracts. The vendor base separates into three strategic archetypes: ERP-anchored enterprise suites, API-native middleware providers, and commodity-focused price indexing specialists. Consolidation pressure intensifies through cooperative purchasing centralization in European dairy markets and strategic partnerships between sensor hardware manufacturers and algorithm developers.
Within the API-native tier, DataFeedWatch occupies a position exemplifying real-time ingredient price indexing specialization, while Feedonomics represents deep ERP integration anchoring among mid-sized agricultural cooperatives. ChannelAdvisor sits within the multi-platform support archetype, spanning feed mill operations and livestock tracking services through channel consolidation capture. These three companies illustrate how competitive positioning diverges between narrow defensibility in volatile commodity data and broad interoperability across distributed farm networks.
| Leading Market Players |
|---|
| Productsup |
| Intelligent Reach |
| Feedonomics |
| FeedOps |
| VersaFeed |
| ChannelEngine |
| ChannelAdvisor |
| Feedoptimise |
| DataFeedWatch |
| Others |
Supply Flow & Price Mechanics
Edge computing architectures are modularizing feed management deployment by enabling localized data processing at barn-level, simultaneously compressing latency-sensitive subscription tiers and concentrating hardware-software bundling decisions among German and Dutch cooperatives with federation-level procurement authority.
Pricing Analysis
Margin tightening in cloud-based tiers reflects veterinary nutritionist scarcity driving implementation support costs upward. Subscription models tied to animal-unit volumes dominate cooperative purchasing, with price differentiation hinging on API integration depth and embedded carbon-accounting certification. Pricing pressure intensifies in the mobile-application tier as Indian smallholder penetration demands offline-capable nutrient calculators at minimal cost. Feed manufacturers guarding proprietary databases exhibit lowest price sensitivity, while fragmented dairy operators in emerging markets face acute budget constraints.
Supply Chain Analysis
Specialized software engineering talent shortages in Eindhoven, Munich, and Bangalore constrain platform development velocity for sensor-integrated modules. Supply concentrates in the Netherlands, Germany, and India, with raw material dependencies spanning cloud infrastructure services, precision agriculture sensors, and veterinary data APIs. Single-source vulnerability in rumen bolus monitor manufacturing creates chokepoint exposure. Distribution runs through agricultural cooperative federations in Europe and nutrition consultant aggregators in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic formulation engine capacity scarcity props pricing power for vendors with embedded carbon-accounting modules, as EU Green Deal compliance deadlines outstrip qualified development team availability.
For Market Incumbents: Acquire specialized API integration teams to anchor position against middleware specialists eroding enterprise accounts. Consolidate sensor hardware partnerships to defend against feed manufacturers developing captive rumen monitoring capabilities. Prioritize carbon credit verification workflow investments as regulatory disclosure requirements tighten. For New Entrants and Emerging Players: The mid-tier price gap between premium ERP-anchored suites and economy mobile tools offers entry space for hybrid edge-computing offerings. Target Bavarian dairy cooperatives piloting barn-level processing with freemium sensor integration upsells. Deploy through nutrition consultant aggregators consolidating procurement authority in concentrated European markets. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP vendors seeking livestock vertical penetration. Long-term viability favors platforms with veterinary health record interoperability and proven carbon-accounting module deployment. Watch EU Green Deal enforcement variance across member states as inflection signal for compliance-driven upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Seamless data flow between feed software and milking parlor sensors satisfies livestock owner interoperability demands in Germany. |
| Carbon Accounting Module Launch | Embedded lifecycle assessment calculators capture EU Green Deal compliance-driven upgrade cycles among Dutch cooperatives. |
| Edge Computing Deployment | Barn-level processing architectures reduce latency for automated feeding decisions in Bavarian precision dairy operations. |
| Mobile-First Advisory Tool | Offline-capable nutrient calculators penetrate India's fragmented smallholder dairy sector at minimal customer acquisition cost. |
| Sensor Hardware Bundling | Rumen bolus monitor integration enables real-time diet adjustment automation, shifting procurement toward combined offerings. |
Methodological Framework
Independent corroboration across feed software vendor executives, veterinary nutritionists, and agricultural cooperative procurement officers underwrites the qualitative findings. Secondary validation draws from EU regulatory filings, USDA National Organic Program documentation, FDA Veterinary Feed Directive guidance, and livestock technology trade association reports. Bottom-up segmentation modeling triangulates against top-down market sizing from cloud infrastructure deployment disclosures and sensor manufacturer shipment data.
Rate-of-change decomposition separates volume expansion from value capture across deployment model, herd-size tier, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from algorithmic formulation engine adoption curves, carbon-accounting module attach rates, and cooperative purchasing centralization trends. Forecast inputs incorporate API integration investment cycles and precision feeding compliance cost escalations in named dairy belts.
Inputs from vendor product roadmaps and regulatory enforcement calendars were available through the study window; gaps in smallholder mobile-adoption telemetry introduce uncertainty bands around emerging market penetration assumptions. Forecasts reflect documented assumptions regarding EU Green Deal implementation velocity and veterinary nutritionist workforce expansion. Material deviation in carbon credit market liquidity or sensor hardware supply normalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Cattle Feeder Market
Livestock Management
Cattle Squeeze Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Swine Feed Market
Livestock Management
Bird Feeder Market
Livestock Management
Hominy Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
South America Swine Feed Market
Livestock Management
North America Feed Binders Market
Livestock Management
Herd Management Software Market