
 Swine Feed Market | 2026-2036
Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Feed Market Intelligence
The bundling of feed with farm management software is rebalancing buyer decisions away from pure price considerations. Cargill leverages its global supply chain to offer tailored nutritional solutions across diverse regions. Archer Daniels Midland Company specializes in sourcing and processing key ingredients like soybean meal and corn. Charoen Pokphand Foods PCL dominates Southeast Asian markets via its extensive integrated farming network.
Swine feed is a compound ration formulated for domestic pigs, containing precise energy and protein levels to optimize growth and health. Its composition is scientifically designed to support specific life stages, from farrowing to finishing. Grower and finisher feeds represent the largest volume segments, while starter feeds command higher margins. Corn and soybean meal form the base, but value-added vitamin and mineral premixes are critical for performance.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern feed contaminants and medication usage. In China, national GB standards for feed hygiene dictate permissible ingredient levels and processing requirements, directly impacting market access. Producers must now decide whether to invest in alternative protein sources or optimize existing supply chains for traditional corn and soy.
Market Dynamics
The central tension in the swine feed market is the clash between volatile commodity input costs and intensifying demand from integrated producers for specialized, high-performance formulations mandated by new animal welfare and antibiotic-use regulations.
Growth Catalysts
- Regulatory Mandates:The phase-out of antibiotic growth promoters under FDA and EFSA rules requires the adoption of alternative additives like probiotics and organic acids.
- Production Consolidation:The shift to large commercial farms in China and Brazil boosts demand for standardized, high-efficiency rations that support uniform growth cycles.
- Precision Feeding:Digital farm management tools enable data-driven nutrition, increasing the value of specialized, life-stage-specific formulations.
Market Restraints
- Input Cost Volatility:Producer margins are directly exposed to price fluctuations in core commodities like corn and soybean meal, driven by unpredictable global harvests.
- Disease Outbreak Risk:The threat of African Swine Fever can cause catastrophic demand collapses in key markets, creating extreme instability for feed suppliers.
- Regulatory Friction:Conflicting national standards for ingredients, particularly between China and Western suppliers, act as non-tariff trade barriers.
Strategic Opportunities
- Alternative Proteins:Commercializing novel protein sources like insect meal and algae offers a strategic hedge against the price volatility of soybean meal.
- Functional Additives:Developing scientifically validated ingredients that improve gut health provides a direct replacement for phased-out antibiotic growth promoters.
- Digital Service Bundling:Integrating feed supply with farm management software creates high-value revenue streams tied to animal performance outcomes.
Industry Challenges
- Reformulation Complexity:Removing antibiotic growth promoters requires complex and costly research to find effective alternative additive combinations without compromising piglet health or growth rates.
- Supply Chain Traceability:Meeting demands from food retailers for full traceability of feed ingredients, including certifications for non-GMO or sustainable soy, adds significant logistical and administrative costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Feed Market |
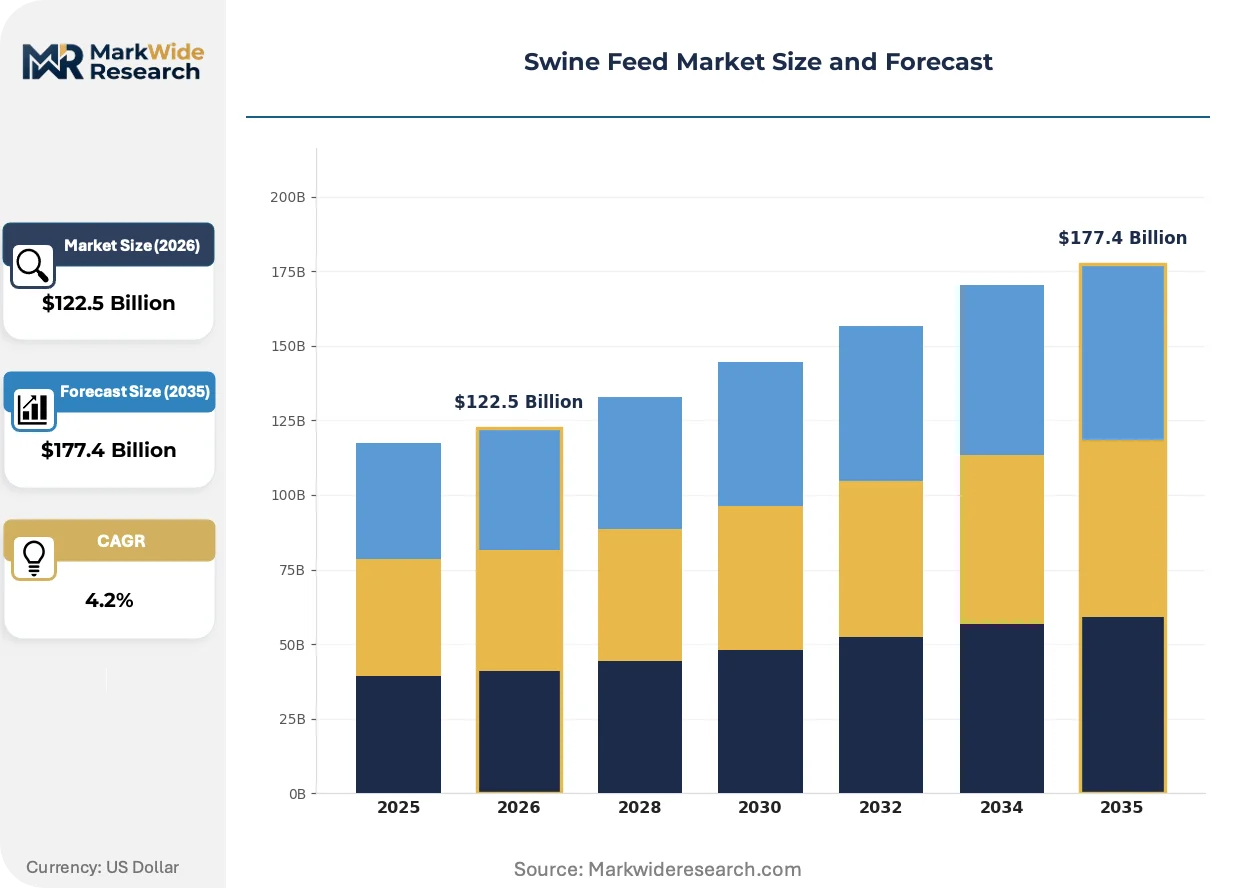
| Market Size in 2026 | $122.5 Billion |
| Market Size in 2035 | $177.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creep Feed, Starter Feed, Grower Feed, Finisher Feed, Sow Feed, Gestation Feed Ingredient: Corn, Soybean Meal, Wheat Middlings, Fish Meal, Vitamin Premix, Mineral Premix Form: Pellets, Mash, Crumbles, Extruded, Textured, Granules End User: Commercial Farms, Family Farms, Contract Farming, Research Institutions |
| Companies Covered | Koninklijke DSM N.V., LALLEMAND Inc., Cargill Incorporated, New Hope Group Co. Ltd., Novus International, Inc., Archer Daniels Midland Company, BASF SE, Charoen Pokphand Foods PCL, Chr. Hansen A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Feed Market Strategic Shifts & Innovations
The market is transforming from a focus on bulk commodity supply to science-driven nutritional solutions. This evolution is driven by the operational demands of large-scale farming and tightening global regulations on animal health and environmental impact.
On-farm nutrient analysis systems, using technologies like near-infrared spectroscopy, provide real-time data on ingredient quality. Large integrated producers are rapidly adopting these tools to fine-tune feed rations daily. This capability is decentralizing formulation control from centralized mills to the individual farm, allowing for more precise and responsive animal nutrition.
European Food Safety Authority (EFSA) mandates are progressively lowering the permissible levels of zinc oxide in piglet feeds to reduce environmental contamination. This forces manufacturers to innovate with non-medicated gut health solutions like protected organic acids and probiotics. Starter and pre-starter feed segments are most impacted, accelerating research into synergistic additive combinations.
A clear shift toward sustainability-verified supply chains is altering ingredient purchasing criteria for major feed producers. Large food companies and retailers now require documented proof of sustainable sourcing for key inputs like soybean meal. This change is most advanced in Northern Europe, where downstream pressure for low-carbon pork products is most intense.
Swine Feed Market Segmentation
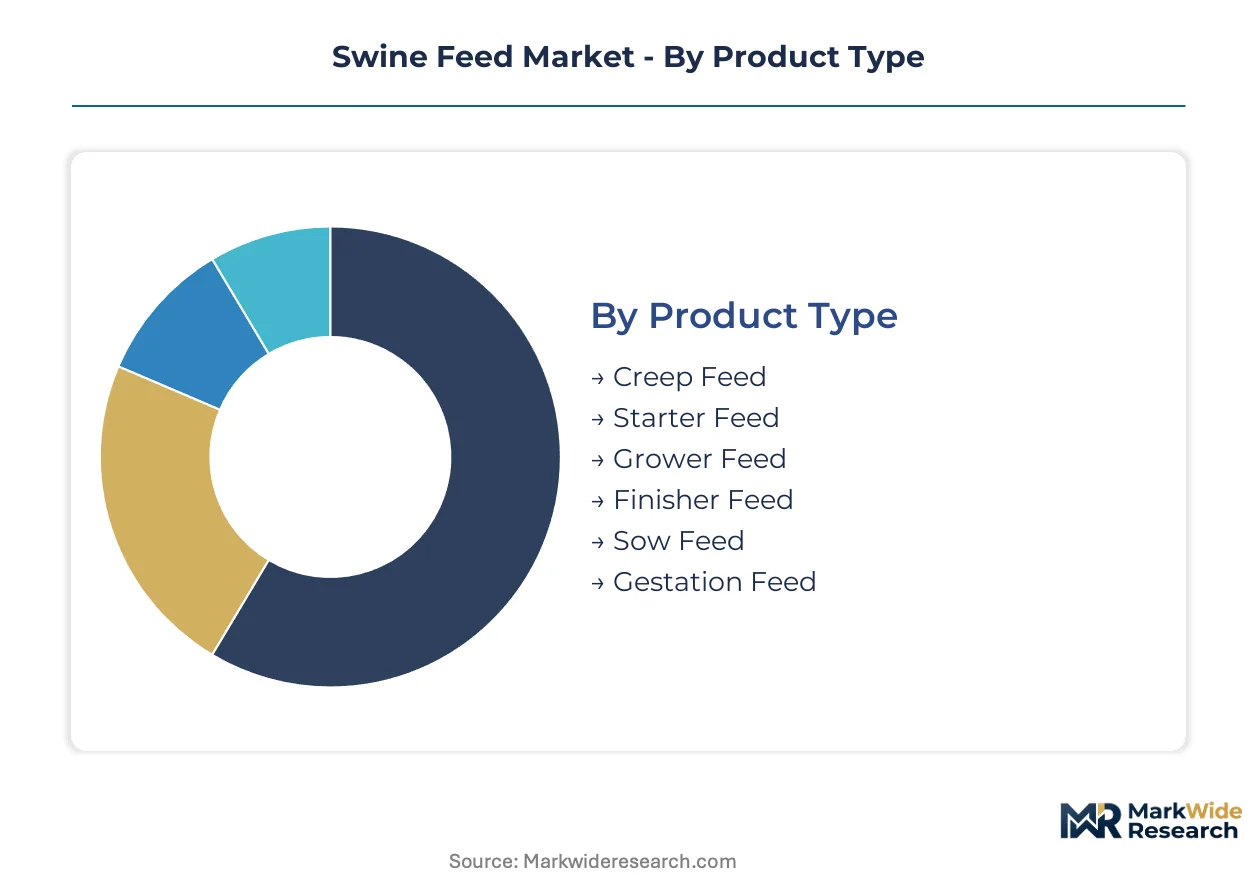
The swine feed market requires precise segmentation to address the diverse nutritional needs of pigs at various life stages and the operational demands of different farm types. Understanding these segments is crucial for manufacturers to develop targeted formulations and optimize supply chain strategies.
Product Type:
The swine feed market segments by product type, reflecting the precise nutritional requirements across different pig life stages.
- Creep Feed:This specialized feed is formulated for piglets transitioning from sow's milk to solid food, typically high in digestible protein and lactose to support early digestive development. Demand for Creep Feed is concentrated in large farrow-to-finish operations in China.
- Starter Feed:Designed for young pigs post-weaning, Starter Feed contains highly palatable ingredients and specific amino acid profiles to promote rapid growth and gut health. Producers in Europe prioritize Starter Feed innovation due to strict antibiotic reduction mandates.
- Grower Feed:Formulated for pigs in their mid-growth phase, Grower Feed balances protein and energy for muscle development and efficient feed conversion. Large commercial farms in Brazil represent a significant demand base for standardized Grower Feed.
- Finisher Feed:This feed type targets pigs nearing market weight, optimizing lean meat deposition and carcass quality. Its formulation focuses on energy density and specific amino acid ratios.
- Sow Feed:Tailored for breeding sows, Sow Feed supports reproductive performance, milk production, and overall maternal health. Specific formulations vary based on gestation and lactation cycles.
- Gestation Feed:Provided to pregnant sows, Gestation Feed ensures proper fetal development and prevents excessive weight gain, crucial for farrowing success.
Mature deployment sits with Finisher Feed. Newer deployment is concentrated in Starter Feed.
Ingredient:
Ingredient composition dictates both nutritional efficacy and production cost within swine feed formulations.
- Corn:Serving as the primary energy source in most swine diets, corn provides digestible carbohydrates essential for growth and metabolic function. Volatile global harvests directly impact feed costs for producers in the United States.
- Soybean Meal:This ingredient provides a crucial protein source, rich in essential amino acids necessary for muscle development and overall pig health. Demand for sustainably sourced Soybean Meal is increasing from European feed manufacturers.
- Wheat Middlings:A co-product of wheat milling, Wheat Middlings offer a fibrous energy source and contribute to gut health. Its inclusion often depends on regional availability and cost-effectiveness.
- Fish Meal:A highly digestible protein source, Fish Meal is particularly valuable in starter diets for its palatability and amino acid profile. Its usage is constrained by price volatility and sustainability concerns.
- Vitamin Premix:These concentrated blends supply essential vitamins, crucial for immune function, metabolism, and overall animal well-being. Premixes are vital for performance in intensive farming systems.
- Mineral Premix:Providing necessary trace minerals, Mineral Premix supports bone development, enzyme activity, and reproductive health. Specific mineral levels are tailored to life stage and regional deficiencies.
The market for Corn and Soybean Meal dominates overall volume. Value-added Vitamin Premix and Mineral Premix segments exhibit a steeper expansion trajectory.
Form:
Feed form directly influences palatability, digestion efficiency, and waste reduction in swine operations.
- Pellets:Formed by compressing feed ingredients, Pellets improve palatability, reduce dust, and prevent ingredient segregation, leading to better feed intake and conversion. Commercial farms in China widely adopt Pellets for efficiency.
- Mash:Mash feed consists of ground ingredients in a loose form, offering a cost-effective option for producers. It is commonly used in smaller operations or for specific dietary requirements.
- Crumbles:Crumbles are finely broken pellets, often used for young pigs due to their ease of consumption and improved digestibility. This form bridges the gap between mash and pellets for piglets.
- Extruded:Extruded feeds involve cooking ingredients under high pressure, improving digestibility and nutrient absorption, particularly for starter diets. This form is gaining traction for its performance benefits.
- Textured:Textured feeds combine different particle sizes and forms, often including whole grains, to enhance palatability and stimulate appetite. This form caters to specific niche markets.
- Granules:Similar to crumbles but often with a more uniform particle size, Granules are used for specific life stages or specialized formulations. They offer a balance of palatability and reduced waste.
Pellets and Mash forms capture the largest installed capacity. Specialized forms like Extruded and Granules are gaining share fastest among producers.
End User:
End-user categories differentiate based on operational scale, purchasing power, and specific feed customization needs.
- Commercial Farms:These large-scale operations prioritize high-efficiency, standardized feed formulations to maximize production output and minimize costs. Their demand for specialized, life-stage-specific feeds drives innovation in the market.
- Family Farms:Typically smaller in scale, Family Farms often seek more versatile feed options or rely on local suppliers for their swine nutrition needs. Cost-effectiveness is a primary purchasing consideration for these farms.
- Contract Farming:Under this model, feed specifications are often dictated by integrators, ensuring consistent quality and performance across contracted operations. This segment concentrates purchasing power through large-scale agreements.
- Research Institutions:These entities require highly specialized and experimental feed formulations for studies on animal nutrition, genetics, and disease resistance. Their demand is for precision and flexibility in feed composition.
Commercial Farms command significant purchasing influence. Research Institutions provide critical demand for specialized, experimental formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zones of concentrated agricultural production, particularly in major pork-producing nations, drive regional demand for specialized swine feed formulations. These areas benefit from government initiatives supporting large-scale livestock operations and feed processing infrastructure. Such concentrated production optimizes supply chain logistics and encourages advanced nutritional solutions.
China
China's vast commercial farms drive significant demand for specialized creep and starter feeds. National GB standards for feed hygiene dictate permissible ingredient levels and processing requirements, impacting market access. The Yangtze River Delta region features dense concentrations of integrated swine farms and feed mills, optimizing feed distribution.
Brazil
Regulatory frameworks from ANVISA govern feed contaminants and medication usage within the country. Large commercial farms represent a significant demand base for standardized grower feed formulations. The state of Santa Catarina, a major pork-producing hub, sees extensive adoption of high-efficiency feed rations.
Germany
European Food Safety Authority (EFSA) mandates progressively lower permissible zinc oxide levels in piglet feeds. German producers prioritize starter feed innovation due to strict antibiotic reduction mandates. North Rhine-Westphalia, a key agricultural state, hosts advanced feed research facilities and integrated pig production.
United States
Volatile global harvests directly impact feed costs for corn, the primary energy source in most swine diets. The US Food and Drug Administration (FDA) governs feed contaminants and medication usage, particularly regarding antibiotic growth promoters. The Corn Belt states, including Iowa and Illinois, anchor large-scale swine production and feed ingredient sourcing.
Vietnam
The country's expanding commercial swine sector fuels demand for high-performance, life-stage-specific formulations. The Ministry of Agriculture and Rural Development (MARD) oversees feed quality and safety standards. Integrated farming networks in the Mekong Delta region concentrate feed consumption and processing activities.
Swine Feed Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the swine feed sector. The market exhibits a tiered structure, with large global players leveraging extensive supply chains to offer comprehensive solutions. Strategic archetypes include integrated food companies, specialized animal nutrition firms, and commodity ingredient processors. Geographic expansion into high-growth regions and continuous portfolio diversification are common competitive moves among these entities.
At the scale-driven end, Cargill Incorporated, a US-based multinational conglomerate, leverages its global supply chain for tailored nutritional solutions. Archer Daniels Midland Company, another US-based firm, occupies a position as a major processor and supplier of key ingredients like soybean meal and corn. Charoen Pokphand Foods PCL, a Thai public company limited, exemplifies an integrated farming network model, dominating Southeast Asian markets through extensive in-house feed production and distribution. These companies represent different facets of market participation, from ingredient sourcing to integrated farming.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| LALLEMAND Inc. |
| Cargill Incorporated |
| New Hope Group Co. Ltd. |
| Novus International, Inc. |
| Archer Daniels Midland Company |
| BASF SE |
| Charoen Pokphand Foods PCL |
| Chr. Hansen A/S |
| Others |
Cost & Logistics Intelligence
Specialized nutritionist expertise in European markets creates labor-cost differentials that contribute to premium pricing for advanced swine feed formulations, particularly in starter and pre-starter segments. This cost structure directly influences the availability and price points of high-performance feed solutions across different regions.
Pricing Analysis
Premium pricing for short lead times characterizes specialized swine feed orders, reflecting the urgency of maintaining consistent animal nutrition schedules. The market utilizes a hybrid pricing model, combining commodity spot pricing for base ingredients like corn and soybean meal with contract-based long-term offtake for value-added premixes. Price differentiation stems from quality grade, such as non-GMO certifications, and the level of customization for specific life stages. Pricing pressure stems from volatile commodity input costs, impacting producer margins. Family Farms exhibit the highest price sensitivity, while large Commercial Farms prioritize performance over cost for specialized formulations.
Supply Chain Analysis
Direct-to-farm deliveries from regional feed mills manage the bulk of swine feed distribution, particularly for large commercial operations. Geographic supply concentration for key inputs centers on the United States and Brazil for corn and soybean meal, with China serving as a major local producer and consumer. The supply chain relies heavily on raw material dependencies, including corn, soybean meal, and specialized vitamin premixes. Commodity price volatility, driven by unpredictable global harvests, represents a significant structural risk. Distribution frequently occurs through integrated farming networks, ensuring efficient delivery to concentrated production zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swine feed market operates as a supply-constrained environment, where specialized additive manufacturing capacity creates a bottleneck, propping up pricing for functional ingredients.
For Market Incumbents:
Anchor global market share through strategic investments in sustainable sourcing certifications for soybean meal and corn, mitigating regulatory shifts. Acquire specialized additive manufacturers to deepen vertical integration into functional ingredient production. Develop proprietary alternative protein sources to hedge against commodity price volatility and reduce reliance on traditional inputs. Expand digital service bundling with farm management software to enhance customer loyalty and capture outcome-based revenue streams.
For New Entrants and Emerging Players:
Veterinary clinics and animal health distributors represent ideal channel partners for new entrants offering novel gut health solutions. Target the starter feed segment in Europe, leveraging strict antibiotic reduction mandates to introduce scientifically validated functional additives. Focus on commercializing alternative protein sources like insect meal for niche markets seeking sustainable options. Implement digital platforms that integrate feed supply with precision feeding tools, offering data-driven nutritional insights to smaller commercial farms.
For Investors and Strategic Acquirers:
The window for entry favors specialized biotech firms with proven functional additive portfolios over the long-term horizon. Focus acquisition strategies on companies possessing proprietary alternative protein technology or advanced data-driven nutrition platforms. These targets offer significant intellectual property and market differentiation in a consolidating industry. A clear signal to watch is the rapid commercialization of insect meal or algae protein at scale, indicating a shift in ingredient sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Sustainable Sourcing | Secures market access in environmentally conscious regions like Northern Europe for major feed producers. |
| Acquire Additive Manufacturers | Enhances control over critical functional ingredient supply, replacing phased-out antibiotic growth promoters. |
| Develop Alternative Proteins | Diversifies ingredient portfolio, reducing exposure to volatile corn and soybean meal prices. |
| Integrate Digital Farm Tools | Creates high-value revenue streams tied to animal performance outcomes for large commercial farms. |
| Expand into Starter Feed Segment | Addresses high-margin demand for specialized formulations driven by strict European regulatory mandates. |
Research Approach
Multi-period observation of commodity price indices and feed formulation shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with swine nutritionists, large commercial farm managers, feed mill operators, and regulatory affairs specialists. Secondary validation drew from FDA filings, EFSA reports, USDA agricultural statistics, and company financial reports. This approach enabled robust bottom-up and top-down triangulation of market data.
Segment-weighting across product type, ingredient, form, and end-user categories informed the quantitative modeling over the projection horizon. Compound annual growth rates were derived from historical data and projected market expansion, considering shifts in pork production volumes. The analytical framework also incorporated anticipated regulatory changes impacting feed additives and regional consumption patterns as key forecast inputs across the analysis window.
Caveats apply where sudden disease outbreaks or major geopolitical shifts could materially shift the outlook for commodity prices. Forecasts reflect documented assumptions regarding regulatory stability and technological adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Roughage Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Bird Feeder Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
South America Swine Feed Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Layer Breeding System Market
Livestock Management
North America Swine Feed Market
Livestock Management
Wagyu Beef Market
Livestock Management
Cattle Feeder Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
North America Feed Binders Market