
 North America Ruminant Feed Premix Market | 2026-2036
North America Ruminant Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ruminant Feed Premix Market Analytics
Buyer concentration among large-scale dairy cooperatives and integrated beef cattle operations is hardening across the region. Cargill, Incorporated leverages its grain origination network to secure cost-advantaged vitamin and mineral inputs for captive premix production. Archer Daniels Midland Company anchors its position through backward integration into amino acid and enzyme manufacturing. BASF SE differentiates via specialty carotenoid and organic trace mineral portfolios targeting high-performance herds.
North America ruminant feed premix denotes a precisely blended mixture of vitamins, minerals, amino acids, and functional additives dosed at 0.5% to 3% of total ration weight, manufactured through multi-stage micro-dosing and homogeneous mixing to prevent nutrient segregation during transport and storage. Its primary purpose is to close nutritional gaps in base forages and grains, thereby optimizing rumen fermentation efficiency, reproductive performance, and immune competence in cattle, sheep, and goats. Vitamin premix commands stable volume but faces margin compression from commodity vitamin price cycles, while nutritional additives including yeast derivatives and rumen-protected fats represent the fastest-expanding margin pool as producers seek alternatives to antibiotic growth promoters. Mineral premix retains foundational demand in pasture-based systems across the Great Plains, though powder form premixes are losing share to granular and pellet formats that reduce dust losses and improve handler safety.
The FDA Veterinary Feed Directive and USDA organic certification standards jointly constrain medicinal additive inclusion, compelling reformulation toward preventive health applications and nutritional support categories. State-level environmental regulations in California and Wisconsin regarding phosphorus runoff further shape mineral premix specifications, particularly for confined dairy operations. Stakeholders must monitor evolving EPA nutrient management criteria and regional feed-safety audits to anticipate compliance-driven product redesign cycles.
Market Dynamics
The FDA Veterinary Feed Directive compels feed manufacturers to eliminate antibiotic growth promoters from ruminant formulations, redirecting R&D investment toward rumen microbiome modulators and precision mineral delivery systems that satisfy compliance without sacrificing performance metrics.
Growth Catalysts
- Upper Midwest dairy belt expansion:Large-scale operations across Wisconsin, Minnesota, and Iowa drive bulk premix procurement volumes as herd sizes consolidate above 1,000 head per facility.
- USDA organic certification standards:Premium milk pricing differentials incentivize certified organic premix adoption, particularly among cooperatives supplying private-label retailers.
- Rumen-protected fat technologies:Energy-dense bypass fat formulations improve feed conversion efficiency in high-producing Holstein herds during early lactation.
Market Restraints
- Vitamin price volatility:Commodity vitamin A and E cycles squeeze formulation margins, forcing premix producers to absorb cost spikes or renegotiate annual contracts with dairy cooperatives.
- Phosphorus runoff regulations:Wisconsin and California environmental standards constrain mineral premix phosphorus content, limiting traditional limestone-dicalcium phosphate blends in confined operations.
- Base ingredient substitution:Distillers grains and alternative protein meals displace conventional corn-soy rations, reducing standardized premix dosing requirements per ton of finished feed.
Strategic Opportunities
- Canadian prairie pasture systems:Underpenetrated beef cow-calf operations across Alberta and Saskatchewan present volume expansion potential for mineral premixes tailored to extensive grazing.
- EPA nutrient management incentives:Emerging cost-share programs for precision feeding technologies create demand for premixes with embedded real-time formulation adjustment capabilities.
- Yeast derivative-bioactive convergence:Combining live yeast cultures with polyphenol extracts offers differentiated positioning against commodity yeast products in the preventive health category.
Industry Challenges
- Rumen microbiome modeling expertise:Shortage of nutritionists trained in next-generation sequencing data interpretation delays customized premix deployment for high-performance herds.
- Multi-species certification complexity:Simultaneous FDA, USDA Organic, and state-level feed safety audits extend product launch timelines by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ruminant Feed Premix Market |
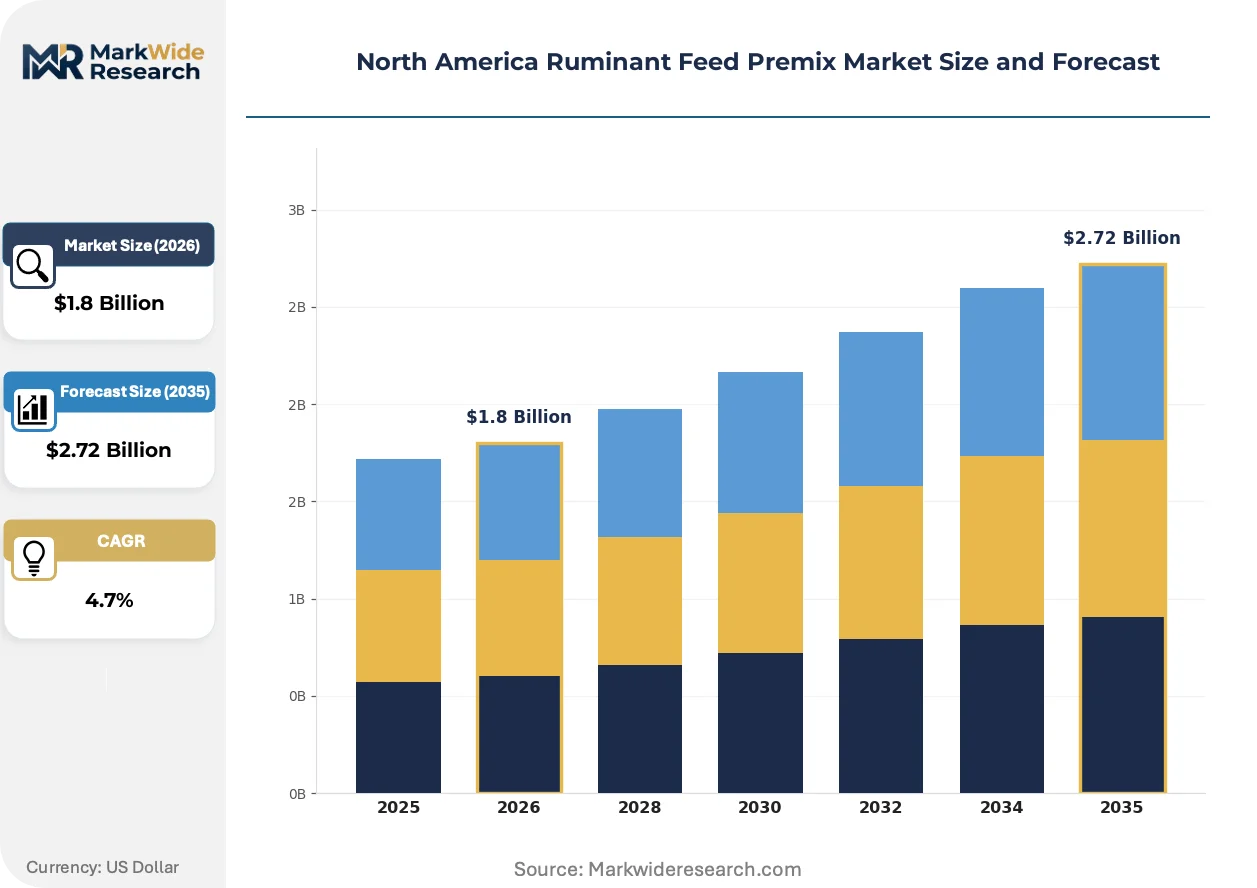
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premix, Vitamin Premix, Nutritional Additives, Medicinal Additives Form: Powder, Granular, Liquid, Pellet End User: Dairy Farms, Beef Cattle Operations, Sheep Production, Goat Farms Application: Growth Promotion, Preventive Health, Nutritional Support, Feed Efficiency |
| Companies Covered | Archer Daniels Midland Company, BASF SE, Kemin Industries, Inc., DSM-Firmenich AG, Land O'Lakes Inc., Cargill, Incorporated, IFF (Danisco Animal Nutrition), Biomin, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ruminant Feed Premix Market Evolving Landscape
Precision livestock technologies and microbiome science are redefining premix formulation from static nutrient supplementation toward dynamic, animal-specific intervention platforms that integrate real-time metabolic feedback.
Rumen-protected choline and betaine formulations are electrifying the transition cow nutrition segment. Large dairy operations in California's Central Valley and New York's Finger Lakes region are adopting these methyl donor technologies at 15-20% annual expansion rates. The shift is compressing demand for traditional fat-soluble vitamin premixes while elevating specialty additive margins.
The FDA Veterinary Feed Directive's prohibition of medically important antibiotics in feed is reshaping medicated additive portfolios. Producers must reformulate ionophore and coccidiostat programs under veterinary oversight, redirecting investment toward organic acid and essential oil blends. Confined dairy operations in Wisconsin and beef feedlots in the Texas Panhandle face the steepest compliance redesign cycles.
Direct procurement from integrated premix manufacturers is displacing traditional distributor relationships among the largest dairy cooperatives. Bulk volume buyers now negotiate captive supply agreements that bypass regional feed dealers. This consolidation is most visible across the I-29 dairy corridor stretching from South Dakota through Iowa into northern Missouri.
North America Ruminant Feed Premix Market Segmentation
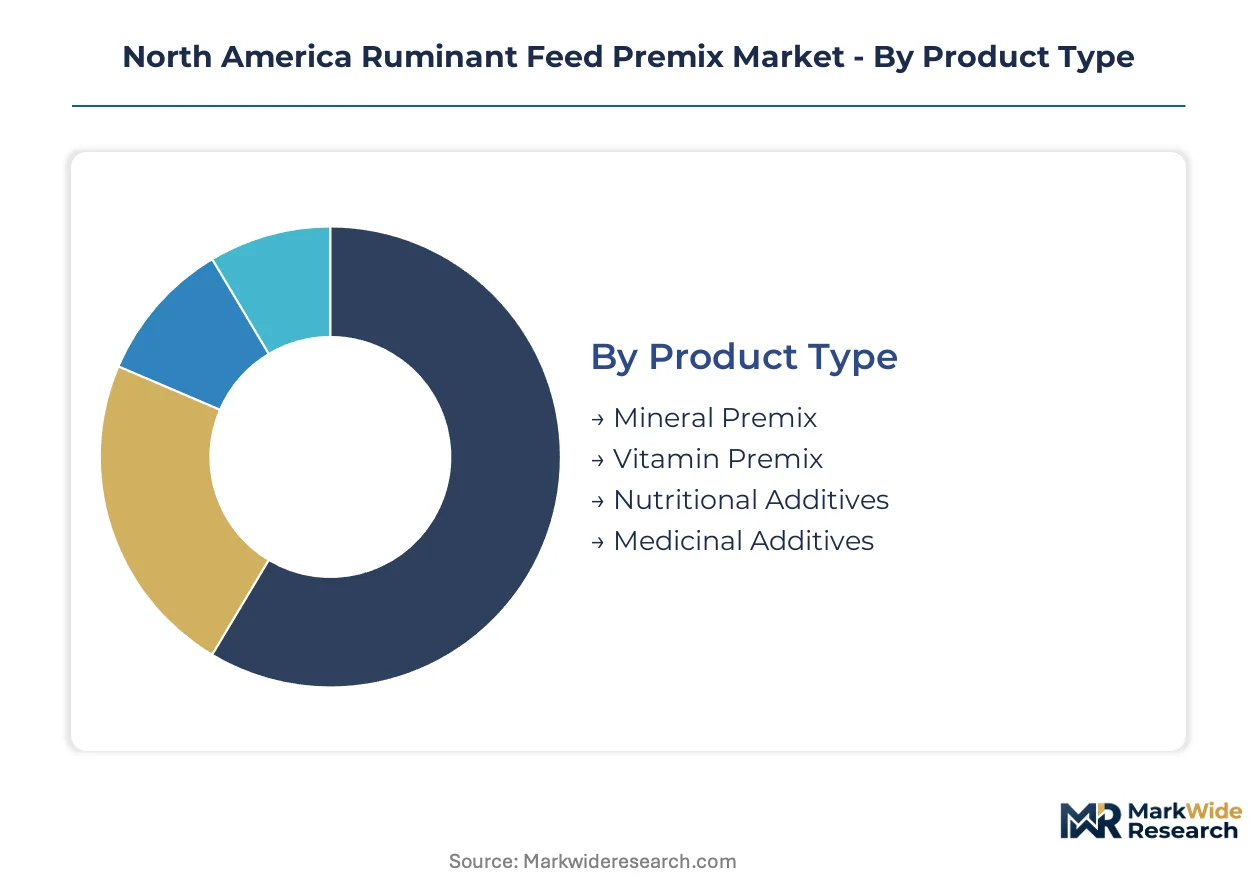
North American ruminant feed premix segmentation reflects divergent supply chain economics across functional categories. Product type and formulation choices directly determine manufacturing complexity, regulatory burden, and margin capture potential for premix suppliers serving the region's consolidated dairy and beef operations.
Product Type:
Supply concentration clusters around mineral and vitamin premix production, where backward integration into bulk vitamin synthesis and mineral sourcing creates cost advantages for integrated manufacturers.
- Mineral Premix:Blends of macro and trace minerals including selenium, zinc, and copper formulated to correct forage deficiencies. Demand concentrates in Great Plains pasture-based beef operations and Upper Midwest confined dairies where Wisconsin and Minnesota regulators enforce phosphorus runoff limits. The FDA Veterinary Feed Directive has eliminated antibiotic growth promoters, redirecting mineral premix R&D toward rumen microbiome support.
- Vitamin Premix:Fat-soluble and water-soluble vitamin complexes dosed at 0.5-1.5% of ration weight to prevent deficiency diseases and optimize metabolic efficiency. California's Central Valley dairies and New York's Finger Lakes region drive premium vitamin premix volumes for high-producing Holstein herds facing heat stress and transition cow metabolic challenges. Commodity vitamin price volatility squeezes formulation margins during supply disruptions.
- Nutritional Additives:Yeast derivatives, rumen-protected fats, and organic acid blends displacing traditional medicated additives. Beef feedlots across the Texas Panhandle and Kansas are adopting these alternatives fastest under veterinary oversight requirements.
- Medicinal Additives:Ionophores and coccidiostats now restricted to veterinary prescription under FDA VFD compliance. Reformulation toward preventive health applications dominates R&D investment.
Today's leader: Mineral Premix. Tomorrow's challenger: Nutritional Additives.
Form:
Cost tier differentiation separates commodity powder formats from premium granular and pellet technologies that reduce handling losses and improve safety compliance.
- Powder:Fine-ground homogeneous blends offering lowest unit cost but highest dust exposure during handling. Large cooperative dairies across Iowa and South Dakota continue bulk powder procurement for on-farm mixing despite OSHA respiratory hazard concerns.
- Granular:Agglomerated particles with reduced segregation tendency during transport. Alberta and Saskatchewan beef operations favor granular mineral premixes for extensive pasture supplementation where infrequent handling demands physical stability.
- Liquid:Suspension or solution formulations enabling precise metered delivery through automated feed systems. Ontario dairy operations lead liquid premix adoption for total mixed ration integration.
- Pellet:Compressed cylindrical forms eliminating dust entirely and improving handler safety. Wisconsin confined dairies facing state-level feed safety audits are converting pellet formats fastest for mineral and vitamin premix categories.
Powder retains volume leadership. Pellet gains share fastest among safety-conscious operators.
End User:
Customer type concentration among large-scale operations creates procurement power asymmetries that reshape pricing structures across all premix categories.
- Dairy Farms:Confined operations with 1,000+ head driving bulk premix demand for transition cow nutrition and lactation optimization. The I-29 corridor from South Dakota through northern Missouri anchors North American dairy premix consumption.
- Beef Cattle Operations:Feedlots and cow-calf producers requiring mineral supplementation for grazing systems and finishing rations. Canadian prairie provinces present underpenetrated expansion potential for extensive grazing mineral programs.
- Sheep Production:Smaller-scale operations with specialized copper-sensitive formulations. Niche demand concentrates in Texas Hill Country and Rocky Mountain range operations.
- Goat Farms:Emerging dairy goat enterprises in Wisconsin and California requiring species-adapted mineral ratios. USDA organic certification compliance drives premium premix adoption.
Dairy Farms dominate procurement volumes. Beef Cattle Operations represent the steepest expansion trajectory.
Application:
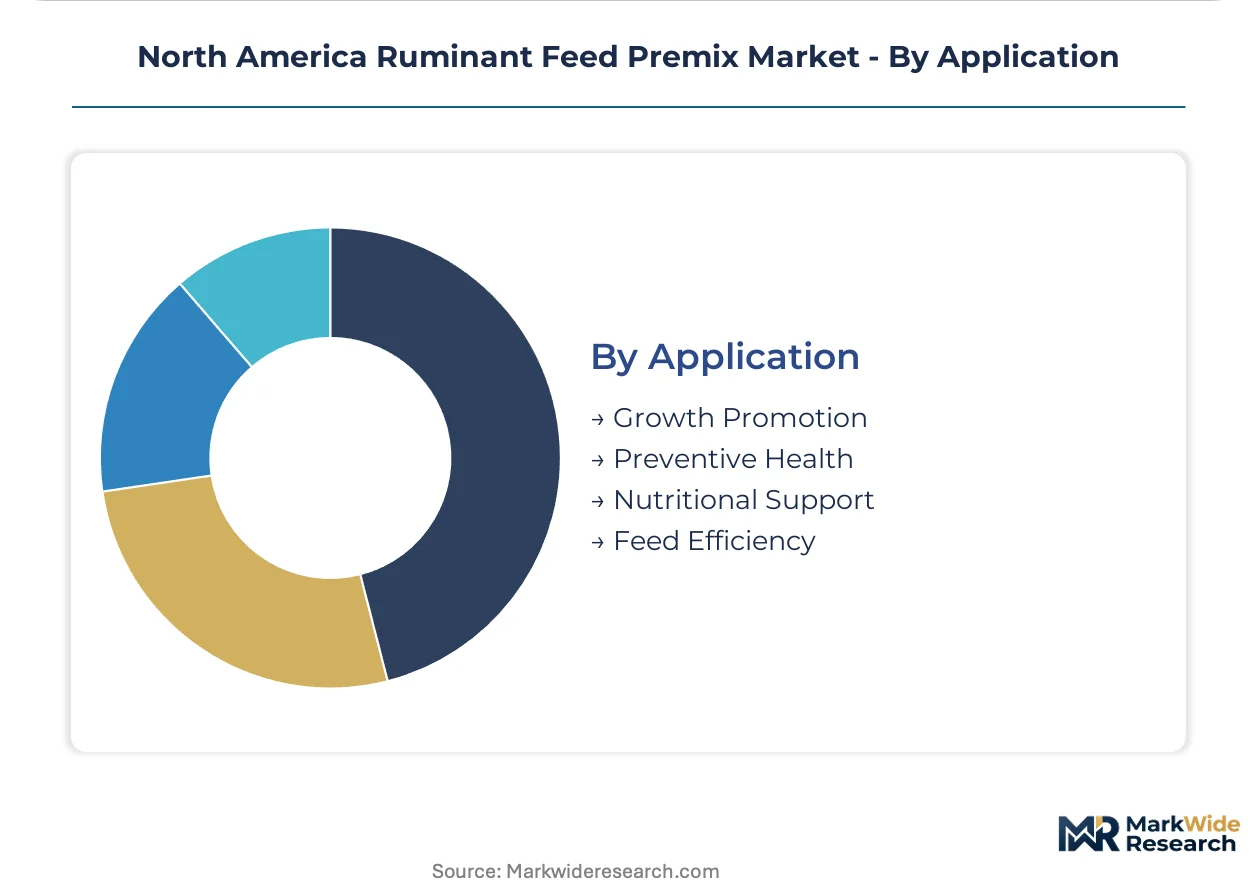
Margin stratification favors preventive health and feed efficiency applications over commodity growth promotion as regulatory constraints reshape formulation economics.
- Growth Promotion:Traditional antibiotic-dependent applications now restricted under FDA VFD. Reformulation toward rumen microbiome modulators and metabolic enhancers dominates supplier pipelines.
- Preventive Health:Immune competence and disease resistance formulations gaining share as producers eliminate subtherapeutic antibiotics. California and Wisconsin dairies lead adoption of yeast derivative and essential oil blends.
- Nutritional Support:Deficiency correction and metabolic optimization for transition cows and stressed animals. Rumen-protected choline and betaine formulations are electrifying this segment in high-production herds.
- Feed Efficiency:Energy and protein utilization optimization through rumen-protected fats and amino acid balancing. Feedlots across Nebraska and Colorado prioritize efficiency premixes amid volatile feed grain costs.
Preventive Health commands premium positioning. Feed Efficiency is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger premix volumes than Canada, though Canadian prairie operations present steeper expansion trajectories for mineral supplementation programs.
United States
Wisconsin's confined dairies and California's Central Valley herds drive differentiated premix demand for transition cow nutrition and heat stress mitigation. The FDA Veterinary Feed Directive restricts antibiotic growth promoters, redirecting formulation investment toward rumen microbiome modulators. The I-29 corridor from South Dakota through northern Missouri anchors concentrated bulk procurement among 1,000+ head operations.
Canada
Alberta and Saskatchewan beef cow-calf operations require extensive grazing mineral premixes with physical stability for infrequent pasture supplementation. Health Canada and the PMRA regulate feed safety and veterinary drug residues, shaping cross-border formulation compliance. Ontario dairy operations lead liquid premix adoption for automated total mixed ration integration.
Mexico
Northern Mexico's feedlot complexes near the US border import premix formulations aligned with FDA-compliant specifications for export-oriented beef production. The country's national agricultural regulator enforces feed safety standards that increasingly harmonize with North American trade requirements. Sonora and Chihuahua concentrate demand for high-energy finishing ration premixes.
North America Ruminant Feed Premix Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated vendor base. Integrated agribusinesses leverage captive grain origination and backward integration into amino acid manufacturing to compress input costs. Three archetypes dominate: full-line nutrition platforms, specialty additive innovators, and cooperative-owned manufacturing entities. Competitive maneuvering concentrates on strategic partnerships with large dairy cooperatives and geographic expansion into underpenetrated Canadian prairie systems.
Within the diversified agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain integration. BASF SE anchors the specialty chemical positioning for high-performance herd applications. These three entities represent divergent strategic bets: captive raw material security versus differentiated bioactive portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| Kemin Industries, Inc. |
| DSM-Firmenich AG |
| Land O'Lakes Inc. |
| Cargill, Incorporated |
| IFF (Danisco Animal Nutrition) |
| Biomin |
| Alltech |
| Others |
Value Network & Pricing Analysis
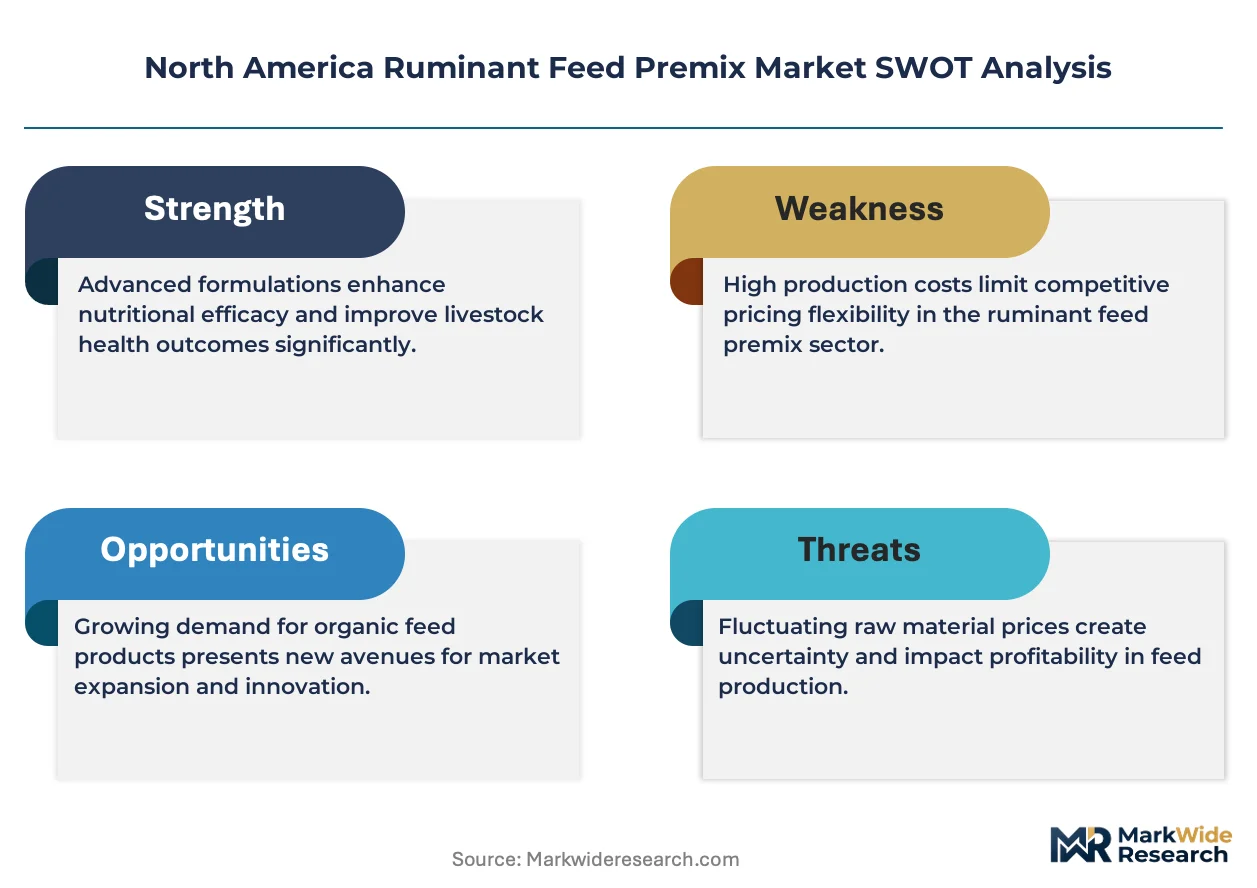
Premium-mid-economy pricing differentiation across the North American ruminant feed premix market manifests in divergent supply chain configurations, where certified organic and specialty additive tiers command captive sourcing relationships while commodity vitamin premixes flow through distributor networks. FDA Veterinary Feed Directive compliance costs and phosphorus runoff constraints in Wisconsin and California further stratify pricing tiers, embedding regulatory burden into supply chain design.
Pricing Analysis
Capacity additions in the Upper Midwest are reshaping price floors for bulk mineral premixes as integrated agribusinesses expand captive production. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with USDA organic certified premixes capturing widest spreads. Pricing pressure stems from commodity vitamin price volatility, particularly vitamins A and E, compressing formulation margins for non-integrated producers. Large dairy cooperatives above 1,000 head exhibit lowest price sensitivity due to captive supply agreements, while smaller pasture-based beef operations in the Canadian prairie remain most price-sensitive.
Supply Chain Analysis
Freight cost escalation across the I-29 dairy corridor and cross-border routes into Alberta and Saskatchewan is redrawing optimal sourcing radii for bulk premix procurement. Geographic supply concentration centers on the United States for vitamin synthesis and mineral processing, with Canada contributing specialized liquid formulation capacity and Mexico providing finishing ration premixes for export-oriented feedlots. Raw material dependencies include bulk vitamin feedstocks, organic trace mineral sources, and rumen-protected fat substrates. Single-source vulnerability in vitamin A and E supply creates structural risk during commodity cycle disruptions. Distribution runs through direct procurement agreements with large cooperatives, displacing traditional regional feed dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ruminant feed premix market functions as a regulatory compounder, where FDA Veterinary Feed Directive implementation continues to drive demand for compliant nutritional alternatives and reshape competitive positioning.
For Market Incumbents: Cement supply security through backward integration into amino acid and enzyme manufacturing, mirroring Archer Daniels Midland Company's captive production model. Expand mineral sourcing networks across the Upper Midwest to secure cost-advantaged inputs against vitamin price volatility. Prioritize certification investment for USDA organic and state-level feed safety compliance to defend premium positioning against emerging specialty additive innovators. For New Entrants and Emerging Players: Canadian prairie beef cow-calf operations present the most penetrable white-space target, with Alberta and Saskatchewan mineral premix demand underserved by extensive grazing specialists. Target Ontario dairy automation integration as a secondary entry point, where liquid premix adoption for total mixed ration systems creates technical differentiation opportunities. Pursue yeast derivative-bioactive convergence as the primary go-to-market angle, combining live yeast cultures with polyphenol extracts against commodity competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty additive innovators possessing rumen microbiome modeling capabilities and next-generation sequencing interpretation expertise. Long-term viability favors platforms with regulatory compliance infrastructure spanning FDA, USDA Organic, and state-level feed safety audits. Acquisition target archetype: mid-scale premix manufacturers with established Upper Midwest dairy relationships and underutilized capacity for nutritional additive expansion. Watch EPA nutrient management incentive program rollout as the signal for precision feeding technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Manufacturing | Captive supply of lysine and methionine reduces formulation cost exposure for integrated premix producers. |
| USDA Organic Certification Investment | Premium milk pricing differentials in private-label retail channels justify compliant premix reformulation costs. |
| Rumen Microbiome R&D Partnership | Collaboration with sequencing laboratories accelerates customized premix deployment for high-performance herds. |
| Canadian Prairie Distribution Expansion | Alberta and Saskatchewan beef operations require mineral premixes with physical stability for infrequent pasture handling. |
| Precision Feeding Technology Integration | EPA cost-share programs create demand for premixes with real-time formulation adjustment capabilities. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each country's dairy belt and beef production regions. Primary interviews engaged feed mill operators, dairy cooperative procurement managers, veterinary nutritionists, premix manufacturing plant managers, and regulatory compliance officers across Wisconsin, California, Alberta, and Ontario. Secondary validation drew from FDA Veterinary Feed Directive guidance documents, USDA organic certification databases, EPA nutrient management criteria, Health Canada PMRA feed safety standards, and SEC filings of publicly traded agribusinesses. Bottom-up volume estimates triangulated against top-down market sizing across product type, form, and end user segments.
Granularity-level modeling captured mineral premix, vitamin premix, nutritional additives, and medicinal additives at the SKU level, with form factors disaggregated across powder, granular, liquid, and pellet technologies. End user segmentation distinguished confined dairy operations, feedlot complexes, and pasture-based cow-calf systems. CAGRs were derived from regression analysis of historical procurement volumes and regulatory-driven reformulation cycles. Industry-specific forecast inputs included herd consolidation rates across the I-29 corridor, organic certification adoption curves, and rumen-protected fat technology penetration in transition cow nutrition.
Underlying measurement precision varies by segment; nutritional additives and pellet form factors carry tighter precision than commodity vitamin premixes due to fragmented supplier bases. Forecasts reflect assumptions regarding FDA enforcement consistency, state-level phosphorus regulation stability, and feed grain price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Herd Management Software Market
Livestock Management
North America Swine Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Pig Feed Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Bird Feeder Market
Livestock Management
United States Swine Feed Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Europe Ruminant Feed Premix Market