
 Global Rice Milling Market | 2026-2036
Global Rice Milling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Milling Market Outlook
Modular equipment bundling is realigning procurement patterns across the rice milling value chain. Buhler Group leverages its integrated destoner-separator platforms to anchor premium positioning in automated large-scale installations. Satake Corporation sustains technology leadership in optical sorting systems for export-grade processing. Zhejiang QiLi Machinery specializes in cost-optimized small-to-medium capacity lines that compete aggressively in farmer and cooperative segments across South Asia.
Rice milling encompasses the mechanical transformation of paddy into polished rice through sequential dehusking, whitening, grading, and sorting operations using friction and abrasive whitening chambers operating at controlled temperatures to preserve grain integrity. The process serves commercial food processors and exporters requiring consistent head-rice recovery rates above specified thresholds. Automated technology lines command the strongest margin pools as food processors and exporters in Thailand and Vietnam replace semi-automatic installations. Small scale capacity equipment retains volume dominance across farmer end-user segments in India and Bangladesh, though large scale automated systems represent the fastest structural expansion. Traditional technology segments face displacement across all capacity tiers as labor costs and quality consistency requirements intensify.
India's BIS grain standards, Vietnam's national food safety protocols, and ISO 22000 certification requirements collectively shape equipment specifications and market access conditions for mill suppliers. The EU Green Deal's embedded carbon accounting for imported rice indirectly pressures exporter-facing mills to adopt energy-efficient advanced technology configurations. Stakeholders must monitor how dual carbon goals in China and evolving EU deforestation regulations redirect investment toward traceable, low-energy milling infrastructure.
Market Dynamics
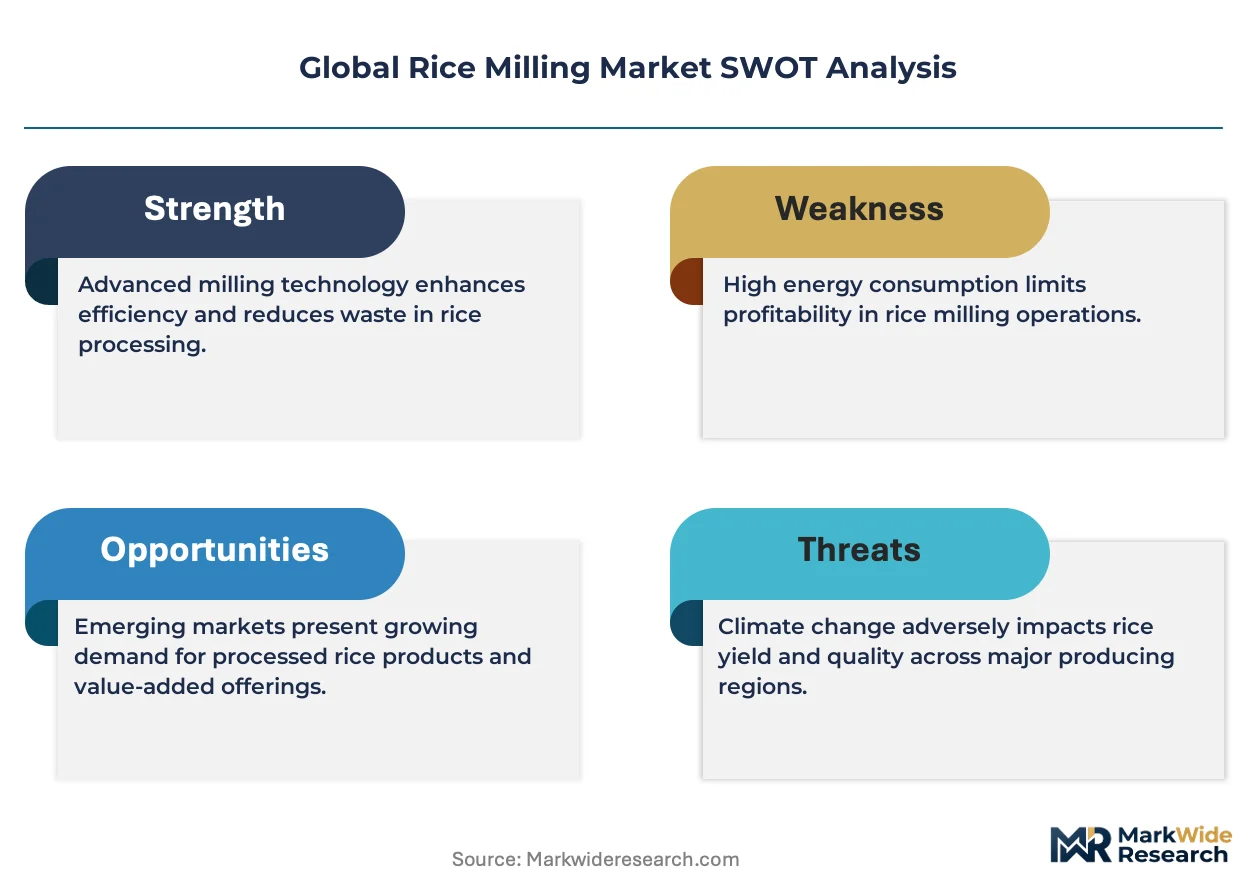
Automated optical sorting systems are displacing gravity separators across Southeast Asian export corridors as food processors face tightening EU Green Deal carbon accounting requirements for rice imports.
Growth Catalysts
- India FSSAI Fortification Mandates:National grain quality standards compel millers to install precision sorting and grading equipment that meets micronutrient enrichment protocols.
- Export-grade specifications:Vietnam's Mekong Delta processors require large-scale automated husker lines to satisfy international head-rice recovery thresholds.
- Labor cost trajectories:Thai commercial mills accelerate mechanization investments as agricultural wage inflation erodes semi-automatic operation economics.
Market Restraints
- Steel and bearing input volatility:Abrasive whitening chamber manufacturing depends on alloy steel pricing that fluctuates with commodity cycles.
- Technical skill scarcity:Optical sorter calibration and AI-driven defect recognition systems require technicians with mechatronics training unavailable in rural milling districts.
- EU deforestation compliance friction:Importers face traceability documentation burdens that delay equipment procurement cycles for exporter-facing mills.
Strategic Opportunities
- Bangladesh cooperative segment:Farmer-owned milling associations represent underpenetrated demand for modular small-capacity destoner-whitener bundles.
- Energy efficiency incentives:China's dual carbon goals create subsidy channels for low-consumption friction whitening systems replacing legacy abrasive configurations.
- Remote monitoring convergence:IoT sensor networks combined with predictive maintenance software enable service revenue streams beyond equipment sales.
Industry Challenges
- ISO 22000 certification timelines:Exporters face 12-18 month compliance windows that delay automated line commissioning and revenue recognition.
- Legacy equipment integration:Brownfield mills struggle to interface new optical sorting modules with existing pneumatic conveying infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Milling Market |
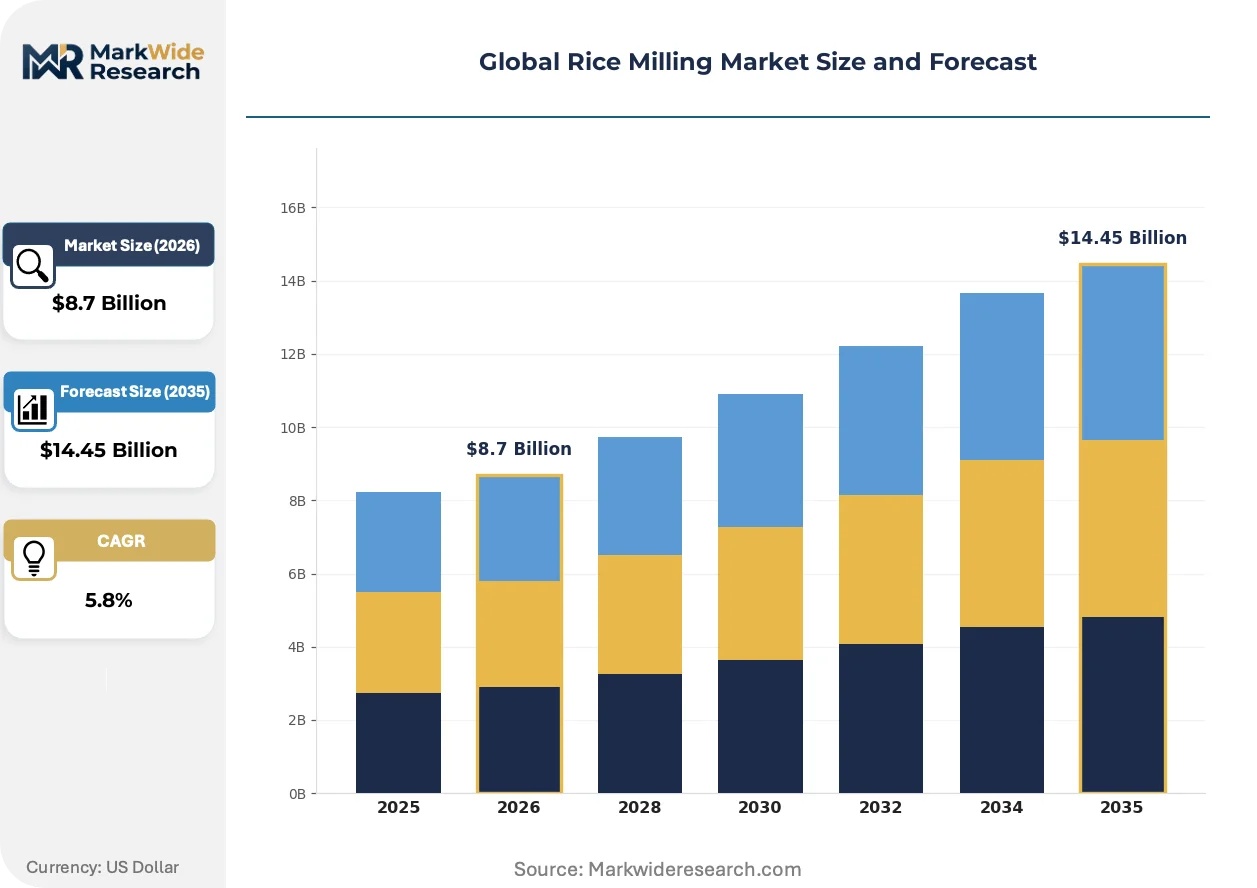
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Rice Milling Machine, Husker, Destoner, Separator Capacity: Small Scale, Medium Scale, Large Scale, Custom Technology: Traditional, Automated, Semi-Automatic, Advanced End User: Farmers, Food Processors, Exporters, Retailers |
| Companies Covered | Buhler Group, Satake Corporation, AG Growth International, Fowler Westrup India Pvt. Ltd., Zhejiang QiLi Machinery Co. Ltd., PETKUS Technologie GmbH, Alvan Blanch, Yamamoto, G.G. Dandekar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Milling Market Strategic Shifts
Digitalization of milling operations is compressing maintenance cycles and enabling outcome-based service models that realign supplier-customer relationships around yield metrics rather than equipment throughput.
Near-infrared spectroscopy is converging with real-time grain quality monitoring to enable automated moisture and protein adjustment during whitening operations. Large-scale Vietnamese exporters are deploying these systems to maintain consistent export-grade specifications across variable paddy harvests. The technology is converging with cloud-based batch tracking to create verifiable provenance records for EU import compliance.
REACH chemical safety protocols and the EU Green Deal's embedded carbon accounting are forcing exporter-facing mills to document energy consumption per ton of polished rice output. Equipment suppliers must now certify abrasive whitening chamber thermal efficiency and pneumatic system power draw to maintain market access. Thai and Vietnamese processors are prioritizing European-manufactured low-friction bearing systems to satisfy these disclosure requirements.
Service unbundling is separating equipment procurement from maintenance contracts as millers seek variable cost structures aligned with seasonal processing volumes. Cooperative buyers in India's eastern states now lease optical sorting capacity during peak harvest windows rather than owning depreciating assets year-round. This pattern concentrates in regions with pronounced monsoon-driven production seasonality.
Global Rice Milling Market Segmentation
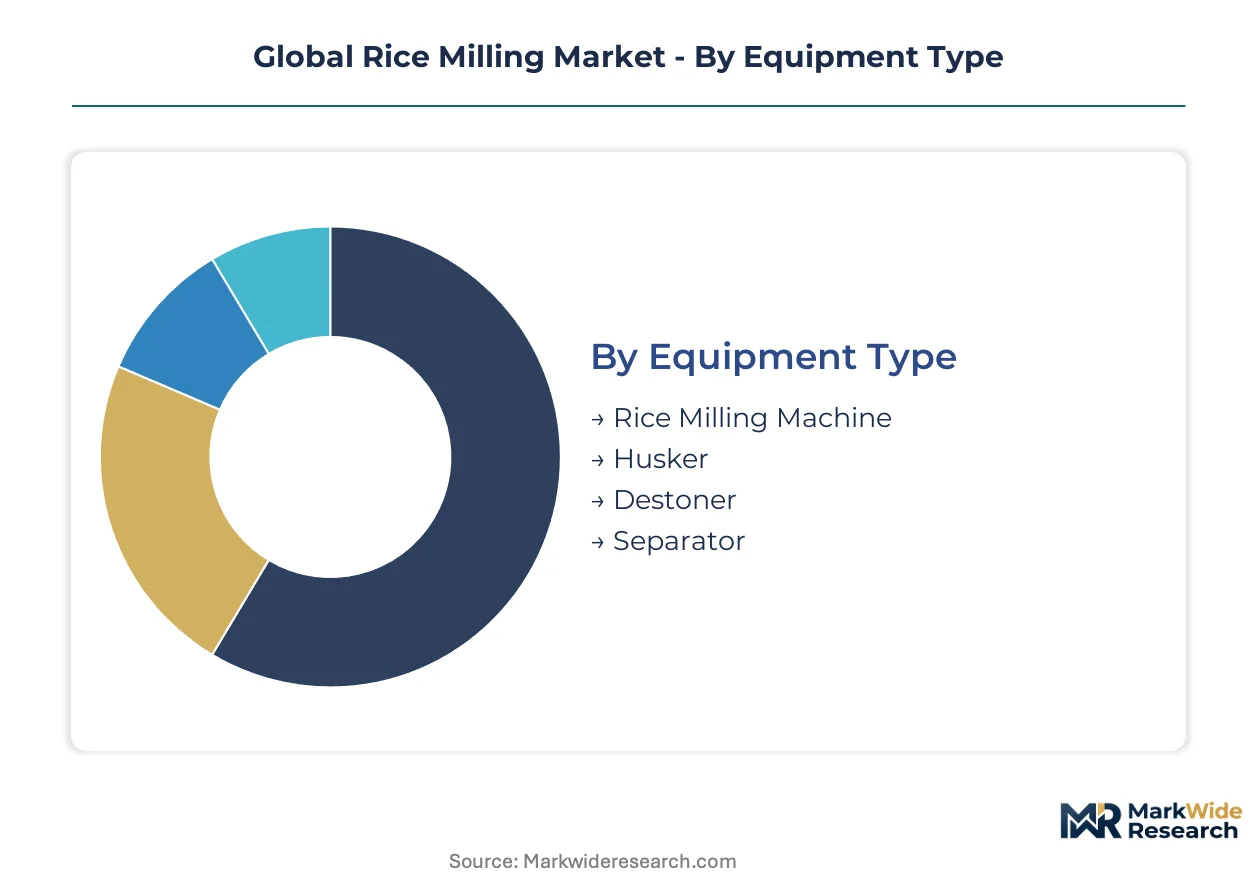
Equipment configuration choices in rice milling determine capital recovery timelines and operational flexibility. Segmentation reveals where upgrade investments concentrate and which technology tiers face displacement pressure from regulatory and labor cost shifts.
Equipment Type:
Replacement cycles diverge sharply across equipment categories as mills modernize dehusking and separation stages before whitening investments.
- Rice Milling Machine:Integrated systems combining destoning, husking, and polishing in sequential configurations dominate new facility investments. Vietnamese exporters in the Mekong Delta specify these lines to meet EU Green Deal carbon disclosure requirements for embedded energy in exported rice.
- Husker:Rubber-roll and abrasive-disc configurations handle the critical first-stage dehusking where grain integrity preservation determines head-rice recovery rates. Thai commercial processors prioritize automated husker upgrades as agricultural wage inflation erodes semi-automatic operation economics.
- Destoner:Density-based separation units remove stones and heavy impurities before whitening.
- Separator:Paddy separators and thickness graders sort broken from whole grains.
Rice Milling Machine sits at the top of the volume ranking, with Husker climbing the fastest.
Capacity:
Cost tier positioning shapes procurement patterns as farmer cooperatives seek modular entry points while export processors scale toward continuous-flow installations.
- Large Scale:Continuous-flow automated lines processing multiple tons per hour serve export-grade specifications in Vietnam and Thailand. These installations command premium margins as processors replace semi-automatic equipment to satisfy tightening international head-rice recovery thresholds.
- Small Scale:Decentralized units under two tons per hour capacity dominate farmer and cooperative segments across India's eastern states and Bangladesh. India's FSSAI fortification mandates push even small-scale operators toward precision sorting attachments that were previously uneconomical.
- Medium Scale:Intermediate capacity bridges cooperative associations and regional processors.
- Custom:Purpose-built configurations address specific paddy varieties or facility constraints.
Small Scale retains volume leadership across South Asian farmer segments, with Large Scale gaining share fastest among export-facing processors.
Technology:
Application requirements dictate technology tier selection as food safety certification and traceability demands reshape equipment specifications.
- Automated:Sensor-driven optical sorting and AI-based defect recognition systems displace gravity separators across Southeast Asian export corridors. These configurations enable ISO 22000 certification compliance that maintains access to European import markets.
- Advanced:Near-infrared spectroscopy and real-time moisture adjustment converge with cloud-based batch tracking for provenance verification. Large-scale Vietnamese exporters deploy these systems to document energy consumption per ton for EU Green Deal embedded carbon accounting.
- Semi-Automatic:Mixed-mechanization configurations persist where labor costs remain manageable.
- Traditional:Manual or single-stage mechanical processing faces structural displacement across all capacity tiers.
Automated technology commands the steepest expansion trajectory among export processors, with Advanced systems climbing fastest in premium segment penetration.
End User:
Customer type determines service model expectations as suppliers unbundle equipment from maintenance contracts to align with seasonal processing patterns.
- Food Processors:Commercial millers serving domestic distribution networks prioritize consistent throughput and head-rice recovery optimization. Thai processors accelerate mechanization investments as wage inflation erodes semi-automatic economics and quality consistency requirements intensify.
- Farmers:Individual producers and cooperative associations seek cost-optimized small-capacity lines with seasonal leasing flexibility. India's eastern state cooperatives now lease optical sorting capacity during peak harvest windows rather than owning depreciating assets year-round.
- Exporters:International market-facing operations require certified equipment meeting destination country food safety protocols.
- Retailers:Vertically integrated food chains specify private-label processing configurations.
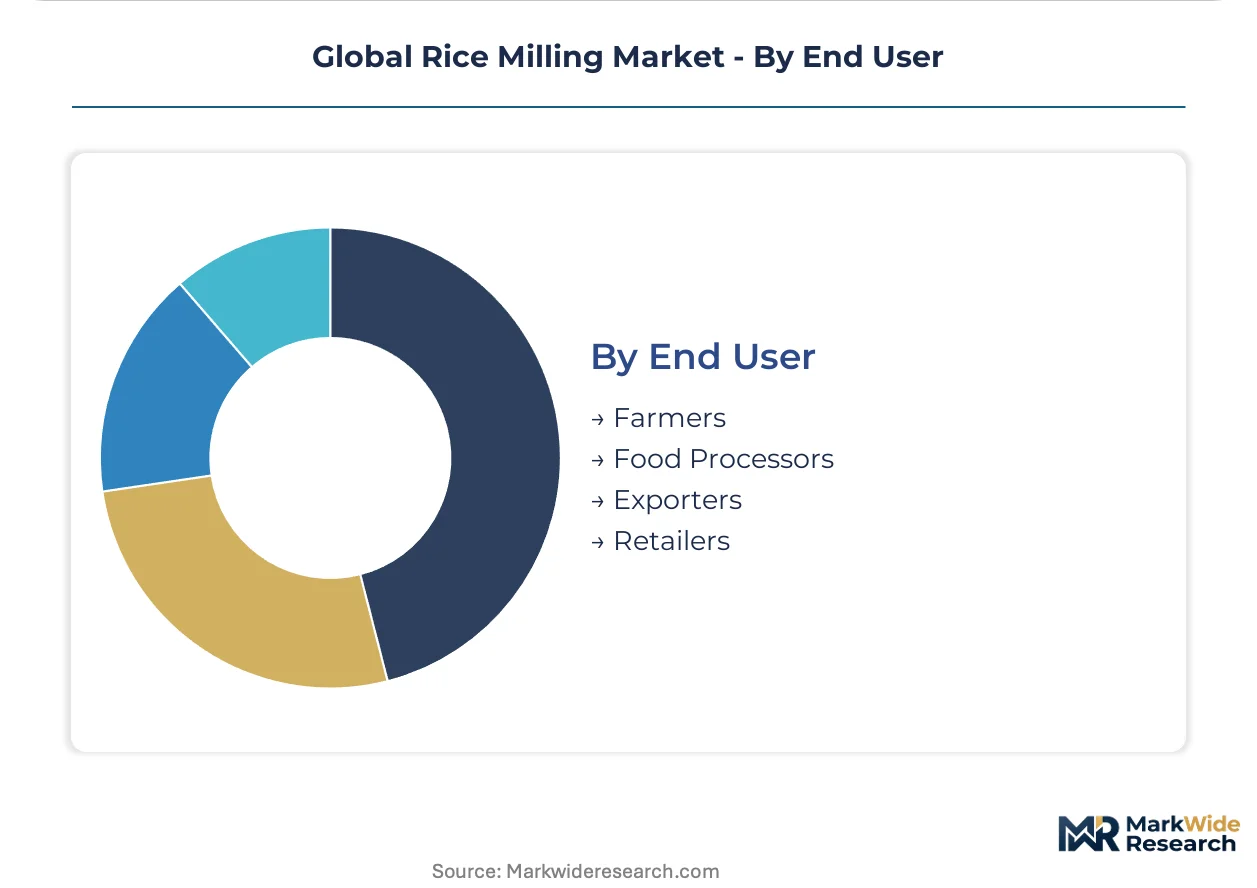
Food Processors anchor equipment demand by volume, with Farmers representing the fastest-climbing segment through cooperative aggregation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rice milling technology first achieved industrial scale in Japan during the early twentieth century, then diffused through Southeast Asian export corridors and South Asian domestic markets. Equipment specifications now diverge sharply between high-volume export processors and small-scale farmer cooperatives.
China
Domestic processors face dual carbon goals that subsidize low-consumption friction whitening systems. MIIT efficiency mandates push millers toward automated optical sorting to reduce per-ton energy intensity. Yangtze River Delta clusters around Jiangsu and Zhejiang provinces anchor large-scale automated line manufacturing.
India
FSSAI fortification mandates compel millers across all capacity tiers to install precision sorting attachments. BIS grain standards tighten specifications for head-rice recovery and micronutrient enrichment. Punjab and Haryana cooperatives lease optical capacity during monsoon harvest windows rather than owning year-round.
Vietnam
Mekong Delta exporters require continuous-flow automated husker lines to satisfy EU Green Deal embedded carbon disclosure requirements. National food safety protocols align equipment specifications with ISO 22000 certification timelines. Can Tho and An Giang provinces concentrate large-scale installations serving European import markets.
Thailand
Agricultural wage inflation erodes semi-automatic operation economics in commercial milling districts. Processors accelerate mechanization investments to maintain quality consistency against tightening international head-rice recovery thresholds. Central Plains milling clusters around Nakhon Sawan prioritize automated destoner-separator upgrades.
Indonesia
Government rice self-sufficiency programs drive investment in domestic milling capacity across Java and Sumatra. National standards authorities enforce equipment safety certifications that favor modular small-to-medium capacity lines. East Java cooperative associations represent underpenetrated demand for farmer-owned destoner-whitener bundles.
Global Rice Milling Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and service integration dimensions. The vendor base organizes into three tiers: integrated platform specialists commanding automated large-scale installations, optical sorting technology leaders, and cost-optimized fabricators serving farmer cooperative segments. Market structure reflects consolidation around technology licensing partnerships and geographic distribution alliances rather than horizontal merger activity.
Within the integrated platform tier, Buhler Group and Satake Corporation exemplify divergent specialization models—Swiss-based Buhler anchoring destoner-separator platform bundling, Japanese Satake occupying optical sorting technology leadership. Zhejiang QiLi Machinery Co. Ltd. represents the cost-optimized archetype competing aggressively in South Asian small-to-medium capacity procurement.
| Leading Market Players |
|---|
| Buhler Group |
| Satake Corporation |
| AG Growth International |
| Fowler Westrup India Pvt. Ltd. |
| Zhejiang QiLi Machinery Co. Ltd. |
| PETKUS Technologie GmbH |
| Alvan Blanch |
| Yamamoto |
| G.G. Dandekar |
| Others |
Value Chain & Pricing Dynamics
Export-grade processors in Vietnam's Mekong Delta anchor equipment demand and impose three-tier pricing stratification across premium automated lines, standard semi-automatic configurations, and economy-grade farmer cooperative units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions as ISO 22000 certification requirements and EU Green Deal carbon disclosure obligations differentiate value tiers. Price differentiation rests on automation grade and after-sales service bundling rather than raw capacity metrics. Cost compression in economy-tier small-scale equipment is intensifying as Chinese fabricators expand modular destoner-whitener offerings. Farmer cooperatives in India's eastern states exhibit highest price sensitivity, while Vietnamese exporters prioritize certification-compliant premium configurations regardless of capital outlay.
Supply Chain Analysis
Freight costs from European bearing manufacturers and Japanese optical component suppliers inflate landed costs for Southeast Asian mill operators by fifteen to twenty percent over regional alternatives. Manufacturing concentration centers on China, India, and Germany, with abrasive whitening chamber production drawing from alloy steel mills in Jiangsu and specialty ceramics from Bavaria. Single-source vulnerability persists in AI-driven defect recognition modules sourced from Japanese sensor specialists. Distribution runs through authorized dealer networks with service technicians stationed at provincial hubs across Vietnam, Thailand, and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Rice Milling Market functions as a stable compounder underpinned by mandatory food fortification regulations that lock in equipment replacement cycles across South Asian installed bases.
For Market Incumbents: Deploy predictive maintenance software platforms to capture recurring service revenue as millers seek variable cost structures aligned with seasonal processing volumes. Deepen backward integration into abrasive whitening chamber ceramics to insulate margin pools from alloy steel commodity cycles. Defensive positioning must counter Chinese cost-optimized entrants in Bangladesh cooperative segments. For New Entrants and Emerging Players: AI-driven remote calibration tools offer the most penetrable wedge for overcoming technical skill scarcity in rural Indian milling districts. Target Indonesia's East Java cooperative associations with modular small-capacity destoner-whitener bundles under government rice self-sufficiency programs. Lease-based go-to-market models align with monsoon-driven production seasonality in South Asian farmer segments. For Investors and Strategic Acquirers: Food processing conglomerates with integrated supply chains are the most active acquirer in this space, seeking captive milling capacity for branded rice portfolios. Long-term viability favors automated technology specialists with established ISO 22000 certification pathways over commodity equipment fabricators. Watch for EU deforestation regulation enforcement intensity as inflection indicator for exporter-facing mill upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Licensing | Enables Vietnamese exporters to meet EU Green Deal embedded carbon disclosure thresholds. |
| Backward Integration into Abrasive Ceramics | Reduces dependency on German specialty suppliers for whitening chamber components. |
| IoT Sensor Network Deployment | Creates predictive maintenance revenue streams beyond equipment sales in Thai commercial mills. |
| Cooperative Leasing Program Launch | Captures seasonal demand from India's eastern state farmer associations during monsoon harvests. |
| ISO 22000 Certification Partnership | Accelerates compliance timelines for Mekong Delta processors serving European import markets. |
Study Parameters
Coverage spans Southeast Asia, South Asia, and East Asia, with primary inputs from each region combining interviews with mill operations managers, agricultural cooperative procurement heads, OEM equipment sales directors, and aftermarket service technicians. Secondary validation drew from Vietnam's national food safety protocol filings, India's FSSAI fortification mandate documentation, EU Green Deal technical guidance, customs trade data for rice processing machinery, and SEC filings of listed agricultural equipment manufacturers. Bottom-up installation counts triangulated against top-down market value estimates.
Granularity-level modeling addressed equipment type, capacity tier, technology sophistication, and end-user category across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles against regulatory mandate timelines. Industry-specific forecast inputs included EU deforestation regulation implementation pace and China's MIIT efficiency mandate subsidy disbursement rates.
The model holds under stable regulatory enforcement and commodity input pricing; deviation in alloy steel volatility or EU carbon border adjustment scope would shift equipment procurement timing. Forecasts reflect documented assumptions regarding fortification mandate adherence rates and cooperative aggregation trends. A model refresh is warranted upon material change in EU Green Deal embedded carbon accounting methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Destoner Machine Market