
 Animal Feed Trace Minerals Market | 2026-2036
Animal Feed Trace Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Trace Minerals Market Outlook
Australian organic trace mineral production is decoupling from conventional sulfate-based supply chains as chelation technology matures. Cargill Inc. leverages its integrated nutrition platforms to control premix formulation and distribution across major livestock regions. DSM-Firmenich sustains R&D intensity in hydroxy trace mineral forms that improve bioavailability in ruminant diets. Zinpro Corp. dominates performance mineral categories through decades of proprietary research and veterinary channel relationships.
Animal feed trace minerals constitute inorganic or organic compounds—copper sulfate, zinc methionine, manganese oxide, sodium selenite—delivered at parts-per-million concentrations to correct dietary deficiencies and support enzymatic function, immune response, and skeletal development in livestock. Zinc leads product type demand due to its role in epithelial integrity and widespread deficiency in cereal-based diets. Aquaculture represents the fastest-growing application as intensive shrimp and salmon farming escalates mineral density requirements. Liquid and pre-mix forms capture expanding margin pools where feed mills outsource precision blending to specialized suppliers.
The FDA's Center for Veterinary Medicine governs feed additive safety under the Food Safety Modernization Act, while the EU's Feed Additives Regulation mandates EFSA-reviewed authorization for all trace mineral sources entering compound feeds. China's Ministry of Agriculture and Rural Affairs enforces GB standards on maximum permitted levels, directly constraining formulation practices in the world's largest pork-producing nation. Stakeholders must monitor evolving organic trace mineral approval pathways and regional maximum-limit harmonization to align product portfolios with compliance thresholds.
Market Dynamics
Organic trace mineral chelation is displacing conventional sulfate formulations as bioavailability premiums reshape formulation economics across ruminant and monogastric feed systems.
Growth Catalysts
- EU Feed Additives Regulation:EFSA-reviewed authorization pathways for hydroxy trace mineral sources accelerate product differentiation and premium positioning in compound feed formulations.
- Intensive aquaculture expansion:Shrimp and salmon farming operations in Southeast Asia escalate mineral density requirements beyond what conventional inorganic sources can efficiently deliver.
- Chelated mineral technology maturation:Advances in amino acid complexation reduce antagonistic mineral interactions in high-cereal diets, improving absorption coefficients in poultry and swine.
Market Restraints
- Copper and zinc price volatility:Base metal commodity swings compress premix margins and complicate long-term contract pricing for integrated feed mills.
- Chinese GB standard maximum limits:Ministry of Agriculture and Rural Affairs enforcement constrains formulation flexibility in the world's largest pork-producing nation.
- Technical bioavailability measurement gaps:Inconsistent in vivo validation protocols across laboratories create uncertainty in comparative efficacy claims between organic and inorganic sources.
Strategic Opportunities
- Brazil poultry sector consolidation:Integrated producers scaling trace mineral supplementation create volume anchor demand for specialized premix suppliers.
- Precision livestock farming convergence:Real-time mineral status monitoring via rumen bolus sensors enables dynamic supplementation protocols tailored to individual animal need.
- US FDA Food Safety Modernization Act:Enhanced feed safety documentation requirements favor suppliers with validated quality management systems and batch traceability infrastructure.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in mineral antagonism modeling and chelate stability under feed processing conditions remains concentrated among veteran nutritionists at established suppliers.
- Organic trace mineral approval timelines:Novel source registration under EU 1831/2003 demands multi-year EFSA safety dossiers that delay market entry for innovative suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Trace Minerals Market |
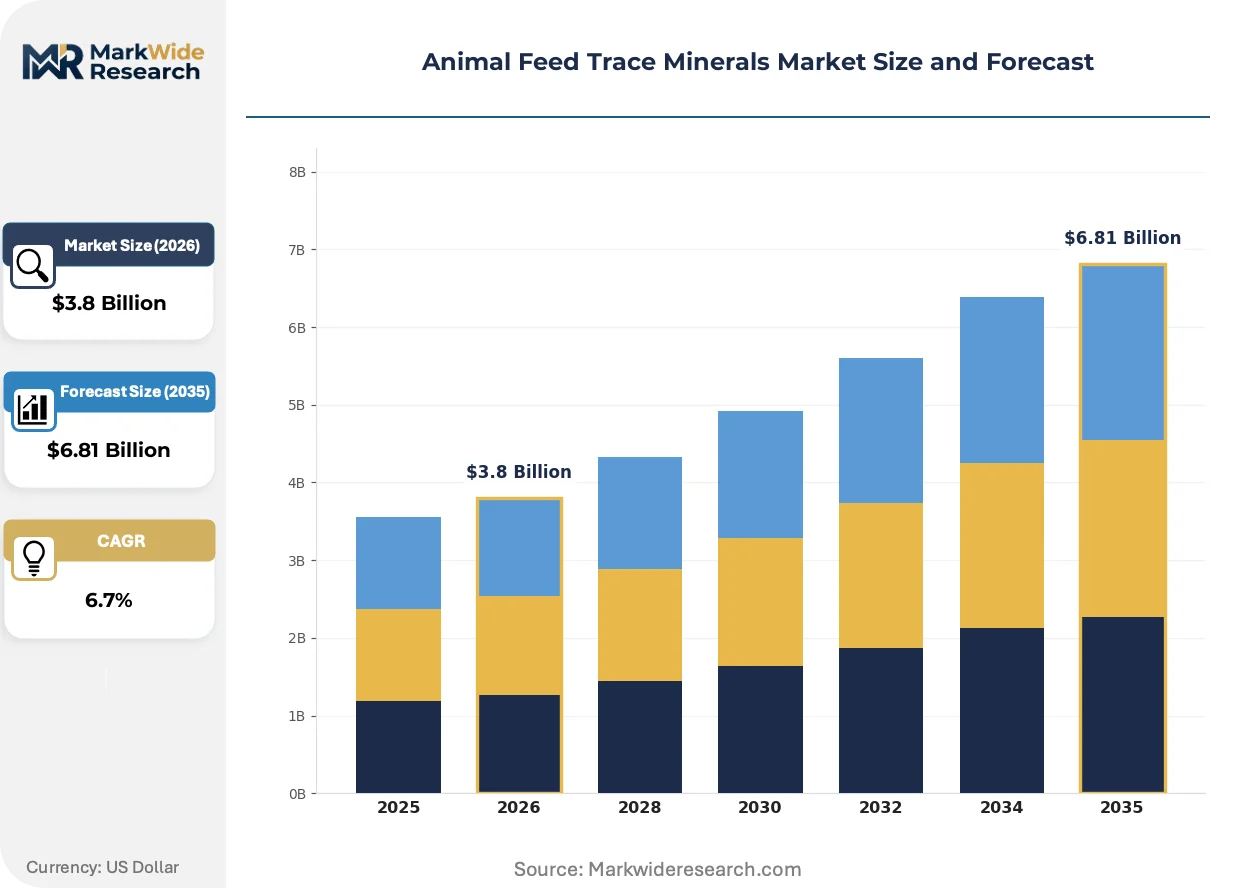
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Zinc, Manganese, Selenium Application: Ruminants, Poultry, Swine, Aquaculture Form: Granular, Powder, Liquid, Pre-mix Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Cargill Inc., Archer Daniels Midland Co., DSM-Firmenich, Zinpro Corp., Kemin Industries Inc., Nutreco NV, Novus International Inc., Alltech Inc., Phibro Animal Health Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Trace Minerals Market Strategic Shifts
Active reformulation toward hydroxy and protein-complexed mineral sources is compressing the performance gap between premium organic and economy inorganic grades, forcing suppliers to demonstrate measurable production outcomes beyond standard deficiency correction.
Hydroxy trace mineral technology is decentralizing premix production authority away from centralized feed mill operations toward specialized nutrition service providers. Large integrators in North American dairy and Brazilian poultry sectors are adopting on-farm mineral blending systems that bypass traditional distribution channels. This shift compresses lead times from formulation decision to diet delivery while demanding technical support capabilities that commodity sulfate suppliers cannot readily provide.
REACH and CLP classification revisions for copper and zinc compounds are tightening occupational exposure limits and environmental release reporting across EU member states. Compound feed manufacturers face reformulation pressure to reduce total mineral loading while maintaining animal performance. The regulatory burden falls heaviest on smaller regional mills lacking dedicated regulatory affairs staff to navigate substance dossier updates.
Buyer concentration among top-ten global protein integrators is compressing supplier negotiation cycles and unbundling technical advisory services from product supply contracts. These procurement teams now demand outcome-based performance guarantees tied to measurable fertility, immunity, or carcass quality metrics. The shift is most visible in US dairy and Northwest European pig production systems where margin pressure accelerates scrutiny of every feed cost line item.
Animal Feed Trace Minerals Market Segmentation
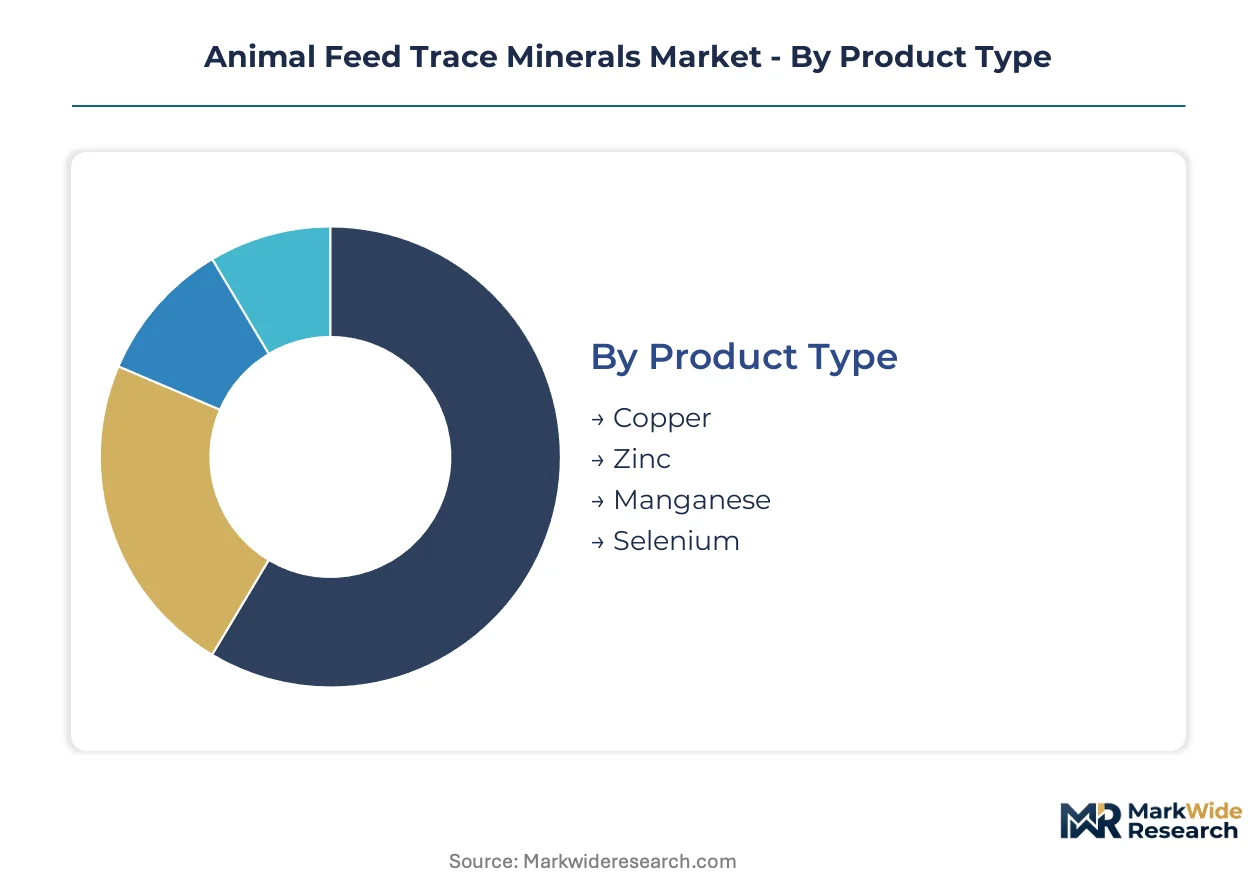
Trace mineral segmentation determines which regulatory pathways suppliers must navigate and where formulation complexity concentrates. Product chemistry, target species, physical form, and channel structure each impose distinct compliance burdens and margin profiles.
Product Type:
Zinc and copper formulations face the heaviest EFSA authorization requirements under EU 1831/2003, while selenium sources trigger additional toxicity threshold scrutiny across multiple jurisdictions.
- Zinc:Sulfate, oxide, and chelated forms dominate compound feed inclusion for epithelial integrity and immune function. Demand concentrates in North American dairy operations optimizing reproductive performance through organic zinc methionine supplementation.
- Copper:Hydroxy and sulfate variants serve distinct ruminant versus monogastric applications with divergent bioavailability coefficients. Brazilian poultry integrators drive volume for growth-promoting formulations despite China's GB standard maximum limits constraining export-oriented suppliers.
- Manganese:Manganese oxide and amino acid complexes support skeletal development and enzyme activation across species.
- Selenium:Sodium selenite and yeast-based organic sources operate under narrow therapeutic windows requiring precise premix blending.
Leading the category by volume: Zinc. Growing fastest: Selenium.
Application:
Species-specific digestive physiology dictates mineral source selection and drives cost tier stratification across livestock sectors.
- Ruminants:Cattle operations require rumen-protected hydroxy forms that bypass microbial degradation and deliver post-ruminal absorption. North American dairy producers anchor demand for reproductive and hoof health formulations.
- Poultry:High-density mineral loading in broiler and layer diets prioritizes bioavailable organic sources to minimize antagonistic interactions. Brazil's vertically integrated poultry sector scales trace mineral supplementation most aggressively.
- Swine:Phytase-mineral interaction management dominates formulation decisions in cereal-soybean diets.
- Aquaculture:Shrimp and salmon farming operations in Southeast Asia escalate mineral density requirements beyond conventional inorganic delivery efficiency.
Dominant by revenue: Ruminants. Expanding most quickly: Aquaculture.
Form:
Physical state determines processing compatibility, dosing precision, and whether feed mills retain blending authority or outsource to specialized nutrition service providers.
- Pre-mix:Precision-blended concentrates enable on-farm customization and compress lead times for large integrators adopting decentralized mineral management systems in North American dairy and Brazilian poultry operations.
- Liquid:Pumpable suspensions facilitate automated dosing in modern feed mill operations and reduce dust exposure compliance burdens under REACH occupational limits.
- Granular:Free-flowing particles suit mechanical blending equipment at mid-scale regional mills.
- Powder:Fine-ground sulfates and oxides serve economy formulations where cost minimization outweighs bioavailability premiums.
Highest margin capture: Pre-mix. Gaining share fastest: Liquid.
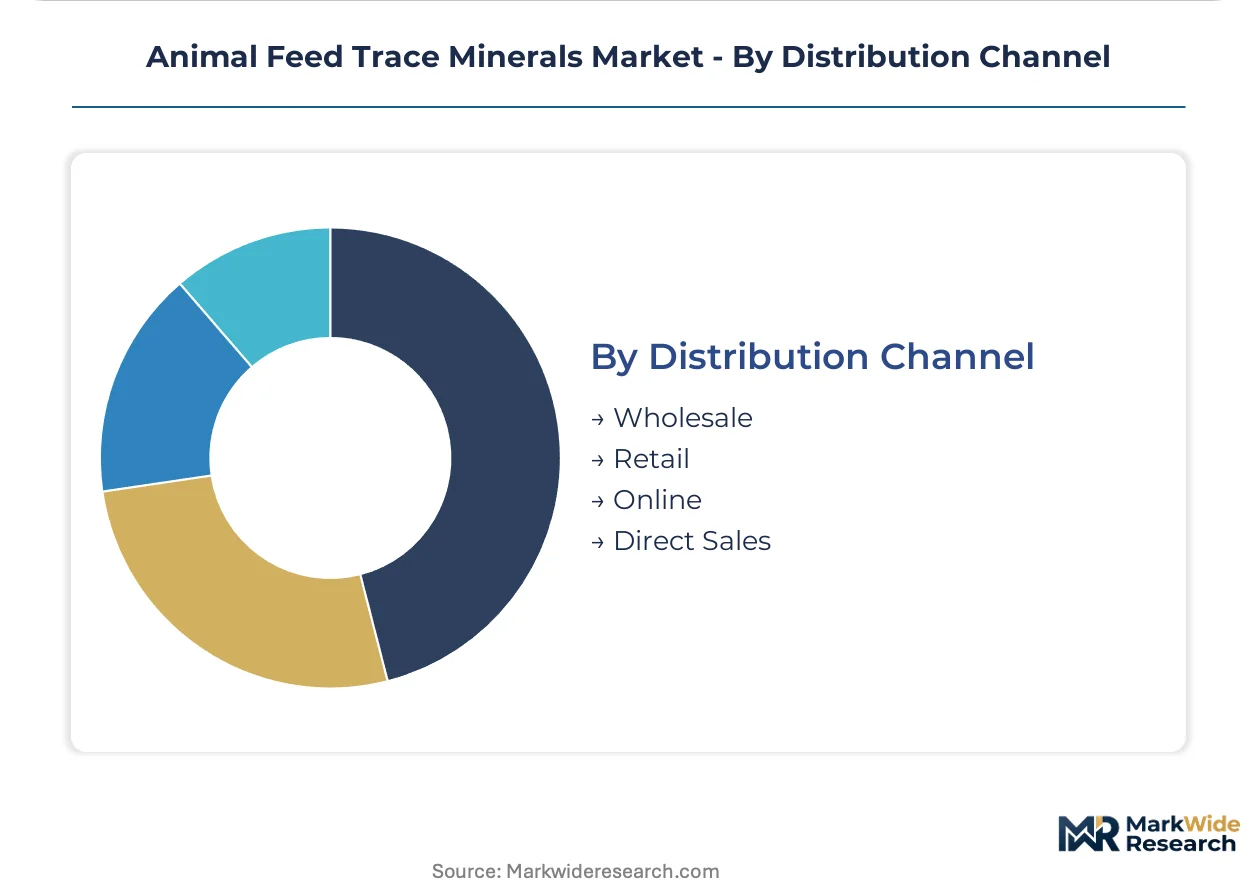
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and whether procurement teams unbundle advisory services from product supply.
- Direct Sales:Large protein integrators negotiate outcome-based performance guarantees tied to fertility, immunity, or carcass quality metrics, bypassing traditional distribution markups. This channel concentrates among top-ten global livestock producers in US dairy and Northwest European pig systems.
- Wholesale:Regional feed mills and cooperatives purchase bulk premixes through distributor networks with attached technical formulation support.
- Retail:Smaller livestock operations access bagged mineral supplements through agricultural supply stores.
- Online:Digital procurement platforms emerge for standardized commodity sulfate formulations with transparent pricing.
Volume leader: Wholesale. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base metal mining clusters in Australia and Chile supply the copper and zinc feedstocks that underpin trace mineral production economics across major livestock regions. Formulation standards diverge sharply between jurisdictions, creating compliance complexity for multinational premix suppliers.
United States
Dairy operations in Wisconsin and California anchor demand for organic zinc methionine formulations targeting reproductive performance. FDA Center for Veterinary Medicine enforcement of Food Safety Modernization Act documentation requirements favors suppliers with validated batch traceability systems. The Midwest feed mill corridor concentrates precision blending capacity serving integrated pork and poultry producers.
Brazil
Vertically integrated poultry processors in São Paulo and Paraná scale trace mineral supplementation most aggressively among emerging markets. ANVISA alignment with international feed additive standards streamlines import pathways for hydroxy mineral sources. The southern agricultural belt hosts specialized premix facilities bypassing traditional distribution channels through on-farm blending systems.
China
Pork production systems in Sichuan and Henan provinces operate under GB standard maximum limits that constrain copper and zinc formulation flexibility. Ministry of Agriculture and Rural Affairs enforcement tightens premix registration requirements for imported organic trace mineral sources. The Yangtze River Delta concentrates feed manufacturing capacity serving coastal integrated livestock operations.
Germany
Northwest European pig producers in Lower Saxony demand outcome-based performance guarantees tied to fertility and immunity metrics. EFSA-reviewed authorization under EU 1831/2003 for hydroxy trace minerals accelerates product differentiation in compound feed formulations. The northern port cluster facilitates mineral concentrate import and redistribution across EU member states.
Australia
Organic trace mineral production facilities in New South Wales and Victoria decouple from conventional sulfate supply chains as chelation technology matures. TGA alignment with feed additive safety frameworks supports export-oriented manufacturing. The southeastern manufacturing corridor supplies premix concentrates to Southeast Asian aquaculture operations.
Animal Feed Trace Minerals Market Competitive Environment
Global majors compete with regional champions across formulation technology and veterinary channel relationships, producing a tiered structure where scale-driven nutrition platforms coexist with specialized mineral research houses. The vendor base clusters around three strategic archetypes: integrated agribusiness conglomerates controlling premix distribution, dedicated trace mineral research specialists, and diversified feed additive suppliers. Consolidation pressures intensify as procurement teams at top-ten protein integrators unbundle technical advisory services from product supply contracts. Dominant competitive moves include backward integration into captive mineral source production and geographic expansion through regulatory approval stacking.
Within the integrated nutrition platform tier, Cargill Inc. and Archer Daniels Midland Co. exemplify scale-driven competitors leveraging global supply chain infrastructure. DSM-Firmenich occupies a position among research-intensive specialists sustaining R&D intensity in hydroxy trace mineral forms. Zinpro Corp. anchors the performance mineral category through decades of proprietary research investment. These three companies represent distinct competitive positions: commodity-scale distribution control, technology-led bioavailability advancement, and veterinary channel specialization.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Co. |
| DSM-Firmenich |
| Zinpro Corp. |
| Kemin Industries Inc. |
| Nutreco NV |
| Novus International Inc. |
| Alltech Inc. |
| Phibro Animal Health Corp. |
| Others |
Value Chain & Pricing Dynamics
Copper sulfate feedstock costs originating from Chilean mining operations cascade through three distinct pricing tiers before reaching compound feed manufacturers. Base metal commodity swings at the smelter level compress premix margins and force contract renegotiations between specialized suppliers and integrated feed mills.
Pricing Analysis
Technical advisory services unbundling from product supply contracts is compressing margin capture for commodity-grade suppliers. Three-tier pricing structure across premium hydroxy forms, standard organic chelates, and economy inorganic sulfates reflects bioavailability certification levels and veterinary channel relationships. Pricing pressure stems from buyer concentration among top-ten global protein integrators demanding outcome-based performance guarantees. Smaller regional feed mills exhibit highest price sensitivity due to limited formulation chemist talent and batch traceability infrastructure gaps.
Supply Chain Analysis
Regional distribution centers in the US Midwest feed mill corridor and Brazil's southern agricultural belt coordinate hub-and-spoke patterns for premix concentrate redistribution. Manufacturing gravity centers on Australia, Chile, and China for copper and zinc feedstock processing, with downstream blending operations tethered to livestock production clusters. Raw material dependencies include mined copper concentrates, zinc oxide intermediates, and amino acid chelating agents. Single-source vulnerability concentrates in Australian organic trace mineral facilities serving Southeast Asian aquaculture. Distribution runs through specialized nutrition service providers bypassing traditional wholesale channels for large integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA-reviewed authorization timelines for novel hydroxy mineral sources create supply-constrained conditions that prop pricing premiums for established registrants.
For Market Incumbents: Deepen captive mineral source production through backward integration into Chilean copper concentrate offtake agreements. Expand premix blending capacity in Brazil's Paraná state to anchor volume from vertically integrated poultry processors. Defend margin position against commodity sulfate traders by accelerating EFSA dossier submissions for next-generation chelated forms. For New Entrants and Emerging Players: Capture white-space demand in Southeast Asian aquaculture operations where mineral density requirements exceed conventional inorganic delivery efficiency. Target on-farm blending system adoption among mid-scale North American dairy cooperatives underserved by Cargill's centralized distribution. Enter through liquid suspension formulations that reduce REACH occupational exposure compliance burdens for EU regional mills. For Investors and Strategic Acquirers: EFSA authorization queue acceleration is the leading indicator that hydroxy trace mineral technology maturation is reaching inflection. Long-term viability favors research-intensive specialists with proprietary chelation patents over commodity-scale distributors. Acquisition target archetype: Australian organic trace mineral producers with TGA-aligned export pathways. Monitor ANVISA regulatory harmonization progress as the signal for Brazilian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Feedstock | Chilean copper concentrate offtake agreements secure supply against LME price volatility. |
| EFSA Authorization Stacking | Multi-jurisdiction regulatory approval accelerates EU compound feed market penetration. |
| On-Farm Blending System Deployment | Decentralized premix production compresses lead times for Brazilian poultry integrators. |
| Hydroxy Mineral R&D Intensification | Post-ruminal absorption improvements differentiate ruminant formulations from sulfate competitors. |
| REACH Compliance Infrastructure | Substance dossier management capabilities attract EU regional mills lacking dedicated regulatory staff. |
Study Parameters
USDA NASS feed consumption surveys, EFSA feed additive register filings, and Chilean copper export customs records formed the secondary backbone for supply-side calibration. Primary interviews with premix formulation chemists, veterinary nutritionists at integrated livestock operations, and procurement leads at top-ten global protein companies provided demand-side validation. Bottom-up mineral inclusion rate modeling triangulated against top-down compound feed production estimates across the analysis window.
Historical trendline analysis of zinc methionine pricing premiums and sulfate commodity spreads informed the projection framework. Segmentation modeling incorporated product chemistry tier, target species digestive physiology, physical form processing compatibility, and channel structure buyer scale. CAGRs derived from mineral density requirement trajectories in aquaculture and precision livestock farming adoption curves. Forecast inputs included EFSA authorization pipeline velocity and Brazilian poultry sector consolidation pace.
The model holds under stable base metal commodity regimes and regulatory harmonization continuity; deviation in Chinese GB standard enforcement stringency or REACH classification revisions would shift trajectory. Forecasts reflect documented assumptions regarding chelation technology maturation and buyer concentration trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Global Animal Feed Micronutrients Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
South America Eubiotics Market