
 Poultry Premix Market | 2026-2036
Poultry Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Premix Market Analytics
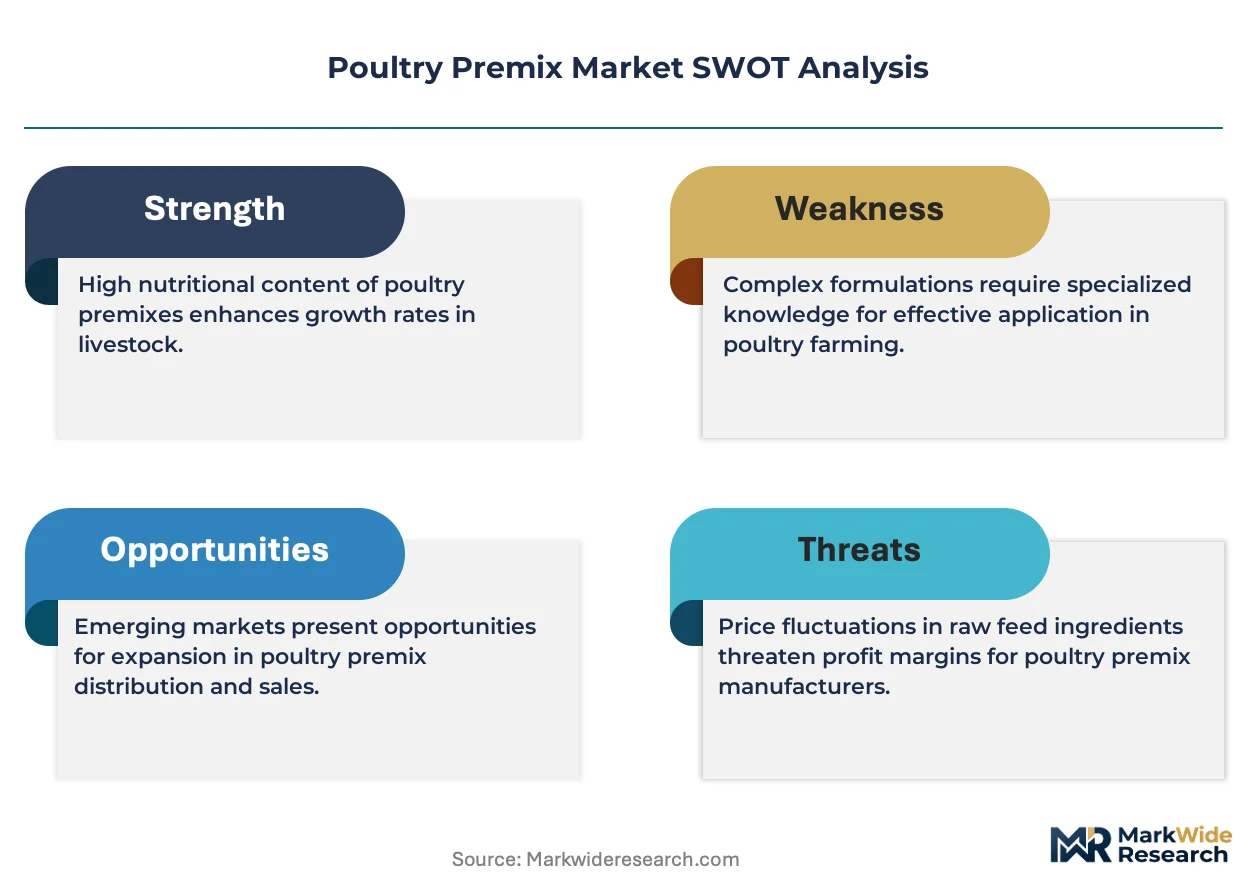
The poultry premix sector is restructuring around a sharp split between traceability-certified premium blends and undifferentiated commodity micronutrient packs. Cargill Incorporated leverages its captive grain supply chains to control input costs across vitamin and mineral premix lines. DSM Animal Nutrition differentiates through precision-delivery technologies that protect nutrient bioavailability during pelleting heat stress. BASF SE anchors its position in carotenoid and enzyme premixes for layer yolk pigmentation and broiler feed conversion.
A poultry premix is a homogeneous blend of micro-ingredients—vitamins, minerals, amino acids, enzymes, and trace elements—dosed at 0.5–3.0% of finished feed weight to correct nutritional gaps in base grain formulations. Manufacturers produce these blends via sequential dilution in horizontal ribbon mixers with coefficient of variation below 5%, ensuring uniform dispersion critical for flock-level metabolic performance. Vitamin premixes command the deepest margin pools due to stability engineering and shelf-life guarantees, while amino acid premixes dominate volume throughput driven by lysine and methionine fortification in high-density broiler rations. Enzyme premixes represent the fastest-expanding category as phytase and NSPase additions displace inorganic phosphate and reduce environmental nitrogen loading.
Feed manufacturers navigate oversight from the FDA's Center for Veterinary Medicine in the United States, which governs medicated feed additives and CGMP compliance, alongside the EU's F-Gas Regulation and REACH constraints on solvent-based vitamin synthesis pathways. India's FSSAI and BIS standards increasingly mandate premix labeling disclosure and heavy metal limits for domestic and export-bound poultry products. Stakeholders must monitor how carbon-accounting rules and antibiotic-residue thresholds in import markets reshape formulation priorities and sourcing geography.
Market Dynamics
Antibiotic growth promoter bans across major protein import markets are forcing feed manufacturers to rebuild premix formulations around enzyme and organic acid alternatives, compressing formulation cycles and rewiring supplier relationships.
Growth Catalysts
- EU F-Gas Regulation:Synthetic vitamin production pathways face solvent restrictions that favor biotech fermentation methods, accelerating capital flows toward precision fermentation facilities in Denmark and the Netherlands.
- Export-grade flock uniformity mandates:Brazil's MAPA certification requirements for European and Middle Eastern buyers are driving commercial integrators toward traceability-certified vitamin premix programs with full chain-of-custody documentation.
- Phytase engineering advances:Next-generation thermostable phytase variants withstand pelleting temperatures above 85°C, enabling feed mills to eliminate inorganic phosphate entirely from broiler starter rations.
Market Restraints
- Vitamin precursor volatility:Feed-grade niacin and pantothenic acid depend on petrochemical derivatives whose pricing tracks crude oil and natural gas feedstock swings, compressing blender margins during energy price spikes.
- Chinese API concentration:Over 70% of global vitamin C, B12, and D3 fermentation capacity sits in Shandong and Zhejiang provinces, creating single-geography supply vulnerability for premix formulators in the Americas and Europe.
- REACH registration costs:Novel organic trace mineral chelates face multi-year toxicology dossier requirements that freeze smaller premix houses out of premium mineral innovation pipelines.
Strategic Opportunities
- Vietnam and Indonesia feed mill consolidation:Mid-tier Southeast Asian compounders are upgrading from commodity micronutrient packs to precision-delivery enzyme premixes as domestic broiler integrators verticalize into processing.
- Carbon-accounting integration:The EU Green Deal's CBAM extension to agricultural inputs creates first-mover advantage for premix suppliers offering certified low-carbon vitamin K3 and synthetic amino acid alternatives.
- Layer yolk pigmentation premiums:Carotenoid premixes delivering specific L*a*b* color coordinates command price multiples in Japanese and UAE retail egg markets where shell color consistency drives shelf placement.
Industry Challenges
- Formulation chemist scarcity:Premix houses struggle to recruit specialists capable of balancing vitamin stability, mineral antagonism, and enzyme activity retention through extrusion and pelleting heat stress profiles.
- Multi-jurisdiction label compliance:A single premix SKU exported to the US, EU, and Saudi Arabia requires simultaneous FDA medicated feed additive alignment, EFSA additive registry confirmation, and SFDA halal certification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Premix Market |
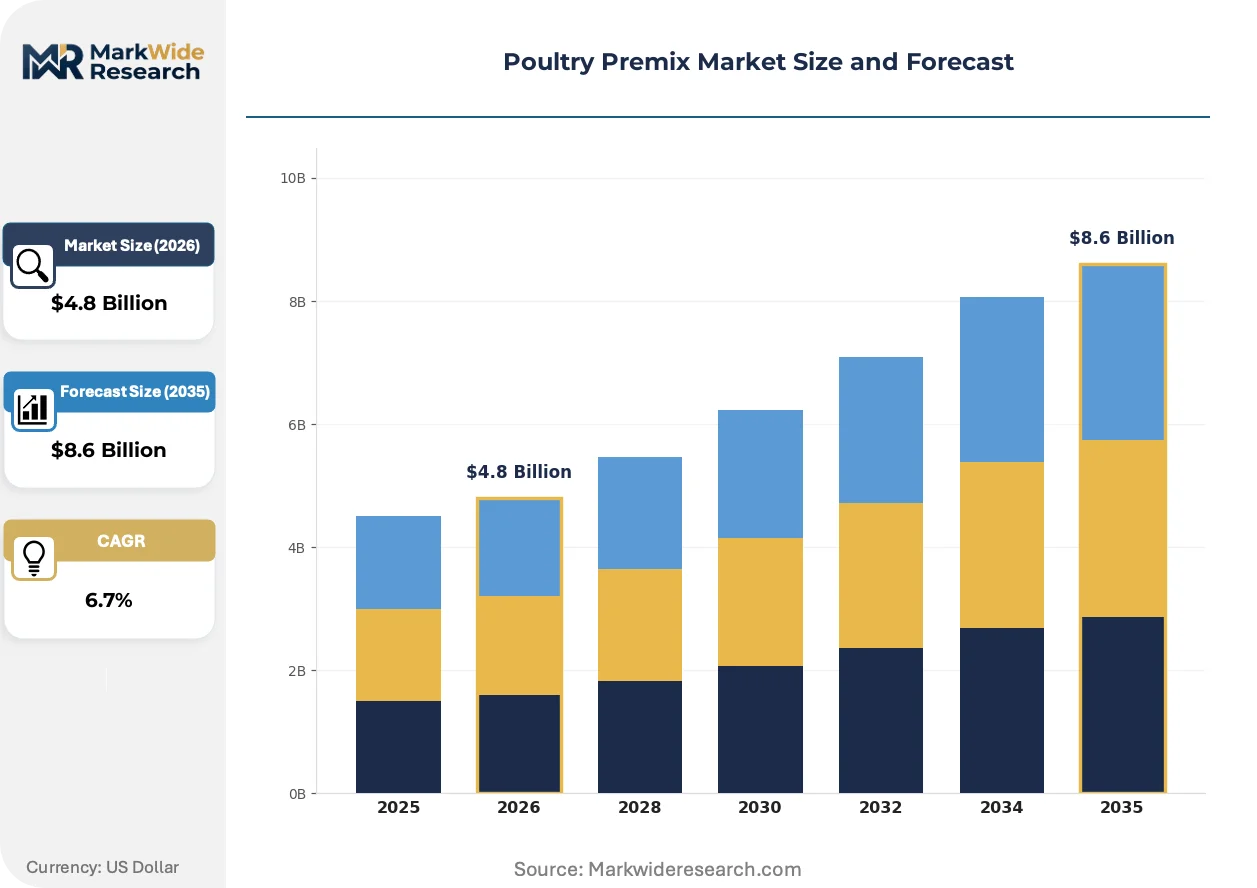
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes Application: Broilers, Layers, Turkeys, Others Form: Powder, Liquid, Granular, Pellets End User: Commercial Farms, Backyard Farmers, Integrators, Feed Manufacturers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Nutreco N.V., DSM Animal Nutrition, Charoen Pokphand Foods PCL, Land O'Lakes Inc, ForFarmers NV, BASF SE, Kemin Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Premix Market Evolving Landscape
Microencapsulation and precision-delivery technologies are redrawing competitive boundaries between commodity micronutrient suppliers and performance-premium premix houses, with heat stability and shelf-life guarantees replacing price-per-kilogram as the primary purchasing criterion.
Coated vitamin technologies using lipid-matrix or polymer-shell encapsulation protect thiamine, pyridoxine, and fat-soluble vitamins from steam conditioning and pelleting temperatures above 80°C. Large-scale feed manufacturers in Thailand and Poland are adopting these formats at double-digit annual rates despite 15-25% cost premiums. The technology is integrating premix suppliers into earlier-stage feed formulation consultations, locking out commodity blenders from high-performance broiler and layer ration specifications.
REACH and F-Gas Regulation constraints on solvent-based vitamin synthesis are redirecting European production investment toward bio-fermentation and enzymatic conversion pathways. DSM and BASF have retooled German and Swiss facilities to meet ECHA substance volume thresholds without traditional petrochemical intermediates. Layer operations in France and Spain now face extended lead times for synthetic carotenoid premixes, accelerating trials of marigold extract and paprika oleoresin alternatives.
Integrated poultry operators are consolidating premix procurement under multi-year performance contracts that tie pricing to feed conversion ratio outcomes rather than input tonnage. Brazilian and Thai broiler giants now specify enzyme premix suppliers based on documented improvements in European Production Efficiency Factor scores. This model concentrates purchasing power among the top fifteen global protein companies, squeezing regional premix blenders into undifferentiated commodity vitamin and mineral pack segments.
Poultry Premix Market Segmentation
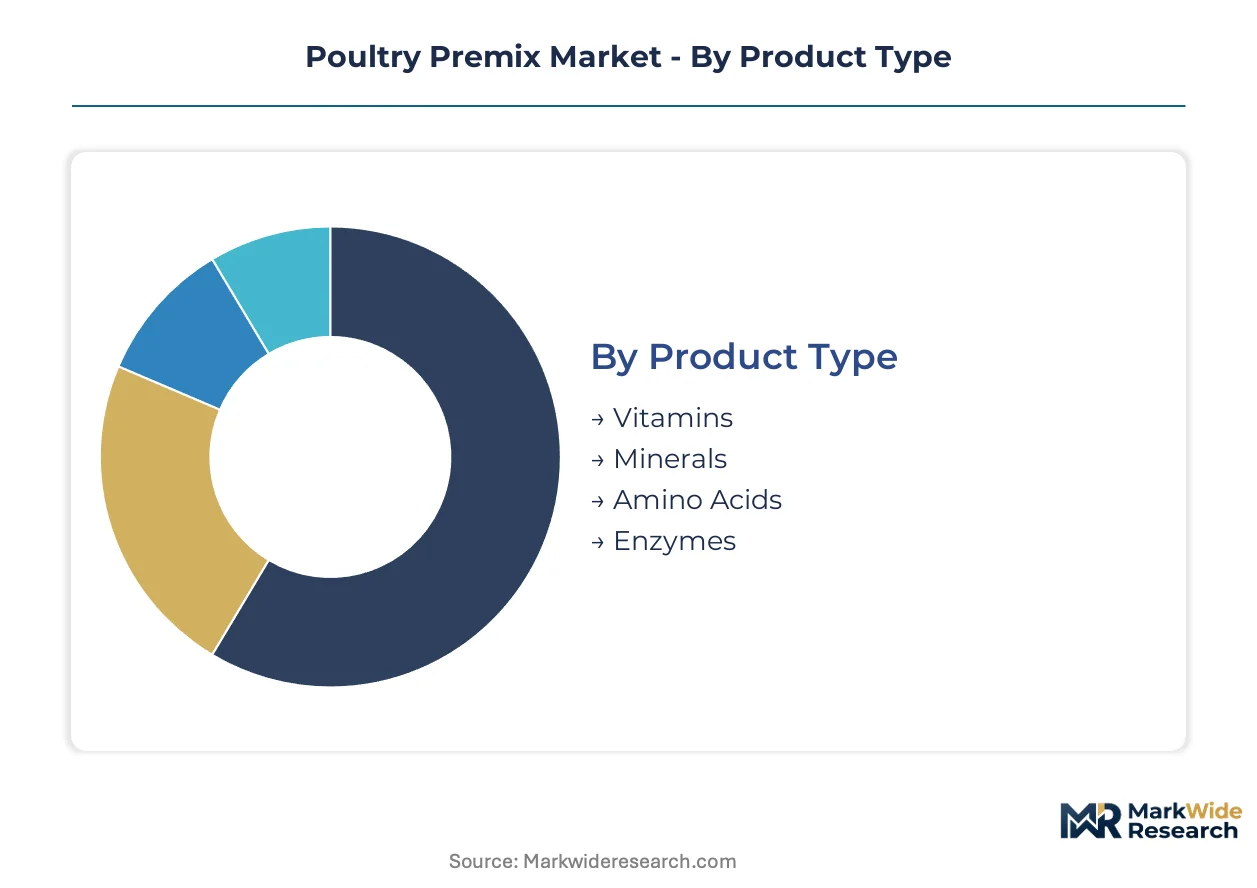
Poultry premix segmentation tracks how feed manufacturers trade off between micronutrient density, heat stability, and delivery economics. Each category reflects distinct technical upgrade cycles—enzyme engineering advances, precision-delivery coatings, and formulation automation—that reshape supplier selection criteria across broiler and layer operations.
Product Type:
Feed mills upgrade premix portfolios on three-to-five-year cycles driven by pelleting temperature thresholds, shelf-life guarantees, and regulatory pressure on antibiotic alternatives.
- Enzymes:Phytase and NSPase formulations displace inorganic phosphate from starter rations while cutting environmental nitrogen loading. Thermostable variants now withstand conditioning above 85°C, enabling complete phosphate elimination in high-performance Brazilian and Thai broiler programs.
- Vitamins:Microencapsulated fat-soluble and B-complex blends command premium positioning through bioavailability protection during extrusion. DSM and BASF compete on stability engineering as ECHA solvent restrictions push European production toward fermentation-derived K3 and D3.
- Minerals:Organic trace mineral chelates—zinc methionine, selenium yeast—replace inorganic sulfates in export-grade layer operations facing EU heavy metal thresholds.
- Amino Acids:Lysine and methionine fortification dominates volume throughput in high-density broiler rations, with liquid DL-methionine gaining share in automated dosing systems.
Vitamin premixes sit at the top of the volume ranking, with enzyme formulations climbing the fastest as phytase engineering unlocks complete mineral reformulation.
Application:
Species-specific premix demand splits along feed conversion efficiency targets and output quality premiums that justify differentiated micronutrient investment.
- Broilers:Rapid-growth genetics drive lysine-to-energy ratio precision, with enzyme premixes delivering measurable improvements in European Production Efficiency Factor scores. Brazilian integrators now tie supplier contracts to documented FCR outcomes rather than tonnage.
- Layers:Yolk pigmentation specifications in Japanese and UAE retail channels command carotenoid premix premiums tied to L*a*b* color coordinate certification. Marigold extract and paprika oleoresin alternatives gain trials as synthetic carotenoid lead times extend under REACH constraints.
- Turkeys:Extended grow-out periods require adjusted vitamin E and selenium antioxidant loading to manage oxidative stress in heavy toms.
- Others:Duck and game bird premixes remain niche, concentrated in French and Chinese specialty protein operations.
Broiler applications absorb the greatest premix tonnage, while layer programs generate the steepest margin expansion through pigmentation premiums.
Form:
Physical format selection hinges on mill automation level, mixing uniformity requirements, and climate-controlled storage availability.
- Powder:Standard ribbon-mixer dispersion for small-to-mid scale compounders, with coefficient of variation targets below 5% ensuring flock-level metabolic consistency.
- Liquid:Post-pelleting spray application protects heat-labile vitamins and enzymes, adopted at double-digit rates in Thai and Polish large-scale operations despite infrastructure investment.
- Granular:Flowability-optimized for automated dosing systems in integrated Brazilian and Indonesian feed mills.
- Pellets:Pre-dispersed micronutrient concentrates for on-farm blending by backyard and mid-tier commercial operations.
Powder maintains dominant volume position, with liquid formats expanding most quickly as precision-delivery coatings justify post-process application infrastructure.
End User:
Procurement authority concentrates with scale, separating integrated operators with formulation control from price-sensitive fragmented buyers.
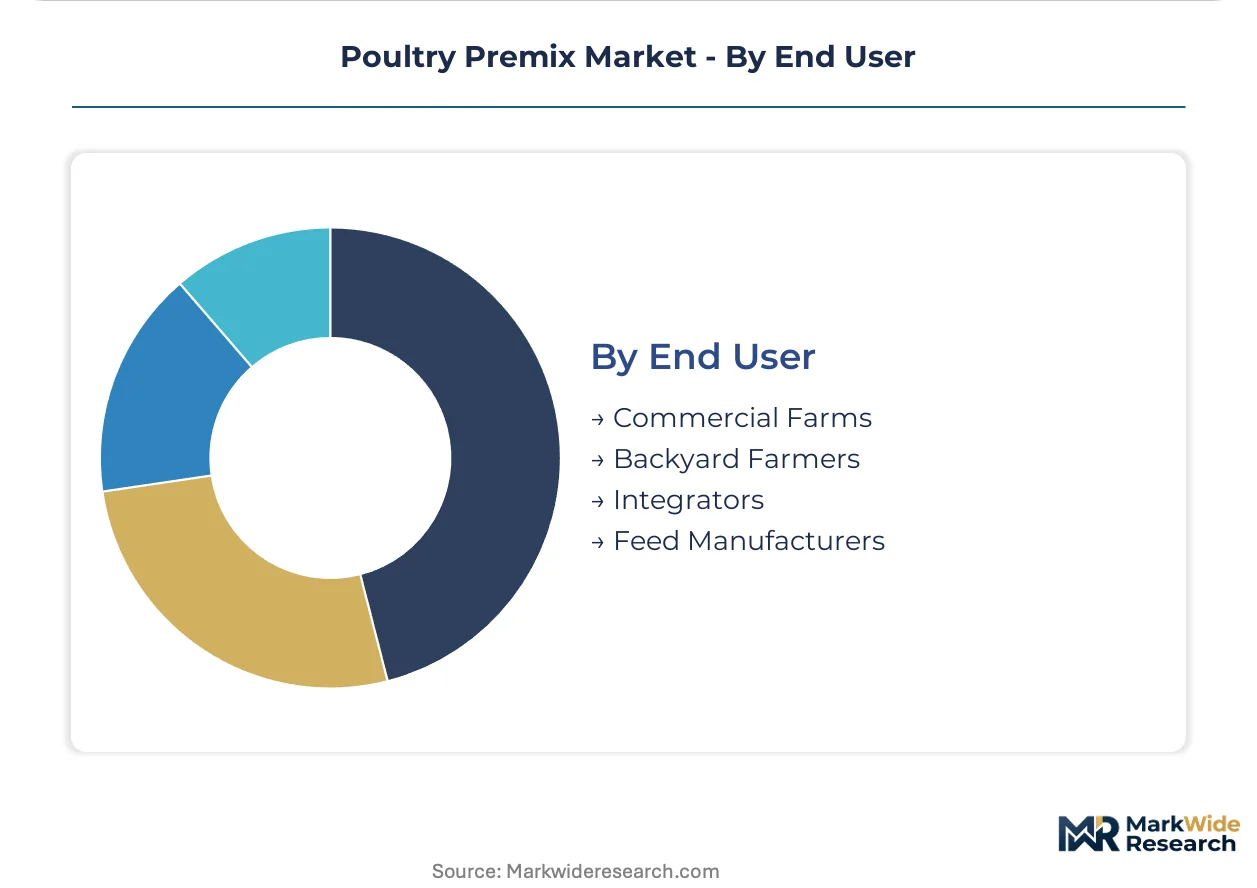
- Feed Manufacturers:Compounders specify premix performance guarantees and full chain-of-custody documentation to serve export-grade integrators. Multi-jurisdiction label compliance—FDA medicated feed alignment, EFSA additive registry, SFDA halal certification—freezes smaller blenders out of premium specifications.
- Integrators:Vertically controlled protein companies consolidate purchasing under multi-year enzyme premix contracts tied to feed conversion outcomes, squeezing regional suppliers into commodity vitamin and mineral segments.
- Commercial Farms:Mid-scale operations rely on branded premix packs with stability guarantees rather than custom formulation.
- Backyard Farmers:Undifferentiated commodity micronutrient blends dominate, with minimal technical service attachment.
Feed manufacturers command the largest premix procurement volume, with integrators gaining share fastest as Brazilian and Thai broiler giants verticalize into processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's commercial integrators drive traceability-certified premix adoption at a faster clip than United States feed manufacturers, where FDA medicated feed compliance absorbs reformulation resources that otherwise target enzyme-based antibiotic alternatives.
United States
Midwestern feed compounders confront FDA Center for Veterinary Medicine oversight on medicated feed additives while rebuilding premix portfolios around phytase and organic acid alternatives. The Iowa-Illinois corridor hosts dense concentrations of integrated broiler operations trialing post-pelleting liquid enzyme application systems.
Brazil
Commercial integrators in São Paulo and Paraná states expand vitamin premix programs to satisfy MAPA certification for European and Middle Eastern export markets. Campinas-based feed engineering clusters now specify full chain-of-custody documentation from premix suppliers serving export-grade flock uniformity mandates.
Germany
REACH registration constraints and ECHA solvent restrictions redirect vitamin production investment toward precision fermentation facilities in Lower Saxony. The Rhineland chemical corridor houses retooled plants delivering bio-fermentation-derived K3 and D3 to layer operations facing extended synthetic carotenoid lead times.
China
Shandong and Zhejiang provinces concentrate over 70 percent of global vitamin C, B12, and D3 fermentation capacity, creating supply vulnerability for premix formulators elsewhere. Qingdao feed manufacturing clusters increasingly integrate captive premix production to reduce dependence on external micronutrient suppliers.
Vietnam
Mid-tier compounders in the Mekong Delta upgrade from commodity micronutrient packs to precision-delivery enzyme premixes as domestic broiler integrators consolidate processing capacity. Ho Chi Minh City feed engineering hubs now specify thermostable phytase variants for high-temperature pelleting lines.
Poultry Premix Market Competitive Landscape
Top-tier vendors anchor premium precision-delivery and traceability-certified segments, while regional blenders compete on undifferentiated commodity vitamin and mineral packs. The market structure splits between integrated nutrition conglomerates with captive supply chains and specialized premix houses with formulation chemistry depth. Two strategic archetypes dominate: grain-originated suppliers leveraging backward integration into input costs, and biotechnology-anchored players competing on stability engineering and heat-stress protection. Competitive moves concentrate on multi-year performance contracts tied to feed conversion outcomes and geographic expansion through Southeast Asian feed mill partnerships.
Within the integrated nutrition tier, Cargill Incorporated and Archer Daniels Midland Company represent grain-originated suppliers with captive supply chain leverage, while DSM Animal Nutrition and BASF SE exemplify biotechnology-anchored specialists competing on precision-delivery technologies and fermentation-derived vitamin pathways. Charoen Pokphand Foods PCL occupies a position bridging Southeast Asian market access with vertical integration into protein processing. These four entities collectively illustrate the competitive tension between scale-driven input cost control and premium positioning through bioavailability engineering.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| DSM Animal Nutrition |
| Charoen Pokphand Foods PCL |
| Land O'Lakes Inc |
| ForFarmers NV |
| BASF SE |
| Kemin Industries Inc |
| Others |
Value Network & Pricing Analysis
Petrochemical-derived vitamin precursors—niacin, pantothenic acid, and feed-grade choline—flow from Shandong and Zhejiang fermentation complexes through three pricing tiers downstream: traceability-certified premium blends for Brazilian export-grade integrators, performance-guaranteed enzyme premixes for Thai feed mills, and undifferentiated commodity micronutrient packs for fragmented Southeast Asian compounders.
Pricing Analysis
Capacity additions in precision fermentation facilities across Denmark and the Netherlands are reshaping price floors for bio-derived vitamins, pressuring legacy petrochemical-synthetic margins. Three-tier pricing structure across premium, standard, and economy levels separates DSM and BASF stability-engineered microencapsulated blends from regional commodity blenders. Price differentiation hinges on heat-stability certification and full chain-of-custody documentation. Cost compression in commodity vitamin packs is intensifying because Brazilian and Thai integrators consolidate procurement under multi-year performance contracts. Backyard farmers and mid-tier commercial operations remain most price-sensitive, while export-grade layer operations in Japan and UAE absorb steep carotenoid premix premiums for yolk color consistency.
Supply Chain Analysis
Vitamin B12, C, and D3 fermentation supply rests on Chinese production clusters in Shandong and Zhejiang provinces, with secondary sourcing from German and Swiss precision fermentation facilities. Raw material dependencies span corn-derived dextrose for fermentation feedstock, petrochemical intermediates for synthetic vitamin pathways, and marigold oleoresin for natural carotenoid alternatives. Single-geography concentration above 70 percent for critical vitamin APIs creates supply vulnerability for premix formulators in the Americas and Europe facing REACH registration delays. Distribution runs through integrated nutrition conglomerates with captive grain supply chains and specialized premix houses with formulation chemistry depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poultry premix market functions as a geographic-arbitrage play between EU REACH-constrained synthetic vitamin production and Southeast Asian feed mill consolidation driving enzyme premix upgrades.
For Market Incumbents: Cement positioning in traceability-certified premium segments through backward integration into precision fermentation capacity in Denmark or the Netherlands, insulating margin pools from ECHA solvent restrictions. Lock in multi-year performance contracts with Brazilian and Thai integrators that tie pricing to documented feed conversion ratio improvements, creating switching costs that freeze regional commodity blenders out of high-performance specifications.
For New Entrants and Emerging Players: Mid-tier Vietnamese and Indonesian compounders upgrading from commodity packs to precision-delivery enzyme premixes represent the most penetrable buyer archetype, underserved by incumbent technical service teams focused on top-fifteen global protein companies. Enter through thermostable phytase specialization for high-temperature pelleting lines, leveraging formulation chemist scarcity at established houses to capture share in the fastest-expanding premix category.
For Investors and Strategic Acquirers: Roll-up economics work for regional premix blenders with formulation chemistry depth because customer concentration among integrated protein operators is squeezing undifferentiated competitors into acquisition-ready distress. Target mid-cap specialists with established EFSA additive registry positions and SFDA halal certification documentation. Watch for EU Green Deal CBAM extension to agricultural inputs as the inflection signal that revalues low-carbon vitamin K3 and synthetic amino acid alternative suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | DSM and BASF retooled German facilities to meet ECHA substance volume thresholds without petrochemical intermediates. |
| Performance-Contract Procurement Consolidation | Brazilian integrators now specify enzyme premix suppliers based on documented European Production Efficiency Factor score improvements. |
| Microencapsulation Technology Licensing | Thai and Polish feed manufacturers adopt coated vitamin formats at double-digit rates despite 15-25 percent cost premiums. |
| Halal Certification Documentation Investment | Single premix SKUs exported to US, EU, and Saudi Arabia require simultaneous FDA, EFSA, and SFDA alignment. |
| Carbon-Accounting Integration Program | EU Green Deal CBAM extension creates first-mover advantage for certified low-carbon vitamin K3 alternatives. |
Research Methodology
Multiple input streams—formulation chemistry interviews with premix house technical directors, procurement pattern analysis with Brazilian and Thai integrator feed mill managers, and regulatory alignment assessments with EFSA and FDA compliance officers—were reconciled against secondary validation from customs trade data, SEC 10-K filings of integrated nutrition conglomerates, and ECHA substance volume threshold disclosures. Bottom-up premix volume modeling across enzyme, vitamin, mineral, and amino acid categories was triangulated with top-down feed industry production estimates.
Historical growth trajectories were cross-referenced against expert panel inputs from DSM Animal Nutrition and BASF SE product strategy leads to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product type, application species, physical form, and end-user procurement authority tier. CAGRs were derived from fitted growth curves incorporating phytase engineering adoption rates, REACH registration timeline constraints, and Southeast Asian feed mill consolidation velocity.
Underlying measurement precision varies by segment; enzyme premix growth rates carry tighter precision than mineral premix projections given faster formulation cycle turnover. Forecasts reflect assumptions about regulatory enforcement continuity, fermentation capacity expansion schedules, and integrator verticalization pace. A small set of triggers—EU CBAM agricultural extension timing, Chinese vitamin API export license shifts, and thermostable phytase patent expiries—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market