
 Smart Feeding Systems Market | 2026-2036
Smart Feeding Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Feeding Systems Market Insights
Agricultural equipment distribution is tilting toward direct-to-farm digital channels and integrated service contracts. DeLaval International AB leverages its robotic milking installed base to cross-sell connected feeding modules. GEA Group Aktiengesellschaft anchors its position through backward integration into stainless-steel dispensing hardware. Big Dutchman International GmbH competes on scale across European pork and poultry integrators.
Smart feeding systems encompass automated hardware and software platforms that meter, mix, and distribute feed rations based on real-time animal biometric data, typically operating with dispensing precision within grams per head and integrating with herd management databases. These systems reduce labor inputs and optimize feed conversion ratios across commercial livestock operations. Automatic Feeders dominate installed value due to mature dairy adoption, while Nutrient Delivery Systems capture expanding margin pools in precision protein dosing. IoT-Enabled Systems lead technology deployment, though Data Analytics Tools represent the fastest-expanding attachment revenue as farmers monetize consumption pattern insights.
The EU F-Gas Regulation and CE machinery directives constrain refrigerant-dependent cooling components in automated feed storage, while national veterinary drug residue programs shape formulation software compliance requirements. REACH chemical standards influence contact-material specifications for feed pathway surfaces. Stakeholders must weigh regulatory compliance costs against subscription revenue from analytics platforms as capital equipment margins compress.
Market Dynamics
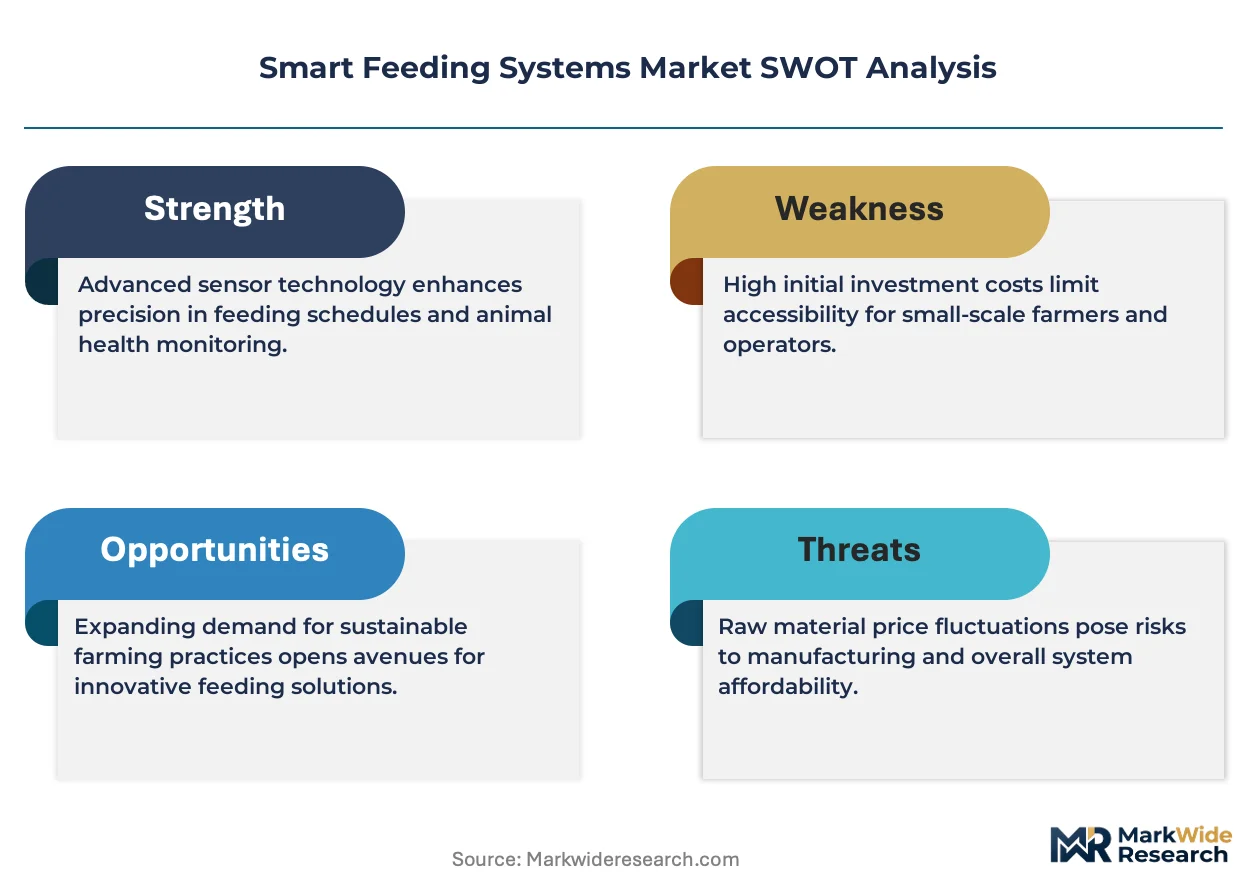
EU F-Gas Regulation compliance deadlines are forcing accelerated hardware replacement cycles across automated feed storage systems, compressing capital equipment lifespans and redirecting procurement budgets toward climate-compliant refrigerant architectures.
Growth Catalysts
- Precision protein dosing mandates:Veterinary drug residue programs in Denmark and the Netherlands require gram-level feed formulation tracking, expanding demand for nutrient delivery systems with integrated compliance logging.
- REACH chemical standards:Contact-material specifications for feed pathway surfaces now require stainless-steel certification, favoring hardware vendors with backward integration into metallurgy.
- Dairy cooperative consolidation:Netherlands-based procurement alliances are standardizing on connected feeding modules that integrate with robotic milking infrastructure.
Market Restraints
- Stainless steel input volatility:Dispensing hardware fabrication depends on austenitic steel grades subject to nickel price swings, compressing margin predictability for European manufacturers.
- Refrigerant supply concentration:Climate-compliant cooling components for feed storage rely on limited EU-certified refrigerant suppliers, creating procurement bottlenecks during retrofit peaks.
- CE machinery directive friction:Multi-country conformity assessment timelines extend equipment certification cycles by eight to fourteen months.
Strategic Opportunities
- Analytics platform monetization:Consumption pattern insights from IoT-enabled systems represent attachable recurring revenue streams as hardware margins compress.
- Denmark precision livestock corridor:Underpenetrated swine operations in Jutland present white-space deployment for automated nutrient delivery beyond established dairy bases.
- EU Green Deal alignment:Carbon accounting requirements for livestock operations create demand for feed conversion ratio optimization software with embedded emissions tracking.
Industry Challenges
- Veterinary software integration:Formulation compliance modules must synchronize with national drug residue databases, requiring specialized API development and testing protocols.
- Biometric sensor calibration:Real-time animal data feeds demand field-level technical expertise scarce in rural installation territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Feeding Systems Market |
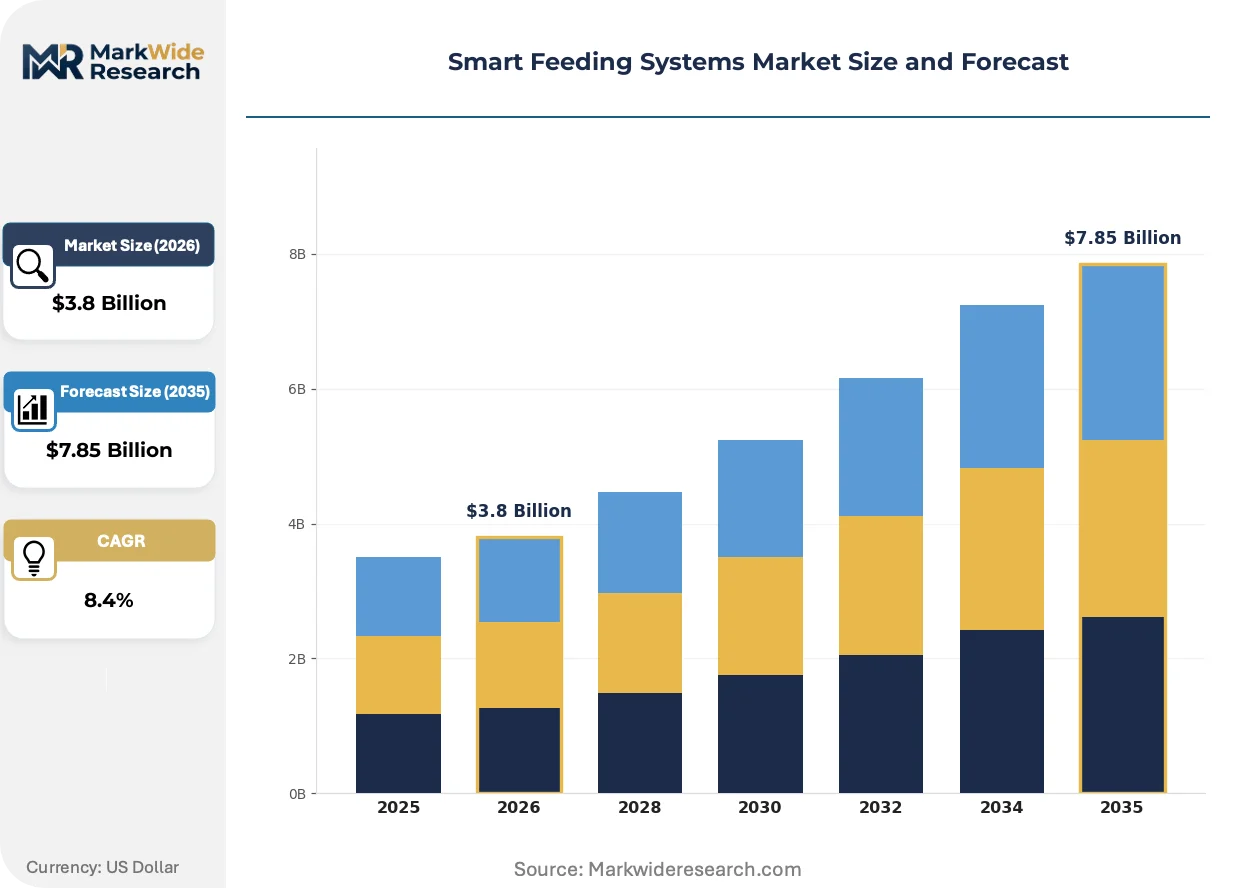
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Feed Dispensing Units, Smart Feeders, Nutrient Delivery Systems End User: Livestock Farmers, Pet Owners, Aquaculture Operators, Poultry Producers Technology: IoT-Enabled Systems, GPS Tracking, Automation Solutions, Data Analytics Tools Application: Animal Nutrition, Pet Care, Fish Farming, Agricultural Practices |
| Companies Covered | GEA Group Aktiengesellschaft, DeLaval International AB, Lely Holding Sarl, Tetra Laval International S.A., Big Dutchman International GmbH, Trioliet B.V., Schauer Agrotronic GmbH, VDL Agrotech, Agco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Feeding Systems Market Trends and Innovations
Feed automation is pivoting from standalone dispensing hardware toward software-defined ration management, with data monetization architectures displacing capital-sales dependency.
Computer vision-based intake monitoring is migrating from experimental dairy installations to standard pork and poultry configurations. Danish integrators are deploying camera arrays at feed stations to detect individual consumption patterns without wearable tags. The technology is migrating from high-value dairy applications toward mid-market protein operations, compressing the addressable premium for sensor hardware.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent cooling retrofits in automated feed storage. Equipment with hydrofluorocarbon-based climate control faces obsolescence by 2030, redirecting R&D budgets toward CO2 and ammonia alternatives. Dairy operations in the Netherlands and Germany are front-loading replacement cycles to avoid stranded-asset risk.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete analytics subscriptions and on-demand technical support tiers. Pork integrators in Denmark now procure software licenses separately from hardware service packages, pressuring vendors to demonstrate standalone value for data insights. Channel partners are responding with modular pricing architectures.
Smart Feeding Systems Market Segmentation
Smart feeding systems segment across hardware, software, and service layers with divergent replacement cycles and margin profiles. Procurement patterns vary sharply between dairy cooperatives seeking integrated platforms and independent livestock operators prioritizing standalone dispensing units.
Product Type:
Replacement cycles stretch from five-year hardware refreshes to decade-long infrastructure investments, creating distinct revenue recognition patterns across the installed base.
- Automatic Feeders:Mature electromechanical platforms with programmable dispensing schedules and basic ration control. Dairy operations in the Netherlands anchor procurement volume through cooperative standardization programs tied to robotic milking retrofits.
- Nutrient Delivery Systems:Precision protein dosing hardware with gram-level formulation accuracy and integrated compliance logging. Veterinary drug residue mandates in Denmark are accelerating deployment across Jutland swine integrators requiring audit-ready documentation trails.
- Feed Dispensing Units:Mid-tier hardware serving small-to-mid livestock operations with limited connectivity features.
- Smart Feeders:Connected devices with cloud-based ration management and remote monitoring capabilities.
Automatic Feeders dominate installed base. Nutrient Delivery Systems is where expansion concentrates.
End User:
Customer sophistication spans from precision livestock farming corridors to fragmented backyard operations, shaping service contract structures and technical support intensity.
- Livestock Farmers:Commercial cattle, swine, and small ruminant operations requiring herd-scale automation. EU Green Deal carbon accounting requirements are embedding feed conversion ratio optimization into procurement specifications for Dutch and German dairy cooperatives.
- Poultry Producers:Layer and broiler integrators with high-throughput feeding lines demanding continuous uptime guarantees. Danish integrators are unbundling software licenses from hardware service packages, pressuring vendors toward modular pricing architectures.
- Aquaculture Operators:Marine and freshwater farming systems with specialized feed dispersal requirements.
- Pet Owners:Consumer households purchasing connected feeders with portion control and smartphone integration.
Livestock Farmers command the largest hardware procurement budgets. Poultry Producers show the steepest expansion trajectory for analytics attachments.
Technology:
Technology layers stack from sensor hardware through connectivity infrastructure to software monetization, with margin migration toward recurring revenue components.
- IoT-Enabled Systems:Networked sensor arrays and edge computing devices collecting real-time consumption data. Netherlands dairy operations are front-loading replacement cycles to avoid stranded-asset risk from EU F-Gas Regulation phase-down schedules affecting climate-controlled feed storage.
- Data Analytics Tools:Consumption pattern insights and predictive ration optimization software. Pork integrators in Denmark now procure these capabilities separately from hardware, creating attachable recurring revenue streams as equipment margins compress.
- Automation Solutions:Programmable logic controllers and robotic dispensing mechanisms without cloud connectivity.
- GPS Tracking:Location-based monitoring for grazing livestock and mobile feeding operations.
IoT-Enabled Systems anchor current deployment value. Data Analytics Tools represent the fastest-climbing margin pool.
Application:
Application contexts range from regulated commercial protein production to discretionary consumer pet care, with compliance burdens and price sensitivity diverging accordingly.
- Animal Nutrition:Commercial livestock feed optimization with veterinary oversight and residue compliance. REACH chemical standards now require stainless-steel certification for feed pathway surfaces, favoring hardware vendors with backward integration into metallurgy.
- Fish Farming:Aquaculture feed management with water-quality integration and species-specific formulation requirements.
- Agricultural Practices:Broad farming applications including mixed livestock and crop-livestock integration.
- Pet Care:Consumer-facing automated feeding with convenience and health monitoring features.
Animal Nutrition concentrates commercial value. Fish Farming offers white-space deployment beyond established terrestrial livestock bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation compliance deadlines anchor procurement momentum in European livestock corridors. Denmark and the Netherlands concentrate precision livestock farming infrastructure. Germany and France follow with dairy cooperative standardization programs.
Netherlands
Dairy cooperatives standardize procurement of connected feeding modules integrated with robotic milking infrastructure. The EU F-Gas Regulation accelerates retrofit demand for climate-compliant refrigerant architectures in automated feed storage. Friesland and Overijssel host concentrated deployment corridors where cooperative procurement alliances front-load replacement cycles.
Denmark
Veterinary drug residue mandates drive gram-level feed formulation tracking across Jutland swine integrators. National compliance programs require audit-ready documentation trails for precision protein dosing. The precision livestock farming corridor concentrates deployment of nutrient delivery systems with integrated logging capabilities.
Germany
Dairy operations front-load hardware replacement cycles to avoid stranded-asset risk from refrigerant phase-down schedules. CE machinery directive timelines extend equipment certification cycles. Bavaria and Lower Saxony anchor cooperative procurement volume for climate-compliant feed storage systems.
France
EU Green Deal carbon accounting requirements embed feed conversion ratio optimization into procurement specifications. EFSA oversight shapes formulation software compliance for veterinary drug residue programs. Brittany and Normandy concentrate dairy infrastructure investment tied to emissions tracking capabilities.
United States
USDA conservation programs incentivize precision feed management for methane reduction in commercial cattle operations. FDA veterinary feed directive compliance drives demand for documented ration tracking. Wisconsin and California dairy belts anchor North American deployment of automated nutrient delivery platforms.
Smart Feeding Systems Market Competitive Landscape
Integrated platform vendors and specialized hardware fabricators split the market along connectivity depth. Consolidation pressure concentrates around robotic milking installed bases where cross-selling opportunities attach feeding modules to existing automation infrastructure. Two archetypes dominate: vertically integrated metallurgy specialists controlling stainless-steel dispensing supply chains, and software-defined analytics platforms monetizing consumption pattern data. Competitive moves center on backward integration into contact-material certification and unbundled service contract architectures.
Within the integrated dairy automation tier, DeLaval International AB and GEA Group Aktiengesellschaft exemplify platform vendors leveraging robotic milking footprints to anchor connected feeding deployments. Big Dutchman International GmbH occupies a position among scale-oriented hardware specialists serving pork and poultry integrators across European protein corridors. These three anchors represent divergent strategic vectors: software attachment revenue, metallurgical backward integration, and volume-scale deployment across livestock categories.
| Leading Market Players |
|---|
| GEA Group Aktiengesellschaft |
| DeLaval International AB |
| Lely Holding Sarl |
| Tetra Laval International S.A. |
| Big Dutchman International GmbH |
| Trioliet B.V. |
| Schauer Agrotronic GmbH |
| VDL Agrotech |
| Agco Corporation |
| Others |
Pricing and Supply Chain Analysis
Austenitic stainless steel supply concentration in Germany and Italy directly determines margin retention for European dispensing hardware fabricators facing REACH certification requirements. Nickel price volatility propagates through component costs, compressing equipment margins while elevating the value capture of software-defined service tiers.
Pricing Analysis
Hardware procurement costs diverge by fifteen to twenty-five percent between Netherlands dairy cooperatives and independent Danish swine operators. Three-tier pricing structure across premium, standard, and economy levels reflects stainless-steel certification grade and bundled analytics subscription depth. Pricing pressure stems from cooperative procurement alliance consolidation demanding volume discounts. Independent livestock operators exhibit highest price sensitivity, while integrated dairy platforms prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
Contract manufacturing for sensor assemblies and PLC controllers concentrates among EMS providers in Germany, Poland, and the Czech Republic. Feed pathway fabrication draws from Italian and German stainless-steel mills with REACH-certified metallurgy capabilities. Single-source vulnerability runs through EU-certified refrigerant suppliers for climate-controlled storage retrofits. Distribution runs through agricultural equipment dealers with service technician networks across Friesland, Jutland, and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart feeding systems occupy an early-cycle expansion phase as veterinary drug residue mandates force gram-level tracking adoption across underpenetrated swine corridors. Precision livestock farming infrastructure buildout in Denmark and the Netherlands provides the penetration tailwind.
For Market Incumbents: Harden defensible positions through captive stainless-steel metallurgy certification and API integration with national drug residue databases. DeLaval and GEA Group leverage robotic milking installed bases to cross-sell connected feeding modules before emerging analytics-native entrants displace hardware-centric revenue streams. CE machinery directive compliance investment creates certification moats extending equipment replacement cycles.
For New Entrants and Emerging Players: Pursue white-space deployment in Jutland swine operations where nutrient delivery system penetration lags dairy automation density. Denmark's precision livestock corridor offers the most penetrable geography given veterinary mandate enforcement without incumbent platform lock-in. Go-to-market positioning through unbundled software licenses targets pork integrators already fragmenting traditional bundled service contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward software-defined analytics platforms monetizing consumption pattern data as hardware margins compress across the analysis window. Acquisition targets exhibit recurring revenue attachment rates above industry hardware-sales dependency. The signal to watch is cooperative procurement alliance standardization velocity as an inflection indicator for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless-Steel Metallurgy | REACH certification control secures margin retention against nickel price volatility. |
| API Development for Veterinary Database Integration | Denmark and Netherlands drug residue compliance creates platform stickiness. |
| Analytics Platform Unbundling | Modular pricing architectures capture recurring revenue from Danish pork integrators. |
| Climate-Compliant Refrigerant Architecture Transition | EU F-Gas Regulation alignment prevents stranded-asset risk in feed storage systems. |
| Denmark Precision Livestock Corridor Expansion | Jutland swine operations represent underpenetrated deployment beyond dairy bases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, encompassing dairy cooperative procurement directors, swine integrator operations managers, agricultural equipment dealer principals, and precision livestock farming technology specialists. Secondary validation drew from EU F-Gas Regulation implementation timelines, REACH chemical standard certifications, EFSA veterinary oversight documentation, and national drug residue program compliance records. Bottom-up equipment deployment estimates and top-down cooperative procurement budget analysis were triangulated to anchor market sizing.
Calibration against historical retrofit cycle patterns and refrigerant phase-down schedule acceleration informed projection modeling across the analysis window. Segmentation dimensions encompassed hardware type, software monetization tier, livestock category, technology layer, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle compression and analytics attachment rate trajectories. Forecast inputs incorporated EU Green Deal carbon accounting adoption curves and veterinary mandate enforcement intensity variations.
Sensitivities concentrate around nickel price volatility impacts on hardware margins, refrigerant supplier bottleneck duration, and cooperative procurement alliance consolidation velocity. Forecasts reflect documented assumptions regarding F-Gas Regulation compliance deadline adherence and CE machinery directive timeline stability. Quarterly review of stainless-steel input cost indices and veterinary software integration certification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Animal Feed Protease Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Herd Management Software Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Roughage Feed Market
Livestock Management
Bird Feeder Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
United States Swine Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
China Swine Feed Market
Livestock Management
Layer Breeding System Market
Livestock Management
Swine Feed Market