

Equine Artificial Insemination Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Artificial Insemination Market Insights
Veterinary embryologists trained in advanced reproductive technologies is bifurcating the competitive landscape between full-service laboratories and equipment-only suppliers. Zoetis leverages its pharmaceutical distribution network to bundle semen extenders with hormonal protocols. MINITÜB anchors European supply chains through precision-manufactured collection kits and cryopreservation systems. IMV Technologies dominates portable refrigeration units for field-based cooled semen programs.
Equine artificial insemination encompasses the clinical collection, processing, preservation, and transcervical deposition of stallion semen to achieve pregnancy without natural mating, typically requiring extenders containing glucose-egg yolk or milk-based diluents to protect spermatozoa during cooling or freezing. The practice enables genetic dissemination across continents while reducing injury risk to valuable breeding stock and controlling infectious disease transmission. Fresh semen commands premium pricing for same-day breeding protocols, while frozen semen unlocks international trade in elite genetics despite lower post-thaw fertility rates. Sexed semen represents an emerging margin pool as sorting technology improves for Thoroughbred and Warmblood breeders seeking gender-biased foal crops.
The USDA enforces health certificate and CEM testing requirements for interstate and international semen shipment, directly shaping cold-chain logistics and quarantine protocols for commercial studs. FDA oversight of semen extenders as animal drugs creates formulation barriers for new market entrants lacking veterinary pharmaceutical registrations. Equine researchers and breeding farm managers must monitor evolving genomic selection criteria and cryopreservation advances to optimize genetic return on insemination investment.
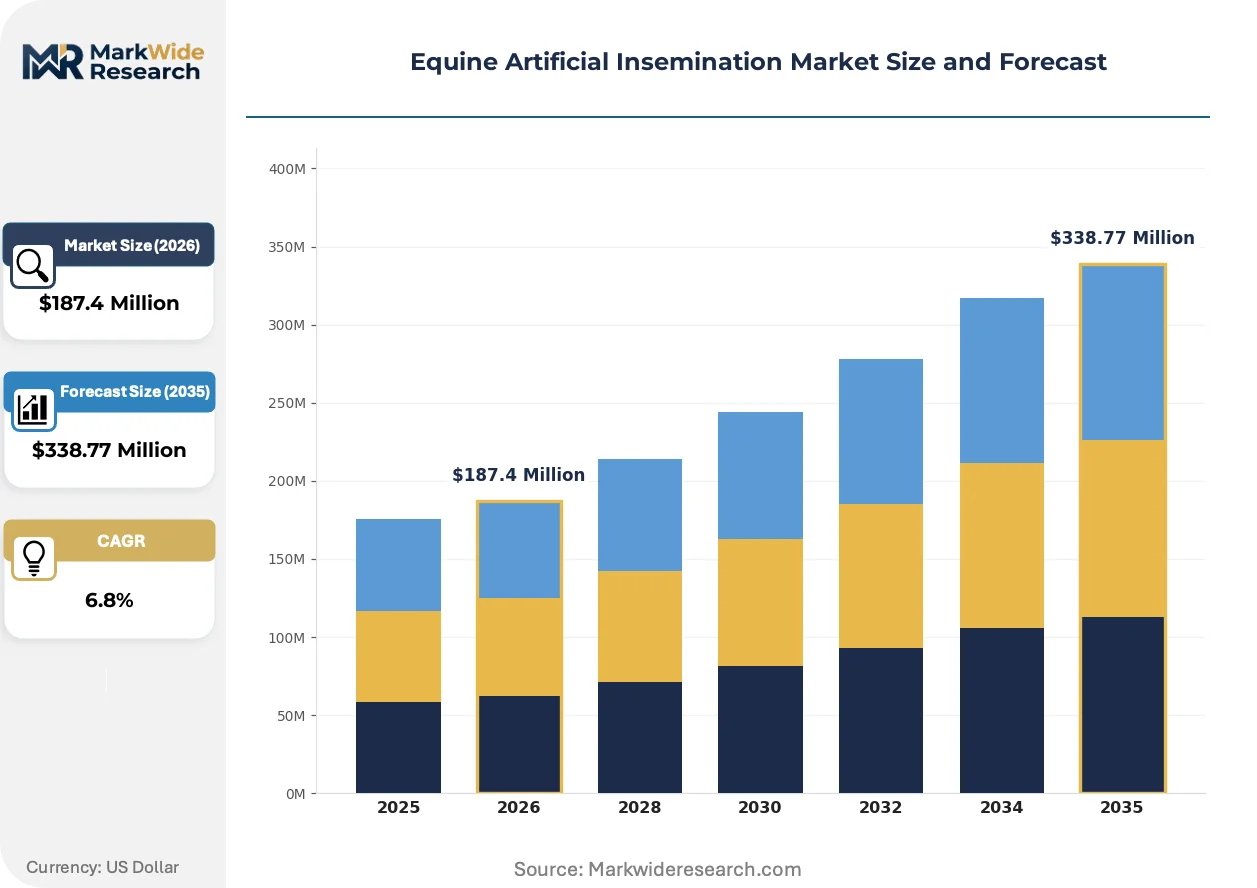
Market Dynamics
Veterinary biosecurity protocols are tightening across breeding jurisdictions following contagious equine metritis outbreaks, forcing studs to abandon live cover in favor of processed semen with documented health certification chains.
Growth Catalysts
- Cooled Semen Logistics:Advanced refrigeration units enable 48-hour viability windows, allowing Kentucky and Irish breeding farms to access distant stallion genetics without mare transport costs.
- USDA Interstate Health Certificates:Standardized CEM testing requirements for semen shipment have created compliant cold-chain infrastructure that reduces disease transmission risk and builds buyer confidence.
- Genetic Selection Pressure:Thoroughbred and Warmblood breeders increasingly prioritize proven performance bloodlines, driving demand for verified progeny data linked to processed semen batches.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryopreservation depends on regional industrial gas distributors, with pricing volatility in rural breeding clusters limiting frozen semen program expansion.
- FDA Extender Classification:Semen diluents fall under animal drug oversight, creating multi-year registration barriers for novel formulation entrants without veterinary pharmaceutical infrastructure.
- Post-Thaw Fertility Gap:Frozen semen consistently delivers lower conception rates than cooled alternatives, restricting adoption among commercial broodmare operations with tight breeding windows.
Strategic Opportunities
- Sexed Semen Sorting:Flow cytometry advances targeting X-chromosome bearing spermatozoa offer Thoroughbred breeders gender-biased foal crops for racing or breeding stock purposes.
- Veterinary Embryologist Training:Certification programs in advanced reproductive technologies create service revenue pools for laboratories capable of offering transcervical insemination and embryo transfer.
- Field-Based Cooled Programs:Portable refrigeration systems enable on-farm semen processing without centralized laboratory infrastructure, penetrating previously underserved regional breeding clusters.
Industry Challenges
- Cryopreservation Protocol Standardization:Variability in freezing rates and extender formulations across laboratories produces inconsistent post-thaw motility, complicating international genetic trade.
- Veterinary Reproductive Specialist Scarcity:Qualified embryologists capable of transcervical catheter placement and ultrasound-guided insemination remain concentrated in established breeding regions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Artificial Insemination Market Trends and Innovations
Reproductive biotechnology is reshaping how elite equine genetics circulate across breeding jurisdictions, with three distinct forces altering competitive positioning among service providers and equipment suppliers.
Microfluidic sperm sorting technology is fragmenting the traditional flow cytometry market for sexed semen production. Smaller breeding operations now access gender-selection capabilities previously restricted to university laboratories and large commercial studs. This capability diffusion is compressing pricing power among incumbent sorting service providers while enabling boutique stallion stations to differentiate through specialized foal-gender programs.
EU REACH chemical registration requirements are reshaping semen extender formulation strategies for European distributors. Milk-based diluents face scrutiny for residual antibiotic content, pushing manufacturers toward defined protein-free alternatives. German and Dutch veterinary suppliers are accelerating validation of synthetic cryoprotectant blends to preempt regulatory discontinuation of legacy egg-yolk formulations.
Stud farm procurement patterns are consolidating around full-service reproductive partnerships rather than equipment-only transactions. Kentucky breeding operations increasingly contract for integrated semen collection, processing, and delivery services with guaranteed pregnancy rates. This service bundling is displacing standalone portable refrigeration unit sales in the North American performance horse segment.
Equine Artificial Insemination Market Segmentation
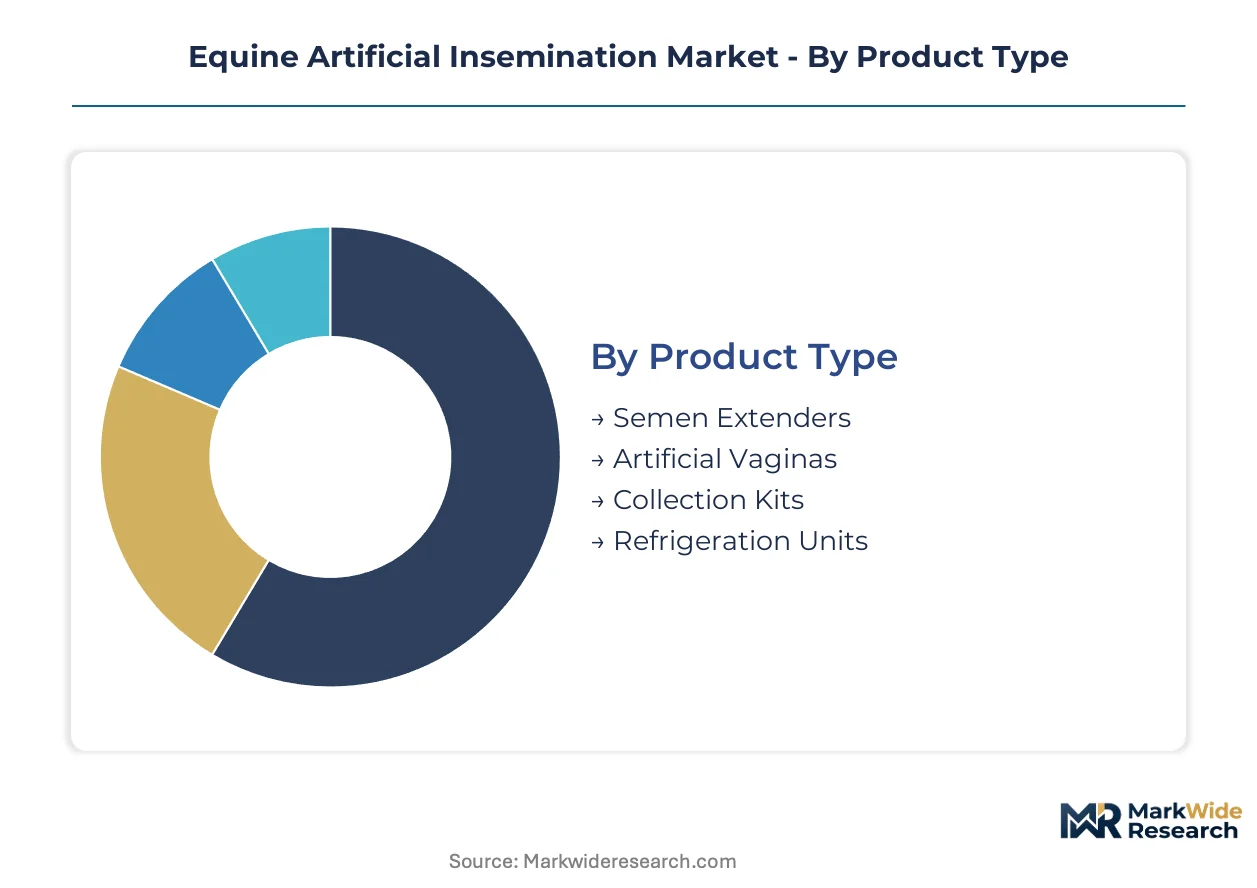
Segmentation in equine artificial insemination reveals how equipment, consumables, and services flow through distinct procurement channels. Breeders, veterinarians, and research institutions each trigger different purchasing patterns based on technical sophistication and regulatory compliance requirements.
Product Type:
Distribution channels bifurcate sharply between consumable reorders and capital equipment sales, with veterinary distributors dominating extender volumes while direct manufacturer relationships anchor refrigeration unit procurement.
- Semen Extenders:Glucose-egg yolk and milk-based diluents protect spermatozoa during temperature transitions. Kentucky breeding farms drive bulk extender demand through integrated service contracts with guaranteed pregnancy rates.
- Refrigeration Units:Portable cooling systems enable 48-hour semen viability for field-based programs. Irish studs and Australian regional breeders prioritize these units to eliminate mare transport costs.
- Artificial Vaginas:Precision-molded collection devices with thermal regulation capabilities.
- Collection Kits:Disposable packages containing sterile sheaths, filters, and transport vessels.
By volume, Semen Extenders leads. By growth pace, Refrigeration Units is expanding most quickly.
Application:
Cost tiers separate high-volume breeding operations from specialized service providers, with capital intensity and regulatory burden determining margin structures across each application node.
- Breeding Farms:Large-scale Kentucky and Irish operations maintain in-house laboratories with full-time embryologists. These facilities command premium pricing for verified progeny data and health-certified semen batches.
- Veterinary Clinics:Regional practices offer transcervical insemination and pregnancy monitoring without full processing capabilities. Clinics in Germany and France face EU REACH compliance costs for extender formulations.
- Stud Services:Commercial stallion stations focusing on collection and distribution.
- Racing Stables:Performance-oriented operations prioritizing genetic access over ownership.
By revenue concentration, Breeding Farms dominates. By margin expansion, Veterinary Clinics is climbing the fastest.
End User:
Customer sophistication levels create three distinct service tiers, from research-grade precision to commercial breeding efficiency.
- Horse Breeders:Thoroughbred and Warmblood operations seeking verified bloodlines. Breeders in Japan and Saudi Arabia import frozen semen under strict quarantine protocols, paying premium logistics costs for genetic access.
- Performance Trainers:Competition-focused professionals requiring rapid genetic turnaround. Trainers across Florida and California prefer cooled semen programs for flexibility in matching mares to distant stallions.
- Equine Researchers:University programs advancing cryopreservation protocols.
- Equestrian Clubs:Member-based organizations with periodic breeding needs.
By transaction value, Horse Breeders leads. By technology adoption speed, Performance Trainers is gaining share fastest.
Technology:
Maturity curves separate established methods from emerging capabilities, with fertility rates and regulatory complexity shaping adoption boundaries.
- Cooled Semen:48-hour viability windows balance accessibility with fertility performance. Kentucky and Irish breeding farms have displaced fresh methods, driving demand for portable refrigeration and standardized extender formulations.
- Sexed Semen:Flow cytometry sorting targets X-chromosome bearing spermatozoa for gender-biased foal crops. Microfluidic advances are fragmenting pricing power among traditional sorting service providers.
- Fresh Semen:Same-day collection and deposition protocols with highest conception rates.
- Frozen Semen:Cryopreserved batches enabling international genetic trade despite lower post-thaw fertility.
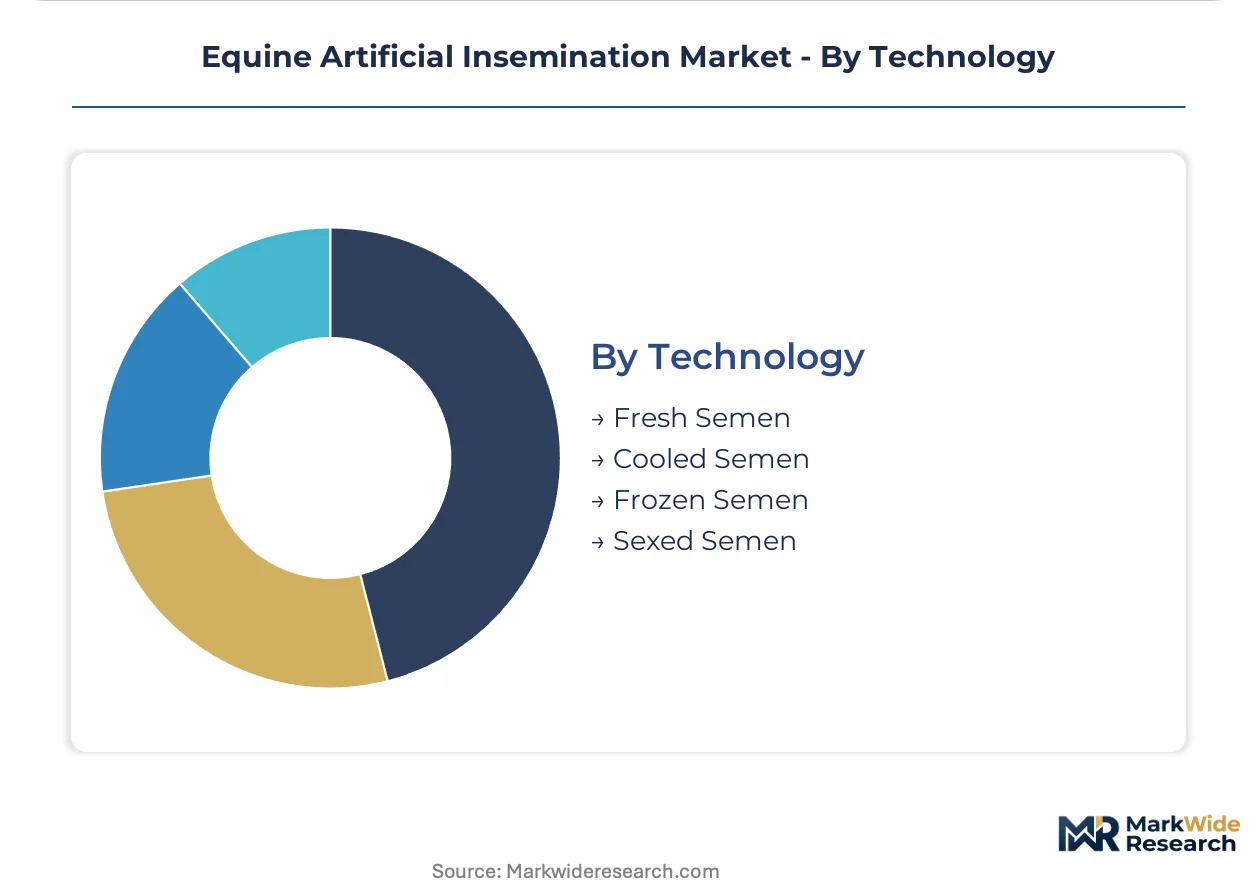
By current deployment scale, Cooled Semen leads. By capability diffusion, Sexed Semen shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA health certificate requirements anchor North American breeding operations, while EU REACH chemical regulations reshape extender formulations across European supply chains. Kentucky and Ireland maintain the densest concentrations of commercial studs, with Japan and Australia emerging as high-value import destinations for verified genetics.
United States
Kentucky breeding farms drive cooled semen demand through integrated service contracts with guaranteed pregnancy rates. USDA enforces CEM testing and interstate health certificates for semen shipment, creating compliant cold-chain infrastructure. The Bluegrass region concentrates full-service laboratories employing certified veterinary embryologists for transcervical insemination.
Ireland
Irish studs prioritize portable refrigeration units to eliminate mare transport costs while accessing distant stallion genetics. The country operates under EU REACH requirements for semen extender chemical registration. County Kildare and County Tipperary host dense clusters of Thoroughbred breeding operations with in-house processing capabilities.
Germany
German veterinary suppliers accelerate validation of synthetic cryoprotectant blends to preempt regulatory discontinuation of legacy egg-yolk formulations. ECHA oversees chemical safety assessments for extender ingredients under REACH. Lower Saxony and Bavaria concentrate precision-manufactured collection kit production for European distribution.
Japan
Japanese Thoroughbred breeders import frozen semen under strict quarantine protocols administered by the national animal health authority. METI guidelines shape biotechnology investment in reproductive technologies. Hokkaido breeding clusters pay premium logistics costs for verified progeny data linked to North American and European stallions.
Australia
Australian regional breeders deploy field-based cooled semen programs using portable refrigeration systems without centralized laboratory infrastructure. The Department of Agriculture enforces biosecurity protocols for imported genetics. New South Wales and Victoria stud farms increasingly contract for integrated collection and delivery services.
Equine Artificial Insemination Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the equine artificial insemination supply chain. Full-service laboratories with certified embryologists command premium pricing through guaranteed pregnancy rate contracts, while equipment-only suppliers compete on manufacturing scale and distribution reach. Pharmaceutical-backed players bundle semen extenders with hormonal protocols, and precision manufacturers anchor European supply chains through cryopreservation systems. Competitive moves concentrate on strategic partnerships between laboratories and breeding farms, plus geographic expansion of portable refrigeration distribution networks into underserved regional clusters.
Among pharmaceutical and veterinary suppliers, Zoetis represents the bundled-service archetype leveraging distribution infrastructure across multiple animal health categories. MINITÜB anchors German precision manufacturing for collection kits and cryopreservation equipment. IMV Technologies exemplifies the portable equipment specialization tier, with its product range concentrating on field-based refrigeration systems for cooled semen logistics.
| Leading Market Players |
|---|
| IMV Technologies |
| Stallion AI Services |
| Zoetis |
| Neogen Corporation |
| Zerlotti Genetics |
| MINITÜB |
| Dairymac |
| HOFFMAN A.I. BREEDERS |
| Spervital |
| Others |
Pricing and Supply Chain Analysis
Forty-eight-hour semen viability windows concentrate pricing power among Kentucky and Irish laboratories with verified cold-chain infrastructure, while regional breeders without captive logistics face cost premiums that compress margins and limit genetic access.
Pricing Analysis
Price spreads between Kentucky full-service laboratories and regional field-based programs reflect service bundling premiums versus equipment-only procurement. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed pregnancy rate contracts from per-dose transactional sales and bulk extender reorders. Pricing pressure stems from microfluidic sperm sorting technology diffusion that fragments flow cytometry service margins. Commercial broodmare operations with tight breeding windows exhibit highest price sensitivity due to fertility risk exposure, while Japanese and Saudi Arabian importers absorb premium logistics costs for verified genetics.
Supply Chain Analysis
Container availability constraints on transatlantic trade lanes elevate inbound logistics costs for German-manufactured collection kits and cryopreservation equipment destined for North American breeding farms. Supply concentrates in Germany, the United States, and Ireland for precision-manufactured artificial vaginas and portable refrigeration units. Raw material dependencies include liquid nitrogen from regional industrial gas distributors, glucose-egg yolk extender components, and synthetic cryoprotectant chemical feedstocks. Single-source vulnerability characterizes liquid nitrogen supply concentration in rural breeding clusters. Distribution runs through veterinary pharmaceutical distributors for consumables and direct manufacturer relationships for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive positioning as stud farms consolidate procurement around integrated reproductive partnerships rather than equipment-only transactions, with interoperability between laboratory information systems and breeding farm management software emerging as the decisive ecosystem battleground.
For Market Incumbents: Consolidate laboratory networks through acquisition of regional veterinary embryologist practices to secure certified talent pools and anchor guaranteed pregnancy rate contracts. Lock in backward integration into semen extender manufacturing to preempt FDA registration barriers for new formulation entrants. Defend against microfluidic sorting technology fragmentation by embedding proprietary protocols into full-service bundles that resist unbundling.
For New Entrants and Emerging Players: Lead with portable refrigeration system deployment targeting Australian regional breeders and underserved North American performance horse clusters lacking centralized laboratory infrastructure. Penetrate veterinary clinic segments in Germany and France facing EU REACH compliance cost pressures with defined protein-free extender alternatives. Position around field-based cooled semen programs as the lowest-capital-intensity entry vector.
For Investors and Strategic Acquirers: Carve-out targets emerge from animal health pharmaceutical parents seeking to divest non-core reproductive technology assets amid portfolio rationalization pressures. Long-term viability hinges on service revenue durability as equipment sales commoditize. Monitor USDA interstate health certificate enforcement intensity as the inflection signal—tightening biosecurity protocols accelerate processed semen substitution for live cover and expand addressable market for compliant cold-chain providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Embryologist Certification Programs | Creates captive service revenue pools for laboratories offering transcervical insemination and embryo transfer capabilities. |
| Synthetic Cryoprotectant Validation | Preempts ECHA regulatory discontinuation of legacy egg-yolk formulations under EU REACH chemical registration requirements. |
| Portable Refrigeration Distribution Expansion | Penetrates Australian and North American regional breeding clusters without centralized laboratory infrastructure. |
| Integrated Service Partnership Contracts | Displaces standalone equipment sales in Kentucky through guaranteed pregnancy rate bundling with genetic verification. |
| Microfluidic Sperm Sorting Technology Licensing | Fragments traditional flow cytometry pricing power and enables boutique stallion station differentiation. |
Research Methodology
The analysis maps semen extender formulations, portable refrigeration systems, and artificial vagina manufacturing, each validated through breeding farm managers, veterinary embryologists, pharmaceutical distribution executives, and regulatory affairs specialists at animal health agencies. Primary interviews with Kentucky laboratory directors and Irish stud farm operators combined with secondary validation against USDA interstate health certificate filings, ECHA REACH chemical registration databases, FDA animal drug oversight records, and customs trade data for cryopreservation equipment imports. Bottom-up demand modeling from individual breeding operation procurement patterns triangulated against top-down pharmaceutical supplier revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled technology type, application node, end-user sophistication tier, and geographic regulatory cluster as core segmentation dimensions. CAGRs derived from fitted growth curves incorporating liquid nitrogen supply concentration constraints, veterinary specialist scarcity indices, and biosecurity protocol enforcement intensity as industry-specific forecast inputs.
Forecasts assume regulatory continuity in USDA interstate health certificate regimes and EU REACH chemical registration requirements; material policy shifts would require re-modeling cold-chain compliance costs and extender formulation barriers. Practitioners should keep alternative scenarios live as contagious equine metritis outbreak frequency and FDA animal drug classification precedents evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.