
 China Wheat Protein Market | 2026-2036
China Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Wheat Protein Market Outlook
Enzymatic hydrolysis and precision fermentation is rewriting protein extraction yields from lower-grade wheat streams. Shandong Qufeng Food Technology Co. Ltd leverages vertical integration from milling to isolate production across its provincial facilities. Archer Daniels Midland Company anchors imported wheat sourcing networks that sustain premium isolate throughput. Wilmar International Ltd competes on bulk gluten supply contracts with national bakery chains.
Wheat protein comprises the water-insoluble gluten complex of gliadin and glutenin fractions, typically recovered through dough washing and centrifugal separation to achieve protein contents ranging from 75% to 85% on a dry basis. Its primary commercial purpose centers on viscoelastic structure formation in leavened baked goods and fibrous texturization in plant-based meat analogues. Wheat gluten dominates volume flows into industrial bakery operations where protein strength directly determines loaf volume recovery. Hydrolyzed wheat protein generates the fastest growth trajectory as cosmetics formulators and nutraceutical compounders seek lower molecular weight peptides for solubility and bioavailability. Textured wheat protein occupies the emerging margin pool as domestic meat substitute brands scale extrusion capacity.
China's SAMR enforces GB standards for protein content claims and additive labeling that directly constrain formulation choices and market access for imported concentrates. The country's national food safety regulator alongside provincial agricultural authorities coordinates wheat quality grading that upstream affects gluten extraction efficiency and final isolate purity. Stakeholders must monitor how evolving MEE wastewater discharge rules for starch and gluten processors reshape production economics across Shandong's concentrated manufacturing belt.
Market Dynamics
Enzymatic hydrolysis is compressing extraction costs for lower-grade wheat streams while SAMR's tightened protein labeling rules force reformulation investments across Shandong's processing belt. This dual pressure squeezes margin structures and accelerates consolidation among isolate manufacturers.
Growth Catalysts
- Plant-based meat analogues:Domestic meat substitute brands scale extrusion capacity, pulling textured wheat protein volumes into foodservice channels.
- GB standards enforcement:SAMR's protein content claim rules create compliance barriers that favor certified domestic producers over imports.
- Shandong cluster density:Proximity of milling, starch processing, and isolate production within provincial boundaries cuts logistics costs for gluten recovery.
Market Restraints
- Wheat quality volatility:Provincial agricultural grading variations disrupt gluten extraction yields and isolate purity consistency.
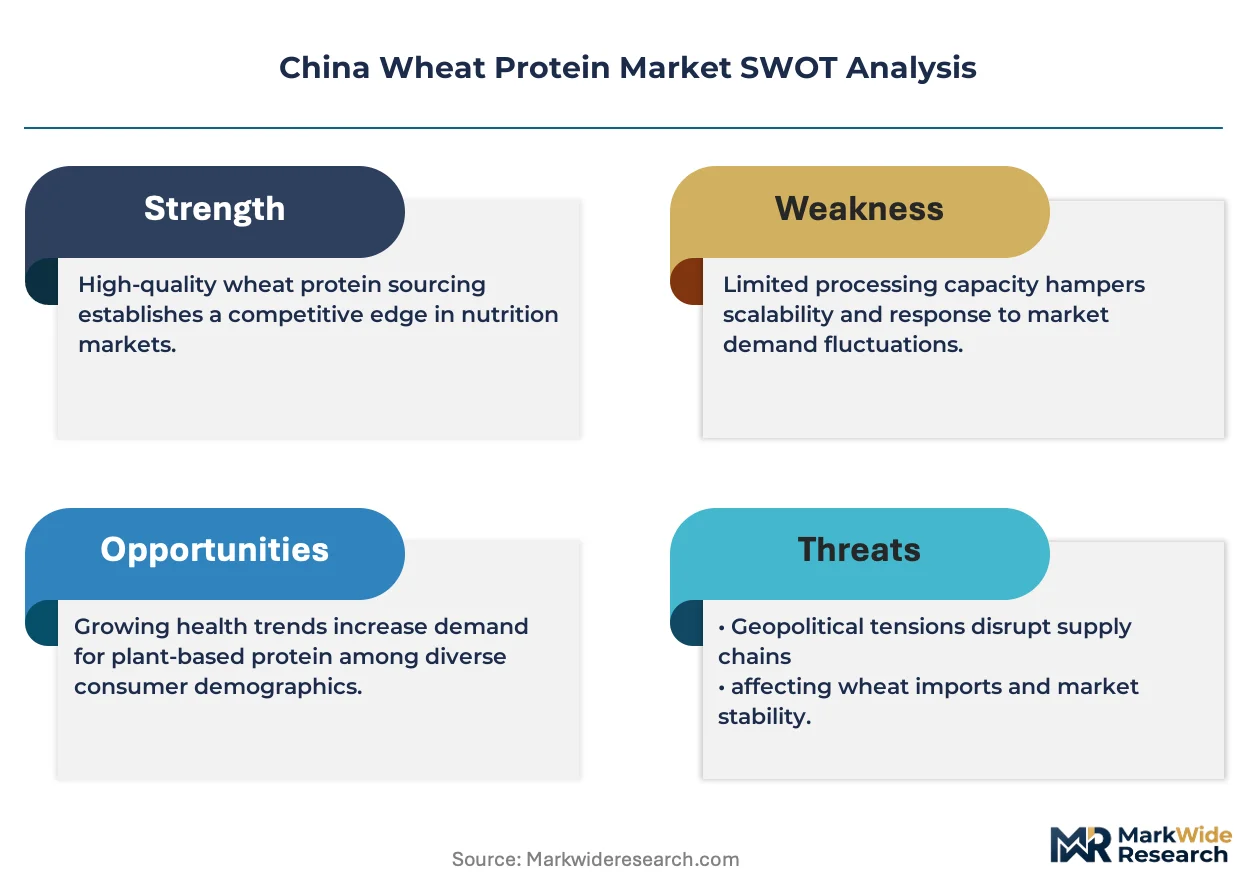
- Shandong supply concentration:Overreliance on a single province's processing capacity exposes buyers to localized weather and policy shocks.
- Peptide substitute threat:Soy and pea protein isolates compete for plant-based meat applications with comparable texturization at lower input costs.
Strategic Opportunities
- Cosmetics peptide demand:Hydrolyzed wheat protein's lower molecular weight fractions penetrate skincare formulators seeking bioavailable ingredients.
- Henan underpenetration:Wheat production in central provinces lacks downstream isolate infrastructure, offering greenfield processing sites.
- Dual carbon alignment:MEE wastewater discharge rules favor processors investing in closed-loop water recovery systems with carbon credit eligibility.
Industry Challenges
- Enzyme engineering talent scarcity:Precision fermentation and hydrolysis optimization require specialized biochemists concentrated in coastal biotech hubs.
- GB certification timelines:SAMR's updated additive labeling approvals delay new isolate product launches by 12-18 months.
- Legacy equipment retrofit costs:Centrifugal separation systems require capital upgrades to meet MEE effluent standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Wheat Protein Market |
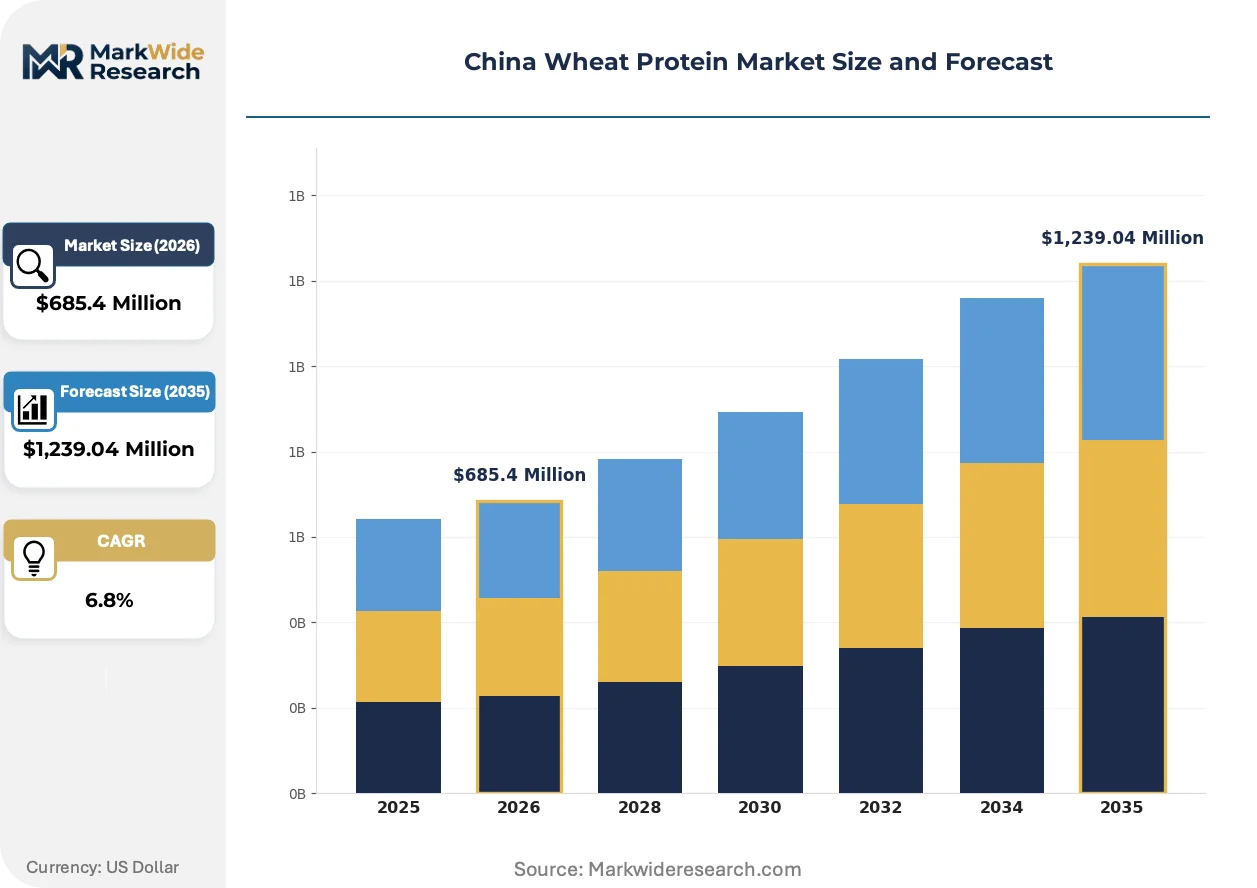
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Wheat Protein, Hydrolyzed Wheat Protein, Isolated Wheat Protein, Wheat Gluten Application: Bakery, Meat Substitutes, Snacks, Beverages Form: Powder, Granule, Liquid, Concentrate End User: Food Industry, Nutraceuticals, Animal Feed, Cosmetics |
| Companies Covered | Anhui Ante Food Co. Ltd, Archer Daniels Midland Company, Ezaki Glico Co. Ltd, Shandong Qufeng Food Technology Co. Ltd, Wilmar International Ltd, Shandong Newnature Biotechnology Co., Ltd., Shandong Bailong Chuangyuan Bio-tech Co., Ltd., Shandong Benyue Biological Technology Co., Ltd., Cargill, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Wheat Protein Market Strategic Shifts
Precision fermentation and enzymatic processing are rewriting cost structures for protein recovery while regulatory tightening reshapes competitive access. Three forces currently dominate strategic planning for wheat protein stakeholders.
Enzymatic hydrolysis systems operating at ambient temperature reduce energy inputs for peptide extraction from damaged wheat streams. Cosmetics compounders and nutraceutical blenders adopt these isolates for solubility advantages in aqueous formulations. Conventional acid hydrolysis methods are rendering obsolete across premium peptide segments.
SAMR's updated GB standards for protein content claims and additive labeling tighten formulation disclosure requirements. Imported concentrates face extended compliance reviews while domestic certified producers gain shelf space advantages. Bakery chains and meat substitute manufacturers reformulate around declared protein thresholds to maintain market access.
Direct procurement contracts between plant-based meat brands and Shandong processors displace traditional distributor intermediaries. Foodservice operators and retail private labels negotiate volume commitments with isolate producers for textured wheat protein supply. This channel compression concentrates price negotiation leverage with buyers in eastern coastal manufacturing zones.
China Wheat Protein Market Segmentation
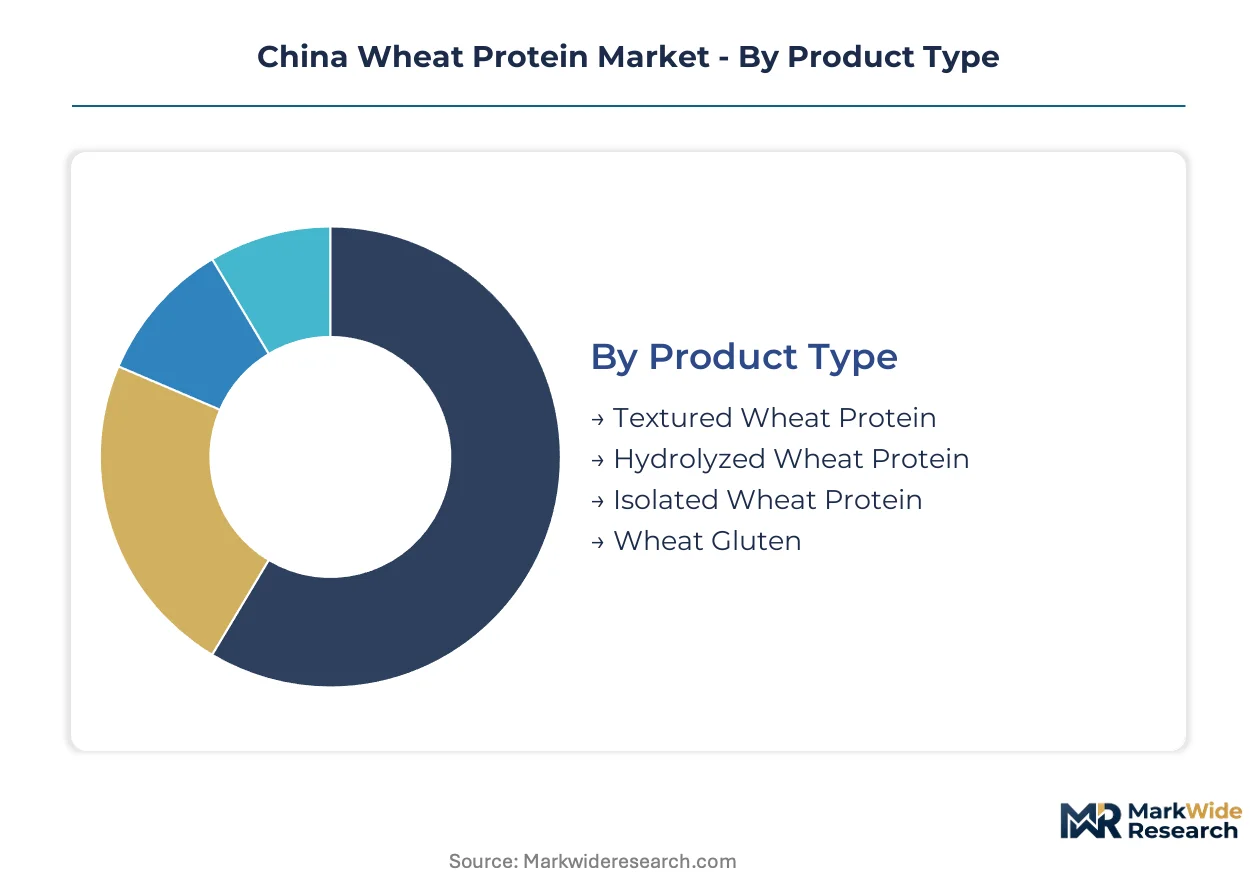
China's wheat protein market segments along functional performance tiers that dictate procurement patterns across Shandong's processing belt. Distinct technical specifications separate commodity gluten from high-value isolates, creating divergent margin structures and customer loyalty profiles.
Product Type:
Mature commodity grades anchor volume flows while emerging specialty isolates capture expanding margin pools.
- Wheat Gluten:The water-insoluble protein complex recovered through dough washing delivers 75-85% protein content for industrial bakery operations. Shandong's milling clusters supply national bread manufacturers where protein strength determines loaf volume recovery. SAMR's tightened labeling rules force reformulation investments that favor certified domestic processors over imports.
- Hydrolyzed Wheat Protein:Enzymatic hydrolysis reduces molecular weight to enhance solubility for cosmetics formulators and nutraceutical compounders. Precision fermentation advances are compressing extraction costs from damaged wheat streams. Cosmetics brands in coastal manufacturing zones specify these peptides for bioavailability in aqueous skincare formulations.
- Textured Wheat Protein:Extruded fibrous structures serve plant-based meat analogues scaling capacity in foodservice channels.
- Isolated Wheat Protein:Premium concentrates achieve higher purity thresholds for specialized nutritional applications.
Wheat gluten retains volume leadership; hydrolyzed wheat protein holds the steepest expansion curve.
Application:
Cost tiers separate commodity food manufacturing from premium functional nutrition positioning.
- Bakery:Industrial bread and noodle manufacturers consume the largest protein volumes where gluten strength controls processing economics. National bakery chains negotiate bulk supply contracts with Shandong processors for consistent protein performance across production runs.
- Meat Substitutes:Domestic plant-based brands scale extrusion capacity, pulling textured wheat protein into direct procurement relationships that displace traditional distributor channels.
- Snacks:Processed savory applications utilize modified gluten for texture enhancement in regional brands.
- Beverages:Hydrolyzed peptides penetrate functional drink formulations targeting protein fortification claims.
Bakery commands procurement volume; meat substitutes are climbing the fastest.
Form:
Supply concentration in powder processing reflects downstream handling efficiency requirements.
- Powder:Spray-dried isolates dominate bulk logistics for industrial food manufacturers and nutritional compounders. Shandong's integrated facilities optimize powder flowability for automated bakery mixing systems and extrusion lines.
- Liquid:Hydrolyzed protein solutions serve cosmetics formulators seeking direct incorporation into emulsion systems without rehydration steps.
- Granule:Agglomerated formats reduce dusting for meat analogue extrusion operations.
- Concentrate:Intermediate protein grades bridge commodity and isolate specifications for cost-sensitive applications.
Powder retains distribution dominance; liquid formats gain share fastest in coastal cosmetics clusters.
End User:
Customer type determines specification stringency and certification burden under SAMR oversight.
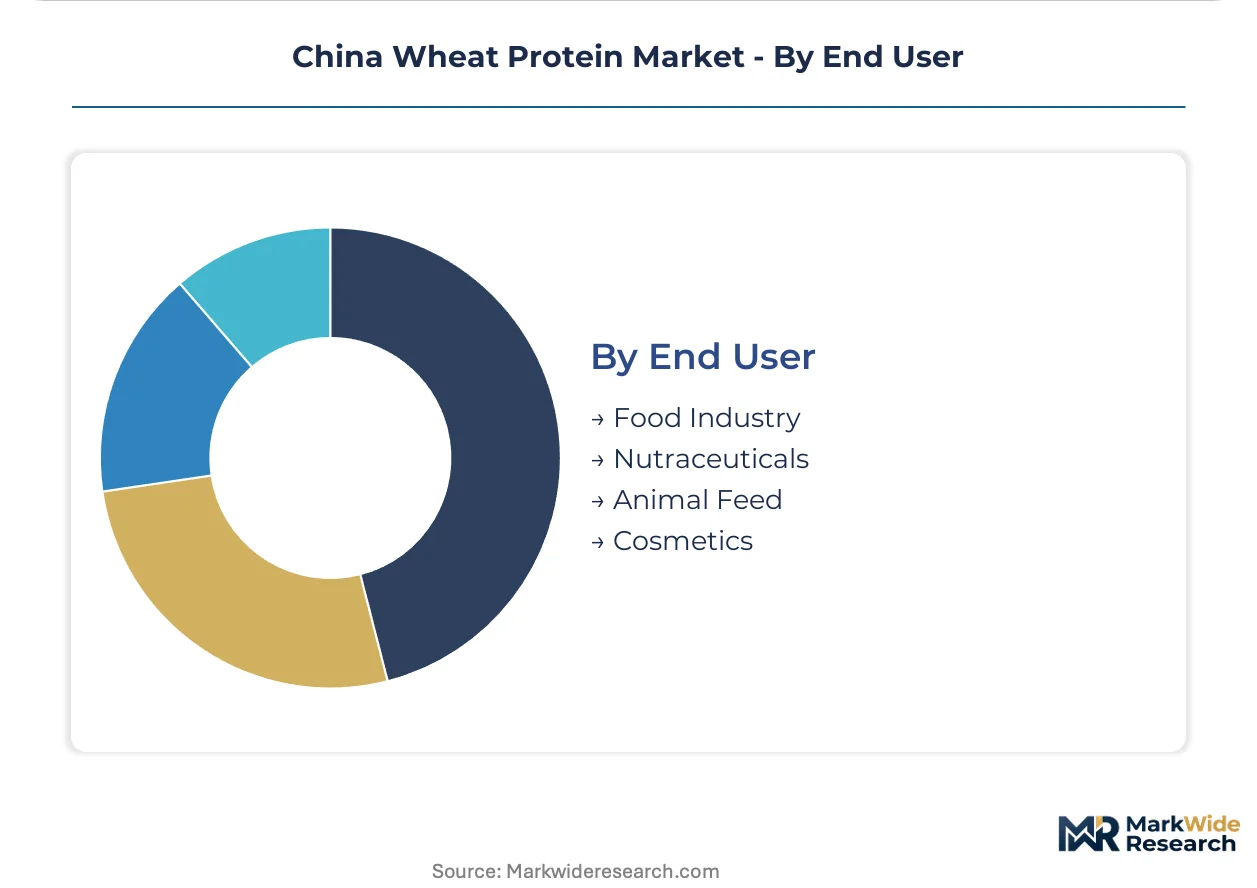
- Food Industry:Bakery chains and processed food manufacturers represent the foundational demand base with established supplier relationships across Shandong's processing belt. GB standards enforcement creates compliance barriers that concentrate procurement among certified domestic producers.
- Cosmetics:Skincare formulators specify low molecular weight hydrolyzed peptides for bioavailability claims in premium product lines.
- Nutraceuticals:Dietary supplement compounders seek isolate purity for protein content labeling.
- Animal Feed:Lower-grade gluten fractions serve pet food and livestock nutrition with reduced specification thresholds.
Food industry anchors procurement volume; cosmetics demonstrates the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery chains and plant-based meat manufacturers concentrate procurement decisions in eastern coastal zones where Shandong's processing infrastructure dominates supply access. Provincial wheat quality grading systems and SAMR enforcement patterns create divergent compliance costs across China's interior.
Shandong Province
Industrial bread manufacturers and noodle processors anchor demand volumes where gluten strength determines production economics. SAMR's GB standards for protein content claims force reformulation investments that favor certified domestic processors over imported concentrates. The provincial milling cluster around Jinan and Qingdao integrates starch processing with isolate recovery, cutting logistics costs for gluten extraction operations.
Jiangsu Province
Cosmetics formulators in Nanjing and Suzhou industrial parks specify low molecular weight hydrolyzed peptides for bioavailability in premium skincare lines. MEE wastewater discharge rules for starch processors reshape production economics for facilities serving coastal manufacturing zones. The Yangtze River Delta concentration of nutraceutical compounders pulls spray-dried isolate volumes into dietary supplement supply chains.
Henan Province
Wheat production in central China lacks downstream isolate infrastructure, creating greenfield processing opportunities for gluten recovery operations. Provincial agricultural authorities coordinate quality grading that upstream affects extraction efficiency for potential facility investments. Zhengzhou's logistics hub position offers distribution advantages for processors targeting western bakery markets.
Guangdong Province
Foodservice operators and retail private labels in the Pearl River Delta negotiate direct procurement contracts for textured wheat protein supply. Plant-based meat brands scaling extrusion capacity pull isolate volumes through channel relationships that displace traditional distributor intermediaries. Shenzhen and Guangzhou cosmetics clusters specify liquid hydrolyzed protein solutions for emulsion system integration.
Beijing-Tianjin-Hebei
National bakery chains headquartered in Beijing negotiate bulk supply contracts requiring consistent protein performance across production runs. SAMR's tightened additive labeling approvals delay new isolate product launches by 12-18 months, affecting market access timelines. Tianjin port facilities sustain imported wheat sourcing networks that supplement domestic grain flows for premium isolate throughput.
China Wheat Protein Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions defined by certification status and vertical scope. The vendor base clusters around Shandong's integrated milling-to-isolate infrastructure and coastal trading networks for imported wheat streams. Three archetypes dominate: provincial integrated processors with captive grain supply, multinational traders anchoring import logistics, and precision fermentation specialists targeting hydrolyzed peptide segments. Competitive moves concentrate on M&A for regional processing assets and strategic partnerships for enzyme engineering capabilities.
Among Shandong-based integrated processors, Shandong Qufeng Food Technology Co. Ltd and Shandong Newnature Biotechnology Co., Ltd. exemplify the provincial cluster archetype with facilities spanning milling to isolate production. Archer Daniels Midland Company occupies a position representing multinational trading networks that sustain premium isolate throughput through imported wheat sourcing. These three entities anchor distinct competitive vectors: provincial integration against global logistics against specialty biotechnology positioning.
| Leading Market Players |
|---|
| Anhui Ante Food Co. Ltd |
| Archer Daniels Midland Company |
| Ezaki Glico Co. Ltd |
| Shandong Qufeng Food Technology Co. Ltd |
| Wilmar International Ltd |
| Shandong Newnature Biotechnology Co., Ltd. |
| Shandong Bailong Chuangyuan Bio-tech Co., Ltd. |
| Shandong Benyue Biological Technology Co., Ltd. |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's milling-to-isolate infrastructure concentrates upstream supply control, directing margin pools toward certified domestic processors capable of meeting SAMR's tightened GB labeling standards. This geographic clustering enables cost-plus contract structures that index wheat input costs to protein content tiers, while enzymatic hydrolysis advances compress extraction economics for lower-grade grain streams.
Pricing Analysis
Cost-plus contracts with wheat futures indexation dominate procurement between Shandong processors and national bakery chains. Three-tier pricing structure across premium isolate, standard gluten, and economy-grade concentrate levels separates SAMR-certified producers from uncertified competitors. Pricing pressure stems from pea and soy protein substitutes achieving comparable texturization at lower input costs for plant-based meat applications. Industrial bakery chains demonstrate highest price sensitivity due to bulk volume procurement, while cosmetics formulators show lowest sensitivity given peptide bioavailability specifications.
Supply Chain Analysis
Contract manufacturing concentration rests with Shandong Qufeng Food Technology Co. Ltd and Shandong Newnature Biotechnology Co., Ltd., which integrate milling through isolate recovery within provincial boundaries. Wheat supply draws from domestic Henan and Shandong production zones, supplemented by Archer Daniels Midland Company's imported grain networks through Tianjin port facilities. Single-source vulnerability concentrates in Shandong's processing belt exposure to localized weather and MEE wastewater enforcement. Distribution runs through direct procurement contracts displacing traditional distributor channels for textured wheat protein supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis and precision fermentation are disrupting extraction cost structures, creating a high-growth window where SAMR certification barriers favor prepared incumbents and specialized entrants.
For Market Incumbents: Harden certification moats by accelerating SAMR GB compliance investments ahead of 12-18 month approval timelines that delay competitor launches. Secure backward integration into Henan wheat sourcing to diversify supply concentration risk away from Shandong weather exposure. Anchor premium isolate throughput through long-term offtake contracts with coastal cosmetics formulators seeking bioavailable peptide supply security. For New Entrants and Emerging Players: Establish a beachhead in Henan Province's greenfield processing corridor where wheat production lacks downstream isolate infrastructure and land costs undercut Shandong facility economics. Target hydrolyzed wheat protein for cosmetics applications where specification escalation outpaces commodity gluten commoditization. Lead with precision fermentation capabilities sourced from coastal biotech hubs to bypass legacy centrifugal equipment retrofit requirements. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive Shandong milling assets and SAMR-certified isolate production. The five-to-ten year viability window favors processors investing in closed-loop water recovery systems aligned with MEE dual carbon eligibility. Watch enzyme engineering talent migration from coastal biotech clusters to provincial processing facilities as the inflection signal for competitive capability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Henan Wheat Sourcing | Diversifies supply concentration risk while capturing upstream margin from central China's production belt. |
| Precision Fermentation Capacity Buildout | Enables ambient-temperature peptide extraction that undercuts acid hydrolysis costs for cosmetics applications. |
| SAMR GB Certification Fast-Track | Creates 12-18 month regulatory moat against imported concentrate competitors facing extended compliance reviews. |
| Closed-Loop Water Recovery Investment | Aligns with MEE discharge rules while generating carbon credit eligibility for dual carbon compliance. |
| Direct Procurement Channel Establishment | Displaces distributor intermediaries for textured wheat protein supply to plant-based meat brands scaling extrusion. |
Study Parameters
Cross-validation between primary interviews with wheat protein plant managers, SAMR regulatory affairs leads, bakery chain procurement officers, and cosmetics formulators anchors the qualitative findings against secondary validation through customs trade data, GB standards filings, and SEC disclosures from multinational grain traders. Bottom-up triangulation across Shandong provincial production statistics and top-down reconciliation with national wheat processing capacity estimates ensures dimensional consistency.
Calibration against historical protein content claim enforcement patterns and enzymatic hydrolysis adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, form factor, and provincial regulatory cluster. CAGRs derive from elasticity-adjusted demand projections for plant-based meat analogues and cosmetics peptide penetration, with wheat quality grading volatility and MEE enforcement intensity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in wheat commodity price volatility and RMB exchange rate movements would shift the trajectory of import-dependent premium isolate economics. Forecasts reflect documented assumptions regarding SAMR approval timeline stability and precision fermentation scale-up rates. Quarterly review of provincial agricultural quality grading announcements and MEE wastewater discharge enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Egypt Rice Market
Grains
White Rice Flour Market
Grains
North America Wheat Protein Market
Grains
Grain Silos and Storage System Market
Grains
Global Grain Analysis Market
Grains
Paraguay Grains Market
Grains
Low Fat Rice Market
Grains
Colombia Grains Market
Grains
Rolled Oats Market
Grains
Corn Market
Grains
Asia-Pacific Rice Market
Grains
Millets Market
Grains
Africa Wheat Protein Market
Grains
White Beans Market
Grains
Grain Storage Systems Market
Grains
Cameroon Grains Market