
 Potassium Tetrafluoroborate Market | 2026-2036
Potassium Tetrafluoroborate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Tetrafluoroborate Market Intelligence
Fluoroborate-based flux chemistry is reconfiguring how printed circuit board assemblies achieve solder joint reliability under lead-free mandates. Solvay S.A. leverages its integrated fluorine value chain to sustain supply security for Asian electronics fabricators. Stella Chemifa Corporation anchors high-purity crystal production for Japanese semiconductor chemical distributors. Morita Chemical Industries differentiates through specialized granule formulations tailored to automated soldering lines.
Potassium tetrafluoroborate (KBF₄) is an inorganic salt synthesized via neutralization of hydrofluoric acid with potassium carbonate, yielding a white crystalline solid with melting point near 530°C that functions primarily as a fluxing agent, metallurgical additive, and fluorine source in specialty chemical synthesis. Powder grades dominate volume throughput in mass soldering operations where dissolution kinetics favor fine particle distribution, while solution formats command premium positioning in precision electronics plating baths where concentration consistency governs deposit quality. The ceramics application segment is maturing around established enamel frit formulations, whereas metal surface treatment represents the fastest-expanding demand pool as aluminum foundries adopt KBF₄-containing grain refiners for automotive lightweighting programs.
REACH registration requirements in Europe and EPA toxic substance reporting obligations in the United States constrain market access for producers lacking documented environmental health profiles, while China's GB standards on fluoride emissions shape manufacturing investment decisions. ECHA's ongoing scrutiny of boron compounds under SVHC candidate listing processes creates compliance uncertainty that favors vertically integrated suppliers with in-house regulatory affairs capabilities. Stakeholders must monitor evolving fluorine chemical restrictions across multiple jurisdictions while assessing captive versus merchant supply strategies for critical electronics-grade material.
Market Dynamics
Electronics-grade purity specifications are tightening procurement standards across Asian semiconductor fabrication corridors, forcing flux suppliers to revalidate synthesis protocols and analytical certification workflows.
Growth Catalysts
- MEE emissions enforcement:China's Ministry of Ecology and Environment is accelerating capital flows toward closed-loop fluoride recovery systems that reduce waste treatment liabilities for KBF₄ producers.
- Lead-free solder mandates:Electronics assemblers in South Korea and Taiwan are expanding fluoroborate flux consumption to achieve RoHS-compliant joint reliability under thermal cycling stress.
- Automotive aluminum grain refinement:Foundries serving electric vehicle chassis programs are integrating KBF₄-containing master alloys to control cast microstructure during high-pressure die casting.
Market Restraints
- Hydrofluoric acid price volatility:Feedstock cost swings tied to Chinese fluorspar export quotas compress margin predictability for merchant producers lacking backward integration into acid production.
- East Asian supply concentration:Over two-thirds of electronics-grade crystal output originates from Japanese and South Korean chemical specialists, creating single-source vulnerability for European plating chemical distributors.
- REACH SVHC listing trajectory:ECHA's ongoing boron compound evaluation threatens additional downstream notification obligations that would lengthen qualification timelines for EU market entry.
Strategic Opportunities
- Indian electronics manufacturing zones:PLI scheme incentives for semiconductor and component assembly are creating first-mover advantage for flux suppliers establishing local blending operations under BIS certification pathways.
- Solid-state battery electrolyte precursors:KBF₄-derived fluorine chemistry is emerging as a processing aid in sulfide electrolyte synthesis for next-generation lithium-metal cell architectures.
- Direct-to-fabricator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume soldering operations seeking just-in-time powder delivery.
Industry Challenges
- Analytical chemist scarcity:ICP-MS and ion chromatography expertise for trace boron and fluoride quantification is concentrating at contract laboratories, extending internal QC validation timelines for smaller producers.
- Multi-jurisdiction dossier maintenance:Simultaneous compliance with EPA TSCA reporting, REACH registration, and China's new chemical notification requirements strains regulatory affairs staffing at sub-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Tetrafluoroborate Market |
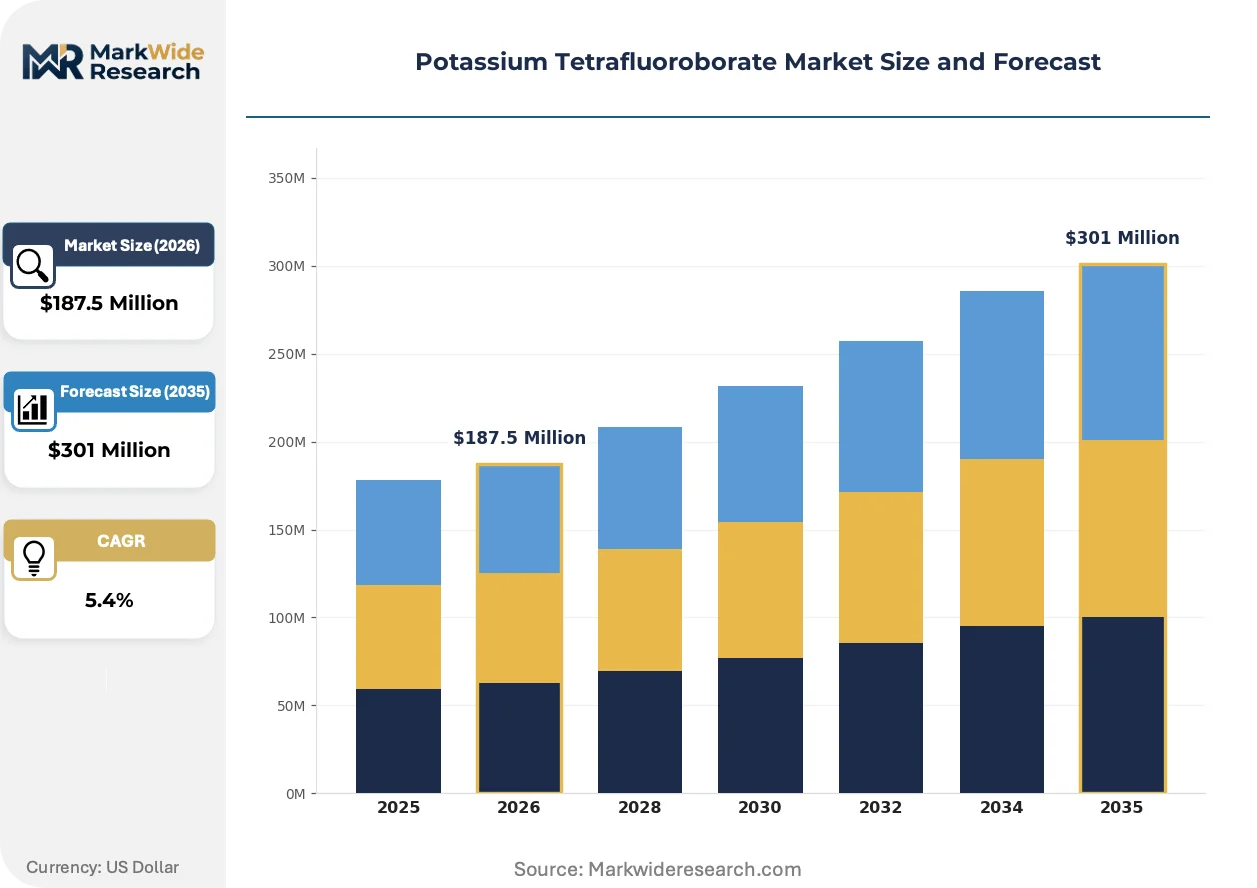
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $301 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Crystals Application: Electronics, Ceramics, Metal Surface Treatment, Fluorine Chemistry End User: Chemical Manufacturers, Electronics Industry, Research Institutions, Educational Bodies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | American Elements, Solvay S.A., Morita Chemical Industries, Honeywell Fine Chemicals, AMG Aluminum, Stella Chemifa Corporation, Derivados del Flúor, Foshan Nanhai Fluoride Chemical Co. Ltd., Hunan Merits New Materials Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Tetrafluoroborate Market Strategic Shifts & Innovations
Process intensification in fluoride salt synthesis is compressing capital requirements while analytical instrumentation advances are tightening impurity detection thresholds beyond legacy specification limits.
Continuous flow reactor technology for KBF₄ crystallization is rendering obsolete batch kettle operations that dominated twentieth-century production economics. Japanese chemical specialists have piloted modular flow systems achieving narrower particle size distribution without mechanical milling. The structural consequence is a capability wedge that batch-dependent merchant producers cannot replicate without full process revalidation.
China's GB standards on inorganic fluoride emissions are forcing acid neutralization plants to install scrubber-integrated crystallizers that recover product from vent streams. MEE inspection protocols now mandate real-time fluoride monitoring with data transmission to provincial environmental databases. Electronics-grade producers in Jiangsu and Zhejiang are responding by segregating high-purity lines from industrial-grade operations to prevent cross-contamination from upgraded environmental controls.
Consolidated procurement desks at multinational electronics assemblers are compressing supplier panels from five or six regional distributors to two or three integrated chemical service providers. Tier-one soldering material vendors are absorbing specification-setting authority previously held by individual fabrication sites. South Korean semiconductor packaging houses are driving this concentration through centralized global contracts that bundle KBF₄ with activator packages and technical service support.
Potassium Tetrafluoroborate Market Segmentation
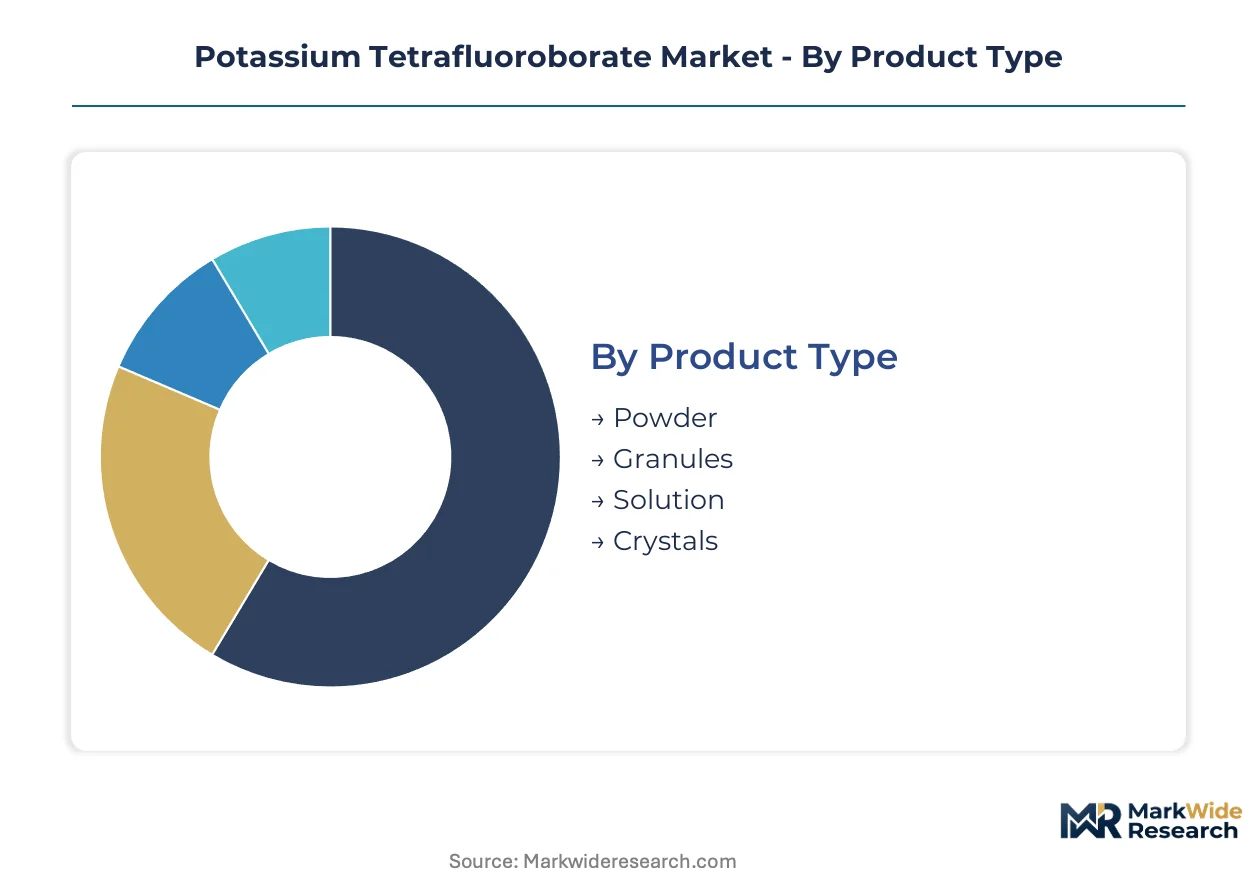
Potassium tetrafluoroborate procurement cycles vary dramatically across physical formats and end-use applications. Electronics-grade specifications compress inventory turns to weeks, while industrial ceramics formulations sustain month-long holding patterns. Understanding these velocity differentials enables suppliers to align working capital deployment with segment-specific demand rhythms.
Product Type:
Powder grades turn inventory fastest due to mass soldering throughput, while crystal formats sit longest awaiting semiconductor qualification cycles.
- Powder:Fine particle distribution below 100 microns maximizes dissolution kinetics in wave soldering baths. South Korean contract electronics manufacturers consume powder volumes through automated flux dispensing systems serving lead-free assembly lines.
- Solution:Aqueous formulations at standardized concentrations eliminate on-site dissolution variability for precision plating operations. Japanese semiconductor fabrication corridors specify solution formats to maintain bath chemistry consistency across multi-tool lines.
- Granules:Free-flowing agglomerates suit manual soldering stations and small-batch metallurgical applications.
- Crystals:High-purity monocrystalline forms command extended qualification timelines for analytical reagent and specialty fluorine source applications.
Powder dominates installed base. Solution is where expansion concentrates.
Application:
Cost tier stratification separates commodity flux consumption from premium plating chemistry, with metal surface treatment commanding intermediate positioning.
- Electronics:Flux formulations for printed circuit board assembly and semiconductor packaging represent the primary demand anchor. RoHS compliance mandates across South Korea and Taiwan are displacing legacy halide activators with fluoroborate-based alternatives.
- Metal Surface Treatment:Aluminum grain refinement in automotive die casting integrates KBF₄-containing master alloys for microstructure control. Electric vehicle chassis programs in China are expanding foundry uptake of these formulations.
- Ceramics:Enamel frit production for sanitary ware and architectural coatings maintains steady offtake through established formulation lock-ins.
- Fluorine Chemistry:Specialty synthesis applications including boron trifluoride generation and fluorinating agent production serve niche pharmaceutical and agrochemical intermediates.
Electronics commands revenue concentration. Metal surface treatment is climbing the fastest.
End User:
Customer type determines specification stringency, with chemical manufacturers facing loosest purity thresholds and electronics industry buyers enforcing tightest analytical certification.
- Chemical Manufacturers:Merchant producers of downstream fluorine compounds purchase industrial-grade material in bulk quantities. Chinese acid neutralization plants supply this tier through spot market arrangements.
- Electronics Industry:Tier-one soldering material vendors and semiconductor packaging houses drive electronics-grade specifications. Centralized procurement desks at multinational assemblers are compressing supplier panels to integrated service providers.
- Research Institutions:National laboratories and university chemistry departments consume analytical-grade crystals for method development and reference standard preparation.
- Educational Bodies:Undergraduate teaching laboratories represent fragmented, price-sensitive demand for demonstration-scale quantities.
Chemical manufacturers anchor volume throughput. Electronics industry is where margin expansion concentrates.
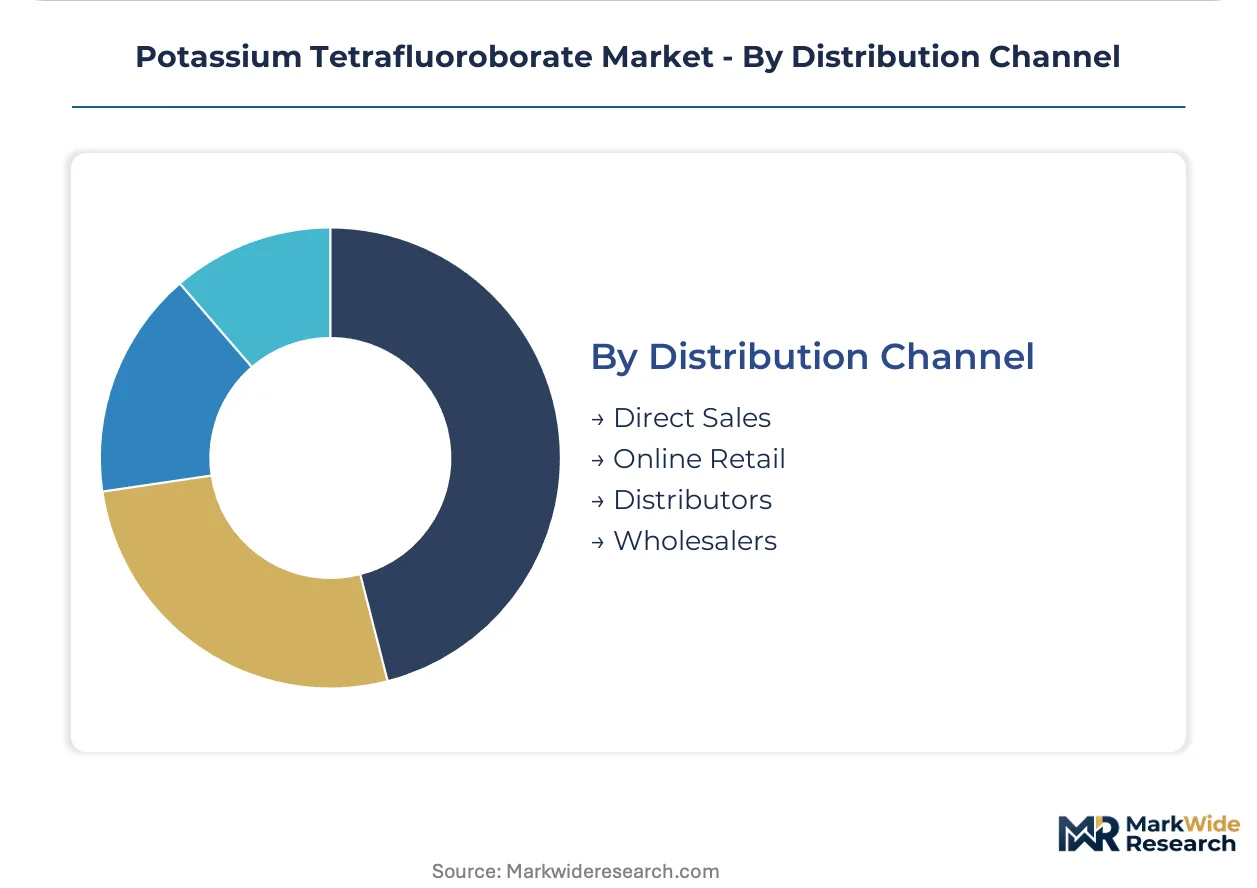
Distribution Channel:
Supply chain configuration separates direct technical service relationships from transactional spot purchasing, with digital channels emerging between these poles.
- Direct Sales:Long-term contracts bundle KBF₄ with activator packages, analytical certification, and on-site technical support. South Korean semiconductor packaging houses favor this channel for global contract standardization.
- Distributors:Regional chemical distributors maintain inventory buffers for mid-volume soldering operations and smaller plating shops. European plating chemical distributors face single-source vulnerability due to East Asian supply concentration.
- Online Retail:Specialty chemical platforms are disintermediating traditional networks for just-in-time powder delivery to mid-tier fabricators.
- Wholesalers:Bulk commodity handlers serve industrial ceramics and metallurgical applications with minimal technical service overlay.
Direct sales dominates premium tier positioning. Online retail is gaining share fastest among mid-volume accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers dominate export flows to South Korean semiconductor packaging corridors and Japanese electronics chemical distributors, creating a triangular trade pattern that concentrates high-purity grade availability in East Asian fabrication clusters.
China
Jiangsu and Zhejiang provinces host acid neutralization plants supplying industrial-grade material to domestic aluminum foundries serving electric vehicle programs. MEE inspection protocols mandate real-time fluoride emissions monitoring with data transmission to provincial environmental databases. Electronics-grade producers in these coastal clusters are segregating high-purity lines from industrial-grade operations to prevent cross-contamination.
Japan
Japanese semiconductor chemical distributors source monocrystalline formats for analytical reagent and specialty fluorine synthesis applications. METI oversight of fluorine chemical handling shapes manufacturing investment decisions and facility certification requirements. The Kansai industrial corridor around Osaka anchors high-purity crystal production for regional electronics supply chains.
South Korea
Semiconductor packaging houses in the Seoul Capital Area drive fluoroborate flux consumption for RoHS-compliant printed circuit board assembly. Centralized procurement desks at multinational assemblers are compressing supplier panels to integrated chemical service providers. The Busan-Ulsan corridor supports ancillary plating chemical blending operations serving display panel manufacturers.
United States
American plating chemical distributors face supply vulnerability due to East Asian concentration of electronics-grade crystal output. EPA toxic substance reporting obligations under TSCA constrain market access for producers lacking documented environmental health profiles. The Pacific Northwest hosts research institutions consuming analytical-grade crystals for method development and reference standard preparation.
Germany
German automotive suppliers integrate KBF₄-containing master alloys for aluminum grain refinement in electric vehicle chassis die casting. ECHA scrutiny of boron compounds under SVHC candidate listing processes creates compliance uncertainty favoring vertically integrated suppliers with in-house regulatory affairs capabilities. The North Rhine-Westphalia industrial basin concentrates foundry demand from OEM lightweighting programs.
Potassium Tetrafluoroborate Market Key Industry Players
On the supply side, the industry is bifurcated between integrated fluorine value chain operators and merchant neutralization specialists lacking backward integration into acid production. Japanese and Belgian chemical conglomerates anchor the premium tier through captive hydrofluoric acid supply, while Chinese provincial producers compete on industrial-grade spot pricing. Three archetypes dominate: integrated fluorine majors with acid-to-salt vertical control, regional neutralization specialists serving commodity metallurgical demand, and electronics-grade pure-plays with crystallization expertise. Capacity expansion in closed-loop fluoride recovery systems and strategic partnerships for semiconductor qualification support represent the dominant competitive vectors.
Among integrated fluorine majors, Solvay S.A. exemplifies the premium-tier archetype through its Belgian-based fluorine value chain, while Stella Chemifa Corporation occupies a parallel position within the Japanese market structure. Morita Chemical Industries represents the specialized formulation segment with differentiated granule products. These three names anchor the competitive topology without exhausting the vendor landscape.
| Leading Market Players |
|---|
| American Elements |
| Solvay S.A. |
| Morita Chemical Industries |
| Honeywell Fine Chemicals |
| AMG Aluminum |
| Stella Chemifa Corporation |
| Derivados del Flúor |
| Foshan Nanhai Fluoride Chemical Co. Ltd. |
| Hunan Merits New Materials Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese acid neutralization plants is compressing spot pricing for industrial-grade material while simultaneously constraining electronics-grade premiums, as MEE-mandated environmental upgrades force producers to cross-subsidize high-purity line investments through commodity volume throughput.
Pricing Analysis
Batch-process pricing for legacy kettle operations diverges sharply from continuous-flow reactor premiums, with the technology-generation gap widening as Japanese crystallization specialists achieve narrower particle distributions without mechanical milling. Three-tier pricing structure across electronics-grade, industrial-grade, and reagent-grade levels anchors the market, with differentiation driven by ICP-MS certification thresholds and volume scale commitments. Cost compression in industrial-grade tiers is intensifying because hydrofluoric acid feedstock volatility erodes merchant producer margins lacking captive acid supply. Chemical manufacturers purchasing bulk spot quantities exhibit highest price sensitivity, while semiconductor packaging houses enforcing centralized global contracts show lowest elasticity due to qualification lock-in effects.
Supply Chain Analysis
Export control regimes on fluorine chemical processing equipment limit Western producers' access to continuous-flow crystallization technology, reinforcing East Asian supply concentration. China, Japan, and South Korea anchor global electronics-grade output, with the supply base drawing from hydrofluoric acid, potassium carbonate, and specialized filtration media inputs. Single-source vulnerability concentrates risk for European plating chemical distributors dependent on Japanese and South Korean crystal specialists. Distribution runs through direct technical service relationships for tier-one soldering material vendors, while regional distributors buffer mid-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
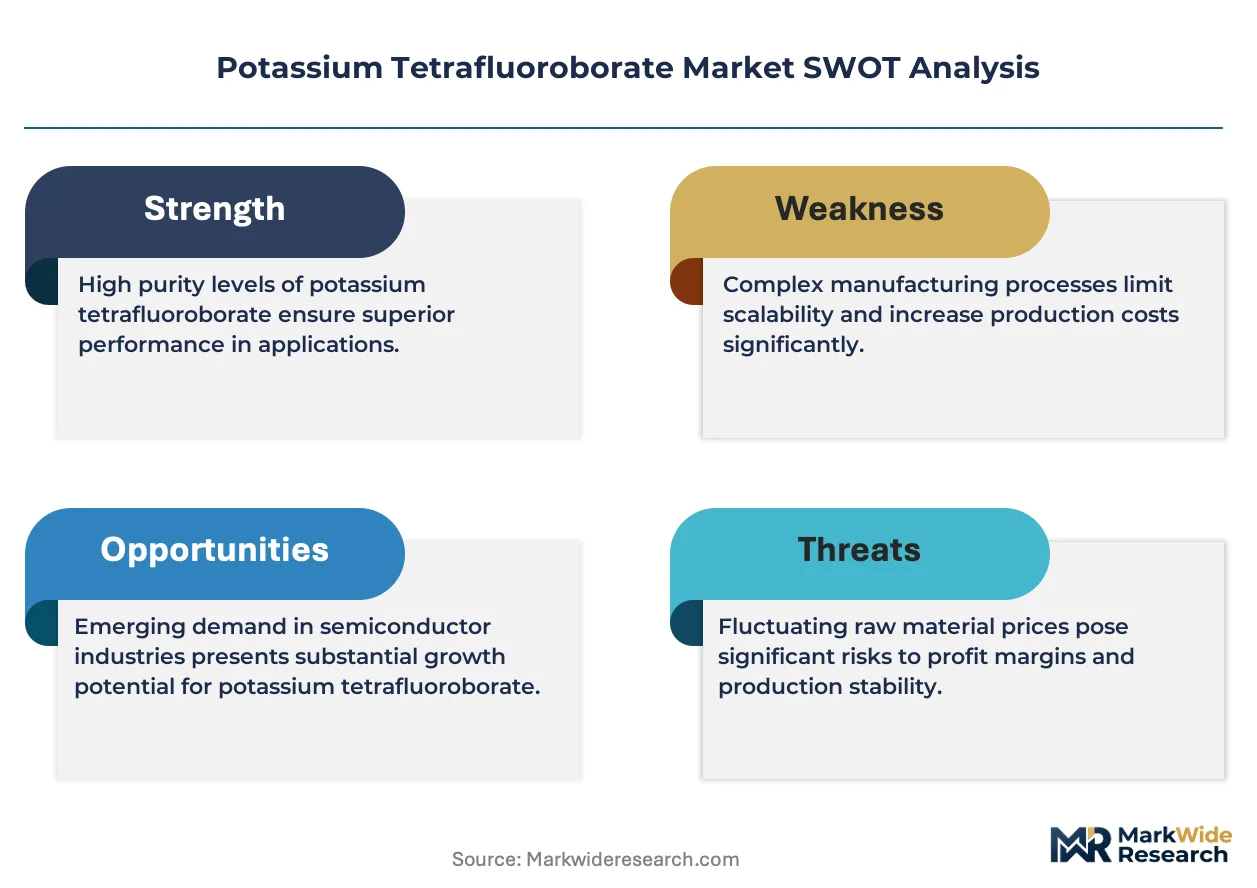
Fragmentation across grade tiers and geographic regulatory clusters creates multiple niche entry points, as divergent MEE, REACH, and EPA compliance timelines prevent scale players from dominating all segments simultaneously.
For Market Incumbents: Harden qualification moats around electronics-grade specifications by investing in closed-loop fluoride recovery systems that MEE protocols now mandate, while simultaneously securing captive hydrofluoric acid supply to defend against feedstock volatility eroding merchant competitors. Consolidate distributor relationships before digital platforms disintermediate regional chemical networks serving mid-volume soldering operations. For New Entrants and Emerging Players: Indian electronics manufacturing zones under PLI scheme incentives represent the most penetrable entry point for flux suppliers establishing local blending operations, as BIS certification pathways remain less congested than East Asian qualification queues. Solid-state battery electrolyte precursor applications offer a second white-space target, with KBF₄-derived fluorine chemistry emerging as a processing aid in sulfide electrolyte synthesis. A technical service bundling go-to-market angle differentiates against commodity spot sellers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop environmental control installations, favoring acquisition targets with pre-certified MEE-compliant facilities over greenfield construction. Electronics-grade pure-plays with crystallization expertise and established semiconductor packaging house relationships present the strongest long-term viability profile. The signal to watch is qualification timeline compression at South Korean centralized procurement desks, which would indicate consolidation momentum accelerating beyond organic growth capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrofluoric Acid | Captive acid supply insulates margin stability against Chinese fluorspar export quota volatility. |
| Closed-Loop Fluoride Recovery Installation | MEE-mandated scrubber-integrated crystallizers transform environmental compliance into product recovery economics. |
| Semiconductor Qualification Partnership | Direct technical service relationships with Seoul Capital Area packaging houses secure multi-year offtake commitments. |
| Continuous Flow Reactor Conversion | Modular flow systems achieve particle size distribution control that batch kettle operations cannot replicate. |
| Digital Platform Channel Entry | Specialty chemical platforms disintermediate traditional distributors for just-in-time powder delivery to mid-tier fabricators. |
Research Approach
A standing panel of fluorine chemical plant managers, electronics industry procurement leads, semiconductor packaging technical directors, and plating chemical distribution channel partners provided ongoing calibration across the study period. Primary interview intelligence combined with customs trade data, SEC filings from integrated chemical conglomerates, MEE environmental disclosure databases, and REACH registration dossiers. Bottom-up crystallization capacity estimates triangulated against top-down flux consumption modeling across South Korean and Taiwanese assembly corridors.
Scenario-bracketing around MEE enforcement intensity and REACH SVHC listing probability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include physical format tier, application end-use, purity certification level, and regional production hub cluster. CAGRs derived from elasticity-adjusted demand curves incorporating RoHS compliance penetration rates and electric vehicle aluminum casting intensity assumptions.
Macroeconomic conditions sit as an overlay; deviation in Chinese manufacturing PMI, fluorspar export quota allocations, or semiconductor capital expenditure cycles would shift the trajectory. Material shifts in ECHA boron compound regulatory classification or MEE real-time monitoring protocol expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Functional Composites Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Alkali-Silica Reaction Mitigation Functional Agents Market
Functional Materials
Thin Film Materials Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Smart Material Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Thermal Interface Pads and Material Market