
 Alkali-Silica Reaction Mitigation Functional Agents Market | 2026-2036
Alkali-Silica Reaction Mitigation Functional Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Alkali-Silica Reaction Mitigation Functional Agents Market Insights
Asset-light leasing models for concrete additive production equipment is reconfiguring competitive entry barriers, allowing regional blenders to challenge established suppliers. Sika AG leverages its global distribution network to sustain specification-grade supply chains across multiple continents. BASF SE anchors its position through backward integration into lithium compound sourcing. Heidelberg Materials competes by controlling captive fly ash streams from its cement operations.
Alkali-silica reaction mitigation functional agents are chemical or mineral admixtures, typically containing lithium salts, pozzolanic materials, or calcium nitrate at dosages of 3-10% by cement weight, that disrupt gel expansion mechanisms in concrete pore structures. Their primary industrial purpose is to extend structural service life in high-alkali environments prone to aggregate reactivity. Lithium compounds occupy the premium tier due to their direct ion-exchange mechanism and predictable performance in critical infrastructure. Pozzolanic materials and fly ash represent the volume-driven segments where margin pools depend on proximity to coal-fired power generation or cement kiln dust sources. Silica fume leads in marine structures and tunnel lining applications where low permeability requirements dominate specification sheets.
Federal Highway Administration guidelines and ASTM C1567 standard test methods govern product approval for US transportation infrastructure, creating a two-tier market between certified and uncertified suppliers. The EPA's coal ash disposal regulations influence fly ash availability and pricing dynamics for pozzolanic blenders. EN 206 and national annexes across European member states establish parallel conformity routes that US exporters must navigate for cross-border project participation. Stakeholders must monitor how emerging low-carbon concrete mandates reshape the relative economics of mineral versus chemical mitigation strategies.
Market Dynamics
Federal infrastructure spending in the United States is compressing project timelines for ASR mitigation, forcing transportation agencies to pre-qualify larger supplier pools before bid release. This demand surge is restructuring how lithium compound and pozzolanic material producers allocate production capacity between spot markets and specification-grade contracts.
Growth Catalysts
- FHWA Bridge Investment Guidelines:Federal Highway Administration funding priorities mandate ASR-resistant concrete for structures exceeding fifty-year design life, creating specification-grade demand in bridge deck and substructure applications.
- Coal Ash Beneficiation:Advanced classification technologies are converting previously landfilled fly ash into ASTM C618-compliant pozzolans, expanding mineral admixture supply for ready-mix producers.
- Texas:The state's expansive reactive aggregate deposits and accelerated highway construction program generate concentrated demand for lithium nitrate solutions in concrete pavement overlays.
Market Restraints
- Lithium Carbonate Volatility:Battery sector competition for lithium compounds creates input cost instability that chemical admixture formulators cannot fully pass through in fixed-price infrastructure contracts.
- Appalachian Fly Ash Concentration:Coal-fired generation retirements in the Ohio River Valley are constraining Class F fly ash availability for eastern US concrete producers.
- ASTM C1567 Duration:The sixteen-week accelerated mortar bar test timeline delays product qualification, freezing out innovative formulations from fast-track federal projects.
Strategic Opportunities
- California Low-Carbon Concrete Mandates:The state's Buy Clean program incentivizes supplementary cementitious materials over lithium salts, creating volume opportunities for pozzolanic blenders with verified environmental product declarations.
- Marine Infrastructure:Port expansion projects from Savannah to Long Beach specify silica fume-lithium hybrid systems for chloride exposure resistance, opening premium formulation segments.
- Equipment Leasing:Asset-light production technology is enabling regional concrete additive blenders to enter specification-grade supply chains without capital-intensive fixed plant investment.
Industry Challenges
- Petrographic Analysis Capacity:Qualified aggregate reactivity assessors are concentrated in a handful of commercial laboratories, creating bottlenecks for project-level ASR risk evaluation.
- Multi-Admixture Compatibility:Lithium compounds require precise dosing coordination with superplasticizers and corrosion inhibitors, complicating quality control for field-mixed concrete operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkali-Silica Reaction Mitigation Functional Agents Market |
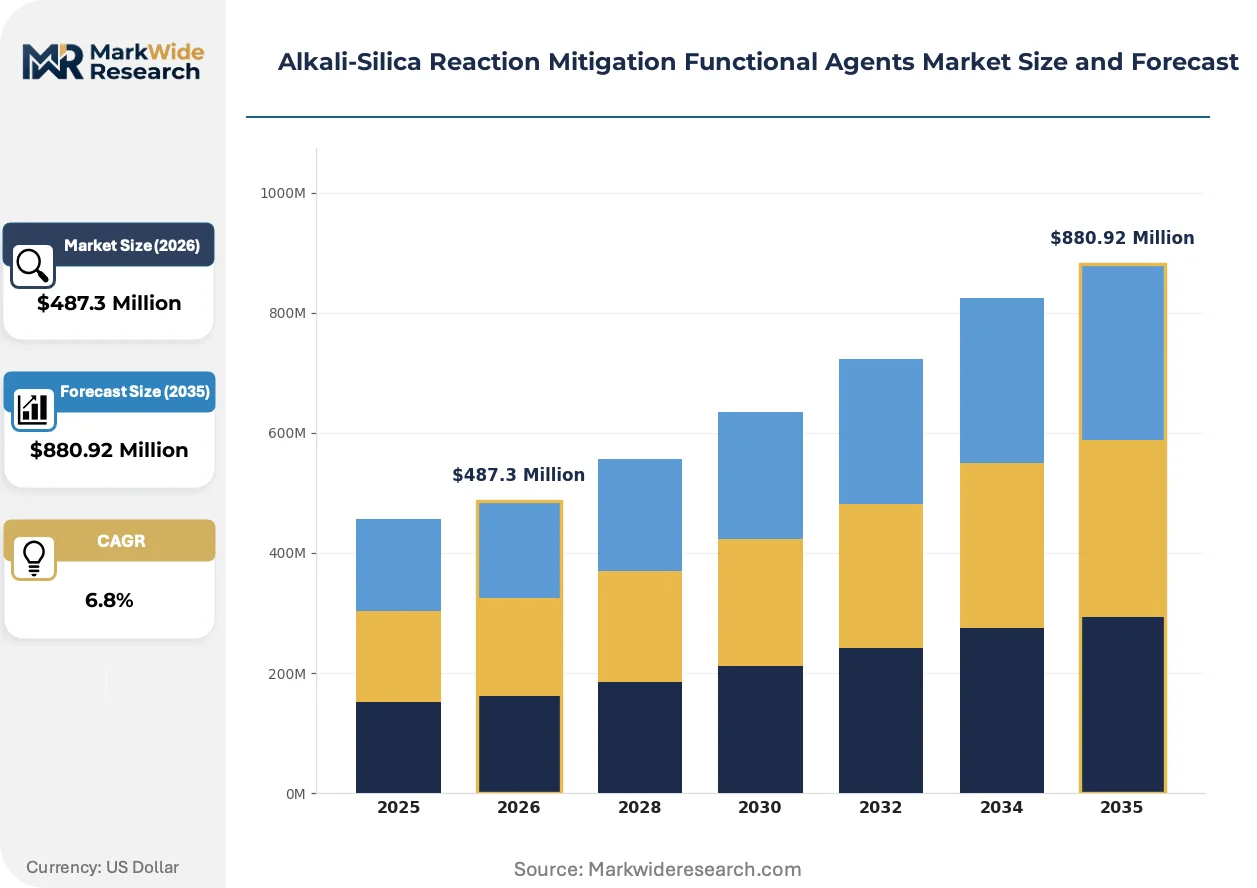
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Compounds, Calcium Nitrate, Pozzolanic Materials, Silica Fume, Fly Ash Application: Concrete Durability Enhancement, Precast Concrete, Bridge Construction, Tunnel Lining, Marine Structures End User: Construction Contractors, Infrastructure Developers, Precast Manufacturers, Municipal Agencies, Engineering Consultants Deployment Method: Admixture, Surface Treatment, Coating, Integral Mixing, Post-Treatment |
| Companies Covered | Sika AG, BASF SE, Saint-Gobain, Fosroc International, Euclid Chemical, W. R. Grace & Co., Heidelberg Materials, Holcim, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkali-Silica Reaction Mitigation Functional Agents Market Trends and Innovations
Specification-grade concrete production is fragmenting between centralized batch plant operations and project-site additive injection systems. This operational divergence is forcing suppliers to develop dual-format product lines with divergent packaging and logistics requirements.
Lithium-silicate hybrid admixtures are collapsing the performance gap between premium chemical mitigation and volume mineral approaches. State DOTs in Arizona and Nevada are specifying these systems for desert exposure conditions where thermal cycling accelerates gel formation. The technology is compressing price differentiation between historically separate product tiers.
EPA's coal ash disposal regulations under the Resource Conservation and Recovery Act are reclassifying beneficial use pathways for fly ash. Concrete producers must now document contaminant testing for each ash source, increasing administrative burden but securing long-term supply legitimacy. Beneficiation technology providers are capturing margin from this compliance-driven demand.
Transportation agency procurement offices are unbundling ASR mitigation from general concrete supply contracts. Florida and Illinois DOTs now require separate admixture vendor qualification, enabling direct supplier relationships that bypass ready-mix intermediaries. This channel restructuring is most advanced in states with centralized material testing laboratories.
Alkali-Silica Reaction Mitigation Functional Agents Market Segmentation
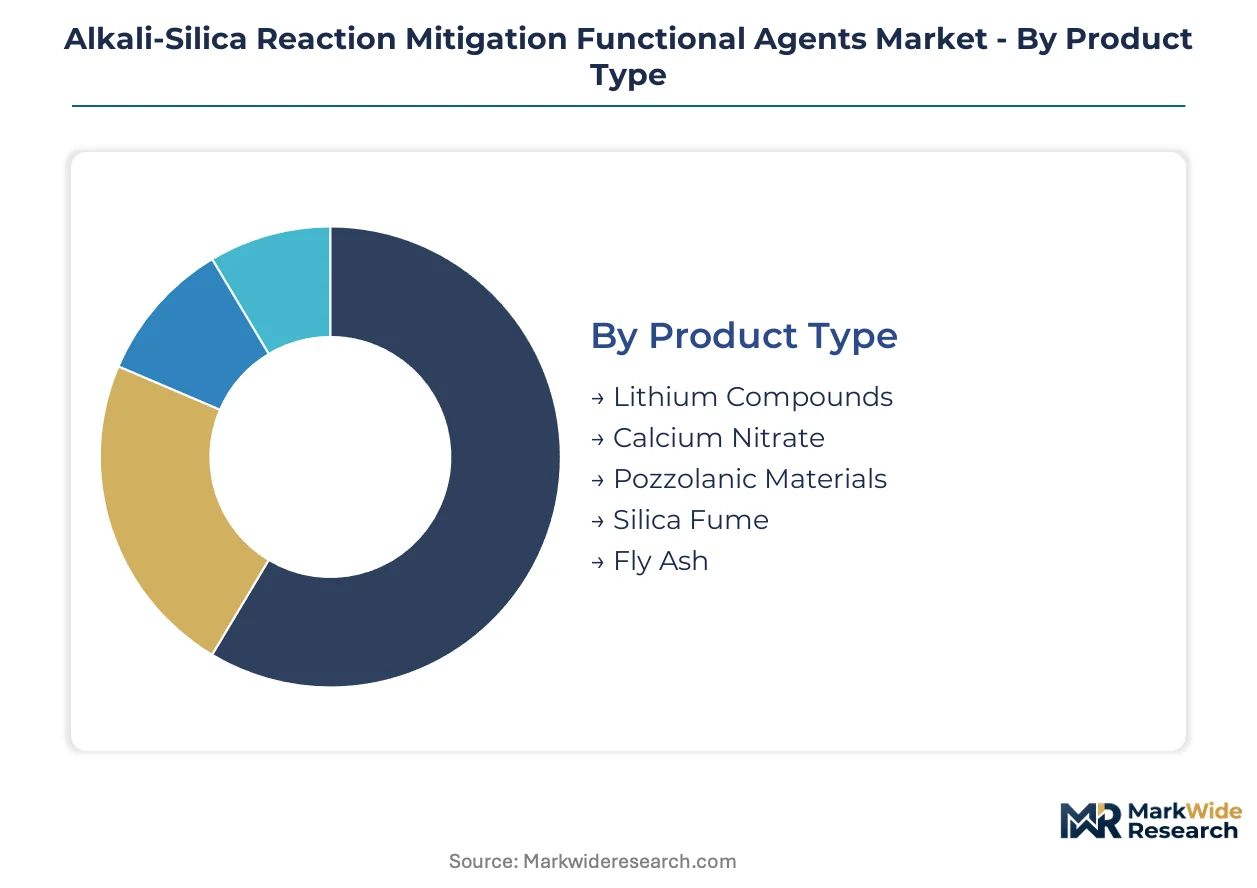
Segmentation in the ASR mitigation market reveals how product chemistry, application severity, and procurement authority reshape competitive boundaries. Suppliers must align formulation portfolios with the specific qualification pathways that each segment demands.
Product Type:
Mature mineral admixtures dominate volume flows while emerging chemical systems capture specification premiums.
- Lithium Compounds:Lithium nitrate and lithium carbonate solutions operate through direct ion-exchange mechanisms that disrupt silica gel expansion at the molecular level. Bridge construction across the United States concentrates demand as FHWA guidelines mandate these compounds for structures exceeding fifty-year design life, though battery sector competition for lithium feedstock creates input cost volatility that formulators struggle to pass through in fixed-price infrastructure contracts.
- Pozzolanic Materials:Natural pozzolans and calcined clays provide aluminosilicate reactivity that consumes portlandite and reduces pore solution alkalinity. Texas highway construction programs generate concentrated procurement volumes where expansive reactive aggregate deposits make pozzolanic blending economically essential, yet beneficiation technology investments are required to achieve consistent ASTM C618 compliance.
- Fly Ash:Coal combustion byproduct with Class F and Class C designations depending on calcium content.
- Silica Fume:Microsilica from ferrosilicon production, specified for low permeability in aggressive exposure conditions.
- Calcium Nitrate:Nitrate-based crystallization accelerator with secondary ASR suppression properties.
Fly Ash handles the majority of throughput; Lithium Compounds is the fastest mover on share.
Application:
Application segmentation tracks how exposure severity and asset criticality stratify product selection criteria.
- Bridge Construction:Decks, substructures, and precast elements face combined ASR, freeze-thaw, and chloride exposure requiring multi-mechanism protection. Federal infrastructure spending in the United States is compressing project timelines and forcing transportation agencies to pre-qualify larger supplier pools before bid release, restructuring how producers allocate capacity between spot markets and specification-grade contracts.
- Marine Structures:Piles, seawalls, and port facilities demand simultaneous ASR mitigation and chloride ingress resistance. Port expansion projects from Savannah to Long Beach specify silica fume-lithium hybrid systems, opening premium formulation segments where low permeability requirements dominate specification sheets.
- Tunnel Lining:Segmental concrete linings in groundwater-bearing formations.
- Precast Concrete:Factory-cured elements with controlled mixing and curing environments.
- Concrete Durability Enhancement:General-purpose ASR protection for buildings and pavements.
Bridge Construction commands the largest specification-grade volume; Marine Structures is expanding most quickly as port modernization accelerates.
End User:
End user segmentation exposes how procurement authority concentration reshapes channel economics.
- Infrastructure Developers:Public-private partnership entities and state transportation agencies with centralized material testing laboratories. Florida and Illinois DOTs now require separate admixture vendor qualification, enabling direct supplier relationships that bypass ready-mix intermediaries.
- Construction Contractors:Field operations managing multi-admixture compatibility challenges where lithium compounds require precise dosing coordination with superplasticizers and corrosion inhibitors.
- Precast Manufacturers:Controlled-environment producers with captive batching systems.
- Municipal Agencies:City and county public works departments with limited in-house testing capacity.
- Engineering Consultants:Specification writers and petrographic analysis coordinators.
Infrastructure Developers concentrate procurement authority; Construction Contractors represent the broadest addressable base.
Deployment Method:
Deployment segmentation captures the operational divergence between centralized production and distributed field application.
- Admixture:Liquid or powdered products dosed at the ready-mix plant, the dominant format for specification-grade concrete production.
- Integral Mixing:Dry-blended powders incorporated during cement manufacturing, capturing economies of scale for large infrastructure programs.
- Surface Treatment:Lithium silicate penetrants applied to hardened concrete for remedial intervention.
- Coating:Barrier systems that limit moisture ingress to slow ASR progression.
- Post-Treatment:Electrochemical or pressure-injection remediation for distressed structures.
Admixture deployment handles the majority of new construction volume; Surface Treatment is gaining share fastest in the repair and rehabilitation segment.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ASR mitigation agents track divergent regulatory maturities and infrastructure investment cycles across major economies. Chemical admixture formulators in Europe and North America supply specification-grade lithium compounds to markets where domestic production capacity remains underdeveloped.
United States
Federal infrastructure spending through the Infrastructure Investment and Jobs Act compresses project timelines for bridge deck rehabilitation across the Interstate Highway System. The Federal Highway Administration mandates ASTM C1567 compliant materials for structures exceeding fifty-year design life. Texas highway construction programs generate concentrated procurement volumes where expansive reactive aggregate deposits in the Hill Country make pozzolanic blending economically essential.
Germany
Autobahn expansion and tunnel modernization projects drive specification-grade demand for low-permeability concrete systems. EN 206 and national annex requirements establish conformity routes that domestic admixture producers must navigate for federal transport contracts. The Rhine-Ruhr industrial corridor concentrates ready-mix production capacity where cement producers integrate captive fly ash streams from regional power generation.
China
High-speed rail extensions and hydropower dam construction create sustained demand for ASR-resistant concrete in alkaline aggregate environments. GB standards and Ministry of Ecology and Environment regulations govern coal ash utilization in construction materials. The Yangtze River Delta manufacturing cluster hosts blending operations that serve port expansion projects from Shanghai to Ningbo-Zhoushan.
India
National highway development through the Bharatmala program exposes reactive aggregate deposits in western and southern states to accelerated construction schedules. Bureau of Indian Standards certification requirements and Central Pollution Control Board fly ash utilization mandates shape product qualification pathways. The Gujarat industrial corridor anchors domestic production capacity where cement majors backward-integrate into mineral admixture sourcing.
United Arab Emirates
NEOM and Red Sea coastal infrastructure projects specify marine-grade concrete with simultaneous ASR and chloride resistance. The Emirates Authority for Standardization and Metrology enforces conformity assessment protocols for imported admixtures. Dubai's construction material testing laboratories concentrate petrographic analysis capacity that project developers require for aggregate reactivity evaluation.
Alkali-Silica Reaction Mitigation Functional Agents Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical majors and captive mineral processors that control critical input streams. Tiered competitive positioning separates premium lithium compound formulators from volume-driven pozzolanic blenders dependent on power generation byproduct access. Three archetypes dominate: global admixture specialists with specification-grade distribution networks, cement producers leveraging captive fly ash or kiln dust resources, and regional blenders deploying asset-light production technology. Capacity expansion and backward integration into lithium compound sourcing represent the dominant competitive moves as battery sector demand intensifies feedstock competition.
Within the global admixture specialist tier, Sika AG and BASF SE exemplify scale-driven positioning through specification-grade supply chains across multiple continents. Heidelberg Materials occupies a distinct archetype as a cement-major with captive control over fly ash streams from integrated power generation assets. These three entities anchor the competitive structure that regional blenders must navigate through equipment leasing models and direct DOT qualification pathways.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Saint-Gobain |
| Fosroc International |
| Euclid Chemical |
| W. R. Grace & Co. |
| Heidelberg Materials |
| Holcim |
| H.B. Fuller |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in lithium compound processing across North American chemical hubs is tightening supplier leverage and amplifying spot-market premiums for specification-grade ASR mitigation agents. This utilization squeeze simultaneously rewards integrated producers with captive feedstock and pressures toll-dependent blenders into fixed-price contract concessions.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where specification-grade lithium compounds command certification premiums over mineral alternatives. Price differentiation rests on ASTM C1567 compliance tier and volume scale, with bridge contractors showing lowest sensitivity due to FHWA-mandated performance guarantees. Cost compression in fly ash blends is intensifying because coal-fired generation retirements constrain Class F supply, while battery sector competition for lithium feedstock erodes margins in chemical admixture tiers.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for lithium carbonate and processed nitrate salts. Raw material flows draw from Chilean brine operations, Australian spodumene mines, and Appalachian coal ash beneficiation facilities. Single-source vulnerability concentrates in qualified petrographic testing laboratories. Distribution runs through specification-grade admixture distributors with DOT pre-qualification status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal infrastructure spending acceleration and EPA coal ash reclassification under RCRA are jointly disrupting procurement patterns for concrete durability additives. These regulatory and fiscal inflections compress supplier qualification timelines while expanding addressable volume for compliant mineral alternatives.
For Market Incumbents: Entrench specification-grade positioning through backward integration into lithium compound sourcing and accelerated ASTM C1567 certification investments. Battery sector entrants threaten feedstock access; defend through long-term offtake agreements with Chilean and Australian producers. Channel control via direct DOT qualification bypasses ready-mix intermediary compression in Florida and Illinois procurement offices.
For New Entrants and Emerging Players: Build out asset-light blending capacity in Texas and California where reactive aggregate deposits and low-carbon mandates create dual demand drivers. California's Buy Clean program offers the most penetrable entry wedge for pozzolanic blenders with verified environmental product declarations. Target marine infrastructure specifications through silica fume-lithium hybrid formulations for Savannah and Long Beach port expansions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-leasing production models, enabling regional blender scalability without fixed-plant commitments. Long-term viability favors integrated chemical majors with captive lithium streams over toll-dependent mineral processors. Watch EPA enforcement discretion on coal ash beneficial use as the signal for fly ash pricing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Sourcing | Secures feedstock priority against battery sector competition for Chilean and Australian supply. |
| ASTM C1567 Certification Investment | Unlocks FHWA-mandated bridge construction contracts across the Interstate Highway System. |
| Coal Ash Beneficiation Capacity Expansion | Converts landfilled fly ash into ASTM C618-compliant pozzolan for Texas highway programs. |
| Direct DOT Qualification Pathway | Bypasses ready-mix intermediaries in Florida and Illinois procurement restructuring. |
| Silica Fume-Lithium Hybrid Development | Captures marine infrastructure specifications for chloride-resistant port expansion concrete. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with state DOT materials engineers, ready-mix plant managers, admixture formulation chemists, and petrographic laboratory directors. Secondary validation drew from FHWA technical advisories, EPA Resource Conservation and Recovery Act dockets, ASTM standard revision records, and state procurement database extracts. Bottom-up volume estimates from project-level concrete specifications were triangulated against top-down chemical admixture production capacity assessments.
Calibration against historical specification-grade adoption patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application severity class, end-user procurement authority concentration, and deployment method format. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure spending authorization trajectories and aggregate reactivity mapping. Key inputs encompassed federal highway obligation schedules and coal-fired generation retirement timelines.
Stress conditions across lithium carbonate price volatility bands, fly ash supply disruption scenarios, and ASTM C1567 timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement continuity and infrastructure appropriation stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Functional Acids Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Thin Film Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Functional Composites Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Smart Card Materials Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Global Smart Material Market