
 Optical Foaming Cleaning Solution Market | 2026-2036
Optical Foaming Cleaning Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Foaming Cleaning Solution Market Analytics
East Asian capacity expansion is reshaping competitive dynamics in precision cleaning chemistry. Carl Zeiss leverages its Jena manufacturing heritage to sustain premium positioning in optical-grade foaming formulations. Bausch + Lomb anchors North American supply through specialized rinsing solutions for contact lens and surgical optics. 3M Company competes across multiple surfactant tiers with broad electronics channel control.
Optical foaming cleaning solutions are aqueous or semi-aqueous formulations containing controlled surfactant blends that generate stable, low-residue foam for delicate substrate cleaning, typically operating at pH 6.5-8.5 to prevent anti-reflective coating damage. Their primary purpose is removing particulate and organic contaminants from precision optics without mechanical abrasion or solvent etching. Foaming agents dominate value contribution due to formulation complexity and patent-protected mildness profiles, while manufacturing equipment application represents the fastest-expanding demand pool as semiconductor lithography nodes shrink. Electronics manufacturers channel the largest volume, though direct sales to research institutions capture disproportionate margin through customized specification work.
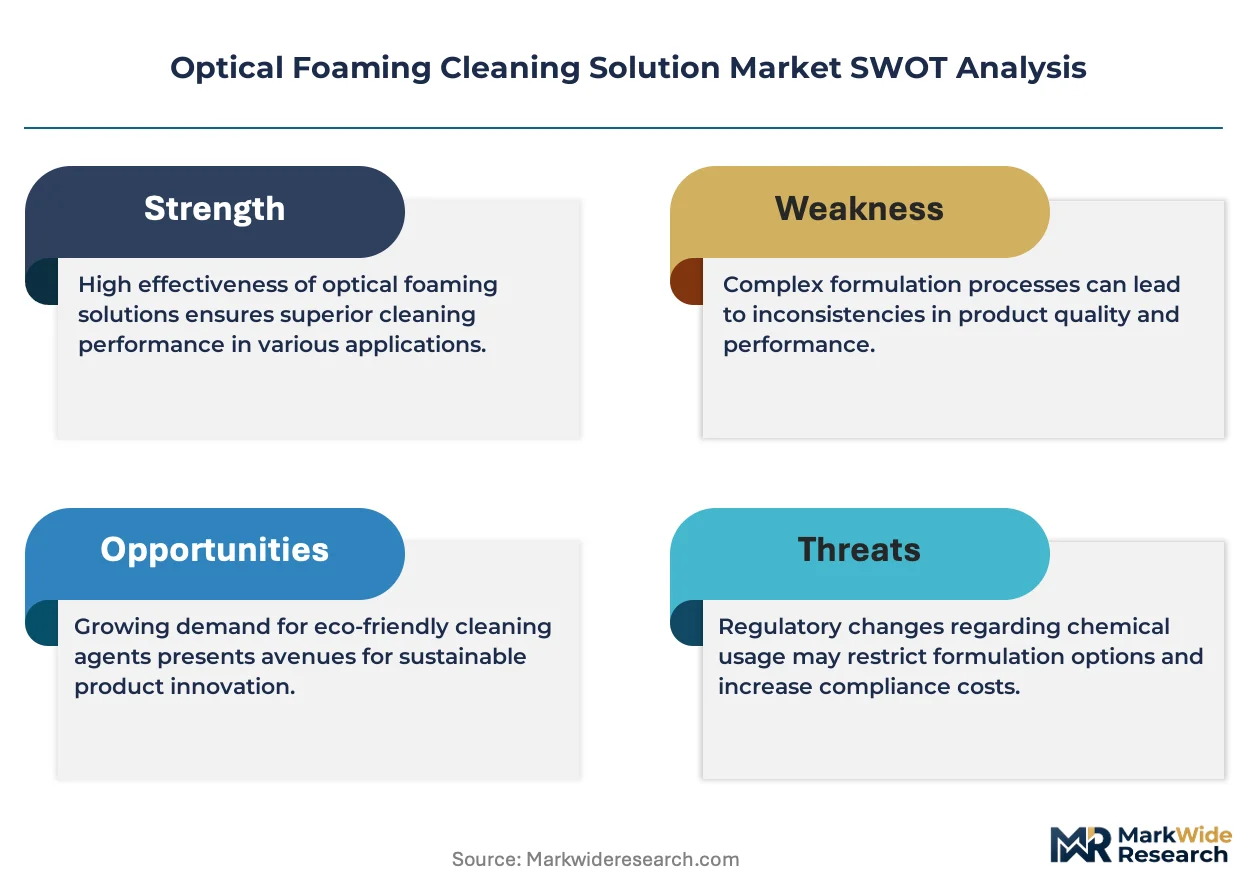
EPA guidelines on volatile organic compound emissions and California's Air Resources Board scoping documents shape permissible solvent content in US-formulated products. REACH registration requirements and the EU Green Deal chemical sustainability taxonomy constrain surfactant selection and biodegradability thresholds for European market access. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these compounds historically enabled residue-free drying in premium optical cleaning protocols.
Market Dynamics
Semiconductor lithography node shrinkage below 7nm is forcing reformulation of aqueous surfactant systems as residue tolerance tightens to sub-nanogram thresholds. This technical pressure cascades through supply chains, concentrating procurement power among foundry operators and their designated equipment suppliers.
Growth Catalysts
- EUV lithography expansion:Next-generation semiconductor manufacturing in Taiwan and South Korea requires ultra-pure cleaning chemistries for photomask and lens maintenance, pulling specialized foaming formulations into high-volume production.
- REACH chemical sustainability taxonomy:European biodegradability mandates accelerate substitution of legacy solvent-based cleaners with aqueous surfactant systems in precision optics clusters.
- California Air Resources Board scoping:Volatile organic compound limits below 25 grams per liter for industrial maintenance products create regulatory pull for low-VOC foaming technologies in West Coast electronics manufacturing.
Market Restraints
- Fluorosurfactant substitution risk:Per- and polyfluoroalkyl substance restrictions under EPA PFAS roadmap and state-level prohibitions eliminate residue-free drying performance historically achieved with fluorinated compounds, forcing costly reformulation cycles.
- Specialty surfactant supply concentration:Alkyl polyglucoside and glucamide mildness agents concentrate production among German and Japanese chemical specialists, creating input vulnerability for formulators outside these supply orbits.
- Technical limitation in high-aspect-ratio features:Foam collapse dynamics in sub-50 micron trenches limit cleaning efficacy for advanced MEMS and micro-optical components, constraining addressable application scope.
Strategic Opportunities
- Underpenetrated Indian precision optics:Bangalore and Pune photonics clusters lack localized supply of semiconductor-grade cleaning chemistries, creating first-mover positioning for compliant aqueous formulations.
- Reusable foam application systems:Closed-loop dispensing equipment reduces chemistry consumption 40-60% in high-throughput flat-panel display manufacturing, enabling service-contract revenue models alongside consumable sales.
- EU Green Deal chemical sustainability taxonomy:Biodegradability scoring creates procurement preference differentiation for surfactant systems achieving >60% OECD 301B biodegradation within 28 days.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant phase behavior and foam rheology at semiconductor purity levels concentrates among retiring specialists in German and Japanese industrial chemistry programs.
- Equipment qualification timelines:Integration with automated wafer handling systems requires 12-18 month validation cycles at foundry customers, compressing product lifecycle returns.
- Cross-jurisdictional substance registration:Divergent PFAS definitions between EPA, ECHA, and state-level regulators create compliance fragmentation for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Foaming Cleaning Solution Market |
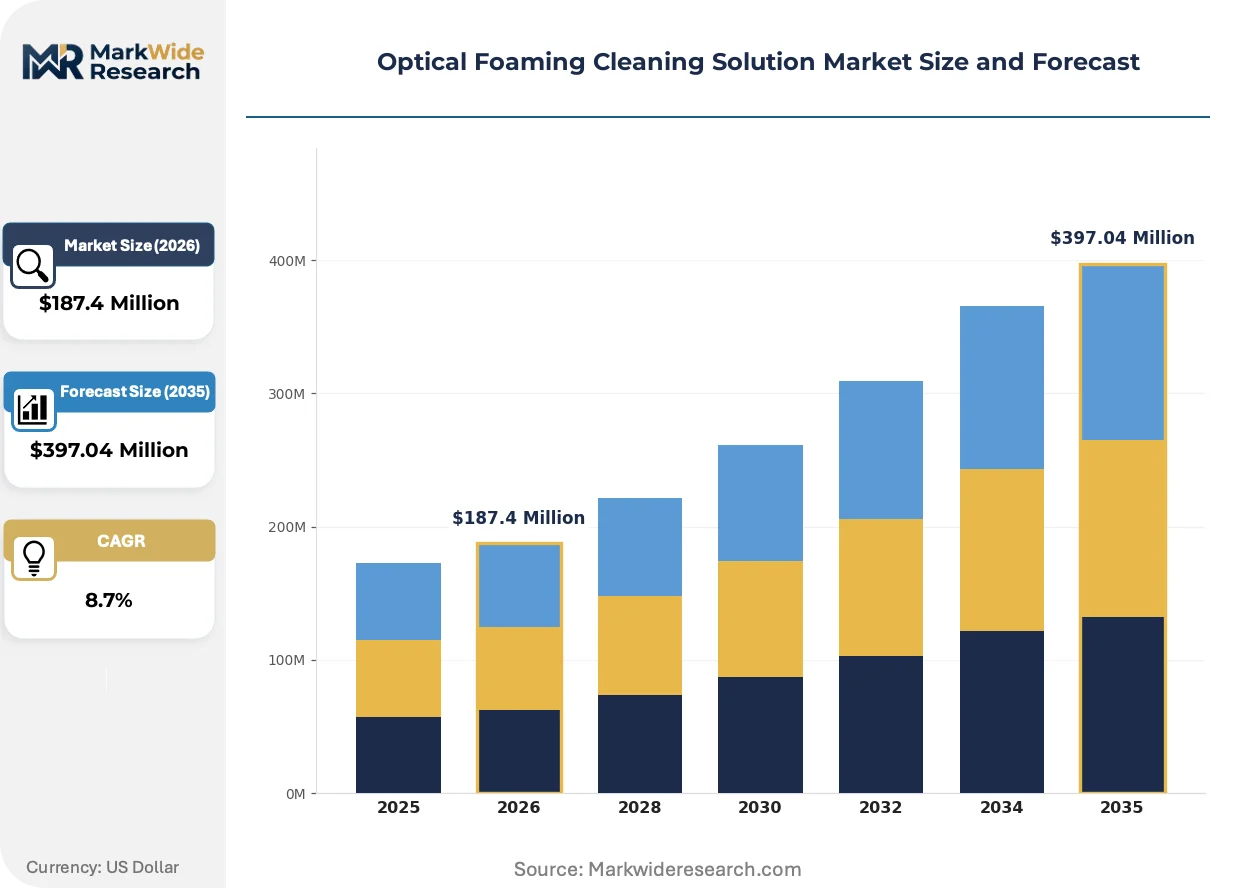
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foaming Agents, Rinsing Solutions, Additives, Surfactants Application: Optical Devices, Lenses, Coatings, Manufacturing Equipment End User: Electronics Manufacturers, Optical Retailers, Laboratories, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Palmero, Bausch + Lomb, Carl Zeiss, 3M Company, Honeywell International, PIP Global, Pyramex, ZEISS International, EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Foaming Cleaning Solution Market Evolving Landscape
Formulation science is converging with equipment engineering as foam generation, application, and removal become integrated process controls rather than discrete steps. This integration is compressing traditional boundaries between chemistry suppliers and capital equipment manufacturers.
Surfactant-polymer complexes is hybridizing foam stability and residue control in single-package systems. Semiconductor foundries in Taiwan and South Korea are adopting these hybrid formulations for EUV pellicle and optics pod cleaning. The technology is hybridizing what were previously separate pre-clean and final-rinse process steps, reducing equipment footprint and chemistry inventory complexity.
REACH Annex XIV authorization requirements for nonylphenol ethoxylates and certain quaternary ammonium compounds are eliminating legacy surfactant options from European supply chains. Formulators must reformulate with alkyl polyglucosides and betaine alternatives that meet OECD 306 biodegradability thresholds. German precision optics manufacturers in Jena and Oberkochen are responding fastest, locking in supply agreements with compliant surfactant specialists ahead of 2026 sunset dates.
Direct specification engagement between end-users and formulators is displacing distributor-mediated procurement in high-volume electronics channels. Foundry operators in Taiwan now contract directly with surfactant houses for customized pH and conductivity ranges, bypassing traditional chemical distribution layers. This pattern concentrates most visibly in East Asian semiconductor manufacturing, where procurement teams embed formulation scientists for co-development programs.
Optical Foaming Cleaning Solution Market Segmentation
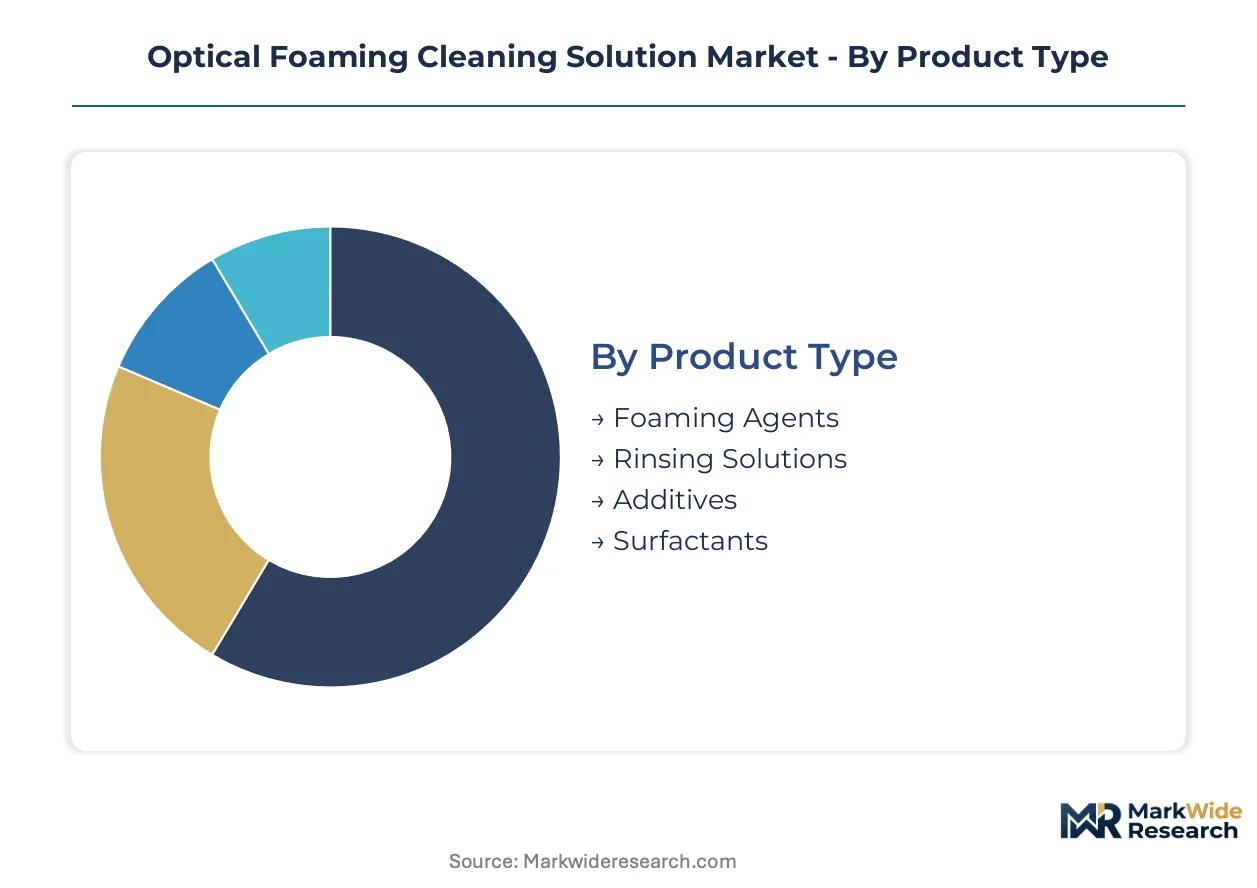
Optical foaming cleaning solutions demand precise segmentation alignment with equipment maintenance cycles and regulatory compliance tiers. Formulation complexity varies sharply across end-use purity requirements, creating distinct service intensity profiles.
Product Type:
After-sales service intensity concentrates in foaming agents and surfactants, where formulation customization and technical support sustain multi-year supplier relationships.
- Foaming Agents:Controlled surfactant blends generating stable, low-residue foam at pH 6.5-8.5. Demand clusters around semiconductor lithography maintenance in Taiwan and South Korea, driven by sub-nanogram residue tolerance thresholds below 7nm nodes.
- Surfactants:Patent-protected mildness profiles including alkyl polyglucosides and glucamides. Procurement concentrates among German and Japanese chemical specialists, constrained by REACH Annex XIV sunset dates for legacy quaternary ammonium compounds.
- Rinsing Solutions:Deionized water-based formulations with conductivity control for final-stage optical cleaning.
- Additives:pH buffers, corrosion inhibitors, and stabilizers for customized formulation enhancement.
Foaming agents hold the largest share; momentum sits with surfactants as biodegradable reformulation accelerates.
Application:
Application segmentation tracks directly with contamination sensitivity and equipment replacement costs.
- Manufacturing Equipment:EUV lithography optics and photomask cleaning systems requiring ultra-pure protocols. Taiwan foundries and South Korean memory manufacturers drive volume as node shrinkage intensifies maintenance frequency.
- Lenses:Precision camera, microscope, and surgical optics with anti-reflective coating compatibility requirements. Germany's Jena and Oberkochen clusters anchor premium specification demand.
- Optical Devices:Binoculars, telescopes, and consumer electronics with moderate purity thresholds.
- Coatings:Protective and functional layer maintenance across display and sensor applications.
Manufacturing equipment commands premium pricing; lenses show steepest expansion trajectory as medical optics diversify.
End User:
Customer type determines procurement channel and specification authority.
- Electronics Manufacturers:Foundry operators and flat-panel display producers with embedded formulation scientists. Direct contracting with surfactant houses displaces traditional distribution in Taiwan and South Korea.
- Research Institutions:National laboratories and university photonics centers requiring customized pH and conductivity ranges. Disproportionate margin capture through specification work offsets lower volumes.
- Laboratories:Quality control and analytical facilities with standardized protocol requirements.
- Optical Retailers:Contact lens and consumer eyewear channels with distributor-mediated procurement.
Electronics manufacturers dominate volume; research institutions deliver highest margin per liter.
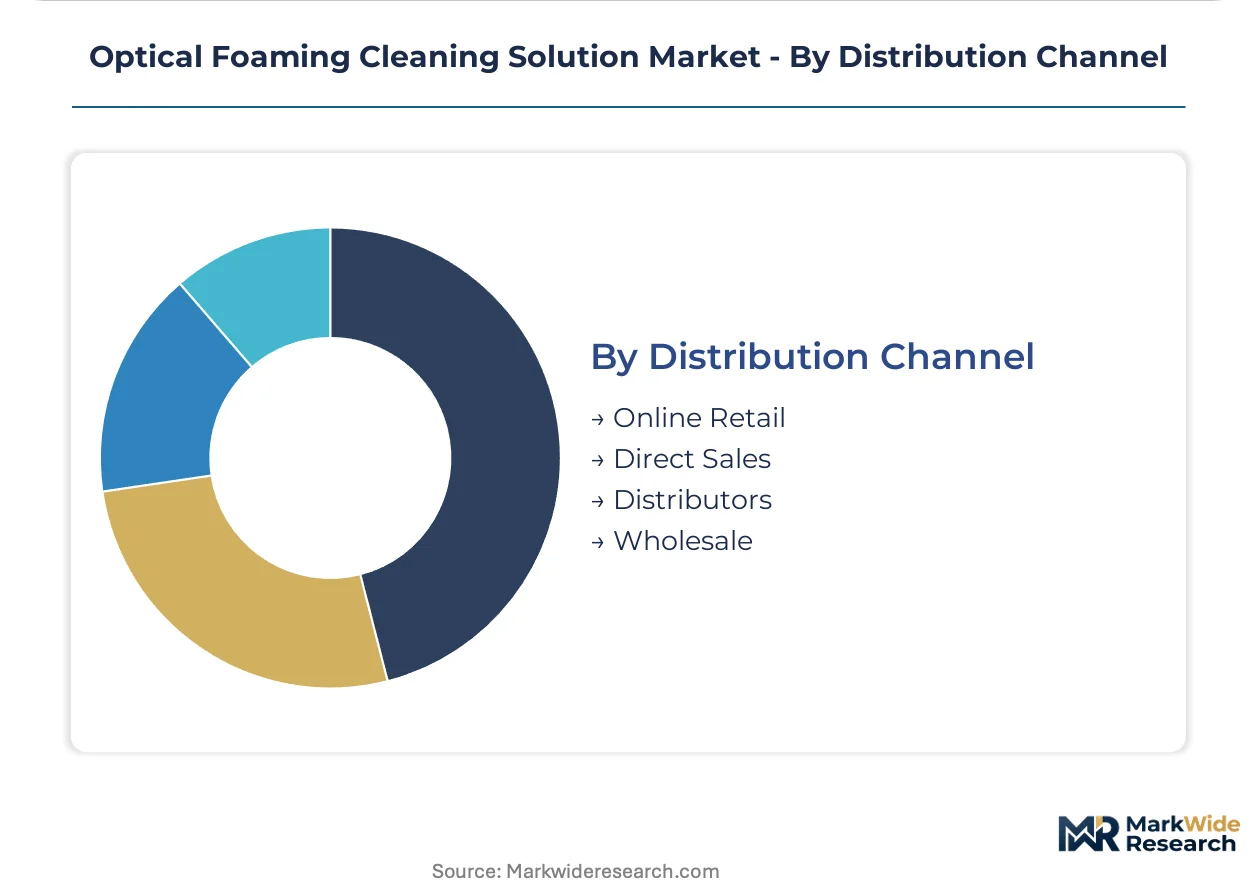
Distribution Channel:
Channel structure reflects customer scale and technical support requirements.
- Direct Sales:Foundry-embedded technical teams and co-development programs. East Asian semiconductor manufacturers bypass distribution layers for customized aqueous surfactant systems.
- Distributors:Regional chemical specialists serving mid-tier electronics and optical retailers. Concentrated in German precision optics clusters around Jena.
- Online Retail:Standardized formulations for laboratory and small-volume institutional buyers.
- Wholesale:Bulk supply agreements for high-throughput flat-panel display manufacturing.
Direct sales capture the fastest-growing volume; distributors retain defensive position in European specialty optics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty surfactant production clusters in Germany and Japan anchor upstream supply for optical foaming formulations. Taiwan and South Korea foundries pull these inputs into high-volume consumption for semiconductor lithography maintenance. Regulatory fragmentation across EPA, ECHA, and state-level PFAS restrictions complicates multi-region formulation strategies.
Germany
REACH Annex XIV sunset dates for nonylphenol ethoxylates are eliminating legacy surfactant options from European supply chains. The EU Green Deal chemical sustainability taxonomy constrains surfactant selection and biodegradability thresholds for market access. Jena and Oberkochen precision optics clusters lock in supply agreements with compliant surfactant specialists ahead of 2026 deadlines.
Taiwan
EUV lithography expansion at TSMC and associated foundries requires ultra-pure cleaning chemistries for photomask and lens maintenance. Direct specification engagement between end-users and formulators is displacing distributor-mediated procurement in high-volume electronics channels. Procurement teams embed formulation scientists for co-development programs with surfactant houses.
South Korea
Memory manufacturers and logic foundries drive demand as node shrinkage intensifies maintenance frequency for lithography optics. The country's national chemical regulator enforces biodegradability mandates that accelerate substitution of legacy solvent-based cleaners. Seoul Capital Area and Busan-Ulsan production corridors concentrate consumption of aqueous surfactant systems.
United States
EPA guidelines on volatile organic compound emissions and California Air Resources Board scoping documents shape permissible solvent content in US-formulated products. California's volatile organic compound limits below 25 grams per liter for industrial maintenance products create regulatory pull for low-VOC foaming technologies. West Coast electronics manufacturing clusters absorb reformulated aqueous systems.
Japan
Alkyl polyglucoside and glucamide mildness agents concentrate production among Japanese chemical specialists, creating input vulnerability for formulators outside this supply orbit. METI industrial standards govern surfactant purity specifications for semiconductor-grade applications. Kanto and Kansai manufacturing belts sustain premium positioning in optical-grade foaming formulations.
Optical Foaming Cleaning Solution Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in surfactant and foaming agent supply. The vendor base stratifies across three tiers: diversified chemical conglomerates with broad electronics channel control, precision optics heritage manufacturers with premium formulation capabilities, and regional surfactant houses serving customized specification work. Dominant competitive moves include direct contracting with foundry operators to bypass distribution layers, and co-development programs embedding formulation scientists at customer sites.
Among heritage optics manufacturers, Carl Zeiss and ZEISS International exemplify the premium-tier archetype anchored in German precision engineering traditions. Bausch + Lomb occupies a position within the North American supply structure for specialized rinsing solutions. 3M Company represents the diversified chemical conglomerate archetype with cross-surfactant-tier presence and broad channel control in electronics manufacturing.
| Leading Market Players |
|---|
| Palmero |
| Bausch + Lomb |
| Carl Zeiss |
| 3M Company |
| Honeywell International |
| PIP Global |
| Pyramex |
| ZEISS International |
| EssilorLuxottica |
| Others |
Value Network & Pricing Analysis
German and Japanese alkyl polyglucoside production clusters anchor surfactant supply for optical foaming formulations, concentrating margin capture among patent-holding specialty chemical houses while downstream formulators face input cost volatility. This upstream control translates into tiered pricing power that separates semiconductor-grade purity specifications from standard laboratory grades.
Pricing Analysis
REACH Annex XIV and California Air Resources Board VOC limits dictate the pricing tier structure across the optical foaming cleaning solution market. Three-tier pricing structure across premium, standard, and economy levels separates EUV lithography-grade formulations with sub-nanogram residue certification from general electronics maintenance and consumer optical products. Price differentiation rests on biodegradability scoring under OECD 301B protocols and embedded formulation scientist support. Pricing pressure stems from fluorosurfactant substitution costs as PFAS restrictions eliminate legacy drying agents. Electronics manufacturers exhibit lowest price sensitivity due to equipment downtime costs, while optical retailers face margin compression from distributor markups.
Supply Chain Analysis
Alkyl polyglucoside and glucamide feedstocks draw from German chemical specialists around Jena and Japanese manufacturers in Kanto and Kansai belts. Specialty surfactant production concentrates in Germany, Japan, and select South Korean chemical complexes. Raw material dependencies include palm-derived fatty alcohols, glucose feedstock for glucoside synthesis, and high-purity deionized water systems. Single-source vulnerability runs through patent-protected mildness agent supply controlled by legacy German and Japanese houses. Distribution runs through direct sales teams embedded at Taiwan and South Korea foundries, bypassing traditional chemical distribution for high-volume semiconductor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUV lithography node shrinkage below 7nm is disrupting established cleaning chemistries, creating first-mover advantage windows for aqueous surfactant systems that achieve sub-nanogram residue thresholds. This technological inflection compresses reformulation cycles and rewards suppliers with embedded customer technical teams.
For Market Incumbents: Insulate premium positioning by locking multi-year supply agreements with Carl Zeiss and TSMC procurement teams ahead of 2026 REACH sunset dates. Backward integration into alkyl polyglucoside production reduces exposure to German and Japanese specialty surfactant concentration. Patent-protected mildness profiles and embedded formulation scientists at customer sites defend against commodity substitution.
For New Entrants and Emerging Players: Build out localized supply capabilities serving Bangalore and Pune photonics clusters where semiconductor-grade cleaning chemistries remain underpenetrated. Target research institutions requiring customized pH and conductivity ranges for disproportionate margin capture through specification work. Direct contracting with national laboratories bypasses entrenched distribution relationships in European markets.
For Investors and Strategic Acquirers: Capital is best deployed toward regional surfactant houses with OECD 301B biodegradability certification and existing relationships with German precision optics manufacturers. Long-term viability hinges on EU Green Deal chemical sustainability taxonomy alignment and PFAS-free formulation pipelines. Monitor EPA PFAS roadmap implementation timelines as inflection indicator for accelerated fluorosurfactant substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Captures margin pools concentrated among German and Japanese specialty chemical houses. |
| Embedded Formulation Scientist Programs | TSMC and Samsung Foundry procurement teams now require co-development partnerships. |
| Biodegradability Certification Investment | OECD 301B scoring above 60% unlocks EU Green Deal procurement preferences. |
| PFAS-Free Formulation Pipeline | EPA roadmap compliance eliminates regulatory risk for multi-region suppliers. |
| Closed-Loop Dispensing Equipment Service Contracts | Reduces chemistry consumption 40-60% in flat-panel display manufacturing. |
Research Methodology
Initial hypotheses were tested against primary input from surfactant formulation chemists, semiconductor foundry procurement managers, precision optics manufacturing engineers, and REACH compliance consultants and refined through secondary validation. Primary fieldwork included technical discussions with German Jena-cluster suppliers and Taiwan foundry embedded scientists. Secondary sources encompassed ECHA REACH registration databases, EPA PFAS regulatory filings, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data for alkyl polyglucoside imports. Bottom-up demand modeling from individual foundry maintenance protocols was cross-checked against top-down market sizing from surfactant production volumes.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include formulation grade tier, end-use equipment type, purity certification level, and regional regulatory cluster. CAGRs were derived from equipment maintenance cycle intensification rates and node shrinkage timelines. Industry-specific forecast inputs incorporated EUV lithography adoption curves and REACH Annex XIV sunset compliance deadlines.
Stress conditions across PFAS regulatory acceleration, specialty surfactant supply disruption, and semiconductor capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about biodegradability mandate enforcement timing and foundry qualification cycle durations. Cross-checking against IHS Markit semiconductor equipment forecasts and Cefic surfactant production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
US Specialty Cleaners Market