
 Korea Personal Care Encapsulation Materials Market | 2026-2036
Korea Personal Care Encapsulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Korea Personal Care Encapsulation Materials Market Insights
Specialized polymer chemists and formulation scientists is bifurcating the competitive landscape into R&D-intensive leaders and contract-dependent followers. Amorepacific Corporation anchors its position through proprietary liposome platforms developed in-house at its Yongin research campus. LG Household & Health Care leverages vertical integration across raw material sourcing to finished skincare products. COSMAX Group dominates third-party encapsulation services for mid-tier brands lacking internal fermentation and particle engineering capabilities.
Korea Personal Care Encapsulation Materials comprise engineered delivery systems—typically 10 nanometers to 100 micrometers in diameter—designed to protect active ingredients such as retinoids, peptides, and botanical extracts from oxidation while enabling controlled release upon skin contact. Liposomes lead product type demand due to their biocompatibility with epidermal lipids and established use in premium anti-aging lines, whereas solid lipid nanoparticles represent the fastest-expanding category as brands seek alternatives to petroleum-derived carriers under tightening clean-beauty standards. Spray drying technology sustains the largest installed manufacturing base among Korean contract manufacturers, though coacervation commands superior margins in fragrance microencapsulation for luxury perfume and color cosmetics.
MFDS cosmetic safety evaluations and K-beauty export certification requirements shape formulation choices, particularly for brands targeting China through cross-border e-commerce channels regulated by NMPA-equivalent standards. MFDS enforces Good Manufacturing Practice for cosmetics, while Korea's PLI scheme for advanced materials indirectly subsidizes domestic encapsulation polymer development. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions in the EU and US reshape silicone-free encapsulation demand, since Korean export-oriented brands face simultaneous compliance pressure across multiple jurisdictions.
Market Dynamics
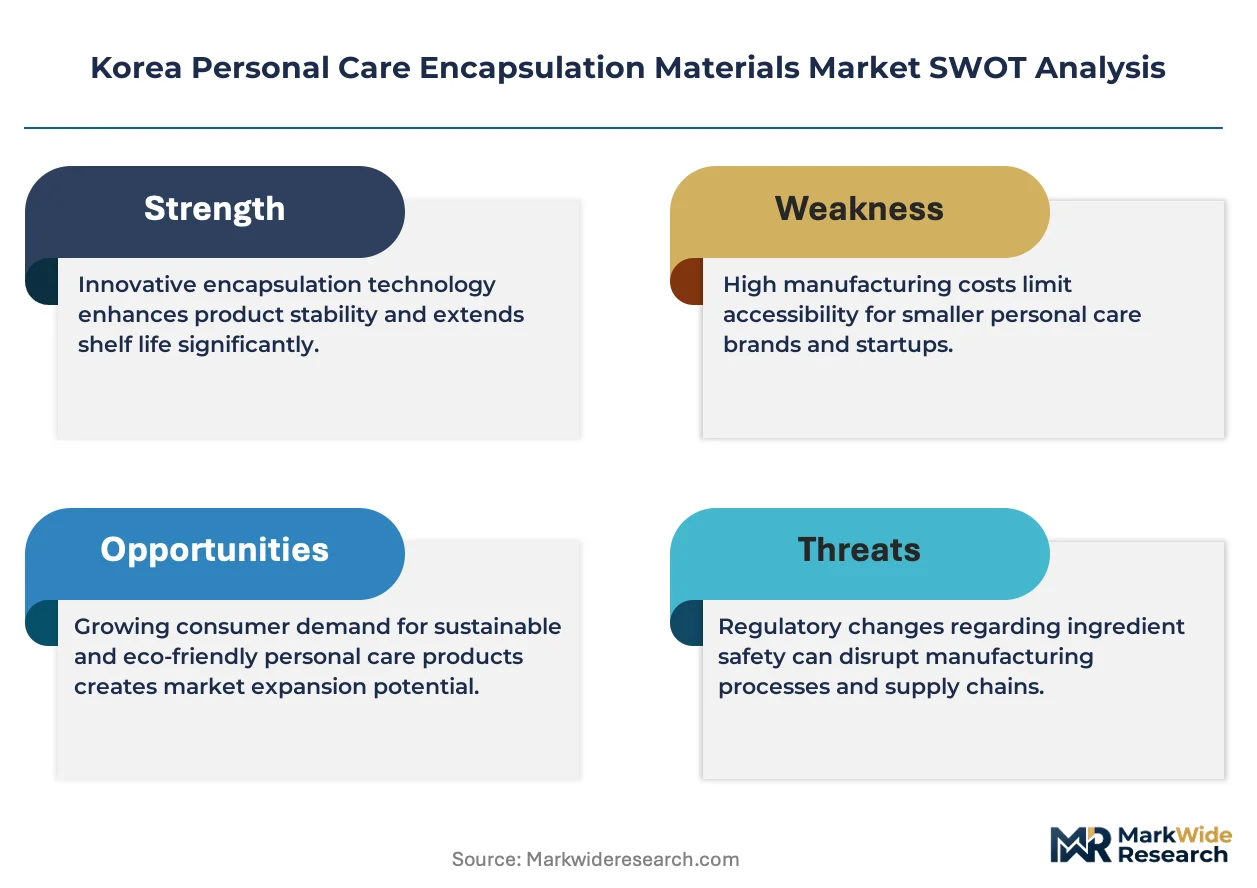
Clean-label K-beauty exports are compressing formulation cycles as brands race to replace petroleum-derived carriers ahead of EU per- and polyfluoroalkyl substance restrictions and China's NMPA-equivalent cross-border standards.
Growth Catalysts
- MFDS Good Manufacturing Practice enforcement:Mandatory safety documentation is pushing mid-tier brands toward certified contract encapsulation partners rather than in-house development.
- Solid lipid nanoparticles:Plant-derived lipid matrices are capturing formulation share from synthetic alternatives as clean-beauty positioning hardens across premium skincare lines.
- Seoul-Incheon corridor concentration:Proximity between R&D campuses and contract manufacturing hubs accelerates pilot-to-scale timelines for novel delivery systems.
Market Restraints
- Phospholipid supply concentration:Liposome-grade lecithin dependence on Argentinian and Ukrainian soybean processing exposes Korean formulators to agricultural commodity volatility.
- Dual carbon compliance costs:China's MIIT energy-intensity standards and EU CBAM border adjustments simultaneously pressure export-oriented encapsulation material producers.
- Silicone encapsulation substitution:Dimethicone-crosspolymer alternatives face technical performance gaps in fragrance retention compared to legacy fluorinated carriers.
Strategic Opportunities
- Busan-Gyeongnam biocluster expansion:Government-designated cosmetics-specialized zones offer tax incentives for encapsulation polymer production facilities outside Seoul's saturated real estate.
- Coacervation-microneedle convergence:Fragrance microcapsules embedded in dissolvable polymer arrays open dermal delivery applications beyond traditional topical cosmetics.
- PLI scheme for advanced materials:Domestic polymer development subsidies reduce reliance on imported encapsulation raw materials for fermentation-derived actives.
Industry Challenges
- Particle engineering talent scarcity:Korean universities produce fewer formulation scientists trained in lipid polymorphism and interfacial chemistry than industry absorption rates require.
- Multi-jurisdiction certification lag:Simultaneous MFDS, NMPA, and EU REACH dossier preparation extends new encapsulation material commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Korea Personal Care Encapsulation Materials Market |
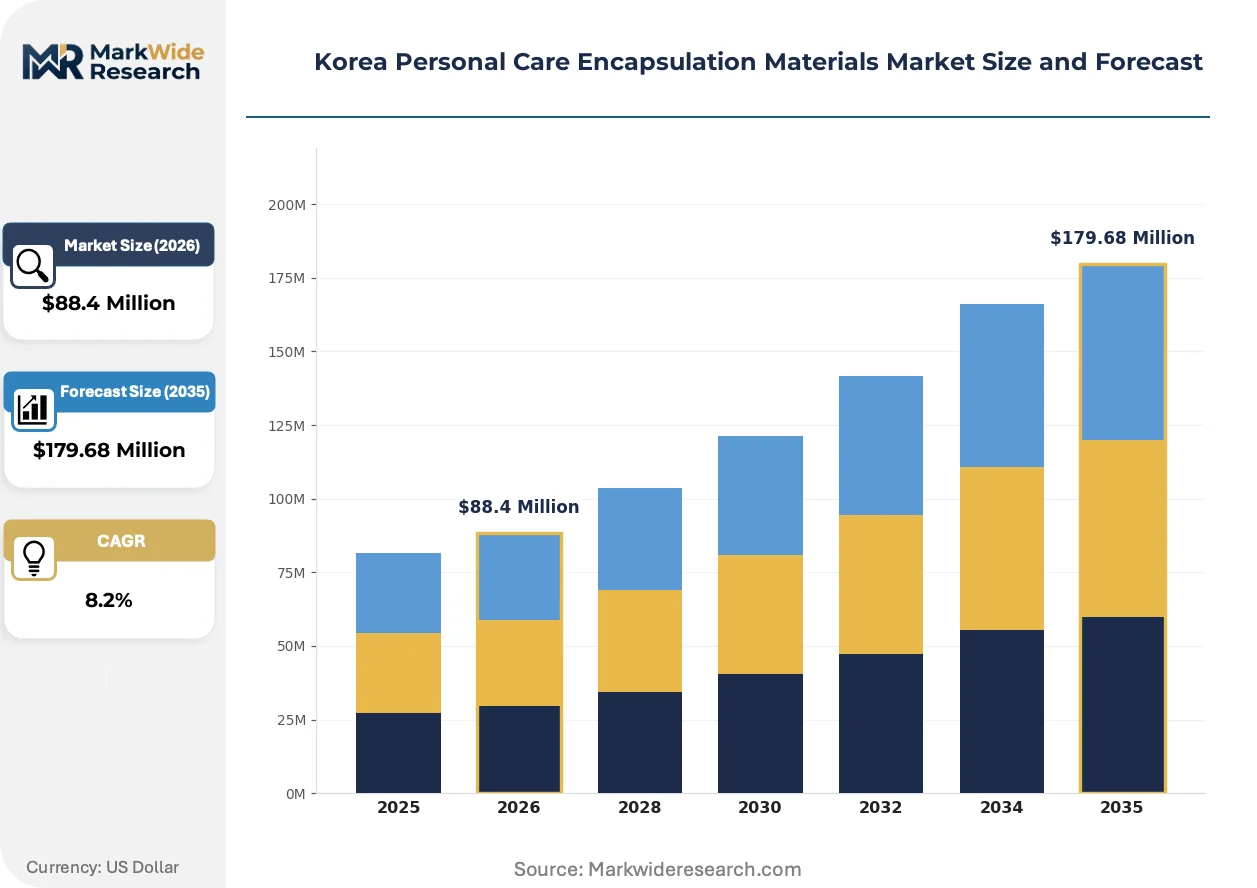
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $179.68 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomes, Microspheres, Nanoparticles, Microcapsules, Solid Lipid Nanoparticles Technology: Coacervation, Spray Drying, Emulsion Polymerization, Extrusion, Ionic Gelation Application: Skincare Formulations, Haircare Products, Makeup Enhancers, Fragrance Delivery, Sunscreens End User: Beauty Salons, Dermatology Clinics, Cosmetic Manufacturers, Research Laboratories |
| Companies Covered | LG Household & Health Care, Neogen Corporation, Kolmar Korea Co. Ltd., Able C&C Co. Ltd., Clio Cosmetics Co. Ltd., COSMAX Group, Cosmecca Korea Co. Ltd., Han Bul Cosmetics Co. Ltd., Amorepacific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Korea Personal Care Encapsulation Materials Market Trends and Innovations
Encapsulation architecture is fragmenting as single-function carriers give way to stimuli-responsive systems that release actives upon specific skin pH or enzymatic triggers rather than passive diffusion.
Spray drying is decomposing from the default manufacturing method toward specialty applications as coacervation and supercritical fluid precipitation capture premium fragrance and sensitive botanical segments. Amorepacific and LG Household & Health Care have installed supercritical CO2 units at Yongin and Osan facilities respectively. This equipment shift is decomposing price competition in standard liposome production while concentrating margin capture in complex multi-core architectures.
MFDS cosmetic safety evaluation guidelines are tightening disclosure requirements for nanomaterial-containing products, forcing reformulation of sub-100 nanometer lipid carriers that previously operated under ingredient-name masking. Brands targeting China through cross-border e-commerce must now synchronize MFDS and NMPA-equivalent documentation. The pre-market notification burden falls heaviest on indie brands lacking regulatory affairs departments, accelerating consolidation around COSMAX Group's compliance-enabled contract services.
Ingredient sourcing transparency has shifted from marketing differentiator to procurement gatekeeper as Chinese distributors demand batch-level fermentation records and solvent residue certificates. Korean brands selling through Tmall Global and Douyin now specify encapsulation partner identity in supplier questionnaires. This audit intensity concentrates contract manufacturing relationships on Busan and Incheon facilities with ISO 22716 and EFfCI cosmetic ingredient certification.
Korea Personal Care Encapsulation Materials Market Segmentation
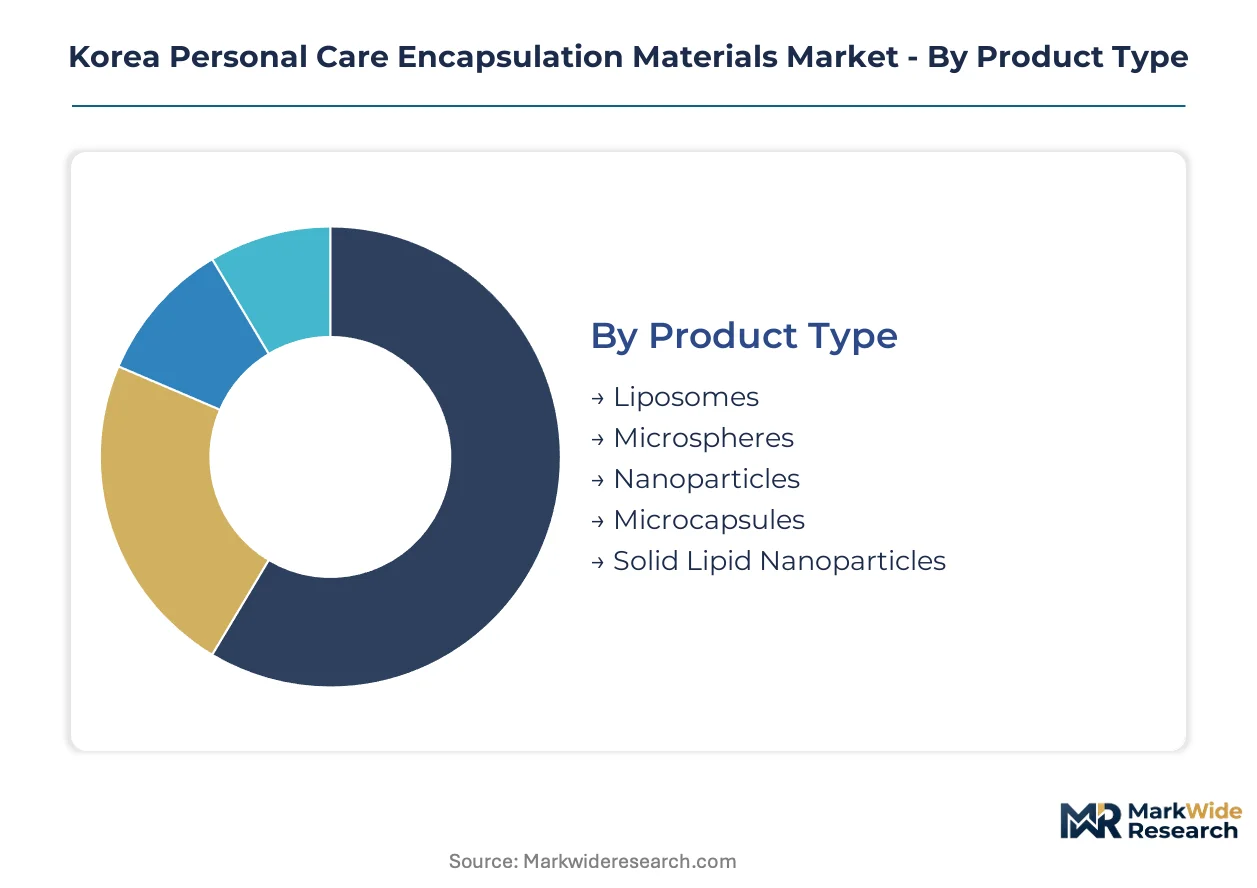
Korean encapsulation material procurement stratifies sharply across delivery system architectures, manufacturing technologies, and end-use compliance requirements. Each segmentation layer concentrates margin capture differently—product type separates premium biocompatibility from commodity carriers, while technology choice determines scalability versus formulation sophistication tradeoffs.
Product Type:
Margin pools concentrate in lipid-based architectures where biocompatibility commands formulation premiums, whereas petroleum-derived alternatives face clean-label displacement pressure.
- Liposomes:Phospholipid bilayer vesicles ranging 25 nanometers to 10 micrometers demonstrate established epidermal lipid affinity. Seoul-Incheon corridor R&D facilities concentrate demand for these carriers in premium anti-aging lines, though Argentinian and Ukrainian soybean supply volatility constrains lecithin procurement.
- Solid Lipid Nanoparticles:Plant-derived lipid matrices—typically glyceride or wax-based—offer petroleum-free alternatives under tightening K-beauty clean-label standards. MFDS cosmetic safety documentation requirements push mid-tier brands toward certified contract manufacturers for these carriers.
- Nanoparticles:Sub-100 nanometer metallic or polymeric cores enable enhanced active loading density.
- Microspheres:Polymeric or ceramic spherical carriers provide sustained-release kinetics for peptide actives.
- Microcapsules:Shell-core architectures protect volatile fragrance molecules from oxidation.
The dominant share belongs to Liposomes, while Solid Lipid Nanoparticles is closing the gap fastest.
Technology:
Equipment capital intensity and process yield rates fragment competitive positioning across manufacturing methods.
- Spray Drying:Atomization of emulsified feedstocks against heated gas streams sustains the largest installed base among Korean contract manufacturers. Yongin and Osan production clusters leverage this scale for standard liposome output, though margin compression intensifies as equipment commoditizes.
- Coacervation:Phase separation of hydrocolloid polymers around hydrophobic cores commands superior margins in luxury fragrance microencapsulation. Amorepacific and LG Household & Health Care capture premium positioning through complex multi-core architectures requiring precise temperature and pH control.
- Extrusion:Mechanical forcing of lipid mixtures through precision orifices produces uniform particle size distributions.
- Emulsion Polymerization:Free-radical initiation within micelle structures yields polymeric microspheres.
- Ionic Gelation:Electrostatic crosslinking of polysaccharide solutions forms hydrogel matrices for sensitive botanical extracts.
Spray Drying retains volume leadership, yet Coacervation claims the steepest expansion trajectory in value terms.
Application:
End-use performance requirements and regulatory exposure reshape carrier specification priorities.
- Skincare Formulations:Retinoid and peptide protection against oxidation drives demand for stimuli-responsive release systems. MFDS nanomaterial disclosure rules force reformulation of sub-100 nanometer carriers previously masked under ingredient nomenclature.
- Fragrance Delivery:Volatile molecule stabilization in color cosmetics and perfume demands shell architectures with precise fracture mechanics. China's NMPA-equivalent cross-border standards add documentation burden for brands targeting Tmall Global and Douyin channels.
- Haircare Products:Cuticle-targeted deposition requires cationic surface modifications.
- Makeup Enhancers:Pigment suspension and skin-feel modification guide carrier selection.
- Sunscreens:UV filter encapsulation reduces dermal penetration while maintaining SPF efficacy.
Skincare Formulations holds the dominant position, with Fragrance Delivery expanding most quickly on luxury positioning.
End User:
Regulatory sophistication and batch-scale requirements segment procurement relationships.
- Cosmetic Manufacturers:Tier-one brands with in-house fermentation capabilities specify custom encapsulation architectures, while mid-tier players outsource to COSMAX Group's compliance-enabled contract services. Dual carbon compliance costs from China's MIIT standards and EU CBAM adjustments pressure export-oriented producers simultaneously.
- Dermatology Clinics:Medical-aesthetic crossover applications demand ISO 13485-adjacent documentation standards. Busan-Gyeongnam biocluster facilities with EFfCI certification capture this high-audit-intensity segment.
- Beauty Salons:Professional treatment protocols favor single-use ampoule formats.
- Research Laboratories:Pilot-scale batches for novel active screening require flexible manufacturing minimums.
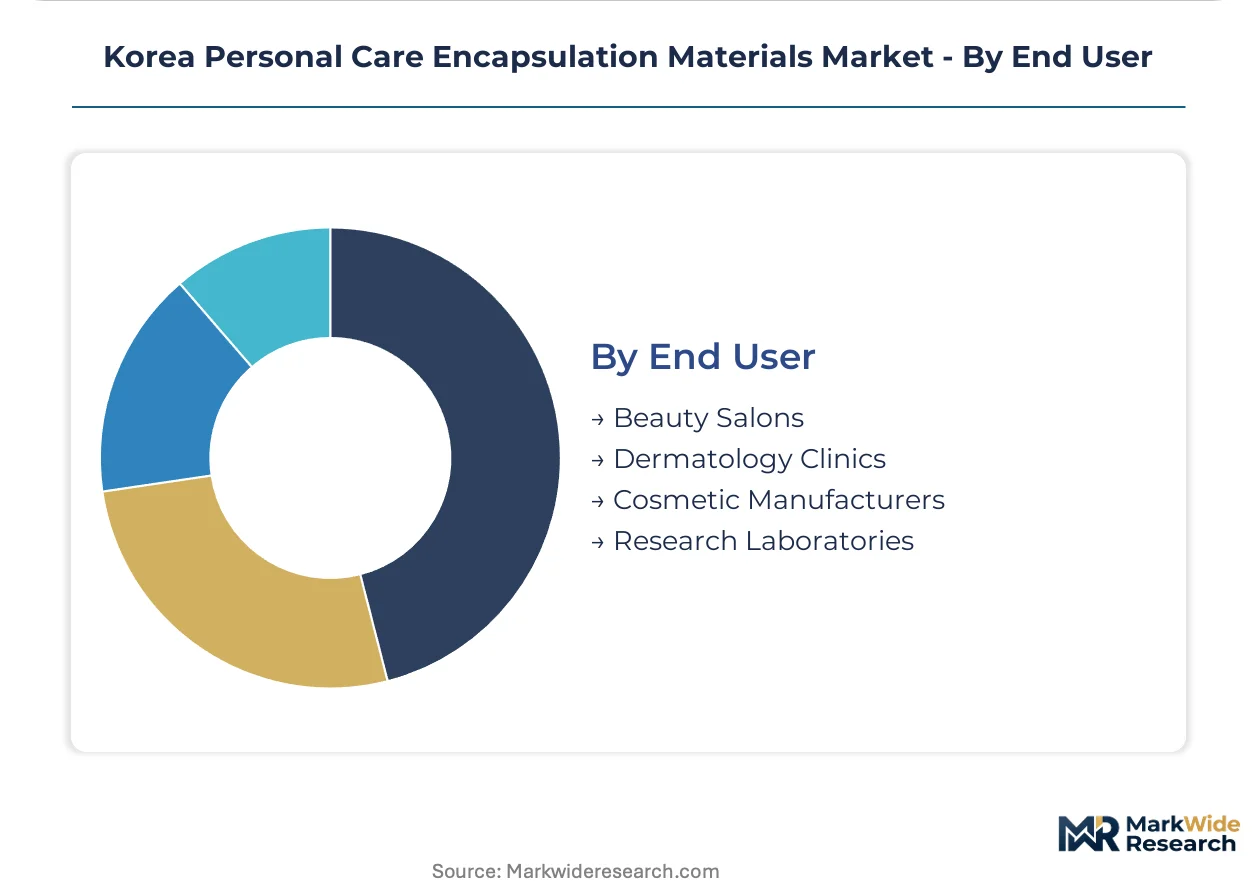
Cosmetic Manufacturers command the dominant procurement volume, though Dermatology Clinics is climbing the fastest on margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS cosmetic safety guidelines anchor Korea's encapsulation material governance, with Seoul-Incheon corridor R&D density shaping formulation standards that export-oriented brands must harmonize across China NMPA-equivalent and EU REACH jurisdictions.
Seoul Capital Area
Premium skincare brand headquarters and proprietary liposome development labs concentrate in Yongin and Osan. MFDS Good Manufacturing Practice enforcement pushes mid-tier brands toward certified contract manufacturers. The Seoul-Incheon corridor accelerates pilot-to-scale timelines through proximity between R&D campuses and production hubs.
Busan-Ulsan
Government-designated cosmetics-specialized zones offer tax incentives for encapsulation polymer facilities outside Seoul's saturated real estate. Busan-Gyeongnam biocluster facilities with EFfCI certification capture high-audit-intensity dermatology clinic segments. Port infrastructure supports phospholipid raw material imports from Argentinian and Ukrainian soybean processors.
Daegu-Gyeongbuk
Textile and chemical industry heritage supplies polymer engineering talent for solid lipid nanoparticle development. Regional universities train fewer formulation scientists than industry absorption rates require. Daegu-based contract manufacturers serve mid-tier brands lacking internal fermentation capabilities.
Daejeon-Sejong
Korea Research Institute of Bioscience and Biotechnology facilities advance stimuli-responsive release system prototypes. PLI scheme for advanced materials subsidizes domestic encapsulation polymer development. Sejong administrative city proximity facilitates regulatory coordination with MFDS headquarters.
Gwangju-Honam
Agricultural processing infrastructure supports plant-derived lipid matrix sourcing for clean-label formulations. Regional biomass suppliers feed solid lipid nanoparticle production lines. Gwangju-based research institutes collaborate on silicone-free encapsulation alternatives under tightening EU per- and polyfluoroalkyl substance restrictions.
Korea Personal Care Encapsulation Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure bifurcating between R&D-intensive proprietary platform developers and compliance-enabled contract service providers. Three archetypes dominate: vertically integrated beauty conglomerates with captive encapsulation capabilities, independent contract manufacturers with multi-jurisdiction certification portfolios, and mid-tier brands dependent on outsourced particle engineering. Competitive moves concentrate on backward integration into raw material sourcing and coacervation technology licensing for fragrance microencapsulation.
Among integrated Korean conglomerates, Amorepacific Corporation and LG Household & Health Care occupy positions as archetype anchors with proprietary liposome platforms and supercritical CO2 manufacturing infrastructure. COSMAX Group exemplifies the contract manufacturing tier, capturing mid-tier brand relationships through compliance-enabled services spanning MFDS, NMPA-equivalent, and EU REACH documentation. Kolmar Korea Co. Ltd. represents the specialist fabricator segment with formulation development capabilities for brands lacking internal particle engineering expertise.
| Leading Market Players |
|---|
| LG Household & Health Care |
| Neogen Corporation |
| Kolmar Korea Co. Ltd. |
| Able C&C Co. Ltd. |
| Clio Cosmetics Co. Ltd. |
| COSMAX Group |
| Cosmecca Korea Co. Ltd. |
| Han Bul Cosmetics Co. Ltd. |
| Amorepacific Corporation |
| Others |
Pricing and Supply Chain Analysis
Scale economies at Seoul-Incheon corridor contract manufacturing clusters compress unit costs for standard liposome output while elevating price floors for complex multi-core architectures requiring supercritical CO2 infrastructure. This concentration bifurcates procurement relationships between mid-tier brands seeking certified volume production and premium players capturing margin through proprietary coacervation capabilities.
Pricing Analysis
Seoul-Incheon production commands formulation premiums over Busan-Gyeongnam facilities due to proximity between R&D campuses and MFDS-certified manufacturing hubs. Three-tier pricing structure across premium, standard, and economy levels separates proprietary liposome platforms from certified contract services and uncertified commodity carriers. Cost compression in standard spray-dried liposomes is intensifying because equipment commoditization erodes technical differentiation. Mid-tier brands lacking internal fermentation capabilities exhibit highest price sensitivity, whereas integrated conglomerates with captive supercritical CO2 units demonstrate lowest sensitivity to input cost fluctuations.
Supply Chain Analysis
Inventory lead times for liposome-grade lecithin stretch across Argentinian and Ukrainian soybean processing seasons, exposing Korean formulators to agricultural commodity volatility. Raw material sourcing concentrates in Argentina, Ukraine, and domestic plant-derived lipid matrix suppliers from Gwangju-Honam agricultural processing infrastructure. Phospholipid supply concentration creates single-source vulnerability during South American harvest disruptions or Black Sea logistics interruptions. Distribution runs through Seoul-Incheon contract manufacturing hubs for mid-tier brands, while integrated conglomerates maintain captive production at Yongin and Osan facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Korea Personal Care Encapsulation Materials sits in early-cycle expansion as clean-label K-beauty exports accelerate solid lipid nanoparticle adoption ahead of EU per- and polyfluoroalkyl substance restrictions.
For Market Incumbents: Consolidate backward integration into phospholipid raw material sourcing to hedge Argentinian and Ukrainian supply volatility. Secure EFfCI and ISO 22716 certifications at Busan-Gyeongnam facilities to capture high-audit-intensity dermatology clinic segments fleeing Seoul's saturated real estate costs. Defensive positioning against silicone-free encapsulation substitutes requires deepening in-house production of plant-derived lipid matrices. For New Entrants and Emerging Players: Anchor in coacervation-microneedle convergence applications where fragrance microcapsules embedded in dissolvable polymer arrays open dermal delivery beyond traditional topical cosmetics. Target government-designated cosmetics-specialized zones in Busan-Ulsan for tax-advantaged encapsulation polymer production. Go-to-market execution should emphasize PLI scheme qualification for advanced materials subsidies reducing imported raw material dependence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with multi-jurisdiction certification portfolios spanning MFDS, NMPA-equivalent, and EU REACH documentation. Long-term viability over the medium-term horizon favors acquisition targets with established fermentation-derived active partnerships and supercritical fluid precipitation capabilities. Watch for inflection when MFDS nanomaterial disclosure rules force sub-100 nanometer carrier reformulation, concentrating demand on compliance-enabled service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phospholipid Sourcing | Argentinian and Ukrainian supply volatility hedges secure lecithin procurement for liposome production. |
| Supercritical CO2 Capacity Installation | Yongin and Osan facilities capture premium margin in complex multi-core fragrance architectures. |
| Busan-Gyeongnam Facility Certification | EFfCI and ISO 22716 qualifications attract dermatology clinic segments with high audit intensity. |
| Coacervation-Microneedle Convergence R&D | Dissolvable polymer arrays extend fragrance microcapsule applications into medical-aesthetic crossover. |
| PLI Scheme Qualification for Advanced Materials | Domestic polymer development subsidies reduce reliance on imported encapsulation raw materials. |
Research Methodology
A spread of perspectives from formulation scientists at contract manufacturers, regulatory affairs specialists navigating MFDS and NMPA-equivalent documentation, procurement leads at mid-tier beauty brands, and phospholipid raw material distributors converged on the working assumptions. Primary interviews combined with secondary validation from MFDS cosmetic safety guidelines, Korea PLI scheme documentation, EU REACH substance restrictions, and customs records for Argentinian and Ukrainian soybean imports. Bottom-up capacity estimates triangulated against top-down export value flows.
Segmentation dimensions modeled span delivery system architecture, manufacturing technology, end-use application, and procurement relationship type across the projection horizon. CAGRs derived from equipment installation trajectories, certification adoption curves, and clean-label formulation shift velocities. Industry-specific forecast inputs include supercritical CO2 unit deployment timelines at integrated conglomerate facilities and MFDS nanomaterial disclosure rule implementation pacing.
Material uncertainties — phospholipid supply disruptions, dual carbon compliance cost escalations, and multi-jurisdiction certification lag extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about K-beauty export growth sustainability and EU per- and polyfluoroalkyl substance restriction timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Functional Acids Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Global Smart Material Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Thermal Interface Pads and Material Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Functional Composites Market
Functional Materials
Thin Film Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Smart Card Materials Market
Functional Materials
Flexible Thin Film Market