
 Thin-Film Encapsulation Market | 2026-2036
Thin-Film Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Thin-Film Encapsulation Market Intelligence
EU F-Gas Regulation is expanding compliance burdens for fluoropolymer-based encapsulation chemistries used in OLED manufacturing. Applied Materials, Inc. leverages its deposition equipment portfolio to anchor high-barrier film production lines across Asian display clusters. Samsung SDI Co., Ltd. sustains captive demand through backward integration into OLED panel supply chains. Universal Display Corporation differentiates by controlling phosphorescent emitter IP that dictates encapsulation thermal budgets.
Thin-film encapsulation denotes sub-micrometer barrier coatings—typically alternating silicon oxide or aluminum oxide inorganic layers with organic planarization coatings deposited by atomic layer deposition or chemical vapor deposition—to prevent oxygen and moisture ingress into moisture-sensitive electronics. The technology serves primarily to extend operational lifetime of flexible OLED displays and perovskite photovoltaic cells where water vapor transmission rates below 10−6 g/m2/day prove essential. Hybrid layers combining inorganic barrier density with organic stress relief currently command the deepest process know-how and highest margin pools, while organic coatings alone face commoditization in solar panel applications. Atomic layer deposition equipment occupies the most capital-intensive tier of the technology segment, though plasma enhanced deposition is gaining traction for wearable electronics where throughput-flexibility tradeoffs favor lower-temperature processing.
EMA medical device standards, REACH substance restrictions on perfluorinated compounds, and Korea's national chemical management framework collectively shape material selection and qualification timelines for encapsulation suppliers targeting healthcare devices and consumer electronics. FDA 510(k) pathways for wearable diagnostic patches further constrain barrier-film biocompatibility claims, narrowing the vendor set for healthcare end user industry applications. Stakeholders must monitor how the EU AI Act's hardware reliability requirements cascade into encapsulation specifications for edge-deployed smart sensors before committing to multi-year deposition platform investments.
Market Dynamics
The EU F-Gas Regulation is compressing fluoropolymer supply chains for OLED barrier films while South Korean panel makers accelerate backward integration into deposition equipment to secure captive encapsulation capacity.
Growth Catalysts
- Flexible OLED display proliferation:Smartphone and tablet manufacturers in China are scaling foldable device production, concentrating demand for multi-layer hybrid barrier architectures that withstand repeated mechanical stress.
- Perovskite solar commercialization:Photovoltaic developers require water vapor transmission rates below 10−6 g/m2/day, pulling atomic layer deposition equipment into gigawatt-scale manufacturing lines.
- REACH substance restrictions:ECHA's tightening controls on perfluorinated compounds are accelerating qualification of silicon oxide-aluminum oxide alternating stacks as compliant barrier alternatives.
Market Restraints
- Capital intensity of ALD platforms:Single-wafer atomic layer deposition systems require $15-25 million per production line, freezing out mid-tier display fabs in Vietnam and Indonesia.
- Fluorinated precursor supply concentration:Three German and Japanese chemical suppliers control 80% of high-purity C4F8 and C3F6 feedstock for plasma-enhanced deposition.
- Thermal budget constraints:Phosphorescent OLED emitters degrade above 85°C, limiting viable inorganic deposition processes to low-temperature plasma variants with 40% slower throughput.
Strategic Opportunities
- Healthcare wearable expansion:FDA 510(k) pathways for diagnostic skin patches create premium qualification tiers for biocompatible barrier films with ISO 10993 compliance.
- India electronics manufacturing:PLI scheme subsidies for display fabs in Maharashtra and Tamil Nadu are attracting encapsulation equipment vendors to establish local service infrastructure.
- Edge AI sensor hardware:The EU AI Act's reliability requirements for deployed smart sensors are extending encapsulation specifications to microcontroller-integrated barrier modules.
Industry Challenges
- Process engineer scarcity:Atomic layer deposition expertise concentrates among veterans of semiconductor memory fabs, creating recruitment bottlenecks for display-focused equipment startups.
- Multi-standard certification lag:Simultaneous EMA medical device, REACH chemical, and Korea MFDS chemical management approvals extend qualification timelines to 18-24 months for healthcare-targeted films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin-Film Encapsulation Market |
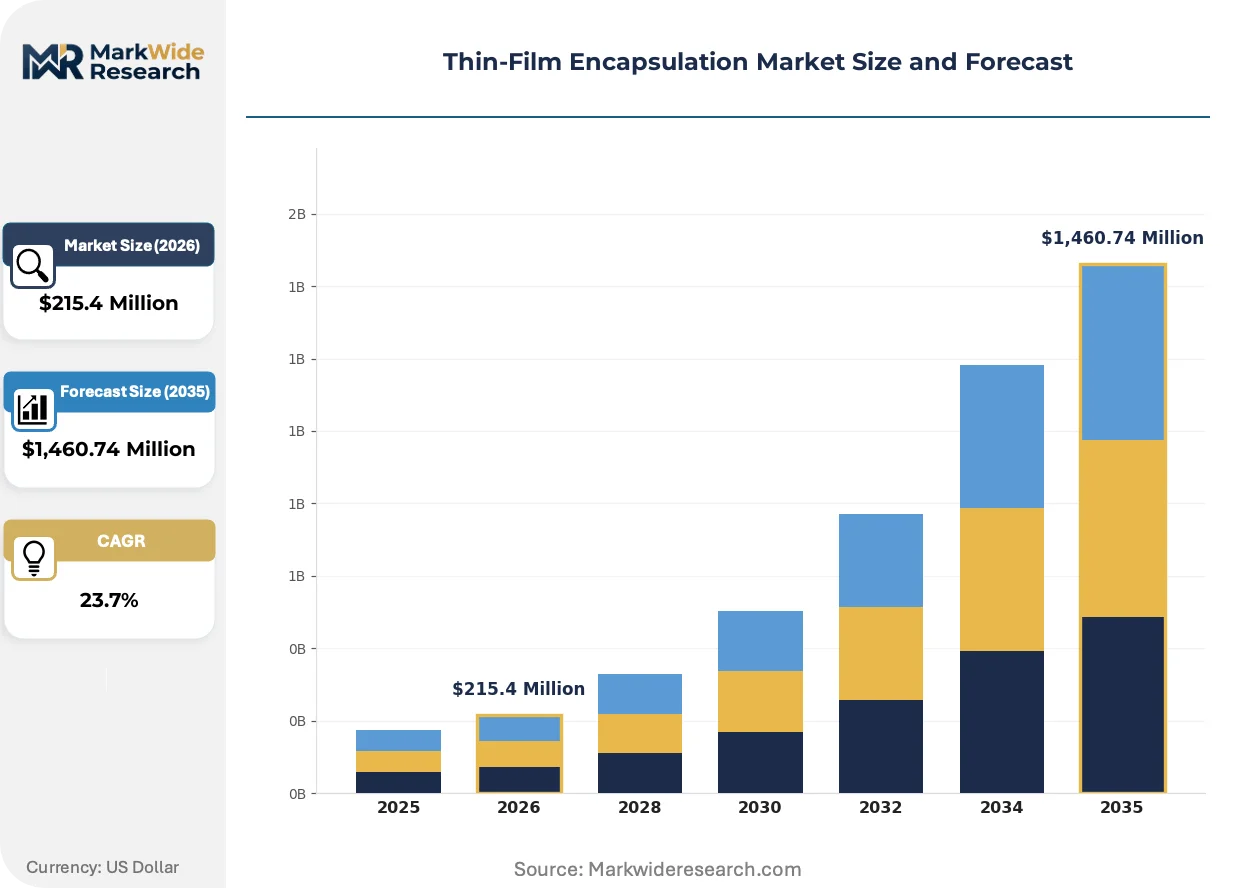
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $1,460.74 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Layers, Organic Coatings, Hybrid Layers, Multi-layer Films Application: Flexible Displays, Solar Panels, Wearable Electronics, Smart Cards End User Industry: Consumer Electronics, Photovoltaic Manufacturers, Healthcare Devices, Smart Packaging Technology: Atomic Layer Deposition, Chemical Vapor Deposition, Physical Vapor Deposition, Plasma Enhanced Deposition |
| Companies Covered | Applied Materials, Inc., Universal Display Corporation, Samsung SDI Co., Ltd., Toppan Inc., Toray Industries, Inc., LG Chem, Veeco Instruments Inc., Kateeva, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin-Film Encapsulation Market Strategic Shifts & Innovations
Barrier film architectures are converging with deposition equipment intelligence to enable real-time defect detection, compressing yield ramp cycles for flexible electronics manufacturing.
Multi-layer hybrid encapsulation is integrating organic planarization coatings between dense inorganic oxide stacks to manage mechanical stress in foldable displays. Samsung Display and BOE Technology are qualifying these architectures for 500,000-fold durability targets. The approach is integrating stress-relief engineering directly into barrier design, collapsing the traditional separation between mechanical and environmental protection functions.
The EU F-Gas Regulation is banning virgin hydrofluorocarbons in display fabrication from 2027, forcing substitution with fluorine-free plasma chemistries. Equipment suppliers are qualifying nitrogen trifluoride alternatives and cryogenic recovery systems. OLED panel manufacturers in the Netherlands and Germany are accelerating equipment retrofits to avoid production line shutdowns during the phased compliance window.
Chinese display fabs are consolidating barrier film procurement through direct equipment partnerships rather than merchant chemical suppliers. BOE and TCL CSOT are negotiating multi-year deposition platform contracts with embedded consumables pricing. This concentration is most visible in Hefei and Shenzhen, where captive supply agreements now cover 60% of regional ALD tool installations.
Thin-Film Encapsulation Market Segmentation
Thin-film encapsulation suppliers face divergent margin pressures across deposition technologies and end-use specifications. Equipment selection and material stack composition determine which segments absorb capital intensity versus commoditization risk.
Product Type:
Buyers prioritize water vapor transmission rate performance against mechanical flexibility requirements when selecting barrier architectures.
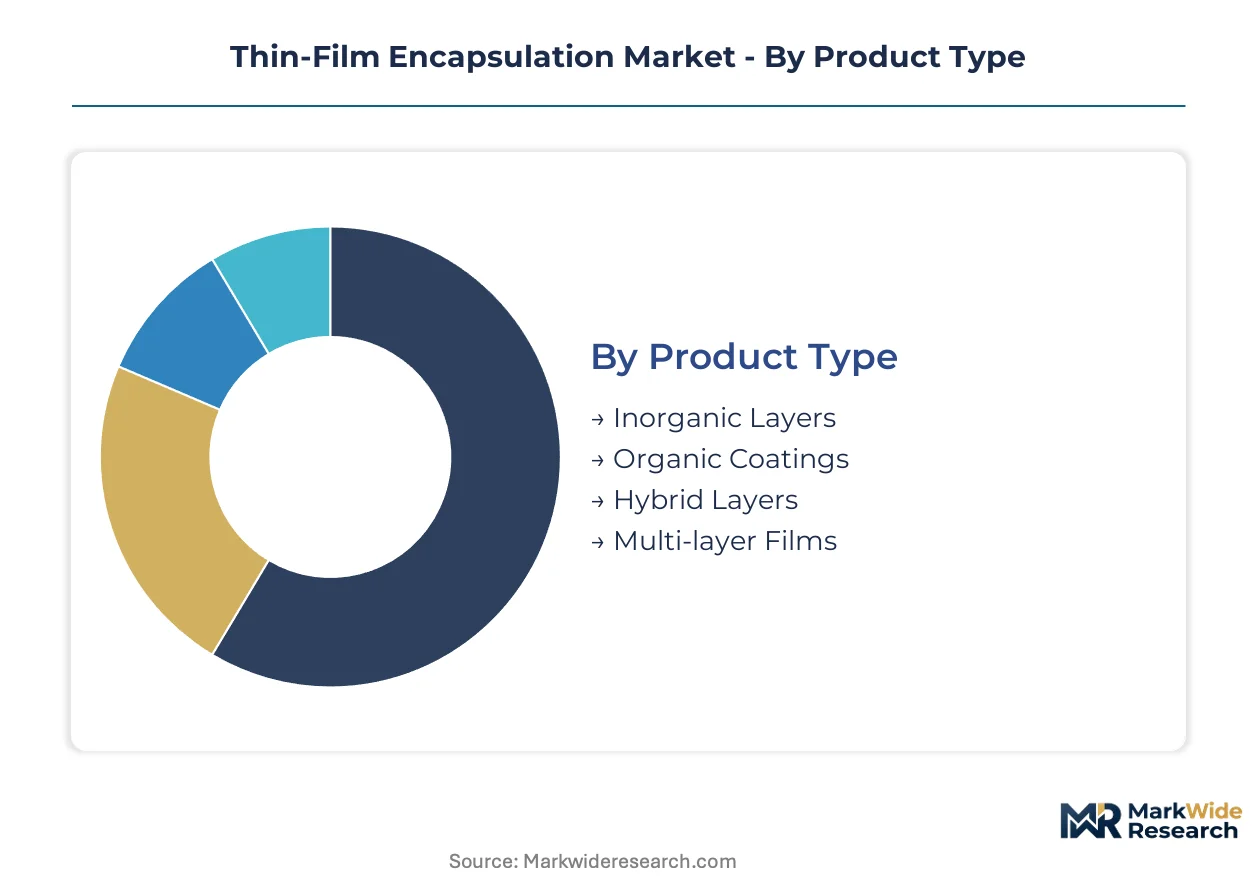
- Hybrid Layers:Alternating silicon oxide or aluminum oxide inorganic stacks with organic planarization interlayers achieve sub-10−6 g/m2/day permeability while managing fold-induced stress. Samsung Display and BOE Technology in South Korea and China are qualifying these architectures for 500,000-fold durability targets in next-generation smartphones.
- Multi-layer Films:Complex architectures exceeding five alternating strata deliver the highest barrier performance for perovskite photovoltaic cells where moisture ingress destroys device function. Photovoltaic developers in China are pulling atomic layer deposition equipment into gigawatt-scale manufacturing lines to produce these films.
- Inorganic Layers:Dense oxide coatings deposited by ALD or PVD provide primary barrier function but require stress-relief pairing for flexible substrates.
- Organic Coatings:Polymer planarization layers alone face commoditization in solar panel applications where barrier requirements are less stringent than display or healthcare uses.
Hybrid layers lead on scale; multi-layer films lead on momentum.
Application:
End-use durability specifications and regulatory exposure shape procurement decisions across device categories.
- Flexible Displays:Foldable OLED panels demand barrier films surviving 200,000+ mechanical cycles while maintaining optical clarity. Chinese smartphone manufacturers are scaling production of foldable devices, concentrating demand for stress-engineered hybrid architectures in Shenzhen and Hefei manufacturing clusters.
- Wearable Electronics:Skin-contact devices require ISO 10993 biocompatibility certification alongside moisture protection. FDA 510(k) pathways for diagnostic patches create premium qualification tiers constraining vendor selection for healthcare-targeted films.
- Solar Panels:Perovskite and organic photovoltaic modules need barrier performance matching flexible displays at lower cost tolerance.
- Smart Cards:Payment and identification cards utilize thin-film encapsulation for chip protection with moderate barrier requirements.
Flexible displays dominate current procurement volume; wearable electronics is climbing the fastest as healthcare integration accelerates.
End User Industry:
Qualification timelines and regulatory jurisdiction determine supplier stickiness across customer verticals.
- Consumer Electronics:Smartphone and tablet manufacturers drive the largest absolute demand for barrier films, with South Korean and Chinese panel makers scaling backward integration into deposition equipment to secure captive encapsulation capacity.
- Healthcare Devices:Wearable diagnostic patches and implantable sensors require simultaneous EMA medical device, REACH chemical, and Korea MFDS approvals extending qualification to 18-24 months. This regulatory burden narrows the vendor set and sustains premium pricing.
- Photovoltaic Manufacturers:Perovskite solar commercialization is pulling atomic layer deposition into energy-sector capital equipment budgets with different ROI expectations than display fabrication.
- Smart Packaging:Food and pharmaceutical logistics applications utilize moderate-barrier films for shelf-life extension with less stringent specifications than electronics.
Consumer electronics leads on scale; healthcare devices leads on margin protection.
Technology:
Capital intensity and thermal budget constraints filter equipment choices by end-use sensitivity and throughput requirements.
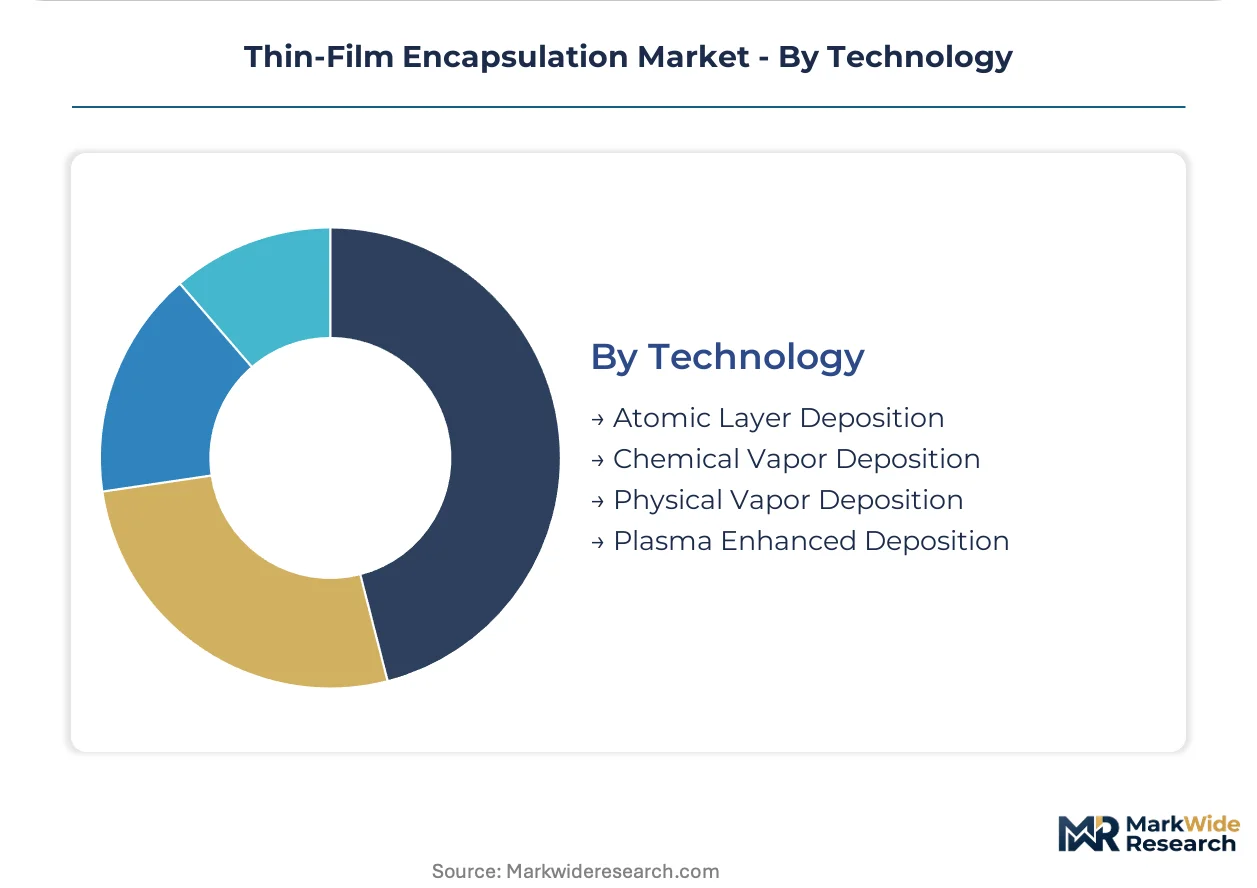
- Atomic Layer Deposition:Single-wafer systems command $15-25 million per production line, delivering angstrom-level thickness control essential for sub-10−6 g/m2/day barriers. This capital intensity freezes out mid-tier display fabs in Vietnam and Indonesia while concentrating supply among memory-fab veterans.
- Plasma Enhanced Deposition:Lower-temperature processing enables deposition on phosphorescent OLED emitters degrading above 85°C, trading 40% throughput reduction for thermal budget compliance in wearable electronics.
- Chemical Vapor Deposition:Higher-throughput alternatives suit solar panel applications where barrier specifications permit slightly elevated permeability.
- Physical Vapor Deposition:Sputtering and evaporation methods serve cost-sensitive applications with moderate barrier requirements.
Atomic layer deposition leads on performance premium; plasma enhanced deposition is gaining share fastest as temperature-sensitive applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea pioneered mass-scale OLED manufacturing during the 2010s, establishing the process foundations that Chinese and Japanese competitors now replicate. Regional differentiation today rests on regulatory compliance timelines, captive supply chain strategies, and equipment vendor proximity to display fabrication clusters.
South Korea
Samsung Display and LG Display drive barrier film demand through backward integration into deposition equipment. The country's national chemical management framework tightens perfluorinated compound handling ahead of EU alignment. Gyeonggi-do province hosts the densest concentration of ALD tool installations serving smartphone panel output.
China
BOE Technology and TCL CSOT scale foldable OLED production, concentrating procurement for 500,000-fold durability architectures. Domestic fab subsidies under the 14th Five-Year Plan accelerate equipment localization. Hefei and Shenzhen manufacturing clusters now cover sixty percent of regional atomic layer deposition tool capacity through captive supply agreements.
Japan
Toray Industries and Toppan anchor fluoropolymer precursor supply chains now constrained by REACH substance restrictions. METI industrial policy supports low-temperature plasma deposition R&D for wearable electronics. Nagoya and Osaka prefectures concentrate equipment engineering talent from semiconductor memory fab veterans.
Germany
OLED equipment retrofits accelerate ahead of the EU F-Gas Regulation's 2027 virgin hydrofluorocarbon ban. ECHA controls on perfluorinated compounds force qualification of silicon oxide-aluminum oxide alternating stacks. Dresden and Munich research clusters pioneer cryogenic recovery systems for plasma chemistry recycling.
United States
Applied Materials anchors high-barrier film production line deployments across Asian display clusters from its Santa Clara headquarters. FDA 510(k) pathways for wearable diagnostic patches create premium qualification tiers for healthcare-targeted films. Greater Boston and Pacific Northwest regions concentrate atomic layer deposition process engineering expertise.
Thin-Film Encapsulation Market Key Industry Players
The competitive structure tilts toward equipment-led consolidation. Memory-fab veterans dominate atomic layer deposition platform supply, freezing out mid-tier display fabs in emerging manufacturing locations. Three archetypes define positioning: integrated equipment-chemical suppliers, captive panel-maker divisions, and specialist barrier film vendors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure deposition platform access.
Among Korea-based fabricators, Samsung SDI Co., Ltd. exemplifies the captive integration archetype through backward control over OLED panel supply chains. Applied Materials, Inc. occupies the equipment-dominant position, anchoring high-barrier production line deployments. Universal Display Corporation represents the IP-driven specialist tier, with phosphorescent emitter control dictating encapsulation thermal budgets for temperature-sensitive deposition processes.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Universal Display Corporation |
| Samsung SDI Co., Ltd. |
| Toppan Inc. |
| Toray Industries, Inc. |
| LG Chem |
| Veeco Instruments Inc. |
| Kateeva |
| 3M |
| Others |
Cost & Logistics Intelligence
High-purity C4F8 and C3F6 precursor indices cascade through fluoropolymer-dependent deposition tiers, compressing margins for plasma-enhanced equipment users while silicon oxide-aluminum oxide alternatives command premium qualification pricing from REACH-compliant buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume scale. Premium tiers absorb ISO 10993 biocompatibility costs for healthcare wearables, while economy tiers face commoditization in solar panel organic coatings. Cost compression in standard-tier hybrid layers is intensifying because Chinese display fabs consolidate procurement through captive equipment partnerships. Photovoltaic manufacturers prove most price-sensitive; healthcare device OEMs least.
Supply Chain Analysis
Photoresist-grade fluoropolymer supply rests on German and Japanese specialty chemical producers controlling precursor feedstock. Atomic layer deposition equipment draws from South Korean and U.S. engineering clusters, while barrier film fabrication concentrates in Chinese and South Korean display hubs. Single-source vulnerability in fluorinated precursor supply exposes equipment operators to ECHA restriction timelines. Distribution runs through direct equipment partnerships rather than merchant chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory-driven demand as the EU F-Gas Regulation's 2027 hydrofluorocarbon ban forces equipment retrofits across European display fabrication.
For Market Incumbents: Cement backward integration into deposition equipment to lock captive demand from OLED panel makers scaling foldable production. Deepen fluorine-free plasma chemistry R&D ahead of REACH tightening on perfluorinated compounds. Prioritize multi-standard certification infrastructure to compress 18-24 month healthcare qualification timelines. For New Entrants and Emerging Players: Launch via equipment service partnerships targeting India's PLI-subsidized display fabs in Maharashtra and Tamil Nadu. Penetrate the wearable electronics segment where FDA 510(k) pathways constrain incumbent vendor sets. Qualify silicon oxide-aluminum oxide stacks as fluoropolymer alternatives to capture REACH-driven substitution demand. For Investors and Strategic Acquirers: Asymmetric upside sits with atomic layer deposition equipment specialists serving temperature-sensitive phosphorescent OLED applications. Five-to-ten year viability hinges on perovskite solar commercialization pulling ALD into energy-sector capital budgets. Watch water vapor transmission rate specifications for edge AI sensors under EU AI Act reliability mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Qualification | Enables EU F-Gas Regulation compliance ahead of 2027 hydrofluorocarbon manufacturing ban. |
| Healthcare Certification Investment | Secures ISO 10993 and FDA 510(k) pathways for diagnostic skin patch barrier films. |
| Captive Equipment Partnership | Locks multi-year ALD platform contracts with embedded consumables pricing in Chinese fabs. |
| Perovskite Solar Equipment Deployment | Pulls atomic layer deposition into gigawatt-scale photovoltaic manufacturing lines. |
| Low-Temperature Plasma R&D | Addresses phosphorescent OLED thermal budgets degrading above 85°C for wearable electronics. |
Research Approach
Multiple input streams — equipment vendor technical specifications, display fab procurement disclosures, and regulatory filing databases — were reconciled across primary interviews with atomic layer deposition process engineers, OLED panel manufacturing executives, and healthcare device regulatory affairs leads. Secondary validation drew from ECHA REACH restriction timelines, FDA 510(k) clearance databases, and Korean MFDS chemical management frameworks. Bottom-up equipment installation counts and top-down display production forecasts were triangulated to anchor market sizing.
Historical capital expenditure patterns for deposition equipment were cross-referenced against panel maker technology roadmaps to build projection scenarios. Segmentation modeling spanned barrier architecture type, deposition technology, end-use application, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories and fab capacity expansion announcements. Industry-specific inputs included water vapor transmission rate specification evolution and fluoropolymer precursor supply concentration metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated perovskite solar commercialization or sudden ECHA fluorinated compound bans. Projections reflect assumptions about equipment localization timelines and regulatory alignment across jurisdictions. A small set of named triggers — EU AI Act hardware reliability mandates, India PLI scheme disbursement velocity, and phosphorescent OLED thermal budget thresholds — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Functional Acids Market
Functional Materials
Adaptive Camouflage Materials Market
Functional Materials
Flexible Thin Film Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Global Piezoelectric Smart Materials Market
Functional Materials
Asia-Pacific Lithium Foil Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Ferroelectric Materials Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Thin Film Materials Market
Functional Materials
Smart Card Materials Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Korea Personal Care Encapsulation Materials Market