
 Global Boron Trifluoride Methanol Complex Market | 2026-2036
Global Boron Trifluoride Methanol Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boron Trifluoride Methanol Complex Market Intelligence
Premium-grade boron trifluoride methanol complex is consolidating around semiconductor and pharmaceutical specifications, while commodity-grade product serves agricultural and bulk chemical applications. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply chains for electronics-grade material. Honeywell International Inc anchors North American availability through its specialty fluorine chemicals portfolio. Arkema SA differentiates via fluorinated intermediates expertise that extends into boron trifluoride derivatives.
Boron trifluoride methanol complex consists of boron trifluoride gas dissolved in methanol, typically at molar ratios between 1:1 and 1:2, forming a clear liquid reagent used primarily as a Lewis acid catalyst in esterification, alkylation, and polymerization reactions. The product requires anhydrous handling and stainless-steel containment due to corrosive hydrolysis products formed on moisture exposure. Liquid boron trifluoride and boron trifluoride complex variants dominate value generation, with the former capturing margin in electronics etching applications and the latter expanding fastest in pharmaceutical contract manufacturing. Packaged delivery mode commands premium pricing over bulk supply, reflecting hazardous-materials handling costs and just-in-time inventory requirements at customer sites.
EPA and OSHA frameworks govern workplace exposure limits and transportation classification for boron trifluoride methanol complex in the United States, while REACH registration obligations shape market access across European Union member states. China's SAMR enforces GB standards for imported specialty chemicals, creating compliance barriers for non-domestic producers. EMA pharmacopeial monographs increasingly reference boron trifluoride complex purity grades, tightening specifications for active pharmaceutical ingredient manufacturing. Stakeholders must monitor regulatory divergence between semiconductor-grade and industrial-grade specifications, as classification shifts could fragment supply chains and force dual-track qualification investments.
Market Dynamics
Semiconductor-grade purity requirements are bifurcating supply chains as pharmaceutical and electronics end-users diverge on specification tolerances, forcing producers to maintain dual qualification tracks for the same base chemical.
Growth Catalysts
- Peptide synthesis expansion:Pharmaceutical contract manufacturers are scaling boron trifluoride methanol complex consumption for therapeutic peptide production, with EMA pharmacopeial monographs validating catalyst-grade specifications for active pharmaceutical ingredient processes.
- REACH purity mandates:ECHA registration obligations for specialty chemical reagents are accelerating upgrades to anhydrous handling infrastructure, converting industrial-grade buyers to higher-tier formulations.
- Electronics etching demand:German semiconductor clusters in Dresden and Munich are absorbing premium-grade liquid boron trifluoride for wafer processing, tightening regional supply availability.
Market Restraints
- Fluorine feedstock volatility:Boron trifluoride gas production depends on fluorspar concentrate availability, with Chinese export quotas creating input cost instability for non-integrated European producers.
- Anhydrous logistics concentration:Stainless-steel tanker fleets and moisture-controlled packaging capabilities concentrate among three German chemical logistics providers, creating single-point failure risks for just-in-time pharmaceutical deliveries.
- Hydrolysis degradation:Moisture exposure during handling generates corrosive hydrogen fluoride and boric acid byproducts, limiting shelf life and requiring specialized containment that elevates delivered costs.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH quality guidelines is opening import pathways for European-certified boron trifluoride methanol complex into Mumbai and Hyderabad generic API hubs.
- Solid-phase peptide synthesis convergence:Automated synthesizer platforms are integrating boron trifluoride complex delivery systems, creating bundled equipment-chemical procurement contracts.
- EU Green Deal fluorine circularity:F-Gas Regulation amendments incentivize spent boron trifluoride recovery and reprocessing, enabling service-based revenue models for chemical distributors.
Industry Challenges
- Anhydrous handling certification:OSHA Process Safety Management compliance for boron trifluoride storage requires specialized technician training programs that face 18-month qualification backlogs at US pharmaceutical sites.
- Dual-track qualification investments:Semiconductor and pharmaceutical customers maintain non-overlapping purity specifications, forcing producers to duplicate analytical testing and quality documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boron Trifluoride Methanol Complex Market |
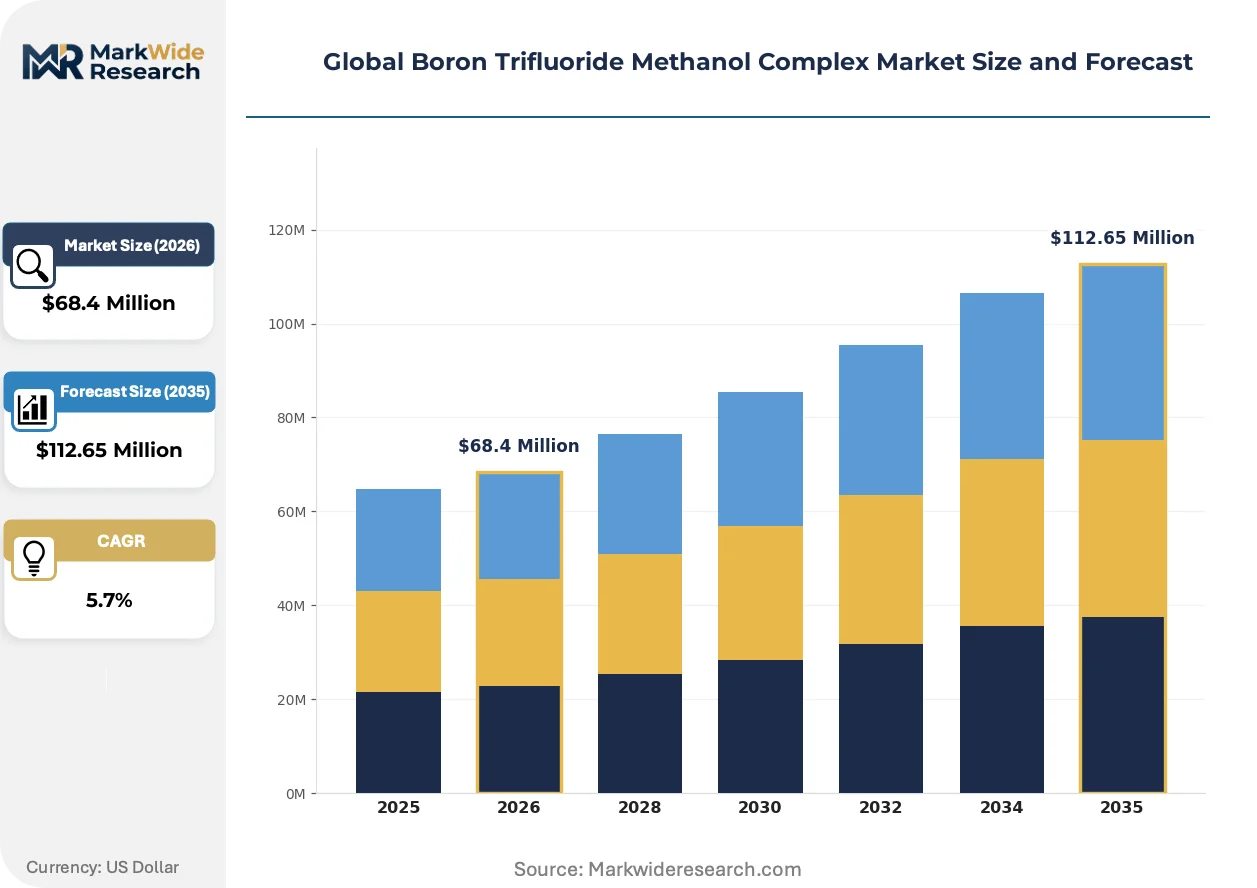
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $112.65 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Boron, Liquid Boron Trifluoride, Boron Trifluoride Gas, Boron Trifluoride Complex End Use Industry: Pharmaceuticals, Agriculture, Chemicals, Electronics Delivery Mode: Bulk, Packaged, On-site, Custom Solutions Packaging Type: Drums, Cylinders, IBCs, Totes |
| Companies Covered | BASF SE, Honeywell International Inc, Arkema SA, Navin Fluorine International Limited, Stella Chemifa Corporation, Gulbrandsen Chemicals, Voltaix LLC, Praxair Technology Inc, Tanfac Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boron Trifluoride Methanol Complex Market Strategic Shifts & Innovations
Modular production architectures and regulatory harmonization pressures are compressing traditional batch manufacturing economics while opening service-based revenue models for chemical distributors.
Pre-packaged boron trifluoride methanol complex in disposable fluoropolymer containers is modularizing pharmaceutical manufacturing workflows. Contract manufacturers in Switzerland and Germany are adopting these single-use formats to eliminate cleaning validation cycles between peptide synthesis campaigns. The format is modularizing facility design by removing fixed stainless-steel infrastructure from multi-product plants.
REACH registration dossiers for boron trifluoride derivatives are tightening substance identity definitions, forcing producers to disclose exact molar ratios and impurity profiles previously treated as proprietary. ECHA's 2023 updated guidance on complex substances requires full analytical characterization for continued market access. Electronics-grade suppliers in Ludwigshafen and Tokyo are responding by publishing certificate-of-analysis data directly to customer quality management systems.
Pharmaceutical buyers are consolidating catalyst procurement through integrated supply agreements that bundle boron trifluoride methanol complex with complementary reagents and technical support. Swiss CDMOs and German generic API producers are displacing spot-market purchasing with multi-year contracts featuring guaranteed allocation clauses. The shift is most visible in Basel and Frankfurt pharmaceutical clusters where supply security now outweighs unit price in vendor selection criteria.
Global Boron Trifluoride Methanol Complex Market Segmentation
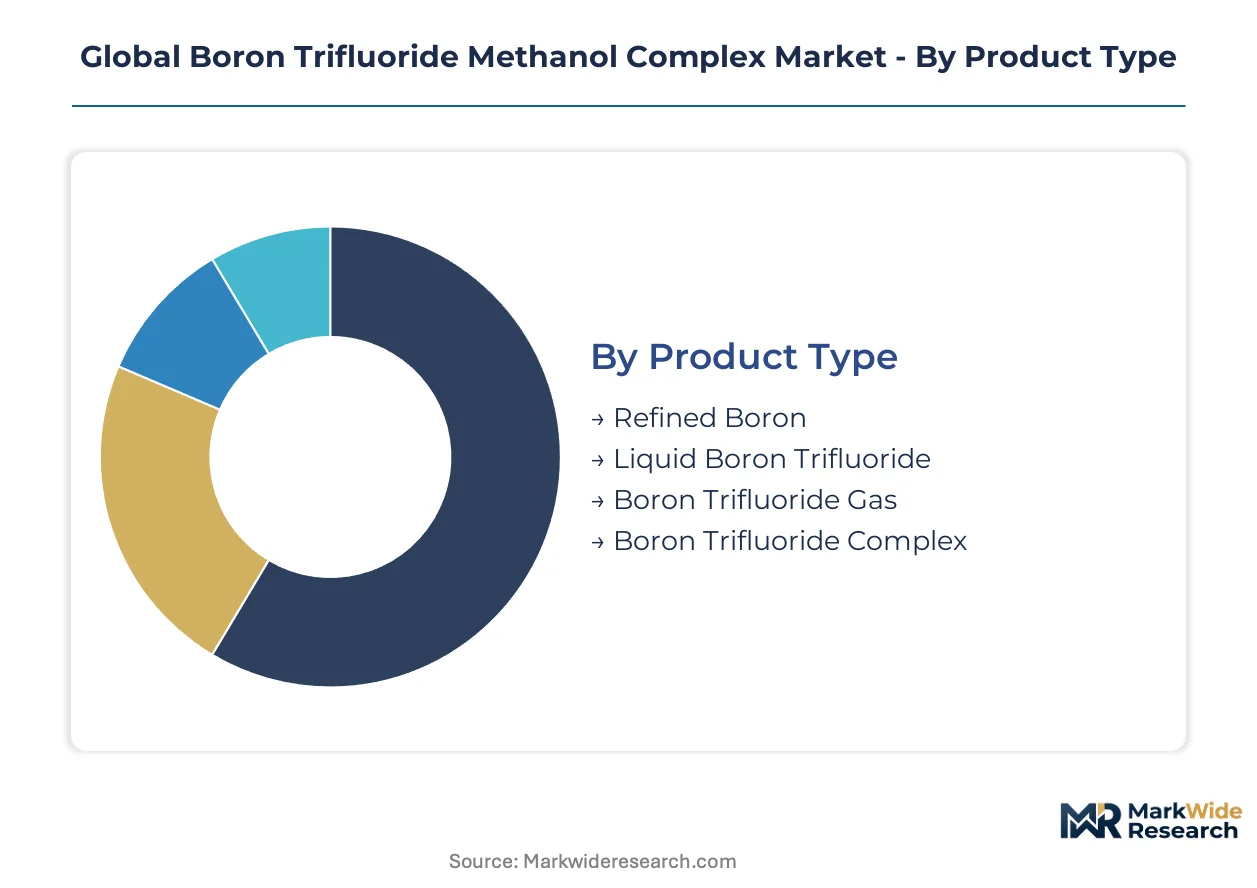
Boron trifluoride methanol complex serves divergent customer requirements across pharmaceutical synthesis, semiconductor etching, and agricultural chemistry. Specification tolerances, handling infrastructure, and regulatory compliance needs fragment procurement patterns into distinct purchasing tiers with non-overlapping vendor qualification tracks.
Product Type:
Purity thresholds and application criticality determine buyer willingness to pay premium spreads over commodity alternatives.
- Liquid Boron Trifluoride:Anhydrous liquid formulation at semiconductor-grade purity serves wafer etching operations in Dresden and Tokyo clusters. German electronics manufacturers absorb regional supply tightness to secure consistent specification compliance for sub-7nm processes.
- Boron Trifluoride Complex:Methanol-dissolved variant dominates pharmaceutical catalyst procurement, with EMA pharmacopeial monographs validating molar ratio specifications for peptide synthesis. Swiss CDMOs specify exact BF3:CH3OH stoichiometry in multi-year supply agreements.
- Refined Boron:Elemental boron feedstock for trifluoride gas generation concentrates among fluorspar-integrated producers.
- Boron Trifluoride Gas:Gaseous phase product supplies electronics etching and polymerization initiator applications with direct feed requirements.
Liquid boron trifluoride leads on scale; boron trifluoride complex leads on momentum.
End Use Industry:
Regulatory stringency and process criticality stratify demand across application verticals with divergent specification tolerances.
- Pharmaceuticals:Peptide synthesis and API intermediate production drives catalyst-grade consumption. EMA monographs and FDA guidance documents enforce certificate-of-analysis requirements that disqualify industrial-grade suppliers from therapeutic manufacturing contracts.
- Electronics:Semiconductor wafer processing demands parts-per-billion purity with moisture exclusion protocols. Tokyo and Munich fabrication clusters source through qualified distributors with stainless-steel cold chain capabilities.
- Chemicals:Polymerization and alkylation catalyst applications absorb commodity-grade volumes with broader specification windows.
- Agriculture:Boron nutrient formulations and pesticide intermediates represent price-sensitive demand with lower purity thresholds.
Pharmaceuticals leads on scale; electronics leads on momentum.
Delivery Mode:
Inventory carrying costs and handling infrastructure availability shape procurement format selection across customer scale tiers.
- Packaged:Pre-portioned containers in fluoropolymer or stainless-steel formats eliminate cleaning validation for pharmaceutical contract manufacturers. Swiss and German multi-product facilities adopt single-use formats to compress campaign changeover intervals.
- Bulk:Tanker delivery to captive storage serves high-volume chemical and electronics producers with dedicated handling infrastructure.
- On-site:Direct pipeline or dedicated tank systems support continuous-process semiconductor fabrication with zero inventory interruption tolerance.
- Custom Solutions:Blended formulations and private-label packaging address specialty chemical distributors serving fragmented regional demand.
Bulk leads on scale; packaged leads on momentum.
Packaging Type:
Moisture exclusion requirements and hazardous materials handling regulations constrain viable container formats across shipping distances.
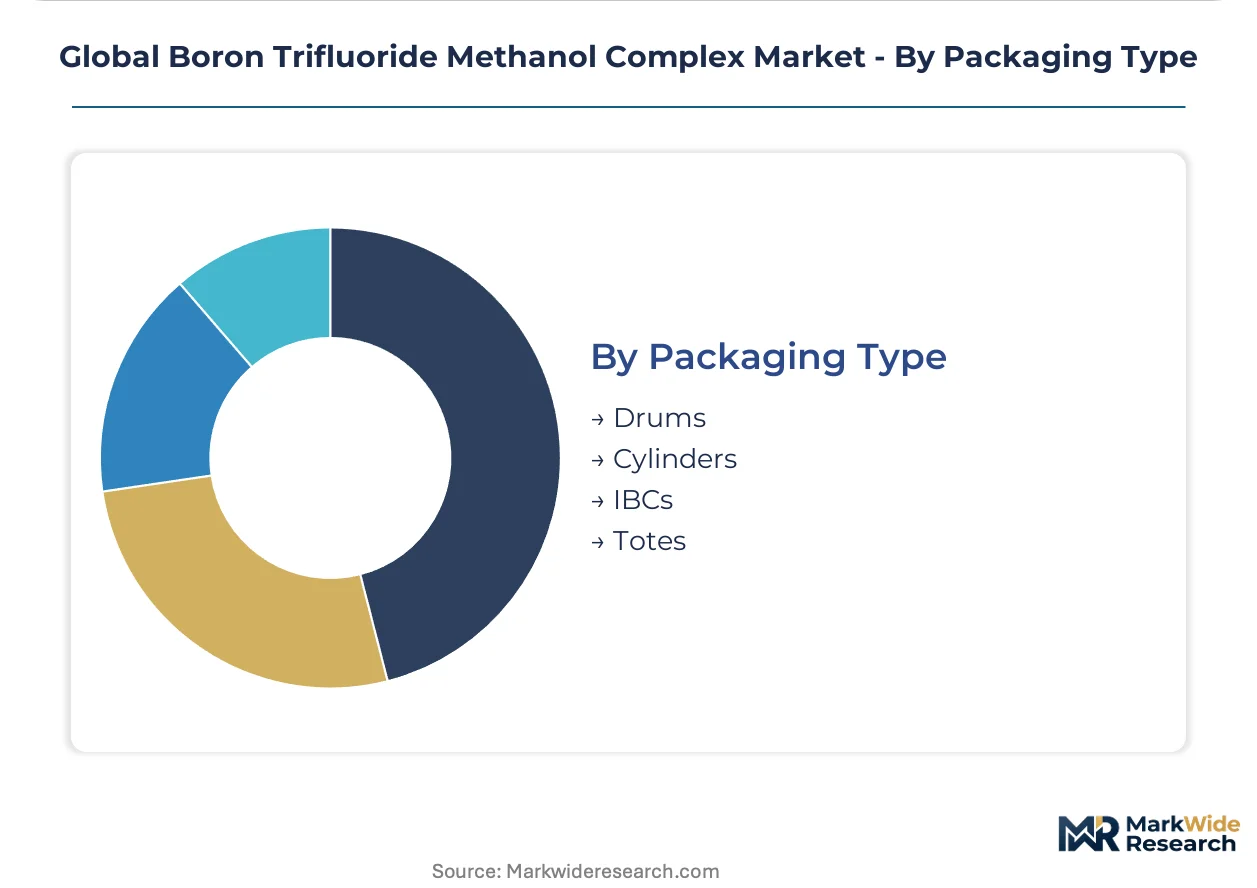
- Cylinders:High-pressure stainless-steel containment for gaseous and liquid-phase product serves electronics and specialty chemical customers. German logistics providers maintain cylinder fleets with pressure-testing certification under ADR transport rules.
- Drums:Standard steel or fluoropolymer-lined containers support mid-volume pharmaceutical and agricultural chemical distribution.
- IBCs:Intermediate bulk containers balance handling efficiency with moisture control for regional chemical manufacturer supply.
- Totes:Disposable fluoropolymer totes enable single-use pharmaceutical workflows without cleaning validation overhead.
Cylinders leads on scale; totes leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical technicians and fluorine-handling expertise concentrate in German industrial clusters, Japanese electronics corridors, and US Gulf Coast chemical hubs. These workforce pools anchor regional supply capabilities for moisture-sensitive reagents. Regulatory divergence across REACH, EPA, and SAMR frameworks fragments qualification requirements.
Germany
EMA pharmacopeial standards and F-Gas Regulation amendments drive pharmaceutical-grade purification investments. ECHA registration dossiers enforce full analytical characterization of boron trifluoride complex substances. Ludwigshafen and Dresden clusters sustain captive supply chains serving European peptide synthesis and semiconductor etching operations.
United States
OSHA Process Safety Management compliance and EPA hazardous materials frameworks govern anhydrous handling infrastructure. FDA guidance documents validate catalyst-grade specifications for therapeutic peptide manufacturing. Gulf Coast chemical corridors and Boston-area biotech clusters absorb packaged delivery formats for multi-product pharmaceutical facilities.
Japan
METI industrial policy and PMDA quality standards shape electronics-grade purity requirements for sub-7nm wafer processing. JIS certification protocols constrain viable supplier pools for moisture-critical reagents. Tokyo and Nagoya fabrication clusters source through qualified distributors with stainless-steel cold chain capabilities.
China
SAMR GB standards and NMPA pharmaceutical regulations create compliance barriers for imported specialty chemicals. MIIT industrial guidelines prioritize domestic fluorine chemical self-sufficiency. Yangtze River Delta pharmaceutical hubs and Beijing-Tianjin electronics corridors drive differentiated grade requirements.
India
CDSCO alignment with ICH quality guidelines opens import pathways for European-certified reagents into generic API manufacturing. DGFT trade frameworks and BIS standards govern specialty chemical market access. Mumbai and Hyderabad pharmaceutical clusters represent emerging demand concentrations for contract manufacturing catalysts.
Global Boron Trifluoride Methanol Complex Market Key Industry Players
Capital-heavy integrated producers compete with asset-light specialty distributors across moisture-controlled supply chains. The market structure concentrates around three German chemical conglomerates with captive fluorspar-to-derivative pipelines, supplemented by regional fluorine specialists in Asia and North America. Strategic archetypes include vertically integrated material science conglomerates, fluorochemical pure-plays with derivative expertise, and semiconductor-grade distributors with logistics certification. Dominant competitive moves encompass capacity expansion at Ludwigshafen-scale integrated sites and strategic partnerships bundling reagent supply with automated synthesizer platforms.
Among German-based integrated chemical producers, BASF SE anchors the premium electronics-grade segment through its Ludwigshafen site capabilities. Arkema SA exemplifies fluorinated intermediates specialization extending into boron trifluoride derivatives. Honeywell International Inc represents North American availability through specialty fluorine chemicals portfolio positioning. Japanese pure-play Stella Chemifa Corporation and Indian fluorochemical specialist Navin Fluorine International Limited occupy regional supply positions serving Asia-Pacific pharmaceutical and electronics clusters.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc |
| Arkema SA |
| Navin Fluorine International Limited |
| Stella Chemifa Corporation |
| Gulbrandsen Chemicals |
| Voltaix LLC |
| Praxair Technology Inc |
| Tanfac Industries Ltd |
| Others |
Cost & Logistics Intelligence
Captive fluorspar-to-derivative integration at Ludwigshafen-scale sites anchors supply positions while generating pricing power through specification-grade differentiation. ECHA registration obligations and OSHA Process Safety Management compliance create fixed-cost barriers that concentrate margin capture among qualified producers serving pharmaceutical and electronics clusters.
Pricing Analysis
Packaged single-use fluoropolymer containers versus bulk tanker delivery splits the market into service-bundled and commodity-transactional tiers. Three-tier pricing structure across semiconductor-grade, pharmaceutical-grade, and industrial-grade formulations reflects certificate-of-analysis complexity and moisture-handling infrastructure requirements. Cost compression in commodity-grade material intensifies because Chinese fluorspar export quotas feed input volatility. Agricultural chemical buyers exhibit highest price sensitivity, while semiconductor fabs accept premium spreads for parts-per-billion purity guarantees.
Supply Chain Analysis
Spent boron trifluoride recovery flows under EU Green Deal fluorine circularity incentives are emerging as reverse-logistics revenue streams for German chemical distributors. Production concentrates in Germany, Japan, and the United States where stainless-steel cold chain capabilities and anhydrous handling certification concentrate. Fluorspar concentrate, high-purity methanol, and specialized fluoropolymer packaging materials constitute critical input dependencies. Single-source vulnerability runs through three German chemical logistics providers controlling moisture-controlled tanker fleets. Distribution runs through qualified distributors with ADR-certified cylinder fleets serving just-in-time pharmaceutical manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-registered European supply and CDSCO-aligned Indian pharmaceutical demand exploits a regulatory compliance cost differential that favors import-dependent generic API hubs.
For Market Incumbents: Deploy capacity addition at captive fluorspar-integrated sites to outcompete non-integrated challengers facing feedstock volatility. Solid-phase peptide synthesis platform partnerships and automated synthesizer integration defend against specialty distributor disintermediation. EMA pharmacopeial monograph alignment and certificate-of-analysis data transparency reinforce switching costs among Swiss and German CDMOs. For New Entrants and Emerging Players: Modular pre-packaged fluoropolymer container technology offers a technology-first wedge into multi-product pharmaceutical facilities seeking cleaning validation elimination. Indian generic API manufacturing clusters represent the most penetrable geography given CDSCO-ICH alignment opening European-certified import pathways. Technical service bundling with peptide synthesis campaign support provides differentiated go-to-market positioning against commodity distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where dual-track qualification investments for semiconductor and pharmaceutical specifications strain mid-cap producer economics. Five-to-ten year viability favors fluorspar-integrated producers with Ludwigshafen-scale captive supply chains. Acquisition targets include regional fluorochemical specialists with ECHA registration dossiers and stainless-steel logistics certification. Monitor F-Gas Regulation amendment implementation and SAMR import license processing velocity as inflection indicators for circularity service model adoption and Chinese market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Feedstock | Captive concentrate supply from Chinese quota-constrained sources insulates margin from input volatility. |
| Single-Use Fluoropolymer Container Launch | Pre-packaged formats eliminate cleaning validation cycles for Swiss multi-product CDMO facilities. |
| EMA Pharmacopeial Monograph Alignment | Certificate-of-analysis transparency meets tightened substance identity definitions for continued EU market access. |
| Peptide Synthesis Platform Partnership | Automated synthesizer integration creates bundled equipment-chemical procurement contracts with guaranteed allocation clauses. |
| Spent Material Recovery Service | F-Gas Regulation incentives enable circularity-based revenue models for German chemical distributors. |
Research Approach
Bottom-up pharmaceutical and electronics end-use modeling reconciled against top-down fluorspar-to-derivative supply tracking forms the analytical core of this study. Primary interviews with peptide synthesis chemists, semiconductor process engineers, chemical procurement leads at CDMOs, and specialty fluorine distributors combined with secondary validation from ECHA registration dossiers, FDA guidance documents, SEC chemical segment filings, and customs trade flow data. Triangulation across these sources reconciles consumption estimates with production capacity disclosures.
Historical trendline analysis of specification-grade pricing spreads and volume shifts across the projection horizon informs the analytical framework. Segmentation dimensions modeled encompass purity grade tier, end-use industry vertical, packaging format type, and regional production hub cluster. CAGRs derive from slope analysis of segment-specific demand curves adjusted for regulatory compliance cost trajectories. Forecast inputs include fluorspar export quota announcements, EMA pharmacopeial monograph revision schedules, and semiconductor node transition timelines.
The model holds under stable REACH registration enforcement and F-Gas Regulation implementation; deviation in SAMR import licensing velocity or OSHA Process Safety Management inspection intensity would shift regional demand allocation. Forecasts reflect these base-case assumptions with sensitivity bands around feedstock cost volatility. Practitioners should monitor Chinese fluorspar export policy announcements and CDSCO ICH guideline adoption progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
FCC Catalyst Additive Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Industrial Catalyst Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Global Emission Control Catalyst (ECC) Market