
 Global Piezoelectric Smart Materials Market | 2026-2036
Global Piezoelectric Smart Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Piezoelectric Smart Materials Market Outlook
The performance gap between aerospace-grade piezoelectric ceramics and commodity sensor elements is broadening. CTS Corporation leverages its vertically integrated ceramic manufacturing to sustain premium positioning in medical imaging transducers. Murata Manufacturing Co., Ltd. anchors high-volume supply for consumer electronics with automated dielectric processing lines.
Piezoelectric smart materials convert mechanical stress into electrical charge through non-centrosymmetric crystal structures, typically exhibiting coupling coefficients above 0.5 for lead zirconate titanate compositions. These materials enable precision motion control, acoustic sensing, and vibration energy harvesting across industrial and medical systems. PZT formulations dominate structural applications due to their superior electromechanical coupling, while polymer-based alternatives capture flexible electronics demand where conformal geometries matter. Thin films command margin pools in MEMS fabrication, whereas bulk ceramics sustain actuator volumes in automotive fuel injection systems.
FDA device classifications shape biocompatibility requirements for implantable piezoelectric sensors in the United States, while REACH restrictions in Europe drive substitution research away from lead-containing compositions. Japan's METI promotes domestic piezoelectric material production through industrial technology roadmaps aligned with precision manufacturing targets. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
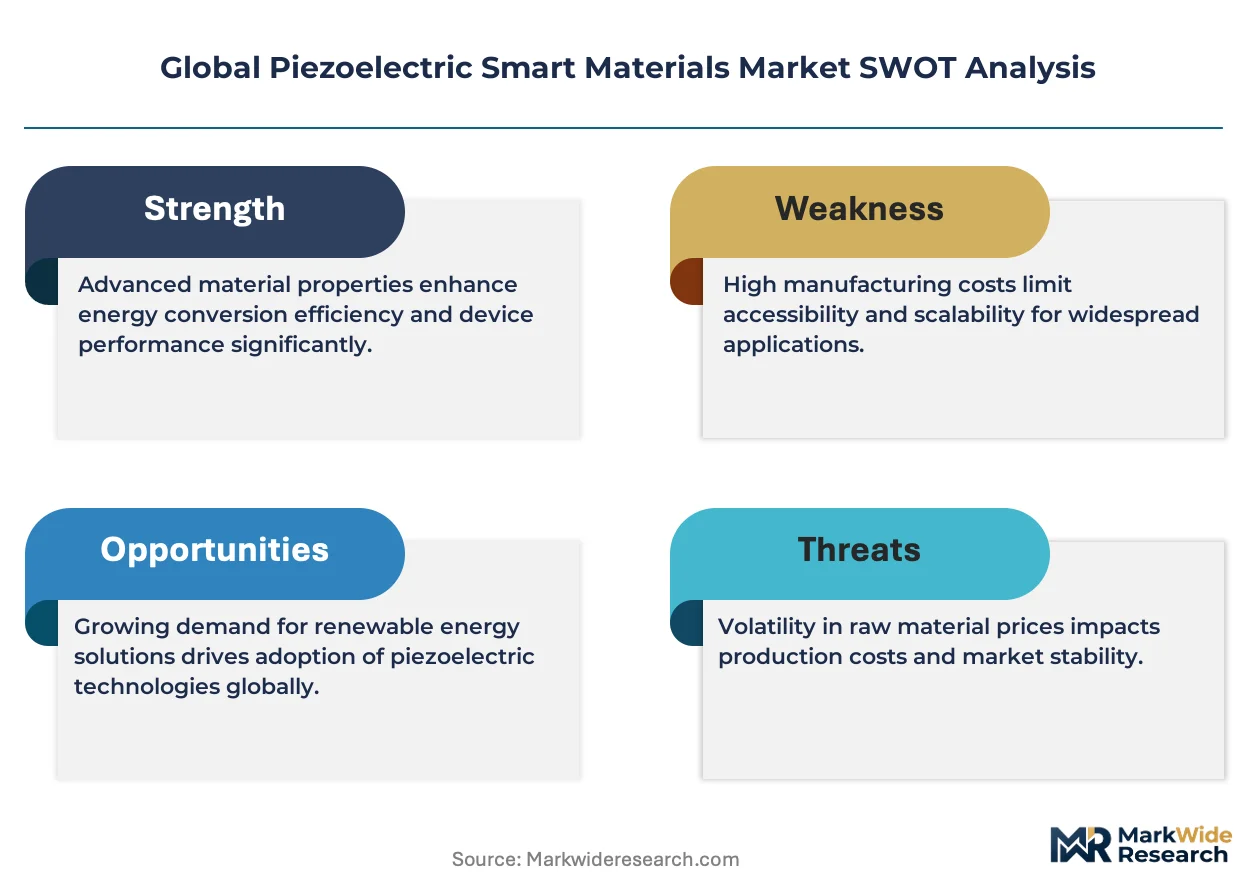
Automotive electrification is forcing piezoelectric material suppliers to requalify formulations for high-temperature inverter environments while simultaneously managing REACH-mandated lead substitution timelines.
Growth Catalysts
- EU Green Deal industrial targets:Ecodesign regulations mandate energy-efficient actuators in manufacturing equipment, expanding piezoelectric motor deployment across German and Italian automation clusters.
- MEMS fabrication scaling:Thin-film deposition advances enable wafer-level integration of piezoelectric layers, reducing sensor package heights for wearable health monitors.
- Japan's precision manufacturing concentration:Kyoto-Osaka industrial corridors sustain dense supplier networks for medical imaging transducers, compressing prototyping cycles for OEM partners.
Market Restraints
- Lead oxide supply volatility:PZT precursor materials face price instability from concentrated Chinese rare earth processing, squeezing margin pools for commodity ceramic producers.
- Polymer piezoelectric performance ceiling:PVDF-TrFE copolymers exhibit electromechanical coupling below 0.3, limiting displacement output for precision positioning stages.
- REACH substance restriction timelines:ECHA candidate list expansions accelerate reformulation costs for European manufacturers ahead of sunset dates.
Strategic Opportunities
- India's medical device PLI scheme:Domestic production incentives for diagnostic equipment create captive demand for ultrasound transducer assemblies.
- Vibration energy harvesting convergence:Integration with IoT sensor nodes enables self-powered industrial condition monitoring in remote infrastructure.
- Direct OEM contracting channels:Tier-1 automotive suppliers are bypassing distributor networks for long-term piezoelectric actuator supply agreements.
Industry Challenges
- PhD-level materials science talent scarcity:Formulation chemistry expertise concentrates in Japanese and German research institutes, constraining R&D scaling for mid-cap competitors.
- FDA 510(k) clearance timelines:Implantable piezoelectric sensor submissions face 18-24 month review cycles, delaying revenue recognition for cardiovascular monitoring applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Piezoelectric Smart Materials Market |
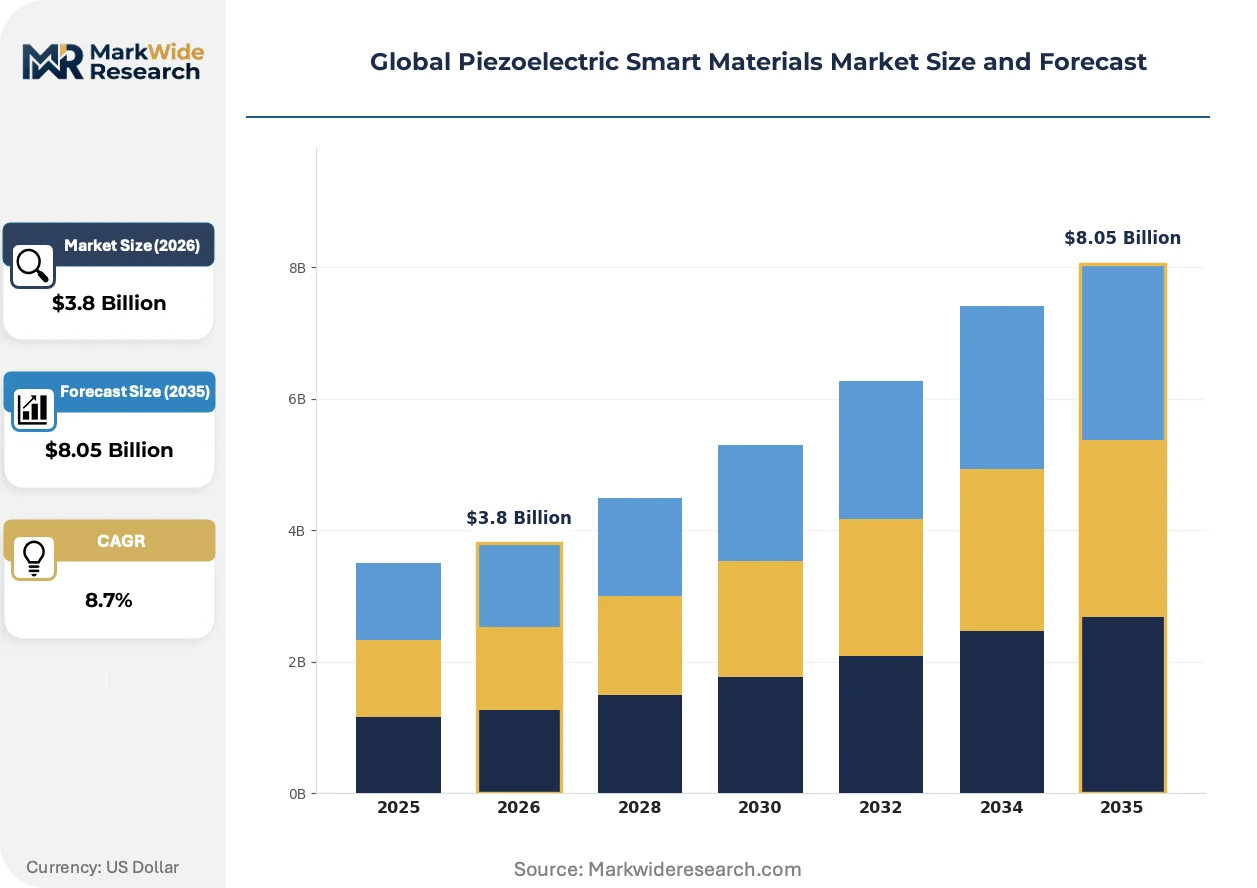
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PZT, Polymer-Based, Quartz, Ceramics Application: Energy Harvesting, Sensors, Actuators, Medical Devices End User: Aerospace, Automotive, Healthcare, Consumer Electronics Form Factor: Thin Films, Bulk Materials, Composites, Fibers |
| Companies Covered | CTS Corporation, PI (Physik Instrumente), Murata Manufacturing Co., Ltd., Arkema Group, CeramTec GmbH, TDK Corporation, APC International, Ltd., QorTek, Inc., Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Piezoelectric Smart Materials Market Strategic Shifts
Material science breakthroughs are compressing the performance gap between established PZT ceramics and emerging lead-free alternatives while regulatory pressure accelerates substitution investments.
Aluminum nitride thin-film deposition is electrifying MEMS resonator fabrication through sputtering process refinements that achieve piezoelectric coefficients approaching bulk ceramic values. Apple and Samsung procurement teams are qualifying AlN-based RF filters for 5G handset subsystems at volumes exceeding 500 million units annually. This electrifying adoption curve is compressing incumbent ceramic resonator margins while creating captive demand for high-purity aluminum sputtering targets.
REACH Annex XVII lead restrictions are forcing European piezoelectric manufacturers to accelerate bismuth sodium titanate and potassium sodium niobate formulation development ahead of 2027 sunset review deadlines. BASF and CeramTec have redirected R&D budgets toward alkaline niobate compositions despite 15-20% electromechanical coupling penalties versus conventional PZT. Medical imaging transducer suppliers in Germany face the steepest compliance costs due to stringent biocompatibility layering requirements atop material substitution.
Japanese automotive OEMs are consolidating piezoelectric fuel injector actuator procurement through keiretsu-affiliated trading houses, displacing open-market spot purchasing with 7-year framework agreements. Denso and Hitachi Automotive Systems are capturing volume commitments from Toyota and Honda that lock in 80% of domestic piezoelectric stack demand. This concentration is visible across Aichi and Shizuoka prefectures where supplier parks co-locate ceramic pressing and electrode firing operations.
Global Piezoelectric Smart Materials Market Segmentation
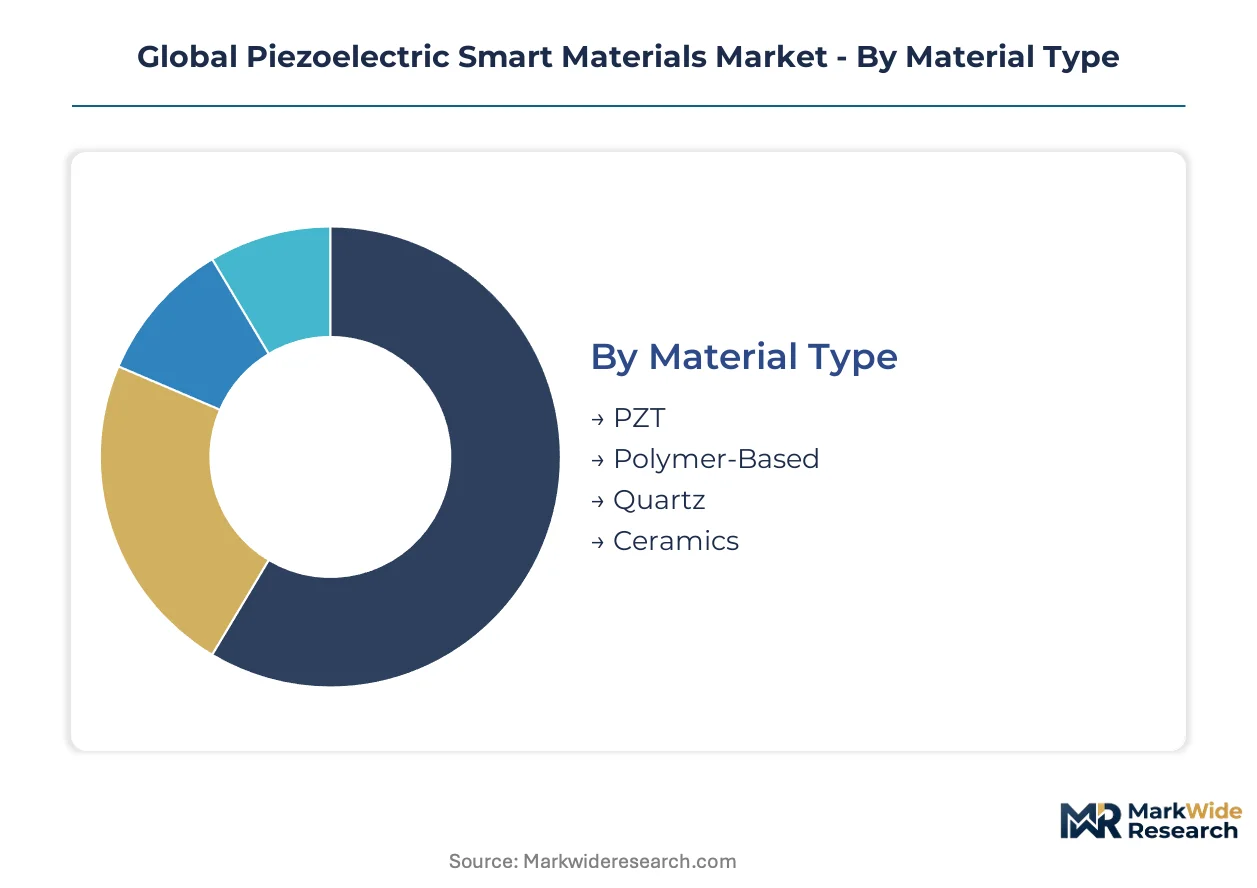
Piezoelectric smart materials fragment across material chemistry, physical form, and application intensity, with upgrade cycles varying from 3-year consumer electronics refresh rates to 15-year infrastructure actuator deployments. Procurement teams must align supplier qualification timelines with these divergent replacement horizons.
Material Type:
Replacement cycles stretch from annual polymer formulation tweaks to decade-long ceramic composition lock-ins for qualified medical devices.
- PZT:Lead zirconate titanate compositions deliver electromechanical coupling coefficients exceeding 0.5, sustaining dominance in precision positioning stages and automotive fuel injectors. Demand clusters in Japan's Aichi prefecture supplier parks where Denso and Hitachi Automotive Systems anchor procurement through keiretsu frameworks.
- Polymer-Based:PVDF-TrFE copolymers enable conformal geometries for wearable health monitors and flexible acoustic sensors, though coupling coefficients below 0.3 constrain displacement output. Adoption accelerates in South Korean consumer electronics supply chains where Samsung procurement teams qualify thin-film deposition for 5G handset subsystems.
- Quartz:Single-crystal oscillators maintain frequency stability for telecommunications infrastructure and precision timing equipment. CTS Corporation leverages captive quartz processing for aerospace-grade resonator supply.
- Ceramics:Non-PZT alkaline niobate formulations address REACH-mandated lead substitution timelines, with BASF and CeramTec redirecting R&D budgets despite performance penalties.
Volume placements concentrate in PZT; the faster expansion belongs to polymer-based alternatives.
Application:
Application intensity correlates with regulatory burden—medical devices face 18-24 month FDA 510(k) cycles while energy harvesting operates outside device classification frameworks.
- Energy Harvesting:Vibration-to-electric conversion enables self-powered IoT sensor nodes for industrial condition monitoring in remote infrastructure. Deployment concentrates in German automation clusters where EU Green Deal ecodesign mandates accelerate actuator electrification.
- Sensors:Pressure, acceleration, and acoustic sensing dominate automotive safety systems and consumer electronics. Murata Manufacturing Co., Ltd. anchors high-volume supply with automated dielectric processing lines in Kyoto-Osaka corridors.
- Actuators:Precision motion control drives demand from semiconductor lithography and optical alignment systems. Japanese automotive OEMs consolidate procurement through 7-year framework agreements displacing spot purchasing.
- Medical Devices:Ultrasound transducers and implantable sensors face layered biocompatibility requirements atop material composition constraints. Germany's medical imaging suppliers absorb steepest compliance costs from REACH Annex XVII restrictions.
Sensor volumes dominate current procurement; medical devices are climbing the fastest amid diagnostic equipment expansion.
End User:
End-user concentration determines margin structure—automotive volumes trade at compressed pricing while aerospace qualifications sustain premium positioning.
- Aerospace:Structural health monitoring and vibration control systems require MIL-STD-810G environmental qualification. CTS Corporation sustains premium positioning through vertically integrated ceramic manufacturing.
- Automotive:Fuel injection actuators and knock sensors drive commodity-scale demand with tight OEM cost-down schedules. Toyota and Honda lock in 80% of Japanese domestic piezoelectric stack demand through keiretsu-affiliated trading houses.
- Healthcare:Diagnostic imaging and therapeutic ultrasound sustain pricing power through regulatory moats. India's PLI scheme for medical devices creates captive demand for transducer assembly localization.
- Consumer Electronics:MEMS microphones and haptic feedback modules operate at wafer-scale integration with 500 million-unit annual RF filter qualification cycles. Apple and Samsung procurement teams drive aluminum nitride thin-film adoption for 5G subsystems.
Automotive procurement represents the largest volume commitment; healthcare applications gain share fastest on diagnostic infrastructure buildouts.
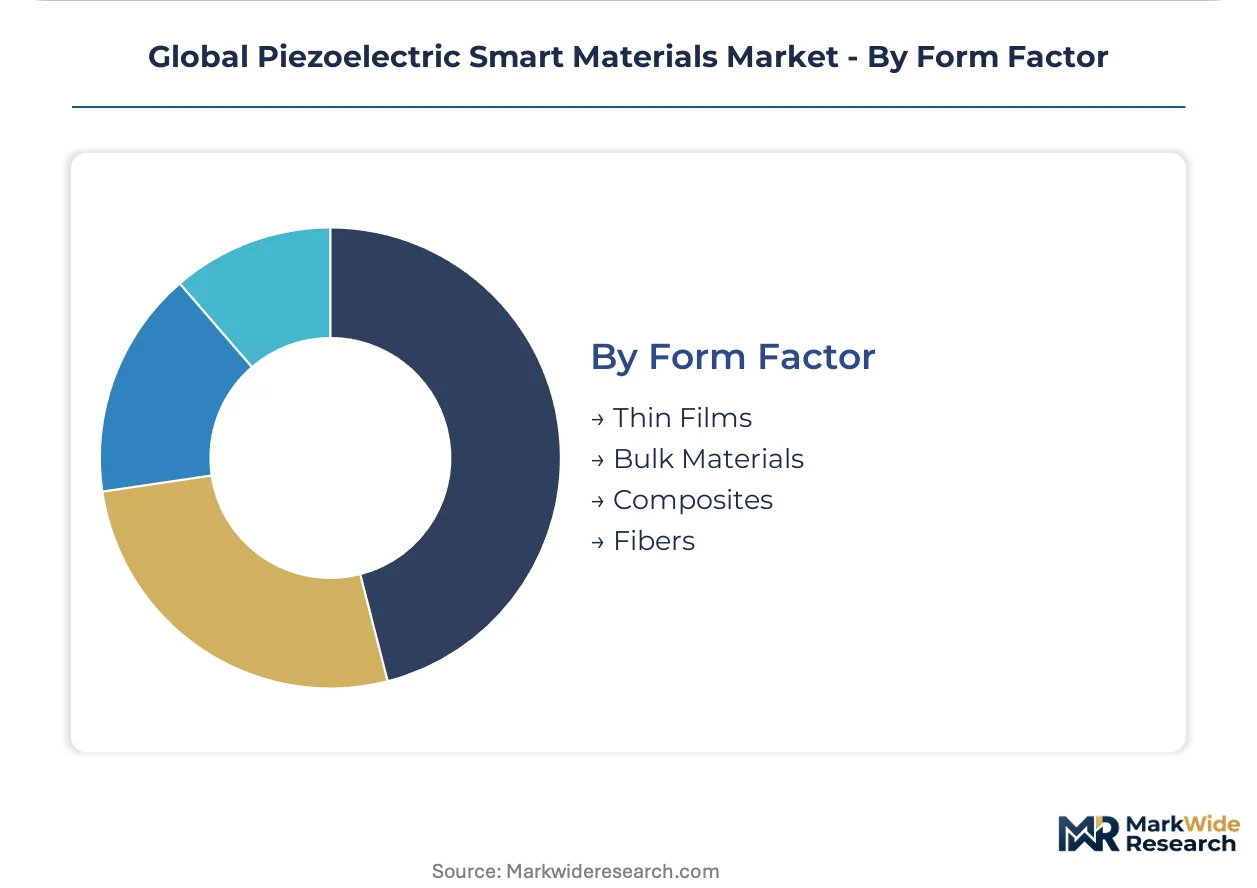
Form Factor:
Form factor selection hinges on integration density—thin films enable wafer-level MEMS fabrication while bulk materials sustain high-force actuator applications.
- Thin Films:Sputtered aluminum nitride and PZT layers achieve sub-micron precision for resonators and energy harvesters. Apple and Samsung procurement exceeds 500 million units annually for RF filter subsystems.
- Bulk Materials:Pressed and sintered ceramic stacks deliver displacement force for industrial positioning and automotive injection systems. Supplier parks in Japan's Shizuoka prefecture co-locate pressing and electrode firing operations.
- Composites:Piezoelectric ceramic-polymer matrices balance stiffness and conformability for structural health monitoring. Demand concentrates in aerospace airframe applications.
- Fibers:Piezoelectric textile integration enables wearable sensing and energy harvesting in smart clothing. South Korean textile-electronics convergence drives pilot production scaling.
Bulk materials retain the largest installed base; thin films are expanding most quickly on MEMS fabrication scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kyoto-Osaka industrial corridors anchor precision manufacturing density for medical imaging transducers, while regulatory divergence across three continents reshapes material formulation roadmaps.
United States
FDA 510(k) clearance timelines for implantable sensors stretch 18-24 months, compressing revenue recognition cycles for cardiovascular monitoring applications. EPA and OSHA standards govern ceramic processing emissions in industrial actuator manufacturing. Boston and Minneapolis medical device clusters concentrate ultrasound transducer R&D alongside major diagnostic OEM headquarters.
Germany
ECHA REACH Annex XVII lead restrictions force alkaline niobate reformulation despite 15-20% electromechanical coupling penalties against conventional PZT. EU Green Deal ecodesign regulations mandate energy-efficient actuators across German automation clusters. Stuttgart and Munich supplier parks absorb steepest compliance costs from layered biocompatibility requirements atop material substitution mandates.
Japan
METI industrial technology roadmaps promote domestic piezoelectric material production aligned with precision manufacturing targets. Toyota and Honda lock in 80% of domestic piezoelectric stack demand through keiretsu-affiliated trading houses displacing spot purchasing. Aichi and Shizuoka prefectures co-locate ceramic pressing and electrode firing operations in dense supplier parks.
China
Rare earth processing concentration for PZT precursor materials creates price volatility squeezing margin pools for commodity ceramic producers. MIIT and GB standards govern piezoelectric component quality in automotive and telecommunications applications. Yangtze River Delta manufacturing zones concentrate MEMS fabrication scaling for consumer electronics subsystems.
India
PLI scheme production incentives for diagnostic equipment generate captive demand for ultrasound transducer assembly localization. CDSCO medical device regulations shape biocompatibility certification pathways for implantable sensors. Bengaluru and Hyderabad precision manufacturing corridors attract component suppliers serving domestic diagnostic infrastructure buildouts.
Global Piezoelectric Smart Materials Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and formulation chemistry specialization. The vendor base stratifies into three tiers: vertically integrated ceramic manufacturers capturing aerospace and medical qualifications, high-volume dielectric processors serving consumer electronics scale, and regional compounders supplying automotive commodity actuators. Dominant competitive moves include backward integration into precursor material processing and long-term framework contracting displacing distributor networks.
Among Japan-based fabricators, Murata Manufacturing Co., Ltd. and Kyocera Corporation exemplify scale-driven dielectric processing archetypes, while CeramTec GmbH represents European specialization in REACH-compliant ceramic formulation. CTS Corporation anchors North American presence through vertically integrated quartz and ceramic manufacturing. These named entities occupy positions across the premium-to-commodity spectrum without implying specific strategic actions or financial performance.
| Leading Market Players |
|---|
| CTS Corporation |
| PI (Physik Instrumente) |
| Murata Manufacturing Co., Ltd. |
| Arkema Group |
| CeramTec GmbH |
| TDK Corporation |
| APC International, Ltd. |
| QorTek, Inc. |
| Kyocera Corporation |
| Others |
Value Chain & Pricing Dynamics
The aerospace-medical certification gap against automotive commodity supply creates a two-speed pricing architecture where qualification intensity determines margin capture. REACH Annex XVII compliance costs in Europe and FDA 510(k) timelines in the United States force premium pricing for qualified formulations, while keiretsu-locked volumes in Japan compress spot-market pricing for uncommitted automotive stacks.
Pricing Analysis
Yield-guaranteed actuator performance anchors value-based pricing for precision positioning stages in semiconductor lithography. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810G aerospace qualifications from automotive commodity knock sensors and consumer electronics haptic modules. Price differentiation rests on electromechanical coupling coefficients and biocompatibility certification tiers. Cost compression in automotive commodity ceramics is intensifying because Toyota and Honda keiretsu frameworks displace open-market procurement. Consumer electronics buyers exhibit highest price sensitivity due to wafer-scale integration and 500 million-unit annual qualification cycles.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for medical devices are reshaping sourcing patterns for ultrasound transducer assemblies. Raw material supply concentrates in China for rare earth PZT precursors, Japan for high-purity aluminum sputtering targets, and Germany for REACH-compliant alkaline niobate formulations. Critical dependencies include lead oxide from concentrated Chinese processing, ceramic pressing equipment from Japanese suppliers, and high-purity gases for thin-film deposition. Single-source vulnerability in rare earth processing creates price volatility squeezing margin pools for commodity ceramic producers. Distribution runs through keiretsu-affiliated trading houses in Japan, direct OEM contracting channels in automotive, and distributor networks for medical device qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII sunset deadlines erect a cost-of-compliance barrier that rewards pre-qualified European ceramic formulators while forcing reformulation investments on laggards. ECHA candidate list expansions accelerate capital requirements ahead of restriction timelines, consolidating advantage among players with existing alkaline niobate development pipelines.
For Market Incumbents: To counter keiretsu procurement concentration displacing open-market volumes, CTS Corporation and CeramTec should deepen backward integration into precursor material processing and secure long-term framework agreements with Tier-1 automotive suppliers. Captive supply of high-purity aluminum sputtering targets and in-house ceramic pressing operations defend margin pools against commodity price volatility from Chinese rare earth concentration.
For New Entrants and Emerging Players: Aluminum nitride thin-film deposition for 5G RF filters offers the most penetrable technology-first entry point given Apple and Samsung procurement volumes exceeding 500 million units annually. India's medical device PLI scheme creates white-space demand for domestic ultrasound transducer assembly. A materials-science-specialist positioning with PhD-level formulation chemistry capabilities enables differentiation against scale-driven incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists holding aerospace and medical qualifications given FDA 510(k) backlog compression and REACH substitution timelines. Long-term viability over the next decade favors players with captive ceramic manufacturing and established biocompatibility certifications. Watch ECHA candidate list expansion velocity as the inflection signal for reformulation cost acceleration and consolidation pressure on unprepared commodity producers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Development | BASF and CeramTec R&D redirection toward alkaline niobate addresses 15-20% coupling penalties versus PZT. |
| Keiretsu Framework Contracting | Denso and Hitachi Automotive Systems capture 80% of Japanese domestic piezoelectric stack demand through Toyota and Honda alliances. |
| Thin-Film Deposition Scaling | Aluminum nitride sputtering process refinements enable wafer-level MEMS integration for 5G handset subsystems. |
| Backward Integration into Precursors | Captive processing of high-purity aluminum targets and rare earth supply hedges against Chinese concentration risk. |
| Medical Device PLI Localization | India's production incentives for diagnostic equipment generate captive demand for ultrasound transducer assembly. |
Study Parameters
Trade databases, regulatory filings with ECHA and FDA, and industry association reports formed the secondary backbone for this analysis. Primary interviews with ceramic formulation chemists, medical device procurement managers at diagnostic OEMs, Tier-1 automotive supplier sourcing leads, and MEMS fabrication engineers validated demand assumptions and substitution timelines. Bottom-up volume estimates across material type, application, and form factor segments were triangulated against top-down market sizing from customs data and production capacity disclosures.
Historical trendline analysis of automotive sensor integration rates, MEMS fabrication scaling curves, and medical imaging equipment shipments informed the projection framework. Segmentation dimensions modeled include material chemistry, physical form factor, application intensity, and end-user concentration across aerospace, automotive, healthcare, and consumer electronics verticals. CAGRs were derived from regression analysis of adoption curves and regulatory deadline impacts. Industry-specific forecast inputs incorporated REACH Annex XVII substitution timelines and Japan METI industrial technology roadmap targets.
Several conditions sit outside the modeled scope, including unforeseen raw material supply disruptions, accelerated ECHA restriction timelines, and breakthrough lead-free compositions eliminating performance penalties. Forecasts reflect documented assumptions about keiretsu procurement stability and medical device qualification pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Materials
Flexible Thin Film Market
Functional Materials
Global Smart Material Market
Functional Materials
Thin-Film Encapsulation Market
Functional Materials
Functionalized Nanocomposites Market
Functional Materials
Energy Efficient Materials Market
Functional Materials
Global Thin Film Coatings Market
Functional Materials
Functional Acids Market
Functional Materials
Rapid Self-Healing Gel Market
Functional Materials
Potassium Tetrafluoroborate Market
Functional Materials
Functional Additives and Barrier Coatings Market
Functional Materials
Thin Film Materials Market
Functional Materials
Global Positive Material Identification Market
Functional Materials
Global Thin and Ultra-Thin Films Market
Functional Materials
UHMWPE for Li-Battery Market
Functional Materials
Korea Personal Care Encapsulation Materials Market
Functional Materials
Adaptive Camouflage Materials Market