
 Potassium Hydrogen Sulfite Market | 2026-2036
Potassium Hydrogen Sulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydrogen Sulfite Market Analytics
Clean-label reformulation pressure is rewriting how food manufacturers select preservation chemistries, pushing sulfite suppliers toward transparent supply chains and third-party certifications. BASF SE leverages its European distribution network to supply German and French wine producers with certified food-grade material. Murphy and Son Ltd. anchors its position in UK brewing through specialized liquid delivery formats tailored to craft brewery specifications.
Potassium hydrogen sulfite is a potassium salt of sulfurous acid with the chemical formula KHSO3, typically supplied as a white crystalline solid or aqueous solution containing 45-50% active sulfite content; manufacturers produce it via absorption of sulfur dioxide in potassium carbonate solution for use as an oxygen scavenger, antimicrobial agent, and reducing agent across food, chemical, and water treatment industries. Food-grade powder dominates current revenue as bakery and beverage processors standardize on dry-blend compatibility, while pharmaceutical-grade material commands premium positioning due to stringent USP monograph compliance and limited qualified suppliers. Water treatment applications represent the fastest-expanding segment as municipal utilities in industrial corridors adopt sulfite-based dechlorination to protect downstream membrane systems.
USDA organic labeling standards and FDA food additive regulations in the United States, alongside REACH chemical registration requirements in Europe, collectively restrict non-compliant sulfite sources and elevate documentation burdens for cross-border suppliers. India's FSSAI has tightened preservative maximum limits in processed foods, redirecting domestic demand toward certified industrial-grade imports for non-food chemical applications. Stakeholders must monitor evolving sulfite threshold adjustments across national food safety regimes to anticipate grade-mix shifts before procurement cycles lock in.
Market Dynamics
Clean-label reformulation mandates from EFSA are forcing food processors to abandon synthetic antioxidants, redirecting procurement toward certified sulfite-based alternatives with full supply-chain traceability documentation.
Growth Catalysts
- EFSA Additive Regulations:Tightening restrictions on synthetic antioxidants in processed foods are accelerating sulfite substitution across European bakery and beverage manufacturing.
- Membrane Protection Demand:Municipal utilities in industrial corridors are adopting sulfite-based dechlorination to safeguard reverse osmosis and nanofiltration infrastructure.
- Wine Export Quality Standards:German and French producers require food-grade potassium hydrogen sulfite to meet third-party certification requirements for premium export markets.
Market Restraints
- Sulfur Dioxide Feedstock Volatility:Energy-intensive sulfur recovery processes expose producers to natural gas price swings that compress margin structures.
- Qualified Supplier Concentration:USP monograph compliance for pharmaceutical-grade material limits viable sources to a narrow base of certified European manufacturers.
- Peroxyacid Substitution Threat:Non-sulfite oxygen scavengers are gaining traction in sensitive flavor applications where residual sulfur compounds create taste interference.
Strategic Opportunities
- Indian Industrial-Grade Pivot:FSSAI tightening of preservative maximum limits is redirecting domestic sulfite demand toward certified imports for chemical synthesis and water treatment.
- REACH Registration Tailwind:Comprehensive chemical dossier requirements create compliance barriers that favor established European sulfite producers with existing registration portfolios.
- Liquid Delivery Format Expansion:Craft brewery specifications for specialized aqueous solutions open channel innovation beyond traditional powder distribution.
Industry Challenges
- Analytical Chemist Scarcity:Specialized sulfite assay expertise for USP and food-grade certification creates recruitment bottlenecks at quality control laboratories.
- Cross-Border Documentation Burden:Divergent national sulfite threshold adjustments require continuous regulatory monitoring to prevent procurement cycle misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydrogen Sulfite Market |
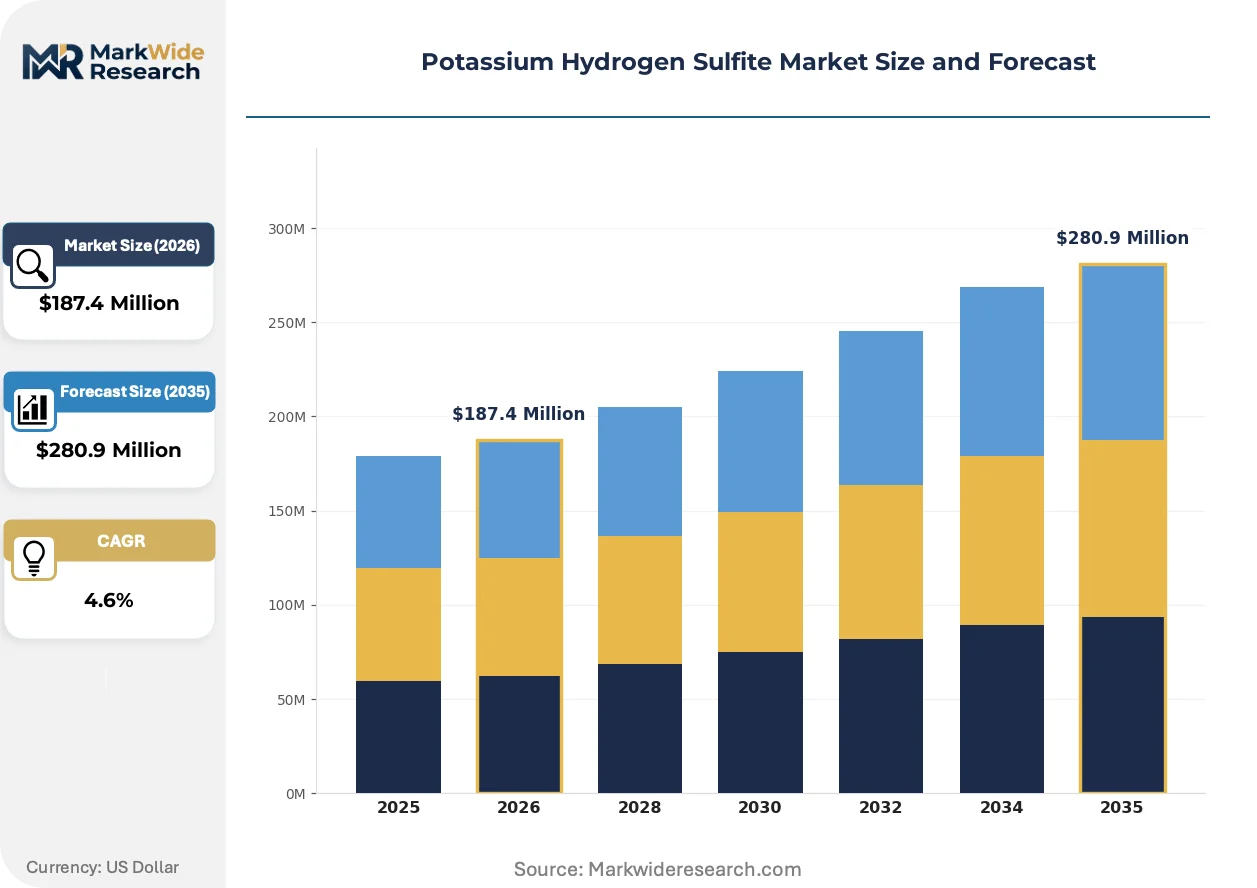
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Application: Food Preservation, Water Treatment, Chemical Manufacturing, Photography End User: Food Industry, Cosmetics, Pharmaceuticals, Waste Management Delivery Mode: Liquid, Solid, Powder, Granular |
| Companies Covered | ESSECO Srl, Occidental Chemical Corp., Aditya Birla Chemicals, Murphy and Son Ltd., Jay Dinesh Chemicals, Avantor Inc., Hydrite Chemical Co., TNJ Chemical Industry Co. Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydrogen Sulfite Market Evolving Landscape
Digital traceability platforms are rewriting supplier-buyer relationships in sulfite procurement, with blockchain-enabled certification verification becoming a non-negotiable requirement for premium food-grade contracts.
Continuous sulfite monitoring systems using electrochemical sensors are virtualizing quality assurance workflows for large-scale beverage processors. German wineries and UK breweries deploy these sensors for real-time dissolved oxygen and residual sulfite tracking. The technology is virtualizing laboratory testing schedules, compressing batch release timelines from days to hours while reducing analytical labor overhead.
REACH chemical registration requirements in Europe are elevating documentation burdens for cross-border suppliers while restricting non-compliant sulfite sources from market access. Industrial buyers now require full substance data sheet transparency extending through three supply tiers. Pharmaceutical-grade material faces the steepest compliance escalation, with limited qualified suppliers capturing premium positioning.
Consolidated procurement desks at multinational food processors are unbundling after-sales technical service from base chemical supply contracts. Buyers now source potassium hydrogen sulfite through centralized tenders while engaging separate formulation consultants for application support. This pattern is most visible in Germany, where brewery technical teams have decoupled sulfite procurement from Murphy and Son's traditional liquid delivery advisory services.
Potassium Hydrogen Sulfite Market Segmentation
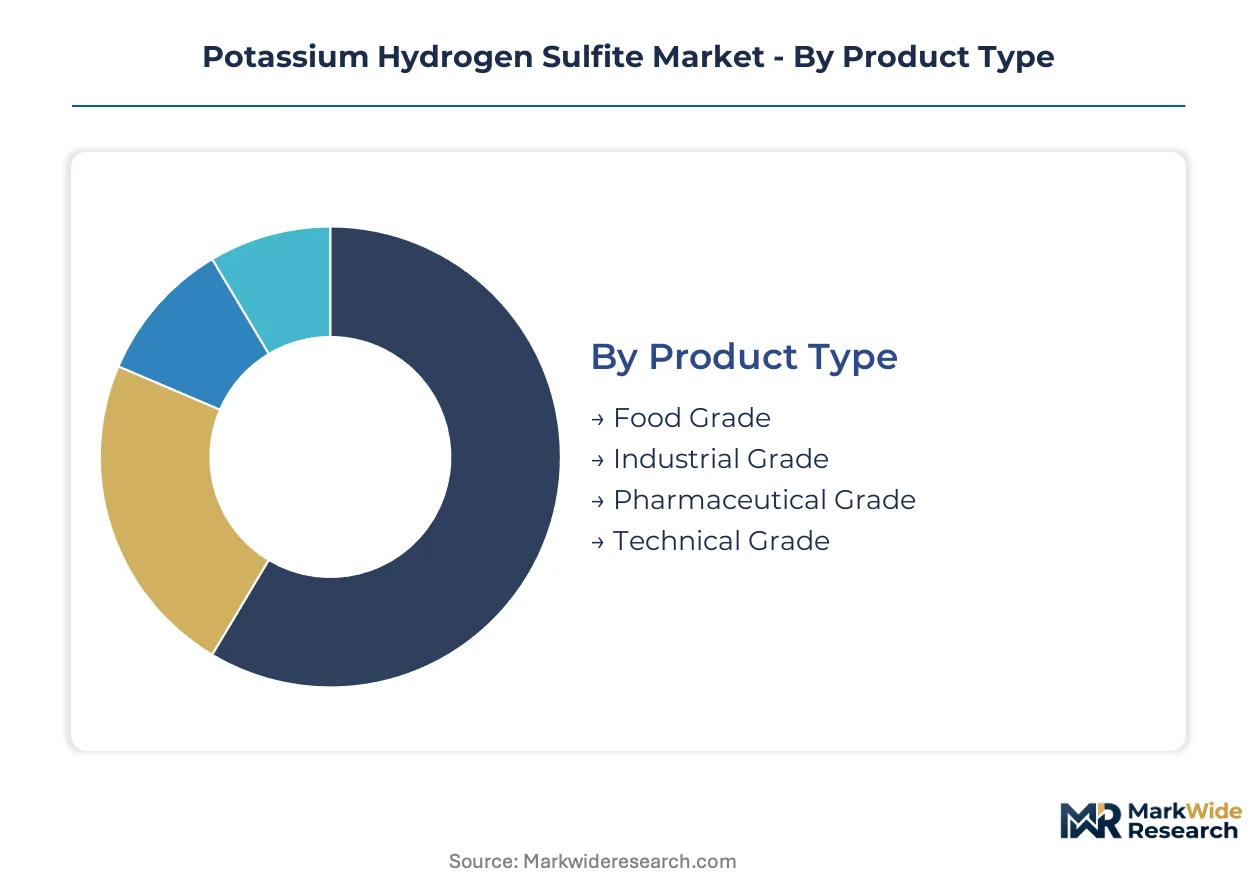
Potassium hydrogen sulfite procurement patterns diverge sharply across certification tiers, application chemistries, and physical delivery formats. Food-grade specifications anchor current revenue concentration, while industrial-grade volumes accelerate in water treatment corridors. Understanding these segment boundaries enables suppliers to align production capacity with diverging compliance burdens and formulation requirements.
Product Type:
Certification grade determines pricing architecture, documentation depth, and qualified supplier pools across downstream verticals.
- Food Grade:White crystalline material meeting EFSA additive specifications for sulfite content and heavy metal limits. German wineries and French bakery chains drive procurement of certified lots with full supply-chain traceability documentation under tightening clean-label mandates.
- Industrial Grade:Standardized material for chemical synthesis and water treatment applications with reduced assay requirements. Indian municipal utilities and chemical manufacturers absorb expanding volumes as FSSAI restrictions redirect domestic sulfite demand away from food applications.
- Pharmaceutical Grade:USP monograph-compliant material with stringent impurity profiling and stability testing. Limited qualified European manufacturers control supply amid recruitment bottlenecks for specialized sulfite assay expertise.
- Technical Grade:Unrefined material for non-critical industrial processes requiring basic reducing agent functionality. Photography chemical processors and textile bleaching operations represent core demand pockets.
Food grade commands the established base. The steepest expansion runs through industrial grade.
Application:
Functional chemistry requirements reshape volume allocation across oxygen scavenging, antimicrobial protection, and redox process applications.
- Food Preservation:Sulfite-based antimicrobial and antioxidant protection for beverages, baked goods, and dried fruits. EFSA synthetic antioxidant restrictions accelerate substitution toward certified sulfite systems in European bakery and beverage manufacturing.
- Water Treatment:Dechlorination and oxygen scavenging to protect reverse osmosis and nanofiltration membrane infrastructure. Municipal utilities in industrial corridors adopt continuous sulfite monitoring systems for real-time dissolved oxygen tracking.
- Chemical Manufacturing:Reducing agent for organic synthesis, dye production, and pharmaceutical intermediates. REACH registration requirements favor established European producers with comprehensive chemical dossiers.
- Photography:Traditional silver halide processing applications in specialty imaging and archival restoration. Declining analog photography volumes constrain segment trajectory.
Food preservation anchors revenue concentration. Water treatment gains share fastest.
End User:
Customer procurement sophistication spans centralized tender desks, specialized technical service relationships, and spot-market purchasing.
- Food Industry:Consolidated procurement at multinational processors with unbundled technical advisory contracts. German brewery technical teams now separate sulfite procurement from formulation consulting engagements.
- Cosmetics:Preservative and antioxidant applications in personal care formulations with emerging clean-label pressure. Regulatory divergence across national cosmetic safety regimes complicates cross-border supply.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications requiring USP compliance and batch-specific certification. Limited supplier base elevates pricing premiums for qualified material.
- Waste Management:Dechlorination and heavy metal reduction in industrial effluent treatment. Environmental compliance tightening drives adoption of sulfite-based reduction chemistries.
The food industry dominates procurement volume. Waste management climbs fastest.
Delivery Mode:
Physical format selection balances handling efficiency, dissolution kinetics, and automated dosing system compatibility.
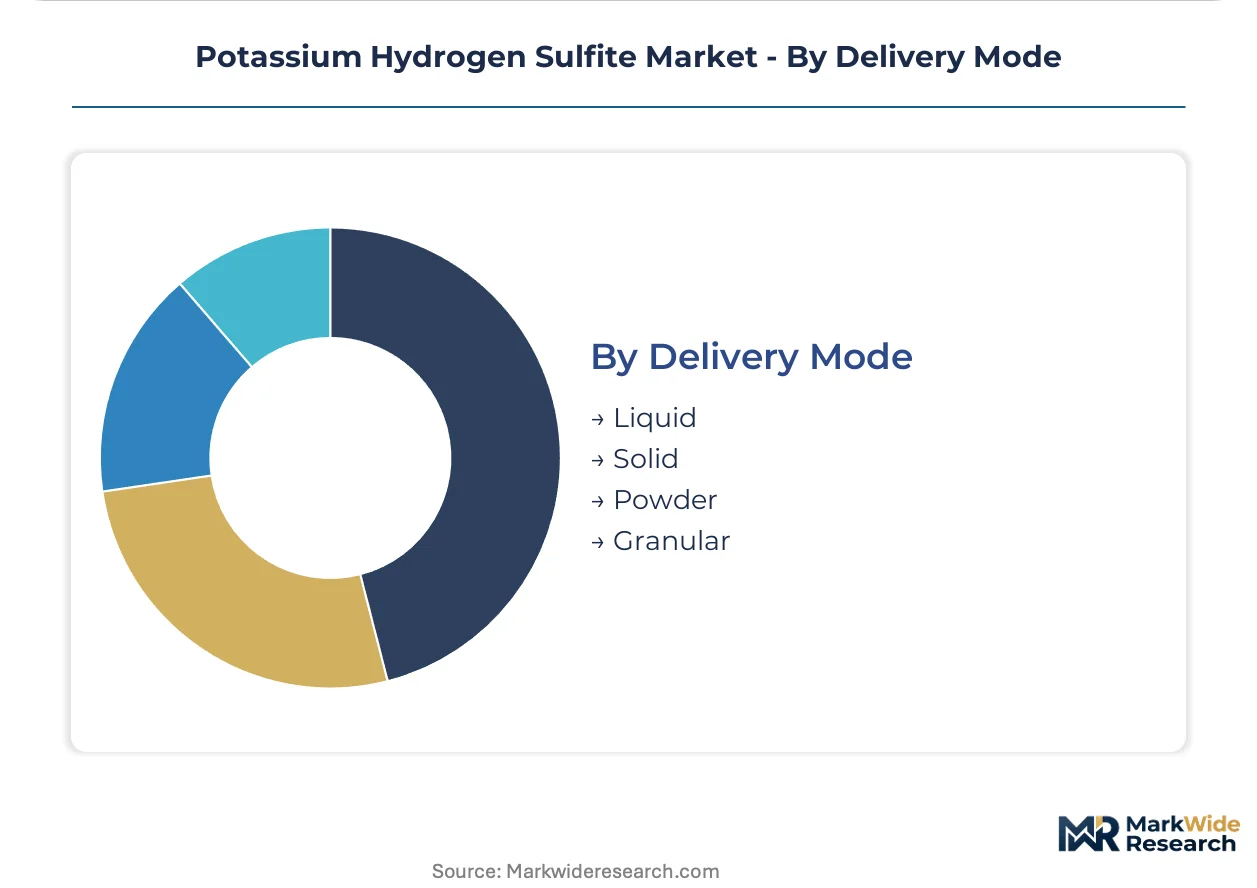
- Liquid:Aqueous solutions containing 45-50% active sulfite content for automated injection systems. UK craft breweries specify specialized liquid formats with tailored concentration profiles and delivery logistics.
- Solid:Compressed blocks or tablets for controlled-release applications in water treatment basins. Municipal utilities favor solid formats for reduced storage footprint and simplified inventory management.
- Powder:Fine crystalline material for dry-blend compatibility in bakery premixes and beverage concentrates. Food processors standardize on powder for homogeneous distribution in flour-based matrices.
- Granular:Coarse particulate for reduced dust generation and improved flow characteristics in pneumatic conveying systems. Industrial chemical manufacturers prefer granular for bulk handling efficiency.
Powder retains the volume base. Liquid formats expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processors and municipal utilities drive procurement intensity across concentrated manufacturing belts. Buyer sophistication varies sharply by region, with European wine exporters demanding certified traceability documentation while Asian chemical manufacturers prioritize bulk handling efficiency.
Germany
Bavarian breweries and Rhineland-Palatinate wine exporters anchor food-grade sulfite consumption. EFSA additive regulations enforce strict maximum residue limits for sulfites in processed foods. The Stuttgart industrial corridor hosts membrane filtration equipment manufacturers that specify sulfite-based dechlorination chemistry for export systems.
United States
California Central Valley fruit processors and Great Lakes municipal utilities represent dual demand poles. FDA food additive regulations and EPA drinking water standards create overlapping compliance frameworks. The Houston Ship Channel chemical complex absorbs industrial-grade volumes for organic synthesis and refinery applications.
India
Gujarat chemical manufacturers and Maharashtra water treatment facilities redirect sulfite demand toward industrial applications. FSSAI tightening of preservative maximum limits in processed foods constrains food-grade domestic consumption. The Mumbai-Pune industrial belt imports certified industrial-grade material for pharmaceutical intermediate synthesis.
France
Bordeaux and Champagne wine houses require food-grade sulfite with full supply-chain traceability for premium export markets. REACH chemical registration requirements restrict non-compliant import sources. The Lyon chemical corridor consumes industrial-grade material for dye production and textile processing applications.
United Kingdom
Midlands craft breweries and Scottish whisky distilleries specify specialized liquid delivery formats with tailored concentration profiles. UK Food Standards Agency regulations align with EFSA thresholds while maintaining separate domestic enforcement protocols. The Manchester chemical processing cluster absorbs technical-grade sulfite for specialty manufacturing applications.
Potassium Hydrogen Sulfite Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. European chemical conglomerates leverage REACH registration portfolios to restrict market access, while regional distributors capture craft brewery segments through formulation advisory services. Three archetypes dominate: integrated chemical majors with captive sulfur dioxide supply, specialty sulfite refiners with USP certification capabilities, and beverage-focused distributors with liquid-format logistics expertise. Capacity expansion and certification portfolio diversification constitute the dominant competitive moves.
Among European-integrated chemical majors, BASF SE anchors the premium food-grade tier through its German manufacturing base and established distribution networks. Murphy and Son Ltd. exemplifies the beverage-specialist distributor archetype with its UK brewing sector focus. Aditya Birla Chemicals occupies a position within the Asian industrial-grade supply tier, serving chemical synthesis and water treatment applications across Indian manufacturing corridors.
| Leading Market Players |
|---|
| ESSECO Srl |
| Occidental Chemical Corp. |
| Aditya Birla Chemicals |
| Murphy and Son Ltd. |
| Jay Dinesh Chemicals |
| Avantor Inc. |
| Hydrite Chemical Co. |
| TNJ Chemical Industry Co. Ltd. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor carries sulfur dioxide feedstock and finished sulfite products between German manufacturing hubs and Mediterranean ports, with its cost volatility compressing margins for distributors while amplifying price spreads between certified food-grade and basic industrial-grade material.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks dominate long-term supply agreements for industrial-grade material. Three-tier pricing structure across pharmaceutical, food, and technical grades reflects assay burden and documentation depth. Pricing pressure stems from sulfur dioxide feedstock volatility tied to European energy markets. Municipal utilities exhibit highest price sensitivity due to budget-constrained procurement cycles, while pharmaceutical manufacturers absorb premiums for USP-compliant supply security.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from European chemical majors tighten working capital pressure on regional distributors. Manufacturing concentrates in Germany, France, and India, with captive sulfur dioxide recovery at integrated sites. Supply chains draw from elemental sulfur, potassium carbonate, and energy inputs. Single-source vulnerability runs through qualified pharmaceutical-grade refiners. Distribution runs through specialized chemical distributors with cold-chain liquid logistics capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as water treatment utilities accelerate sulfite-based dechlorination adoption and craft beverage processors unbundle technical services from chemical procurement.
For Market Incumbents: Build regulatory moats through REACH registration portfolio depth and USP certification maintenance. Deepen backward integration into captive sulfur dioxide recovery to offset feedstock volatility. Expand liquid-format logistics infrastructure to capture unbundled craft brewery demand before regional distributors consolidate advisory relationships.
For New Entrants and Emerging Players: Establish a beachhead in Indian industrial-grade imports serving chemical synthesis and water treatment corridors. Target Maharashtra municipal utilities with certified material redirected from constrained food applications. Pursue toll-manufacturing arrangements with established European refiners to bypass registration barriers.
For Investors and Strategic Acquirers: Specialty sulfite refiners with dual food-pharma certification capabilities present acquisition targets with embedded scarcity value. Long-term viability hinges on clean-label tailwinds sustaining sulfite substitution momentum against peroxyacid alternatives. Monitor EFSA threshold adjustment announcements as inflection signals for grade-mix demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Dioxide Recovery | Captive feedstock supply insulates BASF and Occidental from natural gas price swings at Rhineland and Gulf Coast facilities. |
| Pharmaceutical Grade Certification Investment | USP monograph compliance creates defendable scarcity rent for Avantor and limited European qualified suppliers. |
| Liquid Delivery Format Expansion | Specialized aqueous solutions capture unbundled craft brewery procurement at UK Midlands and Scottish distillation clusters. |
| REACH Registration Portfolio Diversification | Comprehensive chemical dossiers restrict market access for non-compliant Asian imports across European industrial corridors. |
| Long-term Supply Agreement with Municipal Utilities | Membrane protection contracts with German and US utilities secure volume baseload amid spot-market sulfur volatility. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at sulfite manufacturing facilities, procurement leads at German wineries and UK breweries, distribution channel partners, and technical R&D directors at water treatment equipment manufacturers, and refined through secondary validation against customs trade data, ECHA registration databases, SEC 10-K chemical segment disclosures, and Cefic specialty chemical reports, with bottom-up and top-down triangulation reconciling volume estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeling across certification grade, end-use industry, physical delivery format, and regional production hub dimensions. CAGRs were derived from normalized growth trajectory analysis. Forecast inputs incorporated membrane filtration infrastructure deployment pipelines and EFSA additive regulation amendment schedules.
Sensitivities concentrate around sulfur dioxide feedstock cost trajectories, REACH enforcement intensity, and sulfite threshold adjustments by national food safety regulators. Forecasts reflect documented assumptions about substitution elasticity and certification compliance timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Sodium Bromide Market