
 Potassium Permanganate Market | 2026-2036
Potassium Permanganate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Permanganate Market Intelligence
Sodium hypochlorite is restructuring competitive economics in municipal water treatment, forcing potassium permanganate suppliers to defend value through superior iron-manganese removal performance and lower trihalomethane formation. LANXESS leverages its integrated manganese dioxide supply chain to sustain cost discipline across European and North American accounts. Carus Group Inc. anchors its position through specialized on-site generation systems that reduce transport hazards for municipal clients.
Potassium permanganate is a dark purple crystalline salt with the chemical formula KMnO4, produced through electrolytic oxidation of potassium manganate in alkaline solution; it functions as a powerful oxidizing agent with a standard reduction potential of 1.51 volts, serving primarily in water purification, chemical synthesis, and surface disinfection applications. Water treatment applications dominate volume consumption as municipalities prioritize iron, manganese, and hydrogen sulfide removal ahead of filtration stages. Powder and crystal grades capture divergent margin pools, with powder commanding premiums in pharmaceutical synthesis where particle size distribution governs reaction kinetics, while flake grades serve bulk industrial oxidation with lower purity tolerances.
EPA drinking water standards and WHO guideline values for iron and manganese directly shape product specification requirements and testing protocols for suppliers seeking municipal qualification. REACH registration obligations in Europe and China's GB standards for chemical purity create layered compliance barriers that filter smaller producers from premium segments. Stakeholders must monitor evolving substitution dynamics between potassium permanganate and advanced oxidation processes as energy costs shift the economics of on-site electrochemical generation.
Market Dynamics
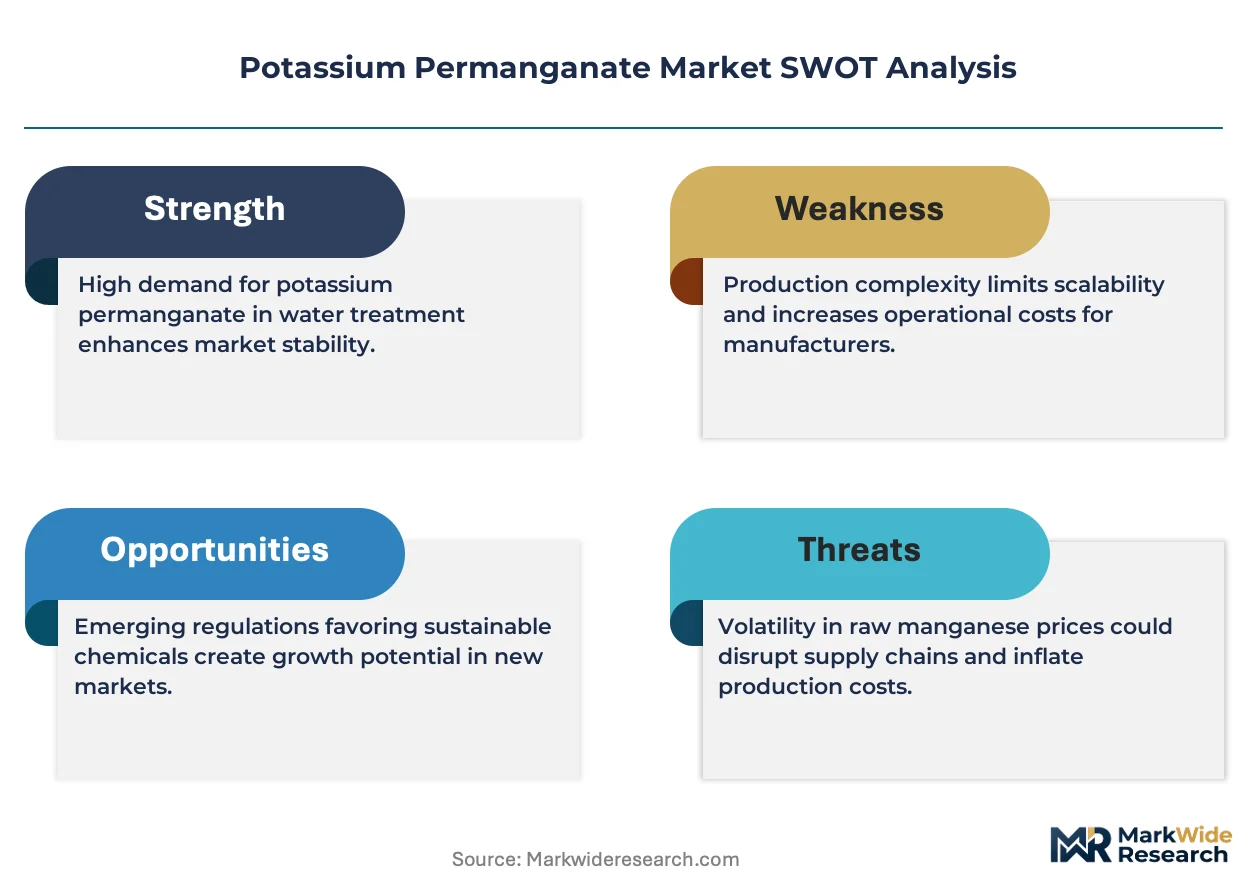
Sodium hypochlorite economics are forcing potassium permanganate suppliers to defend value through superior iron-manganese removal performance and lower trihalomethane formation in municipal water systems.
Growth Catalysts
- WHO Drinking Water Guidelines:Stricter iron and manganese limits in developing nations are accelerating qualification of advanced oxidation chemistries for municipal pre-treatment stages.
- Southeast Asia Infrastructure Buildout:Utilities in Vietnam, Indonesia, and Thailand are expanding pre-oxidation capacity to handle elevated groundwater manganese levels.
- Electrolytic Production Scale-up:China's domestic electrolytic oxidation capacity is capturing both local industrial demand and export volume to African and Latin American markets.
Market Restraints
- Manganese Dioxide Feedstock Concentration:Battery sector demand for high-purity manganese dioxide is tightening raw material availability for permanganate producers.
- Sodium Hypochlorite Substitution:Lower-cost bulk chlorination chemistry is displacing permanganate in secondary disinfection applications across cost-constrained municipal systems.
- REACH Registration Burden:ECHA compliance costs and data requirements are filtering smaller European producers from pharmaceutical-grade segments.
Strategic Opportunities
- On-Site Generation Systems:Electrolytic permanganate production at municipal treatment plants eliminates transport hazards and opens recurring service revenue streams.
- Pharmaceutical Synthesis Grade:Ultra-low particulate powder specifications for active pharmaceutical ingredient oxidation command 40-60% price premiums over industrial flake grades.
- India Water Mission Expansion:Jal Jeevan Mission rural connectivity targets are creating first-time demand for iron-manganese removal in previously untreated groundwater systems.
Industry Challenges
- Electrolytic Process Engineering Talent:Skilled operators for alkaline electrolytic oxidation cells are scarce outside established Chinese and German production clusters.
- Municipal Qualification Timelines:EPA and state-level drinking water product certification cycles extend 18-24 months, delaying revenue recognition for new supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Permanganate Market |
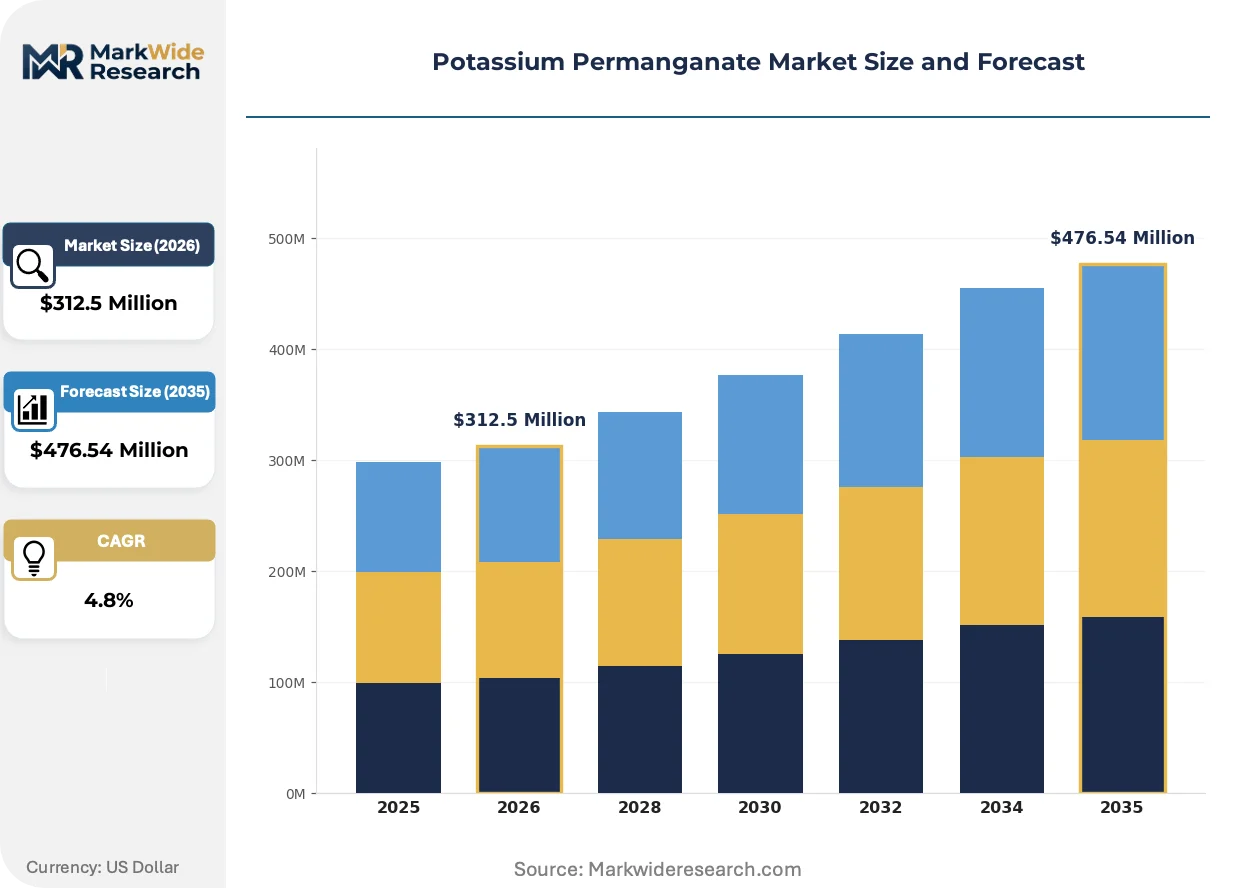
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Crystal, Powder, Granule Application: Water Treatment, Textile Dyeing, Pharmaceuticals, Chemical Syntheses End User: Industrial Manufacturing, Agriculture, Healthcare, Environmental Services Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-Party Distributors |
| Companies Covered | LANXESS, GFS Chemicals, Inc., Carus Group Inc., Zunyi Shuangyuan Chemical Group Co., Ltd., Nippon Chemical Industrial CO., LTD., Chongqing Changyuan Chemical Corporation Limited, Olin Corporation, Gujarat Heavy Chemicals Limited, ICL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Permanganate Market Strategic Shifts & Innovations
Electrochemical process intensification and regulatory chemistry shifts are compressing traditional supply models while opening service-based revenue architectures in water treatment.
Membrane electrolysis for on-site potassium permanganate generation is unifying oxidation chemical production with point-of-use consumption. Municipal utilities in Germany and Australia are piloting containerized electrolytic systems that eliminate bulk transport of hazardous crystalline material. This technology is unifying chemical supply with infrastructure ownership, converting permanganate vendors from product sellers to equipment-service providers.
EPA's pending revisions to secondary maximum contaminant levels for manganese are tightening analytical detection requirements for municipal compliance. Water utilities must deploy more sensitive spectrophotometric methods to demonstrate removal efficacy. Small and medium-sized systems in the US Midwest and Northeast are most affected, accelerating partnerships with certified analytical laboratories.
Specification-driven procurement is consolidating municipal chemical buying through cooperative purchasing agreements. State-level procurement consortia in Texas, California, and Florida are aggregating demand and standardizing quality specifications. This concentration is most visible in the US Sun Belt, where rapid population growth is forcing efficiency gains in utility operations.
Potassium Permanganate Market Segmentation
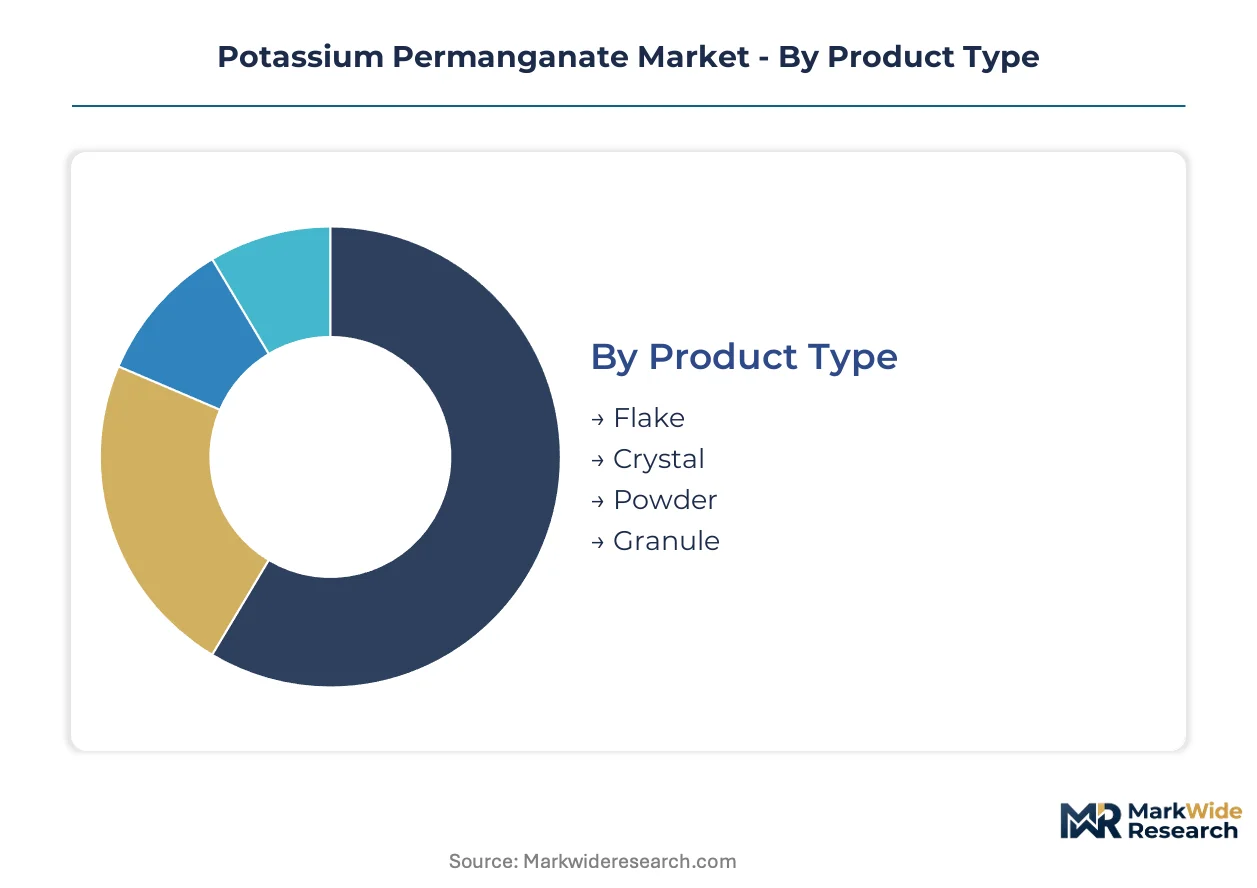
Potassium permanganate specifications vary sharply across end-use requirements. Municipal water utilities prioritize dissolution kinetics and purity grades, while pharmaceutical synthesis demands ultra-low particulate contamination. Understanding these technical boundaries enables precise supplier positioning.
Product Type:
Physical form dictates handling protocols, dissolution rates, and purity thresholds across oxidation applications.
- Crystal:Large crystalline structures with controlled particle geometry optimize dissolution control in continuous-feed municipal systems. Southeast Asian utilities specify crystal grades for iron-manganese removal stations where dosing precision governs filtration performance.
- Powder:Fine particulate specifications with narrow size distribution enable rapid reaction kinetics in pharmaceutical oxidation and laboratory synthesis. Pharmaceutical manufacturers in Germany and Switzerland command premium specifications for active ingredient production.
- Flake:Compressed sheet morphology suits bulk industrial oxidation with lower purity tolerances and extended dissolution timelines. Chemical synthesis operations in China utilize flake grades for cost-efficient organic compound oxidation.
- Granule:Intermediate particle sizing bridges dissolution speed and handling convenience for agricultural and environmental remediation deployments.
Mature deployment sits with Crystal. Newer deployment is concentrated in Powder.
Application:
Functional chemistry requirements separate commodity oxidation from regulated purification processes.
- Water Treatment:Pre-oxidation chemistry for iron, manganese, and hydrogen sulfide removal dominates municipal procurement volumes. WHO guideline alignment drives specification upgrades in Vietnam, Indonesia, and Thailand groundwater systems.
- Pharmaceuticals:Ultra-pure grades for active pharmaceutical ingredient synthesis carry certification burdens from FDA, EMA, and NMPA registrants. Swiss and German manufacturers anchor demand for GMP-compliant material.
- Chemical Syntheses:Broad-spectrum oxidation for organic intermediate production concentrates in Chinese and Indian manufacturing clusters.
- Textile Dyeing:Bleaching and color-stripping applications utilize technical-grade material with tolerance for higher insoluble content.
Volume leadership rests with Water Treatment. Value expansion is climbing fastest in Pharmaceuticals.
End User:
Procurement sophistication and specification stringency separate industrial commodity buyers from regulated sector purchasers.
- Industrial Manufacturing:Chemical synthesis, metal finishing, and electronics fabrication drive bulk consumption with price-sensitive tendering. Chinese producers supply domestic industrial users and export markets.
- Healthcare:Hospital disinfection, wound care formulations, and pharmaceutical manufacturing impose pharmacopeial compliance requirements. FDA and EMA inspections govern supplier qualification timelines.
- Environmental Services:Soil remediation and groundwater treatment projects utilize technical grades for contaminant oxidation.
- Agriculture:Fungicide formulations and irrigation system maintenance represent dispersed, specification-tolerant demand.
Contract maturity concentrates in Industrial Manufacturing. Specification escalation is advancing most rapidly in Healthcare.
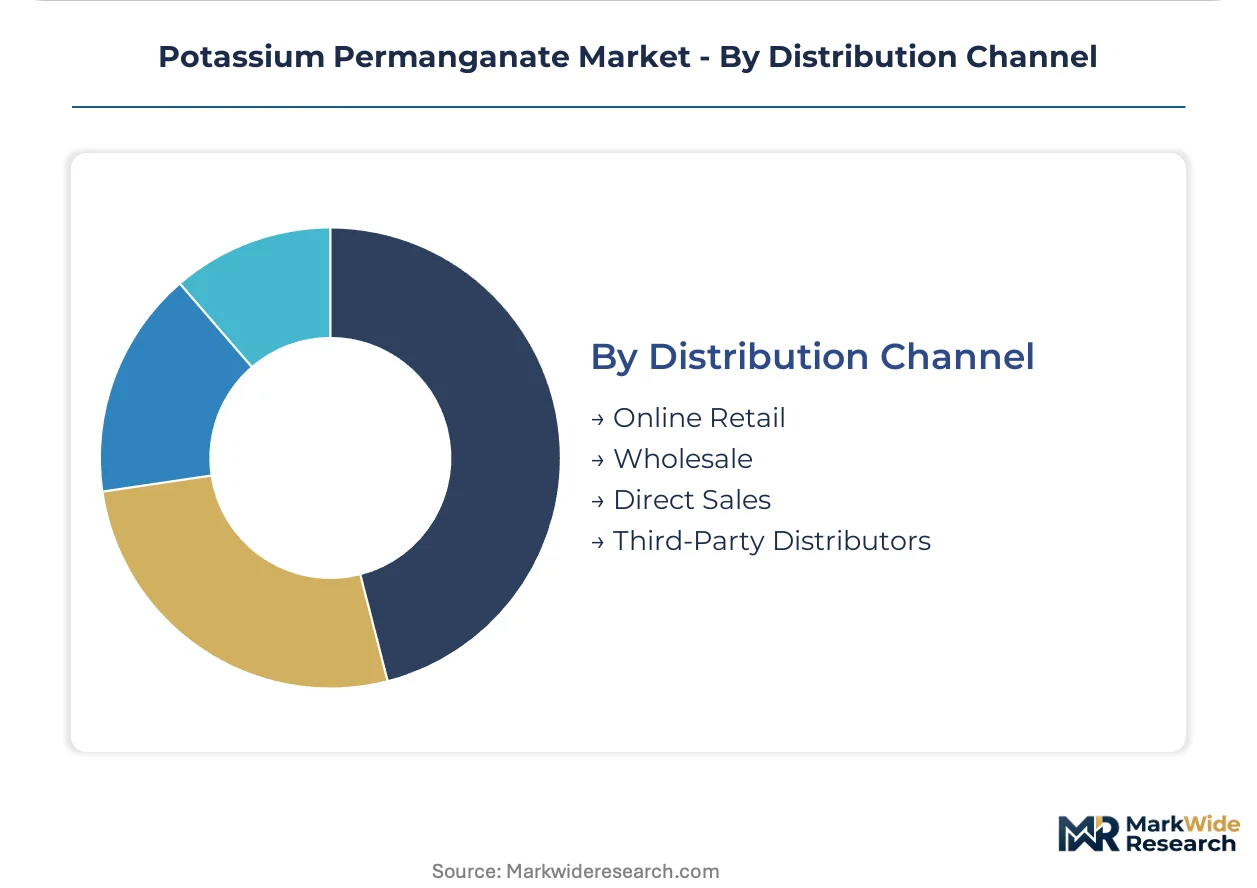
Distribution Channel:
Supply chain configuration balances hazard transport economics with customer technical service requirements.
- Direct Sales:Large municipal utilities and pharmaceutical manufacturers negotiate long-term supply agreements with technical support provisions. German and Australian pilots of on-site generation systems convert product sales to equipment-service contracts.
- Third-Party Distributors:Regional chemical distributors stock standard grades for industrial and agricultural accounts with fragmented demand.
- Wholesale:Bulk volume aggregation serves mid-scale water treatment facilities and chemical processors.
- Online Retail:Small-package sales for laboratory, educational, and specialty agricultural applications.
Relationship depth is greatest in Direct Sales. Channel experimentation is expanding most quickly through Third-Party Distributor technical partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of global potassium permanganate consumption, with domestic electrolytic oxidation capacity serving both industrial users and export markets across Africa and Latin America.
China
Groundwater iron-manganese removal projects in Jiangsu and Zhejiang provinces are expanding municipal water treatment procurement. GB standards for chemical purity govern domestic production certification. Chongqing and Guizhou host the country's dominant electrolytic oxidation manufacturing clusters, supplying technical-grade flake to chemical synthesis operations.
United States
EPA secondary maximum contaminant level revisions for manganese are tightening compliance requirements across Midwest and Northeast utilities. State-level procurement consortia in Texas, California, and Florida aggregate demand through cooperative purchasing agreements. Carus Group anchors supply relationships through specialized on-site generation systems that reduce transport hazards.
Germany
REACH registration obligations filter smaller producers from pharmaceutical-grade segments, consolidating supply among ECHA-compliant registrants. LANXESS leverages integrated manganese dioxide supply chains to sustain cost discipline across European accounts. Bavarian and North Rhine-Westphalian chemical clusters prioritize GMP-compliant powder specifications for active pharmaceutical ingredient oxidation.
India
Jal Jeevan Mission rural connectivity targets are creating first-time demand for iron-manganese removal in previously untreated groundwater systems. BIS certification requirements shape municipal chemical qualification timelines. Gujarat and Maharashtra industrial corridors absorb bulk flake grades for chemical synthesis and textile processing applications.
Australia
Containerized electrolytic generation pilots are converting permanganate vendors from product sellers to equipment-service providers. TGA-aligned water quality frameworks influence municipal procurement specifications. Queensland and New South Wales utilities are deploying membrane electrolysis systems that unify chemical production with point-of-use consumption.
Potassium Permanganate Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated manganese dioxide producers commanding cost advantages in industrial flake grades while pharmaceutical-grade powder remains concentrated among REACH-registered specialists. The vendor base organizes around three archetypes: electrolytic oxidation specialists with captive feedstock, diversified chemical conglomerates with backward integration into manganese mining, and regional toll manufacturers serving cost-sensitive industrial accounts. Capacity expansion and on-site generation technology licensing represent the dominant competitive moves reshaping supply relationships.
Within the integrated specialist tier, LANXESS and Carus Group exemplify divergent strategic positioning—LANXESS anchoring European pharmaceutical-grade supply through ECHA-compliant production, Carus occupying the equipment-service intersection with municipal on-site generation systems. Among Asia-Pacific producers, Zunyi Shuangyuan Chemical Group and Chongqing Changyuan Chemical represent the scale-driven Chinese electrolytic oxidation segment serving both domestic industrial demand and export volume to developing markets.
| Leading Market Players |
|---|
| LANXESS |
| GFS Chemicals, Inc. |
| Carus Group Inc. |
| Zunyi Shuangyuan Chemical Group Co., Ltd. |
| Nippon Chemical Industrial CO., LTD. |
| Chongqing Changyuan Chemical Corporation Limited |
| Olin Corporation |
| Gujarat Heavy Chemicals Limited |
| ICL |
| Others |
Cost & Logistics Intelligence
Backward integration into manganese dioxide feedstock anchors pricing power for established electrolytic oxidation specialists, while toll manufacturers remain exposed to battery-sector demand competition for high-purity ore. This upstream control separates cost-disciplined European and Chinese producers from price-takers in fragmented industrial flake segments.
Pricing Analysis
Volume leadership in municipal water treatment generates thin margins on crystal and flake grades, while pharmaceutical powder specifications command substantial premiums through GMP certification requirements. Price differentiation rests on particulate contamination thresholds and REACH registration status rather than brand recognition alone. Cost compression in industrial flake tiers is intensifying as sodium hypochlorite substitution accelerates across secondary disinfection applications. Municipal utilities exhibit highest price sensitivity due to cooperative purchasing aggregation, whereas Swiss and German pharmaceutical manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-municipal channels handle large utility demand through long-term supply agreements with technical service provisions, while regional distributors serve fragmented agricultural and industrial accounts. Production gravity centers on China, Germany, and India, with Chinese electrolytic capacity feeding export volume to African and Latin American markets. Raw material supply draws from manganese ore deposits in South Africa, Gabon, and Australia, with battery-sector competition tightening high-purity dioxide availability. Single-source vulnerability concentrates in electrolytic cell engineering talent, which remains scarce outside Chongqing and German production clusters. Distribution runs through specialized chemical handlers with hazardous material certifications for crystalline permanganate transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a vertical-integration race where control over manganese dioxide feedstock and electrolytic oxidation technology determines sustainable margin capture across specification tiers.
For Market Incumbents: Acquire captive manganese dioxide supply arrangements to insulate against battery-sector demand competition and secure cost discipline for industrial flake production. Defend municipal relationships through on-site generation system deployment that converts transactional chemical sales into recurring equipment-service revenue streams. Counter sodium hypochlorite substitution by emphasizing superior iron-manganese removal kinetics and lower trihalomethane formation in pre-oxidation applications. For New Entrants and Emerging Players: Containerized electrolytic generation technology offers a technology-first wedge into municipal utilities seeking to eliminate hazardous material transport liabilities. Target India's Jal Jeevan Mission rural connectivity expansion, where first-time iron-manganese removal demand outstrips established supplier presence in previously untreated groundwater systems. Pursue pharmaceutical-grade powder qualification through BIS and NMPA certification pathways to access premium specification tiers with limited incumbent competition. For Investors and Strategic Acquirers: Exit pathways concentrate in equipment-service model transitions and REACH-registered pharmaceutical-grade specialists with ECHA-compliant production infrastructure. Long-term viability favors integrated producers with backward manganese dioxide control and electrolytic oxidation expertise spanning the analysis window. Monitor EPA secondary maximum contaminant level revision timing as inflection indicator for municipal specification upgrade cycles and analytical service demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Dioxide | Captive ore supply insulates permanganate producers from battery-sector demand competition and price volatility. |
| On-Site Generation System Deployment | Electrolytic production at municipal plants converts product sales to recurring service revenue with higher retention. |
| Pharmaceutical-Grade Certification Investment | FDA, EMA, and NMPA registrations unlock 40-60% price premiums through GMP-compliant powder specifications. |
| REACH Registration Maintenance | ECHA compliance preserves access to European pharmaceutical and municipal segments that filter non-registered producers. |
| India Water Mission Partnership | Jal Jeevan Mission rural targets create first-time demand for iron-manganese removal in untreated groundwater systems. |
Research Approach
Multi-period observation of electrolytic oxidation capacity additions, municipal qualification timelines, and manganese dioxide price movements anchored the trend analysis, supplemented by interviews with plant managers at Chinese and German production facilities, procurement leads at Southeast Asian water utilities, technical R&D directors at pharmaceutical manufacturers, and distribution channel partners handling hazardous chemical logistics. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, EPA drinking water certification records, and ECHA registration databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure consistency across regional demand estimates.
Input-output matrices mapped electrolytic cell capacity, manganese dioxide feedstock flows, and end-use demand by specification tier across the projection horizon. Segmentation dimensions modeled include physical form grade, application chemistry requirements, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from regression analysis of historical consumption patterns against infrastructure investment indicators and water quality guideline evolution. Industry-specific forecast inputs incorporated WHO guideline revision timelines and municipal pre-oxidation capacity buildout pipelines.
Several conditions sit outside the modeled scope, including unannounced EPA regulatory revisions, breakthrough electrochemical generation technologies, and abrupt battery-sector demand shifts for high-purity manganese dioxide. Forecasts reflect assumptions about electrolytic oxidation capacity expansion rates and municipal qualification cycle durations that may require adjustment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fine Chemicals Market
Chemicals
Global Chiral Chemicals Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
Egypt Acidulants Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Glyoxal Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Elemental Fluorine Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Methanol to Gasoline Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Paraphenylenediamine (PPD) Market