
 Potassium Hydrogen Fluoride Market | 2026-2036
Potassium Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydrogen Fluoride Market Analytics
Project finance tied to green chemistry infrastructure is reshaping competitive entry in fluorochemicals. Solvay S.A. leverages its integrated bromine-fluorine platform to secure long-term supply contracts. Honeywell International Inc. anchors North American production through proprietary acid-grade fluorspar processing. Gujarat Fluorochemicals Limited dominates Indian supply with captive hydrofluoric acid capacity.
Potassium hydrogen fluoride (KHF₂) is an inorganic salt composed of potassium, hydrogen, and fluorine in a 1:1:2 molar ratio, typically manufactured via neutralization of hydrofluoric acid with potassium carbonate or hydroxide and supplied as colorless crystals or aqueous solutions. It functions primarily as a fluorinating agent, glass-etching medium, and metal surface treatment chemical in industrial and electronic applications. Electronic grade material commands premium positioning due to ultra-low impurity thresholds demanded by semiconductor etching processes. Industrial grade supply remains volume-led through metal cleaning and surface treatment applications. Glass etching demand sustains steady offtake from architectural and automotive panel manufacturers.
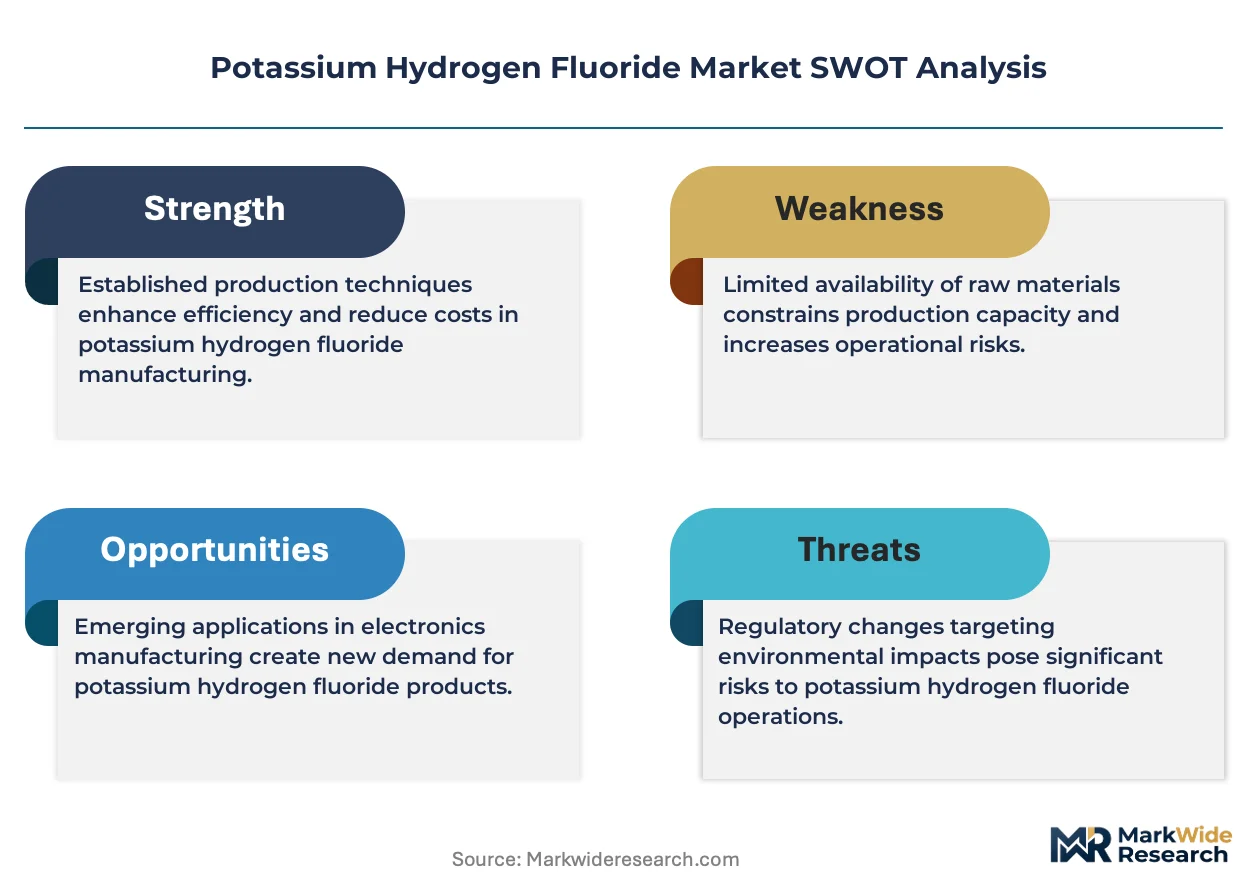
EPA oversight in the United States enforces strict fluoride emission limits that elevate compliance costs for KHF₂ producers and downstream users. REACH registration requirements in Europe mandate comprehensive toxicity dossiers, constraining market access for non-compliant suppliers. China's MEE enforces wastewater discharge standards that compel investment in fluoride capture and recycling technology. Stakeholders must track evolving per-fluorinated substance restrictions that could redirect technical grade demand toward alternative chemistries.
Market Dynamics
China's MEE enforcement of closed-loop fluoride recovery mandates is compressing production economics for non-compliant facilities while concentrating supply among integrated chemical parks in Jiangsu Province.
Growth Catalysts
- Semiconductor Etching Demand:Wafer fabrication facilities in Taiwan and South Korea consume electronic-grade potassium hydrogen fluoride for precision surface treatment. Ultra-pure specifications align with sub-7nm node requirements.
- REACH Registration Thresholds:ECHA toxicity dossier requirements filter out marginal European suppliers. Compliant producers capture displaced volume from non-registered competitors.
- Fluorochemical Cluster Agglomeration:Captive hydrofluoric acid supply in Gujarat's chemical corridor secures feedstock cost advantages for Indian KHF₂ manufacturers.
Market Restraints
- Acid-Grade Fluorspar Concentration:Mexican and Chinese fluorspar deposits supply 80% of global acidspar feedstock. Geopolitical friction or export licensing disrupts upstream material flows.
- EPA Fluoride Emission Limits:US stack monitoring and scrubber mandates elevate fixed compliance costs for domestic producers. Smaller operators face disproportionate capital burden.
- Ammonium Bifluoride Substitution:Metal surface treatment applications in automotive pretreatment lines increasingly specify ammonium salts. KHF₂ loses volume in non-electronic cleaning segments.
Strategic Opportunities
- India PLI Scheme for Electronics:Domestic semiconductor and display manufacturing incentives create captive demand for electronic-grade fluorochemicals. Local KHF₂ production avoids import duty exposure.
- EU F-Gas Regulation Phase-Down:Refrigerant gas containment mandates expand fluoride recycling infrastructure. Spent KHF₂ from etching operations becomes recoverable feedstock.
- Digital Procurement Platforms:Specialty chemical marketplaces reduce distributor layers for mid-volume buyers. Direct manufacturer relationships improve price transparency and lot traceability.
Industry Challenges
- Electronic-Grade Certification Timelines:SEMI standard compliance requires 18-24 month qualification cycles with foundry customers. Product switching costs lock incumbent suppliers into mature accounts.
- Fluoride Waste Handling Expertise:Closed-loop system design and calcium fluoride sludge management demand specialized environmental engineering talent. Skill scarcity constrains brownfield expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydrogen Fluoride Market |
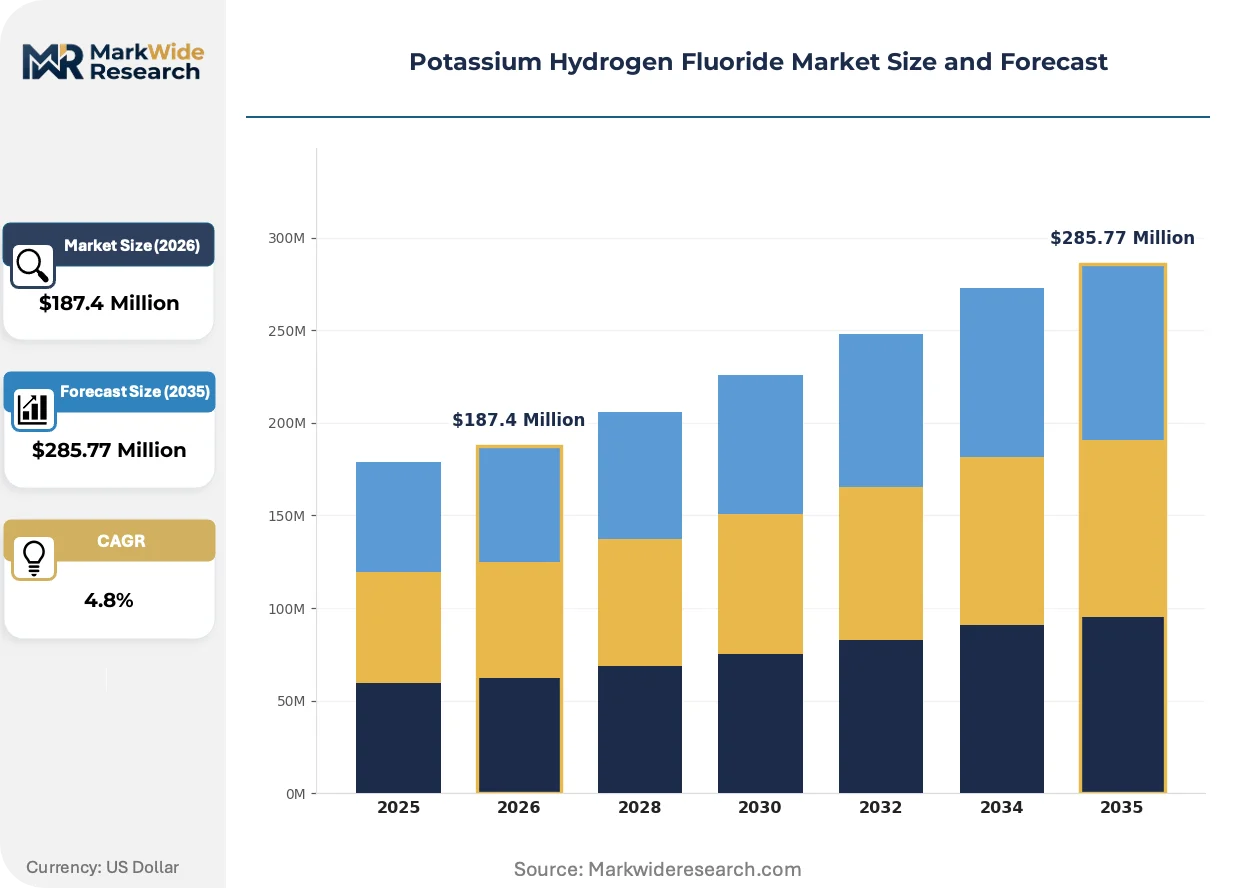
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Electronic Grade, Industrial Grade, Reagent Grade Application: Glass Etching, Metal Cleaning, Surface Treatment, Chemical Synthesis End User: Electronics, Chemicals, Manufacturing, Laboratory Packaging Type: Drum, Bag, Bottle, Bulk |
| Companies Covered | Solvay S.A., Honeywell International Inc., Morita Chemical Industries Co., Ltd., Stella Chemifa Corporation, Fluoro Chemicals LLC, Gujarat Fluorochemicals Limited, Navin Fluorine International Limited, Tanfac Industries Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydrogen Fluoride Market Evolving Landscape
Fluorochemical process intensification and purity verification technologies are compressing production batch cycles while elevating quality thresholds for semiconductor-grade material.
Membrane electrolysis for anhydrous hydrogen fluoride generation is rendering obsolete traditional wet-process acid production in new Chinese installations. Jiangsu Province chemical parks adopt solid-state electrolytic cells to eliminate sulfuric acid calcination steps. This technology reduces energy intensity and particulate emissions simultaneously.
EU F-Gas Regulation mandates comprehensive refrigerant lifecycle tracking through the HFC phasedown schedule. Fluorochemical processors must document fluoride recovery rates and destruction efficiency. Semiconductor etching operations face heightened scrutiny on spent KHF₂ disposition pathways.
Consolidated procurement by East Asian electronics foundries compresses supplier qualification cycles and elevates lot-to-lot consistency requirements. Long-term offtake agreements with volume commitments displace spot market purchasing. Taiwan and South Korea wafer manufacturers now specify 99.99% purity floors with individual metal impurity limits below 10 ppb.
Potassium Hydrogen Fluoride Market Segmentation
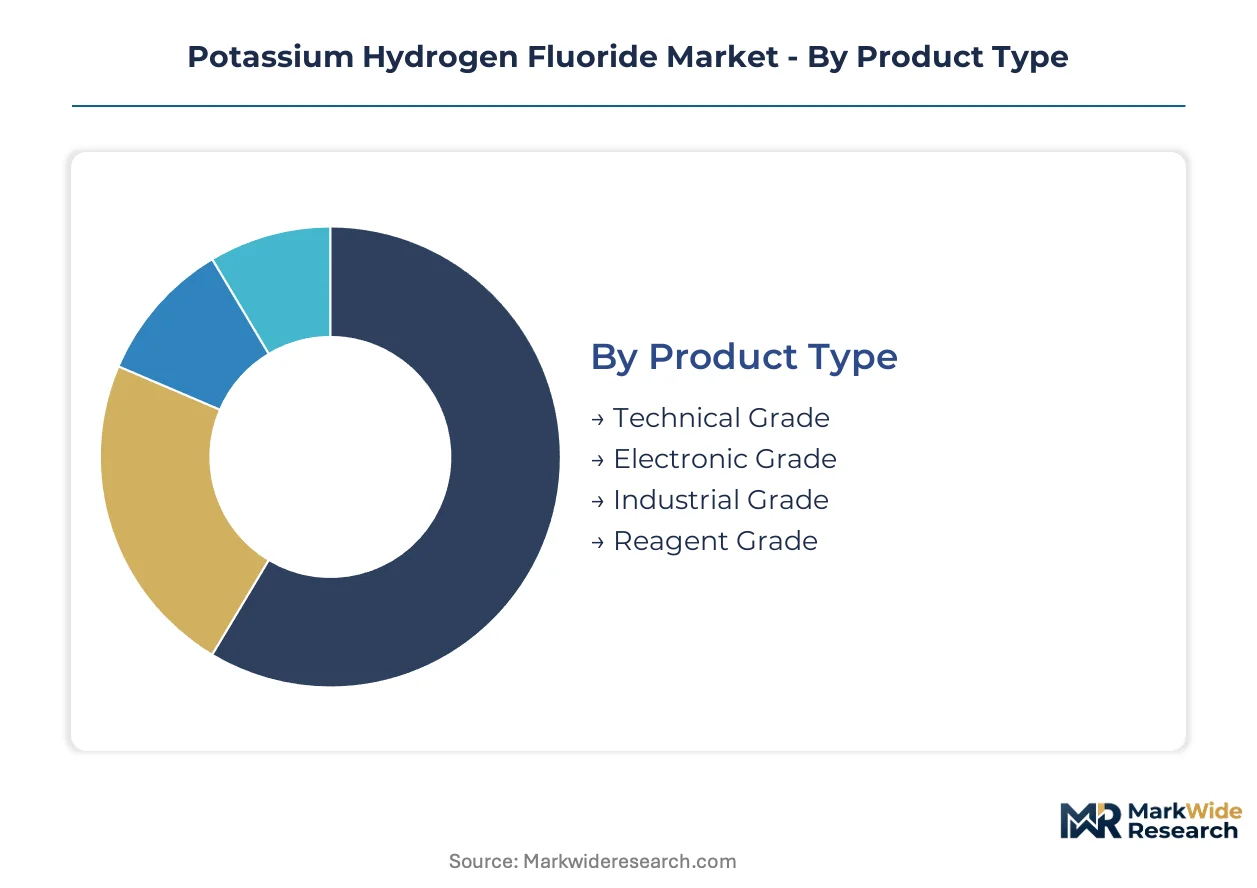
Potassium hydrogen fluoride demand fragments across purity thresholds that separate semiconductor-grade specifications from commodity metal treatment applications. Grade differentiation determines pricing power, regulatory burden, and customer qualification timelines for suppliers.
Product Type:
Mature industrial grades dominate volume throughput while electronic specifications command margin premiums through exacting purity protocols.
- Technical Grade:Standard purity material serves general fluorination reactions and bulk chemical manufacturing where impurity tolerance exceeds 100 ppm. Foundry demand in Taiwan and South Korea specifies this grade for non-critical etching steps, though volume is plateauing as process sophistication advances.
- Electronic Grade:Ultra-pure KHF₂ with total metallic impurities below 100 ppb enables sub-7nm semiconductor node fabrication. Jiangsu Province chemical parks concentrate production due to captive hydrofluoric acid integration and MEE-mandated closed-loop recovery systems that assure contamination control.
- Industrial Grade:Mid-tier material bridges glass etching and architectural panel manufacturing where optical clarity requirements are moderate. Indian producers leverage Gujarat's fluorochemical cluster feedstock cost advantages to serve domestic demand.
- Reagent Grade:Laboratory-scale supply for analytical chemistry and research applications with documented batch certificates of analysis. Volume concentrates through specialty chemical distributors rather than direct manufacturer relationships.
Technical Grade handles the majority of throughput; Electronic Grade is the fastest mover on share.
Application:
Cost tier stratification separates precision semiconductor processes from commodity surface preparation workflows.
- Glass Etching:Hydrofluoric acid generation in situ enables architectural and automotive panel frosting without direct acid handling. Jiangsu manufacturers supply drum quantities to flat glass processors under long-term offtake agreements.
- Metal Cleaning:Oxide layer removal in aluminum and steel pretreatment lines consumes industrial-grade material. Ammonium bifluoride substitution is eroding KHF₂ volume in European automotive pretreatment specifications.
- Surface Treatment:Electronic-grade demand concentrates in Taiwan wafer fabrication facilities for precision substrate preparation. SEMI qualification cycles lock qualified suppliers into mature foundry accounts.
- Chemical Synthesis:Fluorinating agent applications in pharmaceutical and agrochemical intermediate production. REACH registration requirements filter European supply to compliant producers with complete toxicity dossiers.
Metal Cleaning retains the largest volume footprint; Surface Treatment is climbing the fastest as semiconductor capacity expands.
End User:
Customer type determines procurement modality, with electronics buyers consolidating supply through direct manufacturer contracts and chemical processors relying on distributor networks.
- Electronics:Semiconductor foundries and display panel manufacturers specify electronic-grade material with individual metal impurity limits below 10 ppb. India's PLI scheme for electronics manufacturing is creating captive domestic demand to replace imports.
- Chemicals:Fluorochemical and specialty chemical producers consume technical and reagent grades for downstream synthesis. Captive hydrofluoric acid supply in Gujarat secures feedstock cost advantages for integrated Indian producers.
- Manufacturing:Glass processors and metal fabricators purchase industrial-grade material in bulk packaging. EPA fluoride emission limits in the United States elevate compliance costs for downstream users with open-loop process designs.
- Laboratory:Research institutions and analytical laboratories procure reagent-grade material in bottle quantities through specialty chemical distributors. Lot traceability requirements favor established supplier relationships over price-driven switching.
Manufacturing channels the greatest absolute volume; Electronics is gaining share fastest through foundry capacity expansion.
Packaging Type:
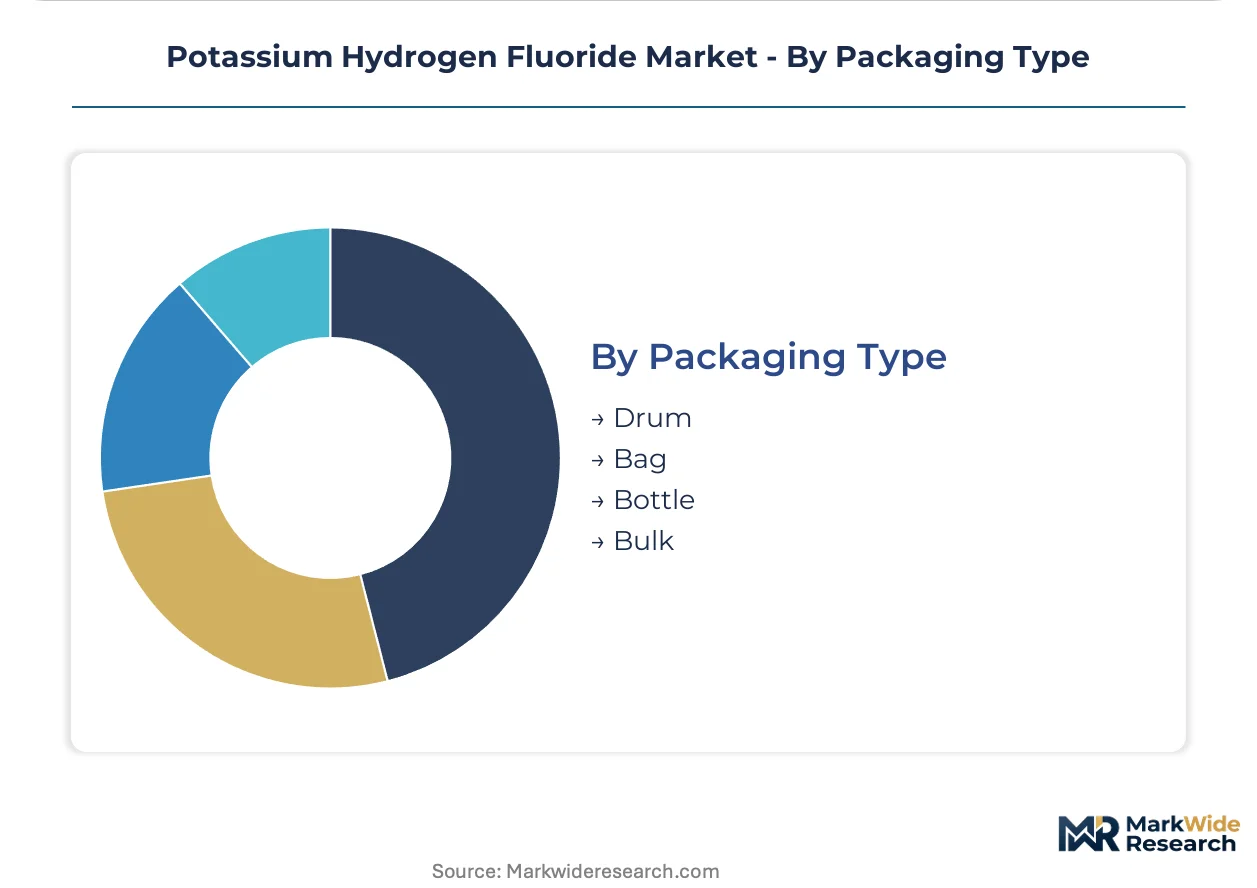
Volume scale and handling safety requirements segment procurement modalities across end-user categories.
- Drum:Standard 200-liter steel or plastic drums serve mid-volume electronics and chemical manufacturing customers. Taiwan and South Korea foundries specify drum delivery with contamination-sealed closures.
- Bag:Flexible intermediate bulk containers and lined bags suit dry crystal shipments to glass etching and metal cleaning operations. Indian domestic supply leverages bag packaging for cost-efficient road freight distribution.
- Bottle:Laboratory-scale containers from 500 milliliters to 5 liters address reagent-grade demand with individual batch documentation. Specialty chemical distributors manage bottle inventory for fragmented research customer bases.
- Bulk:Tank truck and railcar deliveries serve captive consumption within integrated chemical parks. Jiangsu Province fluorochemical clusters utilize bulk transfer to eliminate packaging waste under MEE circular economy mandates.
Drum packaging moves the largest revenue share; Bulk is expanding most quickly through chemical park integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in potassium hydrogen fluoride track the geographic distribution of semiconductor fabrication capacity and fluorochemical processing infrastructure, with East Asian economies running structural deficits in electronic-grade material that Chinese and Indian producers supply.
China
Jiangsu Province chemical parks consume captive hydrofluoric acid output for electronic-grade KHF₂ production serving Taiwan and South Korea foundries. MEE wastewater discharge standards compel closed-loop fluoride recovery investments that raise entry barriers for non-integrated facilities. Xuzhou and Changzhou industrial clusters concentrate acid-grade fluorspar processing and downstream salt manufacture under unified environmental compliance regimes.
United States
Domestic electronics manufacturers rely on imported electronic-grade material as EPA fluoride emission limits elevate production costs for greenfield acid regeneration facilities. Honeywell International Inc. maintains acid-grade fluorspar processing in Illinois and Kentucky, though KHF₂ finishing capacity remains limited. Gulf Coast chemical processors handle bulk technical-grade imports for metal treatment applications in Texas and Louisiana refining corridors.
India
Gujarat's fluorochemical cluster leverages captive hydrofluoric acid capacity from Dahej and Vadodara industrial zones to serve domestic metal cleaning and emerging electronics manufacturing demand. PLI scheme incentives for semiconductor fabrication are drawing KHF₂ investment toward Maharashtra and Karnataka greenfield sites. DGFT import duty structures favor local electronic-grade production over Chinese material for strategic end-uses.
Germany
REACH registration requirements filter supply to ECHA-compliant producers with complete toxicity dossiers, constraining spot market availability for technical-grade applications. BASF SE maintains integrated fluorochemical production in Ludwigshafen serving European pharmaceutical and specialty chemical synthesis demand. EU F-Gas Regulation phase-down mandates are expanding fluoride recycling infrastructure that recovers spent etching chemicals from Dutch and Belgian semiconductor operations.
Japan
Domestic producers including Morita Chemical Industries Co., Ltd. and Stella Chemifa Corporation supply precision electronic-grade material for Kansai and Kyushu wafer fabrication facilities. METI industrial policy supports domestic fluorochemical self-sufficiency amid supply chain security concerns. Osaka and Nagoya industrial corridors maintain captive etching chemical production aligned with sub-5nm node development timelines.
Potassium Hydrogen Fluoride Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and intermediate processing. The vendor base separates into three functional layers: diversified chemical conglomerates with captive fluorspar access, regional fluorochemical pure-plays with hydrofluoric acid integration, and specialty distributors serving laboratory and mid-volume industrial accounts. Strategic positioning concentrates on backward integration into acid-grade fluorspar supply and forward qualification with semiconductor foundry customers.
Among diversified chemical conglomerates, Solvay S.A. and Honeywell International Inc. exemplify platform-scale positioning with integrated bromine-fluorine and acid-grade processing capabilities respectively. Gujarat Fluorochemicals Limited occupies a distinctive role as a regional pure-play with captive Indian hydrofluoric acid supply. Specialty Japanese producers Morita Chemical Industries Co., Ltd. and Stella Chemifa Corporation represent precision-grade specialists serving East Asian semiconductor ecosystems.
| Leading Market Players |
|---|
| Solvay S.A. |
| Honeywell International Inc. |
| Morita Chemical Industries Co., Ltd. |
| Stella Chemifa Corporation |
| Fluoro Chemicals LLC |
| Gujarat Fluorochemicals Limited |
| Navin Fluorine International Limited |
| Tanfac Industries Ltd. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Acid-grade fluorspar concentration in Mexican and Chinese deposits determines both pricing tier spreads and supply chain shape for potassium hydrogen fluoride producers. This single-source dependency for 80% of global acidspar feedstock compresses margins for non-integrated processors while amplifying premium capture for chemical parks with captive hydrofluoric acid supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate procurement across technical and industrial grades. Three-tier pricing structure across electronic, industrial, and technical levels reflects SEMI certification status and individual metal impurity thresholds below 10 ppb. Cost compression in industrial grades is intensifying because ammonium bifluoride substitution erodes volume in metal surface treatment applications. Electronics foundries exhibit least price sensitivity due to 18-24 month qualification cycles that lock qualified suppliers into mature accounts.
Supply Chain Analysis
Extended payment terms from East Asian electronics foundries strain working capital for mid-tier producers without supply-chain finance facilities. Jiangsu Province chemical parks in China, Gujarat's fluorochemical corridor in India, and Kansai industrial zone in Japan concentrate electronic-grade production capacity. Feedstock flows draw from acid-grade fluorspar deposits, sulfuric acid calcination inputs, and potassium carbonate sources. Single-source vulnerability runs through Mexican fluorspar export licensing regimes. Distribution runs through direct manufacturer contracts for electronics buyers and specialty chemical distributors for laboratory accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor node advancement below 7nm is accelerating electronic-grade fluorochemical penetration in wafer fabrication. This early-cycle expansion story justifies capacity positioning ahead of India's PLI scheme maturation and EU F-Gas Regulation phase-down compliance deadlines.
For Market Incumbents: Entrench SEMI-qualified supply positions through captive hydrofluoric acid integration in Jiangsu Province chemical parks. Counter ammonium bifluoride substitution threat by bundling etching chemistry technical service with material supply. Prioritize closed-loop fluoride recovery certification to satisfy MEE wastewater discharge standards. For New Entrants and Emerging Players: Establish a beachhead in India's emerging electronics manufacturing corridor before PLI scheme incentives fully mature. Target Maharashtra and Karnataka greenfield sites for electronic-grade production to avoid DGFT import duty exposure. Pursue foundry technical qualification partnerships rather than spot market volume plays. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive feedstock and SEMI certification. Long-term viability hinges on fluorochemical cluster positioning within MEE-compliant chemical parks. Monitor Jiangsu Province environmental enforcement intensity as inflection indicator for supply concentration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid-Grade Fluorspar | Captive Mexican or Chinese fluorspar supply secures feedstock cost position against export licensing volatility. |
| Electronic-Grade Certification Investment | SEMI standard compliance opens sub-7nm foundry accounts with 18-24 month qualification cycle protection. |
| Closed-Loop Fluoride Recovery Deployment | MEE-mandated wastewater systems enable Jiangsu Province chemical park residency and Taiwan supply contracts. |
| Long-Term Foundry Offtake Agreement | Direct manufacturer relationships with Taiwan and South Korea wafer fabricators displace distributor layers. |
| Joint Venture in India Electronics Corridor | PLI scheme alignment in Maharashtra or Karnataka captures domestic semiconductor manufacturing demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with semiconductor foundry procurement managers, fluorochemical plant engineers, specialty chemical distribution channel partners, and MEE compliance officers. Secondary validation incorporated customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and ECHA REACH registration dossiers. Bottom-up volume modeling across grade tiers, end-use industries, packaging formats, and regional production hubs was triangulated against top-down macroeconomic indicators.
Calibration against historical capacity utilization rates and foundry capital expenditure disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included purity grade tier, application workflow, end-user industry, and packaging modality. CAGRs were derived from regression analysis of installed semiconductor fabrication capacity and fluorochemical intensity per wafer layer. Forecast inputs incorporated EPA stack monitoring compliance cost trajectories and EU F-Gas Regulation phase-down schedules.
Stress conditions across fluorspar export licensing disruption, ammonium bifluoride substitution acceleration, and MEE enforcement intensity variation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on semiconductor node migration timelines and chemical park environmental compliance investment rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
5 Dinitroaniline Market
Chemicals
Copper Oxychloride Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
Household Insecticides Market
Chemicals
Phenylethyl Market
Chemicals
Mercuric Chloride Market
Chemicals
Barbituric Acid Market
Chemicals
Thiourea Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Calcium Borate Market