
 BDO Synthesis Catalyst Market | 2026-2036
BDO Synthesis Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
BDO Synthesis Catalyst Market Insights
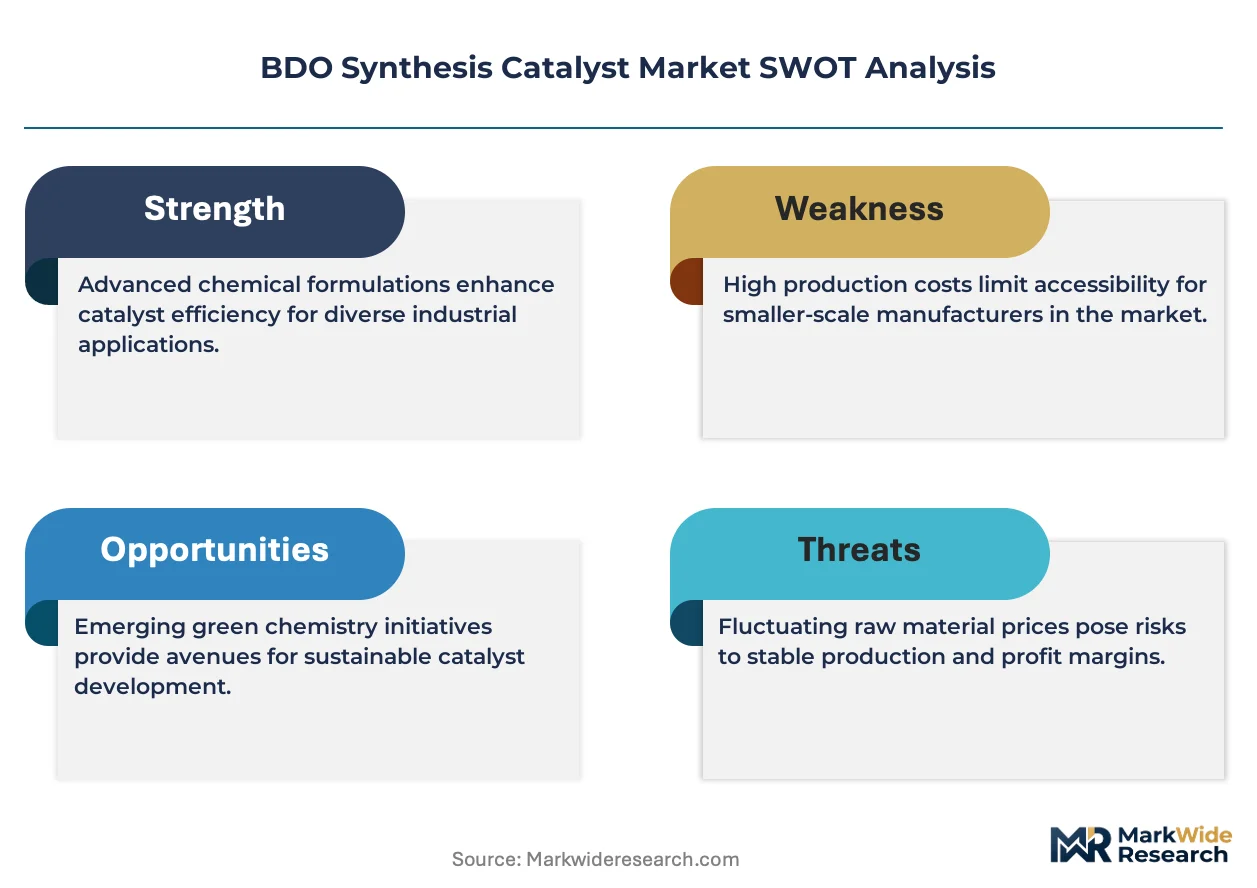
The BDO synthesis catalyst market is rebalancing around a widening performance gap between premium fixed-bed systems and commodity-grade slurry alternatives. BASF leverages its integrated catalyst-to-polymer value chain to sustain pricing power in European polyurethane supply. Johnson Matthey anchors its position through proprietary precious-metal formulations for Reppe process hydrogenation. Haldor Topsoe competes via scale advantages in steam reforming-derived syngas routes.
BDO synthesis catalysts are heterogeneous or homogeneous substances—typically copper-chromite, nickel-based, or noble-metal formulations on alumina or silica supports—that accelerate the conversion of feedstocks such as butyne-1,4-diol or maleic anhydride into 1,4-butanediol under controlled temperature and pressure conditions. These catalysts achieve selectivity rates exceeding 98% in commercial hydrogenation reactors, enabling downstream production of tetrahydrofuran and polybutylene terephthalate. Heterogeneous catalysts dominate installed capacity due to lower separation costs and regenerability, while enzymatic variants represent the fastest-expanding technology segment as bio-based BDO routes gain traction. Hydrogenation technology occupies the largest share of catalyst consumption, though carbonylation processes from maleic anhydride are capturing margin pools in regions with abundant syngas infrastructure.
REACH in Europe and China's GB 31571 emissions standard for the petrochemical industry shape catalyst specifications by mandating lower volatile organic compound releases and stricter heavy-metal content limits. The EPA's New Source Performance Standards for chemical manufacturing plants in the United States further constrain allowable byproduct formation rates in BDO production facilities. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to standardize catalyst platforms or develop region-specific formulations.
Market Dynamics
Integrated BDO-to-PTMEG plants in East China's chemical clusters are consolidating procurement around single-source catalyst suppliers capable of guaranteeing 98%+ hydrogenation selectivity under tightening emissions thresholds.
Growth Catalysts
- REACH and GB 31571 alignment:European and Chinese emissions standards for volatile organic compounds are forcing polyurethane manufacturers to upgrade from commodity slurry catalysts to regenerable fixed-bed systems with lower heavy-metal leaching.
- Bio-based BDO route expansion:Enzymatic catalyst variants are capturing pilot-scale deployment as fermentation-derived feedstocks gain traction in specialty polymer applications requiring renewable content certification.
- Reppe process hydrogenation intensity:Precious-metal formulations on alumina supports are penetrating butanediol production lines serving tetrahydrofuran and spandex fiber markets.
Market Restraints
- Precious-metal input volatility:Palladium and ruthenium price swings compress margin stability for noble-metal catalyst formulations used in high-selectivity hydrogenation stages.
- Supplier concentration in syngas infrastructure:Steam reforming-derived catalyst production clusters in Denmark and Germany create geographic single-point vulnerability for maleic anhydride carbonylation routes.
- Copper-chromite substitution ceiling:Nickel-based alternatives face technical barriers in achieving comparable selectivity rates above 95% in commercial fixed-bed reactors.
Strategic Opportunities
- India's specialty chemical corridor:Gujarat and Maharashtra state industrial zones are greenfielding BDO capacity with open procurement for hydrogenation catalyst systems not locked into incumbent supplier relationships.
- Dual carbon policy tailwinds:China's MEE carbon intensity mandates are accelerating retrofit demand for catalysts enabling lower-temperature hydrogenation with reduced steam consumption.
- Digital catalyst monitoring convergence:IoT-enabled reactor diagnostics paired with predictive regeneration scheduling are creating service-attachment revenue streams beyond commodity catalyst sales.
Industry Challenges
- precious-metal recovery expertise gap:Smaller polyurethane producers lack in-house capability to extract and refine palladium from spent fixed-bed catalysts without third-party tolling.
- Cross-jurisdictional formulation complexity:Catalyst suppliers must maintain parallel product lines to satisfy diverging heavy-metal content limits under EPA New Source Performance Standards versus ECHA REACH annex XVII restrictions.
- Legacy reactor retrofit integration:Existing Reppe process plants face mechanical constraints in accommodating higher-activity catalyst geometries without pressure vessel modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BDO Synthesis Catalyst Market |
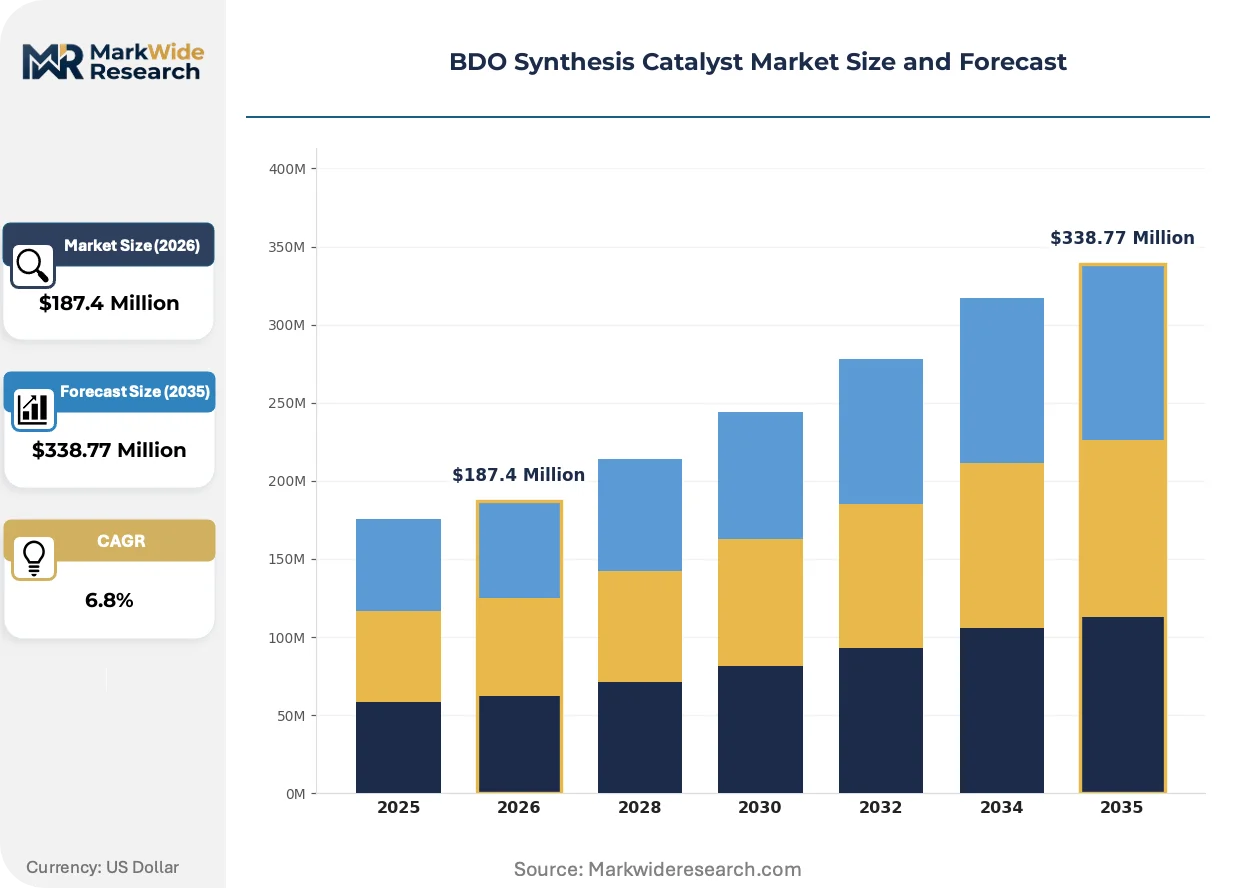
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Catalyst Type: Heterogeneous, Homogeneous, Enzymatic, Mixed Metal Oxide Technology: Hydrogenation, Dehydrogenation, Oxidation, Carbonylation, Esterification Application: Plasticizers Production, Solvents Manufacturing, Polyurethanes, Adhesives, Lubricants End User Industry: Chemical Manufacturers, Coatings Producers, Plastic Fabricators, Adhesive Specialists |
| Companies Covered | BASF, Shepherd Chemical Company, Dalian Reak Technology, Sunchem, Hunan Yussen Energy Technology, Johnson Matthey, Haldor Topsoe, Clariant, Axens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BDO Synthesis Catalyst Market Trends and Innovations
Process intensification and emissions compliance are converging to reshape catalyst specification priorities across BDO production routes, with technology choices increasingly locked in at the engineering procurement stage.
Single-atom catalyst architectures on nitrogen-doped carbon supports are unifying dispersion efficiency with precious-metal loading reduction. PTMEG producers in Zhejiang province are piloting these systems at 40% lower palladium content than conventional impregnated alumina. This unifying technology is compressing the total cost of ownership gap between noble-metal and base-metal hydrogenation pathways.
REACH authorization requirements for chromium(VI) compounds are accelerating copper-zinc oxide formulation development for butynediol hydrogenation. Catalyst manufacturers are reformulating active phases to eliminate hexavalent chromium from copper-chromite precursors without sacrificing mechanical strength. European polyurethane supply chains are absorbing 12-18 month qualification timelines for these replacement systems.
Long-term offtake contracting is displacing spot catalyst purchasing in integrated BDO-PTMEG complexes. Zhejiang and Jiangsu province chemical parks are negotiating five-year catalyst supply agreements with embedded technical service and regeneration clauses. This pattern concentrates procurement leverage with suppliers capable of guaranteeing performance warranties across multiple reactor turnarounds.
BDO Synthesis Catalyst Market Segmentation
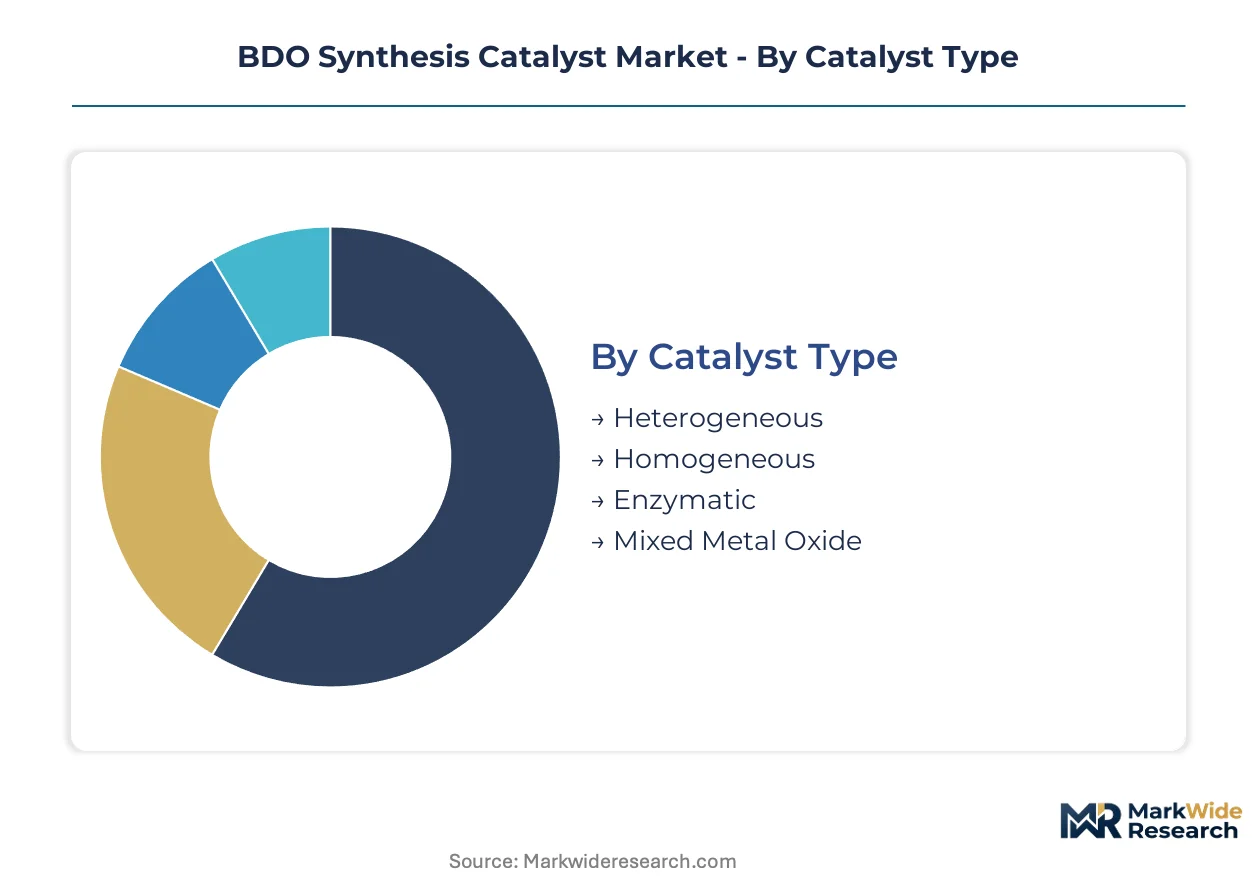
Catalyst selection in BDO production locks in process economics for decades. Procurement patterns diverge sharply between integrated PTMEG operators seeking regeneration cycles and specialty chemical producers prioritizing batch flexibility.
Catalyst Type:
Cost tier separates buyers seeking regenerable fixed-bed systems from those tolerating single-use slurry alternatives.
- Heterogeneous:Copper-chromite and nickel-based formulations on alumina or silica supports dominate commercial hydrogenation reactors. Demand concentrates in East China's integrated BDO-to-PTMEG plants, where regenerability under REACH-aligned emissions thresholds drives procurement decisions.
- Homogeneous:Soluble precious-metal complexes enable precise temperature control in batch hydrogenation of butynediol. German polyurethane manufacturers favor these systems for specialty tetrahydrofuran grades requiring ultra-low metal contamination.
- Enzymatic:Bio-based BDO routes in pilot deployment leverage engineered oxidoreductases for fermentation-derived feedstock conversion.
- Mixed Metal Oxide:Copper-zinc oxide formulations replace chromium-containing precursors under tightening hexavalent chromium restrictions.
Heterogeneous catalysts lead volumes today; enzymatic variants are gaining share fastest.
Technology:
Application chemistry dictates reactor configuration and catalyst specification priorities.
- Hydrogenation:Selective reduction of butynediol or maleic anhydride derivatives consumes the largest catalyst volumes. Zhejiang province chemical parks anchor demand for high-activity precious-metal formulations achieving 98%+ selectivity.
- Carbonylation:Syngas-based routes from maleic anhydride capture margin pools where steam reforming infrastructure exists. Denmark and Germany host concentrated catalyst production serving this technology.
- Dehydrogenation:Tetrahydrofuran production from BDO employs chromium-free copper catalysts in circulating fluidized bed reactors.
- Oxidation:Direct oxidation pathways remain pre-commercial for most BDO derivatives.
- Esterification:Polybutylene terephthalate precursor synthesis uses acid catalysts in separate process trains.
Hydrogenation technology commands installed capacity; carbonylation is climbing the fastest.
Application:
Downstream polymer specifications cascade into catalyst activity and heavy-metal leaching requirements.
- Polyurethanes:PTMEG production for spandex fibers demands hydrogenation catalysts with sub-ppm metal carryover. Jiangsu province plants negotiate five-year supply agreements embedding regeneration clauses.
- Plasticizers Production:BDO-derived adipate esters for PVC compounding tolerate broader catalyst specifications than fiber-grade applications.
- Solvents Manufacturing:Tetrahydrofuran for pharmaceutical extraction requires ultra-high purity BDO feedstock.
- Adhesives:Reactive hot-melt formulations use BDO polyols with less stringent hydrogenation selectivity thresholds.
- Lubricants:Polyalkylene glycol base stocks represent emerging BDO derivative demand.
Polyurethanes anchor consumption volumes; plasticizers are expanding most quickly.
End User Industry:
Scale and integration level determine whether buyers self-regenerate or rely on tolling services.
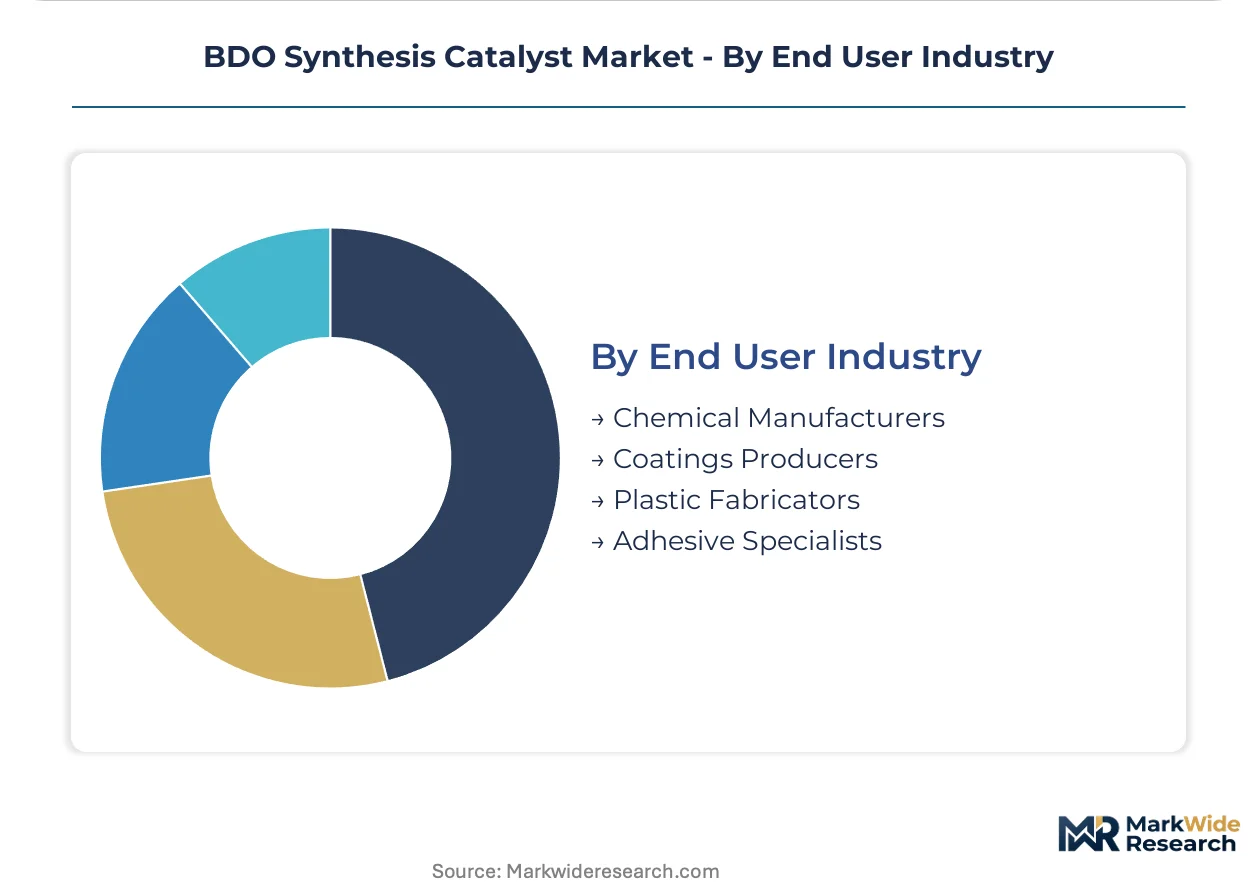
- Chemical Manufacturers:Integrated BDO-PTMEG operators in China's chemical clusters consolidate procurement around single-source suppliers capable of guaranteeing performance across multiple reactor turnarounds.
- Coatings Producers:Polyurethane dispersion manufacturers in Germany source catalyst systems aligned with ECHA REACH authorization timelines for chromium-free formulations.
- Plastic Fabricators:Polybutylene terephthalate producers purchase BDO rather than operating captive hydrogenation capacity.
- Adhesive Specialists:Reactive polyurethane adhesive formulators represent fragmented demand with spot purchasing patterns.
Chemical manufacturers dominate procurement volumes; coatings producers are adopting fixed-bed systems fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalyst engineering talent concentrates in Germany's Ruhr industrial corridor and China's Yangtze River Delta, where hydrogenation process expertise has accumulated across decades of polyurethane supply chain development.
Germany
REACH authorization timelines for chromium-free formulations drive polyurethane manufacturers toward copper-zinc oxide catalyst alternatives. ECHA restrictions on hexavalent chromium compounds force 12-18 month qualification cycles for replacement systems. The North Rhine-Westphalia chemical cluster around Leverkusen and Dormagen anchors BASF's integrated catalyst-to-polymer operations.
China
GB 31571 emissions standards tighten volatile organic compound thresholds for BDO production facilities. MEE carbon intensity mandates accelerate retrofit demand for lower-temperature hydrogenation catalysts. Zhejiang province chemical parks in Ningbo and Shaoxing negotiate five-year supply agreements embedding regeneration clauses and performance warranties.
United States
EPA New Source Performance Standards constrain byproduct formation rates in chemical manufacturing plants. The Gulf Coast petrochemical corridor between Houston and Corpus Christi hosts maleic anhydride carbonylation capacity serving domestic tetrahydrofuran markets. Texas and Louisiana facilities face pressure to align catalyst specifications with cross-border trade requirements.
India
Gujarat and Maharashtra state industrial zones greenfield BDO capacity with open procurement for hydrogenation catalyst systems. BIS standards for chemical process equipment create compliance pathways for imported catalyst technologies. The Dahej and Mundra special economic zones attract catalyst suppliers seeking relationships outside incumbent European and Chinese networks.
Japan
METI industrial decarbonization roadmaps prioritize catalyst efficiency improvements in bulk chemical production. JIS standards for chemical process safety influence reactor design specifications affecting catalyst geometry constraints. The Chubu region around Nagoya maintains specialized hydrogenation catalyst refurbishment capabilities serving domestic PTMEG producers.
BDO Synthesis Catalyst Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across catalyst formulation and reactor engineering segments. The supplier base concentrates around integrated chemical conglomerates with captive catalyst manufacturing and independent specialty catalyst houses. Three archetypes dominate: precious-metal formulation specialists, base-metal scale producers, and integrated polymer-catalyst value chain operators. Competitive moves center on five-year offtake contracting with embedded technical services and geographic expansion through tolling partnerships in emerging chemical corridors.
Within the integrated chemical conglomerate tier, BASF anchors European supply through its catalyst-to-polymer value chain control. Among precious-metal formulation specialists, Johnson Matthey occupies a position exemplifying proprietary alumina-supported hydrogenation systems. Haldor Topsoe represents the syngas-route scale producer archetype with concentrated production serving maleic anhydride carbonylation demand.
| Leading Market Players |
|---|
| BASF |
| Shepherd Chemical Company |
| Dalian Reak Technology |
| Sunchem |
| Hunan Yussen Energy Technology |
| Johnson Matthey |
| Haldor Topsoe |
| Clariant |
| Axens |
| Others |
Pricing and Supply Chain Analysis
Palladium and ruthenium price volatility cascades through fixed-bed catalyst tiers, compressing margins for noble-metal formulations while copper-zinc oxide alternatives capture procurement share in REACH-aligned European supply chains. Long-term offtake contracting with embedded regeneration services now separates premium supplier relationships from commodity spot purchasing in East China's integrated BDO-to-PTMEG complexes.
Pricing Analysis
The bundled-vs-unbundled service split separates catalyst procurement into two distinct value tiers. Long-term supply agreements embedding technical service, predictive regeneration scheduling, and performance warranties command premium positioning against spot-market commodity catalyst sales. Price differentiation rests on regeneration capability guarantees and heavy-metal leaching compliance certification under ECHA REACH and China's GB 31571 standards. Pricing pressure stems from precious-metal input volatility compressing noble-metal formulation margins. Small polyurethane producers exhibit highest price sensitivity due to limited in-house precious-metal recovery expertise, while integrated chemical manufacturers absorb premium tier costs through captive regeneration infrastructure.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr corridor and China's Yangtze River Delta maintain hub-and-spoke patterns serving hydrogenation catalyst demand. Production concentrates in Germany, China, and Denmark, with steam reforming-derived syngas routes anchored in Danish and German manufacturing clusters. Raw material dependencies include alumina and silica support materials, copper and nickel active-phase metals, and palladium-ruthenium precious-metal inputs. Single-source vulnerability in syngas infrastructure creates geographic concentration risk for maleic anhydride carbonylation catalyst supply. Distribution runs through integrated BDO-PTMEG plant procurement channels with five-year contracting displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BDO synthesis catalyst market functions as a geographic-arbitrage play where REACH authorization timelines in Europe and GB 31571 compliance windows in China create 12-18 month lead-time differentials for chromium-free formulation qualification.
For Market Incumbents: Hedge precious-metal exposure through tolling partnerships with spent catalyst recovery specialists in Japan's Chubu region. BASF and Johnson Matthey should deepen backward integration into alumina support manufacturing to defend margin position against copper-zinc oxide substitution. Capacity addition in Gujarat and Maharashtra chemical corridors captures India's greenfield BDO procurement before supplier relationships crystallize. For New Entrants and Emerging Players: The premium-to-economy price-point gap in fixed-bed hydrogenation systems creates entry space for regenerable base-metal alternatives achieving 95%+ selectivity. Target India's Dahej and Mundra special economic zones where open procurement for catalyst systems persists outside incumbent European and Chinese networks. Pursue technical service bundling as the primary go-to-market angle, embedding IoT-enabled reactor diagnostics to differentiate from commodity catalyst suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional catalyst refurbishment specialists because precious-metal recovery expertise concentrates in fragmented tolling operations across Japan, Germany, and China. Platform consolidation of these mid-cap service providers captures recurring revenue streams from regeneration cycles. Watch for dual carbon policy acceleration in China's MEE enforcement as the inflection signal for lower-temperature hydrogenation catalyst retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year offtake contracting with embedded regeneration clauses locks in procurement leverage with Zhejiang province chemical parks. |
| Backward Integration | In-house alumina support production reduces precious-metal formulation cost exposure for Johnson Matthey and BASF. |
| Green Manufacturing Transition | Copper-zinc oxide formulations eliminate hexavalent chromium to satisfy ECHA REACH authorization timelines. |
| Capacity Expansion | Greenfield hydrogenation catalyst production in Gujarat and Maharashtra captures India's emerging BDO capacity. |
| Joint Venture | Tolling partnerships with Japanese Chubu region refiners secure palladium recovery capabilities for European polyurethane producers. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged plant managers at integrated BDO-PTMEG facilities, procurement leads at polyurethane manufacturers, technical R&D directors at catalyst formulators, and channel partners in regional distribution networks. Secondary sources included customs and trade data, SEC 10-K filings from chemical conglomerates, ECHA REACH authorization databases, and Chinese GB standards documentation. Bottom-up capacity and consumption estimates triangulated against top-down industry association data from Cefic and the American Chemistry Council.
Granularity-level modeling disaggregated volume and value outputs across catalyst type, hydrogenation technology application, and end-use industry segments throughout the forecast period. The analytical framework projected hydrogenation selectivity thresholds, precious-metal loading requirements, and regeneration cycle economics across the projection horizon. CAGRs derived from segment-level growth trajectories weighted by regional production capacity shares. Industry-specific inputs included MEE carbon intensity mandate enforcement timelines and ECHA chromium(VI) compound restriction phase-in schedules.
Caveats apply where precious-metal price volatility, REACH-GB regulatory divergence, or bio-based BDO route commercialization could materially shift the outlook. Forecasts reflect documented assumptions around emissions standard enforcement consistency and syngas infrastructure expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Catalyst Regeneration Market
Catalysts
North America Industrial Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Natural Zeolites Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
North America Refining Catalysts Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Global FCC Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Photocatalyst Market