
 Air Filtration Media Market | 2026-2036
Air Filtration Media Market Size, Share, and Industry Trends Forecast 2026-2036
Air Filtration Media Market Outlook
Glass microfiber is hardening its position against synthetic meltblown alternatives in high-efficiency applications, driven by superior particulate capture rates and thermal stability. Donaldson Company leverages its vertical engine filtration platform to extend media expertise into industrial clean air systems. Freudenberg Filtration Technologies sustains R&D intensity across pleated and pocket configurations for HVAC OEMs. Ahlstrom-Munksjö anchors European supply through specialty wetlaid nonwoven operations in Finland and Italy.
Air filtration media comprises engineered fibrous matrices—glass microfiber, synthetic polymers, activated carbon composites, or natural fibers—manufactured to specified MERV, HEPA, or ULPA efficiency ratings with defined pressure-drop curves and dust-holding capacities. These materials remove particulate, gaseous, or biological contaminants from air streams to protect equipment, processes, or human respiratory health. HEPA media commands premium positioning in healthcare and cleanroom end uses where 99.97% efficiency at 0.3 micron is mandatory. Activated carbon segments compete on impregnation chemistry and adsorption kinetics for industrial vapor-phase applications. Panel form factors dominate replacement cycles in commercial HVAC, while cartridge configurations lead in heavy manufacturing environments.
The EPA enforces NAAQS revisions that tighten allowable PM2.5 thresholds, compelling facility operators to upgrade from MERV 8 to MERV 13+ media. OSHA indoor air quality guidelines and ASHRAE Standard 62.1 ventilation requirements shape product specifications across commercial and institutional buildings. ISO 16890 test protocols for HVAC filters and IEST-RP-CC001 cleanroom standards define international performance benchmarks. Stakeholders must monitor regulatory alignment between regional efficiency mandates and their existing media certification portfolios.
Market Dynamics
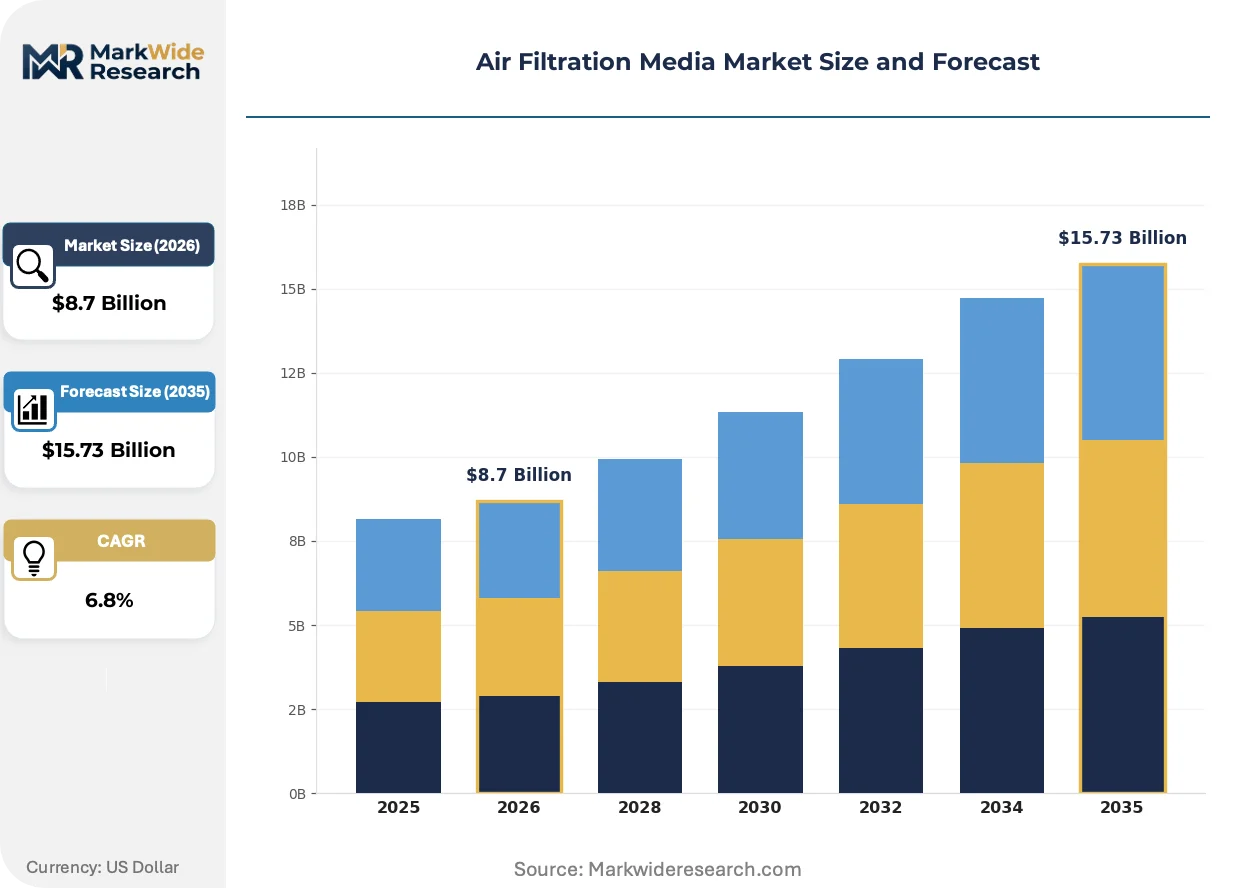
The EPA's tightened PM2.5 National Ambient Air Quality Standards are forcing facility operators across industrial and commercial segments to upgrade filtration infrastructure, compressing replacement cycles and elevating efficiency specifications throughout the supply chain.
Growth Catalysts
- Healthcare Infrastructure Expansion:Hospital construction in China's industrial corridor cities drives HEPA-grade system installations. Operating rooms and isolation wards mandate 99.97% efficiency at 0.3 micron.
- ASHRAE Standard 62.1:Ventilation requirements in commercial buildings compel MERV 13+ retrofits. Property managers face compliance deadlines that accelerate media replacement schedules.
- Glass Microfiber Superiority:Thermal stability and particulate capture rates above synthetic meltblown alternatives secure position in high-efficiency applications. Cleanroom operators specify wetlaid nonwoven constructions.
Market Restraints
- Specialty Glass Fiber Supply Concentration:European wetlaid operations in Finland and Italy anchor premium media supply. Disruptions cascade through HEPA and ULPA certification pipelines.
- Activated Carbon Input Volatility:Coconut shell and coal-based carbon prices fluctuate with agricultural yields and mining permits. Impregnation chemistry costs compress margin on vapor-phase applications.
- ISO 16890 Test Protocol Friction:Regional efficiency mandates misalign with existing media certification portfolios. Manufacturers maintain parallel testing streams for HVAC export markets.
Strategic Opportunities
- Industrial Corridor Retrofits:Chinese manufacturers face dual carbon goals and MEE enforcement. Facility upgrades create demand for cartridge configurations in heavy manufacturing environments.
- Smart Filtration Convergence:Pressure-drop sensors and IoT monitoring integrate with pleated and pocket configurations. Predictive maintenance contracts extend OEM relationships beyond replacement cycles.
- Natural Fiber Positioning:Biodegradable matrices target sustainability-conscious buyers in European institutional buildings. Wetlaid operations diversify feedstock beyond glass and synthetics.
Industry Challenges
- IEST-RP-CC001 Certification Timeline:Cleanroom media validation requires extended laboratory protocols. Product launches delay six to twelve months behind formulation completion.
- Legacy HVAC System Integration:Panel form factor replacements in commercial buildings encounter ductwork constraints. Retrofit specialists engineer adapter assemblies for non-standard installations.
- Technical Talent Scarcity:Formulation chemists with glass microfiber and synthetic polymer expertise command premium compensation. R&D intensity concentrates among established filtration technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Filtration Media Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: HEPA, Activated Carbon, Electrostatic, Fiberglass Application: Residential, Industrial, Automotive, HVAC Form Factor: Panels, Bags, Cartridges, Rolls End User: Manufacturing, Healthcare, Commercial, Government |
| Companies Covered | 3M, Ahlstrom-Munksjö, Donaldson Company, Freudenberg Filtration Technologies, Berry Global, Calgon Carbon Corporation, Lydall, Hollingsworth & Vose, AIM Nonwovens and Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Filtration Media Market Strategic Shifts
Material science advances and regulatory stringency are compressing the gap between HVAC and cleanroom performance thresholds, while digital monitoring capabilities reshape how buyers evaluate total cost of ownership across replacement cycles.
Electrospun nanofiber surface layers are absorbing premium positioning in mid-efficiency applications previously served by meltblown media. Commercial building operators specify these constructions to achieve MERV 13+ ratings without excessive pressure-drop penalties. The technology is absorbing market share from conventional synthetic depth media in retrofit-heavy segments.
REACH restrictions on persistent organic pollutants are eliminating certain fluorinated treatments from glass microfiber formulations. European HVAC OEMs reformulate hydrophobic coatings to maintain oil-mist resistance in kitchen and industrial exhaust applications. The F-Gas Regulation's phase-down schedule accelerates development of low-global-warming-potential membrane alternatives for specialized containment.
Buyers now unbundle filter supply from installation and monitoring services, fragmenting procurement across specialized distributors and direct manufacturer relationships. Large facility management groups centralize specifications through corporate sustainability offices rather than regional maintenance teams. This pattern concentrates most visibly in US healthcare systems consolidating under national GPO contracts.
Air Filtration Media Market Segmentation
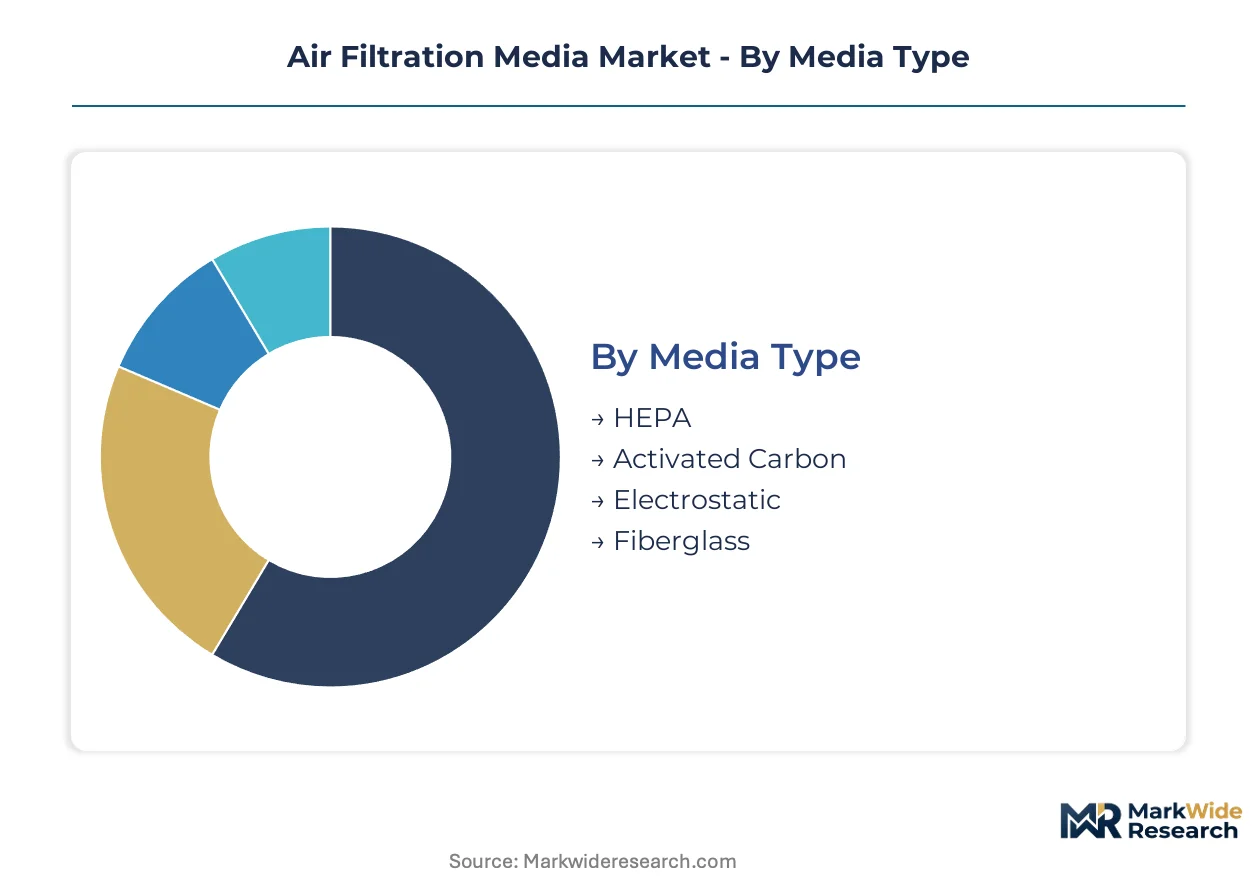
Air filtration media segmentation reveals how technical specifications, application environments, and procurement channels fragment into distinct competitive arenas. Each dimension carries unique margin profiles, certification requirements, and customer loyalty patterns that shape supplier strategy.
Media Type:
Glass microfiber commands premium positioning while synthetic alternatives capture volume through cost efficiency and manufacturing scalability.
- HEPA:Wetlaid glass microfiber matrices achieve 99.97% efficiency at 0.3 micron through controlled fiber diameters and binder chemistry. Hospital construction in China's industrial corridor cities drives specification for operating rooms and isolation wards. EPA's tightened PM2.5 National Ambient Air Quality Standards compress replacement cycles in healthcare retrofits.
- Activated Carbon:Impregnated carbon composites compete on adsorption kinetics and surface area metrics for vapor-phase industrial applications. Coconut shell and coal-based input prices fluctuate with agricultural yields and mining permits, compressing margin stability.
- Electrostatic:Charged synthetic media delivers mid-efficiency capture at reduced pressure-drop penalties. Commercial HVAC retrofits specify these constructions for MERV 11-13 performance without fan motor upgrades.
- Fiberglass:Depth-loading synthetic glass constructions dominate residential furnace filter replacement cycles. Big-box retail distribution and private-label contracts concentrate procurement among mass-market suppliers.
Today's leader: HEPA. Tomorrow's challenger: Electrostatic.
Application:
Regulatory intensity and asset replacement cycles create divergent growth trajectories across end-use environments.
- Residential:Panel form factor replacements follow seasonal patterns tied to heating and cooling system maintenance. MERV 8-11 specifications dominate, with MERV 13 gaining share through ASHRAE Standard 62.1 awareness campaigns.
- Industrial:Cartridge configurations lead in heavy manufacturing environments where dust-loading capacity and pulse-clean compatibility determine specification. Chinese manufacturers retrofit facilities under dual carbon goals and MEE enforcement, creating demand concentration.
- Automotive:Cabin air filtration specifications split between standard particulate and combination carbon-HEPA constructions for premium vehicle segments. OEM supply agreements lock in multi-year volume commitments with stringent qualification protocols.
- HVAC:Commercial building operators face ASHRAE Standard 62.1 ventilation requirements that compel MERV 13+ retrofits. Property managers navigate compliance deadlines that accelerate media replacement schedules across institutional portfolios.
Industrial applications climb the fastest on regulatory enforcement. Residential maintains volume leadership through replacement cycle density.
Form Factor:
Installation labor economics and system architecture dictate form factor selection across new construction versus retrofit opportunities.
- Panels:Rigid framed constructions dominate commercial HVAC replacement cycles through standardized dimensional compatibility. Facility management groups centralize specifications through corporate sustainability offices rather than regional maintenance teams.
- Bags:Pocket configurations deliver extended dust-holding capacity in high-volume air handling systems. Industrial cleanrooms and pharmaceutical manufacturing specify multi-pocket arrays for continuous operation intervals.
- Cartridges:Cylindrical pleated constructions integrate with pulse-jet cleaning systems in heavy manufacturing dust collection. Chinese industrial corridor retrofits favor cartridge configurations for their compatibility with existing ductwork infrastructure.
- Rolls:Bulk media supply enables custom fabrication by OEMs and specialized filter manufacturers. Variable dimensions and efficiency grades support non-standard industrial applications and prototype development.
Panels anchor current revenue through replacement density. Cartridges represent the steepest expansion trajectory on industrial retrofit demand.
End User:
Procurement sophistication and total cost of ownership evaluation maturity separate institutional buyers from transactional purchasers.
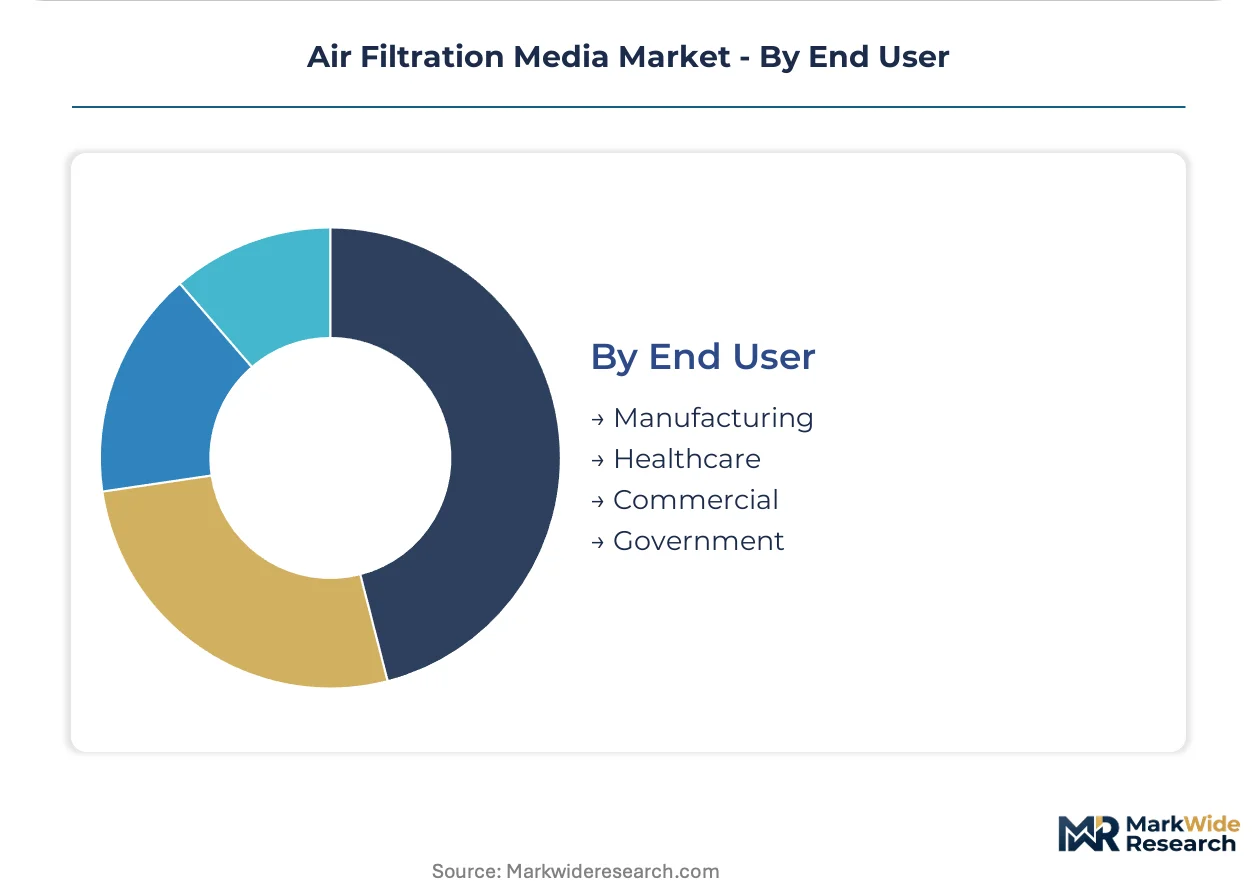
- Manufacturing:Process protection and worker safety drive specification for high-efficiency media in cleanroom and containment applications. ISO 16890 test protocols and IEST-RP-CC001 cleanroom standards define performance benchmarks for supplier qualification.
- Healthcare:Infection control protocols mandate HEPA-grade systems in operating rooms, isolation wards, and pharmaceutical compounding areas. US healthcare systems consolidating under national GPO contracts concentrate procurement through centralized sustainability offices.
- Commercial:Property managers balance first-cost constraints against energy consumption penalties from excessive pressure-drop. ASHRAE Standard 62.1 compliance deadlines accelerate upgrade timelines across Class A office and retail portfolios.
- Government:Federal and municipal procurement follows standardized specifications with extended qualification timelines. Defense and nuclear applications impose additional security clearance and traceability requirements on media suppliers.
Healthcare leads on specification intensity. Manufacturing offers the broadest addressable base across efficiency tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor cities concentrate retrofit demand as manufacturers face dual carbon goals and MEE enforcement. Facility operators across Tianjin, Suzhou, and Shenzhen upgrade dust collection infrastructure. The EPA's tightened PM2.5 standards in the United States compress replacement cycles for commercial HVAC systems.
United States
Healthcare systems consolidating under national GPO contracts drive HEPA-grade specifications for operating rooms and isolation wards. The EPA enforces NAAQS revisions that tighten allowable PM2.5 thresholds, compelling facility operators to upgrade from MERV 8 to MERV 13+ media. Hospital construction concentrates in Texas, Florida, and the Southeast corridor where population migration accelerates infrastructure investment.
Germany
Automotive OEMs specify combination carbon-HEPA constructions for premium vehicle cabin air systems, locking in multi-year volume commitments. The F-Gas Regulation's phase-down schedule accelerates development of low-global-warming-potential membrane alternatives for specialized containment. Manufacturing clusters in Bavaria and Baden-Württemberg anchor supply relationships with tier-one filtration suppliers.
China
Industrial corridor cities from Tianjin to Suzhou retrofit facilities under dual carbon goals and MEE enforcement, creating demand concentration for cartridge configurations. The country's national environmental regulator tightens emissions standards across heavy manufacturing sectors. Pharmaceutical manufacturing expansion in Jiangsu and Zhejiang provinces drives cleanroom media validation requirements.
India
Commercial building operators navigate BIS efficiency mandates alongside ASHRAE-aligned ventilation upgrades in metro office portfolios. The country's national standards body aligns HVAC filtration specifications with international test protocols. Construction activity concentrates in Maharashtra, Karnataka, and Telangana where IT/ITES campuses drive specification intensity.
Japan
Semiconductor fabrication facilities demand ULPA-grade media for advanced node production environments with zero-tolerance contamination protocols. METI industrial policy supports domestic supply chain resilience for critical filtration components. Cleanroom construction concentrates in the Kyushu region and Hiroshima prefecture where memory and logic foundries expand capacity.
Air Filtration Media Market Competitive Environment
Global majors compete with regional champions across certification depth and application specialization. The vendor base organizes around three tiers: integrated filtration technology platforms with captive media operations, specialty nonwoven manufacturers supplying OEM filter fabricators, and regional converters serving replacement cycle demand. Consolidation pressure concentrates in synthetic meltblown segments where scale economies dominate. Strategic moves center on backward integration into fiber production and technology licensing for electrospun nanofiber surface layers.
Among integrated technology platforms, Donaldson Company and Freudenberg Filtration Technologies exemplify archetypes combining engine filtration expertise with industrial clean air system extension. Ahlstrom-Munksjö occupies a position within specialty wetlaid nonwoven supply, anchoring European HEPA and ULPA certification pipelines through Finland and Italy-based operations. These three represent distinct competitive positions: vertical engine filtration leverage, diversified HVAC and cleanroom R&D intensity, and regional specialty nonwoven concentration respectively.
| Leading Market Players |
|---|
| 3M |
| Ahlstrom-Munksjö |
| Donaldson Company |
| Freudenberg Filtration Technologies |
| Berry Global |
| Calgon Carbon Corporation |
| Lydall |
| Hollingsworth & Vose |
| AIM Nonwovens and Interiors |
| Others |
Value Chain & Pricing Dynamics
Healthcare systems consolidating under national GPO contracts concentrate procurement power and compress margin capture across HEPA-grade media tiers. This buyer concentration forces suppliers into three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Specialty glass fiber and activated carbon input costs cascade directly into finished media quotations through quarterly adjustment clauses. Price differentiation hinges on MERV certification tier and wetlaid manufacturing origin, with Finnish and Italian-sourced glass microfiber commanding premiums over synthetic meltblown alternatives. Cost compression in mid-efficiency segments intensifies as electrospun nanofiber surface layers displace conventional depth media. Residential furnace filter buyers exhibit highest price sensitivity, while cleanroom operators prioritize IEST-RP-CC001 certification over unit economics.
Supply Chain Analysis
Reverse logistics for spent cartridge configurations remain underdeveloped, with most industrial users disposing rather than refurbishing pulse-jet compatible elements. Wetlaid glass microfiber production concentrates in Finland, Italy, and the United States, while activated carbon feedstock draws from coconut shell operations in Sri Lanka and Indonesia plus coal-based sources in China. Single-source vulnerability pervades HEPA certification pipelines where European operations anchor global supply. Distribution runs through specialized industrial distributors for cartridge configurations and big-box retail channels for residential panel replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air filtration media has entered a late-cycle quality phase where specification intensity trumps volume growth, driven by EPA PM2.5 enforcement compelling MERV 13+ upgrades across commercial building portfolios.
For Market Incumbents: Cement supply security through backward integration into specialty glass fiber production or captive wetlaid operations in Finland and Italy. Expand ISO 16890 certification depth to defend against electrospun nanofiber substitutes in mid-efficiency retrofits. Prioritize IoT-enabled predictive maintenance contracts to extend OEM relationships beyond transactional replacement cycles. For New Entrants and Emerging Players: Regional hospital construction consortia in China's industrial corridor cities represent the most penetrable buyer archetype for HEPA-grade system installations. Target biodegradable natural fiber matrices for European institutional sustainability mandates as a differentiated entry vector. Pursue direct manufacturer relationships with facility management groups centralizing specifications through corporate sustainability offices. For Investors and Strategic Acquirers: Industrial filtration technology platforms are the most active acquirers in this space, seeking electrospun nanofiber capabilities and cleanroom certification pipelines. Five-to-ten year viability rests on regulatory enforcement durability rather than cyclical construction activity. Target acquisition candidates with IEST-RP-CC001 validation infrastructure and established pharmaceutical manufacturing relationships. Monitor EPA NAAQS enforcement intensity and MEE inspection frequency in China as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Production | Secures supply continuity for HEPA and ULPA certification pipelines against European concentration risk. |
| Electrospun Nanofiber Surface Layer Development | Captures mid-efficiency retrofit demand from synthetic meltblown media in ASHRAE 62.1 compliance upgrades. |
| IoT-Enabled Predictive Maintenance Contracts | Transforms transactional panel and cartridge replacement into recurring revenue relationships with facility operators. |
| Natural Fiber Matrix Formulation | Positions biodegradable alternatives for REACH-compliant European institutional procurement specifications. |
| Cleanroom Certification Pipeline Expansion | Accelerates IEST-RP-CC001 validation timelines to match pharmaceutical manufacturing expansion in Jiangsu and Zhejiang. |
Study Parameters
Bottom-up HVAC and cleanroom modeling reconciled against top-down glass microfiber and synthetic polymer supply tracking forms the analytical core of this study. Primary interviews with filtration media R&D directors, commercial HVAC procurement managers, hospital GPO contract specialists, and industrial facility maintenance heads combined with secondary validation from EPA NAAQS filings, ASHRAE standard documentation, customs trade data, and SEC 10-K disclosures from integrated filtration technology platforms. Triangulation across these sources ensures segment-level precision.
Input-output matrices map raw material flows through wetlaid and meltblown manufacturing stages to end-use applications across the projection horizon. Segmentation dimensions include media type, application environment, form factor, and end-user procurement sophistication. CAGR derivation incorporates replacement cycle compression from regulatory enforcement, hospital construction pipelines, and industrial retrofit timelines. Forecast inputs include EPA enforcement intensity metrics and MEE inspection frequency data from China's industrial corridor cities.
Underlying measurement precision varies by segment; HEPA and activated carbon categories carry tighter precision than residential fiberglass given certification standardization. Forecasts reflect assumptions about regulatory enforcement durability and input cost pass-through mechanics. Practitioners should monitor EPA PM2.5 standard revision timelines and coconut shell agricultural yield reports for early demand and margin signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Sintered Metal Filters Market
Filters
Europe Industrial Air Filtration Market
Filters
Chloramine Filter Market
Filters
Canada Filtration and Separation Market
Filters
Europe Activated Carbon Market
Filters
Color Filter Glass Market
Filters
String Wound Filter Materials Market
Filters
Global Depth Filtration Market
Filters
Fabric Filters Market
Filters
Coolant Filtration Skids Market
Filters
Global Gas Phase Filtration Market
Filters
Filtering Centrifuges Market
Filters
Activated Carbon Market
Filters
Round Plate Filter Press Market
Filters
Global Gas Filtration Media Market
Filters
Global Liquid Filtration Market