
 Africa Sodium Cyanide Market | 2026-2036
Africa Sodium Cyanide Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Sodium Cyanide Market Outlook
Gold mining is recalibrating the Africa Sodium Cyanide Market as heap-leach operations expand across West African greenstone belts. Sasol leverages its integrated chemical manufacturing base in South Africa to sustain regional supply chain density. Orica Limited anchors explosives and reagent distribution networks across multiple African mining jurisdictions. The Chemours Company competes through specialized solid-form cyanide packaging optimized for remote-site logistics.
Sodium cyanide is an inorganic compound with the formula NaCN, typically manufactured through the Andrussow process or BMA (Blausäure-Methan-Ammoniak) process yielding briquettes or granular forms with purity grades exceeding 98 percent; its primary function is as a lixiviant in precious-metal extraction, forming stable cyanoaurate complexes that enable gold recovery from low-grade ores. Solid sodium cyanide dominates procurement volumes across African mining corridors due to superior shelf stability and transport economics. Liquid formulations represent the fastest-growing category as on-site dilution systems reduce handling risks and align with evolving safety protocols. Granular and crystalline grades command premium positioning where dissolution kinetics directly influence metallurgical recovery rates.
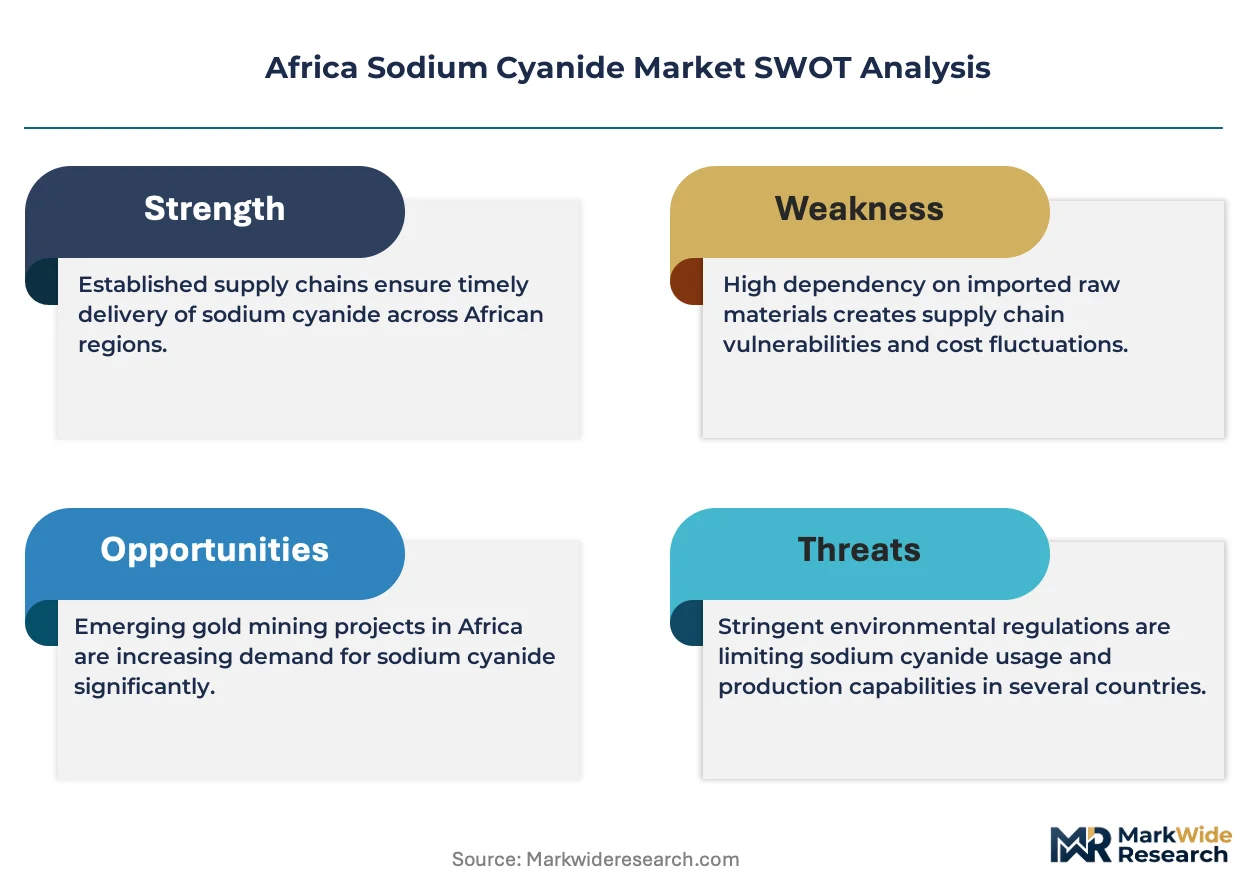
South Africa's Department of Mineral Resources and Energy enforces tailings facility compliance under the National Environmental Management Act, while Ghana's Environmental Protection Agency mandates cyanide management codes aligned with the International Cyanide Management Institute framework; these dual regulatory layers elevate product certification requirements and restrict market access for uncertified suppliers. Kenya's National Environment Management Authority and Tanzania's Mining Commission are adopting analogous standards, broadening the compliance perimeter across East African extractive zones. Stakeholders must monitor regulatory harmonization trajectories and pre-empt certification investments before procurement specifications tighten across additional jurisdictions.
Market Dynamics
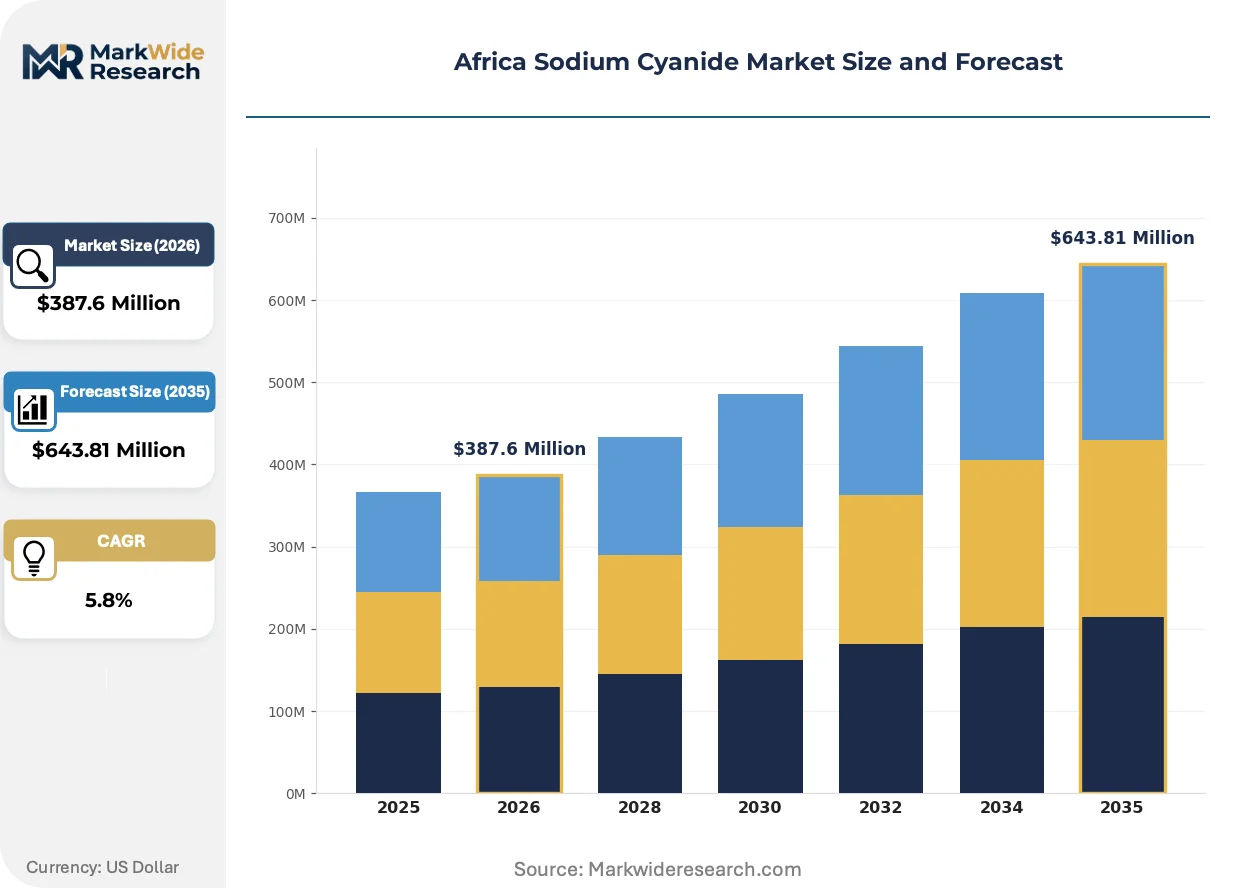
Heap-leach gold extraction across West African greenstone belts is intensifying sodium cyanide procurement volumes, while South Africa's National Environmental Management Act enforcement is compressing supplier certification timelines and elevating purity specifications across the value chain.
Growth Catalysts
- International Cyanide Management Institute certification:Ghana's Environmental Protection Agency mandates ICMI-aligned cyanide management codes, creating procurement preference for certified suppliers across the Ashanti gold belt.
- Heap-leach circuit expansion:Brownfield mine developments in Mali and Burkina Faso are scaling sodium cyanide offtake for low-grade ore processing.
- Carbon-in-pulp technology adoption:West African mining operators are retrofitting processing plants with CIP circuits that optimize cyanide consumption rates per ounce recovered.
Market Restraints
- Caustic soda feedstock volatility:Sodium cyanide production costs track caustic soda and ammonia input prices, which fluctuate with energy markets and chlor-alkali plant operating rates.
- South African supply concentration:Sasol's integrated chemical complex near Johannesburg anchors regional manufacturing, creating single-source vulnerability for East and West African buyers.
- Hydrogen cyanide handling restrictions:The Andrussow process requires HCN intermediate management under strict occupational exposure limits, constraining new entrant capacity additions.
Strategic Opportunities
- Tanzania's Mining Commission alignment:Regulatory harmonization with ICMI standards is opening certification pathways for suppliers previously excluded from East African procurement.
- Liquid formulation dilution systems:On-site mixing infrastructure reduces transport tonnage and handling risk, creating service-revenue attachment opportunities for chemical distributors.
- Kenya's National Environment Management Authority adoption:Analogous cyanide management protocols to Ghana and Tanzania are expanding the compliant supplier addressable market in East Africa.
Industry Challenges
- Metallurgical chemist scarcity:Heap-leach optimization and cyanide destruction circuit design require specialized expertise that mining operators struggle to source locally.
- Tailings facility compliance timelines:South Africa's Department of Mineral Resources and Energy enforcement actions are accelerating facility upgrade deadlines, compressing reagent qualification windows.
- Multi-jurisdiction certification complexity:Suppliers must maintain parallel compliance with Ghana's EPA, Tanzania's Mining Commission, and Kenya's NEMA requirements, fragmenting quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Sodium Cyanide Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Granular, Crystalline Application: Mining, Agriculture, Chemical Production, Pharmaceuticals Form: Powder, Solution, Blocks, Tablets End User: Mining Companies, Agricultural Firms, Chemical Manufacturers, Research Institutions |
| Companies Covered | TSPC, The Chemours Company, Sasol, HeBei ChengXin, Evonik Industries, Orica Limited, Australian Gold Reagents Pty Ltd, Honeywell International, TAEKWANG INDUSTRIAL CO., LTD, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Sodium Cyanide Market Strategic Shifts
Solid-form packaging innovations and on-site dilution infrastructure are reshaping how sodium cyanide moves from manufacturing nodes to remote mining sites across African extraction corridors.
Specialized solid briquette formulations with optimized dissolution kinetics are unifying transport efficiency with metallurgical performance. Mining operators in Mali and Burkina Faso are adopting these grades to reduce dissolution tank residence times. The technology is unifying logistics cost compression with recovery rate improvements in low-grade heap-leach operations.
South Africa's National Environmental Management Act tailings facility protocols are mandating cyanide destruction circuit verification and water quality monitoring. Mining license renewals now require demonstrated compliance with progressive rehabilitation schedules. The regulatory pressure is elevating demand for higher-purity reagent grades that minimize residual cyanide in tailings streams.
Buyer concentration among major gold mining houses is consolidating procurement decisions through centralized chemical management contracts. Distributors with multi-site service capabilities are displacing single-mine supply arrangements. This pattern is most visible in Ghana, where AngloGold Ashanti and Newmont operations have standardized on integrated reagent and logistics packages.
Africa Sodium Cyanide Market Segmentation
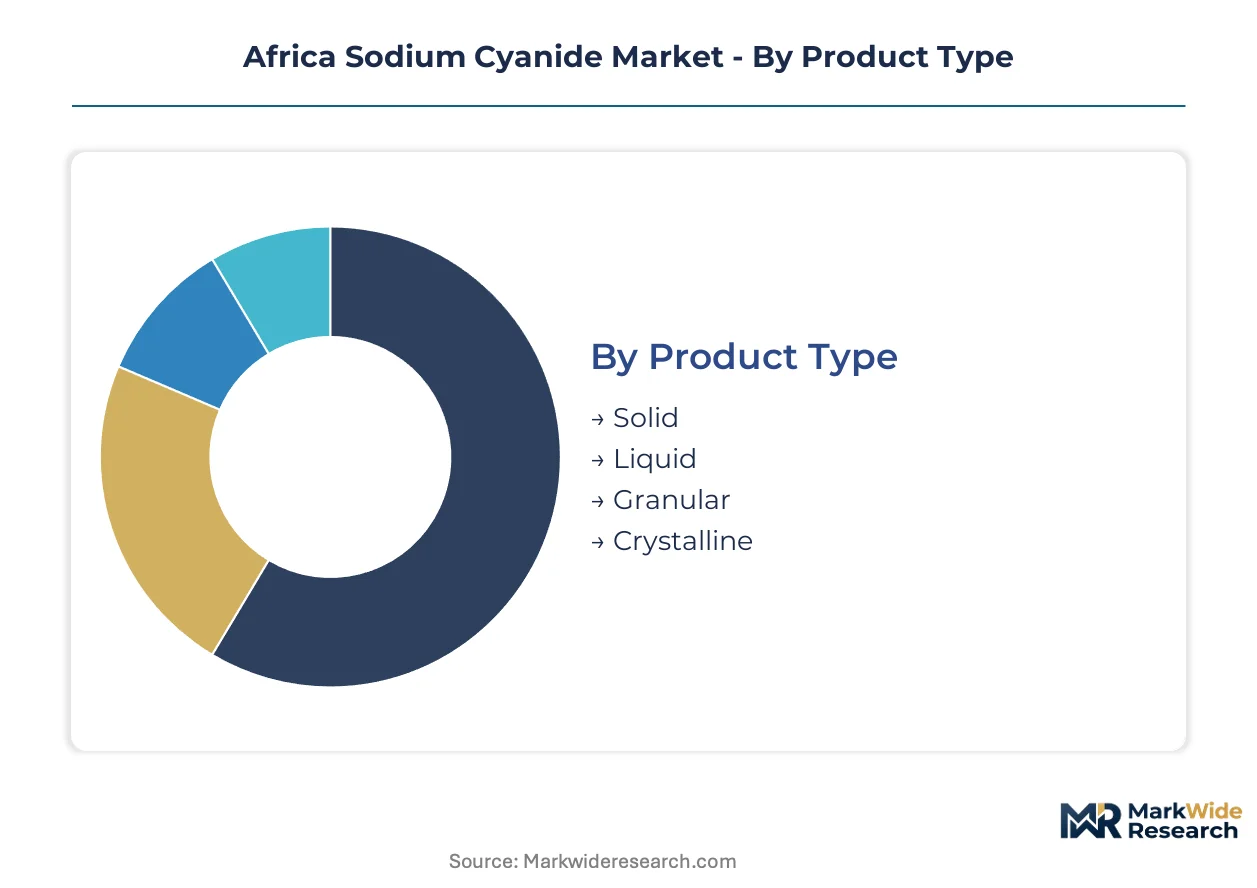
Gold extraction economics and regulatory compliance are fragmenting procurement patterns across African sodium cyanide markets. Buyers prioritize transport efficiency, dissolution kinetics, and certification alignment over commodity pricing alone.
Product Type:
Cost tier differentiation separates large-scale heap-leach operators from smaller carbon-in-pulp facilities.
- Solid:Briquette and granular formulations exceeding 98% purity dominate procurement volumes across Ghana, Mali, and Burkina Faso mining corridors. Shelf stability and containerized transport economics anchor demand from remote West African greenstone belt operations where road infrastructure limits liquid delivery logistics.
- Liquid:Pre-diluted solutions reduce on-site handling risks and align with South Africa's National Environmental Management Act safety protocols. Adoption concentrates among South African gold majors retrofitting processing plants with closed-loop dilution systems that minimize occupational exposure incidents.
- Granular:Intermediate particle size grades optimize dissolution tank residence times for medium-scale operators.
- Crystalline:High-purity grades command premium positioning where metallurgical recovery rates directly influence project economics.
Volume sits with Solid; growth tilts toward Liquid.
Application:
End-use maturity separates established extraction technologies from emerging regulatory-driven categories.
- Mining:Lixiviant applications in precious-metal extraction consume the majority of African sodium cyanide offtake. Heap-leach and carbon-in-pulp circuits across Ghana's Ashanti belt and Mali's Yanfolila district anchor procurement volumes as brownfield expansions scale processing capacity.
- Agriculture:Fumigation and pest control applications are expanding in Kenya and Tanzania as national environment authorities adopt cyanide management codes. Regulatory alignment with International Cyanide Management Institute standards is opening certification pathways for agricultural distributors previously excluded from chemical procurement.
- Chemical Production:Intermediate synthesis for specialty chemicals and plastics additives.
- Pharmaceuticals:Precursor applications in pharmaceutical manufacturing.
Mining commands current volume; Agriculture shows steepest expansion trajectory as East African regulatory harmonization proceeds.
Form:
Supply chain configuration determines form selection across extraction and industrial applications.
- Powder:Fine particulate grades enable rapid dissolution kinetics critical to carbon-in-pulp circuit efficiency. Procurement concentrates among South African gold majors operating centralized reagent mixing facilities with advanced dust suppression infrastructure.
- Solution:Ready-to-use liquid formulations eliminate on-site dissolution steps and reduce handling risk exposure. Demand is climbing fastest in Tanzania as Mining Commission regulations tighten occupational safety requirements for cyanide transport and storage.
- Blocks:Compressed solid units for controlled-release applications in specialized extraction scenarios.
- Tablets:Metered-dose solid forms for precision application in agricultural and research settings.
Powder retains volume leadership; Solution is gaining share fastest among safety-conscious operators.
End User:
Customer scale and technical capability determine specification requirements and service attachment opportunities.
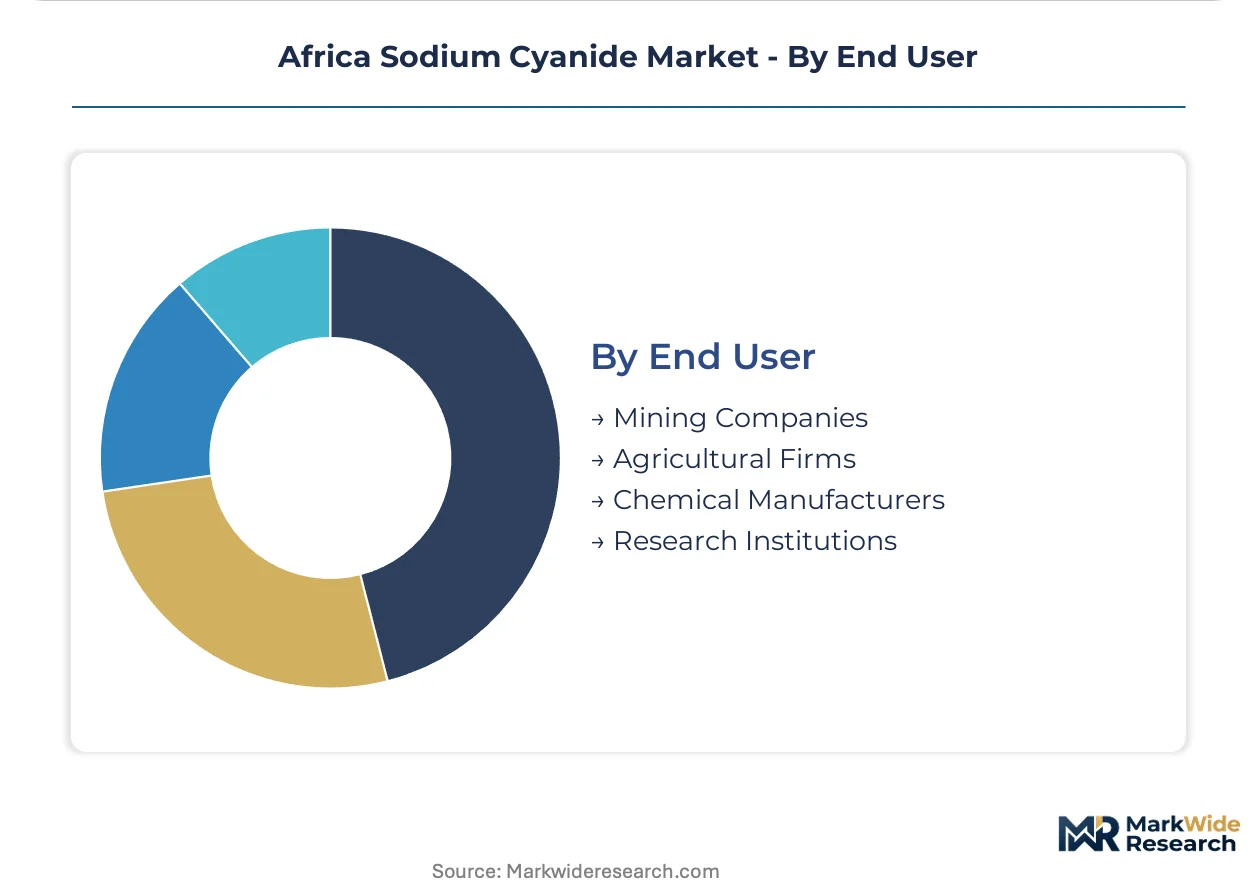
- Mining Companies:Large-scale gold extraction operators across West and East African belts drive specification-setting for purity grades and certification standards. AngloGold Ashanti and Newmont operations in Ghana have consolidated procurement through integrated reagent and logistics contracts that bundle cyanide supply with technical support services.
- Agricultural Firms:Fumigation service providers and large-scale farming operations in Kenya and Tanzania are expanding offtake as national environment management authorities align with International Cyanide Management Institute protocols. These buyers prioritize compliant packaging and documented chain-of-custody over commodity pricing.
- Chemical Manufacturers:Specialty chemical producers requiring sodium cyanide as synthesis intermediate.
- Research Institutions:Analytical laboratories and metallurgical research facilities with precision-grade requirements.
Mining Companies anchor absolute volume; Agricultural Firms are expanding most quickly as regulatory compliance spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in South Africa while consumption spreads across West and East African mining belts. Sasol's integrated chemical complex near Johannesburg supplies reagent to regional distributors. Ghana, Mali, and Burkina Faso anchor the fastest-growing demand nodes.
South Africa
The Department of Mineral Resources and Energy enforces tailings facility compliance under the National Environmental Management Act. Mining license renewals now require demonstrated cyanide destruction circuit verification. Johannesburg anchors regional manufacturing while the Witwatersrand basin drives domestic offtake for gold processing.
Ghana
The Ashanti gold belt hosts AngloGold Ashanti and Newmont operations scaling heap-leach capacity. Ghana's Environmental Protection Agency mandates International Cyanide Management Institute-aligned management codes. Tarkwa and Obuasi mining districts concentrate procurement decisions through centralized chemical management contracts.
Mali
Brownfield expansions in the Yanfolila district are scaling sodium cyanide offtake for low-grade ore processing. The national mining code requires environmental impact assessments for cyanide storage facilities. Kayes and Sikasso regions host emerging heap-leach operations retrofitting processing infrastructure.
Burkina Faso
Greenstone belt developments are intensifying procurement volumes for carbon-in-pulp circuits. The Ministry of Mines and Quarries aligns permitting with regional environmental standards. The Houndé and Mana mining corridors anchor reagent demand from remote-site operations.
Tanzania
The Mining Commission is adopting cyanide management protocols harmonized with International Cyanide Management Institute standards. Lake Victoria gold fields drive demand for liquid formulation dilution systems. Mwanza and Geita districts concentrate mining activity requiring compliant reagent supply chains.
Africa Sodium Cyanide Market Competitive Environment
Top-tier vendors anchor regional supply chains, while mid-tier distributors compete on logistics coverage and certification maintenance. South African manufacturing concentration creates single-source vulnerability for East and West African buyers. Two strategic archetypes dominate: integrated chemical producers with captive feedstock and specialized distributors with multi-site service networks. Competitive moves center on certification pre-emption and on-site dilution infrastructure deployment.
Among integrated chemical manufacturers, Sasol and Evonik Industries exemplify the feedstock-integrated archetype with regional manufacturing footprints. Orica Limited occupies a position within the explosives and reagent distribution tier, leveraging multi-jurisdiction logistics networks. The Chemours Company represents the specialized packaging segment, optimizing solid-form cyanide for remote-site transport economics. Australian Gold Reagents and TAEKWANG INDUSTRIAL anchor Asia-Pacific supply positions serving African import demand.
| Leading Market Players |
|---|
| TSPC |
| The Chemours Company |
| Sasol |
| HeBei ChengXin |
| Evonik Industries |
| Orica Limited |
| Australian Gold Reagents Pty Ltd |
| Honeywell International |
| TAEKWANG INDUSTRIAL CO., LTD |
| Others |
Value Chain & Pricing Dynamics
Caustic soda futures volatility cascades through sodium cyanide manufacturing costs, compressing margins for distributors serving Ghana's Ashanti belt while amplifying price differentiation between ICMI-certified and uncertified supply tiers across West African mining corridors.
Pricing Analysis
Margin tightening in standard-grade supply traces to ammonia feedstock cost spikes and Sasol's regional pricing power. Three-tier pricing structure across premium ICMI-certified, standard industrial-grade, and economy non-certified levels separates procurement pools. Cost-down pressure on economy tiers accelerates because Tanzania's Mining Commission and Kenya's NEMA are tightening certification windows. Large-scale heap-leach operators in Mali and Burkina Faso show lowest price sensitivity due to metallurgical recovery rate premiums, while small-scale carbon-in-pulp facilities in Ghana's peripheral districts face acute procurement budget constraints.
Supply Chain Analysis
Direct-to-mine channels handle AngloGold Ashanti and Newmont's centralized chemical management contracts, while distributor networks serve fragmented mid-tier operators. Manufacturing concentrates in South Africa's Sasol complex, with secondary sourcing from Australian Gold Reagents and TAEKWANG INDUSTRIAL's Asia-Pacific plants. Hydrogen cyanide intermediate management, caustic soda, and ammonia feedstocks anchor raw material dependencies. Single-source vulnerability from Johannesburg-centered production creates structural risk for East and West African buyers during South African port congestion or energy rationing events. Distribution runs through Orica Limited's multi-site logistics networks and specialized chemical distributors with ICMI certification maintenance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Ghana's Environmental Protection Agency ICMI-aligned mandates erect barrier-to-entry moats favoring certified incumbents with pre-positioned audit infrastructure.
For Market Incumbents: Hedge certification concentration risk by diversifying liquid formulation dilution system deployments across Tanzania's Lake Victoria gold fields and Kenya's emerging agricultural fumigation corridors. Sasol's integrated feedstock position faces displacement threat from Australian Gold Reagents' Asia-Pacific supply expansion; priority lever rests on backward integration into caustic soda sourcing and pre-emptive ICMI-NEMA dual certification investments before Kenyan specifications tighten. For New Entrants and Emerging Players: Digital-channel route through agricultural fumigation distributors in Kenya and Tanzania offers lowest certification friction entry point, as NEMA protocols remain less stringent than Ghana's EPA enforcement. White-space targets concentrate in liquid formulation on-site mixing infrastructure for mid-scale heap-leach operators in Burkina Faso's Houndé corridor and Mali's Sikasso region. Go-to-market angle emphasizes documented chain-of-custody compliance over commodity pricing to displace informal supply channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distributors with existing ICMI certification and established relationships with Tanzania's Mining Commission in Dar es Salaam and Mwanza logistics hubs. Long-term viability frames around regulatory harmonization completion across East African Community member states, with certification maintenance infrastructure as durable competitive moat. Signal to watch: Kenya's NEMA publication of mandatory ICMI-equivalent implementation timelines triggering consolidation pressure on uncertified regional distributors.| Strategic Initiative | Industry Significance |
|---|---|
| ICMI Certification Pre-emption | Early compliance with Ghana's EPA and Tanzania's Mining Commission protocols secures procurement preference from AngloGold Ashanti and Newmont operations. |
| Liquid Formulation Infrastructure | On-site dilution systems reduce transport tonnage and align with South Africa's National Environmental Management Act safety mandates. |
| Backward Integration into Feedstock | Captive caustic soda supply from chlor-alkali operations insulates margin compression from energy market volatility. |
| East African Distribution Expansion | Kenya's NEMA adoption of ICMI-aligned standards opens compliant supplier addressable market for previously excluded distributors. |
| Specialized Solid-Form Packaging | Optimized briquette dissolution kinetics reduce tank residence times for low-grade heap-leach operators in Mali's Yanfolila district. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving metallurgical plant managers at Ghanaian gold operations, procurement leads at West African mining houses, chemical distribution channel partners, and technical R&D directors at sodium cyanide manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators from mining sector investment databases and national minerals commission production statistics.
Granularity-level framing applied country-specific modeling for South Africa, Ghana, Mali, Burkina Faso, Tanzania, and Kenya, with grade tier segmentation across solid briquette, liquid, and granular formulations, end-use industry splits between mining extraction and agricultural fumigation, and packaging format differentiation. CAGRs derived from regression analysis of historical offtake patterns against mine development pipeline data and regulatory implementation schedules, with heap-leach circuit expansion rates and carbon-in-pulp retrofit adoption as industry-specific forecast inputs across the projection horizon.
The model holds under stable regulatory implementation timelines and continued gold price support for low-grade ore processing; deviation in ICMI certification enforcement intensity or South African energy supply disruptions would shift volume and value trajectories. Periodic stress-testing of base assumptions against mining license renewal schedules and national environment authority protocol publications is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrogen Chloride Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Aluminum Phosphide Market
Chemicals
Mercuric Chloride Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Scouring Agents Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
1, 4 Butanediol Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Peroxyacetic Acid Market
Chemicals
North America Methanol Market
Chemicals
Bronopol Market
Chemicals
Myclobutanil Market