
 North America Potassium Permanganate Market | 2026-2036
North America Potassium Permanganate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potassium Permanganate Market Intelligence
Municipal water utilities is rotating toward potassium permanganate for pre-oxidation ahead of coagulation and filtration upgrades. Carus Group Inc leverages its captive manganese dioxide mining and electrochemical production footprint to anchor supply security across the Midwest. GFS Chemicals, Inc. competes through reagent-grade specialization for pharmaceutical and laboratory channels. Hawkins controls regional distribution density, operating a network of blending and storage facilities that reduce lead times for environmental agency buyers.
Potassium permanganate is a dark purple crystalline salt with the chemical formula KMnO₄, manufactured through the electrolytic oxidation of potassium manganate in alkaline solution; it functions as a powerful oxidizing agent with a standard reduction potential of +1.51 volts, making it effective for removing dissolved iron, manganese, and hydrogen sulfide from water streams. Industrial grade material dominates volume throughput due to bulk procurement by municipal treatment plants, while reagent grade commands premium pricing from research institutions requiring ACS-certified purity specifications. Water treatment application leads absolute consumption, though pharmaceutical synthesis represents a concentrated margin pool where batch consistency and documentation standards elevate supplier switching costs.
The EPA enforces Maximum Contaminant Level Goals for manganese under the Safe Drinking Water Act, compelling utilities to adopt pre-oxidation protocols that favor permanganate over chlorine for targeted metal precipitation. Health Canada and PMRA coordinate cross-border standards for drinking water additives, creating alignment pressure on suppliers serving the Ontario-Quebec corridor. State-level environmental agencies in California and Texas impose additional discharge monitoring requirements that shape product formulation and logistics investments. Stakeholders must track emerging per- and polyfluoroalkyl substance remediation protocols, as permanganate oxidation is under evaluation for destroying PFAS precursors in groundwater plumes.
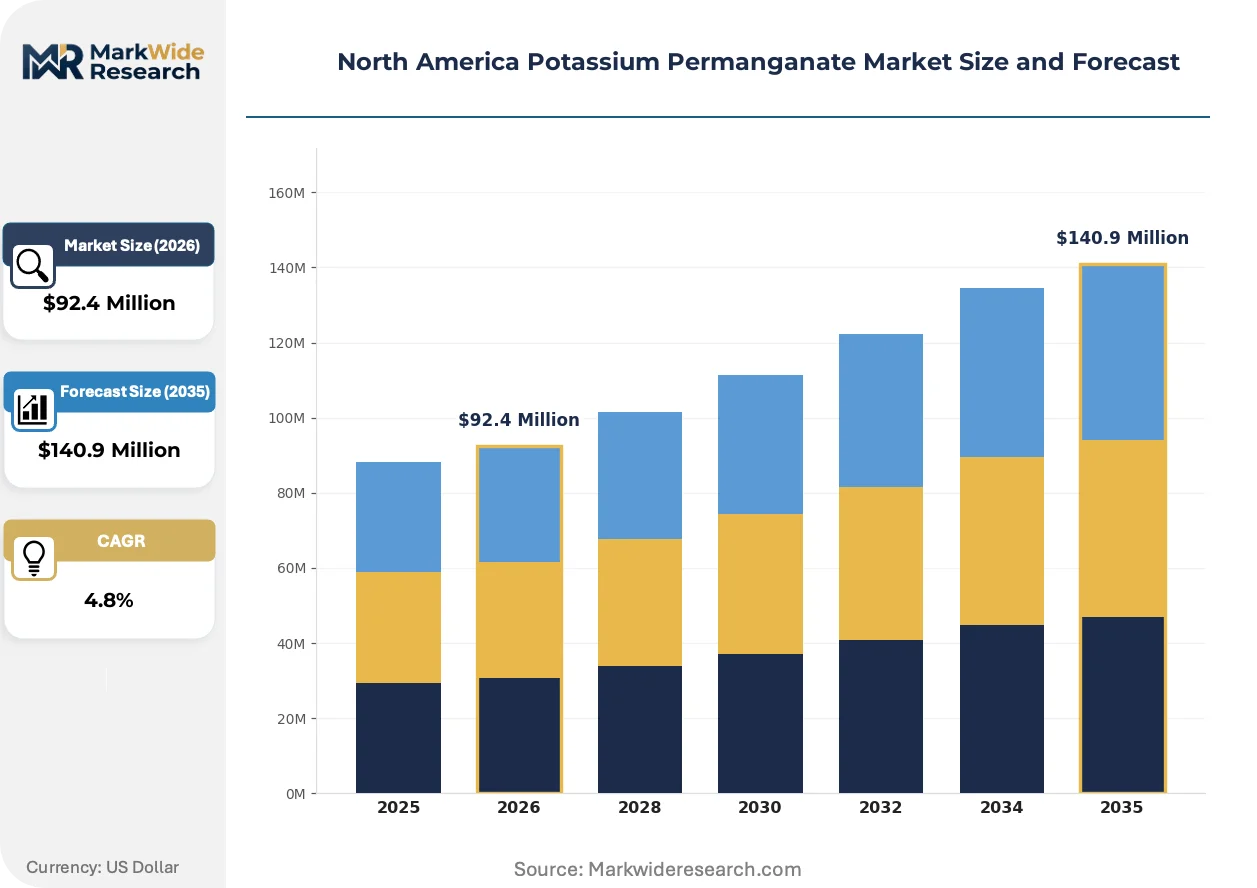
Market Dynamics
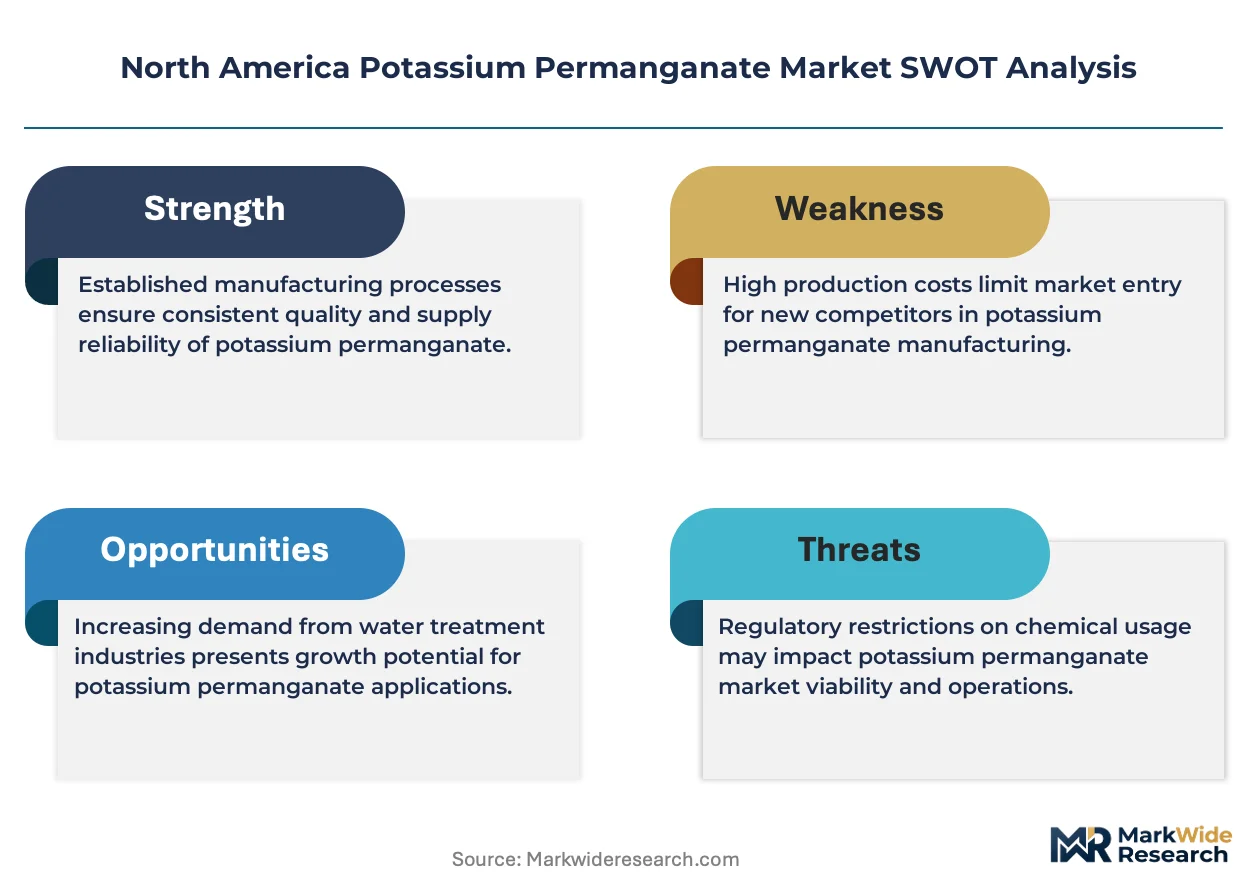
EPA manganese limits under the Safe Drinking Water Act are forcing municipal utilities toward pre-oxidation infrastructure, concentrating demand in the Great Lakes corridor where aging water systems require intensive chemical remediation.
Growth Catalysts
- Safe Drinking Water Act enforcement:EPA Maximum Contaminant Level Goals for manganese compel utilities to adopt permanganate pre-treatment over chlorine alternatives.
- Great Lakes infrastructure decay:Aging iron and manganese-laden distribution systems in Michigan, Ohio, and Wisconsin drive chemical-intensive remediation cycles.
- PFAS precursor oxidation trials:State environmental agencies are evaluating permanganate for destroying per- and polyfluoroalkyl substance precursors in contaminated groundwater.
Market Restraints
- Manganese dioxide supply concentration:Domestic electrochemical production depends on captive mining operations concentrated in the upper Midwest, creating single-source vulnerability.
- Chlorine cost advantage:Bulk sodium hypochlorite systems maintain lower per-unit oxidation costs for utilities with less stringent metal removal requirements.
- Transportation hazard classification:DOT oxidizer shipping restrictions elevate logistics costs and limit storage density at remote treatment facilities.
Strategic Opportunities
- Quebec-Ontario corridor expansion:Health Canada and PMRA alignment on drinking water additives creates cross-border standardization for suppliers with Canadian distribution.
- Pharmaceutical synthesis grade:Reagent-grade material for active pharmaceutical ingredient oxidation commands premium pricing through ACS-certified batch documentation.
- On-site generation systems:Electrolytic permanganate production units at large municipal plants reduce transportation liability and enable just-in-time inventory.
Industry Challenges
- Electrochemical technician scarcity:Specialized alkaline electrolysis operation and maintenance skills concentrate among legacy chemical manufacturing workforces nearing retirement.
- California discharge compliance:State Water Resources Control Board monitoring requirements for oxidation byproducts extend commissioning timelines for new treatment installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potassium Permanganate Market |
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $140.9 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Medical Grade, Laboratory Grade, Reagent Grade Application: Water Treatment, Chemical Synthesis, Pharmaceutical, Agriculture End User: Manufacturing Sector, Healthcare Facilities, Environmental Agencies, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale |
| Companies Covered | Carus Group Inc, GFS Chemicals, Inc., CORECHEM Inc, Hawkins, Brenntag North America, Inc., Spectrum Chemical Mfg. Corp., Parchem, Univar Solutions, Wintersun Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potassium Permanganate Market Strategic Shifts & Innovations
Electrochemical manufacturing advances and regulatory tightening on metal residuals are reshaping how oxidants are specified, delivered, and consumed across municipal and industrial water systems.
Membrane electrolysis cell designs with titanium anode coatings are supplanting traditional carbon-based electrode systems in permanganate production. Midwestern chemical manufacturers are retrofitting generation facilities to capture efficiency gains from improved current density management. This technology compression is reducing unit capital costs for on-site oxidation systems while tightening purity specifications for delivered product.
EPA's pending revisions to Secondary Maximum Contaminant Levels for iron and manganese are accelerating pre-oxidation mandate adoption. State primacy agencies in Texas and California are incorporating these federal guidelines into operator certification requirements. Municipal procurement departments are responding with multi-year chemical supply contracts that lock in volume commitments ahead of anticipated price adjustments.
Specification-driven purchasing is consolidating vendor relationships around suppliers with integrated mining-to-delivery capabilities. Environmental agency buyers are unbundling technical service contracts from chemical supply agreements, forcing distributors to compete on logistics performance rather than bundled consulting. This pattern is most pronounced in the Ohio River Valley, where regional water authorities centralize procurement across multiple treatment plants.
North America Potassium Permanganate Market Segmentation
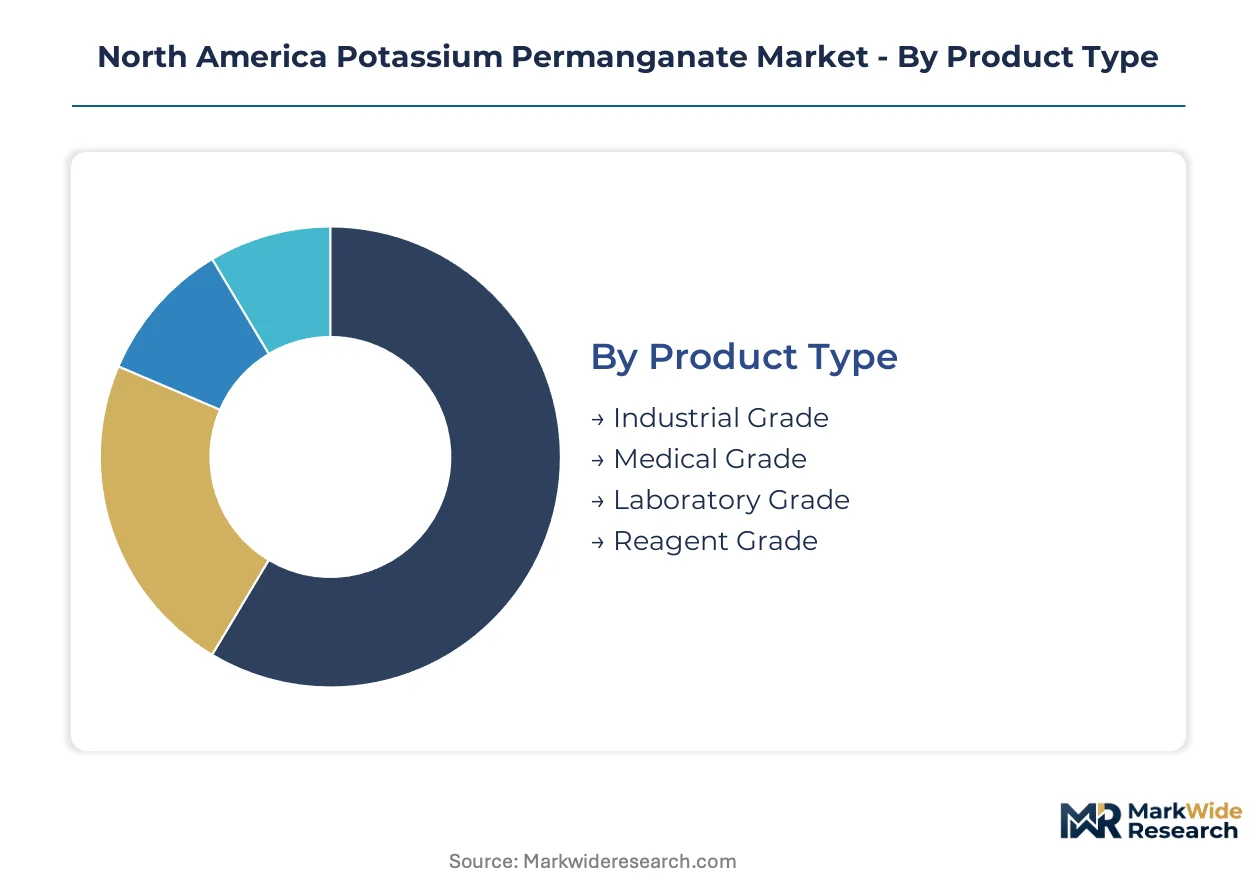
Potassium permanganate demand fragments sharply across purity grades and end-use specifications. Each segment carries distinct regulatory burdens, pricing tiers, and supply chain configurations that reshape competitive positioning.
Product Type:
Industrial grade dominates domestic volume through municipal water treatment contracts across the Great Lakes states. Reagent and laboratory grades serve export-oriented pharmaceutical channels with premium documentation requirements.
- Industrial Grade:Technical specifications center on 99% minimum KMnO₄ purity with controlled moisture content below 0.5%. Demand concentrates in Michigan, Ohio, and Wisconsin municipal utilities where EPA manganese limits force pre-oxidation infrastructure investment. Bulk procurement contracts lock in multi-year supply security.
- Reagent Grade:ACS-certified material meets American Chemical Society purity standards with full batch traceability. Pharmaceutical synthesis in New Jersey and Massachusetts drives specification-heavy procurement where supplier switching costs escalate through validation documentation.
- Medical Grade:USP-compliant material for topical antiseptic and dermatological applications carries FDA drug establishment registration requirements.
- Laboratory Grade:Educational and analytical research consumption across university systems prioritizes cost efficiency over certification depth.
Industrial grade commands the established base. The steepest expansion runs through reagent grade.
Application:
Water treatment absorbs the majority of volume throughput while pharmaceutical oxidation protocols deliver margin concentration. Agricultural and chemical synthesis applications split between commodity pricing and specialty formulation requirements.
- Water Treatment:Pre-oxidation of iron, manganese, and hydrogen sulfide in municipal systems demands rapid dissolution rates and consistent purple color intensity as visual dosage indicators. Texas and California utilities lead adoption of automated feed systems that reduce operator exposure.
- Pharmaceutical:Active pharmaceutical ingredient oxidation requires nitrogen-purged packaging and COA documentation for each production lot. FDA inspection readiness elevates supplier qualification timelines.
- Chemical Synthesis:Organic oxidation reactions and fine chemical production consume standardized industrial grades with volume-based pricing.
- Agriculture:Soil remediation and aquaculture disinfection applications in Florida and California face state-level discharge monitoring that shapes formulation choices.
Water treatment anchors volume throughput. Pharmaceutical applications are climbing the fastest.
End User:
Environmental agencies and healthcare facilities operate under divergent procurement frameworks. Manufacturing sector buyers prioritize logistics reliability while research institutions emphasize specification flexibility.
- Environmental Agencies:State and municipal water authorities across the US Great Lakes corridor execute centralized procurement with technical service unbundling. EPA compliance documentation requirements extend vendor qualification periods.
- Healthcare Facilities:Hospital pharmacies and wound care centers in urban corridors maintain just-in-time inventory for topical antiseptic applications.
- Manufacturing Sector:Chemical processors and electronics manufacturers in the Ohio River Valley require bulk delivery with dedicated storage tank installation.
- Research Institutions:University laboratories and government research centers prioritize small-package availability with rapid fulfillment.
Environmental agencies command the established base. Healthcare facilities are gaining share fastest.
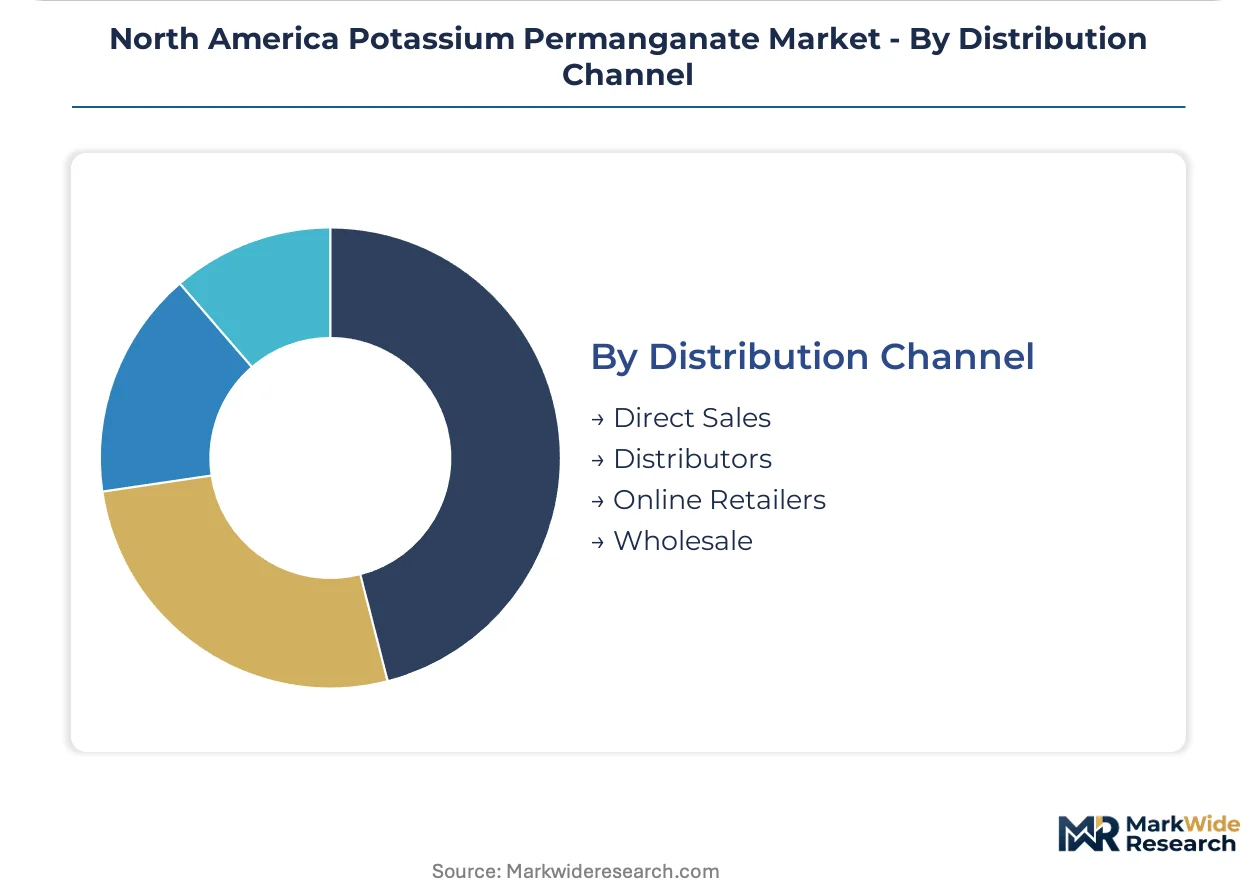
Distribution Channel:
Channel selection reflects customer scale and hazard classification constraints. DOT oxidizer shipping restrictions fragment last-mile delivery economics across remote and urban destinations.
- Distributors:Regional chemical distributors like Hawkins operate blending and storage facilities that reduce lead times for municipal buyers. Network density in the Midwest anchors competitive positioning through inventory proximity.
- Direct Sales:Large municipal utilities and pharmaceutical manufacturers negotiate manufacturer-direct contracts with dedicated logistics arrangements.
- Wholesale:Industrial supply houses aggregate demand from smaller manufacturing and agricultural accounts.
- Online Retailers:Laboratory and small-scale users access packaged material through specialized chemical e-commerce platforms with hazardous materials shipping compliance.
Distributors command the established base. Direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes-St. Lawrence Seaway System anchors North American potassium permanganate distribution, connecting Midwestern electrochemical production to Atlantic and Gulf Coast markets. Rail corridors and barge networks concentrate chemical logistics around Chicago, Detroit, and Montreal transshipment points.
United States
EPA manganese limits under the Safe Drinking Water Act compel municipal utilities across Michigan, Ohio, and Wisconsin to install permanganate pre-oxidation systems. The Great Lakes corridor hosts aging iron-laden distribution infrastructure requiring intensive chemical remediation. Detroit and Cleveland water authorities execute centralized procurement contracts that lock in multi-year supply security.
Canada
Health Canada and PMRA coordinate cross-border standards for drinking water additives, aligning Ontario and Quebec regulations with US EPA protocols. The St. Lawrence River industrial corridor concentrates demand from municipal treatment plants serving Toronto and Montreal metro areas. Provincial environmental agencies mandate pre-oxidation for manganese removal in older distribution systems.
Mexico
CONAGUA water quality standards are tightening metal discharge limits for municipal systems in Mexico City and Monterrey. Northern border states import US-manufactured permanganate through Laredo and Nogales rail gateways. Industrial water treatment in Baja California and Chihuahua drives specification-grade demand from maquiladora chemical processors.
North America Potassium Permanganate Market Key Industry Players
Concentration sits with electrochemical manufacturers possessing captive manganese dioxide mining and integrated production footprints. The supplier base tiers between integrated producers controlling raw material supply and regional distributors competing on logistics density. Two strategic archetypes dominate: vertically integrated chemical manufacturers and network-dense regional distributors. Competitive moves center on backward integration into manganese ore sourcing and expansion of blending facility networks to reduce last-mile delivery times.
Among integrated producers, Carus Group Inc exemplifies the mining-to-delivery archetype through its captive electrochemical production footprint. GFS Chemicals, Inc. occupies a specialization position serving reagent-grade pharmaceutical and laboratory channels. Hawkins anchors regional distribution density through its network of Midwestern blending and storage facilities.
| Leading Market Players |
|---|
| Carus Group Inc |
| GFS Chemicals, Inc. |
| CORECHEM Inc |
| Hawkins |
| Brenntag North America, Inc. |
| Spectrum Chemical Mfg. Corp. |
| Parchem |
| Univar Solutions |
| Wintersun Chemical |
| Others |
Cost & Logistics Intelligence
Multi-year offtake contracts between Great Lakes municipal utilities and electrochemical producers lock in both manganese dioxide supply access and price visibility across volatile raw material cycles. These arrangements insulate buyers from spot market swings while securing producer utilization rates.
Pricing Analysis
Volume-discount tiering structures separate industrial-grade municipal contracts from reagent-grade pharmaceutical procurement. Price differentiation rests on ACS certification requirements and nitrogen-purged packaging standards that elevate documentation costs. Pricing pressure intensifies in industrial grades as chlorine alternatives compete on per-unit oxidation economics. Municipal buyers exhibit highest price sensitivity due to fixed-rate water tariffs, while pharmaceutical manufacturers absorb premium tiers for FDA inspection readiness.
Supply Chain Analysis
Inbound logistics costs from DOT oxidizer shipping restrictions elevate last-mile delivery expenses for remote treatment facilities. Geographic supply concentration centers on upper Midwest captive mining operations, with secondary electrochemical capacity in Ontario. Raw material dependencies include manganese dioxide ore, potassium hydroxide, and titanium anode coatings. Single-source vulnerability from concentrated Midwest mining creates structural risk. Distribution runs through regional blending facilities that reduce lead times for environmental agency buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery driven by EPA enforcement waves that trigger replacement demand for pre-oxidation infrastructure every seven to ten years.
For Market Incumbents: Fortify captive manganese dioxide mining positions through lease extensions and electrochemical capacity maintenance. Chlorine cost competition threatens industrial-grade margins, making backward integration into ore sourcing the critical defensive lever. Expand blending facility networks in the Ohio River Valley to tighten logistics control against regional distributors. For New Entrants and Emerging Players: Anchor in Quebec-Ontario corridor expansion where Health Canada-PMRA alignment reduces regulatory qualification barriers. The most penetrable white-space sits in on-site electrolytic generation systems for large municipal plants lacking DOT shipping expertise. Pursue equipment-leasing models that bundle technical service with chemical supply. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with captive mining and established EPA compliance documentation. Long-term viability hinges on exposure to municipal water infrastructure replacement cycles rather than commodity chemical exposure. Watch PFAS remediation protocol approvals as the inflection signal for demand acceleration in groundwater treatment applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive manganese dioxide mining secures supply continuity against Midwest concentration risk. |
| On-Site Generation Deployment | Electrolytic permanganate units at municipal plants eliminate DOT shipping liability exposure. |
| Reagent Grade Certification | ACS batch documentation elevates switching costs in pharmaceutical oxidation channels. |
| Cross-Border Distribution Expansion | Health Canada-PMRA alignment enables Ontario-Quebec corridor standardization. |
| PFAS Remediation Trials | State agency evaluation of permanganate for precursor oxidation opens groundwater treatment demand. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, municipal procurement records, and electrochemical industry trade data. Primary interviews engaged plant managers at integrated producers, procurement leads at Great Lakes water authorities, and distribution channel partners serving the Ohio River Valley. Secondary validation drew from Safe Drinking Water Act compliance filings, DOT hazardous materials shipping statistics, and Health Canada drinking water additive registrations. Bottom-up demand modeling triangulated against top-down chemical production capacity assessments.
Segmentation dimensions modeled include purity grade tier, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from volume trajectory analysis incorporating municipal infrastructure replacement cycles and pharmaceutical batch consistency requirements. Industry-specific forecast inputs encompass EPA Secondary Maximum Contaminant Level revision timelines and state-level PFAS remediation protocol adoption rates.
Material uncertainties — manganese ore price volatility, electrochemical technician retirement waves, and chlorine substitution economics — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and municipal capital budget stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market