
 Photographic Film Processing Chemicals Market | 2026-2036
Photographic Film Processing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Photographic Film Processing Chemicals Market Analytics
Fine art photography is realigning demand within the Photographic Film Processing Chemicals Market as museums, galleries, and archival institutions sustain analog workflows for permanence and aesthetic authenticity. Eastman Kodak Company leverages its century-old formulation expertise to dominate professional-grade developer chemistry. Fujifilm Corporation anchors supply chains across Asia-Pacific with integrated film and chemical manufacturing. Harman Technology specializes in Ilford-branded black-and-white processing chemistry, occupying a defensible niche among monochrome enthusiasts.
Photographic film processing chemicals comprise developer, fixer, stop bath, and wash aid formulations engineered to reduce silver halide crystals into metallic silver and stabilize latent images against light degradation. These chemicals typically operate within precise pH ranges and temperature tolerances to control grain structure and tonal gradation in analog output. Developer formulations lead product type demand as the most frequently replenished and technically sensitive processing stage. Fine art applications represent the fastest-growing application segment as institutional buyers prioritize archival permanence over speed. Liquid concentrates capture growing preference among small-scale labs and home darkrooms for shelf stability and shipping efficiency.
EPA standards under the US Clean Water Act constrain phenidone and hydroquinone discharge from commercial processing facilities, while REACH registration requirements in Europe mandate toxicological documentation for boric acid and formaldehyde-releasing fixer components. Japan's Ministry of Economy, Trade and Industry (METI) oversees chemical substance classification under CSCL, affecting import and domestic manufacture of proprietary developer accelerators. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and regional supply reconfigurations.
Market Dynamics
REACH registration requirements and evolving EPA discharge standards under the US Clean Water Act are forcing reformulation of developer and fixer chemistries, compressing margins for legacy phenidone and hydroquinone-based products while opening pathways for lower-toxicity alternatives.
Growth Catalysts
- Institutional analog workflows:Museums and fine art galleries in Japan and the United States sustain demand for archival-grade processing chemistry to preserve permanence standards. These buyers prioritize tonal authenticity over digital convenience.
- REACH compliance incentives:European formulators accelerating boric acid substitution in fixer solutions gain preferential market access. Registration documentation creates competitive moats against non-compliant imports.
- Home darkroom revival:Liquid concentrate formats reduce shipping weight and extend shelf stability. Enthusiast photographers in Germany and the United Kingdom drive replenishment cycles for developer chemistry.
Market Restraints
- Silver price volatility:Fluctuations in silver halide input costs destabilize fixer pricing. Suppliers cannot pass through full cost swings to institutional buyers locked into annual contracts.
- Single-source precursor dependence:Japan's METI-controlled chemical substance classification limits domestic manufacture of proprietary developer accelerators. Regional supply chains concentrate around Fujifilm and Harman Technology facilities.
- Digital capture substitution:Commercial portrait and event photography segments have migrated to digital workflows. Remaining analog demand concentrates in niches with low volume elasticity.
Strategic Opportunities
- Educational institution partnerships:University photography programs in the United States and United Kingdom require hands-on darkroom training. Curriculum mandates create captive demand for black-and-white processing kits.
- Modular chemistry systems:Pre-measured single-use developer sachets reduce mixing errors for novice users. This format expands addressable market into hobbyist segments with limited technical confidence.
- EU Green Deal alignment:Biodegradable wash aid formulations qualify for preferential public procurement scoring. Municipal darkroom facilities in France and Italy face sustainability reporting requirements.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in silver halide reduction kinetics limits R&D throughput. Academic programs have phased out analog photochemistry specializations.
- Legacy equipment compatibility:Lower-toxicity developer substitutes must match grain structure and tonal gradation of phenidone-based predecessors. Reformulation validation extends product launch timelines.
- Cross-border substance documentation:Divergent classification between Japan's CSCL and REACH creates dual registration burdens. Harmonization remains stalled in OECD technical working groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photographic Film Processing Chemicals Market |
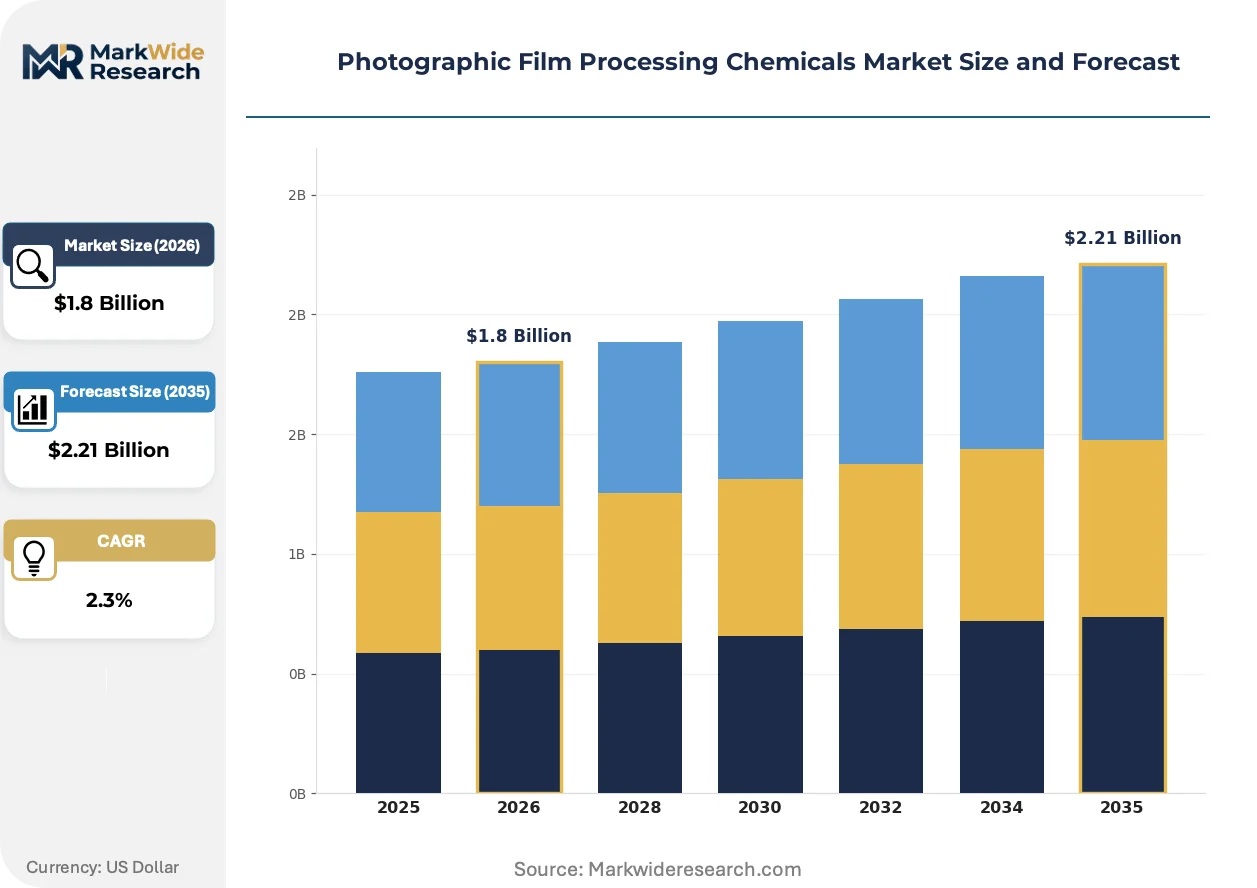
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Developer, Fixer, Stop Bath, Wash Aid Application: Professional Photography, Consumer Photography, Commercial Printing, Fine Art Form: Liquid, Powder, Concentrate, Ready-to-Use Packaging Type: Bottles, Jugs, Cartridges, Sachets |
| Companies Covered | BASF, FOMA BOHEMIA spol. s r.o., Fujifilm Corporation, Hydrite Chemical Co, Bostick & Sullivan Inc, Eastman Kodak Company, Huntsman Corporation, Harman Technology, Agfa-Gevaert N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photographic Film Processing Chemicals Market Evolving Landscape
Formulation chemistry is pivoting toward lower-toxicity architectures as regulatory pressure intensifies across major manufacturing jurisdictions. Three interconnected developments are reshaping competitive positioning in developer, fixer, and auxiliary chemistry segments.
Phenidone-free developer formulations utilizing ascorbic acid derivatives are absorbing market share in professional-grade chemistry segments. Fine art photographers and archival institutions in Germany and Japan have adopted these alternatives to meet discharge permit requirements. The technology is absorbing demand that previously defaulted to hydroquinone-based legacy products, compressing volume for traditional black-and-white developers.
REACH authorization procedures for boric acid and formaldehyde-releasing compounds are tightening fixer formulation standards across European commercial labs. ECHA's 2023 sunset date extensions provided temporary relief, but downstream users now face substitution deadlines. Small-scale processing facilities in Italy and Spain are consolidating volumes to amortize compliance costs, favoring suppliers with integrated registration dossiers.
Direct-to-enthusiast distribution via specialized retailers and manufacturer webstores is displacing traditional wholesale channels for liquid concentrate chemistry. Home darkroom operators in the United Kingdom and United States prefer subscription replenishment models over bulk institutional purchasing. This behavioral shift concentrates margin capture with formulators possessing captive e-commerce infrastructure and regional fulfillment networks.
Photographic Film Processing Chemicals Market Segmentation
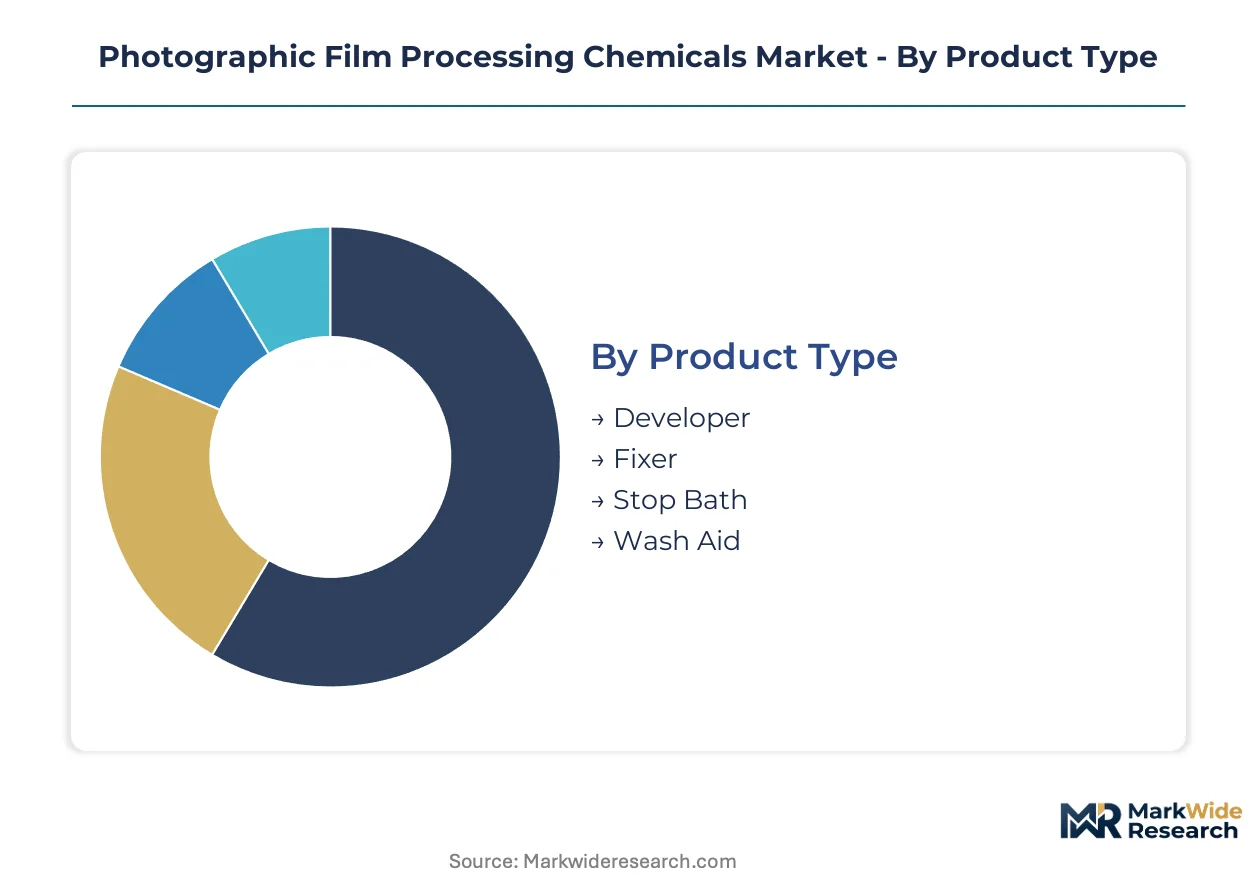
Segmentation in photographic film processing chemicals reveals how formulation chemistry, application intensity, and packaging logistics intersect to shape procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that suppliers must navigate across professional, institutional, and enthusiast buyer bases.
Product Type:
Developer chemistry commands premium pricing due to replenishment frequency and formulation sensitivity, while fixer and auxiliary chemistry compete on volume efficiency and discharge compliance.
- Developer:Reduces exposed silver halide crystals to metallic silver through precise pH-controlled redox reactions. Professional labs in Japan and Germany sustain replenishment cycles that outpace other chemistry types, driven by fine art institutions prioritizing tonal gradation control.
- Fixer:Dissolves unexposed silver halide and stabilizes the latent image against light degradation through ammonium thiosulfate or sodium thiosulfate complexes. Commercial facilities across Italy and Spain face REACH substitution deadlines for boric acid and formaldehyde-releasing components, compressing legacy formulation margins.
- Stop Bath:Acetic acid or citric acid solutions that halt development action instantly to preserve shadow detail.
- Wash Aid:Surfactant-based formulations that accelerate residual fixer removal and reduce water consumption in archival processing.
Mature deployment sits with Developer chemistry in institutional darkrooms. Newer deployment is concentrated in Wash Aid formulations qualifying for EU Green Deal procurement scoring.
Application:
Demand intensity varies sharply between volume-driven commercial segments and premium-priced archival workflows where permanence standards override cost sensitivity.
- Professional Photography:Wedding and portrait studios sustaining hybrid analog-digital workflows require consistent chemistry performance across batch processing. These operators in the United States prioritize liquid concentrate formats for inventory flexibility.
- Fine Art:Museums and galleries commission archival-grade processing for exhibition prints and collection preservation. German institutions have adopted phenidone-free ascorbic acid developers to meet discharge permit requirements without sacrificing tonal authenticity.
- Consumer Photography:Home darkroom enthusiasts and hobbyist photographers drive replenishment demand for black-and-white chemistry kits.
- Commercial Printing:Remaining analog minilabs and specialty printing services process color negative and reversal films.
Established revenue concentration remains with Professional Photography. Fine Art applications are climbing the fastest as institutional buyers expand analog curriculum and exhibition programming.
Form:
Physical state determines shipping economics, shelf stability, and mixing precision—factors that segment buyer preference between high-volume labs and small-scale operators.
- Liquid:Pre-diluted solutions offering immediate use without mixing error. United Kingdom home darkroom operators favor subscription replenishment models for these formats, concentrating margin capture with suppliers possessing regional fulfillment networks.
- Concentrate:Dilution-required formulations that reduce shipping weight and extend shelf stability. Small-scale labs in Germany and the United States prefer these for cost efficiency across intermittent processing schedules.
- Powder:Dry chemical blends requiring dissolution before use, favored for long-term storage.
- Ready-to-Use:Single-step solutions eliminating dilution steps for novice users and educational settings.
Volume leadership belongs to Liquid formulations in commercial labs. Concentrate formats are gaining share fastest among enthusiast segments optimizing shipping costs.
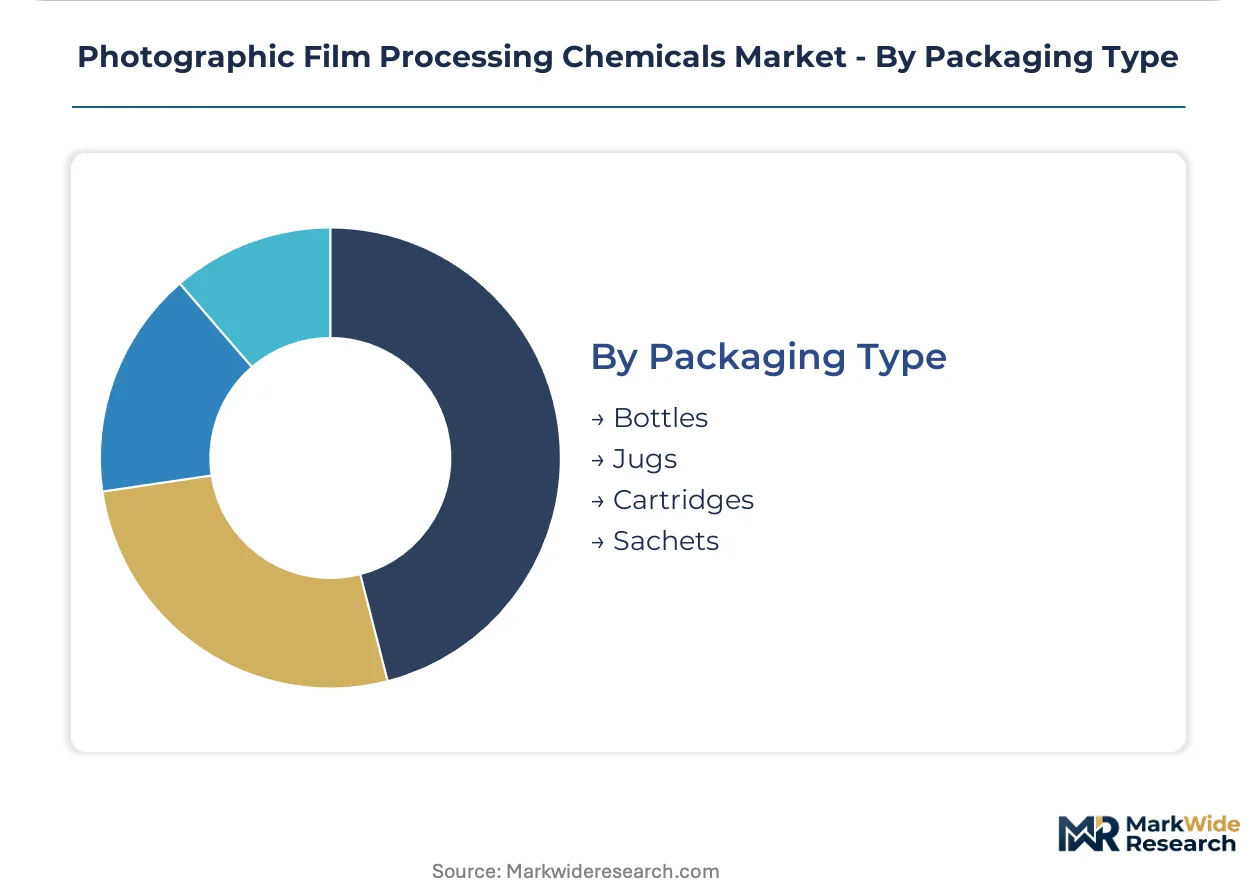
Packaging Type:
Container configuration shapes inventory management, chemical stability, and waste generation profiles across institutional and individual buyer segments.
- Bottles:Standard amber glass or opaque plastic containers protecting photochemistry from oxidation and light degradation. Professional labs in Japan standardize on these for developer storage and controlled dispensing.
- Sachets:Pre-measured single-use packets eliminating mixing errors and reducing chemical waste. University photography programs in the United States and United Kingdom specify these for curriculum-standardized darkroom training.
- Jugs:High-volume polyethylene containers for commercial processing facilities with continuous replenishment systems.
- Cartridges:Sealed dispensing systems for automated processing machines in remaining minilab installations.
Dominant procurement patterns center on Bottles in professional settings. Sachet formats are expanding most quickly through educational institution partnerships and novice-friendly positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Chemical Substances Control Law (CSCL) zones concentrate formulation expertise in Kanto and Kansai industrial corridors, anchoring regional supply chains for analog photochemistry. Fiscal incentives for heritage manufacturing sustain domestic production of developer accelerators and fixer precursors.
United States
EPA discharge standards under the Clean Water Act constrain phenidone and hydroquinone effluent from commercial labs in California and New York. Rochester, New York hosts century-old formulation infrastructure serving institutional darkrooms. University photography programs in Massachusetts and Illinois mandate hands-on analog training, sustaining replenishment demand for educational chemistry kits.
Germany
REACH authorization deadlines for boric acid and formaldehyde-releasing compounds accelerate fixer reformulation across Bavaria and Baden-Württemberg. ECHA registration dossiers create competitive barriers against non-compliant imports. Fine art institutions in Berlin and Cologne have adopted phenidone-free ascorbic acid developers to satisfy municipal discharge permits without tonal compromise.
United Kingdom
Home darkroom enthusiasts in Greater London and Manchester drive liquid concentrate subscription models through specialized retailers. The Environment Agency's evolving effluent guidelines push small-scale labs toward lower-toxicity wash aid formulations. Harman Technology's Ilford-branded chemistry maintains dedicated distribution through regional fulfillment networks serving monochrome hobbyists.
Japan
METI oversees chemical substance classification under CSCL, limiting domestic manufacture of proprietary developer accelerators to Kanto and Chubu industrial zones. Fujifilm Corporation anchors integrated film and chemical supply chains serving professional segments. Archival institutions in Tokyo and Osaka sustain demand for permanence-grade processing chemistry in museum conservation workflows.
Photographic Film Processing Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage formulators commanding premium positioning in institutional channels while toll manufacturers serve volume-driven commercial labs. The vendor base concentrates around three strategic archetypes: integrated film-chemical conglomerates, niche monochrome specialists, and diversified industrial chemical suppliers. Consolidation pressure intensifies as REACH compliance costs favor players with existing registration dossiers. Capacity rationalization and geographic licensing agreements represent the dominant competitive moves as legacy phenidone-based capacity faces substitution deadlines.
Within the heritage-formulator tier, Eastman Kodak Company and Fujifilm Corporation exemplify century-old expertise in professional-grade developer chemistry, while Harman Technology occupies a defensible position among monochrome enthusiasts through its Ilford-branded processing lines. BASF and Huntsman Corporation represent diversified chemical conglomerates with photochemistry divisions embedded within broader specialty materials portfolios. These players anchor competitive dynamics through formulation legacy, integrated manufacturing, and regulatory compliance infrastructure rather than scale-driven cost positioning.
| Leading Market Players |
|---|
| BASF |
| FOMA BOHEMIA spol. s r.o. |
| Fujifilm Corporation |
| Hydrite Chemical Co |
| Bostick & Sullivan Inc |
| Eastman Kodak Company |
| Huntsman Corporation |
| Harman Technology |
| Agfa-Gevaert N.V. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Japan maintain pricing discipline through captive formulation expertise and long-term institutional contracts. Their ownership structure insulates pricing from quarterly earnings pressure while concentrating supply around heritage manufacturing clusters in Rochester, New York and Kanto, Japan.
Pricing Analysis
Short lead-time premiums attach to phenidone-free developer formulations as European labs face REACH substitution deadlines. Three-tier pricing structure across archival-grade, professional-standard, and educational-economy levels segments buyer tolerance. Cost compression in standard-grade fixers intensifies as silver halide input volatility destabilizes ammonium thiosulfate pricing. Educational institutions exhibit highest price sensitivity due to curriculum budget constraints, while museums prioritize tonal authenticity over unit economics.
Supply Chain Analysis
Returns of expired liquid concentrates to regional fulfillment centers in the United Kingdom and Germany enable remanufacturing into educational-grade chemistry. Supply concentrates in Japan, the United States, and the United Kingdom around Fujifilm, Kodak, and Harman Technology facilities. Boric acid and formaldehyde precursor dependencies create single-source vulnerability for European fixer manufacturers. Distribution runs through specialized retailers and manufacturer webstores displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and silver price volatility are forcing consolidation as smaller formulators lack registration dossier resources. Weaker players without ECHA documentation face market exit as substitution deadlines tighten.
For Market Incumbents: Acquire distressed registration dossiers from exiting European competitors to secure REACH-compliant fixer market access. Kodak and Fujifilm should deepen backward integration into proprietary developer accelerator production to offset METI-controlled Japanese supply constraints. Channel control through captive e-commerce infrastructure protects margin capture against toll manufacturer encroachment. For New Entrants and Emerging Players: University photography programs represent an underserved buyer archetype with curriculum-mandated replenishment cycles. Modular single-use sachet formats penetrate novice hobbyist segments with limited technical confidence. Direct-to-educator go-to-market positioning bypasses incumbent wholesale relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor formulators with existing ECHA registration dossiers in Germany and France as substitution deadlines compress legacy capacity values. Long-term viability hinges on archival permanence standards sustaining institutional demand against digital substitution. Monitor ECHA sunset date extensions and METI chemical substance reclassifications as inflection indicators for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Dossier Acquisition | Secures European market access as substitution deadlines eliminate non-compliant competitors. |
| Backward Integration into Developer Accelerators | Reduces dependence on METI-controlled Japanese chemical substance classifications. |
| Educational Institution Partnership Programs | Captures curriculum-mandated demand from university photography departments. |
| Phenidone-Free Formulation Launch | Addresses EPA discharge standards and German municipal permit requirements. |
| Direct-to-Enthusiast E-commerce Buildout | Concentrates margin capture through subscription replenishment models. |
Research Methodology
Independent corroboration across plant managers at commercial processing facilities, procurement leads at museum conservation departments, and distribution channel partners in specialized photography retailers underwrites the qualitative findings. Secondary validation draws from ECHA registration databases, EPA discharge permit filings, and METI chemical substance classification records. Bottom-up volume estimates from institutional replenishment cycles triangulate against top-down market sizing from customs trade data.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. Segmentation modeling incorporates product type, application intensity, physical form, and packaging configuration dimensions. CAGRs derive from historical replenishment patterns projected through institutional budget cycles and regulatory compliance timelines. Silver price volatility and REACH authorization schedules constitute industry-specific forecast inputs.
Revisions become necessary when ECHA extends boric acid sunset dates or METI reclassifies developer accelerator substances under CSCL. Forecasts reflect assumptions about sustained fine art institutional demand and stable educational curriculum mandates. Practitioners should monitor regulatory divergence between REACH and CSCL frameworks for early signals of reformulation cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Diphosphate Market
Chemicals
Global Bleaching Agents Market
Chemicals
CHPTAC Market
Chemicals
Catechol Market
Chemicals
Benzhydrol Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Menadione Market
Chemicals
Maleic Acid Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Hydrazine Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Hexafluorosilicic Acid Market