
 Elemental Fluorine Market | 2026-2036
Elemental Fluorine Market Size, Share, and Industry Trends Forecast 2026-2036
Elemental Fluorine Market Intelligence
The capability gap between large-scale electrochemical generation and smaller, localized production is rotating the competitive landscape. Major industrial gas suppliers like Linde plc leverage extensive distribution networks for a wide range of applications. In contrast, a firm like Kanto Denka Kogyo Co., Ltd. specializes in high-purity fluorine for the electronics sector. Solvay S.A. sustains its position through significant investment in fluorochemical production capacity.
Elemental fluorine is a highly reactive diatomic gas, F2, typically produced through the electrolysis of a molten salt mixture. Its extreme electronegativity makes it one of the most powerful oxidizing agents known, requiring specialized handling and containment materials. Within applications, electronics manufacturing for chamber cleaning is the dominant value driver, outpacing traditional uses in metal treatment. Demand for high-purity fluorine from semiconductor fabricators represents the fastest-growing product and end-user segment combination.
Regulatory frameworks from the US Environmental Protection Agency (EPA), Europe's ECHA under REACH, and China's Ministry of Ecology and Environment (MEE) govern production and transport. These rules impose stringent safety protocols and emissions controls, influencing facility design and operational costs. Future investment decisions will balance the need for supply chain resilience in critical sectors against the capital costs of complying with evolving safety and environmental mandates.
Market Dynamics
The primary force shaping the elemental fluorine market is the relentless demand for higher purity gas from the semiconductor industry. This requirement is a direct consequence of the transition to sub-5nm logic architectures in advanced chip manufacturing.
Growth Catalysts
- Semiconductor Node Advancement:The progression to sub-5nm and smaller chip architectures in fabs necessitates ultra-high purity fluorine for precise chamber cleaning, directly linking market growth to semiconductor technology milestones.
- Geographic Fab Concentration:Demand is heavily concentrated in advanced semiconductor manufacturing clusters located in South Korea, Taiwan, and the United States, creating localized, high-value demand centers.
- Application Value Shift:The economic value derived from fluorine's use in electronics manufacturing now significantly surpasses its application in traditional sectors like metal treatment, focusing investment on this segment.
Market Restraints
- Extreme Reactivity:Fluorine's high reactivity and corrosiveness mandate the use of expensive, specialized handling equipment and materials like Monel alloys, increasing capital and operational costs significantly.
- Energy-Intensive Production:The Moissan process, electrolysis of a molten salt, is extremely energy-intensive, making fluorine production costs highly sensitive to regional electricity price volatility.
- Stringent Transport Regulations:Global and national regulations, including those from the US EPA and ECHA, impose severe restrictions on the transport of elemental fluorine, complicating logistics and limiting supply chain flexibility.
Strategic Opportunities
- On-Site Generation Systems:Developing smaller, modular on-site fluorine generators for semiconductor fabs presents an opportunity to bypass hazardous transport logistics and capture long-term service contracts.
- Next-Generation Batteries:Research into advanced battery chemistries, including fluorinated electrolytes for high-energy-density lithium-ion cells, opens a potential new high-value application beyond electronics.
- Supply Chain Resilience Mandates:Government initiatives like the US CHIPS Act, aimed at securing domestic semiconductor supply chains, create opportunities for investment in local fluorine production capacity.
Industry Challenges
- Specialized Talent Scarcity:A shortage of chemical engineers and technicians with expertise in fluorochemical handling and electrolysis plant operation poses a significant operational challenge for producers.
- High Capital Expenditure:Constructing new fluorine production facilities that comply with modern environmental and safety standards set by bodies like the MEE in China requires substantial upfront capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elemental Fluorine Market |
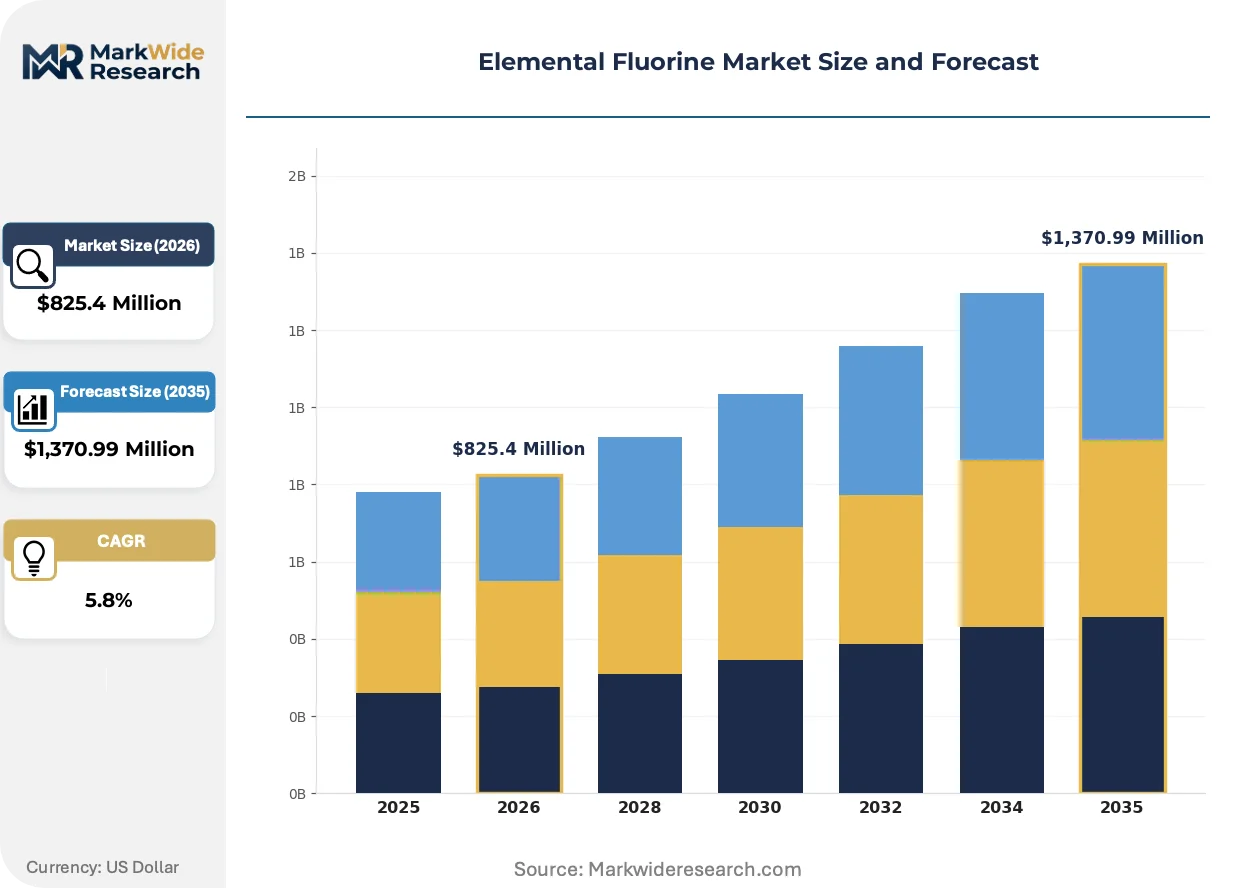
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,370.99 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Refrigerants, Pharmaceuticals, Electronics, Agrochemicals, Specialty Chemicals, Metal Treatment Product Type: Gaseous Fluorine, Liquid Fluorine, Fluorine Mixtures, High-Purity Fluorine, Stabilized Fluorine End User: Chemical Manufacturing, Semiconductor Fabricators, Crop Protection Firms, Pharmaceutical Companies, Metal Processing Plants, Industrial Gas Suppliers Technology: Electrochemical Generation, Gas Phase Fluorination, Liquid Phase Fluorination, Anhydrous Fluorination, Plasma Fluorination |
| Companies Covered | Solvay S.A., Navin Fluorine International Ltd., Air Products and Chemicals, Inc., Linde plc, Kanto Denka Kogyo Co., Ltd., Pelchem SOC Ltd., Advance Research Chemicals, Inc., Air Liquide, Messer SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elemental Fluorine Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of technological demands for atomic-level precision and the logistical imperatives of managing a highly hazardous material. This dynamic pushes innovation toward purity, safety, and localized supply models.
On-site fluorine generation systems provide a direct source of high-purity gas at the point of consumption. Semiconductor fabricators are the primary adopters, integrating these units to support chamber cleaning processes for advanced nodes. This technology is miniaturizing the production footprint, shifting it from large chemical plants to the semiconductor sub-fab.
Global regulations, such as the US EPA's risk management programs and Europe's ECHA directives, are tightening controls on the production and transport of hazardous gases. This forces producers to invest heavily in advanced safety monitoring and containment infrastructure. The electronics sector is most impacted, favoring suppliers with transparent and verifiable compliance with these stringent mandates.
A focus on supply chain security is altering gas procurement strategies within the semiconductor industry. Fab operators are diversifying away from single-source bulk supply contracts, increasingly exploring dual-sourcing or on-site generation as a hedge against disruption. This behavioral change is most apparent in new fabrication plant projects in the United States and Taiwan.
Elemental Fluorine Market Segmentation
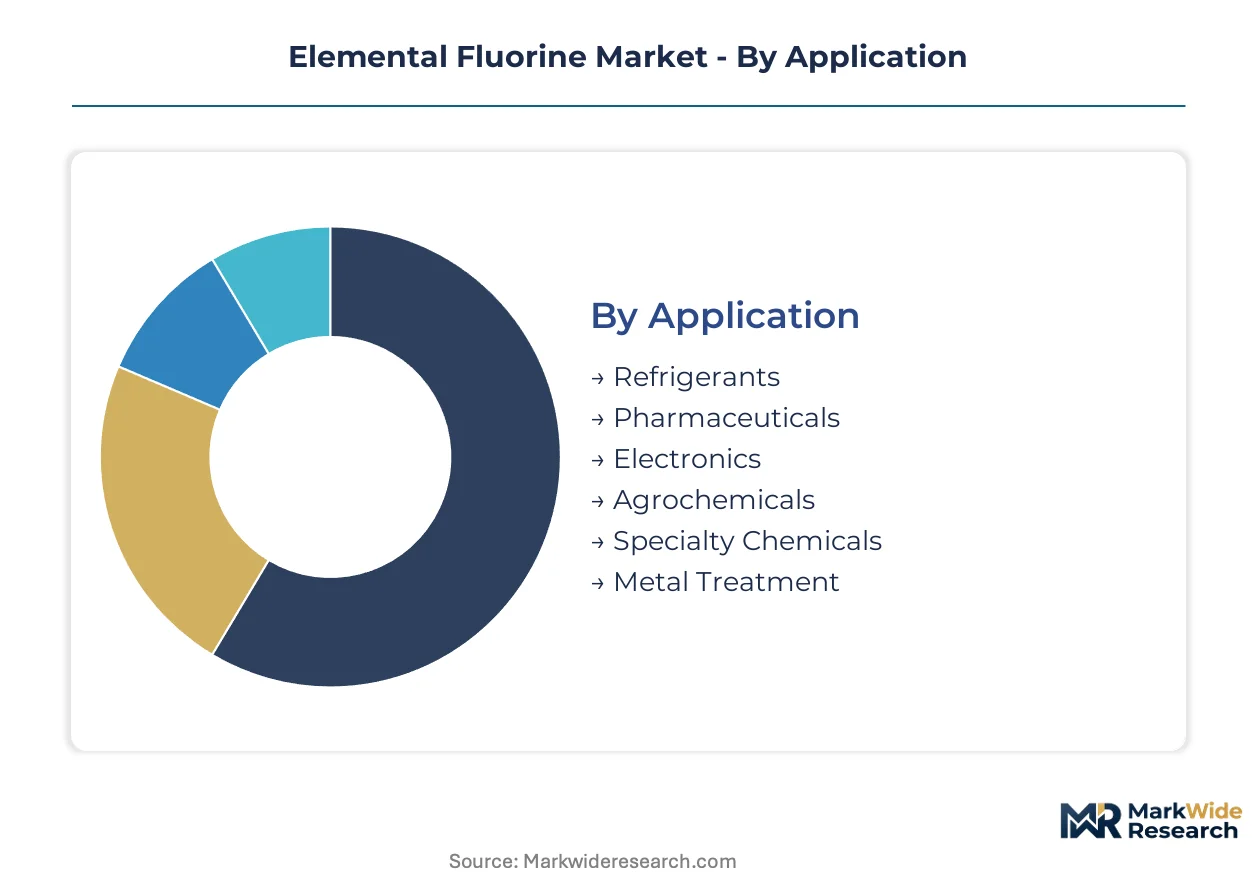
The elemental fluorine market's segmentation reflects diverse applications and specialized requirements for this highly reactive gas. Understanding these distinct segments is critical for producers to strategically allocate resources and tailor product offerings. This analysis highlights the varying value propositions across different market components.
Application:
Margin pools for elemental fluorine applications sit predominantly within specialized, high-value sectors demanding ultra-pure forms.
- Electronics:Fluorine's use in semiconductor manufacturing for chamber cleaning and etching commands value. Demand concentrates in advanced fabrication clusters in South Korea, Taiwan, and the United States, driven by sub-5nm architectures.
- Pharmaceuticals:Elemental fluorine is a crucial building block in synthesizing fluorinated active pharmaceutical ingredients (APIs). Its reactivity enables unique chemical transformations for novel drug development.
- Refrigerants:Fluorine compounds are integral to HFCs and HFOs. Regulatory shifts influence demand for lower global warming potential (GWP) alternatives.
- Agrochemicals:Fluorine incorporated into crop protection chemicals enhances efficacy. Demand comes from new herbicide and pesticide development.
- Specialty Chemicals:This category leverages fluorine's unique properties for advanced materials, including polymers, lubricants, and dielectric gases.
- Metal Treatment:Traditional uses in metal surface passivation and purification represent a foundational, stable segment.
Electronics holds installed capacity for high-purity fluorine consumption. Pharmaceuticals is rotating up the share rankings due to increasing R&D in fluorinated drugs.
Product Type:
The cost tier for elemental fluorine product types varies significantly based on purity levels and delivery methods.
- High-Purity Fluorine:This product, often exceeding 99.999% purity, is essential for advanced semiconductor manufacturing. Demand concentrates in regions with leading-edge fabs like Taiwan and the United States, driven by atomic-level precision.
- Gaseous Fluorine:Elemental fluorine is predominantly handled and delivered as a gas, requiring specialized containment and distribution infrastructure. It is used in industrial processes like chamber cleaning.
- Liquid Fluorine:Used in niche applications like rocket propellants or specialized research, requiring cryogenic temperatures and robust safety protocols.
- Fluorine Mixtures:Combine elemental fluorine with inert gases to reduce reactivity and improve handling safety for industrial applications.
- Stabilized Fluorine:Research targets methods for stabilizing fluorine to enhance transportability and reduce handling risks.
Demand for High-Purity Fluorine shows the steepest expansion trajectory, while Gaseous Fluorine maintains stable volume across industrial applications.
End User:
Application-specific requirements define procurement strategies and technical specifications for elemental fluorine across various end-user segments.
- Semiconductor Fabricators:These firms drive demand for ultra-high purity fluorine, using it for plasma etching and chamber cleaning in advanced chip manufacturing. Demand concentrates in major fab locations globally.
- Pharmaceutical Companies:These companies utilize fluorine in synthesizing complex organic molecules for drug development. Demand is driven by increasing complexity of new chemical entities.
- Chemical Manufacturing:Manufacturers produce fluorinated chemicals, polymers, refrigerants, and specialty gases, often procuring bulk quantities.
- Crop Protection Firms:Employ fluorine as a key ingredient in novel agrochemicals, with demand tied to agricultural innovation cycles.
- Metal Processing Plants:Facilities use fluorine for surface treatment, passivation, and purification of metals, typically for lower purity grades.
- Industrial Gas Suppliers:These entities procure fluorine from producers, distributing it to various end-users while managing complex logistics.
Semiconductor Fabricators are gaining share fastest due to relentless technology advancement, while Chemical Manufacturing represents a foundational segment for elemental fluorine.
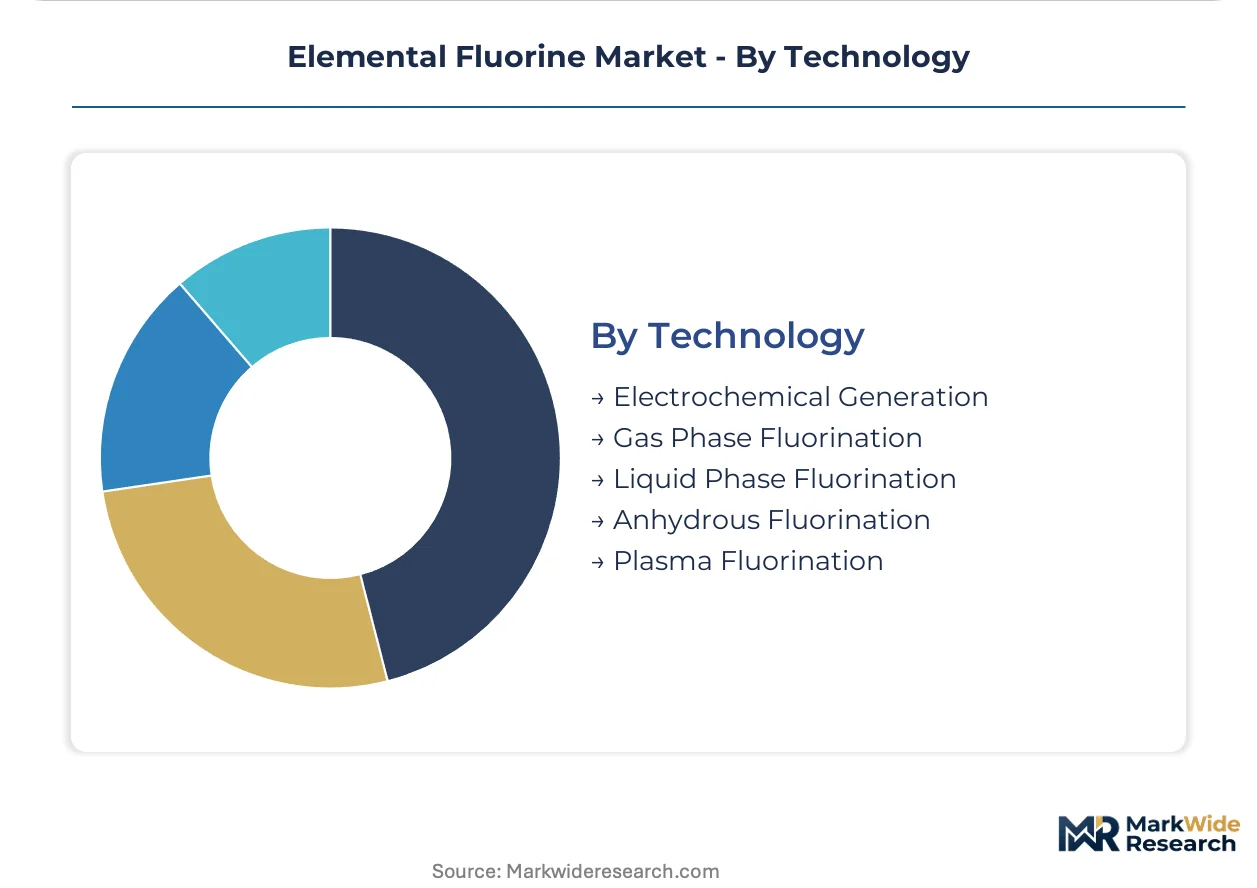
Technology:
Supply concentration for elemental fluorine production technologies is influenced by capital intensity and specialized infrastructure.
- Electrochemical Generation:This is the dominant method for producing elemental fluorine, involving molten salt electrolysis (KF·2HF). It is an energy-intensive process requiring specialized cells and materials.
- Plasma Fluorination:This technology utilizes a plasma environment to generate and react fluorine species, often for surface modification or localized, on-site generation. It gains traction for high-purity applications in fabs.
- Gas Phase Fluorination:Reacts a substrate with fluorine in the gaseous phase for specific chemical syntheses and precise material modifications.
- Liquid Phase Fluorination:Carries out fluorination reactions in a liquid medium, often requiring specialized solvents for organic synthesis routes.
- Anhydrous Fluorination:Conducts fluorination reactions in the absence of water, critical due to fluorine's extreme reactivity with moisture.
Electrochemical Generation is expanding most quickly due to continued industrial demand, with Plasma Fluorination showing consistent growth for specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental fluorine demand exhibits varying elasticity across end-use sectors. Buyers in traditional metal treatment applications often display higher price sensitivity, whereas the semiconductor industry shows significant inelasticity for ultra-high purity gas. This fundamental contrast shapes regional market dynamics and investment priorities.
United States
Demand in the United States concentrates on advanced semiconductor manufacturing, particularly for sub-5nm chip architectures. The US CHIPS Act incentivizes domestic production and secures critical supply chains for high-purity fluorine. New fabrication clusters in Arizona, Texas, and New York are driving localized consumption requirements.
Taiwan
Taiwanese fabricators anchor global demand for ultra-high purity fluorine, essential for their leading-edge semiconductor foundries. Local environmental protection agencies enforce stringent safety protocols for fluorine handling and transport. The Hsinchu Science Park and Southern Taiwan Science Park represent critical consumption hubs.
South Korea
South Korea's robust memory and logic chip production necessitates substantial volumes of high-purity elemental fluorine. The Ministry of Environment (MEE) oversees strict regulations for industrial gas production and emissions. Major semiconductor production sites in Gyeonggi Province and Pyeongtaek are key demand centers.
China
China's expanding chemical manufacturing sector and ambitious semiconductor development plans create significant fluorine demand. The Ministry of Ecology and Environment (MEE) mandates rigorous environmental and safety standards for chemical producers. Industrial zones in the Yangtze River Delta are developing localized fluorine supply capabilities.
Germany
German chemical companies utilize elemental fluorine for specialty fluorochemicals and advanced material synthesis. Europe's ECHA under REACH imposes comprehensive regulations on hazardous substance production and usage. Clusters in Bavaria and North Rhine-Westphalia house significant fluorochemical production facilities.
Elemental Fluorine Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the elemental fluorine market. This tiered structure reflects the capital intensity of production and the specialized handling requirements for this highly reactive gas. Strategic archetypes include large multinational industrial gas suppliers, specialized high-purity fluorine producers, and diversified fluorochemical manufacturers. Capacity expansion initiatives and strategic partnerships across the value chain represent dominant competitive moves.
Within the industrial gas supplier archetype, Linde plc and Air Liquide leverage extensive global distribution networks to serve a wide range of end-users. Kanto Denka Kogyo Co., Ltd. exemplifies a specialized producer, focusing on ultra-high purity fluorine tailored for the electronics sector. Solvay S.A., a diversified chemicals company, represents a significant player in fluorochemical production, sustaining its market position through continuous investment in capacity.
| Leading Market Players |
|---|
| Solvay S.A. |
| Navin Fluorine International Ltd. |
| Air Products and Chemicals, Inc. |
| Linde plc |
| Kanto Denka Kogyo Co., Ltd. |
| Pelchem SOC Ltd. |
| Advance Research Chemicals, Inc. |
| Air Liquide |
| Messer SE & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for ultra-high purity elemental fluorine provide semiconductor fabricators with stable supply access and predictable pricing. This contract structure helps mitigate volatility from energy-intensive production costs and stringent transport logistics.
Pricing Analysis
After-sales service and specialized handling expertise drive lifetime value for elemental fluorine suppliers. The dominant pricing structure for high-purity fluorine is contract-based long-term offtake, while lower purity grades trade closer to commodity spot prices. Price differentiation stems from extreme purity levels required for sub-5nm chip architectures and the specialized containment needed for transport. Pricing pressure points upward due to energy-intensive production and stringent environmental compliance, making semiconductor fabricators the least price-sensitive buyers.
Supply Chain Analysis
South Korea and Taiwan anchor high-purity fluorine consumption for advanced semiconductor manufacturing. The supply chain relies on molten salt (KF·2HF) and specialized Monel alloys for production equipment, making it susceptible to raw material price volatility. A structural risk is single-source vulnerability for ultra-high purity grades, compounded by stringent transport regulations from the US EPA and ECHA. Distribution runs through major industrial gas suppliers for bulk quantities, with a growing trend towards direct-to-fab on-site generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elemental fluorine market is defined by a deep scarcity of specialized talent for handling and producing this highly reactive gas. This capability gap creates significant operational challenges and investment barriers across the value chain.
For Market Incumbents:Compound investments in advanced safety infrastructure and specialized talent development. This mitigates the threat of increasingly stringent regulatory oversight and ensures operational continuity for highly reactive materials. Secure long-term energy supply contracts to hedge against electricity price volatility, a major cost component in electrochemical generation. Prioritize certification investment for ultra-high purity grades to maintain market leadership in the semiconductor sector.
For New Entrants and Emerging Players:Anchor in niche applications like modular on-site fluorine generation systems for semiconductor fabs. This approach bypasses hazardous transport logistics and targets the growing demand from new fabrication clusters in the United States. Explore opportunities in next-generation battery chemistries, specifically fluorinated electrolytes, as a high-value application. A strong go-to-market angle involves strategic partnerships with semiconductor equipment manufacturers.
For Investors and Strategic Acquirers:Specialized high-purity fluorine producers with robust safety protocols represent attractive long-term viability over the next five to ten years. Their expertise is crucial for critical sectors like advanced semiconductors. Target firms with established compliance records and R&D capabilities in localized generation technologies. A key signal to watch is increased government incentives for domestic fluorine production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables major producers like Solvay S.A. to meet growing demand from advanced semiconductor fabs. |
| Green Manufacturing Transition | Addresses stringent environmental mandates from the US EPA and China's MEE, reducing operational risk. |
| Long-term Supply Agreements | Secures stable, high-purity fluorine supply for critical semiconductor fabricators in Taiwan and South Korea. |
| Joint Venture for On-Site Generation | Facilitates localized production, bypassing hazardous transport logistics and enhancing supply chain resilience. |
| Specialized Talent Development Programs | Mitigates the scarcity of chemical engineers and technicians with expertise in fluorochemical handling. |
Research Approach
A standing panel of plant managers, R&D directors, procurement leads at semiconductor fabs, and regulatory compliance officers provided ongoing calibration. This primary intelligence was validated against secondary sources including industry association reports, customs data, and scientific literature. The analytical framework employed both bottom-up market sizing and top-down validation, ensuring robust data integrity.
Outputs were consistently checked against external benchmarks and industry growth projections across the analysis window. The market was segmented by application, product type, end-user, technology, and regional production hub. Compound annual growth rates were derived from historical trends and projected growth drivers, including semiconductor capital expenditure and regional electricity prices.
Decision-makers should treat outputs as directional under base assumptions regarding semiconductor demand and regulatory stability; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging potential risks from geopolitical disruptions or unforeseen regulatory shifts. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Pinoxaden Market
Chemicals
Detergent Alcohols Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Paint Stripper Market
Chemicals
p-Coumaric Acid Market
Chemicals
Household Insecticides Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Japan Methanol Market
Chemicals
Aluminium Chloride Market
Chemicals
Lauryl Dimethyl Amine Oxide Market