
 Global Chiral Chemicals Market | 2026-2036
Global Chiral Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chiral Chemicals Market Foresight
Pharmaceutical-grade enantiopurity specifications is rotating the Global Chiral Chemicals Market toward higher-margin contract manufacturing. Daicel Corporation leverages its chromatography resin technology to dominate preparative separation services for drug developers. BASF SE anchors large-scale asymmetric hydrogenation capacity across multiple production sites. Merck KGaA differentiates through its biocatalysis platform, supplying engineered enzymes for selective transformations.
Chiral chemicals are stereochemically pure organic compounds containing one or more asymmetric carbon centers, typically manufactured through asymmetric synthesis, biocatalysis, or chromatographic resolution to achieve enantiomeric excess exceeding 99 percent for pharmaceutical applications. Their primary industrial purpose centers on producing active pharmaceutical ingredients where biological activity frequently resides in a single enantiomer. Chiral amines command the largest volume share within product type segments due to their prevalence in cardiovascular and central nervous system drugs. Biocatalysis represents the fastest-expanding technology category as enzyme engineering reduces solvent waste and operating temperatures compared to traditional chemical routes. Pharmaceutical synthesis absorbs the dominant share of application demand, though agrochemical production is gaining traction as crop protection regulators mandate stereospecific active ingredients.
FDA enantiopurity guidelines and EMA's MDR framework collectively elevate quality thresholds for chiral drug submissions, compelling manufacturers to validate stereochemical consistency across batches. REACH registration requirements in Europe and China's NMPA technical standards further fragment compliance obligations across production geographies. India's CDSCO aligns with ICH Q11 guidelines for chiral API development, reinforcing the country's contract manufacturing appeal. Stakeholders must monitor evolving pharmacopeial monographs and enzyme patent expirations to reposition technology portfolios ahead of competitive inflection points.
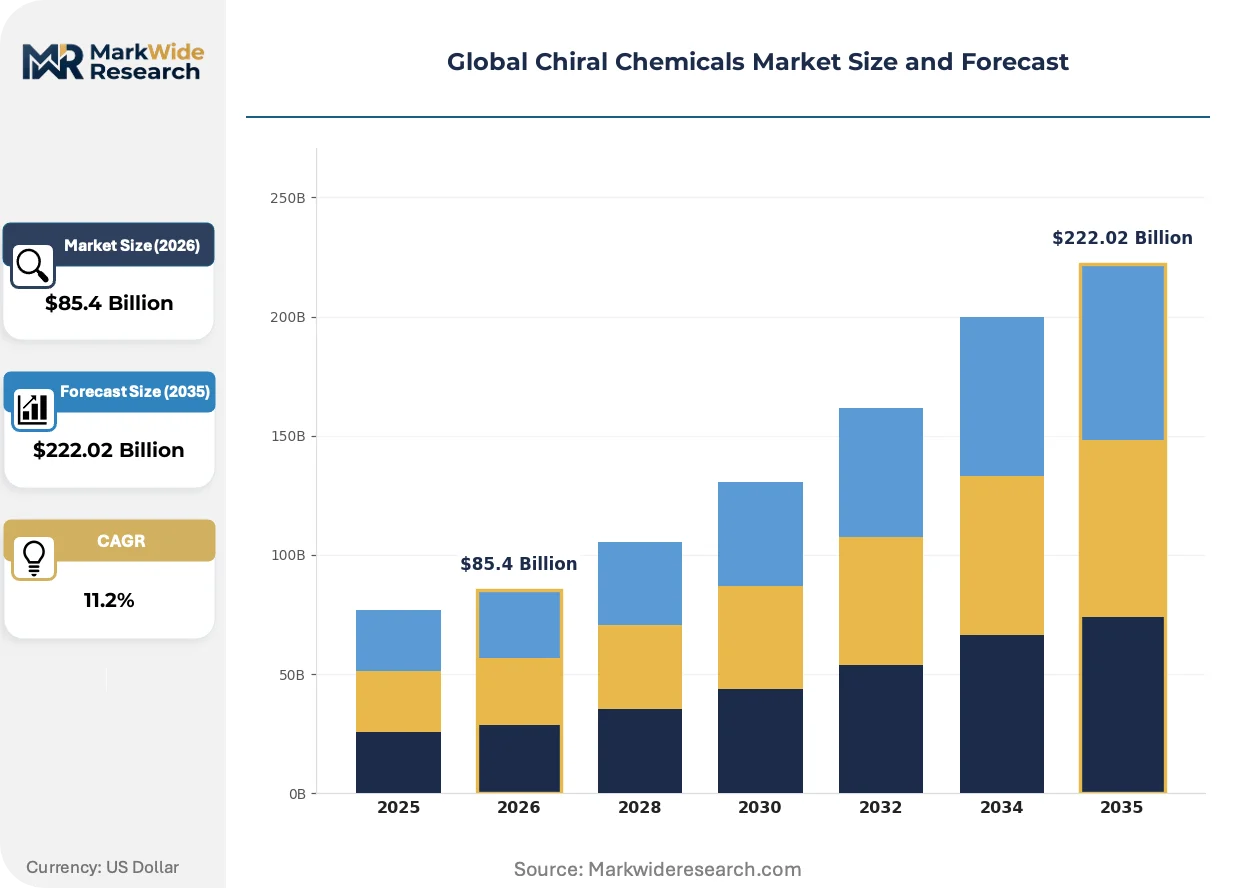
Market Dynamics
FDA and EMA enantiopurity mandates are compressing batch validation timelines while biocatalysis advances slash solvent waste, forcing manufacturers to rebuild process economics around stereochemical consistency rather than throughput volume.
Growth Catalysts
- Regulatory stringency:FDA's tightened enantiopurity requirements for new drug applications compel API manufacturers to invest in chiral separation infrastructure. EMA's MDR framework extends these standards to medical device coatings containing chiral actives.
- Biocatalysis maturation:Engineered enzyme platforms reduce reaction temperatures and eliminate hazardous solvents in asymmetric synthesis. Pharmaceutical contract manufacturers adopt these routes to meet corporate sustainability commitments.
- India:The country's CDSCO alignment with ICH Q11 guidelines attracts multinational pharma outsourcing for chiral API development. Hyderabad and Ahmedabad clusters expand specialized manufacturing capacity.
Market Restraints
- Specialized resin costs:Preparative chromatography media for enantiomeric separation command premium pricing with limited supplier alternatives. Daicel Corporation's market position in chiral stationary phases creates input concentration risk.
- Process validation burden:Demonstrating stereochemical consistency across commercial batches requires extended analytical protocols. FDA guidance on chiral switching studies adds regulatory friction for generic entrants.
- Transition metal volatility:Asymmetric hydrogenation catalysts rely on rhodium and ruthenium complexes subject to precious metal price swings. BASF SE's multi-site production hedges against single-source exposure.
Strategic Opportunities
- Agrochemical stereospecificity:Crop protection regulators in Brazil and Australia mandate enantiopure active ingredients for environmental persistence reduction. Chiral chemical suppliers pivot R&D toward herbicide and fungicide intermediates.
- China NMPA technical standards:The regulator's updated chiral drug quality guidelines create compliance service demand for domestic manufacturers. Foreign technology licensors capture premium positioning in enzyme supply contracts.
- Continuous flow integration:Combining biocatalysis with flow chemistry enables real-time enantiomeric excess monitoring. Early adopters in pharmaceutical process development compress cycle times for clinical candidate supply.
Industry Challenges
- Enzyme engineering talent scarcity:Protein design and directed evolution expertise concentrates at specialized academic centers and platform companies. Contract manufacturers struggle to recruit computational biologists for in-house biocatalysis programs.
- Multi-jurisdiction filing complexity:REACH registration requirements in Europe, China's NMPA technical standards, and India's CDSCO submissions demand divergent stereochemical documentation. Regulatory affairs teams face timeline coordination across agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chiral Chemicals Market |
| Market Size in 2026 | $85.4 Billion |
| Market Size in 2035 | $222.02 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chiral Amines, Chiral Acids, Chiral Alcohols, Chiral Ketones, Chiral Ethers Application: Pharmaceutical Synthesis, Agrochemical Production, Food Additives, Flavors & Fragrances, Specialty Polymers End User: Pharma Manufacturers, Agrochemical Enterprises, Food Industry, Chemical Producers, Material Science Labs Technology: Asymmetric Synthesis, Biocatalysis, Chromatographic Resolution, Enzymatic Resolution, Crystallization Techniques |
| Companies Covered | Daicel Corporation, Codexis, BASF SE, PerkinElmer, Merck KGaA, Johnson Matthey, Chiral Technologies, W. R. Grace & Co., Solvias AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chiral Chemicals Market Shifts & Advancements
Process intensification and regulatory digitization are converging to redefine how chiral chemicals are manufactured, validated, and supplied to pharmaceutical and agrochemical end-users.
Continuous biocatalytic reactors are miniaturizing production footprints while maintaining enantiomeric excess above 99 percent. Mid-scale pharmaceutical manufacturers deploy these systems for clinical trial material supply, avoiding capital-intensive batch infrastructure. The technology is miniaturizing minimum efficient scale thresholds, enabling distributed manufacturing models closer to formulation sites.
EMA's MDR framework extends quality system requirements to chiral active ingredients in medical devices, not just pharmaceuticals. Manufacturers must now document stereochemical stability across sterilization processes. European contract research organizations expand analytical validation services to capture this compliance burden.
Buyer consolidation among top-tier pharmaceutical companies concentrates chiral API procurement decisions. Merck KGaA and specialized biocatalysis houses negotiate multi-year enzyme supply agreements with volume commitments. Japanese and South Korean pharma conglomerates drive this pattern through integrated sourcing mandates for their global manufacturing networks.
Global Chiral Chemicals Market Segmentation
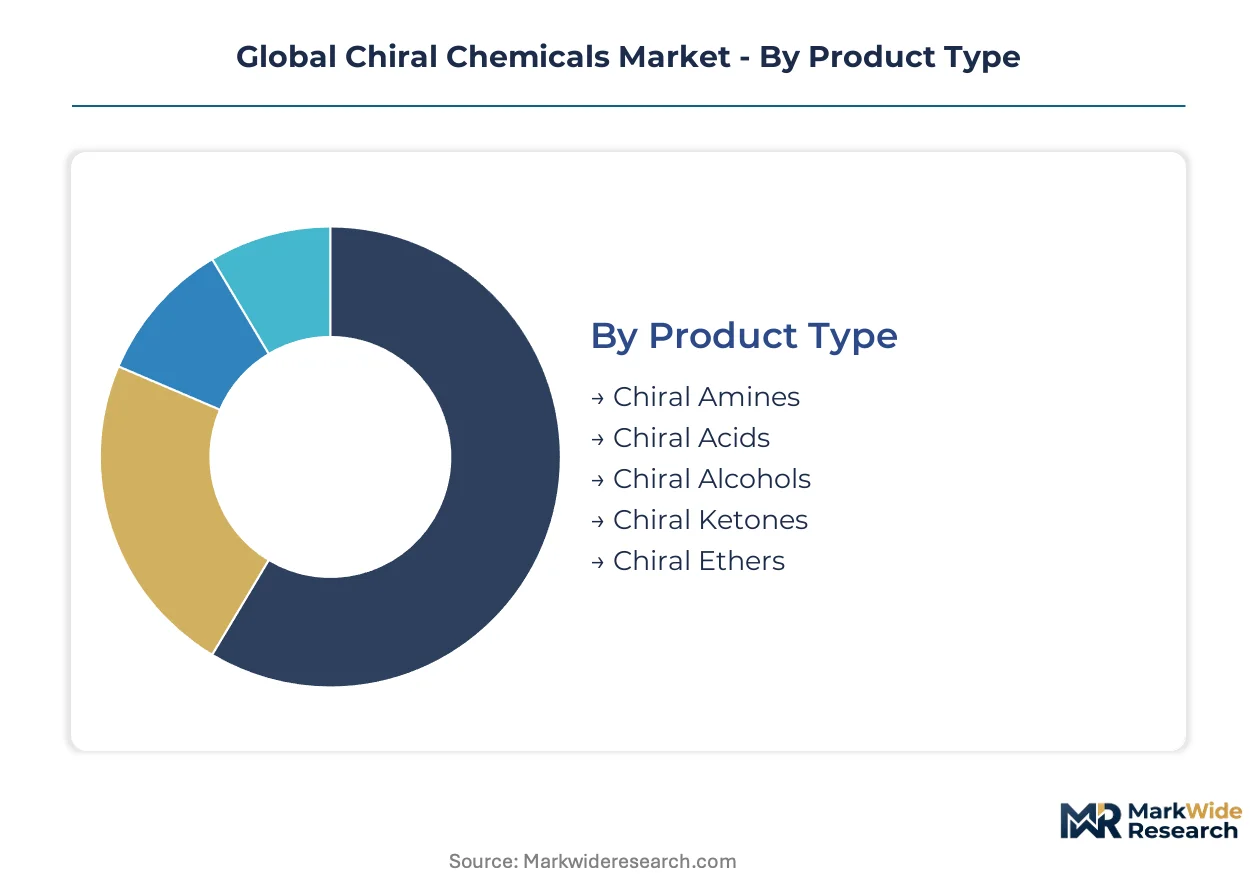
Chiral chemical segmentation reveals distinct procurement patterns across pharmaceutical, agrochemical, and specialty material value chains. Technology choice and end-use specifications determine whether production serves domestic formulation sites or export-driven API supply networks.
Product Type:
Chiral amines and chiral acids anchor export volumes to contract manufacturing hubs in India and China, while chiral alcohols and ketones predominantly serve domestic pharmaceutical formulation demand in North America and Europe.
- Chiral Amines:Nitrogen-containing stereocenters dominate cardiovascular and CNS drug portfolios. Hyderabad and Ahmedabad clusters process bulk volumes for Merck KGaA and multinational pharma networks, driven by FDA enantiopurity mandates tightening batch release protocols.
- Chiral Acids:Carboxylic acid derivatives with defined stereochemistry supply antihypertensive and anti-inflammatory API routes. China's Zhejiang and Jiangsu provinces concentrate manufacturing for export to European generic drugmakers facing REACH registration deadlines.
- Chiral Alcohols:Hydroxyl-bearing stereocenters serve local pharmaceutical formulation in the United States and Germany.
- Chiral Ketones:Carbonyl functionality with asymmetric centers supports domestic specialty chemical production.
- Chiral Ethers:Oxygen-linked stereogenic centers find niche application in fragrance and polymer intermediates.
Chiral amines hold the largest share; momentum sits with chiral acids as European generic manufacturers accelerate API outsourcing.
Application:
Cost tier stratification separates high-margin pharmaceutical synthesis from volume-driven agrochemical and food additive segments, with technology licensing fees concentrating in drug development applications.
- Pharmaceutical Synthesis:Stereochemically pure intermediates for active pharmaceutical ingredients command premium pricing tied to regulatory validation burden. CDSCO-aligned Indian manufacturers capture multinational outsourcing as FDA and EMA tighten enantiopurity submission requirements.
- Agrochemical Production:Enantiopure herbicide and fungicide actives gain regulatory traction in Brazil and Australia. São Paulo-based formulators source chiral intermediates from Chinese suppliers adapting to NMPA technical standards for export compliance.
- Food Additives:Stereoselective flavor compounds serve regional formulation requirements.
- Flavors & Fragrances:Chiral molecules with defined odor profiles target premium consumer product markets.
- Specialty Polymers:Optically active monomers enable advanced material properties in electronics and medical devices.
Pharmaceutical synthesis generates the highest margins; agrochemical production is climbing the fastest as environmental regulators mandate stereospecific actives.
End User:
Customer type determines procurement scale and technical service intensity, with pharma manufacturers demanding dedicated analytical support while chemical producers prioritize volume pricing.
- Pharma Manufacturers:Integrated drug developers and contract API producers drive specification-setting for enantiomeric excess thresholds above 99 percent. Japanese and South Korean conglomerates consolidate sourcing through multi-year enzyme supply agreements with biocatalysis specialists.
- Agrochemical Enterprises:Crop protection formulators in Brazil and Australia require chiral actives for regulatory compliance with environmental persistence standards.
- Food Industry:Flavor houses and ingredient suppliers purchase stereoselective compounds for regional taste profiles.
- Chemical Producers:Bulk intermediates buyers prioritize cost efficiency over technical service intensity.
- Material Science Labs:Research-scale procurement of novel chiral building blocks supports polymer and electronics development.
Pharma manufacturers dominate procurement value; agrochemical enterprises represent the steepest expansion trajectory as regulatory mandates spread beyond pharmaceutical applications.
Technology:
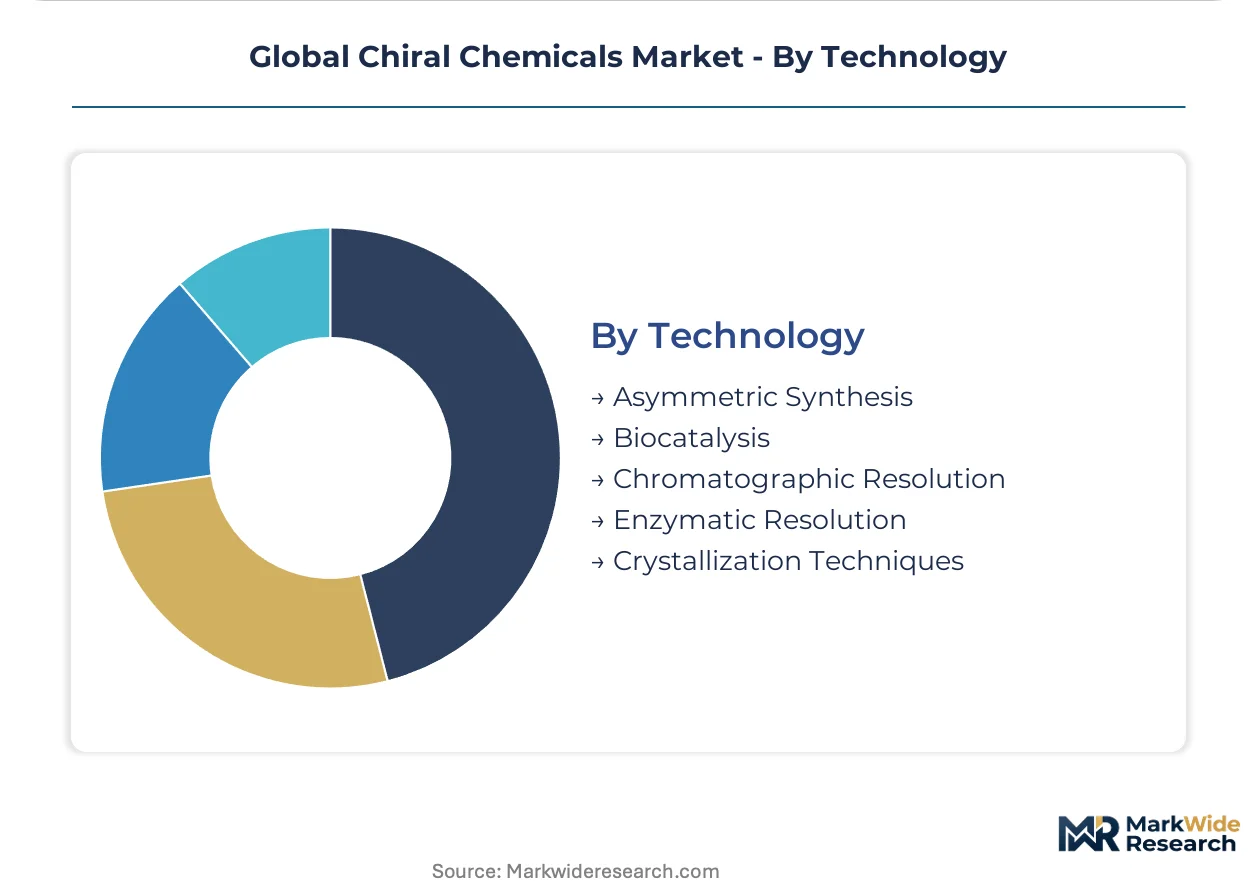
Supply concentration varies sharply by technology maturity, with asymmetric synthesis and chromatographic resolution dominated by established chemical producers while biocatalysis platforms concentrate at specialized enzyme engineering houses.
- Asymmetric Synthesis:Transition metal catalysis with chiral ligands enables large-scale hydrogenation at BASF SE multi-site facilities. Rhodium and ruthenium complex availability creates input cost volatility requiring precious metal hedging strategies.
- Biocatalysis:Engineered enzyme platforms reduce solvent waste and operating temperatures versus chemical routes. Codexis and Merck KGaA license directed evolution capabilities to contract manufacturers seeking sustainability compliance.
- Chromatographic Resolution:Preparative separation with chiral stationary phases concentrates at Daicel Corporation facilities.
- Enzymatic Resolution:Kinetic resolution using hydrolytic enzymes serves intermediate-scale pharmaceutical production.
- Crystallization Techniques:Diastereomeric salt formation provides cost-effective separation for specific compound classes.
Asymmetric synthesis retains the largest installed capacity; biocatalysis is gaining share fastest as enzyme engineering shortens synthetic routes and reduces environmental compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chiral chemical manufacturing clusters concentrate where pharmaceutical and agrochemical contract research networks intersect with specialized chemical infrastructure. India and China dominate export-oriented API intermediate production, while Germany and Switzerland anchor high-value enzyme engineering and analytical services. Regulatory harmonization pressures are redrawing investment flows toward jurisdictions with streamlined pharmacopeial alignment.
India
Hyderabad and Ahmedabad clusters process bulk chiral amine volumes for cardiovascular and CNS drug portfolios. CDSCO alignment with ICH Q11 guidelines attracts multinational pharma outsourcing for API development. Specialized manufacturing parks in Telangana and Gujarat expand preparative chromatography and biocatalysis capacity to meet FDA enantiopurity submission requirements.
China
Zhejiang and Jiangsu provinces concentrate chiral acid production for European generic drugmakers facing REACH registration deadlines. NMPA technical standards for chiral drug quality create compliance service demand for domestic manufacturers. Shanghai and Suzhou hubs integrate asymmetric synthesis infrastructure with export-oriented pharmaceutical intermediate supply chains.
Germany
Ludwigshafen and Leverkusen anchor large-scale asymmetric hydrogenation capacity across multi-site production networks. EMA's MDR framework extends quality system requirements to chiral actives in medical devices, expanding analytical validation obligations. Bavaria-based enzyme engineering specialists license directed evolution platforms to contract manufacturers seeking sustainability compliance.
Switzerland
Basel and Geneva house precision analytical services and chiral separation technology development for pharmaceutical quality control. Swissmedic pharmacopeial standards influence global reference material specifications for enantiomeric excess validation. Specialized CROs expand stereochemical stability documentation services across sterilization process requirements.
United States
New Jersey and Massachusetts clusters drive specification-setting for enantiomeric excess thresholds above 99 percent in innovative drug development. FDA tightened enantiopurity requirements for new drug applications compel API manufacturers to invest in chiral separation infrastructure. Boston-area biocatalysis startups partner with Midwest chemical processors to deploy continuous flow enzymatic reactors.
Global Chiral Chemicals Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized enzyme engineering houses that control critical technology platforms. The vendor base spans three tiers: integrated chemical majors with multi-site catalytic infrastructure, focused biocatalysis licensors with proprietary enzyme libraries, and regional contract manufacturers serving domestic pharmacopeial requirements. Two dominant competitive moves are reshaping positioning: strategic partnerships between enzyme developers and pharmaceutical CMOs, and capacity expansion in Indian and Chinese manufacturing clusters to capture FDA and EMA outsourcing flows.
Within the technology-licensor tier, Codexis and Merck KGaA exemplify engineered enzyme platform providers that reduce solvent waste and operating temperatures versus traditional chemical routes. Daicel Corporation anchors the preparative separation segment through chiral stationary phase technology. BASF SE represents the diversified chemical major archetype with asymmetric hydrogenation capacity distributed across multiple production sites to hedge precious metal input volatility.
| Leading Market Players |
|---|
| Daicel Corporation |
| Codexis |
| BASF SE |
| PerkinElmer |
| Merck KGaA |
| Johnson Matthey |
| Chiral Technologies |
| W. R. Grace & Co. |
| Solvias AG |
| Others |
Supply & Pricing Matrix
Biocatalysis adoption replacing traditional asymmetric synthesis is redrawing procurement geography toward enzyme engineering hubs in Germany and Switzerland while compressing margin structures for legacy chemical processors dependent on precious metal catalysts. This substitution dynamic simultaneously elevates technology licensing fees and fragments volume pricing power across regional contract manufacturing clusters.
Pricing Analysis
FDA enantiopurity guidelines dictate the pricing tier structure across pharmaceutical-grade chiral chemical supply. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated batches from REACH-registered intermediates and unregistered technical grades. Price differentiation hinges on enantiomeric excess certification and volume scale commitments. Cost compression in standard-tier chiral amines is intensifying because Indian manufacturers are expanding asymmetric hydrogenation capacity. Generic drug developers exhibit the highest price sensitivity; innovator pharma manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of chiral stationary phases and engineered enzyme libraries dominates inventory strategy as manufacturers buffer against Daicel Corporation's market concentration and Codexis platform licensing delays. Supply concentrates in India, China, and Germany. Production draws from rhodium and ruthenium complexes, chromatography resins, and recombinant enzyme preparations. Single-source vulnerability in chiral stationary phase supply creates structural risk. Distribution runs through pharmaceutical CMO networks and agrochemical formulator direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EMA, and NMPA jurisdictions is spawning specialized compliance service niches that reward focused technical capabilities over scale economies.
For Market Incumbents: Compound defensive positioning through backward integration into enzyme engineering capabilities and capacity expansion in Telangana manufacturing parks. Biocatalysis startups threaten technology licensing margins. Certification investment in dual FDA-EMA batch validation protocols secures procurement decisions from Japanese pharma conglomerates. For New Entrants and Emerging Players: Differentiate on continuous flow biocatalytic reactor deployment for clinical trial material supply. Agrochemical stereospecificity mandates in Brazil and Australia represent the most penetrable demand pocket. Target enzyme supply agreements with mid-tier European generic manufacturers seeking sustainability compliance without captive R&D investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations in India lacking proprietary biocatalysis platforms. The five-to-ten year viability window favors technology licensors with directed evolution patent estates over pure-play volume processors. Watch for enzyme patent cliff inflections triggering portfolio repositioning among pharmaceutical CMOs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Engineering | Captures sustainability compliance premiums from EMA MDR framework extensions. |
| Capacity Expansion in Indian Manufacturing Clusters | Positions suppliers for FDA outsourcing flows from cardiovascular API developers. |
| Long-term Enzyme Supply Agreement | Locks in multi-year revenue streams from Japanese and South Korean pharma networks. |
| Green Manufacturing Transition | Aligns production with corporate sustainability mandates and REACH registration requirements. |
| Joint Venture for Continuous Flow Technology | Combines biocatalysis expertise with pharmaceutical process development capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filing databases, EMA submission records, and customs trade data for chiral chemical imports. Interviews with regulatory affairs leads at pharmaceutical API manufacturers, procurement directors at agrochemical formulators, plant managers at asymmetric hydrogenation facilities, and technical R&D directors at enzyme engineering houses inform demand-side validation. Bottom-up volume estimates triangulate against top-down market sizing from SEC 10-K disclosures and industry association reports.
Segmentation dimensions modeled include product type, application end-use, technology platform, and regional regulatory cluster across the analysis window. CAGRs derive from growth rate convergence analysis applied to historical shipment data and capacity expansion announcements. Forecast inputs incorporate enzyme engineering patent expiration schedules and CDSCO regulatory alignment milestones.
The analysis sits within stated boundaries; outcomes outside sustained FDA enantiopurity enforcement and continued biocatalysis yield improvements would require recalibration. Forecasts reflect assumptions regarding precious metal price stability and contract manufacturing outsourcing velocity. Revision becomes warranted when NMPA technical standard implementation crosses compliance threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Fluorochemicals Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Ferric Chloride Market
Chemicals
Tanning Agents Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
China Amines Market
Chemicals
SLS and LABSA Market
Chemicals
Malic Acid Market
Chemicals
Hexachloroethane Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Methylamines Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Flatting Agents Market
Chemicals
Chlorosilane Market
Chemicals
Nonanoic Acid Market