
 Glyoxal Market | 2026-2036
Glyoxal Market Size, Share, and Industry Trends Forecast 2026-2036
Glyoxal Market Analysis
Premium-grade glyoxal is decoupling from commodity volumes as pharmaceutical and personal care buyers enforce stricter purity thresholds while textile processors absorb standard grades. BASF leverages its integrated acetaldehyde oxidation network to sustain pharmaceutical-grade output across European sites. WeylChem Group anchors high-specification batches for European disinfectant formulators. Eastman Chemical Company competes on coating-intermediate consistency in North American supply chains.
Glyoxal is a dialdehyde compound (CHO-CHO) typically supplied as an aqueous solution with concentrations ranging from 40% to 100%, manufactured through vapor-phase oxidation of acetaldehyde or ethylene glycol; it functions primarily as a crosslinking agent, disinfectant precursor, and chemical intermediate across industrial formulations. Glyoxal 40% dominates volume flows into textile resin finishing where cost efficiency outweighs concentration premiums, while glyoxal 100% captures concentrated margin pools in pharmaceutical synthesis requiring minimal water content. Intermediate applications are expanding fastest as agrochemical and specialty chemical manufacturers substitute glyoxal for formaldehyde in controlled-release formulations.
EPA regulates glyoxal emissions under TSCA Section 5 for new chemical notifications, while REACH mandates registration and hazard communication for imports into Europe, and China's MEE enforces wastewater discharge limits on glyoxal production facilities. These frameworks elevate compliance costs for smaller producers while creating market access barriers for unregistered Asian exporters. Stakeholders must monitor evolving biocidal product regulations in Europe and tightening VOC thresholds in North American coating applications.
Market Dynamics
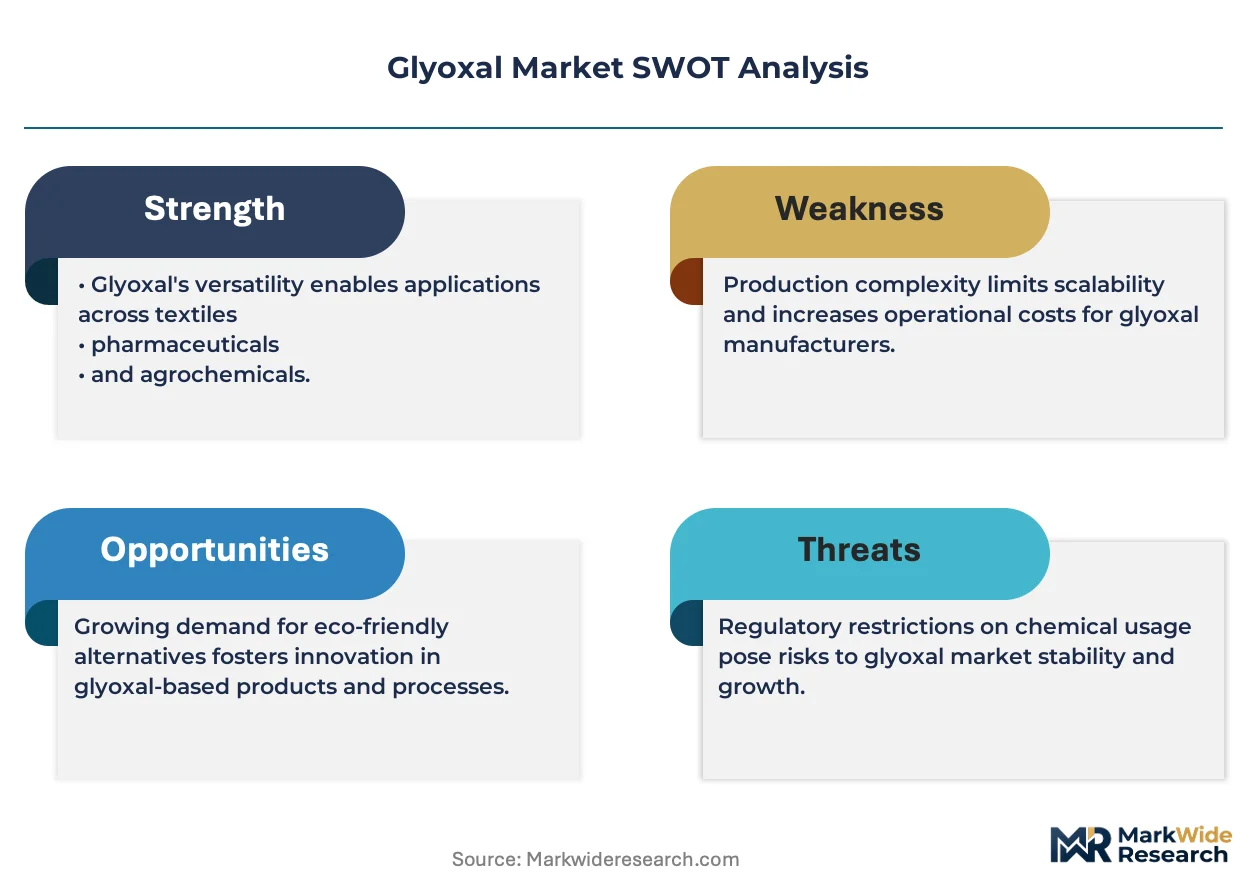
REACH purity mandates are compressing the commodity glyoxal segment while pharmaceutical-grade specifications expand the premium tier, creating a bifurcated supply structure where standard textile grades face margin erosion.
Growth Catalysts
- Formaldehyde substitution protocols:Agrochemical formulators in China are accelerating glyoxal adoption for controlled-release coatings as MEE wastewater rules tighten on formaldehyde discharge.
- Textile resin finishing expansion:India's technical textile sector is absorbing glyoxal 40% volumes for durable-press cotton treatments under rising export quality requirements.
- Disinfectant precursor demand:European biocidal product regulations are channeling procurement toward glyoxal-based formulations as safer alternatives to glutaraldehyde in healthcare surface sterilization.
Market Restraints
- Acetaldehyde feedstock volatility:Crude-linked ethylene pricing transmits directly to glyoxal production economics, squeezing spot margins for non-integrated producers.
- Jiangsu-Zhejiang supply concentration:Over sixty percent of Asian glyoxal capacity clusters in China's eastern coastal provinces, exposing buyers to typhoon-season logistics disruptions.
- Ethylene glycol oxidation yield ceilings:Vapor-phase manufacturing hits thermodynamic limits near ninety-two percent conversion, capping unit cost reductions.
Strategic Opportunities
- Indonesia agrochemical formulation:The country's expanding palm oil protection chemical sector offers untapped glyoxal demand for slow-release fertilizer coatings.
- Biocidal Products Regulation tailwinds:REACH Article 95 listing requirements are creating first-mover advantages for pre-registered glyoxal suppliers into European disinfectant channels.
- Pharmaceutical-grade membrane filtration:Crossflow nanofiltration is unifying purification steps previously requiring multiple crystallization stages, enabling new entrants to achieve USP-grade certification faster.
Industry Challenges
- Process safety engineering scarcity:Glyoxal's exothermic oxidation chemistry demands specialized reactor design expertise that retiring European chemical engineers concentrated at legacy acetaldehyde sites.
- MEE discharge permit timelines:Chinese environmental authorities are extending approval cycles for glyoxal facility expansions, delaying capacity additions by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyoxal Market |
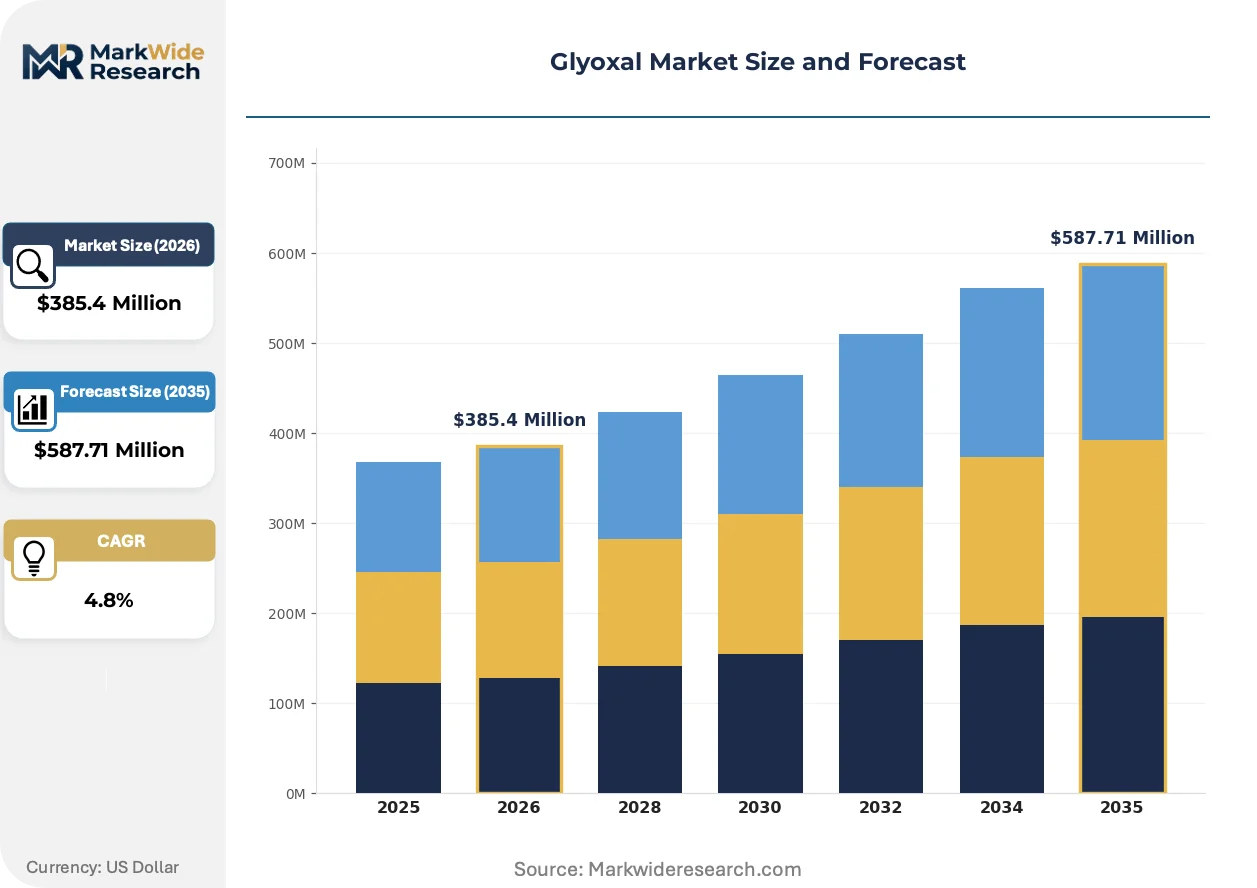
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glyoxal 40%, Glyoxal 50%, Glyoxal 60%, Glyoxal 100% End Use Industry: Textiles, Pharmaceuticals, Agriculture, Personal Care Application: Disinfectant, Coating, Intermediate, Preservative Delivery Mode: Liquid, Powder, Solution, Emulsion |
| Companies Covered | BASF, WeylChem Group, Eastman Chemical Company, Dow, Huntsman International LLC, Formosa Plastics Corporation, Silver Fern Chemical LLC, Hubei Hongyuan Pharmaceutical, Taicang Guangze Fine Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyoxal Market Emerging Trajectories
Membrane separation technologies are compressing the capital intensity gap between commodity and pharmaceutical-grade production, while regulatory chemistry is forcing substitution patterns across multiple end-use verticals.
Continuous-flow reactor engineering is unifying temperature and pressure control across oxidation stages that batch processes previously separated. Specialty chemical manufacturers in Germany are piloting these systems for pharmaceutical-grade output. The technology is unifying quality consistency metrics that previously required separate dedicated lines for each grade tier.
REACH Article 95 biocidal active substance listing is tightening supply chain documentation requirements for glyoxal entering European disinfectant formulations. Industrial chemical distributors are absorbing compliance costs through dedicated import channels. Personal care formulators in France and Germany are most affected, shifting procurement toward pre-registered suppliers with complete substance dossiers.
Direct mill-supply contracting is displacing traditional distributor intermediation in textile resin channels. Large finishing houses in Pakistan and Bangladesh are negotiating annual glyoxal 40% offtake agreements directly with oxidation plant operators. The pattern is most visible in South Asian denim processing clusters where volume concentration supports dedicated logistics arrangements.
Glyoxal Market Segmentation
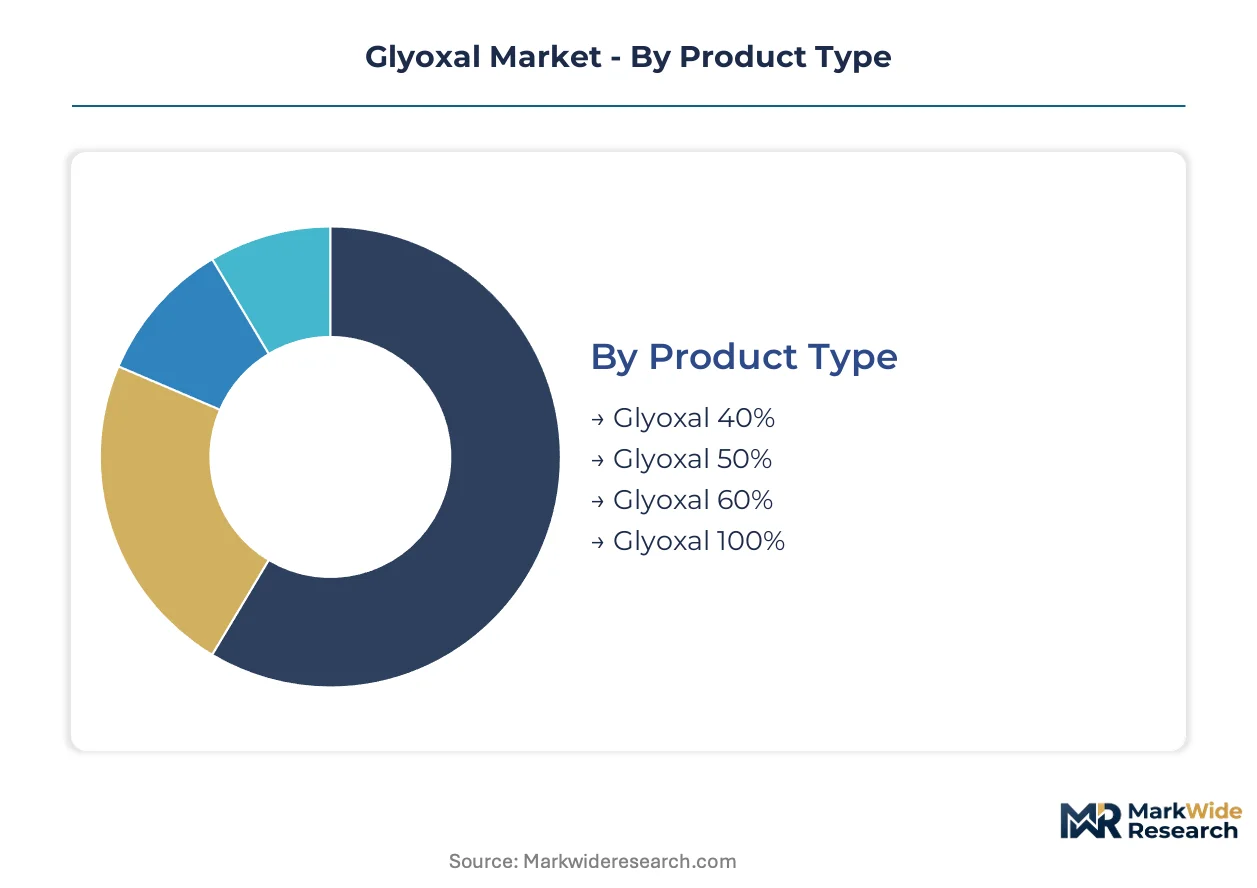
Glyoxal buyers sort themselves by purity tolerance, concentration economics, and regulatory exposure. Each segmentation axis reveals a distinct procurement logic that suppliers must match to capture margin.
Product Type:
Cost tier separates commodity textile processors from pharmaceutical formulators seeking minimal water content.
- Glyoxal 40%:Aqueous solution with water as primary carrier, optimized for textile resin finishing where dilution costs are offset by bulk handling efficiencies. Pakistan's denim processing clusters in Karachi and Faisalabad absorb the largest volumes under direct mill-supply contracts.
- Glyoxal 100%:Anhydrous dialdehyde requiring specialized storage and handling, commanding purity premiums for active pharmaceutical ingredient synthesis. German disinfectant formulators under REACH Article 95 listing requirements specify this grade for glutaraldehyde substitution protocols.
- Glyoxal 50%:Mid-concentration solution balancing transport efficiency with dilution flexibility for coating applications.
- Glyoxal 60%:Intermediate concentration serving agrochemical controlled-release formulations where water content affects polymerization kinetics.
Glyoxal 40% leads volumes today; Glyoxal 100% is gaining share fastest.
End Use Industry:
Application maturity and regulatory stringency create divergent margin profiles across buyer verticals.
- Textiles:Mature crosslinking demand for durable-press cotton treatments, concentrated in India's technical textile sector around Surat and Tiruppur as export quality requirements tighten.
- Pharmaceuticals:Synthesis of active ingredients and excipients where USP-grade certification commands substantial purity premiums; membrane filtration advances are compressing entry timelines for new suppliers.
- Agriculture:Controlled-release fertilizer coatings and crop protection formulations, expanding most quickly as China's MEE wastewater rules accelerate formaldehyde substitution in Jiangsu and Zhejiang production bases.
- Personal Care:Preservative and disinfectant precursor applications, concentrated in French and German formulators navigating REACH biocidal product documentation requirements.
Textiles anchors current procurement volumes; Agriculture shows the steepest expansion trajectory.
Application:
Functional role determines specification stringency and supply chain documentation burden.
- Intermediate:Chemical building block for downstream synthesis, absorbing standard grades where purity thresholds are set by subsequent processing steps rather than final application.
- Disinfectant:Surface sterilization formulations substituting for glutaraldehyde in European healthcare settings; REACH Article 95 listing creates first-mover advantages for pre-registered suppliers.
- Coating:Controlled-release and protective layer applications in agrochemical and textile processing, where film-forming properties outweigh absolute purity metrics.
- Preservative:Personal care and industrial formulations requiring antimicrobial efficacy documentation under biocidal product regulations.
Intermediate applications dominate current offtake; Disinfectant demand is climbing the fastest.
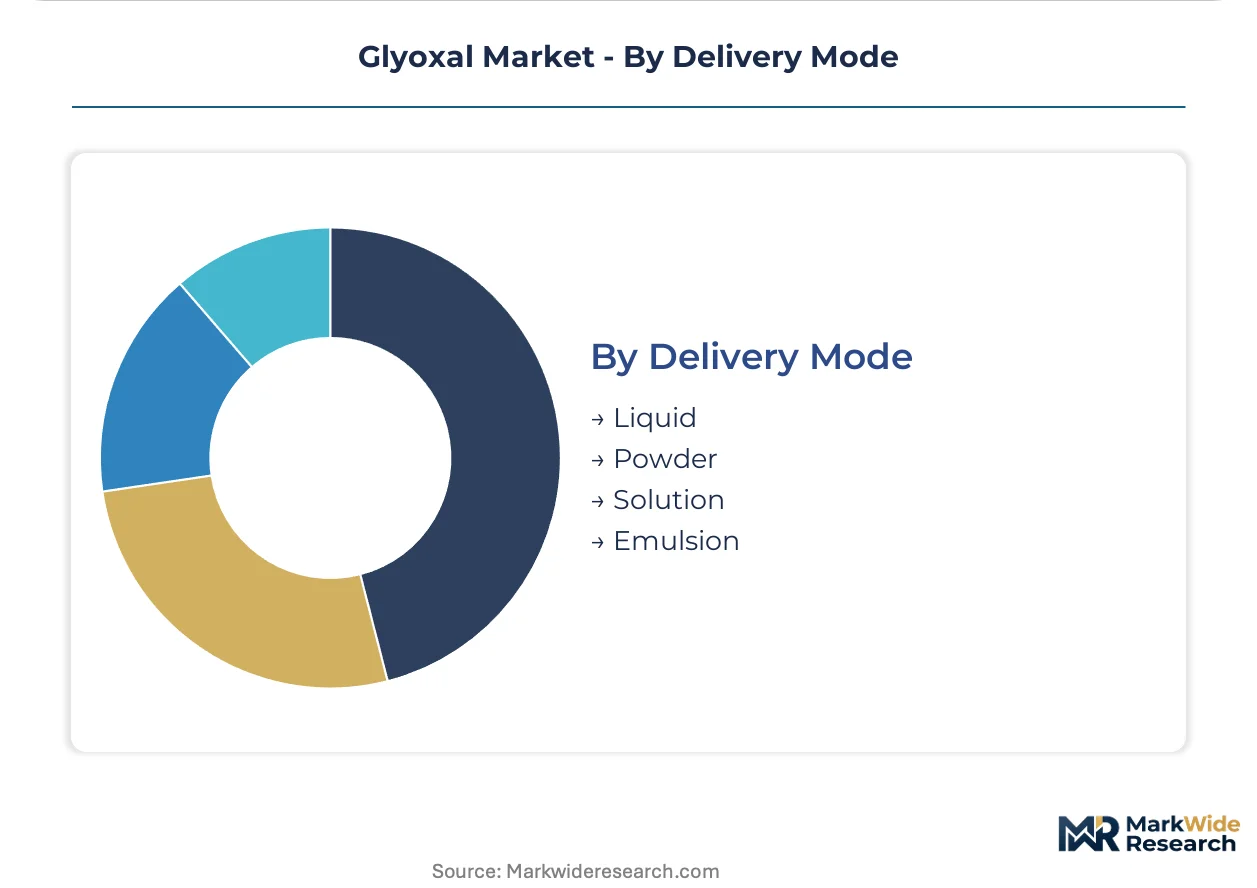
Delivery Mode:
Physical form factors align with customer handling infrastructure and formulation integration requirements.
- Liquid:Standard aqueous solutions in bulk tanker or drum delivery, matching textile finishing house infrastructure across South Asian processing clusters.
- Solution:Pre-formulated blends with stabilizers or co-solvents for direct integration into coating and disinfectant manufacturing lines.
- Powder:Spray-dried or crystalline forms for specialized pharmaceutical and personal care applications requiring precise dosing and extended shelf stability.
- Emulsion:Dispersed-phase systems for coating applications where controlled release kinetics depend on droplet size distribution.
Liquid delivery leads volumes today; Powder formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineers with acetaldehyde oxidation expertise concentrate in Germany's legacy industrial corridors and China's eastern coastal provinces, anchoring production capacity on both continents.
China
Textile resin finishers in Jiangsu and Zhejiang provinces absorb glyoxal 40% volumes under direct mill-supply contracts. MEE wastewater discharge limits on formaldehyde are accelerating glyoxal substitution in agrochemical controlled-release coatings. Production clusters around Taicang and Nantong face eighteen-to-twenty-four-month permit delays for facility expansions.
Germany
Pharmaceutical-grade glyoxal demand from disinfectant formulators is climbing under REACH Article 95 biocidal active substance listing requirements. ECHA registration mandates compress market access for unregistered exporters. BASF leverages integrated acetaldehyde oxidation networks across Ludwigshafen and Schwarzheide sites to sustain high-specification output.
United States
Coating-intermediate buyers enforce consistency specifications for crosslinking applications in textile and paper processing. EPA TSCA Section 5 notifications govern new chemical introductions, elevating compliance documentation burdens. Eastman Chemical Company anchors supply chain relationships with North American durable-press cotton finishers.
India
Technical textile manufacturers around Surat and Tiruppur are expanding glyoxal procurement for export-quality durable-press treatments. BIS quality standards for chemical intermediates are tightening purity documentation requirements. Direct contracting between denim processing clusters and oxidation plant operators is displacing traditional distributor channels.
France
Personal care formulators in Paris and Lyon are shifting procurement toward pre-registered glyoxal suppliers with complete REACH substance dossiers. ANSM biocidal product regulations channel demand toward glutaraldehyde substitutes in healthcare surface sterilization. WeylChem Group anchors high-specification batches for European disinfectant manufacturers.
Glyoxal Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated supply structure. Integrated acetaldehyde oxidation operators sustain margin advantages through captive feedstock access, while non-integrated traders absorb spot price volatility. Three archetypes dominate: multinational chemical conglomerates with backward integration into ethylene value chains, regional specialists concentrating pharmaceutical-grade purification, and commodity distributors arbitraging grade differentials. Capacity expansion and REACH pre-registration are the dominant competitive moves.
Among multinational chemical conglomerates, BASF and Dow exemplify integrated production archetypes with oxidation assets anchored in major industrial corridors. Regional specialists include Taicang Guangze Fine Chemical Co., Ltd., which occupies a position within China's eastern coastal production cluster. These named entities represent the tiered competitive structure where scale-driven operators coexist with purity-focused specialists.
| Leading Market Players |
|---|
| BASF |
| WeylChem Group |
| Eastman Chemical Company |
| Dow |
| Huntsman International LLC |
| Formosa Plastics Corporation |
| Silver Fern Chemical LLC |
| Hubei Hongyuan Pharmaceutical |
| Taicang Guangze Fine Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Acetaldehyde spot pricing on Asian ethylene benchmarks cascades through glyoxal production economics, compressing margins for non-integrated producers while integrated operators capture spread advantages across pharmaceutical and textile grade tiers.
Pricing Analysis
Commodity textile grades trade on unbundled per-kilogram spot terms, while pharmaceutical specifications bundle certification documentation and batch traceability into contract structures. Price differentiation separates USP-grade glyoxal 100% from standard textile grades through purity thresholds and REACH Article 95 registration status. Cost compression in textile-tier glyoxal 40% is intensifying because direct mill-supply contracting eliminates distributor markups. Agrochemical formulators show highest price sensitivity; disinfectant manufacturers absorbing REACH compliance costs demonstrate lowest.
Supply Chain Analysis
Direct-to-mill channels handle South Asian textile processor demand, while distributor networks serve fragmented European personal care formulators. Production gravity centers on China, Germany, and India, with Jiangsu-Zhejiang coastal provinces anchoring Asian capacity. Feedstock supply draws from ethylene oxidation and acetaldehyde merchant markets, with membrane filtration equipment creating new purification dependencies. Single-source vulnerability concentrates in typhoon-exposed Taicang-Nantong logistics corridors. Distribution runs through bulk tanker arrangements for textile clusters and specialized drum shipments for pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glyoxal procurement arbitrage opens between Chinese production economics and European REACH compliance premiums, rewarding operators who bridge regulatory documentation gaps with cost-efficient manufacturing bases.
For Market Incumbents: To counter membrane filtration technology lowering pharmaceutical-grade entry barriers, BASF and Dow should deepen backward integration into captive acetaldehyde supply while accelerating REACH Article 95 dossier completion for biocidal product channels. Capacity preservation in Ludwigshafen and Schwarzheide secures European disinfectant formulator relationships against emerging Asian competitors.
For New Entrants and Emerging Players: E-procurement platforms for South Asian textile clusters offer direct contracting routes that bypass established distributor relationships. Indonesia's palm oil protection chemical sector presents the most penetrable white-space opportunity for controlled-release fertilizer coatings. A technical-service-led go-to-market angle emphasizing polymerization kinetics support differentiates against commodity traders.
For Investors and Strategic Acquirers: Consolidation pressure builds where MEE permit delays strand Chinese capacity expansion timelines and create distressed asset opportunities. Long-term viability favors operators with integrated ethylene-to-glyoxal control and pre-registered European supply positions. Acquisition targets should display membrane filtration capabilities or REACH-compliant disinfectant channel access. Watch for MEE discharge permit issuance velocity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acetaldehyde supply shields BASF from ethylene spot volatility across European oxidation assets. |
| REACH Article 95 Pre-registration | Early biocidal active substance listing secures preferential access to French and German disinfectant formulators. |
| Membrane Filtration Deployment | Crossflow nanofiltration compresses USP-grade certification timelines for new pharmaceutical market entrants. |
| Direct Mill-Supply Contracting | Annual offtake agreements with Karachi and Faisalabad denim processors displace distributor intermediation. |
| Indonesia Market Development | Slow-release fertilizer coating partnerships with palm oil protection chemical manufacturers unlock Southeast Asian demand. |
Methodological Framework
Coverage spans China, Germany, India, and the United States, with primary inputs from each region's production and consumption centers. Plant managers at oxidation facilities, procurement leads at textile finishing houses, distribution channel partners, and technical R&D directors contributed structured interviews. Secondary validation drew from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and MEE discharge permit records. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and grade-tier shifts. Segmentation dimensions include concentration level, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation against historical production and trade flows. Forecast inputs incorporated MEE permit approval timelines and REACH biocidal product regulation implementation phases.
The model assumes a particular technology adoption path for continuous-flow reactor engineering; alternative pathways for batch oxidation optimization would alter the outlook for pharmaceutical-grade cost structures. Forecasts reflect documented assumptions around feedstock price transmission and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Oxybenzone Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Copper Oxychloride Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Chromium Trioxide Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
5 Dinitroaniline Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Tin Chemicals Market
Chemicals
North America Construction Chemicals Market
Chemicals
Germany Methanol Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Global Phenoxyethanol Market