
 Potassium Formate Market | 2026-2036
Potassium Formate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Formate Market Analysis
Market Context
High-purity pharmaceutical-grade specifications are redrawing competitive boundaries in the potassium formate sector. BASF SE leverages its integrated formic acid value chain to sustain cost leadership across European supply corridors. Perstorp Holding AB anchors its position through specialized aqueous solution formulations tailored to North Sea drilling contractors. Eastman Chemical Company differentiates via controlled crystallization technology that commands premium positioning in metalworking applications.
Technical Definition and Segment Structure
Potassium formate is the potassium salt of formic acid, typically manufactured through neutralization of formic acid with potassium hydroxide or carbonate, yielding a hygroscopic crystalline solid or concentrated aqueous solution with density ranging from 1.57 to 1.60 g/cm³ at standard conditions. The compound functions primarily as a high-density, thermally stable, and biodegradable additive in drilling fluids, deicing formulations, and industrial heat transfer systems. Aqueous solution formats dominate volume flows due to their direct pumpability into oilfield operations, while solid powder grades capture concentrated margin pools from chemical manufacturing buyers requiring precise dosing control. Drilling fluids applications lead absolute demand but face cyclicality tied to exploration budgets, whereas deicing fluids represent the structurally fastest-expanding segment as airports and municipalities phase out urea and glycol blends under environmental compliance pressure.
Regulatory Frame and Outlook
EPA guidelines under the Clean Water Act and REACH substance restrictions are accelerating substitution away from potassium chloride and calcium chloride in drilling and deicing uses, directly expanding addressable demand for potassium formate as a compliant alternative. ECHA classification protocols and OSHA workplace exposure standards further shape product purity requirements and handling specifications across manufacturing and downstream application sites. Stakeholders must monitor evolving biodegradability testing protocols and carbon intensity disclosure rules, as these criteria increasingly determine qualification for public infrastructure contracts and oilfield service procurement frameworks.
Market Dynamics
Biodegradability mandates under EPA and REACH frameworks are systematically displacing chloride-based drilling fluids, compressing substitution timelines and rewiring procurement criteria across oilfield services.
Growth Catalysts
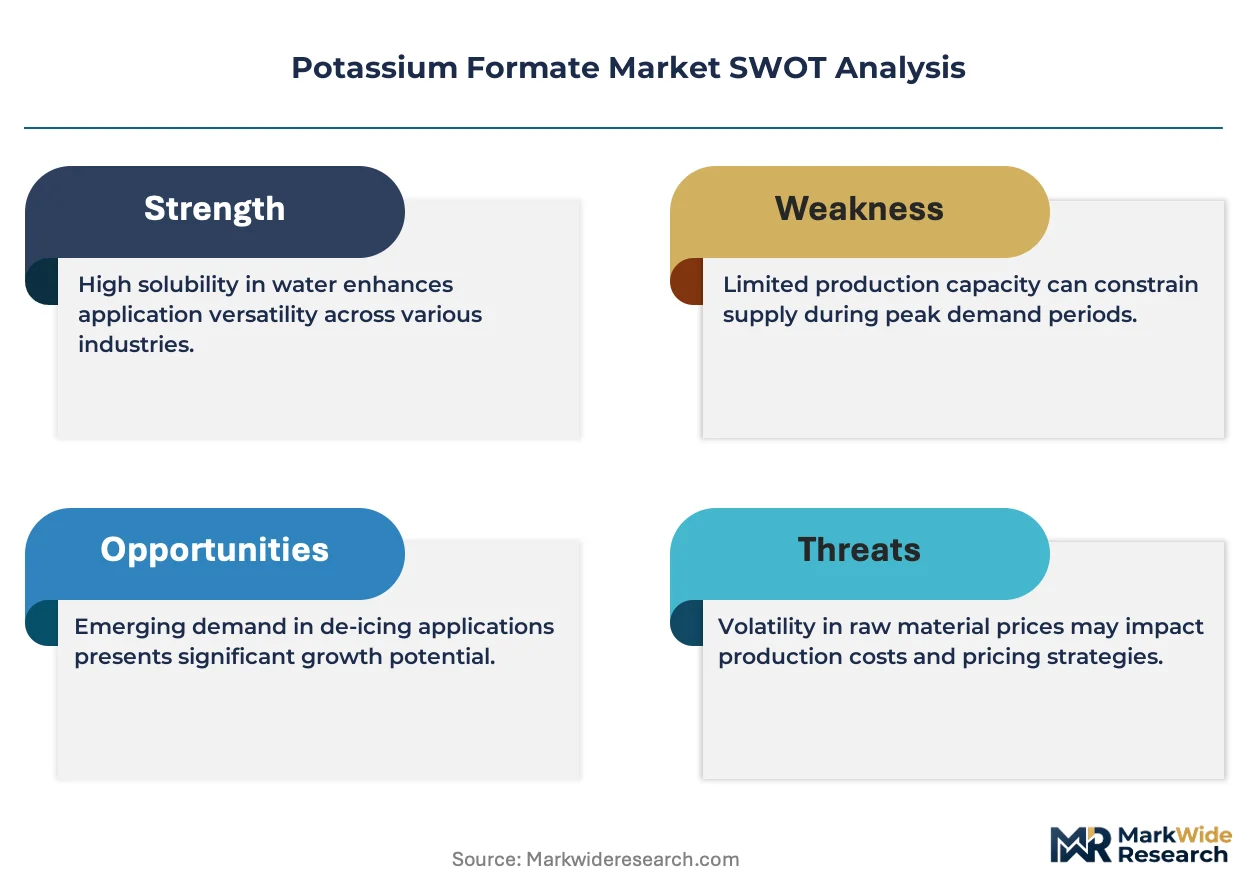
- REACH substance restrictions:European ECHA classification protocols are banning potassium chloride in offshore drilling, forcing North Sea contractors to reformulate with potassium formate aqueous solutions.
- Airport deicing compliance:FAA guidelines and state-level runoff regulations in the United States are phasing out urea-glycol blends, redirecting municipal procurement toward formate-based alternatives.
- Shale formation thermal stability requirements:High-temperature deep drilling in the Permian Basin and Sichuan Basin demands potassium formate's superior thermal decomposition threshold above 200°C.
Market Restraints
- Formic acid feedstock volatility:Potassium formate production costs track methanol oxidation routes and carbon monoxide pricing, exposing margins to petrochemical cycle swings.
- Chinese supply concentration:Bulk solid-grade manufacturing clusters in Shandong and Jiangsu provinces create single-source dependency risks for European and North American blenders.
- Calcium chloride residual substitution:Cost-sensitive road deicing authorities in Russia and Central Asia continue specifying calcium chloride blends despite environmental penalties.
Strategic Opportunities
- India infrastructure buildout:The country's PLI scheme for specialty chemicals and expanding airport capacity in Delhi and Mumbai create first-mover positioning for formate deicing tenders.
- Geothermal heat transfer fluids:Binary-cycle geothermal plants in Iceland and Kenya are testing potassium formate brines as corrosion-inhibited alternatives to glycol-water mixtures.
- Carbon intensity disclosure rules:EU CSRD reporting requirements and Scope 3 tracking are favoring bio-based formate production routes against synthetic chlorides in public procurement scoring.
Industry Challenges
- Pharmaceutical-grade purification capex:Achieving USP-grade crystallization specifications requires multi-stage recrystallization trains and cleanroom packaging lines that strain mid-scale producers.
- OSHA exposure limit compliance:Workplace airborne particulate monitoring and respiratory protection programs for solid powder handling add operational overhead to manufacturing sites.
- Legacy drilling fluid integration:Oilfield service engineers face compatibility testing burdens when blending potassium formate into existing barite-weighted mud systems without phase separation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Formate Market |
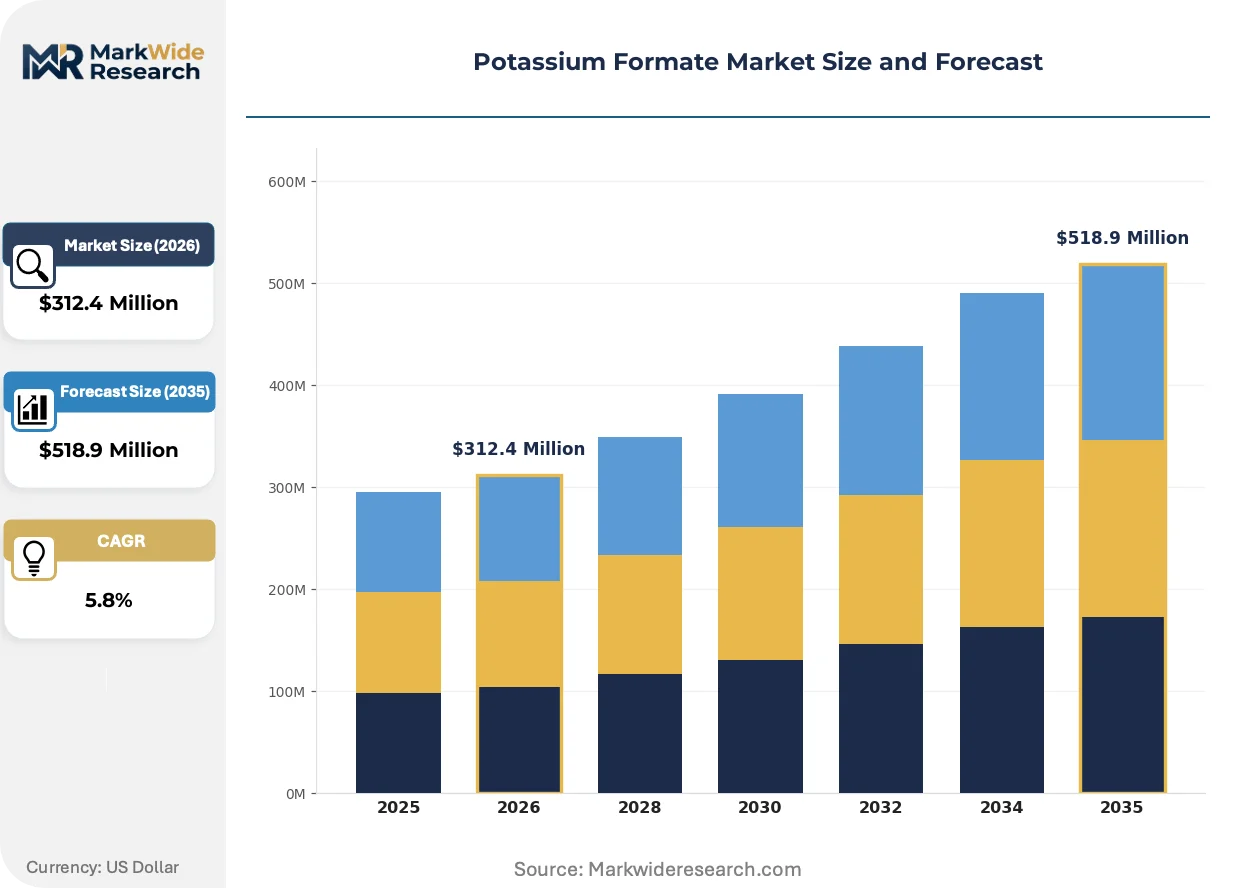
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
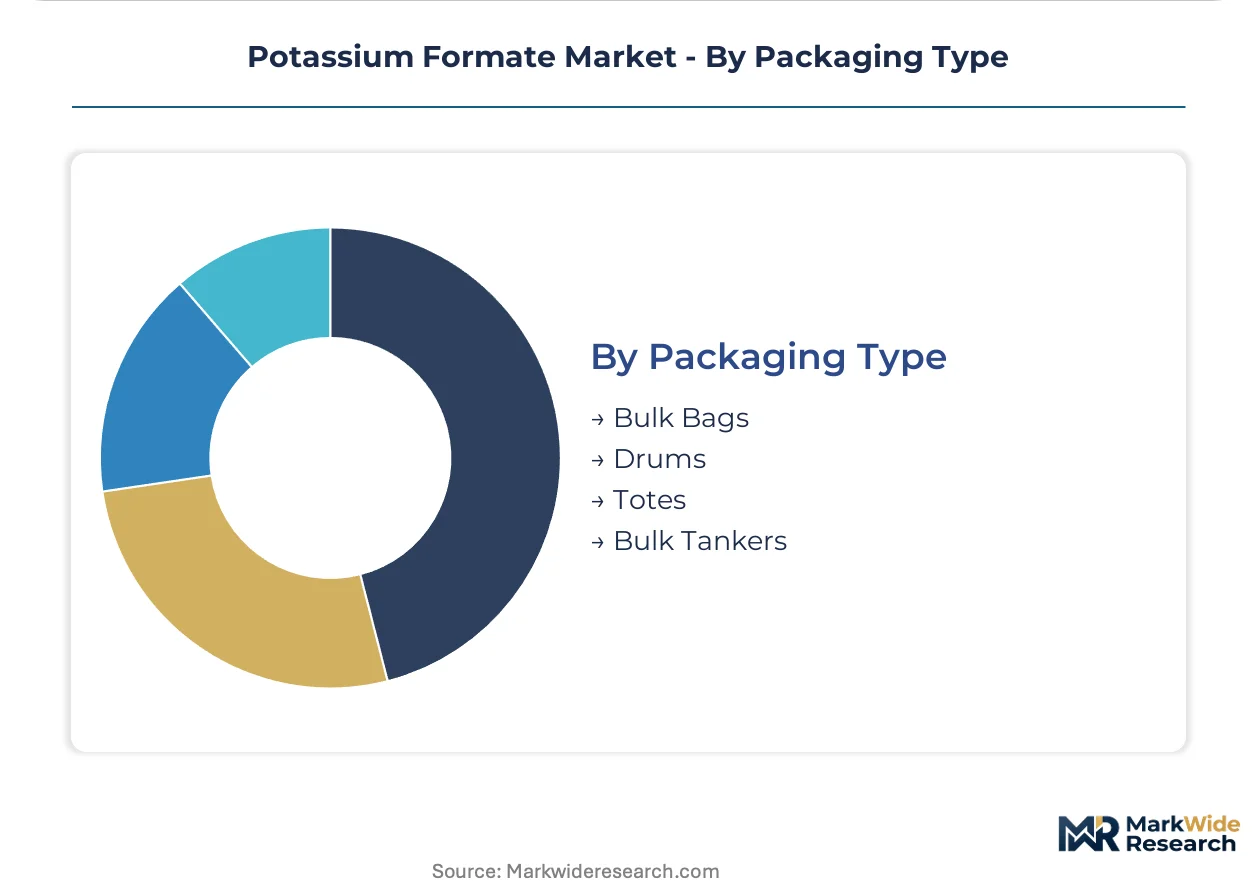
| Segmentation | Product Type: Solid Powder, Aqueous Solution, Crystalline, Granular Application: Deicing Fluids, Drilling Fluids, Corrosion Inhibitors, Heat Transfer Fluids End User Industry: Oilfield Services, Chemical Manufacturing, Metalworking, Refrigeration Systems Packaging Type: Bulk Bags, Drums, Totes, Bulk Tankers |
| Companies Covered | BASF SE, ADDCON GmbH, Perstorp Holding AB, Eastman Chemical Company, Honeywell International, Clariant, Tetra Technologies Inc, Hawkins, Thermo Fisher Scientific Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Formate Market Emerging Trajectories
Formate salt chemistry is crossing into adjacent industrial thermal management applications while regulatory disclosure requirements intensify supply chain traceability demands.
Continuous crystallization technology is bifurcating the solid-grade segment between pharmaceutical-specification producers and technical-grade commodity suppliers. European chemical manufacturers are deploying controlled cooling crystallizers to achieve narrow particle size distributions for parenteral drug applications. This equipment differentiation is compressing margin pools for undifferentiated powder grades while enabling premium positioning for cGMP-certified output.
EPA effluent limitation guidelines under the Clean Water Act are tightening chloride discharge caps for offshore drilling platforms in the Gulf of Mexico. Operators must submit environmental compliance plans specifying biodegradable alternatives before permit renewal. Deepwater contractors are responding by pre-qualifying potassium formate suppliers under master service agreements that lock in multi-year volume commitments.
Specification-driven procurement is consolidating buyer power among integrated oilfield services companies. National oil companies in Saudi Arabia and Brazil are unbundling chemical supply from drilling contracts, creating direct tendering relationships with formate manufacturers. This channel restructuring is visible most acutely in pre-salt basin developments where NOCs specify exact brine density and crystallization point parameters in technical bids.
Potassium Formate Market Segmentation
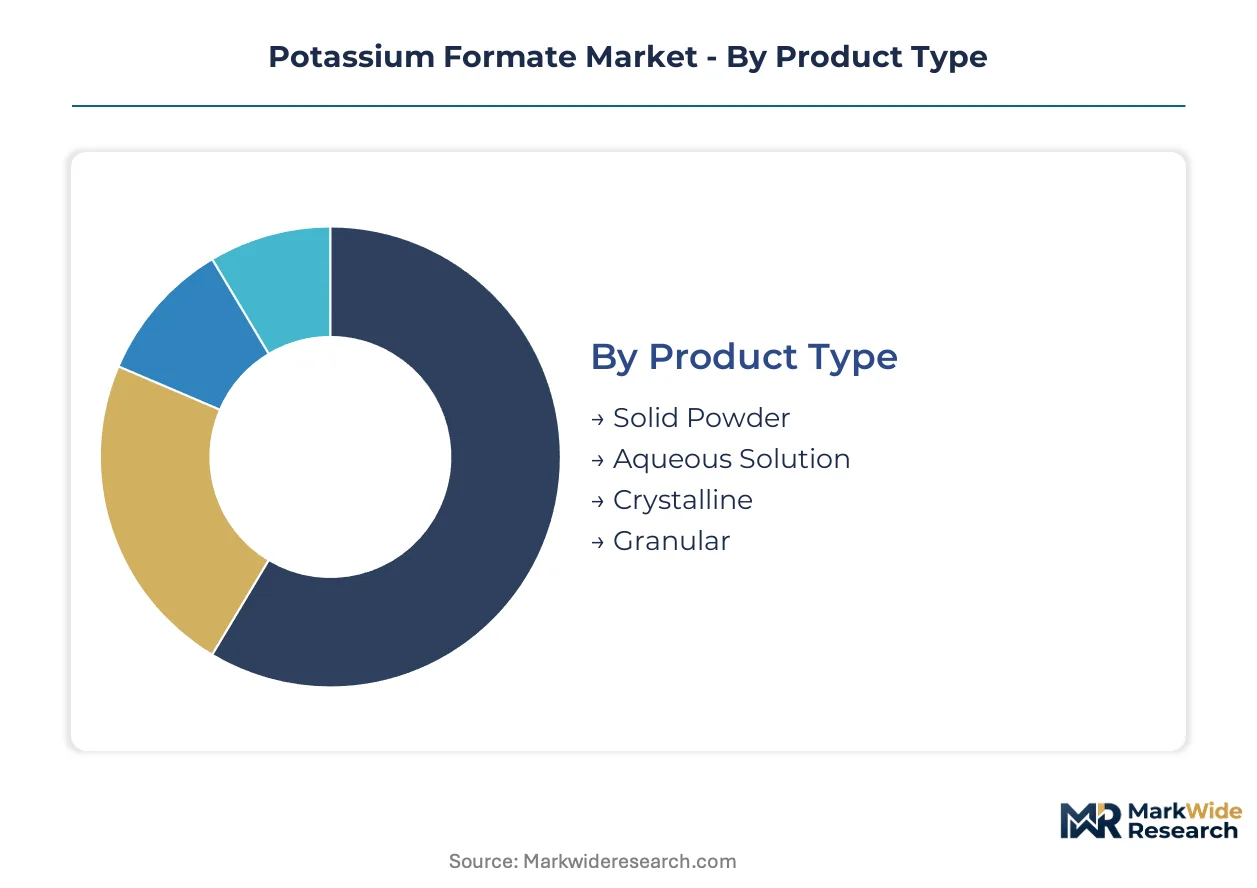
Segmentation in potassium formate markets tracks divergent margin pools across physical forms and application specifications. Product format and end-use purity requirements create distinct competitive arenas with different capital intensity and customer switching costs.
Product Type:
Margin concentration tilts toward formats enabling precise dosing control in high-specification applications.
- Aqueous Solution:Concentrated liquid brine with density of 1.57-1.60 g/cm³ eliminates dissolution steps at wellsite operations. North Sea drilling contractors specify this format under REACH-mandated fluid reformulations, securing multi-year offtake agreements with density-certified suppliers.
- Solid Powder:Hygroscopic crystalline solid demands sealed packaging and climate-controlled logistics but commands premium positioning in chemical manufacturing and pharmaceutical synthesis where precise stoichiometric dosing is required.
- Crystalline:High-purity recrystallized grades meet USP specifications for parenteral drug applications.
- Granular:Free-flowing particle form suits automated bulk handling systems in deicing blend plants.
Aqueous solution holds installed capacity. Crystalline grades are rotating up the share rankings.
Application:
Volume flows concentrate in oilfield services while environmental compliance redirects procurement toward deicing uses.
- Deicing Fluids:Runway and taxiway formulations exploit potassium formate's biodegradability and lower aquatic toxicity versus urea-glycol blends. FAA guidelines and state-level runoff regulations in the United States are accelerating airport authority tenders for formate-based alternatives.
- Drilling Fluids:High-density completion and workover brines leverage thermal stability above 200°C for deep shale formations in the Permian Basin and Sichuan Basin. EPA effluent limitation guidelines under the Clean Water Act are tightening chloride discharge caps, forcing Gulf of Mexico operators to pre-qualify formate suppliers.
- Corrosion Inhibitors:Metalworking coolants and closed-loop heating systems utilize formate salts for ferrous metal passivation.
- Heat Transfer Fluids:Binary-cycle geothermal plants in Iceland and Kenya are piloting formate brines as alternatives to glycol-water mixtures.
Drilling fluids holds installed capacity. Deicing fluids are rotating up the share rankings.
End User Industry:
Customer concentration patterns split between cyclical exploration budgets and steady industrial process demand.
- Oilfield Services:Integrated drilling contractors and national oil companies in Saudi Arabia and Brazil specify exact brine density and crystallization parameters in unbundled chemical tenders for pre-salt developments.
- Chemical Manufacturing:Formic acid derivative producers and pharmaceutical intermediates manufacturers source pharmaceutical-grade solid grades with narrow particle size distributions.
- Metalworking:Precision machining operations deploy formate-based coolants for corrosion inhibition in high-speed cutting applications.
- Refrigeration Systems:Industrial cold storage facilities test formate brines as secondary coolant alternatives in ammonia-based systems.
Oilfield services holds installed capacity. Chemical manufacturing is rotating up the share rankings.
Packaging Type:
Logistics configuration determines working capital requirements and customer intimacy levels across the value chain.
- Bulk Tankers:Dedicated tank truck and ISO tank container deliveries serve high-volume oilfield services operators with direct-to-wellsite logistics, minimizing intermediate handling and contamination risk for aqueous solution grades.
- Bulk Bags:One-ton flexible intermediate bulk containers balance handling efficiency with moisture protection for solid powder shipments to chemical manufacturing and deicing blend plants.
- Drums:200-liter steel or plastic drums serve mid-scale metalworking shops and maintenance operations with limited storage infrastructure.
- Totes:Intermediate bulk containers of 1000-1250 liters bridge bulk and drum formats for regional distributors serving fragmented end-use bases.
Bulk tankers holds installed capacity. Bulk bags are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Shandong and Jiangsu provinces supply aqueous solution grades to North Sea drilling contractors facing REACH-mandated reformulations. Consumption growth concentrates in the United States, China, Germany, Saudi Arabia, and Brazil as regulatory pressure and infrastructure expansion reshape procurement patterns.
United States
Permian Basin deep drilling and Gulf of Mexico offshore operations drive demand for thermally stable brines. EPA effluent limitation guidelines under the Clean Water Act tighten chloride discharge caps, forcing operators to pre-qualify formate suppliers before permit renewal. Houston-area oilfield services companies stock concentrated aqueous solutions for direct-to-wellsite deployment.
China
Sichuan Basin shale formations and expanding airport capacity in Beijing and Chengdu generate dual demand from drilling and deicing applications. The Ministry of Ecology and Environment enforces dual carbon goals that favor biodegradable alternatives in public infrastructure tenders. Shandong province chemical manufacturers export bulk solid grades to European blenders under long-term supply contracts.
Germany
North Sea drilling contractors source REACH-compliant aqueous solutions for offshore platform operations. ECHA substance restrictions explicitly ban potassium chloride in marine environments, compressing substitution timelines. BASF SE leverages integrated formic acid production at Ludwigshafen to supply density-certified brines under multi-year offtake agreements.
Saudi Arabia
Pre-salt basin developments and unbundled chemical procurement from national oil companies create direct tendering relationships with formate manufacturers. The Saudi Food and Drug Authority and national environmental standards shape product purity requirements for industrial applications. Eastern Province drilling contractors specify exact brine density parameters in technical bids for deep gas exploration.
Brazil
Pre-salt carbonate reservoirs and airport modernization in São Paulo and Rio de Janeiro expand addressable demand across oilfield and deicing segments. ANVISA pharmaceutical regulations and national oil company unbundling policies reshape supplier qualification pathways. Santos Basin deepwater projects require high-density completion brines with crystallization points calibrated for tropical seabed conditions.
Potassium Formate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the potassium formate sector. Integrated petrochemical groups with captive formic acid supply dominate cost-efficient aqueous solution production, while specialized chemical manufacturers command premium positioning through pharmaceutical-grade crystallization capabilities. The competitive arena splits between scale-driven commodity suppliers and specification-focused niche operators. Consolidation pressure intensifies as oilfield services companies reduce approved vendor lists under master service agreement frameworks.
Among integrated chemical conglomerates, BASF SE and Eastman Chemical Company exemplify the backward-integrated archetype with in-house formic acid production. Perstorp Holding AB occupies a position within the specialized aqueous solution tier, serving North Sea drilling contractors with density-certified formulations. These three entities anchor the competitive structure by representing distinct strategic postures: petrochemical integration, controlled crystallization technology, and application-specific formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| ADDCON GmbH |
| Perstorp Holding AB |
| Eastman Chemical Company |
| Honeywell International |
| Clariant |
| Tetra Technologies Inc |
| Hawkins |
| Thermo Fisher Scientific Inc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with density-certified suppliers lock in supply access for North Sea drilling contractors while anchoring price visibility against methanol oxidation feedstock swings. These contracts insulate buyers from spot volatility in formic acid markets and secure dedicated tanker capacity for aqueous solution grades.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European supply corridors, separating pharmaceutical-grade crystalline output from technical aqueous solutions. Three-tier pricing structure across premium, standard, and economy levels reflects USP certification status, particle size distribution precision, and bulk volume commitments. Cost compression in solid powder grades is intensifying because Chinese manufacturers are expanding crystallization capacity in Shandong province. Road deicing authorities in Russia and Central Asia demonstrate highest price sensitivity, while oilfield services companies in the Permian Basin show lowest sensitivity due to operational criticality.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for European blenders sourcing solid grades from Jiangsu province manufacturers. Production gravity centers on China, Germany, and the United States, with formic acid supply drawing from methanol oxidation routes and carbon monoxide feedstocks. Single-source vulnerability risk concentrates in Shandong province bulk solid-grade clusters. Distribution runs through dedicated tank truck networks for oilfield services, bulk bag shipments to chemical manufacturers, and drum formats for fragmented metalworking shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of USP-grade crystallization capabilities and cGMP-certified packaging infrastructure constrains supply expansion in pharmaceutical-grade tiers. This capability gap separates premium positioning from commodity competition.
For Market Incumbents: Fortify backward integration into captive formic acid production to neutralize methanol cycle exposure and protect margin structures. Expand density-certified aqueous solution capacity in Ludwigshafen or Houston corridors to capture REACH-driven and EPA-driven substitution demand. Pre-empt emerging entrant threats by locking multi-year master service agreements with integrated oilfield services companies before national oil company unbundling accelerates.
For New Entrants and Emerging Players: Anchor in India's PLI-backed specialty chemicals infrastructure and Delhi-Mumbai airport deicing tenders where incumbent presence remains thin. Target geothermal heat transfer fluid pilots in Iceland and Kenya as specification-free entry points before oilfield qualification barriers harden. Pursue toll manufacturing arrangements with Shandong province producers to bypass crystallization capex requirements while building customer relationships.
For Investors and Strategic Acquirers: Specialized aqueous solution formulators with North Sea drilling contractor relationships and established ECHA compliance documentation represent priority acquisition targets. Long-term viability hinges on positioning upstream of carbon intensity disclosure rules and Scope 3 tracking requirements. Monitor EPA effluent limitation guideline enforcement velocity in Gulf of Mexico permit renewals as inflection indicator for formate substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formic Acid | BASF SE's Ludwigshafen complex demonstrates margin protection against methanol oxidation cost swings. |
| Pharmaceutical-Grade Crystallization Capacity | USP-certified output commands premium positioning in parenteral drug applications with limited supplier base. |
| Long-term Supply Agreement with NOCs | Saudi Aramco and Petrobras unbundling creates direct tendering relationships bypassing oilfield services intermediaries. |
| Geographic Expansion to India | PLI scheme subsidies and airport infrastructure buildout in Delhi reduce customer acquisition cost for deicing tenders. |
| Green Manufacturing Transition | Bio-based formate production routes score favorably under EU CSRD carbon intensity disclosure requirements. |
Methodological Framework
The analysis maps drilling fluid grades, deicing formulations, pharmaceutical specifications, and heat transfer brines, each validated through oilfield services procurement directors, chemical manufacturing plant managers, airport authority maintenance heads, and geothermal plant engineers. Primary interview data triangulates against customs and trade flow databases, ECHA substance restriction filings, SEC 10-K chemical segment disclosures, and FAA guideline documentation. Bottom-up capacity and consumption estimates cross-check with top-down market sizing across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs throughout the forecast period. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions. CAGRs derive from regression analysis of historical substitution patterns and regulatory compliance timelines. Forecast inputs include shale formation thermal stability requirements and airport runway capacity expansion pipelines.
Material uncertainties — formic acid feedstock volatility, REACH substance restriction enforcement velocity, and Chinese supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory substitution timelines and oilfield exploration budget cyclicality. Practitioners should keep alternative scenarios live as biodegradability testing protocols and carbon intensity disclosure rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Global Furfural Solvent Market
Solvents
Isopropylamine Market
Solvents
Citrus Solvents Market
Solvents
Methyl Diethanolamine Market
Solvents
Global Solvent Dyes Market
Solvents
Hydrophobic Solvents Market
Solvents
6-Xylenol Market
Solvents
2-Phenylethanol Market
Solvents
Methyl Undecylenate Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Aromatic Solvents Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Benzene and Its Derivatives Market
Solvents
Fluorinated Solvents Market
Solvents
Diethanolamine (DEA) Market