
 4-Methyl-2-Pentanone Market | 2026-2036
4-Methyl-2-Pentanone Market Size, Share, and Industry Trends Forecast 2026-2036
4-Methyl-2-Pentanone Market Analytics
Buyer concentration in the automotive OEM coatings sector is realigning procurement volumes toward fewer, larger formulation houses with integrated solvent management programs. Shell leverages its integrated refinery-solvent chain to secure feedstock cost advantages across European and Asian supply corridors. Eastman Chemical Company sustains technical leadership in high-purity grades for electronics cleaning applications through dedicated R&D facilities in North America. Mitsubishi Chemical Corporation anchors its position in the Japanese and Southeast Asian markets through long-term supply contracts with domestic adhesive manufacturers.
4-Methyl-2-pentanone, commonly designated methyl isobutyl ketone or MIBK, is a medium-boiling ketone solvent with a specific gravity of 0.80 and a distillation range of 114–117°C, synthesized primarily through acetone condensation followed by hydrogenation and dehydration. The compound functions as an active solvent in nitrocellulose lacquers, acrylic coatings, and vinyl resin systems where moderate evaporation rates enable controlled film formation. Solvent-grade product lines dominate volume throughput due to entrenched demand from industrial coatings and adhesive formulators, while intermediate applications for rubber antioxidants and pharmaceutical precursors command stronger margin profiles. Liquid form factors occupy the majority of commercial transactions, though specialty emulsion variants are gaining traction in waterborne coating systems where phase compatibility challenges persist.
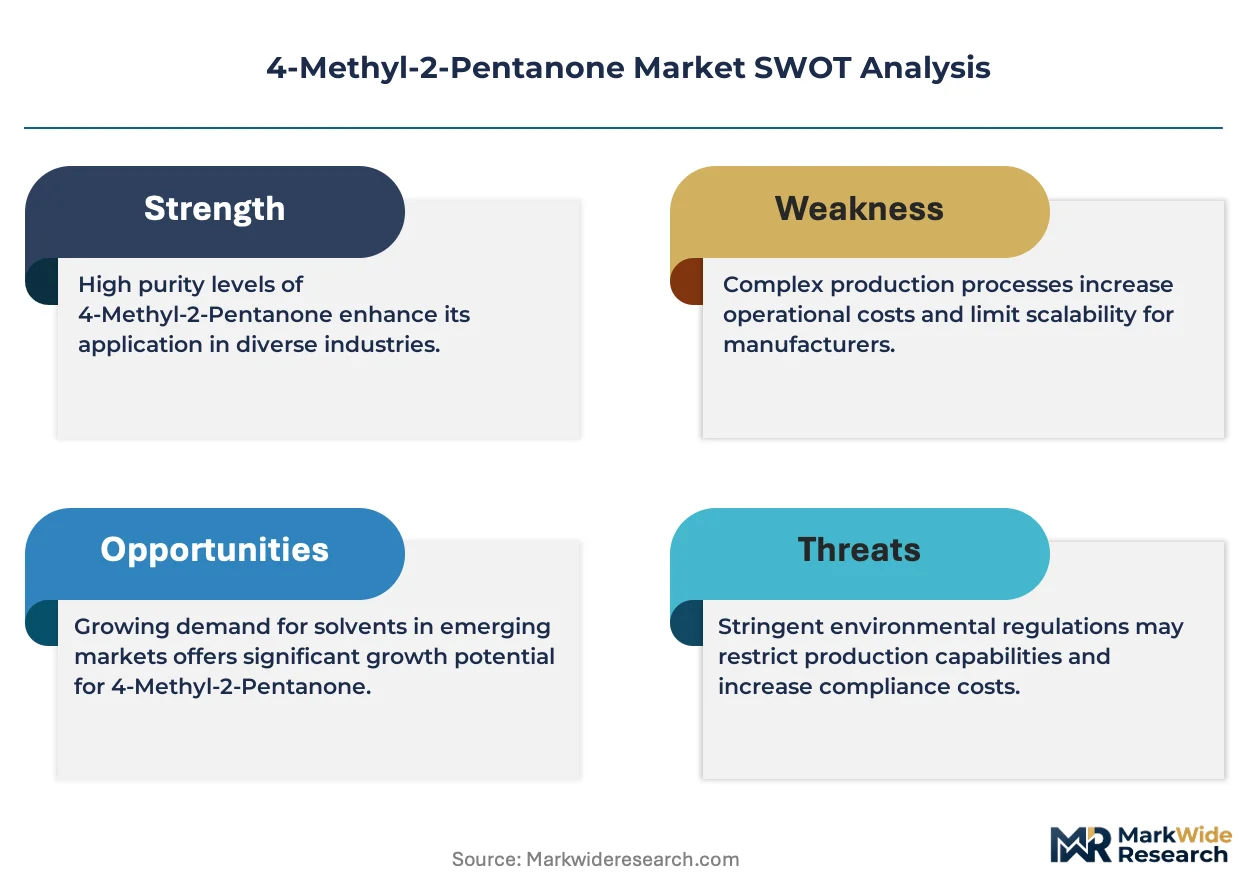
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain MIBK emissions from coating operations, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for continued market access. OSHA permissible exposure limits and analogous workplace safety frameworks in Japan and South Korea shape industrial handling protocols and personal protective equipment specifications. Stakeholders must monitor regulatory harmonization between VOC control mandates and circular economy solvent recovery incentives to anticipate where formulation substitution pressures will intensify versus where premium solvent grades retain structural demand.
Market Dynamics
Formulation chemistry across industrial coatings is pivoting toward solvent systems that balance performance with tightening volatile organic compound thresholds, compressing demand for legacy ketone grades while elevating specification requirements for high-purity variants.
Growth Catalysts
- Automotive refinishing concentration:OEM coating houses in Germany, the United States, and China are consolidating procurement around integrated solvent management programs that favor reliable, large-volume MIBK supply contracts.
- REACH registration completion:ECHA-mandated toxicological dossiers for continued European market access have filtered out marginal suppliers, stabilizing margins for compliant producers.
- Electronics cleaning grade expansion:Semiconductor fabrication facilities in Japan and South Korea are specifying ultra-high-purity ketone solvents for precision cleaning of advanced node wafers.
Market Restraints
- Acetone feedstock volatility:MIBK synthesis depends on acetone condensation economics, and propylene-derived acetone pricing fluctuations transmit directly to ketone solvent cost structures.
- Waterborne formulation substitution:Architectural coating manufacturers are accelerating methyl isobutyl ketone displacement with glycol ether and ester-based coalescents in low-VOC compliance formulations.
- EPA NESHAP emission constraints:National Emission Standards for Hazardous Air Pollutants impose costly abatement equipment requirements on coating operations using MIBK in high-throughput spray applications.
Strategic Opportunities
- Indian industrial coatings penetration:BIS certification alignment and domestic production scale-up create entry pathways for solvent-grade supply into architectural and automotive coating formulators.
- Circular economy solvent recovery incentives:EU Green Deal funding streams and extended producer responsibility frameworks reward closed-loop ketone recycling investments with preferential regulatory treatment.
- Pharmaceutical intermediate specification:cGMP-grade methyl isobutyl ketone for active pharmaceutical ingredient synthesis commands margin premiums three to four times standard industrial solvent pricing.
Industry Challenges
- Process safety engineering talent scarcity:Ketone hydrogenation and dehydration operations require specialized chemical process safety expertise that competes with broader petrochemical sector hiring.
- Multi-jurisdiction certification timelines:Simultaneous EPA, ECHA, and NMPA registration dossier preparation stretches regulatory affairs capacity and delays market entry by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Methyl-2-Pentanone Market |
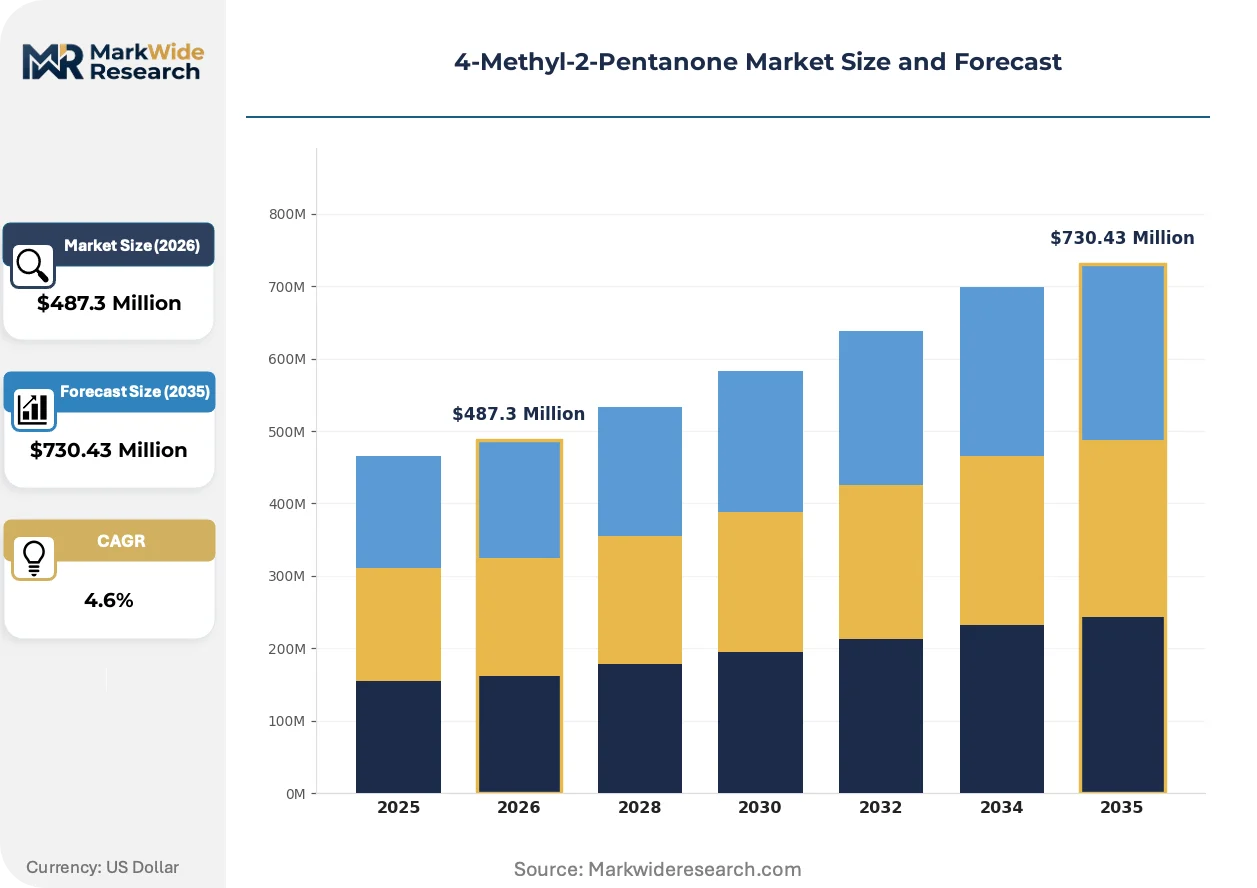
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Additive, Chemical Reagent End Use: Paints, Coatings, Adhesives, Personal Care Form: Liquid, Powder, Emulsion, Aerosol Distribution Channel: Online, Retail, Direct, Wholesalers |
| Companies Covered | Kanto Kagaku Co., Ltd., LCY Chemical Corp., Shell, Eastman Chemical Company, Mitsubishi Chemical Corporation, Dongsung Chemical, Credit Chemical Co., Ltd., The Dow Chemical Company, MicroCare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Methyl-2-Pentanone Market Evolving Landscape
Reactive solvent technology and regulatory compliance automation are compressing traditional formulation development cycles while elevating the technical threshold for market participation.
Membrane separation technology for ketone recovery and purification is expanding into coating operation waste streams as a cost-recovery mechanism. Large automotive refinishing facilities in Stuttgart and Detroit are piloting closed-loop systems that return recovered MIBK to formulation tanks. This hardware deployment is expanding into new service revenue models for solvent suppliers.
REACH authorization sunset dates for legacy solvent substances are forcing coating houses to accelerate substitution testing protocols. ECHA's candidate list expansion is compressing the approved substance portfolio for decorative paints. German architectural coating producers are responding with accelerated R&D partnerships to qualify replacement chemistries before 2027 deadlines.
Specification-driven procurement now dominates solvent purchasing for electronics-grade applications. Korean semiconductor fabricators are unbundling solvent supply from equipment maintenance contracts and awarding multi-year purity-guaranteed agreements directly to chemical producers. This pattern is most visible in the Gyeonggi-do cluster where Samsung and SK Hynix operations anchor demand.
4-Methyl-2-Pentanone Market Segmentation
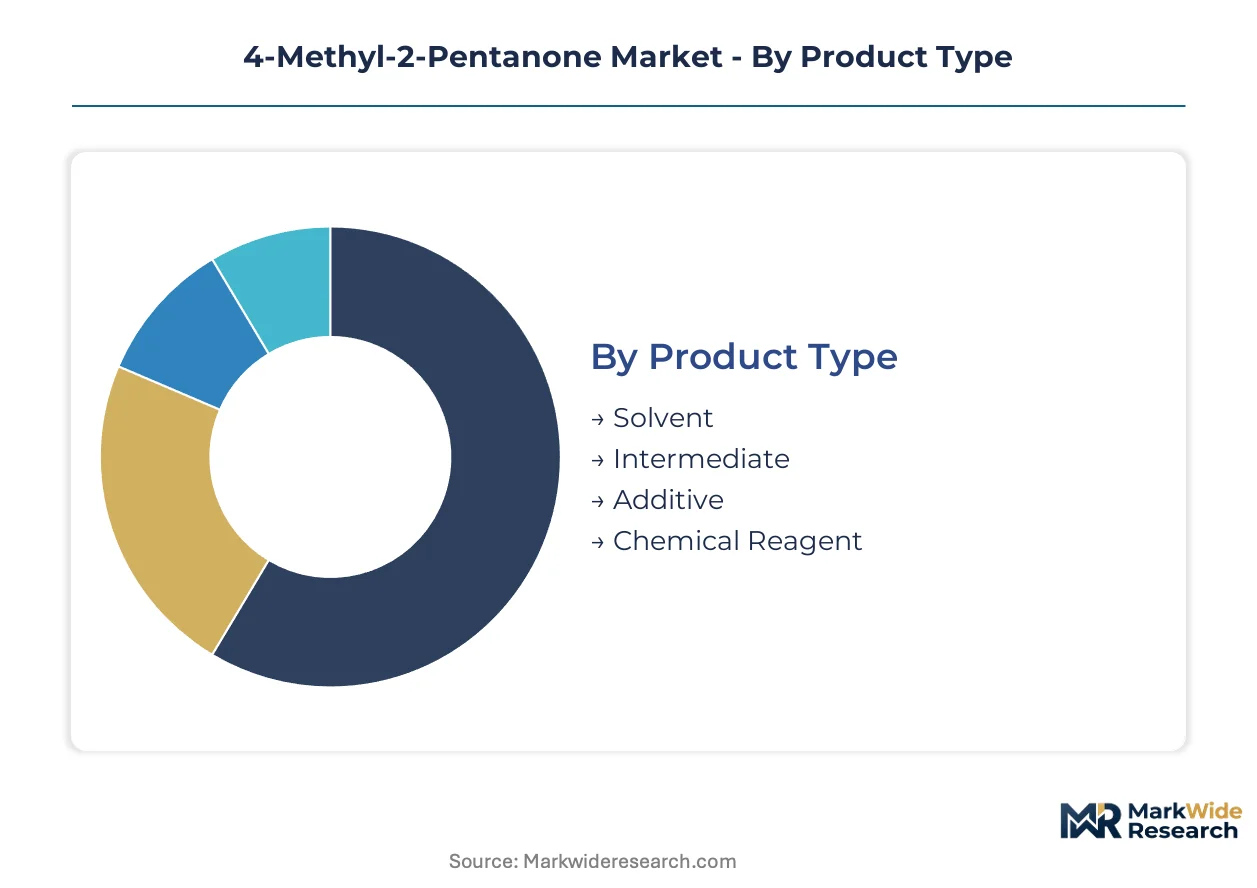
Segmentation in the 4-methyl-2-pentanone market reveals how procurement patterns diverge between high-volume industrial buyers and specification-driven specialty purchasers. Understanding these divides clarifies where margin compression versus premium pricing power concentrates across the value chain.
Product Type:
Buyers select product grades based on purity thresholds and downstream regulatory compliance requirements rather than unit cost alone.
- Solvent:Medium-boiling ketone with specific gravity of 0.80 and distillation range of 114–117°C, serving nitrocellulose lacquers and acrylic coating systems. Demand clusters with automotive refinishing operations in Germany, the United States, and China where controlled evaporation rates enable uniform film formation.
- Intermediate:Feedstock for rubber antioxidants and pharmaceutical precursors requiring cGMP certification for active pharmaceutical ingredient synthesis. Specifications from semiconductor fabricators in Japan and South Korea are elevating purity requirements beyond standard industrial grades.
- Additive:Functional component enhancing flow and leveling properties in coating formulations.
- Chemical Reagent:Laboratory and analytical grade for research and quality control applications.
Volume sits with Solvent; growth tilts toward Intermediate.
End Use:
Application selection tracks directly with volatile organic compound regulatory thresholds and performance specifications in each sector.
- Paints:Architectural and decorative coating systems where moderate evaporation rates support brush and roller application. EPA NESHAP emission constraints are forcing coating houses toward recovery systems or substitution testing.
- Coatings:Industrial protective and automotive OEM finishes demanding batch-to-batch consistency for automated spray lines. REACH authorization sunset dates for legacy solvents are compressing approved substance portfolios for German producers.
- Adhesives:Solvent-borne systems for construction and packaging assembly.
- Personal Care:Nail polish removers and cosmetic formulations requiring low-odor, cosmetic-grade certification.
Coatings commands the largest share; Personal Care is expanding most quickly on clean-label formulation trends.
Form:
Physical state selection depends on handling infrastructure, storage constraints, and compatibility with waterborne formulation trends.
- Liquid:Standard bulk delivery in tank cars and drums for high-throughput coating operations. Liquid form factors occupy the majority of commercial transactions due to entrenched demand from industrial coatings and adhesive formulators.
- Emulsion:Water-dispersible variants gaining traction where phase compatibility challenges persist in low-VOC waterborne systems. ECHA candidate list expansion is accelerating qualification of emulsion-based alternatives before authorization deadlines.
- Powder:Solid-state handling for specialized chemical synthesis and powder coating applications.
- Aerosol:Consumer and professional spray-packaged products for touch-up and field application.
Liquid dominates throughput; Emulsion is gaining share fastest on regulatory substitution pressure.
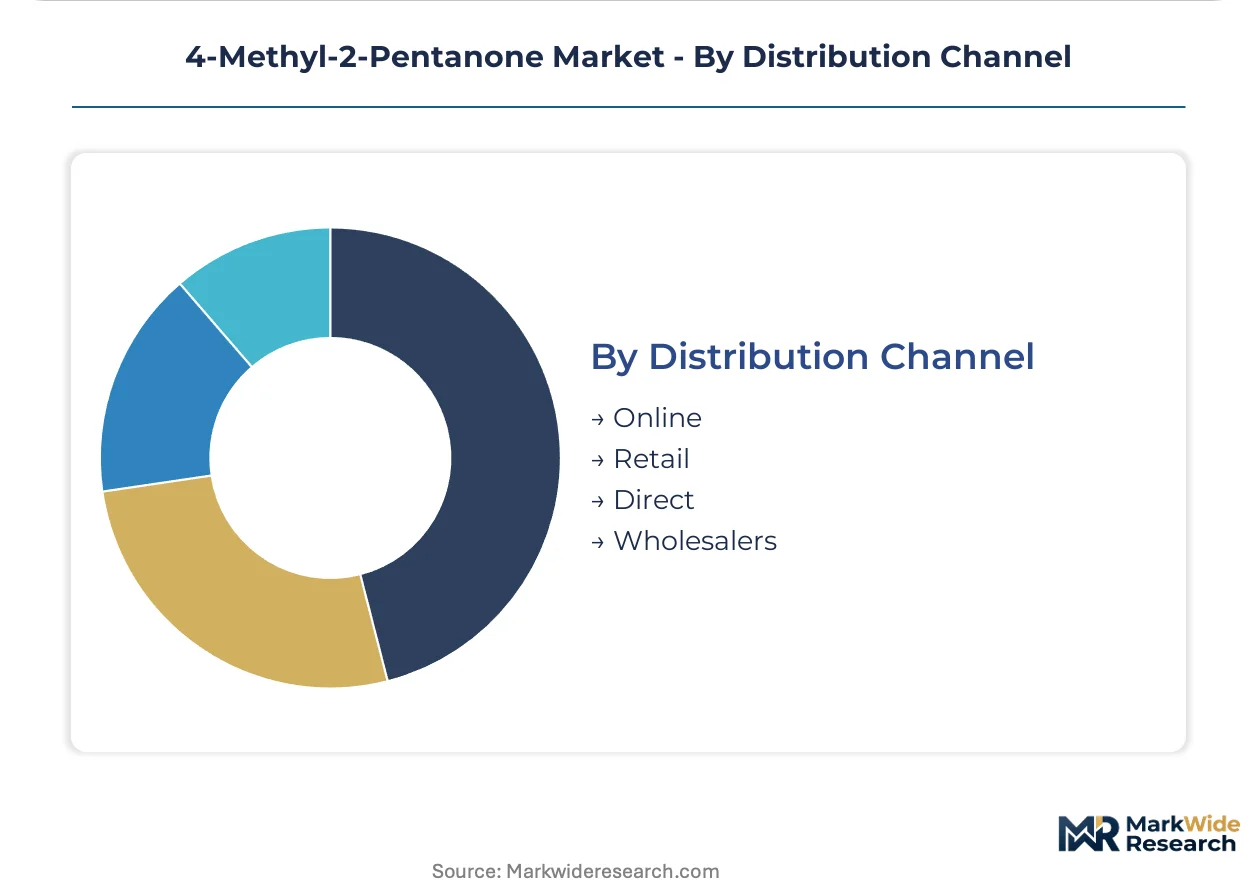
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and inventory carrying cost trade-offs.
- Direct:Long-term supply contracts between ketone producers and large formulation houses with integrated solvent management programs. Shell and Eastman leverage direct relationships to secure feedstock cost advantages and technical collaboration.
- Wholesalers:Regional distributors serving mid-tier coating manufacturers and smaller adhesive formulators requiring less-than-tank-car quantities. Mitsubishi Chemical Corporation anchors Japanese and Southeast Asian markets through wholesaler networks.
- Online:E-procurement platforms for standard grades and spot purchases.
- Retail:Packaged goods for personal care and small-scale professional use.
Direct channels capture the highest volume; Online is climbing the fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acetone condensation economics anchor production geography to propylene refining corridors in East Asia, Western Europe, and the US Gulf Coast. Demand concentrates where automotive OEM coating houses and electronics fabricators cluster around specialized solvent supply chains.
China
Acetone-to-MIBK capacity expansion in Shandong and Jiangsu provinces serves domestic automotive refinishing and architectural coating formulators. NMPA chemical substance registration and evolving GB standards for workplace chemical exposure shape compliance investments. The Yangtze River Delta cluster around Shanghai anchors semiconductor-grade solvent demand from wafer fabrication facilities.
Germany
Automotive OEM coating houses in Stuttgart and Munich drive specification-grade solvent procurement for automated spray line operations. REACH authorization timelines and ECHA candidate list expansions compress approved substance portfolios for decorative paint producers. The North Rhine-Westphalia chemical corridor hosts integrated ketone production serving continental coating formulators.
United States
EPA NESHAP emission constraints on coating operations accelerate solvent recovery system deployment across automotive refinishing facilities. OSHA permissible exposure limits shape industrial handling protocols and personal protective equipment specifications. The US Gulf Coast petrochemical corridor supplies acetone feedstock to domestic MIBK producers serving Great Lakes manufacturing clusters.
Japan
Semiconductor fabricators in the Kanto and Kyushu regions specify ultra-high-purity ketone solvents for advanced node wafer cleaning applications. METI chemical management frameworks and JIS standards govern industrial solvent quality certification. The Osaka-Kobe industrial zone anchors long-term supply contracts between ketone producers and domestic adhesive manufacturers.
South Korea
Electronics-grade solvent procurement from Samsung and SK Hynix operations in Gyeonggi-do drives multi-year purity-guaranteed supply agreements. MFDS chemical substance regulations and workplace safety frameworks align with semiconductor fabrication cleanroom requirements. The Busan-Ulsan petrochemical complex supports downstream ketone purification for export-oriented electronics supply chains.
4-Methyl-2-Pentanone Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade specialization and circular economy recovery services. The market structure reflects moderate consolidation around integrated petrochemical players with captive acetone supply. Three archetypes dominate: refinery-integrated majors, regional chemical specialists, and purity-focused electronics suppliers. Capacity rationalization and strategic partnerships represent the primary competitive vectors as regulatory compliance costs filter marginal participants.
Within the integrated petrochemical tier, Shell and Eastman Chemical Company exemplify feedstock-backed supply security, while Mitsubishi Chemical Corporation anchors Japanese and Southeast Asian market presence through long-term distributor relationships. LCY Chemical Corp. and Kanto Kagaku Co., Ltd. represent regional specialists with proximity advantages in Taiwan and Japan respectively. Dongsung Chemical occupies a position among Korean producers serving domestic electronics fabrication demand. The Dow Chemical Company and Credit Chemical Co., Ltd. sit within the multinational chemical portfolio tier with cross-regional solvent distribution capabilities.
| Leading Market Players |
|---|
| Kanto Kagaku Co., Ltd. |
| LCY Chemical Corp. |
| Shell |
| Eastman Chemical Company |
| Mitsubishi Chemical Corporation |
| Dongsung Chemical |
| Credit Chemical Co., Ltd. |
| The Dow Chemical Company |
| MicroCare Corporation |
| Others |
Value Network & Pricing Analysis
Process safety engineering talent scarcity in the US Gulf Coast and North Rhine-Westphalia chemical corridors widens labor-cost differentials between standard solvent-grade and cGMP-certified intermediate pricing tiers. Acetone feedstock volatility transmits directly through ketone solvent cost structures, compressing margins for non-integrated producers while captive refinery operations maintain pricing flexibility across European and Asian supply corridors.
Pricing Analysis
Volume concentrates with solvent-grade industrial coatings supply where commodity dynamics dominate, while intermediate applications for rubber antioxidants and pharmaceutical precursors capture margin premiums three to four times higher. Three-tier pricing structure across electronics-grade, industrial-grade, and solvent-grade levels tracks purity thresholds and certification requirements rather than unit cost alone. Pricing pressure stems from waterborne formulation substitution in architectural coatings as glycol ether coalescents displace ketone solvents for EPA NESHAP compliance. Automotive OEM coating houses show least price sensitivity due to integrated solvent management programs and long-term contract structures, while mid-tier adhesive formulators face acute cost compression.
Supply Chain Analysis
Direct-to-formulator channels handle high-volume procurement from automotive refinishing clusters in Germany, China, and the United States, while wholesaler networks serve fragmented adhesive manufacturers across Japan and Southeast Asia. Production gravity centers on the US Gulf Coast, North Rhine-Westphalia, and Shandong-Jiangsu provinces where propylene refining corridors feed acetone condensation economics. MIBK synthesis draws from acetone, hydrogen feedstock, and specialized hydrogenation catalysts as primary inputs. Single-source vulnerability concentrates in acetone supply where propylene derivative pricing fluctuates with olefin market cycles. Distribution runs through integrated petrochemical majors with captive feedstock, regional chemical specialists with proximity advantages, and purity-focused electronics suppliers serving semiconductor fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over acetone feedstock and cGMP certification capabilities determines margin sustainability. Players are pursuing backward integration into propylene refining and hydrogenation capacity as the decisive upstream lever.
For Market Incumbents: Extend long-term supply contracts with automotive OEM coating houses to lock in volume commitments before REACH authorization deadlines filter approved substances. Deepen captive acetone supply through refinery integration or strategic offtake agreements with propylene producers to neutralize feedstock volatility exposure from waterborne substitution pressures. For New Entrants and Emerging Players: E-procurement platforms for spot-grade solvent supply offer the lowest barrier to entry for building initial customer relationships without tank-car logistics investments. Target Indian architectural coating formulators seeking BIS-certified solvent alternatives as domestic production scale-up creates procurement flexibility gaps. Qualify emulsion-grade variants for waterborne systems where phase compatibility challenges persist and incumbent technical service is weakest. For Investors and Strategic Acquirers: Re-rating potential sits with cGMP-grade intermediate specialists given pharmaceutical outsourcing trends and active pharmaceutical ingredient synthesis demand. Long-term viability favors producers with dual capability across industrial solvent and electronics-grade purification. Watch semiconductor fabrication capacity announcements in Gyeonggi-do and the Yangtze River Delta as inflection indicators for ultra-high-purity ketone solvent demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetone Supply | Captive propylene-derived feedstock insulates Shell and Eastman from olefin market volatility. |
| cGMP Certification Investment | Pharmaceutical intermediate specifications command margin premiums for active pharmaceutical ingredient synthesis. |
| Closed-Loop Solvent Recovery Deployment | EU Green Deal funding rewards ketone recycling investments with preferential regulatory treatment. |
| Electronics-Grade Purity Scale-Up | Samsung and SK Hynix procurement patterns favor multi-year purity-guaranteed direct agreements. |
| Indian Market Entry Partnership | BIS certification alignment creates pathways into domestic architectural and automotive coating formulators. |
Research Methodology
Document review covered customs and trade data, SEC and ECHA regulatory filings, and ACC industry reports, complemented by interviews with plant managers at ketone production facilities, procurement leads at automotive OEM coating houses, distribution channel partners serving adhesive formulators, and technical R&D directors overseeing purity scale-up programs. Primary fieldwork across the US Gulf Coast, North Rhine-Westphalia, and Yangtze River Delta clusters was validated against secondary sources including chemical production databases and solvent trade flow records. Bottom-up volume modeling triangulated against top-down industry consensus estimates.
Historical capacity utilization trends were cross-referenced against panel input from downstream formulators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry cluster, physical form factor, and regional production hub. CAGRs were derived from regression analysis of demand drivers against supply-side capacity announcements. Forecast inputs incorporated REACH authorization timelines, EPA NESHAP compliance cost trajectories, and semiconductor fabrication node advancement patterns.
The model holds under stable acetone feedstock economics and gradual waterborne substitution; deviation in propylene market volatility or accelerated regulatory phase-outs would shift volume trajectories. Forecasts reflect assumptions about coating industry solvent recovery adoption rates and electronics-grade purity specification evolution. Periodic stress-testing of base assumptions against ECHA candidate list expansions and NMPA registration timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Triethanolamine Market
Chemicals
Global Bleaching Agents Market
Chemicals
Tributyl Phosphate Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Amine Oxide Market
Chemicals
Tanning Agents Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Mercuric Chloride Market
Chemicals
Amyl Nitrite Market
Chemicals
Perchloric Acid Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Global N-Butanol Market