
 Methanol to Gasoline Market | 2026-2036
Methanol to Gasoline Market Size, Share, and Industry Trends Forecast 2026-2036
Methanol to Gasoline Market Foresight
Project finance tied to carbon-capture integration is reshaping capital deployment for methanol-to-gasoline developers. ExxonMobil leverages its fixed-bed MTG reactor expertise to anchor licensing revenue streams across coal-rich geographies. Johnson Matthey sustains catalyst supply relationships that dominate the high-octane gasoline segment. Topsoe competes through integrated technology packages spanning syngas conditioning to finished fuel.
Methanol to gasoline conversion denotes catalytic dehydration and oligomerization of methanol over zeolite catalysts, typically ZSM-5, to produce hydrocarbons in the gasoline boiling range with Research Octane Numbers of 92-96. The process yields aromatic-free, low-sulfur gasoline suitable for direct blending or standalone fuel use. The MTG Process technology category leads installed capacity globally, while Renewable Gasoline commands premium positioning as biogenic methanol feedstocks gain regulatory preference. High-Octane Gasoline differentiates on performance specifications for aviation and racing applications where conventional refining yields insufficient purity.
The US EPA enforces Renewable Fuel Standard obligations that create compliance demand for alternative gasoline pathways, while China's MEE implements dual carbon goals restricting coal-to-fuel project approvals without CCUS co-investment. ISO fuel quality standards govern product interchangeability for international offtake contracts. Stakeholders must monitor feedstock cost divergence between natural gas and coal-derived methanol, as this spread determines project economics more than catalyst efficiency improvements.
Market Dynamics
China's MEE is tightening coal-to-fuel project approvals without mandatory CCUS co-investment, forcing developers to restructure capital stacks around carbon-capture integration. This regulatory pivot is compressing conventional methanol economics while elevating renewable feedstock pathways.
Growth Catalysts
- US EPA Renewable Fuel Standard:Compliance obligations for alternative gasoline pathways create mandated offtake demand for MTG-derived fuels.
- Fleet electrification lag:Commercial transportation operators facing delayed EV infrastructure deployment are extending gasoline blending contracts to bridge emissions compliance gaps.
- Zeolite catalyst advancement:ZSM-5 formulation improvements are lifting gasoline Research Octane Numbers toward aviation fuel thresholds.
Market Restraints
- Coal methanol cost volatility:Thermal coal price swings in Shaanxi province directly compress project margins regardless of catalyst efficiency gains.
- Natural gas feedstock divergence:US Gulf Coast methanol production enjoys persistent cost advantages over coal-derived routes, limiting Chinese export competitiveness.
- Electrification substitution:Battery-electric drivetrains in urban bus and delivery fleets are eroding addressable gasoline demand in dense population centers.
Strategic Opportunities
- Sustainable aviation fuel gap:ASTM certification pathways for MTG-derived high-octane streams open aviation blending markets constrained by renewable supply shortages.
- EU Green Deal carbon border adjustments:CCUS-integrated Chinese production becomes cost-competitive against unabated Mideast naphtha cracking for European gasoline imports.
- Modular reactor scaling:Johnson Matthey and Topsoe are downsizing fixed-bed MTG units for stranded gas field deployment, unlocking feedstock sources below pipeline threshold volumes.
Industry Challenges
- CCUS integration complexity:Amine capture retrofits on existing coal-to-chemical clusters require process shutdowns that disrupt methanol supply contracts.
- ASTM D4814 certification timelines:Fuel property testing for seasonal volatility and octane sensitivity extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methanol to Gasoline Market |
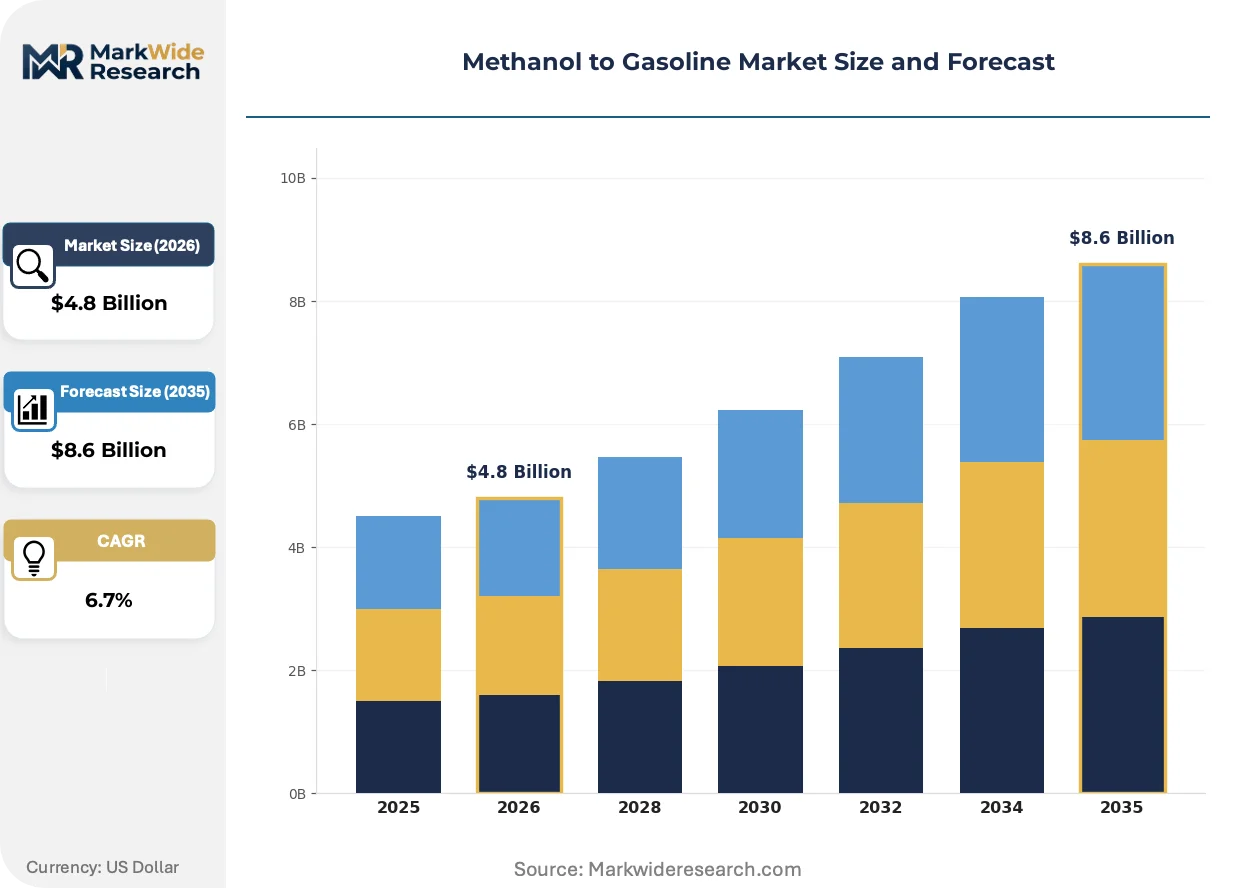
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: MTG Process, Direct Methanol Fuel Cell, Catalytic Conversion, Gasoline Synthesis End User: Automotive Industry, Petrochemical Sector, Energy Providers, Commercial Transportation Product Type: Conventional Gasoline, High-Octane Gasoline, Blended Gasoline, Renewable Gasoline Application: Fuel Production, Chemical Feedstock, Power Generation, Transportation Fuel |
| Companies Covered | Jincheng Anthracite Mining Group, Carbon Recycling International, ExxonMobil, Clariant, Johnson Matthey, Sinopec Engineering (Group) Co., Ltd., Topsoe, Ekobenz Sp. z o. o., Methanex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methanol to Gasoline Market Shifts & Advancements
Process intensification and feedstock diversification are converging to redefine methanol-to-gasoline economics. Developers are pivoting from scale maximization toward carbon intensity minimization.
Fluidized-bed MTG reactor designs are hybridizing with entrained-flow gasification to enable direct coal-to-gasoline conversion without intermediate methanol purification. Chinese state-owned developers in Ningxia are piloting this integration to cut steam demand by one-third. The hybridizing architecture is compressing capital intensity for grassroots projects while complicating retrofit economics for existing methanol assets.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-grade methanol demand for heat pump working fluids, diverting merchant methanol supply away from gasoline synthesis. German chemical distributors are securing long-term offtake contracts that prioritize refrigerant over fuel applications. The regulation is forcing MTG operators toward captive methanol production to secure feedstock security.
Blended gasoline procurement by logistics consortia is consolidating buying power across European road freight operators. Rotterdam terminal operators are offering certified low-carbon gasoline pools that aggregate MTG, bio-naphtha, and refinery streams under single carbon accounting frameworks. The model is most visible in Netherlands-Germany corridor haulage contracts where emissions disclosure mandates exceed national fuel standards.
Methanol to Gasoline Market Segmentation
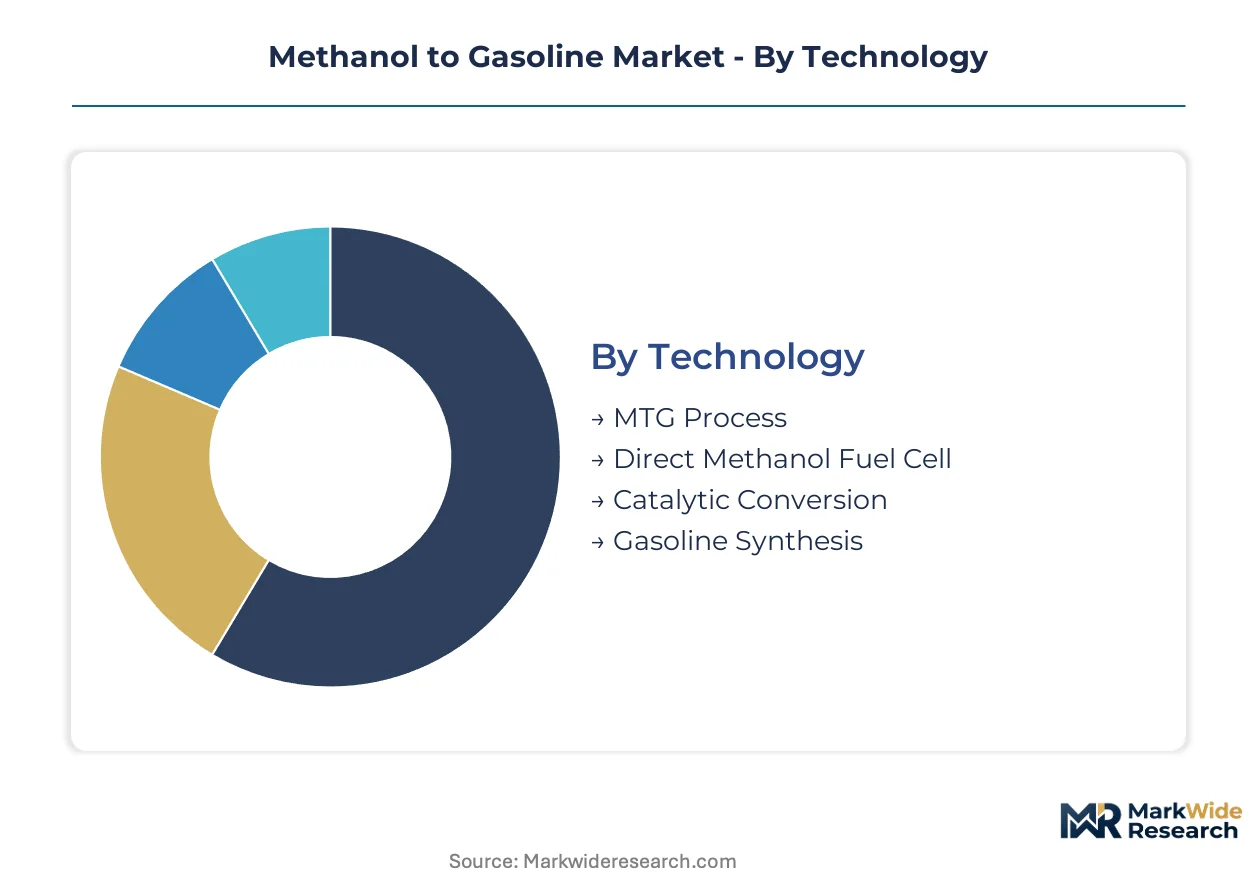
Technology selection determines catalyst replacement schedules and reactor maintenance intervals, which in turn shape service contract structures and long-term operating economics for methanol-to-gasoline facilities. End-use concentration in fleet transportation and petrochemical integration further segments procurement behavior between spot buyers and vertically integrated operators.
Technology:
After-sales service intensity varies sharply across reactor configurations, with fixed-bed units requiring periodic catalyst regeneration and fluidized-bed designs demanding continuous mechanical oversight.
- MTG Process:Fixed-bed ZSM-5 catalytic dehydration dominates commercial installations, with ExxonMobil licensing packages specifying proprietary catalyst formulations and scheduled replacement protocols. Demand concentrates in China's Shaanxi and Ningxia provinces where coal-to-chemical clusters anchor feedstock supply, driven by MEE mandates for CCUS co-investment on new approvals.
- Catalytic Conversion:Broader process category encompassing zeolite-based oligomerization with adjustable gasoline yield ratios, attracting developers seeking operational flexibility between gasoline and olefin outputs. Johnson Matthey and Topsoe compete on integrated service contracts covering catalyst supply through performance guarantees.
- Direct Methanol Fuel Cell:Electrochemical conversion pathway with limited gasoline relevance, primarily serving stationary power and portable fuel cell applications where direct methanol utilization bypasses hydrocarbon synthesis.
- Gasoline Synthesis:Catch-all designation for emerging hybrid processes combining syngas conditioning with direct gasoline condensation, piloted in Chinese state-owned demonstrations to reduce intermediate purification steps.
MTG Process holds the largest share; momentum sits with Catalytic Conversion.
End User:
Cost tier stratification separates integrated petrochemical operators with captive methanol supply from merchant buyers exposed to feedstock price volatility.
- Commercial Transportation:Fleet operators procure blended gasoline under emissions-linked contracts, with Rotterdam terminal operators aggregating certified low-carbon pools for Netherlands-Germany corridor haulage. EPA Renewable Fuel Standard compliance obligations in the US create mandated offtake demand for this segment.
- Automotive Industry:OEM fuel certification programs and ASTM D4814 testing requirements govern direct procurement relationships, with seasonal volatility specifications extending qualification timelines.
- Petrochemical Sector:Integrated crackers seek high-octane gasoline streams for downstream aromatic extraction, valuing low-sulfur specifications that reduce hydrotreating burden.
- Energy Providers:Utility-scale generators with dual-fuel turbine capabilities represent marginal demand, primarily in distributed power applications where liquid fuel storage outcompetes gas pipeline infrastructure.
Commercial Transportation commands the deepest procurement relationships; Automotive Industry is climbing the fastest on certification-driven contract values.
Product Type:
Margin structure follows carbon intensity differentiation, with renewable feedstock pathways capturing premium positioning against conventional coal-derived streams.
- Renewable Gasoline:Biogenic methanol feedstocks—sourced from biomass gasification or captured CO2 electrolysis—qualify for EU Green Deal carbon border adjustment preferences and US RFS credit generation. ASTM certification pathways for sustainable aviation fuel blending open aviation markets constrained by renewable supply shortages.
- High-Octane Gasoline:Research Octane Numbers of 95-98 suit aviation and racing applications where conventional refining yields insufficient purity, with ZSM-5 formulation improvements lifting yields toward aviation fuel thresholds.
- Blended Gasoline:Low-sulfur MTG streams mix with refinery naphtha and bio-naphtha in Rotterdam-certified pools, consolidating buying power across European road freight operators under single carbon accounting frameworks.
- Conventional Gasoline:Aromatic-free, low-sulfur base product suitable for direct use or downstream blending, facing margin compression from coal methanol cost volatility in Shaanxi province.
Conventional Gasoline retains volume leadership; Renewable Gasoline shows the steepest expansion trajectory on regulatory preference.
Application:
Supply concentration in fuel production reflects the dominance of transportation energy demand, while chemical feedstock applications leverage MTG's aromatic-free composition for specialty solvent markets.
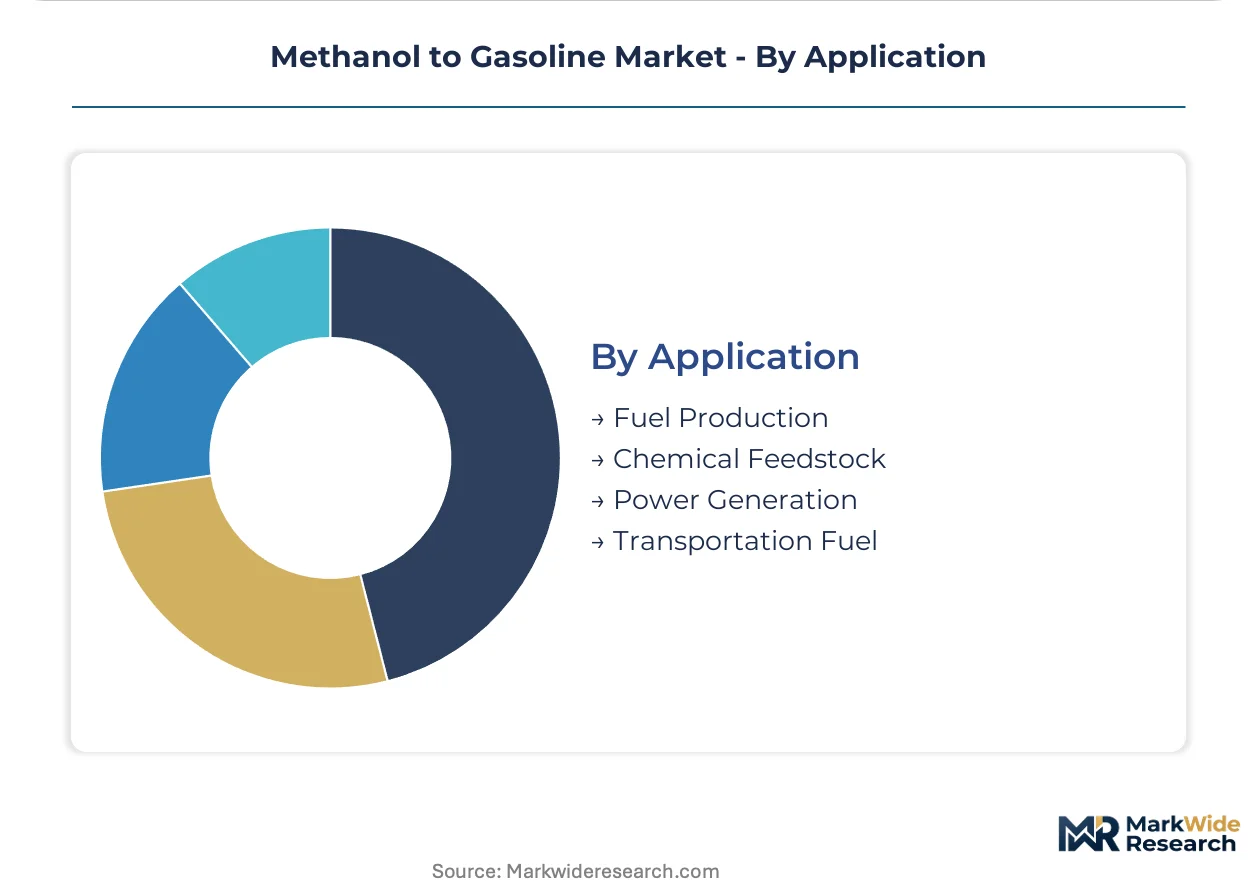
- Fuel Production:Dominant application encompassing finished gasoline blending and standalone fuel supply, with EU F-Gas Regulation diverting merchant methanol toward refrigerant applications and forcing MTG operators toward captive feedstock security.
- Transportation Fuel:Direct dispensing and fleet procurement contracts, concentrated in commercial road freight where electrification lag extends gasoline blending demand.
- Chemical Feedstock:Aromatic-free gasoline streams serve as extraction feedstock for BTX (benzene-toluene-xylene) production, valued in petrochemical integration where sulfur contamination disrupts downstream catalytic processes.
- Power Generation:Peaking turbine fuel and distributed generation applications, limited by competition from natural gas and battery storage in grid-connected markets.
Fuel Production accounts for the greatest capacity deployment; Transportation Fuel is gaining share fastest on fleet contract extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in commercial transportation anchor procurement decisions across coal-rich and gas-rich geographies alike. China's dual carbon goals and the US EPA Renewable Fuel Standard create divergent compliance pathways. Industrial clusters in Shaanxi province, Rotterdam terminals, and US Gulf Coast methanol corridors concentrate production capacity and offtake contracting.
China
Coal-to-chemical clusters in Shaanxi and Ningxia provinces supply captive methanol feedstock for MTG conversion. The MEE mandates CCUS co-investment on all new coal-to-fuel project approvals, restructuring capital stacks around carbon-capture integration. State-owned developers pilot fluidized-bed reactor hybridization with entrained-flow gasification to compress steam demand.
United States
EPA Renewable Fuel Standard compliance obligations create mandated offtake demand for alternative gasoline pathways. US Gulf Coast methanol production enjoys persistent cost advantages over coal-derived routes, anchoring export competitiveness. Fleet operators facing delayed EV infrastructure deployment extend gasoline blending contracts to bridge emissions compliance gaps.
Germany
Rotterdam terminal operators aggregate certified low-carbon gasoline pools for Netherlands-Germany corridor haulage contracts. EU F-Gas Regulation phase-down schedules accelerate refrigerant-grade methanol demand, diverting merchant supply away from fuel synthesis. Chemical distributors secure long-term offtake contracts prioritizing refrigerant over gasoline applications.
Netherlands
Rotterdam terminal infrastructure consolidates buying power across European road freight operators under single carbon accounting frameworks. EU Green Deal carbon border adjustments position CCUS-integrated production competitively against unabated Mideast naphtha cracking. Blended gasoline procurement by logistics consortia exceeds national fuel standards on emissions disclosure mandates.
Saudi Arabia
Stranded gas field development creates feedstock opportunities for modular MTG reactor deployment below pipeline threshold volumes. Industrial integration with existing petrochemical complexes enables downstream aromatic extraction from high-octane gasoline streams. Utility-scale generators with dual-fuel turbine capabilities represent marginal demand in distributed power applications.
Methanol to Gasoline Market Competitive Landscape
Channel-controlling players compete with product-specialist players for licensing revenue and catalyst supply relationships. The market structures around technology licensors with proprietary reactor designs, catalyst suppliers with performance guarantees, and integrated engineering contractors with turnkey execution capabilities. Three archetypes dominate: fixed-bed technology licensors, zeolite catalyst specialists, and state-owned coal-chemical conglomerates with captive integration. Competitive moves concentrate on technology licensing expansion, carbon-capture integration partnerships, and modular reactor scaling for stranded gas applications.
Among technology licensors, ExxonMobil anchors the fixed-bed MTG reactor segment with proprietary catalyst formulations. Johnson Matthey and Topsoe occupy positions spanning catalyst supply through integrated service contracts. State-owned Chinese developers including Jincheng Anthracite Mining Group and Sinopec Engineering represent the vertically integrated archetype with captive coal-methanol supply chains. Methanex Corporation exemplifies the merchant methanol supplier position navigating feedstock cost divergence between natural gas and coal routes.
| Leading Market Players |
|---|
| Jincheng Anthracite Mining Group |
| Carbon Recycling International |
| ExxonMobil |
| Clariant |
| Johnson Matthey |
| Sinopec Engineering (Group) Co., Ltd. |
| Topsoe |
| Ekobenz Sp. z o. o. |
| Methanex Corporation |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit thermal coal price volatility from Shaanxi province directly into methanol feedstock cost structures, compressing margin buffers for coal-derived gasoline while amplifying price spreads between CCUS-integrated and conventional production tiers.
Pricing Analysis
Cost-plus contracts indexed to Platts thermal coal assessments dominate Chinese procurement, with renewable gasoline premiums widening against conventional tiers on EU Green Deal carbon border eligibility. Price differentiation rests on CCUS certification status and ASTM D4814 compliance grade. Cost compression in conventional coal-derived tiers is intensifying because MEE mandates force retrofits without offsetting yield improvements. Merchant buyers in commercial transportation exhibit highest price sensitivity; integrated petrochemical operators with captive methanol supply show lowest.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor relationships between Johnson Matthey catalyst suppliers and Chinese state-owned developers. Feedstock security draws from Shaanxi coal-to-chemical clusters, US Gulf Coast methanol corridors, and Ningxia integrated gasification pilots. ZSM-5 zeolite catalysts, amine capture solvents, and specialized reactor vessels constitute critical input dependencies. Single-source vulnerability concentrates in catalyst formulation IP held by ExxonMobil and Topsoe. Distribution runs through Rotterdam terminal operators aggregating certified low-carbon pools for European road freight offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methanol-to-gasoline market functions as a regulatory entrenchment moat where MEE CCUS mandates and EPA Renewable Fuel Standard obligations create compliance-driven demand inelasticity against substitute fuels.
For Market Incumbents: Entrench through backward integration into captive methanol production and catalyst regeneration capabilities, insulating margin structures from Shaanxi coal price volatility. Secure ASTM D4814 certification extensions ahead of seasonal volatility specification changes. Electrification substitution in urban bus fleets threatens addressable demand; defend through aviation fuel pathway diversification. For New Entrants and Emerging Players: Establish a beachhead in modular MTG reactor deployment for stranded gas fields below pipeline threshold volumes in Saudi Arabia and Central Asia. Target sustainable aviation fuel blending markets where renewable supply shortages create certification-constrained demand. Go-to-market leverage rests on integrated technology licensing with performance-guaranteed catalyst supply contracts. For Investors and Strategic Acquirers: Catalyst specialists with proprietary ZSM-5 formulations and scheduled replacement service protocols represent the priority acquisition archetype. Long-term viability hinges on carbon intensity minimization capability across biogenic and captured CO2 feedstock pathways. Watch for MEE approval velocity on coal-to-fuel projects with mandatory CCUS co-investment as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CCUS Integration Partnership | MEE mandates restructure capital stacks around carbon-capture co-investment for project approvals. |
| Modular Reactor Scaling | Johnson Matthey and Topsoe downsizing fixed-bed units unlocks stranded gas field deployment below pipeline volumes. |
| ASTM Certification Investment | D4814 fuel property testing timelines extend commercialization cycles by 18-24 months without early engagement. |
| Captive Methanol Production | EU F-Gas Regulation diversion of merchant methanol toward refrigerant applications forces feedstock security strategies. |
| Aviation Fuel Pathway Development | High-octane MTG streams with RON 95-98 open sustainable aviation fuel blending markets constrained by renewable supply. |
Research Methodology
Initial hypotheses were tested against primary input from MTG plant operators, catalyst procurement managers, EPC contractors, and EPA compliance officers and refined through secondary validation against customs/trade data, MEE project approval registries, SEC 10-K filings from technology licensors, and ASTM certification timelines. Bottom-up capacity installation tracking and top-down fuel demand modeling were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning technology configuration, end-use concentration, product carbon intensity tier, and regional regulatory cluster. CAGRs were derived from installed capacity buildout schedules and fleet electrification lag assumptions. Industry-specific inputs included ZSM-5 catalyst replacement cycles and CCUS retrofit capital intensity estimates.
Sensitivities concentrate around MEE approval velocity for coal-to-fuel projects, thermal coal price volatility in Shaanxi province, and EV infrastructure deployment timelines in commercial transportation corridors. Forecasts reflect documented assumptions on regulatory enforcement consistency and catalyst efficiency improvement trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Bleaching Agents Market
Chemicals
Phenylethyl Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Copper Oxychloride Market
Chemicals
Morpholine Market
Chemicals
SLS and LABSA Market
Chemicals
HATU Market
Chemicals
Caustic Soda Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Potassium Permanganate Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Iso Nonanol Market
Chemicals
Chromium Trioxide Market