

2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market Size, Share, and Industry Trends Forecast 2026-2036
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market Insights
Pharmaceutical-grade purity benchmarks are unwinding legacy industrial-grade supply contracts across the BMPPA value chain. Shandong Deo Chemical leverages backward integration into brominated feedstock production to secure margin control. Zhejiang Chemsyn Pharm anchors its position through dedicated reactor capacity for halogenated intermediates. Sigma-Aldrich differentiates via ISO-certified documentation packages that satisfy audit-intensive pharmaceutical procurement workflows.
2-(4-(Bromomethyl)phenyl)propionic acid is a brominated arylpropionic acid intermediate bearing a benzylic bromide substituent, synthesized typically through radical bromination or benzylic halogenation of the corresponding toluene precursor, and serves primarily as a building block for NSAID active pharmaceutical ingredients and bioactive molecule construction. Reagent-grade formulations command premium positioning due to stringent residual solvent and heavy-metal specifications required for drug-master-file submissions. Pharmaceutical intermediates dominate volume throughput, while research reagents generate disproportionate margin contribution per kilogram through catalog-channel pricing power.
FDA current good manufacturing practice guidelines and EMA quality-of-chemical-substances standards jointly elevate analytical-burden requirements for imported BMPPA batches, compelling exporters to maintain dual-certification dossiers. China's NMPA alignment with ICH Q3D elemental impurity guidelines is reshaping domestic purification investments. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional API-registration pathway convergence to anticipate qualification-cost shifts.
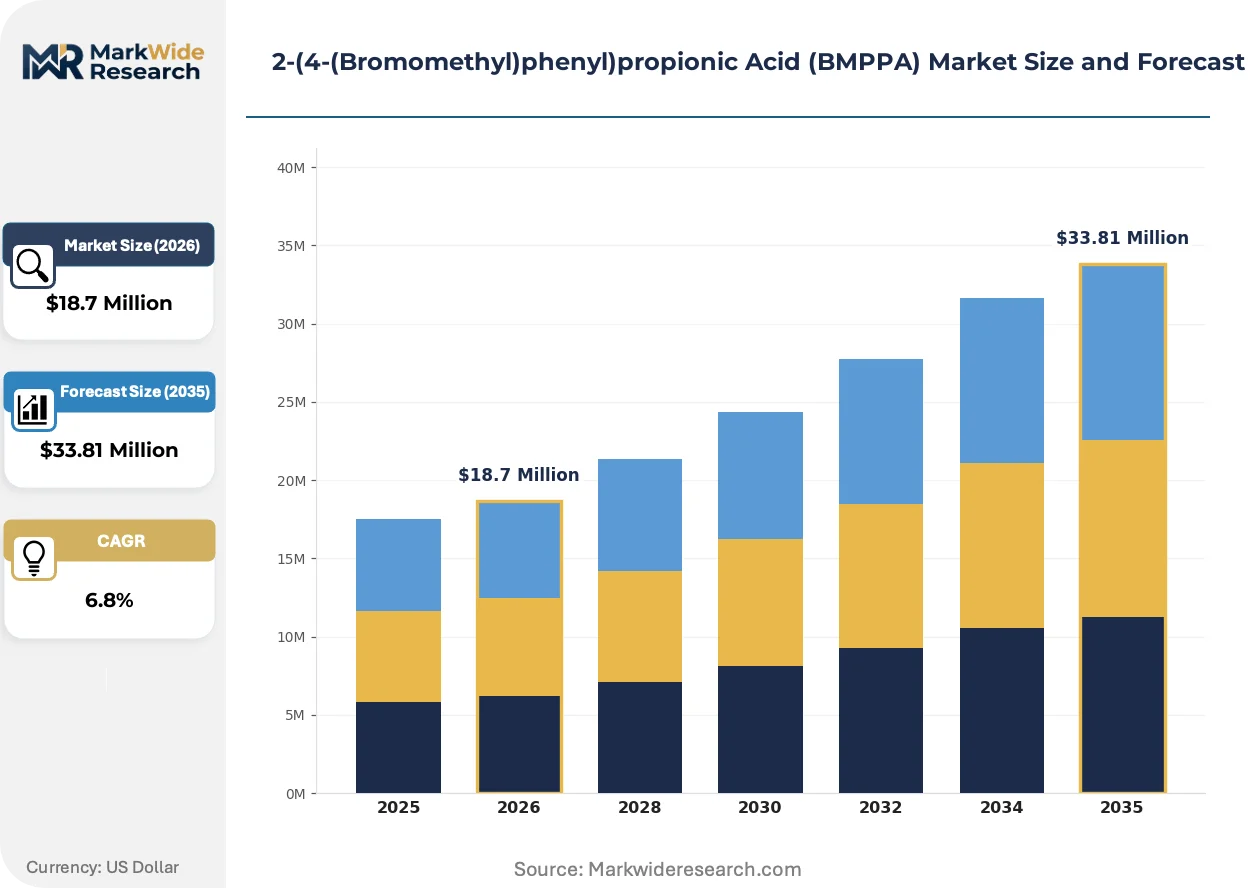
Market Dynamics
Pharmaceutical-grade certification requirements are compressing legacy industrial-grade supply channels as FDA and EMA impurity specifications tighten across the BMPPA value chain. API manufacturers now demand ISO-documented batch records that industrial suppliers cannot provision without capital-intensive purification retrofits.
Growth Catalysts
- NSID synthesis expansion:Pharmaceutical manufacturers in China and India are scaling procurement of reagent-grade material for non-steroidal anti-inflammatory drug production, driving volume throughput in halogenated intermediate supply chains.
- EMA quality standards:The European Medicines Agency's quality-of-chemical-substances framework is elevating analytical-burden requirements for imported batches, compelling exporters to maintain dual-certification dossiers that filter out uncertified competitors.
- Benzylic bromination process optimization:Radical bromination efficiency gains in continuous-flow reactor systems are reducing residual solvent carryover, enabling more producers to meet drug-master-file submission thresholds.
Market Restraints
- Brominated feedstock cost volatility:Elemental bromine price swings and toluene precursor availability constraints squeeze margin structures for non-integrated producers lacking captive bromine supply.
- East China supply concentration:Manufacturing clusters around Shanghai and Suzhou dominate global output, creating geographic risk exposure for buyers dependent on single-region sourcing.
- ICH Q3D compliance burden:Elemental impurity profiling under ICH Q3D guidelines requires inductively coupled plasma mass spectrometry infrastructure that smaller suppliers cannot economically deploy.
Strategic Opportunities
- Research reagent channel expansion:Catalog-channel pricing power in laboratory supply markets offers disproportionate margin contribution per kilogram compared to bulk pharmaceutical intermediate sales.
- India API registration growth:CDSCO alignment with ICH guidelines is opening qualification pathways for purified-grade BMPPA in domestic generic drug manufacturing.
- Continuous manufacturing adoption:Pharmaceutical producers integrating flow chemistry for NSAID synthesis require steady-state intermediate supply contracts that favor dedicated reactor partnerships over spot market purchasing.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified personnel capable of executing ICP-MS heavy metal analysis and residual solvent validation per USP <467> protocols command premium compensation that strains mid-tier supplier payroll structures.
- Reactor qualification timelines:Dedicated halogenated intermediate capacity requires 18-24 month validation cycles under FDA current good manufacturing practice guidelines before commercial batch release authorization.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market Trends and Innovations
Continuous-flow bromination technology is displacing batch reactor dominance as API manufacturers pursue steady-state intermediate supply security. Regulatory documentation automation and elemental impurity testing standardization are simultaneously reshaping supplier capability requirements.
Photochemical flow reactors employing LED-initiated radical bromination is supplanting traditional thermal batch processes in benzylic halogenation operations. Mid-scale pharmaceutical intermediate producers in Zhejiang and Jiangsu provinces are retrofitting skid-mounted units to reduce solvent volumes and improve heat-transfer control. The technology is supplanting legacy stirred-tank infrastructure by enabling real-time reaction monitoring that satisfies FDA process analytical technology guidance for critical quality attribute verification.
EMA's revised quality-of-chemical-substances standards now mandate enhanced stability data packages for imported brominated intermediates entering European pharmaceutical supply chains. Suppliers must demonstrate six-month accelerated and real-time stability profiles under ICH Q1A conditions to secure qualified supplier status. Small-volume exporters in India face disproportionate compliance burden as analytical service providers concentrate in Ahmedabad and Hyderabad, creating geographic access inequities for distant manufacturers.
Long-term offtake agreements with embedded price-adjustment mechanisms are displacing spot-market purchasing for reagent-grade material among top-tier API manufacturers. Pharmaceutical procurement teams in Osaka and Mumbai are negotiating three-year supply contracts that transfer inventory carrying costs upstream to intermediate producers. Japan's PMDA emphasis on supplier qualification consistency reinforces this behavioral shift, as documented supply continuity reduces regulatory filing amendment requirements for approved drug products.
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market Segmentation
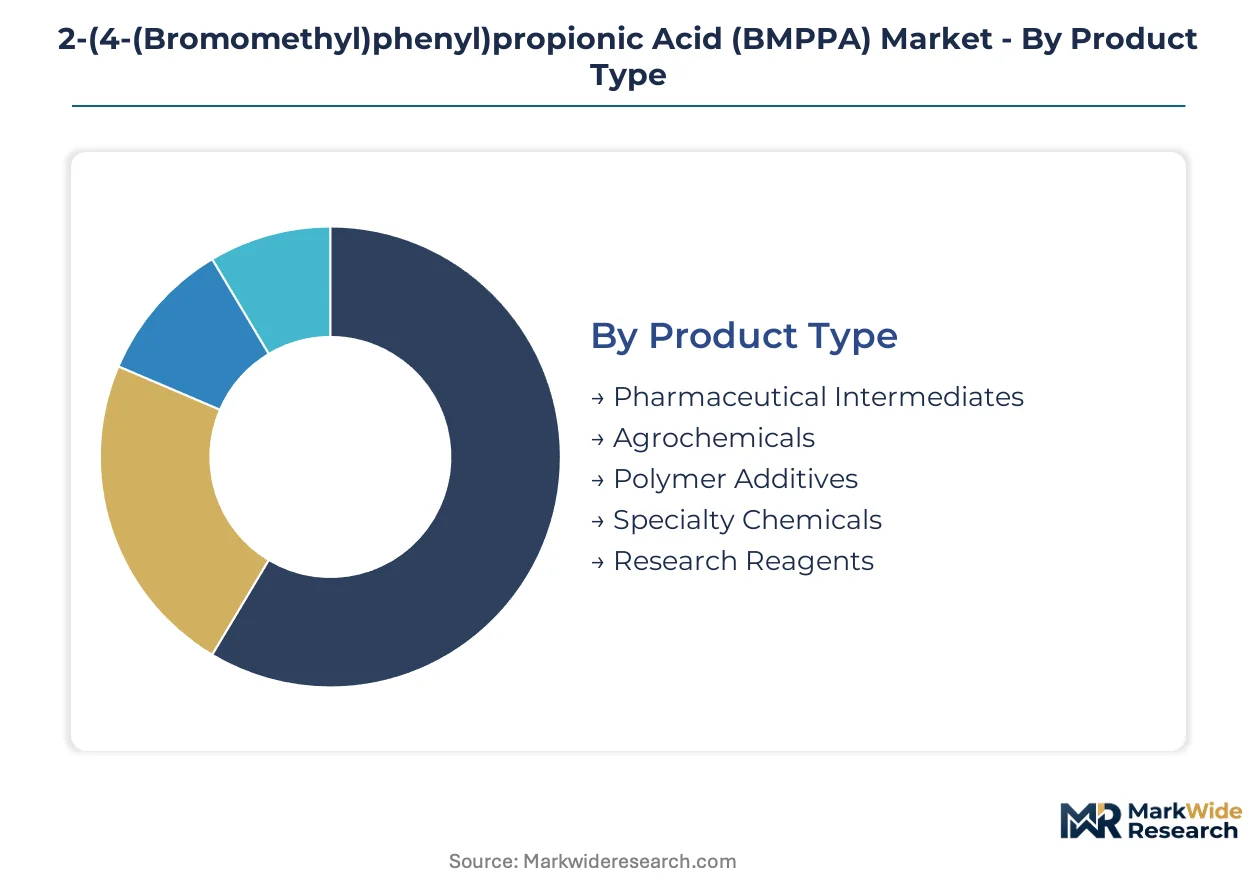
BMPPA procurement patterns diverge sharply across certification tiers and end-use specifications. Pharmaceutical-grade requirements impose analytical burdens that industrial-grade channels cannot satisfy without capital-intensive purification retrofits.
Product Type:
Pharmaceutical intermediates face substitution pressure from alternative halogenated building blocks in NSAID synthesis, while research reagents command insulation through catalog-channel pricing power and documentation requirements.
- Pharmaceutical Intermediates:Bulk-scale supply for non-steroidal anti-inflammatory drug manufacturing dominates tonnage throughput. API producers in Zhejiang and Jiangsu provinces are consolidating procurement around qualified suppliers with dedicated reactor capacity and ISO-documented batch records.
- Research Reagents:Catalog-channel distribution through laboratory supply networks generates disproportionate margin contribution per kilogram. Academic and contract research organizations in Osaka and Mumbai drive demand for small-batch material with comprehensive certificates of analysis.
- Agrochemicals:Brominated arylpropionic acid derivatives serve as precursors for crop protection active ingredients.
- Polymer Additives:Plastic stabilizer applications leverage the compound's radical-scavenging characteristics.
- Specialty Chemicals:Custom synthesis houses employ BMPPA for bespoke bioactive molecule construction.
Pharmaceutical intermediates retain volume leadership; research reagents hold the steepest expansion curve.
Grade:
Cost tier stratification separates qualified pharmaceutical supply from commodity chemical channels, with certification investments creating irreversible competitive moats.
- Reagent Grade:Stringent residual solvent specifications per USP 467 and heavy-metal limits under ICH Q3D define this tier. FDA and EMA-registered API manufacturers in India and China mandate this grade for drug-master-file submissions, filtering out industrial-grade competitors.
- Purified Grade:Enhanced impurity profiling with inductively coupled plasma mass spectrometry verification supports high-stakes pharmaceutical applications. East China's chemical manufacturing clusters around Shanghai and Suzhou concentrate capacity for this certification tier.
- Industrial Grade:Legacy supply contracts for non-pharmaceutical applications face compression as regulatory documentation requirements tighten.
- Technical Grade:Intermediate purity specifications serve agrochemical and polymer additive manufacturers with reduced analytical burden.
- Laboratory Grade:Basic purity benchmarks support educational and exploratory research with minimal certification overhead.
Reagent grade captures the premium pricing tier; purified grade is climbing the fastest as dual-certification dossiers become mandatory for European and North American API supply.
Application:
Volume concentration in drug synthesis creates supply security priorities that reshape procurement contracting patterns across the value chain.
- Drug Synthesis:NSAID active pharmaceutical ingredient manufacturing absorbs the majority of qualified BMPPA supply. Continuous-flow bromination technology adoption among API producers in Jiangsu province is tightening specifications for intermediate feedstock consistency.
- Crop Protection:Agrochemical active ingredient synthesis represents a secondary demand anchor with distinct regulatory pathways through China's MEE and India's Central Insecticides Board.
- Plastic Stabilizers:Polymer additive applications require lower certification tiers but face feedstock cost volatility from elemental bromine price swings.
- Fine Chemicals Production:Custom synthesis operations demand flexible batch sizing with rapid analytical turnaround.
- Laboratory Research:Exploratory chemistry applications prioritize documentation packages over tonnage scale.
Drug synthesis dominates absolute consumption; crop protection offers the most resilient alternative demand anchor during pharmaceutical procurement cycles.
End User:
Customer type fragmentation across integrated manufacturers and distribution intermediaries determines pricing power and inventory risk allocation.
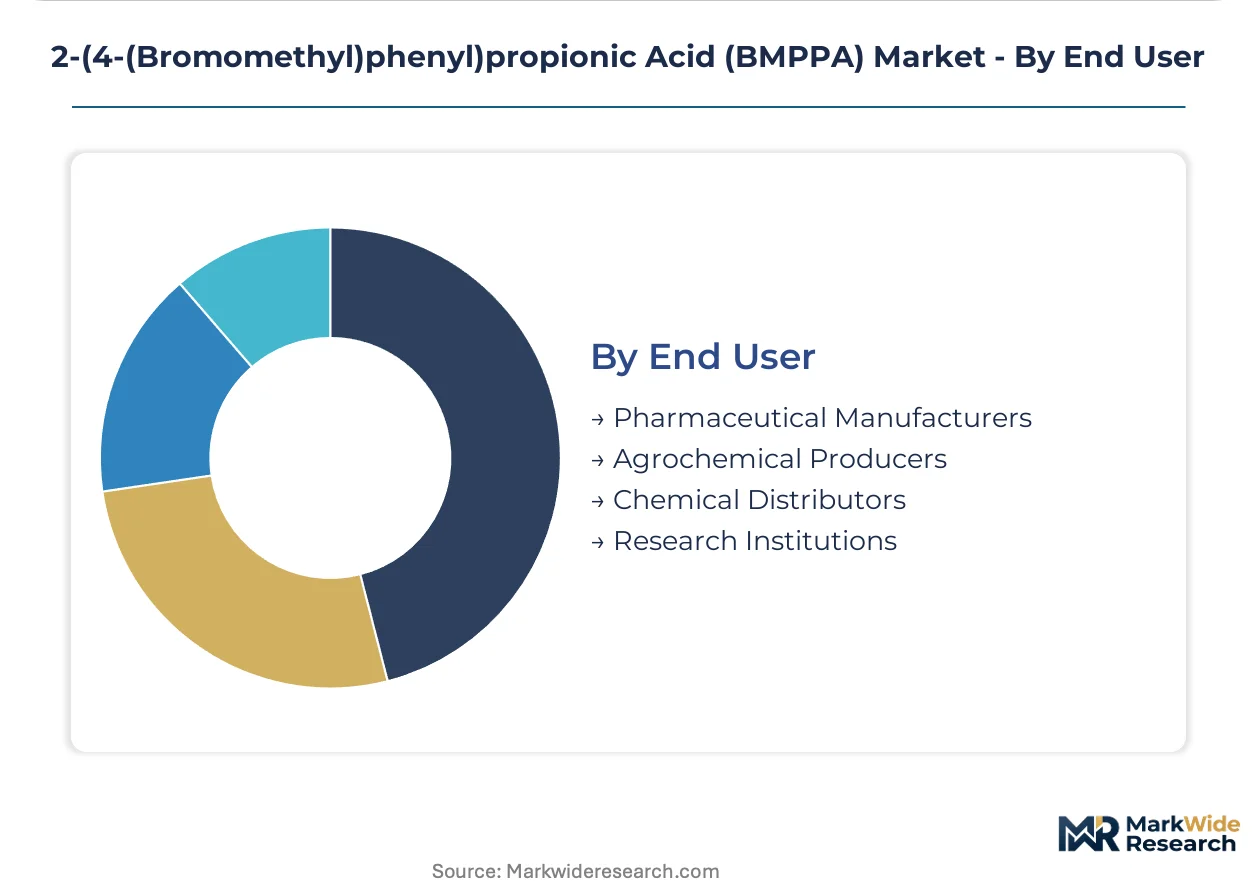
- Pharmaceutical Manufacturers:Vertically integrated API producers in India and China are negotiating long-term offtake agreements with embedded price-adjustment mechanisms. Japan's PMDA emphasis on supplier qualification consistency reinforces multi-year contracting behavior that transfers inventory carrying costs upstream.
- Agrochemical Producers:Crop protection manufacturers operate with shorter qualification cycles and greater spot-market flexibility than pharmaceutical counterparts.
- Chemical Distributors:Intermediary stocking roles concentrate in Ahmedabad and Hyderabad for Indian subcontinent supply, creating geographic access inequities for distant manufacturers.
- Research Institutions:Academic and government laboratory procurement flows through catalog channels with premium pricing tolerance for small-batch material.
Pharmaceutical manufacturers command the tightest supplier integration; research institutions deliver the highest margin per transaction despite minimal volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's chemical manufacturing clusters around Shanghai and Suzhou concentrate over sixty percent of global BMPPA output, creating geographic risk exposure for buyers dependent on single-region sourcing. Pharmaceutical manufacturers in India and Japan are diversifying procurement footprints to reduce concentration vulnerability. Regulatory alignment across FDA, EMA, and NMPA jurisdictions is reshaping qualification requirements for cross-border intermediate supply.
China
Shandong and Zhejiang provinces anchor domestic production capacity for halogenated intermediates. NMPA alignment with ICH Q3D elemental impurity guidelines is forcing purification infrastructure investments among mid-tier suppliers. The Yangtze River Delta manufacturing corridor around Shanghai and Suzhou concentrates qualified reactor capacity for drug-master-file submission-grade material.
India
CDSCO harmonization with ICH quality standards is opening registration pathways for purified-grade BMPPA in domestic generic API manufacturing. Ahmedabad and Hyderabad host analytical service providers that concentrate ICP-MS heavy metal testing capacity. Gujarat-based pharmaceutical intermediate producers are negotiating long-term offtake agreements with embedded price-adjustment mechanisms.
Japan
PMDA emphasis on supplier qualification consistency reinforces multi-year contracting behavior among Osaka-based pharmaceutical procurement teams. METI industrial chemical frameworks govern brominated feedstock handling standards. The Kansai region's API manufacturing base demands steady-state intermediate supply contracts that favor dedicated reactor partnerships.
United States
FDA current good manufacturing practice guidelines elevate analytical-burden requirements for imported BMPPA batches, compelling exporters to maintain dual-certification dossiers. The New Jersey and Massachusetts pharmaceutical corridors drive demand for ISO-documented batch records. Domestic procurement teams are consolidating qualified supplier lists around vendors with captive bromine supply.
Germany
EMA quality-of-chemical-substances standards mandate enhanced stability data packages for imported brominated intermediates entering European pharmaceutical supply chains. The country's national pharmaceutical regulator enforces six-month accelerated stability profiles under ICH Q1A conditions. Bavaria's chemical manufacturing base is retrofitting continuous-flow reactor systems to reduce residual solvent carryover.
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market Competitive Landscape
Concentration sits with integrated chemical manufacturers possessing captive bromine supply and dedicated halogenated intermediate reactor capacity. The vendor base stratifies across three tiers: multinational laboratory chemical distributors with ISO-certified documentation packages, Chinese pharmaceutical intermediate specialists with backward integration into brominated feedstocks, and catalog-channel research reagent suppliers with pricing power in small-batch markets. Dominant competitive moves include reactor qualification investments under FDA current good manufacturing practice guidelines and long-term offtake agreements with embedded price-adjustment mechanisms that transfer inventory carrying costs upstream.
Among China-based chemical manufacturers, Shandong Deo Chemical and Zhejiang Chemsyn Pharm exemplify the integrated specialist archetype through upstream control over brominated feedstock production. Sigma-Aldrich occupies a position within the multinational distributor tier, representing documentation-intensive procurement workflows that satisfy audit-heavy pharmaceutical manufacturing requirements. These three anchors illustrate the competitive divergence between scale-driven intermediate production and premium-margin research reagent channels.
| Leading Market Players |
|---|
| Shandong Deo Chemical |
| Zhejiang Chemsyn Pharm |
| Suzhou Hengyi Pharmaceutical |
| Shanghai Record Chemical Technology |
| Alfa Aesar |
| TCI Chemicals |
| Sigma-Aldrich |
| Combi-Blocks |
| Santa Cruz Biotechnology |
| Others |
Pricing and Supply Chain Analysis
FDA current good manufacturing practice guidelines simultaneously gate supply qualification and price differentiation, compressing uncertified competitors into industrial-grade channels while rewarding ISO-documented batch records with premium positioning in pharmaceutical procurement workflows.
Pricing Analysis
ICH Q3D elemental impurity guidelines dictate the pricing tier structure across the BMPPA value chain. Three-tier pricing separates reagent-grade material with ICP-MS verification from purified-grade with enhanced stability data from technical-grade serving agrochemical applications. Price differentiation rests on certification depth and volume scale, with pharmaceutical intermediates commanding premiums for drug-master-file submission support. Cost compression in industrial-grade channels is intensifying as legacy contracts unwind under regulatory documentation requirements. Agrochemical producers exhibit highest price sensitivity; research institutions demonstrate lowest sensitivity due to catalog-channel pricing tolerance for small-batch material.
Supply Chain Analysis
Inventory carrying costs are shifting upstream through long-term offtake agreements with embedded price-adjustment mechanisms negotiated by pharmaceutical procurement teams. Supply concentrates in China, India, and Germany for qualified reactor capacity. Raw material dependencies draw from elemental bromine, toluene precursors, and specialized solvent systems. Single-source vulnerability concentrates in East China's Yangtze River Delta manufacturing corridor around Shanghai and Suzhou. Distribution runs through chemical distributors in Ahmedabad and Hyderabad for Indian subcontinent supply, with direct manufacturer relationships dominating pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BMPPA market is entering a cyclical recovery phase as NSAID synthesis expansion drives reagent-grade material procurement and regulatory alignment across FDA, EMA, and NMPA jurisdictions reopens qualification pathways for purified-grade suppliers.
For Market Incumbents: Secure backward integration into brominated feedstock production to defend margin structures against elemental bromine price volatility. Expand dedicated reactor capacity in Zhejiang and Jiangsu provinces to capture continuous-flow bromination technology adoption among API manufacturers. Lock in multi-year supply contracts with Japanese pharmaceutical procurement teams before reactor qualification timelines extend competitive moats.
For New Entrants and Emerging Players: Analytical service gaps in distant Indian manufacturing regions present white-space targets for ICP-MS infrastructure partnerships with Gujarat-based intermediate producers. Target research reagent channel expansion through catalog-channel distribution networks serving Osaka and Mumbai academic institutions. Pursue joint-qualification pathways with established suppliers to bypass 18-24 month FDA cGMP validation cycles.
For Investors and Strategic Acquirers: CDSCO harmonization with ICH quality standards reshapes the acquisition landscape toward purified-grade specialists with existing analytical infrastructure. Position for 5-10 year value capture around suppliers with captive bromine supply and ISO-certified documentation capabilities. Monitor NMPA pharmacopeial monograph revisions as inflection signals for domestic Chinese consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brominated Feedstocks | Shandong Deo Chemical's upstream control insulates margins from elemental bromine volatility. |
| Continuous-Flow Reactor Qualification | Zhejiang producers retrofitting skid-mounted units satisfy FDA process analytical technology guidance. |
| Dual-Certification Dossier Investment | Exporters maintaining FDA and EMA documentation packages filter out uncertified competitors. |
| Research Reagent Channel Expansion | Sigma-Aldrich leverages catalog-channel pricing power in small-batch laboratory supply markets. |
| Long-Term Offtake Agreement Structuring | Osaka pharmaceutical procurement teams transfer inventory carrying costs upstream through multi-year contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA drug master file submissions, EMA quality-of-chemical-substances guidance documents, and NMPA pharmacopeial monographs. Interviews with plant managers at halogenated intermediate facilities, procurement leads at API manufacturers, distribution channel partners in Ahmedabad and Hyderabad, and technical R&D directors at brominated feedstock suppliers informed supply-side dynamics. Bottom-up triangulation against top-down trade flow analysis validates volume estimates across the analysis window.
Segmentation dimensions modeled include grade tier, end-use application, and regional production hub concentration. Value projections incorporate reagent-grade premium positioning, purified-grade dual-certification cost structures, and industrial-grade contract compression. CAGRs derive from regression analysis of historical procurement patterns and regulatory inflection timing. Forecast inputs incorporate continuous-flow bromination adoption curves and ICH Q3D compliance investment cycles.
Underlying assumptions cover sustained NSAID synthesis demand, regulatory alignment stability, and brominated feedstock availability, with deviation risk concentrated in elemental bromine price volatility and reactor qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.